
 Bleeding Disorders Testing Market | 2026-2036
Bleeding Disorders Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Bleeding Disorders Testing Market Analytics
Specialized hematopathologist availability is rotating toward molecular coagulation diagnostics, tightening labor pools in conventional hemostasis laboratories. Siemens Healthineers leverages its integrated automation platforms to anchor high-throughput coagulation testing in centralized hospital laboratories. Sysmex Corporation sustains dominance in hematology analyzers that feed preliminary screening data into downstream bleeding disorder workflows. Abbott Laboratories differentiates through point-of-care INR systems that extend testing access beyond traditional laboratory settings.
Bleeding disorders testing encompasses laboratory and near-patient diagnostic methods that quantify coagulation factor activity, platelet function, and fibrinolytic markers to identify congenital or acquired hemostatic defects. Chromogenic substrate assays measure factor VIII and IX activity with precision thresholds of 0.01 IU/mL, enabling carrier detection and treatment monitoring in hemophilia patients. Coagulation panel testing occupies the largest revenue share due to its essential role in pre-surgical screening and anticoagulation management across hospital settings. Factor assays represent the fastest-expanding category as gene therapy eligibility protocols require precise baseline and longitudinal factor activity quantification.
The FDA regulates in vitro diagnostic coagulation assays as Class II or III medical devices, mandating clinical validation studies that shape product development timelines and commercial entry pathways. Clinical Laboratory Improvement Amendments govern analytical performance standards for PT/INR and factor activity testing performed in US laboratories. The EU In Vitro Diagnostic Regulation requires notified body conformity assessments for bleeding disorder test kits, elevating documentation burdens for manufacturers seeking European market access. Stakeholders must monitor evolving pharmacogenomic testing guidelines that could expand factor assay indications beyond traditional hemophilia management into personalized anticoagulation protocols.
Market Dynamics
Gene therapy eligibility protocols are compressing turnaround times for factor activity quantification, forcing laboratories to reconfigure workflows around molecular diagnostic platforms while maintaining CLIA-compliant analytical performance standards.
Growth Catalysts
- FDA Accelerated Approval Pathways:Compressed clinical validation timelines for novel coagulation factor assays enable faster commercial entry for innovative test developers targeting hemophilia management protocols.
- Hemophilia Treatment Center Expansion:Specialized centers across the United States are anchoring clinical testing volume and driving technology upgrades in molecular diagnostic capabilities.
- Next-Generation Sequencing Integration:NGS platforms are enabling carrier detection at precision thresholds previously unattainable with conventional chromogenic substrate methods.
Market Restraints
- EU MDR Documentation Burdens:Notified body conformity assessments for bleeding disorder test kits elevate compliance costs and extend European market access timelines for manufacturers.
- Specialized Hematopathologist Shortage:Labor pool tightening in conventional hemostasis laboratories constrains throughput expansion despite instrument automation advances.
- Chromogenic Substrate Input Volatility:Precision reagent supply concentration creates cost pressure for laboratories maintaining 0.01 IU/mL detection thresholds.
Strategic Opportunities
- Point-of-Care INR Extension:Near-patient testing systems can capture anticoagulation monitoring volume outside traditional hospital laboratory settings.
- Pharmacogenomic Guideline Expansion:Evolving factor assay indications beyond hemophilia into personalized anticoagulation protocols open new clinical utility segments.
- Pre-Surgical Screening Automation:Integrated coagulation panel platforms address unmet demand in ambulatory surgical centers requiring rapid turnaround.
Industry Challenges
- CLIA Proficiency Testing Complexity:Analytical performance standards for PT/INR and factor activity testing require continuous quality management system investment.
- Legacy LIS Integration Friction:Molecular diagnostic platforms face interoperability barriers with established laboratory information systems in centralized hospital settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bleeding Disorders Testing Market |
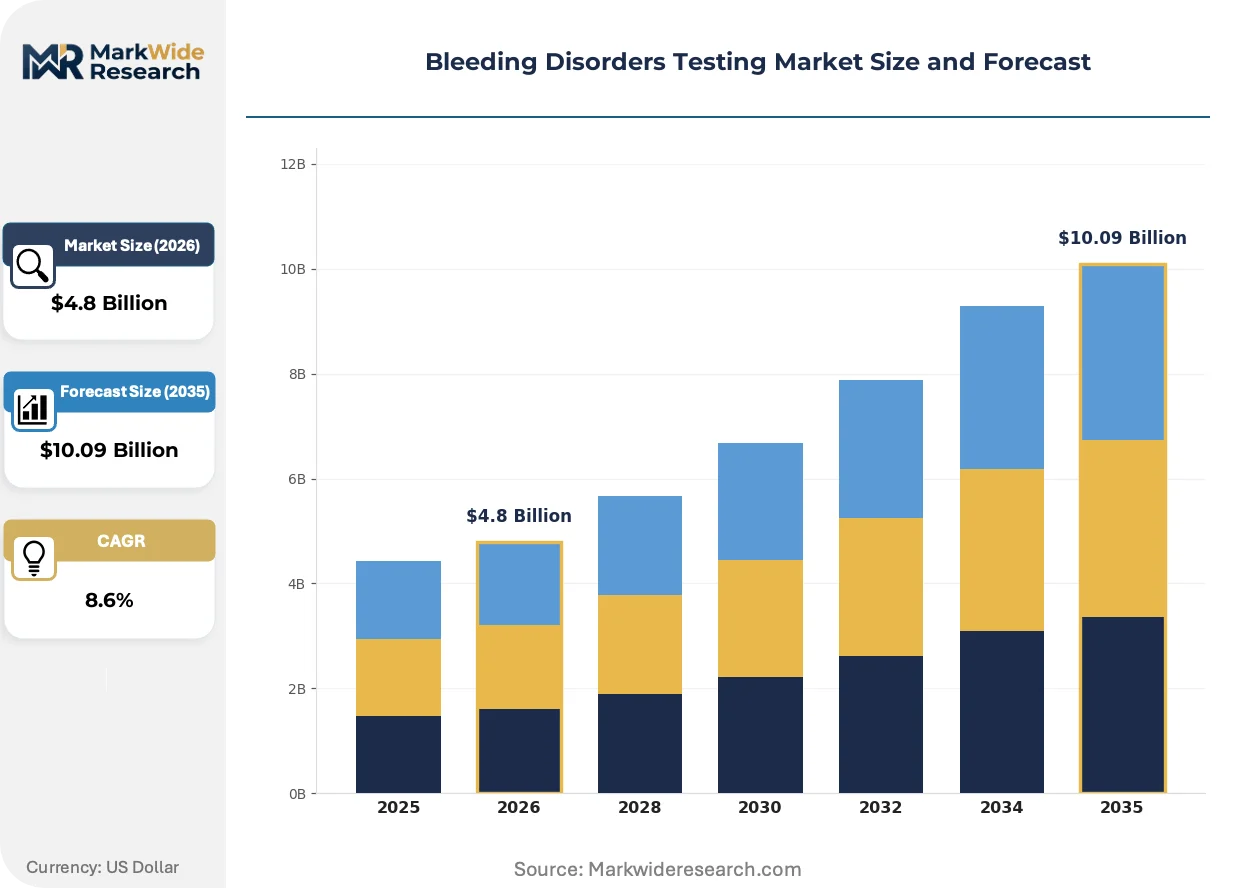
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Coagulation Panel, Platelet Function Test, Factor Assays, PT/INR Technology: ELISA, Chromogenic, MLPA, Lateral Flow Assay End User: Hospitals, Diagnostic Laboratories, Research Institutes, Home Care Sample Type: Blood, Plasma, Serum, Whole Blood |
| Companies Covered | Siemens Healthineers, Sysmex Corporation, F. Hoffmann-La Roche Ltd., Abbott Laboratories, Bio-Rad Laboratories, Thermo Fisher Scientific, HORIBA Ltd., Beckman Coulter, bioMérieux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bleeding Disorders Testing Market Evolving Landscape
Digital pathology integration and automated sample-to-answer platforms are compressing manual interpretation steps in coagulation testing workflows while regulatory frameworks adapt to novel assay categories.
Digital slide imaging coupled with AI-assisted pattern recognition is bifurcating morphological assessment pathways in hematology laboratories. Academic medical centers are adopting these platforms for platelet function analysis within 18-month procurement cycles. This technology is bifurcating the traditional hematopathologist workflow into algorithm-assisted screening versus complex case escalation tiers.
EU MDR Article 10 technical documentation requirements are mandating expanded clinical evidence packages for Class IIb coagulation analyzers. Manufacturers must now submit post-market surveillance data alongside pre-market validation studies. Hemostasis reagent suppliers with existing IVDD certifications face the steepest compliance pathway adjustments.
Consolidated purchasing agreements through integrated delivery networks are displacing standalone laboratory procurement autonomy. Hospital systems are centralizing coagulation testing contracts under multi-year sole-source arrangements with automation-integrated vendors. This concentration is most visible in United States metropolitan markets where hemophilia treatment centers anchor regional referral networks.
Bleeding Disorders Testing Market Segmentation
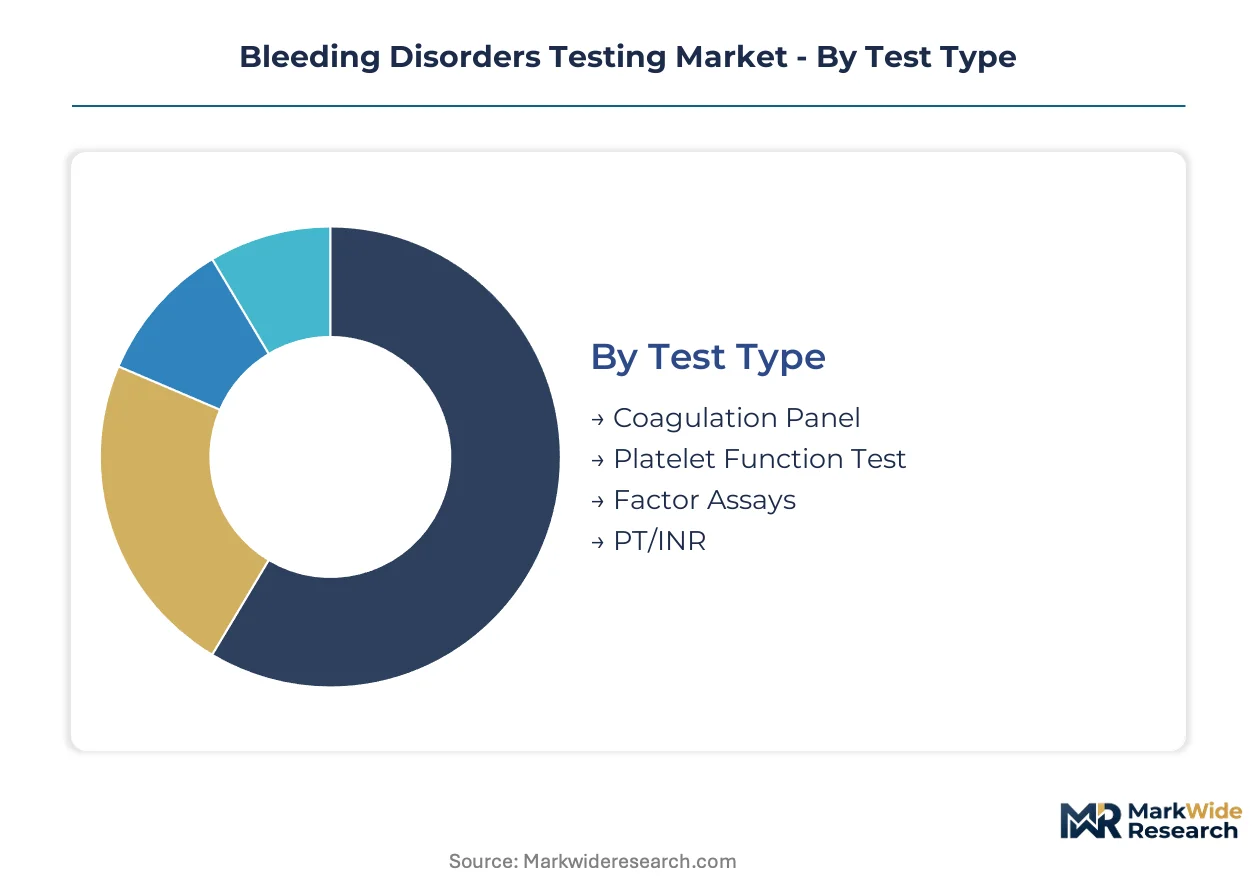
Segmentation in bleeding disorders testing reveals how clinical workflows, regulatory pathways, and reimbursement structures fragment demand across distinct technical and operational categories. Understanding these divisions illuminates where capital investment concentrates and which platforms capture volume migration.
Test Type:
Domestic demand anchors routine screening panels, while specialized factor assays travel through international reference laboratory networks for rare coagulopathy confirmation.
- Coagulation Panel:Standardized PT/aPTT combinations dominate pre-surgical screening and anticoagulation monitoring in hospital core laboratories. United States metropolitan health systems drive procurement volume through consolidated purchasing agreements.
- Factor Assays:Chromogenic and clotting-based methods quantify factor VIII, IX, and von Willebrand activity with precision thresholds required for gene therapy eligibility protocols. Hemophilia treatment centers in Germany and the United States anchor specialized demand for longitudinal activity tracking.
- Platelet Function Test:Aggregometry and impedance methods assess hemorrhagic risk in cardiac surgery and trauma settings.
- PT/INR:Prothrombin time testing with international normalized ratio reporting serves warfarin management across anticoagulation clinics.
Coagulation panels command the established base. The steepest expansion runs through factor assays.
Technology:
Cost tiers separate high-complexity molecular platforms from rapid near-patient formats, with reimbursement differentials reinforcing this stratification.
- Chromogenic:Synthetic substrate methods measure factor activity through colorimetric endpoints, achieving 0.01 IU/mL detection thresholds essential for carrier detection. Academic medical centers in France and Switzerland prioritize these platforms for research-grade precision.
- ELISA:Enzyme-linked immunosorbent assays quantify coagulation factor antigen levels and inhibitors in batch-processing workflows. High-throughput hospital laboratories in Japan favor ELISA for von Willebrand disease subtyping.
- Lateral Flow Assay:Immunochromatographic strips enable point-of-care INR testing outside traditional laboratory infrastructure.
- MLPA:Multiplex ligation-dependent probe amplification detects large gene rearrangements in hemophilia A and B molecular diagnostics.
Chromogenic platforms anchor the premium tier. Lateral flow formats are gaining share fastest in ambulatory expansion.
End User:
Application intensity varies sharply: acute care demands rapid turnaround, while research settings prioritize analytical sensitivity over speed.
- Hospitals:Integrated automation platforms in centralized laboratories process emergency coagulation panels and perioperative screening. United States health systems with hemophilia treatment center affiliations drive technology upgrade cycles.
- Diagnostic Laboratories:Reference laboratories handle esoteric factor assays and molecular confirmatory testing for regional hospital networks. Germany's national laboratory chains specialize in rare bleeding disorder genetics.
- Home Care:Patient-operated INR monitors extend anticoagulation management beyond clinical visits.
- Research Institutes:Academic centers validate novel biomarkers and pharmacogenomic associations in hemostasis.
Hospitals retain the volume base. Home care represents the steepest expansion trajectory.
Sample Type:
Supply concentration in plasma-derived reagents shapes which matrices dominate routine versus specialized testing.
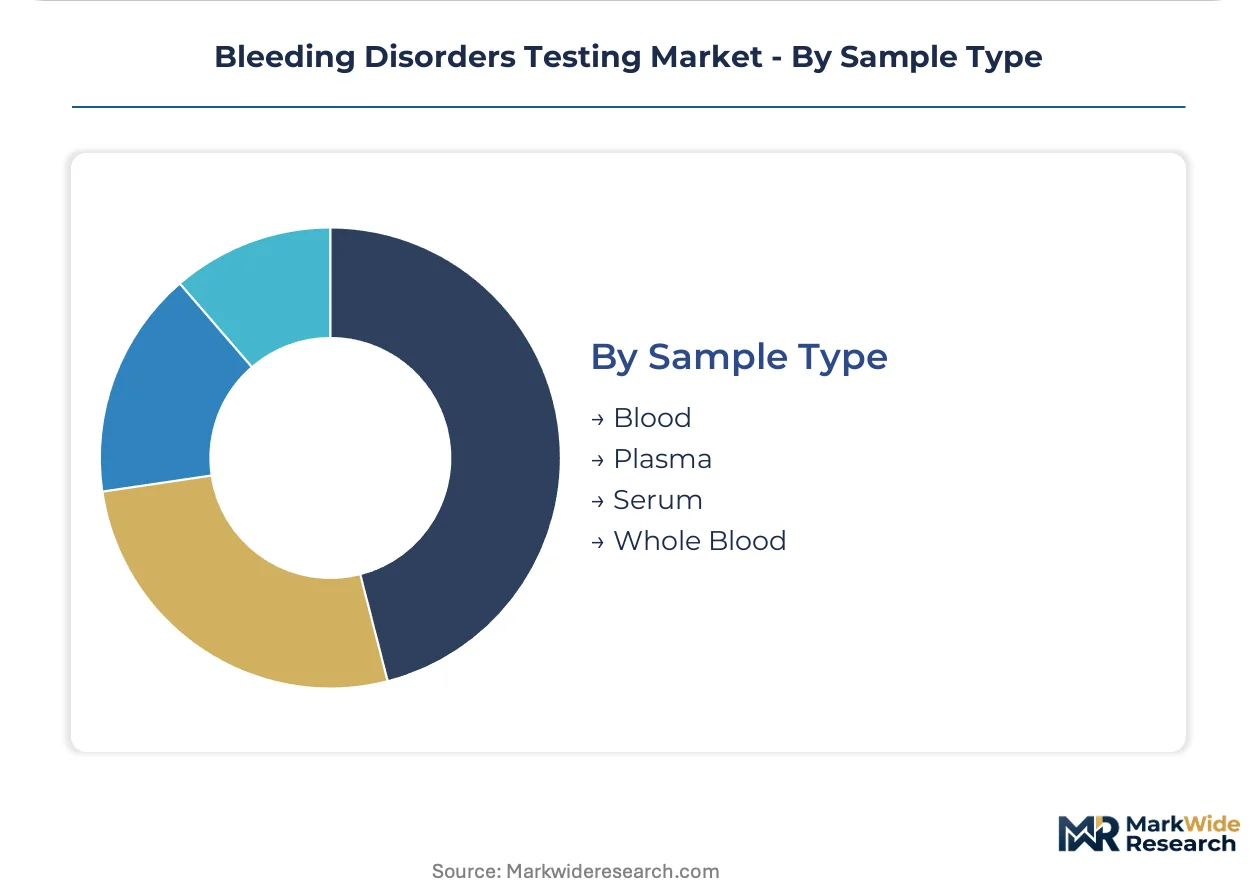
- Plasma:Citrate-anticoagulated plasma serves as the reference matrix for coagulation factor activity measurement and international standard calibration. Blood collection centers in the United States and Austria supply plasma for reagent manufacturing.
- Whole Blood:Native blood samples enable viscoelastic testing and point-of-care coagulation assessment in trauma and cardiac surgery. Swiss and United States trauma centers drive viscoelastic analyzer placement.
- Serum:Clotted blood derivatives support select immunologic coagulation assays.
- Blood:EDTA-anticoagulated specimens feed preliminary hematology screening before coagulation workup.
Plasma commands the established base. Whole blood is climbing the fastest through near-patient adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways anchor the United States as the dominant geography, while EU MDR documentation requirements reshape European market access timelines for coagulation assay manufacturers.
United States
Hemophilia treatment centers in Boston and New York Metro drive molecular diagnostic upgrades for gene therapy eligibility protocols. CLIA proficiency testing mandates enforce analytical performance standards for PT/INR and factor activity quantification. The Southeast cluster around Atlanta anchors consolidated purchasing agreements through integrated delivery networks.
Germany
National laboratory chains specialize in rare bleeding disorder genetics and esoteric factor assays for regional hospital networks. EU MDR notified body conformity assessments extend commercial entry timelines for chromogenic substrate test kits. The Munich-Stuttgart corridor concentrates hematopathologist training programs feeding European reference laboratory demand.
Japan
High-throughput hospital laboratories in Tokyo and Osaka favor ELISA platforms for von Willebrand disease subtyping at precision thresholds. PMDA regulatory frameworks govern in vitro diagnostic coagulation device classifications with validation study requirements. The Kansai region sustains dominance in hematology analyzer manufacturing feeding preliminary screening workflows.
Switzerland
Academic medical centers in Geneva and Basel prioritize chromogenic platforms achieving 0.01 IU/mL detection thresholds for research-grade carrier detection. Swissmedic conformity assessments align with EU MDR technical documentation standards for Class IIb coagulation analyzers. The Zurich-Bern axis concentrates trauma center viscoelastic analyzer placement for whole blood coagulation assessment.
France
ANSM oversight of post-market surveillance data shapes hemostasis reagent supplier compliance pathways under EU MDR Article 10. Digital pathology integration for platelet function analysis concentrates in Paris and Lyon academic medical centers. The Île-de-France region drives 18-month procurement cycles for AI-assisted morphological assessment platforms.
Bleeding Disorders Testing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in bleeding disorders testing, with automation-integrated vendors capturing consolidated hospital contracts while molecular diagnostic specialists serve hemophilia treatment center networks. Siemens Healthineers anchors high-throughput coagulation testing through integrated automation platforms in centralized laboratories. Sysmex Corporation sustains dominance in preliminary hematology screening feeding downstream bleeding disorder workflows. The competitive terrain rewards two moves: sole-source multi-year contracting through integrated delivery networks, and point-of-care format extension beyond traditional laboratory infrastructure.
Within the integrated automation tier, Siemens Healthineers and Sysmex Corporation exemplify platform consolidation strategies that capture hospital core laboratory volume through multi-parameter instrument contracts. Abbott Laboratories occupies a distinct position in near-patient testing, extending INR monitoring access beyond centralized settings. Among molecular diagnostic specialists, Bio-Rad Laboratories and Thermo Fisher Scientific represent the precision reagent and analytical platform archetypes serving gene therapy eligibility protocols. These three company groupings—integrated automation, near-patient access, and molecular precision—collectively span the capital intensity spectrum from high-throughput hospital installations to decentralized patient-operated systems.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Sysmex Corporation |
| F. Hoffmann-La Roche Ltd. |
| Abbott Laboratories |
| Bio-Rad Laboratories |
| Thermo Fisher Scientific |
| HORIBA Ltd. |
| Beckman Coulter |
| bioMérieux |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day lead times for chromogenic substrate reagents concentrate pricing power among Austrian and United States plasma fractionators, while hospital procurement committees face inventory carrying costs that compress margin tolerance for lower-tier assay vendors.
Pricing Analysis
Geographic price spreads of 15-25% separate United States metropolitan hospital systems from European reference laboratories for identical factor assay platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by detection precision and automation integration, with academic medical centers absorbing premium tiers for gene therapy protocols. Pricing pressure stems from consolidated purchasing agreements through integrated delivery networks that extract volume discounts from mid-tier suppliers. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraint, while hemophilia treatment centers prioritize analytical precision over unit economics.
Supply Chain Analysis
Plasma-derived reagent supply concentrates in Austria, the United States, and Germany as the chokepoint governing downstream assay availability. Chromogenic substrates, coagulation factor concentrates, and diagnostic-grade citrate tubes constitute critical input dependencies. Single-source vulnerability in recombinant factor production creates exposure to batch contamination events. Distribution runs through national laboratory chains and GPO-affiliated hospital systems with limited direct-to-laboratory alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized hematopathologist training pipelines in Munich and Boston cannot satisfy molecular diagnostic demand expansion, creating persistent capability scarcity that rewards early-mover certification investments and automated platform deployment.
For Market Incumbents: Secure CLIA-compliant molecular diagnostic platforms through sole-source contracting with hemophilia treatment center networks before EU MDR documentation requirements harden competitive moats. Anchor high-throughput automation in Southeast United States integrated delivery networks where procurement consolidation accelerates. Vertical integration into chromogenic substrate manufacturing mitigates reagent input volatility threatening margin stability. For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks commercial entry for novel coagulation factor assays targeting gene therapy eligibility protocols. White-space opportunity concentrates in point-of-care INR systems for home care anticoagulation management, where patient-operated devices bypass hospital laboratory gatekeepers. Direct-to-consumer channel partnerships with pharmacy chains circumvent entrenched GPO procurement barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified diagnostic conglomerates seeking to divest non-core hemostasis reagent portfolios amid EU MDR compliance cost escalation. Five-to-ten-year viability hinges on molecular diagnostic capability depth rather than legacy chromogenic market share. Monitor FDA accelerated approval pathway utilization rates as inflection signal for platform technology valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 technical documentation accelerates European market access for Class IIb coagulation analyzers. |
| Hospital System Partnership | Sole-source agreements with United States hemophilia treatment centers lock in multi-year reagent volume commitments. |
| Software Companion Development | AI-assisted pattern recognition for platelet function analysis differentiates digital pathology platforms in Paris and Lyon academic centers. |
| Reimbursement Strategy | Pharmacogenomic testing guideline expansion opens factor assay indications beyond traditional hemophilia management protocols. |
| Backward Integration | In-house production of chromogenic substrates insulates against Austrian plasma fractionator supply concentration. |
Research Methodology
Initial hypotheses were tested against primary input from hematopathology laboratory directors, hospital procurement committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EU MDR notified body conformity assessments, ClinicalTrials.gov gene therapy protocols, and CMS Medicare laboratory fee schedules. Bottom-up test volume modeling and top-down market size triangulation converged on segment-level estimates.
Variance decomposition across test type, technology platform, end-user setting, and regional regulatory cluster shaped analytical framework construction over the projection horizon. CAGRs were derived from test volume elasticity to hemophilia treatment center expansion and gene therapy protocol adoption curves. Factor assay precision thresholds and CLIA proficiency testing compliance rates served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under base assumptions of sustained FDA accelerated approval pathway utilization and stable EU MDR implementation timelines; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as pharmacogenomic guideline expansion and digital pathology integration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Over-The-Counter Tests Market
Testing Services
Global Enteric Disease Testing Market
Testing Services
Asia-Pacific Viral Clearance Market
Testing Services
Instrument Calibration Services Market
Testing Services
Home DNA Testing Market
Testing Services
Biological Indicator Vials Market
Testing Services
Toxicity Testing Outsourcing Market
Testing Services
Breath Biopsy Testing Market
Testing Services
Influenza Home Testing Market
Testing Services
Medical Device Testing Services Market
Testing Services
North America Endotoxin and Pyrogen Testing Market
Testing Services
Europe Medical Device Testing Market
Testing Services
Vaginal Panel Testing Market
Testing Services
Global Drug Abuse Testing Market
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
Outsourced Testing Services Market