
 Europe Point-Of-Care-Testing (POCT) Market | 2026-2036
Europe Point-Of-Care-Testing (POCT) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Point-Of-Care-Testing (POCT) Market Foresight
The Europe POCT landscape is rebalancing between premium molecular platforms and commodity lateral-flow strips. Abbott Laboratories leverages its vertically integrated glucose monitoring supply chain to dominate retail pharmacy channels. Siemens Healthineers anchors its position through high-throughput immunoassay analyzers deployed in German hospital networks. BioMerieux SA specializes in syndromic infectious disease panels that command premium pricing in acute care settings.
Point-of-care testing encompasses diagnostic assays performed at or near the site of patient care, typically delivering results within 5–30 minutes through portable or benchtop devices using fingerstick capillary blood, nasal swabs, or urine specimens. The technology eliminates centralized laboratory logistics, enabling immediate clinical intervention for time-critical decisions in emergency medicine, chronic disease management, and infectious disease screening. Glucose monitoring and infectious disease testing represent the most mature product categories, with established reimbursement pathways and high penetration in diabetic and respiratory patient populations. Molecular diagnostics and microfluidics platforms capture the fastest expansion, driven by miniaturization of nucleic acid amplification and multiplexing capabilities that previously required laboratory infrastructure.
EMA and notified bodies under the EU Medical Device Regulation enforce escalating clinical evidence requirements for novel POCT platforms, while REACH and RoHS directives constrain material selection in disposable test cartridges. The EU AI Act introduces conformity obligations for algorithm-interpreted results, particularly affecting emerging digital reader systems. Stakeholders must monitor evolving reimbursement parity between decentralized testing and laboratory-based alternatives as health technology assessment bodies recalibrate cost-effectiveness frameworks.
Market Dynamics
The EU Medical Device Regulation is compressing certification timelines and forcing manufacturers to consolidate clinical evidence portfolios, reshaping how near-patient diagnostics reach European hospital emergency departments and retail pharmacy networks.
Growth Catalysts
- Decentralized care mandates:France and the United Kingdom have embedded same-day diagnostic protocols into national chronic disease management frameworks, creating pull-through demand for rapid glucose and infectious disease panels.
- MDR performance validation requirements:The tightened conformity assessment pathway under EU MDR Article 56 is filtering out marginal suppliers, concentrating procurement authority with validated platform vendors in German hospital networks.
- Capillary blood microsampling:Fingerstick collection methods eliminate phlebotomy infrastructure requirements, enabling deployment in community pharmacy settings across Italy and Spain.
Market Restraints
- Notified body capacity constraints:EMA-designated conformity assessment organizations face backlogs exceeding eighteen months for novel POCT platforms, delaying market entry for microfluidics developers.
- Disposable cartridge material costs:REACH and RoHS compliance for thermoplastics and electronic components in single-use test cassettes elevates per-test manufacturing costs relative to centralized laboratory reagents.
- Laboratory-based molecular substitution:Centralized PCR platforms retain cost advantages for high-volume infectious disease screening in integrated health systems, limiting POCT penetration in budget-constrained markets.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden and Norway maintain lower POCT penetration in primary care relative to Western European benchmarks, presenting whitespace for respiratory and cardiac marker platforms.
- EU AI Act algorithmic diagnostics:The forthcoming conformity framework for machine learning-interpreted test results creates a regulatory tailwind for digital reader systems in acute care settings.
- Retail pharmacy channel expansion:Boots and Walgreens-owned pharmacy networks across the United Kingdom are piloting supervised self-testing programs for anticoagulation and lipid monitoring.
Industry Challenges
- Multidisciplinary integration expertise:Health systems lack personnel trained simultaneously in clinical laboratory science, device maintenance, and electronic health record interoperability.
- Legacy analyzer incompatibility:Hospital information systems in older German and French facilities require middleware development to accept POCT data streams, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Point-Of-Care-Testing (POCT) Market |
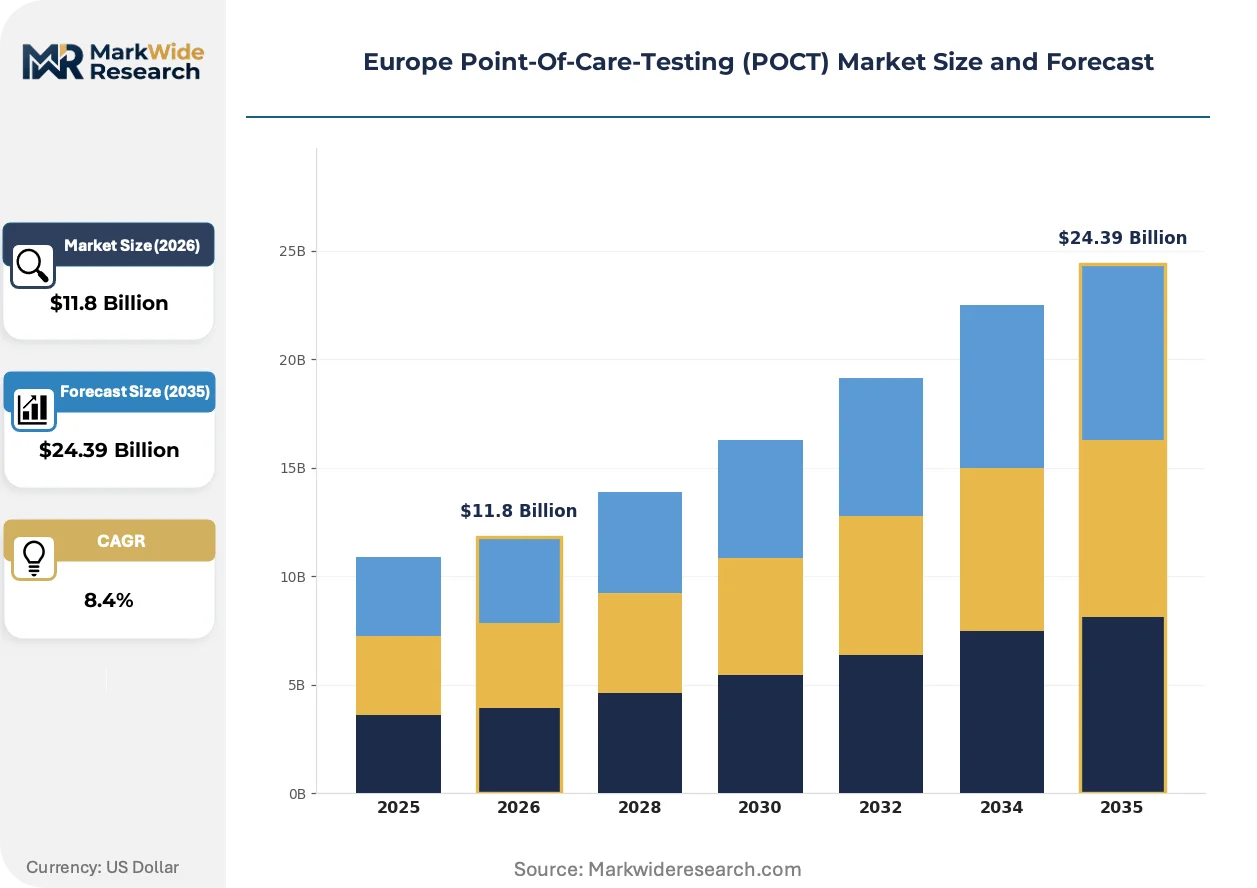
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucose Monitoring, Infectious Disease Testing, Pregnancy Testing, Cardiac Markers End User: Clinics, Homecare, Hospitals, Laboratories Technology: Immunoassay, Molecular Diagnostics, Microfluidics, Lateral Flow Application: Chronic Disease Management, Screening, Disease Diagnosis, Health Monitoring |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Siemens Healthineers AG, Danaher Corporation, Thermo Fisher Scientific Inc., BioMerieux SA, Becton Dickinson and Co., Trinity Biotech Plc, Nova Biomedical Corp., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Point-Of-Care-Testing (POCT) Market Shifts & Advancements
Miniaturization of nucleic acid amplification and multiplexing capabilities is collapsing the functional boundary between near-patient and laboratory diagnostics, compressing result turnaround times from hours to minutes.
Multiplexed syndromic panels is integrating respiratory pathogen detection with antimicrobial resistance markers into single cartridge formats. German emergency departments are adopting these platforms for rapid triage decisions during winter respiratory surges. The technology is integrating previously discrete testing workflows into unified point-of-care protocols, reducing laboratory send-out volumes.
EU AI Act conformity obligations are imposing algorithmic transparency requirements on digital reader systems that interpret lateral-flow test lines. Manufacturers must document training data provenance and performance across demographic subgroups. Acute care settings in France face the steepest compliance burden given their early deployment of smartphone-connected readers.
Pharmacy-led diagnostic supervision is displacing traditional clinician-mediated testing for stable chronic conditions. United Kingdom community pharmacy contracts now reimburse pharmacists for conducting and interpreting POCT results during medication reviews. This channel expansion is most visible in cardiovascular risk assessment programs across England's primary care networks.
Europe Point-Of-Care-Testing (POCT) Market Segmentation
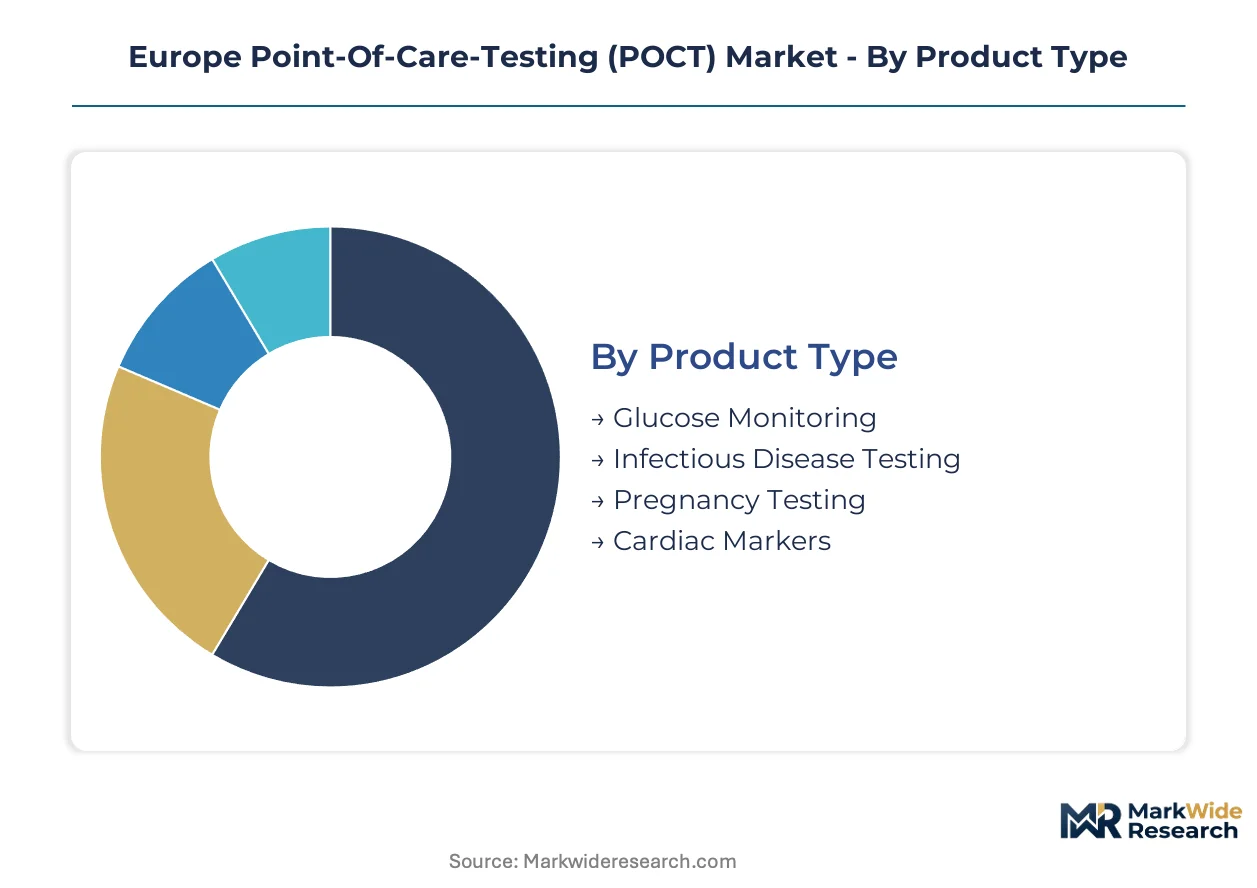
Segmentation reveals how capital requirements, reimbursement pathways, and clinical workflows fragment procurement decisions across European health systems. Product type and technology dimensions expose divergent margin structures and regulatory burdens.
Product Type:
Capital intensity varies sharply: molecular platforms demand substantial upfront instrument investment, while strip-based categories require minimal fixed assets but sacrifice pricing power.
- Glucose Monitoring:Electrochemical biosensors and photometric strips dominate daily diabetic management. German and French retail pharmacy networks absorb the highest prescription volumes, driven by national diabetes framework reimbursement for self-monitoring. MDR Article 56 performance validation has consolidated supplier relationships around vertically integrated glucose meter manufacturers.
- Infectious Disease Testing:Syndromic panels combine respiratory pathogen detection with antimicrobial resistance markers in single-use cartridges. Hospital emergency departments in the United Kingdom and Germany deploy these for rapid triage during winter respiratory surges, compressing laboratory send-out volumes.
- Pregnancy Testing:Lateral-flow hCG strips command commodity pricing in over-the-counter retail channels across Italy and Spain.
- Cardiac Markers:Troponin and BNP rapid assays serve acute coronary syndrome rule-out protocols in Nordic emergency departments.
Glucose monitoring absorbs the bulk of installed capacity; infectious disease testing is expanding most quickly.
End User:
Procurement authority concentrates differently: hospitals negotiate centralized contracts, while homecare and clinic segments fragment across thousands of independent purchasing decisions.
- Hospitals:Emergency departments and intensive care units anchor demand for high-sensitivity cardiac and infectious disease platforms. German hospital networks under Diagnosis-Related Group reimbursement prioritize rapid turnaround to reduce length-of-stay costs.
- Clinics:Primary care networks in France embed same-day diagnostic protocols into chronic disease management frameworks, creating pull-through demand for rapid glucose and lipid panels.
- Homecare:Self-monitoring diabetic populations in the United Kingdom drive subscription replenishment models for glucose test strips.
- Laboratories:Satellite laboratory hubs in Spain and Italy deploy POCT as pre-analytical screening before centralized confirmation.
Hospitals command the highest per-site spending; clinics are gaining share fastest as decentralized care mandates expand.
Technology:
Manufacturing complexity and regulatory evidence requirements stratify competitive moats across technology platforms.
- Molecular Diagnostics:Miniaturized nucleic acid amplification collapses laboratory infrastructure into benchtop devices. French acute care settings deploy smartphone-connected readers under early EU AI Act compliance frameworks, imposing algorithmic transparency documentation burdens.
- Microfluidics:Multiplexed cartridge formats integrate sample preparation, reaction, and detection in disposable cassettes. REACH and RoHS compliance for thermoplastics elevates per-test manufacturing costs relative to centralized laboratory reagents.
- Immunoassay:Chemiluminescent and fluorescent sandwich assays dominate high-throughput hospital installations.
- Lateral Flow:Colloidal gold and fluorescent particle strips serve lowest-cost screening applications with minimal operator training.
Immunoassay platforms retain the largest installed base; microfluidics is climbing the fastest as cartridge miniaturization advances.
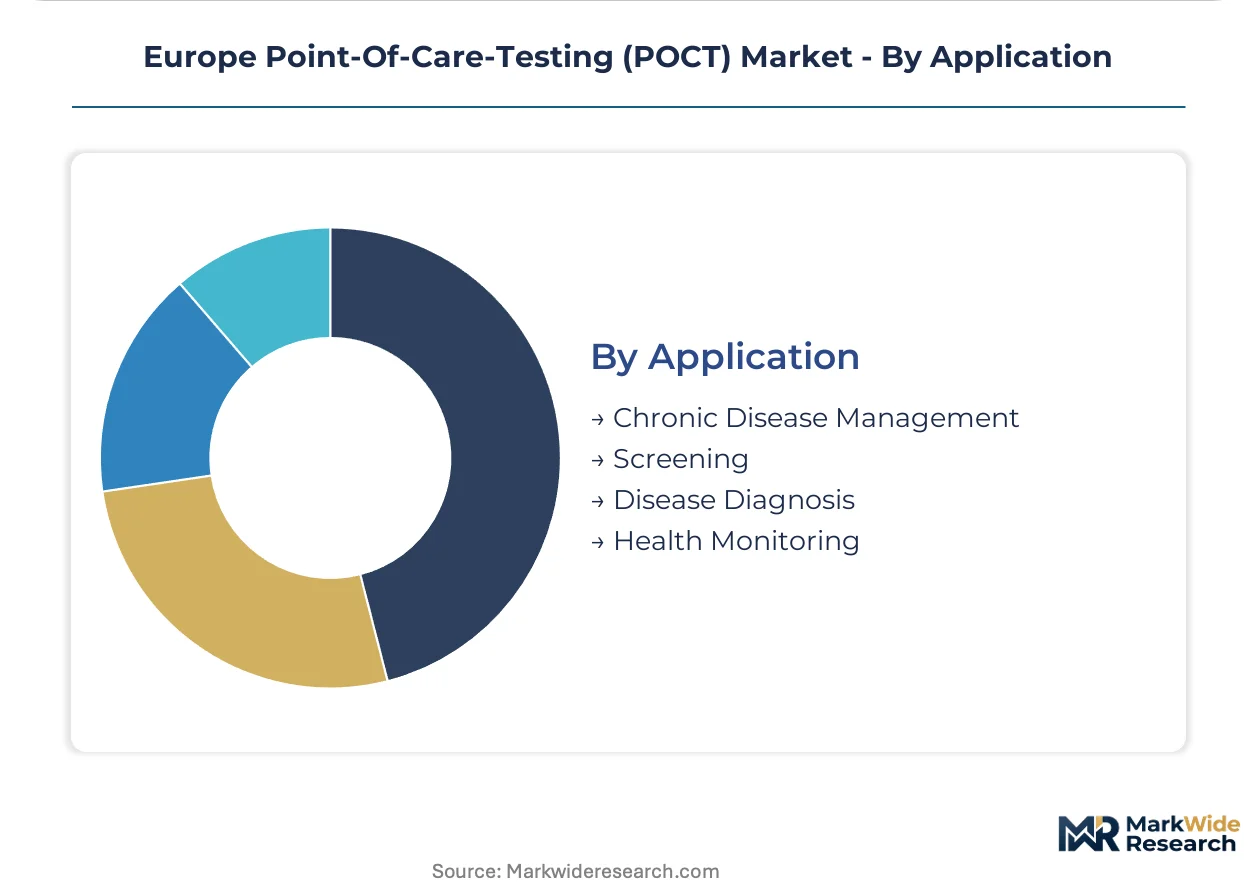
Application:
Clinical utility and reimbursement parity determine addressable market expansion across use cases.
- Chronic Disease Management:Diabetic glucose monitoring and anticoagulation INR testing anchor recurring revenue models. United Kingdom community pharmacy contracts now reimburse pharmacists for conducting and interpreting POCT during medication reviews.
- Screening:Respiratory pathogen and pregnancy screening serve high-volume, low-margin applications.
- Disease Diagnosis:Acute coronary syndrome and sepsis biomarker testing command premium pricing in emergency settings.
- Health Monitoring:Wellness-oriented lipid and HbA1c testing expands in supervised pharmacy self-testing programs.
Chronic disease management generates the steadiest revenue; disease diagnosis captures the highest per-test margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr metropolitan region anchors European POCT manufacturing and procurement networks, with Siemens Healthineers and other diagnostic firms clustering around Düsseldorf and Cologne.
Germany
Hospital emergency departments in Bavaria and North Rhine-Westphalia drive demand for syndromic infectious disease panels under Diagnosis-Related Group reimbursement pressure. The EU MDR Article 56 conformity pathway filters marginal suppliers from German procurement networks. The Rhine-Ruhr corridor concentrates manufacturing for high-throughput immunoassay analyzers deployed across university hospital systems.
United Kingdom
Community pharmacy contracts in England now reimburse pharmacists for conducting POCT during medication reviews, expanding retail channel penetration. NHS England's same-day diagnostic protocols embed rapid testing into chronic disease management frameworks. London and the Southeast anchor pilot programs for supervised self-testing of anticoagulation and lipid markers.
France
Primary care networks prioritize same-day clinical decision-making for diabetic glucose monitoring under national chronic disease frameworks. ANSM enforces escalating clinical evidence requirements for novel POCT platforms entering French acute care settings. The Île-de-France region hosts early deployments of smartphone-connected digital readers facing EU AI Act algorithmic transparency obligations.
Italy
Capillary blood microsampling eliminates phlebotomy infrastructure requirements, enabling deployment in community pharmacy settings across Lombardy and Veneto. Regional health authorities in Northern Italy reimburse rapid glucose panels for diabetic management in primary care. Milan anchors distribution networks for lateral-flow strips serving Mediterranean retail channels.
Sweden
Nordic emergency departments in Stockholm and Gothenburg adopt cardiac marker platforms for acute coronary syndrome rule-out protocols. Swedish primary care maintains lower POCT penetration relative to Western European benchmarks, presenting whitespace for respiratory platform vendors. The country's national pharmaceutical regulator enforces REACH-compliant material standards for disposable test cartridges.
Europe Point-Of-Care-Testing (POCT) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and regulatory validation depth. The vendor base stratifies between vertically integrated glucose monitoring specialists, high-throughput immunoassay platform vendors, and syndromic infectious disease panel developers. Three archetypes dominate: diversified conglomerates with diagnostic divisions, pure-play POCT specialists, and laboratory equipment incumbents extending into near-patient settings. Consolidation pressures favor M&A activity among microfluidics developers facing MDR certification backlogs, while geographic expansion targets underpenetrated Nordic markets.
Among diversified healthcare conglomerates, Abbott Laboratories and Danaher Corporation occupy positions spanning glucose monitoring and molecular diagnostics. Siemens Healthineers anchors the high-throughput hospital installation segment. BioMerieux SA exemplifies the infectious disease specialist archetype, commanding premium positioning in acute care syndromic panels. These three represent distinct competitive vectors: retail pharmacy channel dominance, centralized hospital network penetration, and premium acute care specialization.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers AG |
| Danaher Corporation |
| Thermo Fisher Scientific Inc. |
| BioMerieux SA |
| Becton Dickinson and Co. |
| Trinity Biotech Plc |
| Nova Biomedical Corp. |
| Others |
Supply & Pricing Matrix
Miniaturization of nucleic acid amplification platforms is collapsing per-test manufacturing economics while concentrating procurement authority with German and French hospital networks that command volume discounts. REACH and RoHS compliance for thermoplastics in disposable microfluidic cartridges elevates material costs, forcing tiered sourcing strategies that separate premium-certified from standard-grade components.
Pricing Analysis
Value-based pricing anchors on diagnostic throughput and clinical outcome equivalence to laboratory benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates MDR-validated molecular platforms from commodity lateral-flow strips. Price differentiation hinges on certification grade under EU MDR Article 56 and after-sales service bundling. Cost compression in economy-grade infectious disease panels is intensifying because Italian and Spanish retail pharmacies prioritize lowest-unit-cost procurement. Homecare diabetic populations exhibit highest price sensitivity; German hospital emergency departments show lowest.
Supply Chain Analysis
Workforce availability for precision polymer molding and microelectronics assembly concentrates manufacturing in Germany, Ireland, and Switzerland. Raw material dependencies center on medical-grade thermoplastics, photoresists for biosensor fabrication, and rare-earth phosphors for fluorescent detection. Single-source vulnerability persists for specialized microfluidic chip foundries serving multiplexed cartridge formats. Distribution runs through hospital GPO contracts, pharmacy wholesale networks, and direct-to-clinic logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: notified body capacity bottlenecks under EU MDR extend certification timelines beyond eighteen months, propping pricing power for validated incumbents.
For Market Incumbents: To counter MDR certification backlogs choking microfluidics entrants, accelerate backward integration into captive polymer molding capacity in the Rhine-Ruhr corridor. Prioritize CE marking renewal investments for high-throughput immunoassay platforms before notified body queues deepen.
For New Entrants and Emerging Players: Enter via underpenetrated Nordic primary care networks in Sweden and Norway, where respiratory platform whitespace exceeds Western European benchmarks. Target pharmacy-led diagnostic supervision contracts in United Kingdom community settings. Deploy smartphone-connected digital readers as differentiated go-to-market anchor.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified diagnostic conglomerates seeking acute care specialization. Long-term viability favors microfluidics developers with cleared syndromic panels and established German hospital references. Watch notified body capacity expansion announcements as inflection signal for valuation compression.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Article 56 validation filters marginal suppliers from German procurement networks. |
| Hospital System Partnership | Diagnosis-Related Group reimbursement pressure in Bavaria drives rapid-turnaround adoption. |
| Software Companion Development | EU AI Act algorithmic transparency requirements burden French acute care digital readers. |
| Reimbursement Strategy | NHS England same-day diagnostic protocols embed POCT into chronic disease frameworks. |
| Backward Integration | Captive thermoplastic molding reduces REACH compliance costs for disposable cartridges. |
Research Methodology
Document review covered EU MDR guidance documents, EMA notified body designation records, and hospital procurement databases, complemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at diagnostic manufacturers. Secondary validation drew from ANSM inspection reports, NHS England commissioning frameworks, and REACH compliance disclosures. Bottom-up demand modeling triangulated against top-down market sizing across the projection horizon.
Segmentation outputs reflect product type, technology platform, end-user setting, and application category dimensions modeled throughout the forecast period. CAGRs derived from installed base expansion rates, replacement cycles, and reimbursement parity adjustments. Forecast inputs incorporated MDR certification timeline probabilities and pharmacy channel penetration curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged notified body backlogs or abrupt reimbursement parity withdrawals. Material deviation in EU AI Act implementation timelines or MDR Article 56 enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Fungal Testing Kits Market
Testing Services
Global CA 125 Test Market
Testing Services
Service Laboratory Market
Testing Services
Legionnaire Disease Testing Market
Testing Services
Global Immunoprecipitation Testing Market
Testing Services
Active B12 Test Market
Testing Services
Aerospace and Life Sciences TIC Market
Testing Services
Arthropod-Borne Viral Infections Testing Market
Testing Services
Leukocyte Count Testing Market
Testing Services
Global Coagulation Testing Market
Testing Services
Global Sterility Testing Market
Testing Services
Ige Allergy Blood Tests Market
Testing Services
Nipah Virus (Niv) Infection Testing Market
Testing Services
Monkeypox Testing Market
Testing Services
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market
Testing Services
Hemotransmissive Infections Testing Market