
 Global Vitamin D Testing Market | 2026-2036
Global Vitamin D Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vitamin D Testing Market Foresight
Automated chemiluminescence immunoassay integration into high-throughput analyzers is tilting laboratory economics toward consolidated testing platforms. Siemens Healthineers leverages its Atellica and ADVIA systems to dominate installed-base conversions in integrated delivery networks. Quest Diagnostics sustains volume leadership through its national phlebotomy footprint and direct-to-consumer wellness panels. Abbott Laboratories competes with its Alinity i-series, positioning compact footprint designs for mid-tier hospital laboratories seeking throughput without infrastructure expansion.
Vitamin D testing quantifies circulating 25-hydroxyvitamin D levels, the principal metabolite reflecting nutritional status and hepatic conversion efficiency, typically measured via competitive binding or antibody capture methods with analytical sensitivity thresholds below 4 ng/mL. Immunoassay methods retain dominant share in routine clinical chemistry due to throughput economics and FDA-cleared assay standardization, though liquid chromatography-tandem mass spectrometry segments gain ground where reference laboratories require metabolite specificity for D2-D3 discrimination. Serum sample types anchor reimbursement pathways in Medicare and private payer schedules, while whole blood and saliva alternatives occupy emerging wellness and point-of-care channels with lighter regulatory burdens.
FDA 510(k) clearances and CLIA complexity categorizations govern market entry for new assay platforms, while the European Union's In Vitro Diagnostic Regulation imposes post-market surveillance and clinical evidence requirements that extend certification timelines. ISO 15189 laboratory accreditation standards and College of American Pathologists proficiency testing programs shape quality expectations across diagnostic laboratories and reference sites. Stakeholders must monitor evolving reimbursement thresholds for nutritional screening versus diagnostic indication coding, as payer policy shifts between preventive and disease-state coverage definitions will determine volume trajectories in ambulatory settings.
Market Dynamics
Automated chemiluminescence platforms are compressing laboratory economics toward consolidated high-throughput analyzers, displacing standalone ELISA workstations and reshaping procurement patterns across integrated delivery networks and reference laboratories.
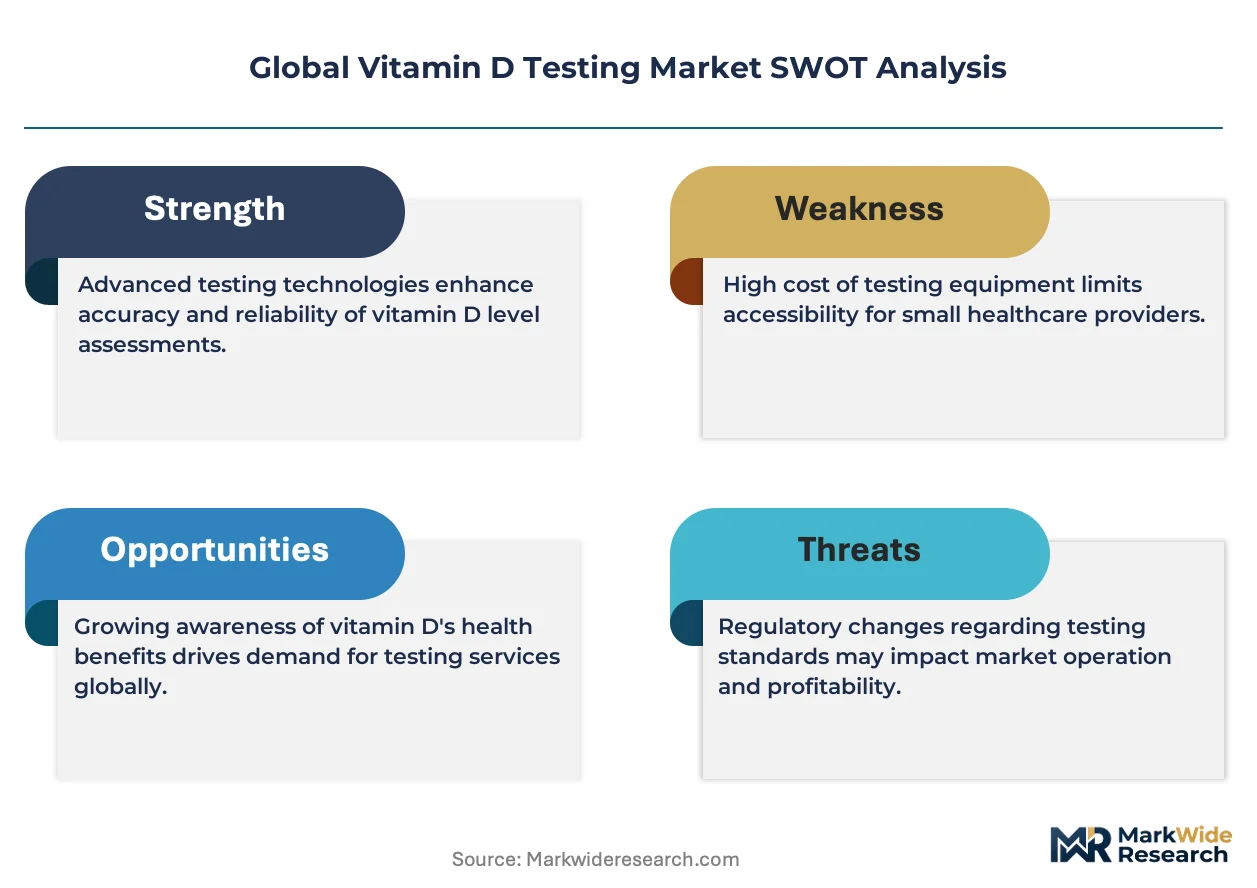
Growth Catalysts
- Aging demographics in Germany, Japan, and the United States:Expanded Medicare reimbursement for metabolic screening panels drives routine 25-hydroxyvitamin D ordering in geriatric populations.
- CLIA-waived point-of-care immunoassay authorization:The FDA's complexity categorization enables primary care physicians to deploy finger-stick testing without laboratory infrastructure.
- Fortified food labeling mandates:Regulatory disclosure requirements in multiple jurisdictions sustain consumer awareness and clinical screening volumes.
Market Restraints
- Reimbursement compression under Medicare's Clinical Laboratory Fee Schedule:Annual fee cuts to nutritional screening codes erode revenue per test for independent laboratories.
- Antibody supply concentration:Capture reagent manufacturing clusters in East Asia create single-source dependencies for competitive binding assays.
- Liquid chromatography-tandem mass spectrometry capital intensity:Reference laboratories face six-figure instrument investments plus specialized operator training for D2-D3 discrimination.
Strategic Opportunities
- Direct-to-consumer wellness channel expansion:Unsupervised testing kits bypass traditional physician ordering in jurisdictions with lighter medical device classification.
- Saliva-based sample collection:Non-invasive alternatives open pediatric and home-health segments previously constrained by venipuncture requirements.
- EU In Vitro Diagnostic Regulation harmonization:Common technical documentation standards reduce country-by-country certification burdens for multinational assay manufacturers.
Industry Challenges
- Proficiency testing program compliance:College of American Pathologists accuracy requirements demand continuous calibration traceability to NIST reference materials.
- Cross-platform standardization gaps:Antibody specificity variations between automated analyzers produce discordant patient results across health system networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vitamin D Testing Market |
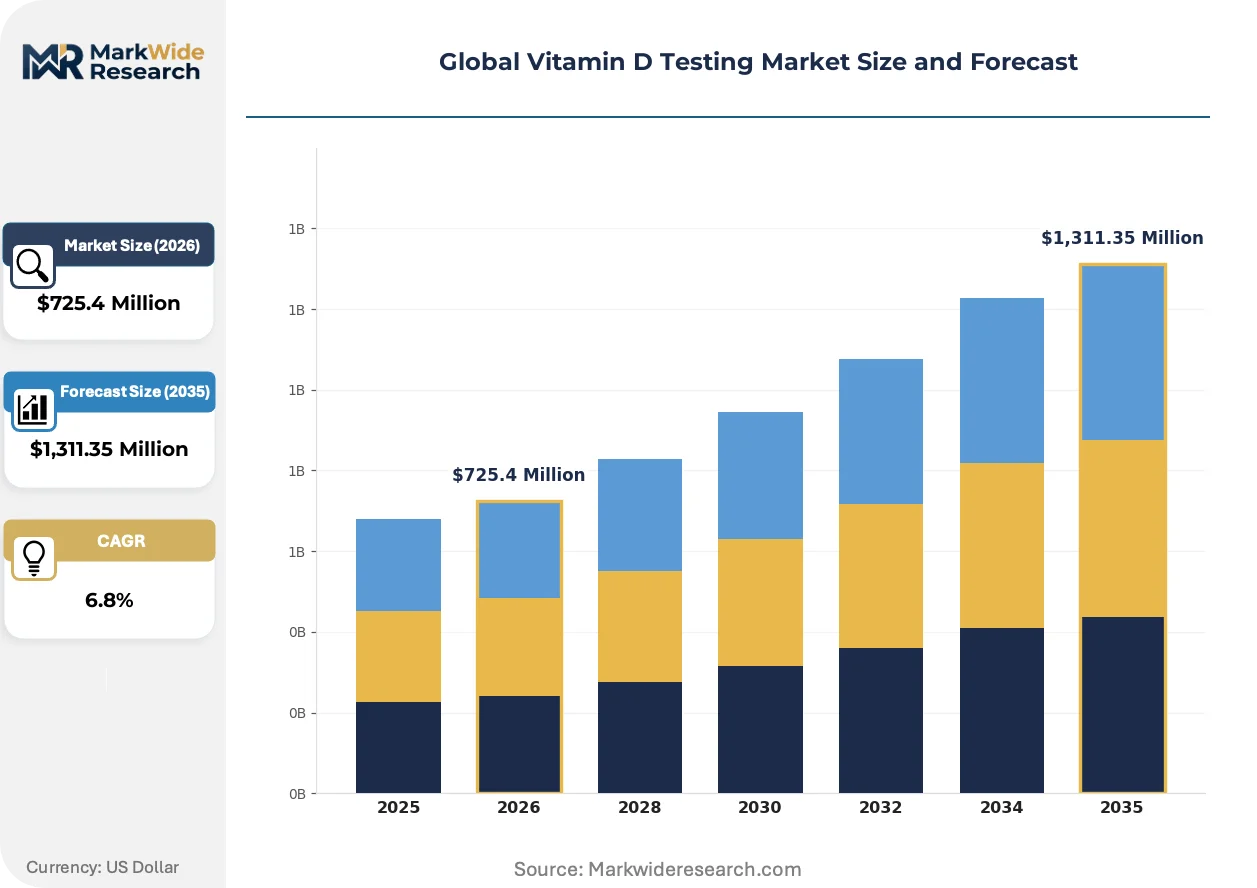
| Market Size in 2026 | $725.4 Million |
| Market Size in 2035 | $1,311.35 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Method: Immunoassay, Liquid Chromatography, Chemiluminescence, Radioimmunoassay, Enzyme-Linked Immunosorbent Assay Sample Type: Serum, Plasma, Whole Blood, Saliva, Urine End User: Diagnostic Laboratories, Clinics, Research Institutes, Wellness Centers, Blood Banks Application: Bone Disorders, Immune Deficiency, Cardiovascular Health, Kidney Diseases, Nutritional Assessment |
| Companies Covered | Siemens Healthineers, Quest Diagnostics, Abbott Laboratories, Beckman Coulter, bioMérieux, DiaSorin S.p.A., Thermo Fisher Scientific, Bio-Rad Laboratories, F. Hoffmann-La Roche Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vitamin D Testing Market Shifts & Advancements
Digital connectivity and assay miniaturization are reconfiguring where testing occurs, shifting volume from centralized laboratories toward distributed point-of-care settings and consumer-direct channels.
Microfluidic cartridge integration into handheld analyzers is digitizing result capture and transmission for remote patient monitoring. Rural clinics and home-health agencies in Australia and Canada are piloting connected devices that stream encrypted data to electronic health records. This architecture compresses turnaround time from days to minutes while eliminating manual transcription errors.
REACH chemical safety dossier requirements are forcing reagent manufacturers to substitute legacy organic solvents in chromatography mobile phases. The European Chemicals Agency's authorization timelines extend reformulation cycles for LC-MS assay kits. Reference laboratories in France and the Netherlands are accelerating validation of aqueous-based separation chemistries to maintain compliance continuity.
Employer-sponsored wellness programs are unbundling preventive screening from traditional health benefit structures. Large self-insured corporations in the United States are contracting directly with diagnostic platforms for quarterly metabolic panels including vitamin D. This channel bypasses physician intermediaries and compressed billing cycles from institutional payers to direct corporate procurement.
Global Vitamin D Testing Market Segmentation
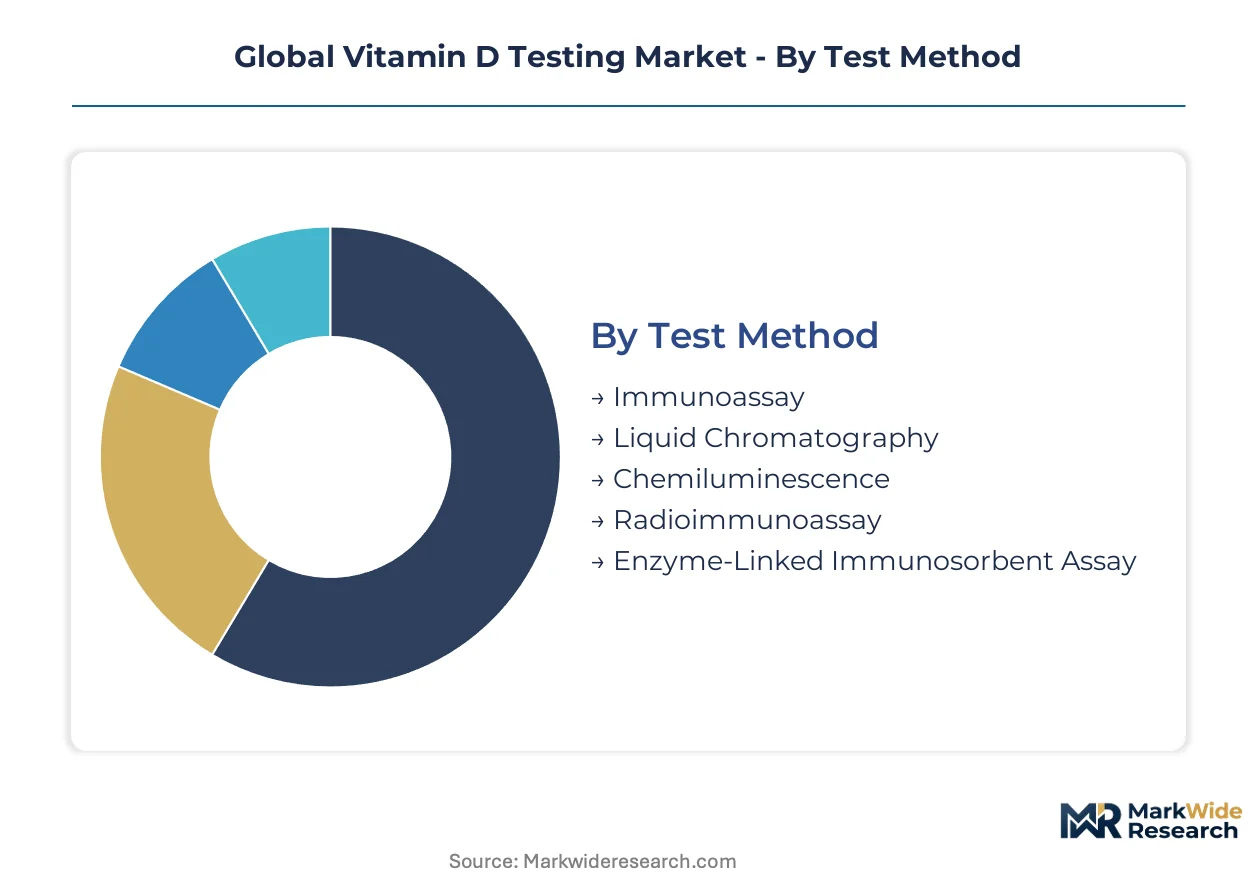
Test method selection dictates capital deployment patterns and reimbursement pathways across laboratory networks. Sample type compatibility shapes point-of-care penetration versus centralized reference laboratory economics. End-user channel dynamics determine pricing power and service intensity requirements for assay manufacturers.
Test Method:
After-sales calibration contracts and reagent supply agreements generate recurring revenue streams that exceed initial instrument margins for automated platforms.
- Immunoassay:Competitive binding and antibody capture methods dominate routine clinical chemistry with throughput economics exceeding 200 tests per hour on automated analyzers. Demand concentrates in hospital laboratories across the United States and Germany where Medicare and statutory health insurance reimburse standardized 25-hydroxyvitamin D panels.
- Chemiluminescence:Acridinium ester and alkaline phosphatase conjugate systems deliver sub-4 ng/mL sensitivity thresholds required for pediatric deficiency screening. Siemens Healthineers and Abbott Laboratories compete for installed-base conversions in integrated delivery networks seeking consolidated high-throughput architectures.
- Liquid Chromatography:Tandem mass spectrometry platforms enable D2-D3 metabolite discrimination for research protocols and forensic toxicology applications.
- Radioimmunoassay:Iodine-125 tracer methods persist in academic reference laboratories with existing gamma counter infrastructure.
- Enzyme-Linked Immunosorbent Assay:Microplate formats serve low-volume clinics and field research settings without automated analyzer capital requirements.
By volume, Immunoassay leads. By growth pace, Chemiluminescence is expanding most quickly.
Sample Type:
Sample stability requirements during transport determine whether testing localizes to bedside or routes through centralized processing hubs.
- Serum:Gold-top tube collection remains the reimbursement anchor for Medicare and private payer schedules in the United States, requiring centrifugation and cold-chain logistics within 72 hours. Quest Diagnostics and LabCorp process millions of annual specimens through national phlebotomy networks.
- Whole Blood:Finger-stick capillary collection enables CLIA-waived point-of-care deployment in primary care clinics without phlebotomy staff. Abbott's i-STAT platform and Siemens' epoc Blood Analysis System compete for placement in rural health clinics across Australia and Canada.
- Plasma:Lithium heparin and EDTA anticoagulant tubes support high-throughput chemistry analyzer integration in European hospital laboratories.
- Saliva:Non-invasive collection opens pediatric and home-health segments previously constrained by venipuncture anxiety and vascular access limitations.
- Urine:Metabolite excretion monitoring serves research applications and nutritional intervention compliance tracking in wellness programs.
Serum specimens command the highest reimbursement rates. Saliva-based alternatives are gaining share fastest in direct-to-consumer channels.
End User:
Procurement authority varies from centralized laboratory purchasing committees to individual physician office decisions, fragmenting vendor sales approaches.
- Diagnostic Laboratories:National reference networks leverage economies of scale in reagent procurement and automated analyzer utilization. Quest Diagnostics sustains volume leadership through its 2,200 patient service center footprint across the United States.
- Clinics:Primary care and endocrinology practices drive routine screening volumes for aging populations with osteoporosis and diabetes comorbidities.
- Research Institutes:Academic medical centers require D2-D3 discrimination and metabolite profiling for nutritional epidemiology studies.
- Wellness Centers:Employer-sponsored programs and direct-to-consumer platforms bypass traditional physician ordering in jurisdictions with lighter medical device classification.
- Blood Banks:Donor screening protocols include vitamin D status assessment for transfusion medicine research and recipient outcome studies.
Diagnostic Laboratories process the highest specimen volumes. Wellness Centers are climbing the fastest as corporate wellness contracts expand.
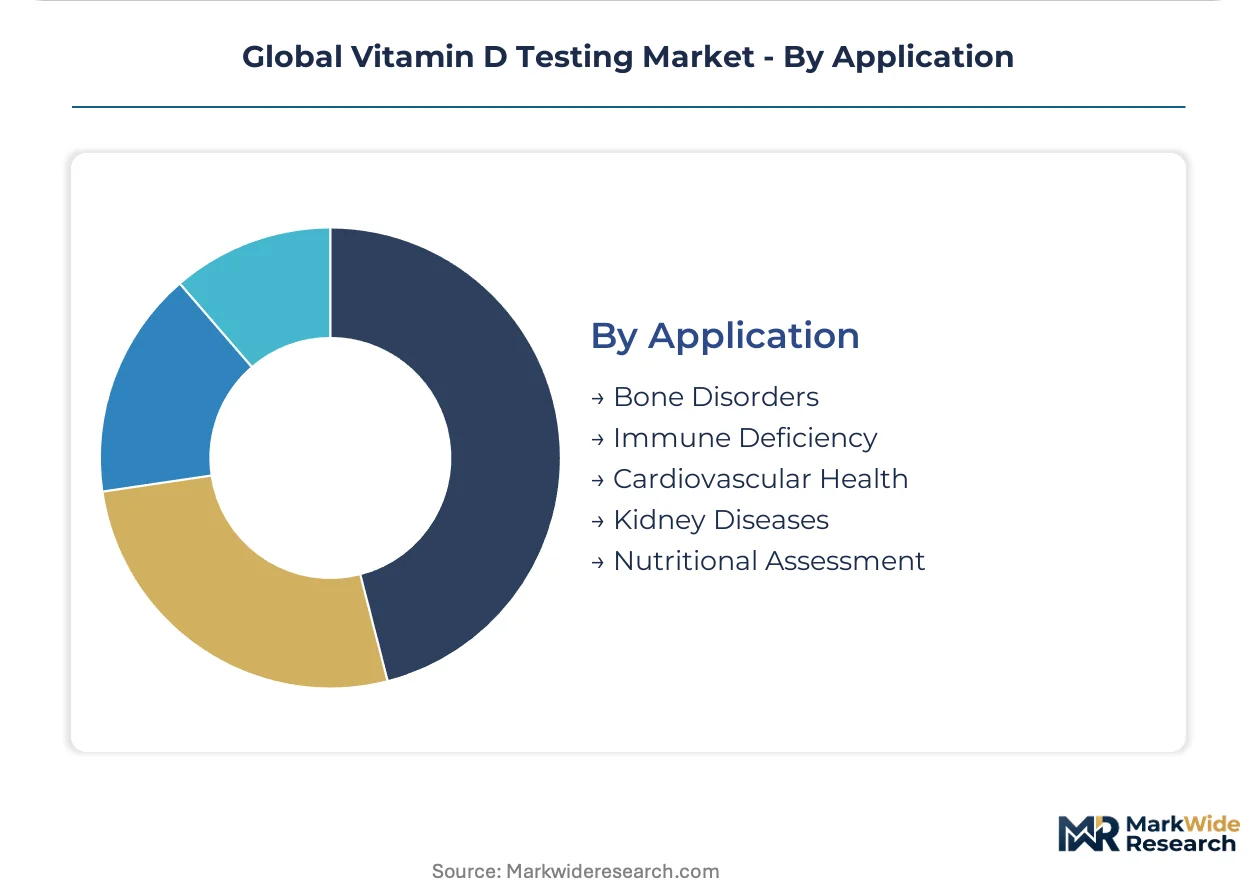
Application:
Clinical indication coding determines whether payers classify testing as preventive screening or disease-state diagnostic, with reimbursement differentials exceeding 40 percent.
- Bone Disorders:Osteoporosis and osteomalacia monitoring drives geriatric screening volumes in Japan, Germany, and the United States where aging demographics expand Medicare-eligible populations.
- Nutritional Assessment:Fortified food labeling mandates and consumer awareness sustain wellness screening demand outside disease-state reimbursement pathways.
- Immune Deficiency:Autoimmune and infectious disease protocols incorporate vitamin D status for treatment response optimization.
- Cardiovascular Health:Hypertension and heart failure management guidelines increasingly reference vitamin D sufficiency targets.
- Kidney Diseases:Chronic kidney disease alters 25-hydroxyvitamin D conversion to active calcitriol, requiring specialized monitoring protocols in nephrology practices.
Bone Disorders indications dominate ordering volume. Nutritional Assessment applications show the steepest expansion trajectory in employer-sponsored wellness channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports diagnostic reagents and automated analyzers to laboratories across the European Union and North American hospital networks. This trade corridor reflects the country's concentration of precision instrumentation manufacturing and its role as a regulatory benchmark setter for IVD certification.
United States
Medicare reimbursement for metabolic screening panels and direct-to-consumer wellness ordering sustain diagnostic volumes in geriatric and employer-sponsored channels. FDA CLIA-waived point-of-care authorizations enable finger-stick testing deployment in primary care clinics without laboratory infrastructure. The Boston-Cambridge biotechnology corridor hosts reference laboratories accelerating LC-MS validation for D2-D3 metabolite discrimination.
Germany
Statutory health insurance mandates for osteoporosis screening and aging demographics expand routine 25-hydroxyvitamin D ordering in ambulatory care. The EU In Vitro Diagnostic Regulation imposes post-market surveillance requirements that extend certification timelines for assay manufacturers. The Rhine-Main metropolitan region concentrates automated analyzer production facilities serving integrated delivery networks across Central Europe.
Japan
PMDA regulatory pathways and national health insurance reimbursement for bone disorder monitoring sustain clinical testing volumes in aging populations. METI industrial policy supports domestic diagnostic platform development to reduce import dependency. The Kansai region around Osaka hosts precision chemistry manufacturing clusters supplying reagents to hospital laboratories throughout East Asia.
Australia
TGA regulatory frameworks and rural healthcare access initiatives drive point-of-care immunoassay adoption in remote clinic networks. Employer-sponsored wellness programs and fortified food labeling awareness sustain consumer-direct testing channels. The Sydney-Melbourne corridor concentrates pathology reference laboratories processing specimens from Pacific Island nations and Southeast Asian medical tourism flows.
United Kingdom
NHS metabolic screening protocols and osteoporosis prevention guidelines sustain hospital laboratory ordering volumes across integrated care systems. MHRA post-Brexit regulatory autonomy creates divergent certification pathways from EU IVDR timelines. The Cambridge-Oxford-London triangle hosts clinical research organizations validating novel saliva-based collection methods for pediatric deficiency screening.
Global Vitamin D Testing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement authority structures. Diagnostic laboratories and integrated delivery networks concentrate purchasing power through multi-year reagent supply contracts, while mid-tier hospital laboratories retain autonomy for analyzer selection. Three archetypes dominate: multinational conglomerates with installed-base leverage, national reference networks with phlebotomy scale, and specialized reagent manufacturers with antibody specificity advantages. Competitive moves center on automated platform consolidation and CLIA-waived point-of-care authorization expansion.
Among diversified health technology conglomerates, Siemens Healthineers and Abbott Laboratories exemplify installed-base conversion strategies through chemiluminescence analyzer ecosystems. Quest Diagnostics occupies a distinct position as a channel-controlling reference network with national specimen collection infrastructure. These three anchors illustrate how scale economics and regulatory authorization breadth determine competitive positioning across laboratory and point-of-care segments.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Quest Diagnostics |
| Abbott Laboratories |
| Beckman Coulter |
| bioMérieux |
| DiaSorin S.p.A. |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| F. Hoffmann-La Roche Ltd |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor's container rate volatility feeds directly into reagent pricing spreads between automated analyzer manufacturers and mid-tier laboratory buyers, compressing margins for antibody-dependent assay kits while amplifying price premiums for consolidated platform vendors with captive logistics networks.
Pricing Analysis
Next-generation chemiluminescence platforms command 40-60 percent price premiums over prior-generation ELISA workstations, while emerging LC-MS tiers occupy ultra-premium positioning for metabolite-specific discrimination. Three-tier pricing structure across premium, standard, and economy levels segments by throughput capacity, CLIA complexity classification, and after-sales calibration bundling. Pricing pressure stems from Medicare Clinical Laboratory Fee Schedule compression on nutritional screening codes, with independent reference laboratories most price-sensitive and integrated delivery networks least sensitive due to volume-negotiated reagent contracts.
Supply Chain Analysis
Supplier-financing facilities extended by East Asian reagent manufacturers to European distributors have lengthened payment terms from 30 to 90 days, straining working capital for mid-tier assay kit vendors. Capture antibody production concentrates in China, South Korea, and Japan, with acridinium ester chemiluminescence substrates and polyclonal antisera drawing from specialized fermentation and conjugation facilities. Single-source vulnerability pervades high-affinity antibody clones, with distribution running through regional distribution hubs serving hospital laboratories and reference networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation in the United States and Germany, where multi-hospital systems negotiate enterprise-wide reagent supply agreements that displace individual laboratory procurement autonomy.
For Market Incumbents: Pre-empt CLIA-waived point-of-care authorization expansion by accelerating finger-stick platform miniaturization before emerging diagnostic entrants capture primary care clinic placement. Defend installed-base positions through backward integration into antibody production, reducing capture reagent dependency on East Asian suppliers. Prioritize Siemens Healthineers and Abbott Laboratories' consolidation playbook: multi-year reagent lock-in contracts with penalty clauses for competitive platform switching.
For New Entrants and Emerging Players: Pursue saliva-based sample collection white space in pediatric and direct-to-consumer wellness channels, where venipuncture constraints and lighter regulatory classification create penetrable entry points. Target employer-sponsored corporate wellness programs with quarterly metabolic panel contracts that bypass traditional physician ordering and institutional payer intermediaries. Lead with digital connectivity integration—encrypted EHR transmission and remote patient monitoring compatibility—as the primary go-to-market differentiator against legacy platform vendors.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates seeking to divest non-core diagnostic reagent portfolios amid EU IVDR compliance cost escalation. Long-term viability centers on platform ecosystems with recurring reagent revenue streams exceeding instrument hardware margins. Watch FDA 510(k) clearance velocity for point-of-care immunoassay platforms as the inflection signal: accelerated authorization timelines indicate regulatory pathway maturation and competitive entry window expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Waived Platform Authorization | FDA complexity categorization enables primary care finger-stick deployment without laboratory infrastructure investment. |
| Backward Integration into Antibody Production | In-house capture reagent manufacturing reduces East Asian single-source dependency and stabilizes supply continuity. |
| Saliva-Based Collection Method Validation | Non-invasive sampling opens pediatric deficiency screening and home-health segments previously constrained by venipuncture. |
| Enterprise Reagent Supply Contracting | Multi-year agreements with integrated delivery networks lock in volume commitments and displace competitor installed bases. |
| Digital Connectivity Integration | Encrypted EHR streaming and remote patient monitoring compatibility differentiate platforms in distributed care settings. |
Research Methodology
Operator-level perspectives from clinical laboratory directors, IVD regulatory affairs specialists, hospital procurement committee members, and point-of-care platform engineers anchored the qualitative base. Secondary validation drew from FDA 510(k) premarket notification databases, EU IVDR technical documentation filings, CMS Medicare reimbursement schedules, and College of American Pathologists proficiency testing program results. Bottom-up test volume modeling across method, sample type, and end-user segments triangulated against top-down market sizing from automated analyzer installed-base estimates and reagent consumption metrics.
Scenario-bracketing framed demand projections across the analysis window, with baseline, upside, and downside cases reflecting reimbursement policy stability, CLIA-waived authorization expansion velocity, and antibody supply chain disruption probability. Segmentation dimensions modeled encompassed test method technology tier, sample type compatibility, end-user channel procurement authority, and geographic regulatory cluster. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns, with inputs including aging demographic trajectories in Germany, Japan, and the United States, and employer-sponsored wellness program penetration rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by emerging point-of-care platform vendors or diversified technology conglomerates entering from adjacent diagnostic segments would shift outcomes. Macroeconomic recession compressing discretionary wellness spending, regulatory reclassification of nutritional screening codes, or breakthroughs in continuous monitoring biosensors would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Toxicology Testing Services Market
Testing Services
Asia Pacific Pregnancy and Ovulation Testing Market
Testing Services
Bimetallic Thermometer Market
Testing Services
Metabolic Biomarker Testing Market
Testing Services
Special Coagulation Tests Market
Testing Services
Beta-Hydroxybutyrate Testing Market
Testing Services
Cannabis Testing Services Market
Testing Services
Breath Biopsy Testing Market
Testing Services
Leukocyte Count Testing Market
Testing Services
Activated Partial Thromboplastin Test Market
Testing Services
Pharmaceutical Dissolution Testing Services Market
Testing Services
Self-Urinary Infection Testing Market
Testing Services
Drug Testing Equipment Market
Testing Services
Global HPV Testing and Pap Test Market
Testing Services
Global Endotoxin and Pyrogen Testing Market
Testing Services
Global HIV Self Test Kits Market