
 Global Anti Thrombin III Testing Market | 2026-2036
Global Anti Thrombin III Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti Thrombin III Testing Market Intelligence
The adoption of reagent rental and instrument leasing models is reshaping competitive positioning by lowering the capital barrier for smaller laboratories. Siemens Healthineers AG leverages its extensive portfolio of automated coagulation analyzers to secure long-term contracts with high-volume hospitals. In contrast, bioMerieux SA differentiates through specialized assays and systems tailored for complex hemostasis testing. Abbott Laboratories competes with a broad diagnostic platform, integrating coagulation tests into its core lab offerings.
Anti Thrombin III testing involves immunoassays or chromogenic substrate assays to quantify the activity of the serine protease inhibitor, antithrombin. Its primary purpose is to diagnose hereditary or acquired antithrombin deficiency, a condition predisposing individuals to venous thromboembolism. Reagents and kits constitute the largest product segment, driven by their recurring consumption in high-throughput hospital and commercial laboratories. While instruments represent a significant initial investment, their value is realized over time, with hospitals being the primary end-user segment.
Regulatory frameworks from the US FDA, Europe's EMA under the In Vitro Diagnostic Regulation (IVDR), and China's NMPA govern market access. These bodies enforce stringent requirements for analytical performance, clinical validation data, and quality systems for all diagnostic assays. Future development hinges on integrating these tests into fully automated hemostasis platforms and potentially expanding into near-patient testing environments.
Market Dynamics
The central structural force shaping the market is the drive toward total laboratory automation. This push, a response to skilled labor shortages and demands for higher testing throughput in hospitals, is compelling the integration of hemostasis testing into consolidated, multi-disciplinary diagnostic platforms.
Growth Catalysts
- Automated Systems:The development of high-throughput automated coagulation analyzers reduces manual intervention and improves turnaround times, supporting adoption in high-volume hospital laboratories across the United States and Europe.
- Clinical Need:A rising prevalence of venous thromboembolism and other thrombotic disorders, particularly within aging populations in developed nations like Germany and Japan, directly increases the volume of antithrombin tests ordered.
- Regulatory Standards:Stringent performance and validation requirements under frameworks like the US FDA's premarket approval process and Europe's IVDR elevate the quality bar, favoring manufacturers with robust clinical data and quality systems.
Market Restraints
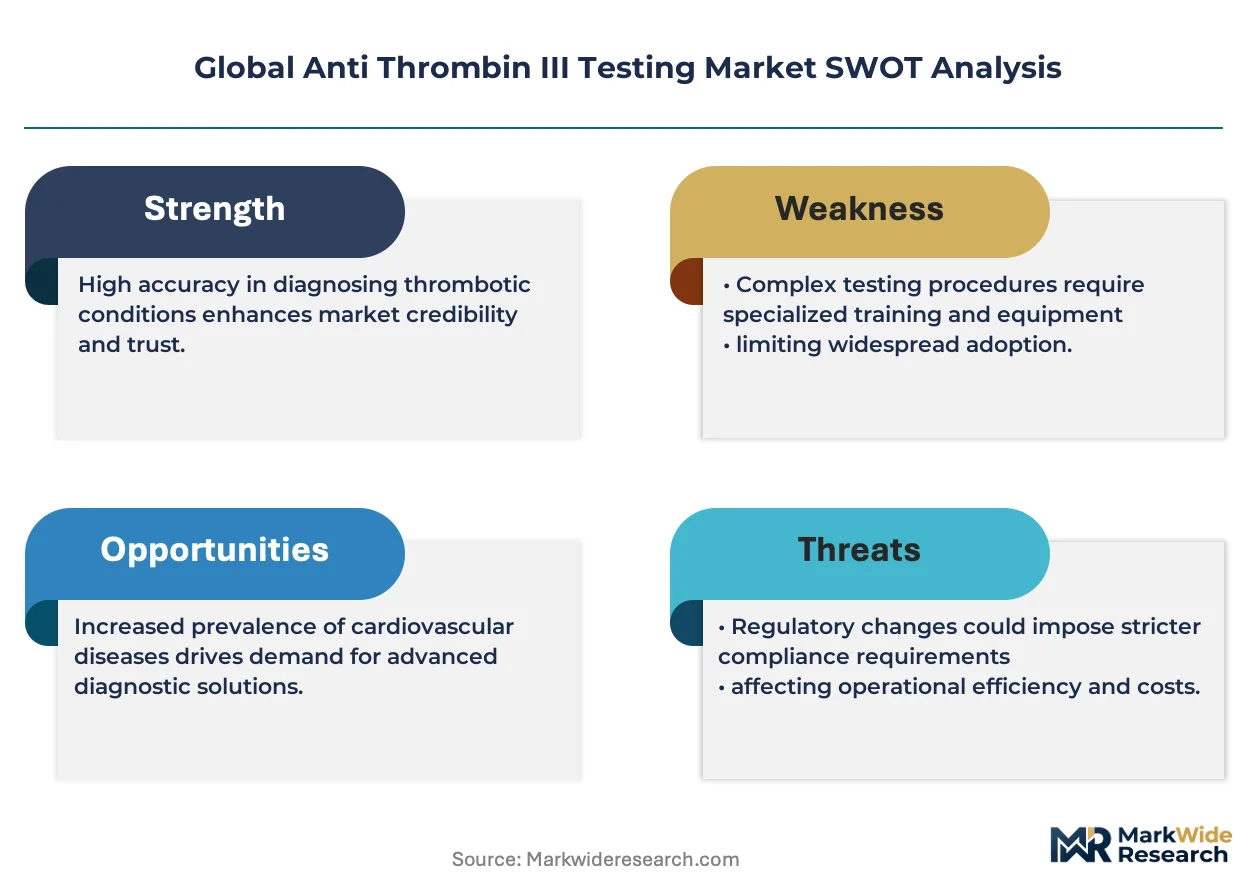
- High Capital Costs:The significant initial investment required for fully automated hemostasis platforms presents a substantial barrier to entry for smaller clinical laboratories and healthcare facilities with constrained budgets.
- Alternative Diagnostics:The availability of genetic tests for identifying hereditary causes of thrombophilia, such as Factor V Leiden mutations, provides an alternative diagnostic route that can sometimes circumvent the need for functional antithrombin protein assays.
- Reimbursement Variability:Inconsistent and often low reimbursement rates for specialized coagulation assays in certain national healthcare systems can disincentivize routine testing and limit market access for newer, more advanced assays.
Strategic Opportunities
- Emerging Market Penetration:Significant white space exists in markets such as Brazil and India, where modernizing healthcare infrastructure and a growing middle class are creating new demand for advanced diagnostic testing for coagulation disorders.
- Point-of-Care Development:Creating reliable point-of-care (POC) antithrombin tests would enable rapid diagnostics in critical settings like intensive care units or operating rooms, expanding testing beyond the central lab.
- Data Integration:Integrating assay results with electronic health records (EHR) and clinical decision support systems offers a pathway to add value by contextualizing antithrombin levels within a patient's broader clinical profile.
Industry Challenges
- Specialized Skill Gaps:A persistent shortage of medical technologists with specialized training in hemostasis and the expertise to operate and troubleshoot complex automated analyzers acts as an operational constraint for laboratories.
- Assay Standardization:A lack of global standardization across different manufacturers' chromogenic and immunoassay methods for antithrombin activity can cause inter-laboratory result variability, complicating patient management and clinical trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti Thrombin III Testing Market |
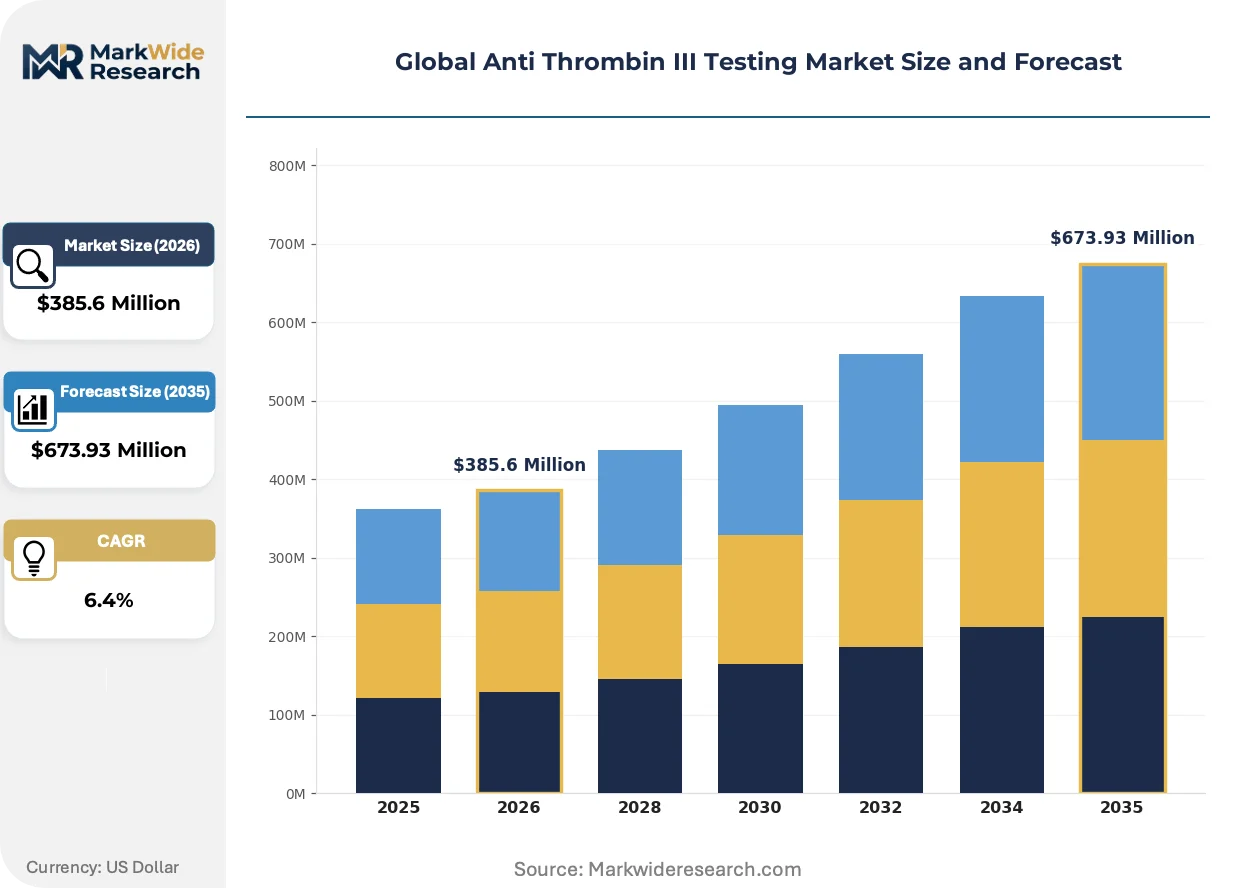
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Instruments, Software Application: Diagnostics, Monitoring, Research, Therapeutics End User: Hospitals, Laboratories, Clinics, Blood Banks Distribution Channel: Direct Sales, Distributors, E-commerce, Resellers |
| Companies Covered | F. Hoffmann-La Roche Ltd, Siemens Healthineers AG, Abbott Laboratories, Thermo Fisher Scientific Inc., Danaher Corporation, Sysmex Corporation, bioMerieux SA, Horiba Abx SAS, HemoSonics LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti Thrombin III Testing Market Strategic Shifts & Innovations
The convergence of advanced assay technologies with sophisticated data management is redefining the workflow and clinical utility of hemostasis diagnostics. This integration enables more comprehensive patient profiling while demanding greater analytical rigor from manufacturers and laboratories alike.
Multiplex assay technologies combine multiple measurement principles, such as chromogenic and immunoturbidimetric methods, on a single platform. High-volume clinical laboratories are adopting these systems to consolidate their test menus and improve efficiency. This technology is hybridizing traditional single-analyte testing with broader coagulation panel diagnostics, enabling a more complete assessment from one patient sample.
Europe's In Vitro Diagnostic Regulation (IVDR) imposes significantly more stringent requirements for clinical evidence, risk management, and post-market surveillance. This regulation forces manufacturers to conduct extensive new validation studies and update technical documentation for existing products. The diagnostic reagent and kit segment is most affected, with some companies rationalizing their portfolios to focus on high-volume assays that justify the compliance investment.
A preference for integrated core laboratory platforms over standalone specialty analyzers is altering procurement patterns in large healthcare networks. Hospital systems, particularly in the United States, are seeking to consolidate vendor contracts to simplify service, inventory management, and data connectivity. This trend disrupts the market for specialized hemostasis instrument vendors, creating an advantage for large diagnostic corporations that offer a broad, integrated instrument portfolio.
Global Anti Thrombin III Testing Market Segmentation
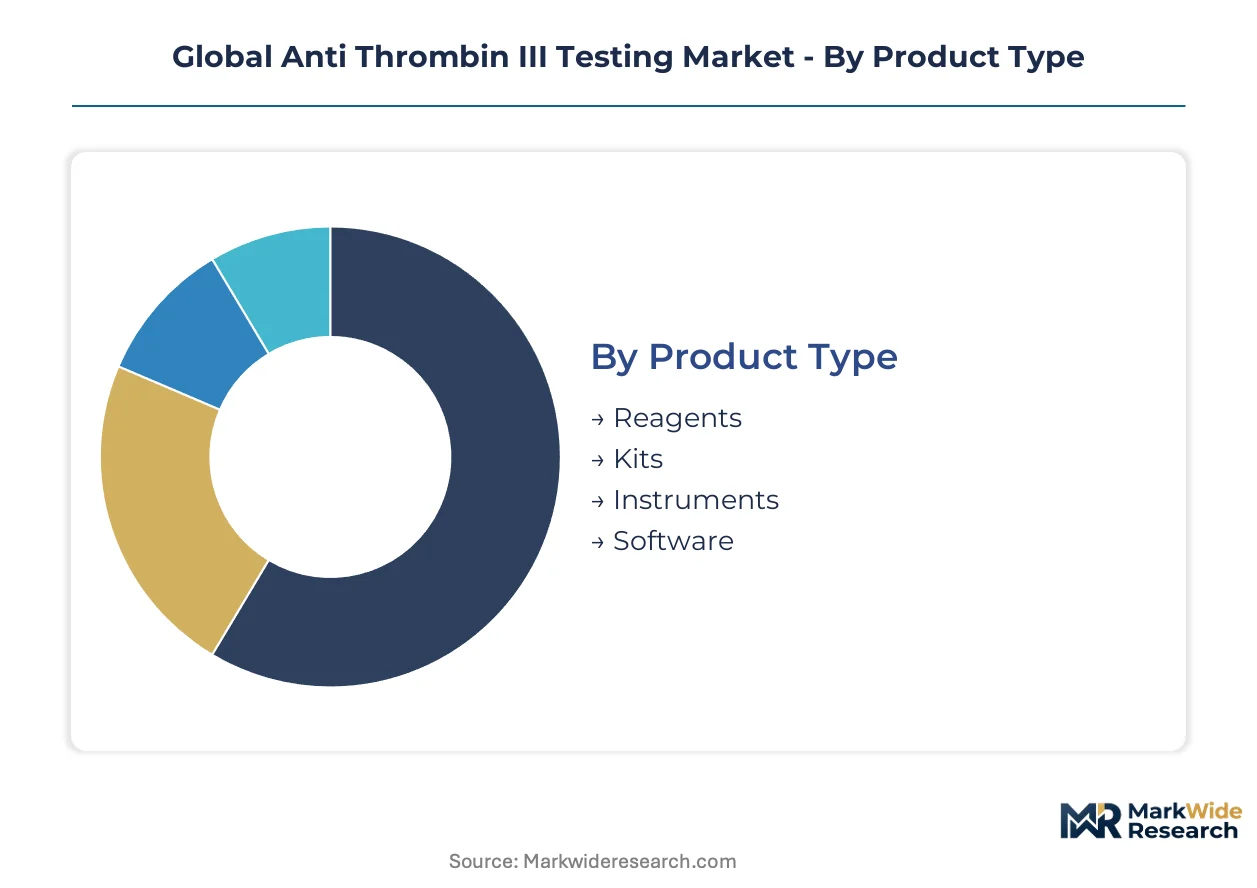
Understanding the segmentation of the Anti Thrombin III Testing Market is crucial for identifying key growth vectors and strategic investment areas. This granular view reveals how different product types, applications, end-users, and distribution channels contribute to the market's overall structure and evolution.
Product Type:
The product type segmentation reveals a market balancing mature diagnostic staples with emerging digital solutions.
- Reagents:These are chemical compounds or mixtures specifically formulated for immunoassays or chromogenic substrate assays to quantify antithrombin activity. Demand concentrates heavily in high-throughput hospital and commercial laboratories due to their recurring consumption and essential role in every test.
- Kits:Pre-packaged combinations of reagents, calibrators, controls, and consumables designed for specific antithrombin testing methodologies. These kits streamline laboratory workflows and ensure consistency across testing sites.
- Instruments:Automated coagulation analyzers designed to process antithrombin III tests with minimal manual intervention, offering high throughput and integration capabilities. Hospitals, particularly in the United States and Europe, drive demand for these systems, seeking efficiency and reduced labor costs.
- Software:Digital solutions for instrument control, data management, result interpretation, and integration with laboratory information systems (LIS) or electronic health records (EHR).
Reagents retain volume leadership; Software holds the steepest expansion curve.
Application:
Volume distribution across applications highlights the primary clinical utilities for antithrombin III testing.
- Diagnostics:The primary application involves the initial identification of hereditary or acquired antithrombin deficiency in patients presenting with venous thromboembolism or a family history of thrombophilia. High incidence of thrombotic disorders in developed nations drives this segment.
- Monitoring:This application focuses on assessing the efficacy of anticoagulant therapies, tracking disease progression, or evaluating antithrombin levels during critical conditions like sepsis or disseminated intravascular coagulation. Growing emphasis on personalized medicine supports monitoring applications.
- Research:Antithrombin III tests are utilized in academic and pharmaceutical research to investigate coagulation pathways, develop new therapeutic agents, and understand the pathophysiology of thrombotic disorders.
- Therapeutics:This segment involves testing to guide the administration of antithrombin concentrate in patients with severe deficiency, ensuring appropriate dosing and treatment outcomes.
While Diagnostics dominates current utilization, Monitoring shows significant potential for expanded routine use.
End User:
Procurement patterns among end-users reflect varying scales of operations and testing requirements.
- Hospitals:These institutions represent the largest end-user segment, conducting a high volume of antithrombin III tests for inpatient and emergency care, pre-surgical screening, and critical care management. The drive for total laboratory automation within hospitals influences instrument procurement decisions.
- Laboratories:This segment includes commercial reference laboratories, specialized hemostasis laboratories, and public health laboratories that perform a wide range of coagulation tests, often receiving samples from smaller clinics. Cost-efficiency and high-throughput capabilities are critical for these centralized facilities.
- Clinics:Smaller outpatient clinics and physician offices may perform basic coagulation screening, but often send specialized antithrombin III tests to larger reference laboratories.
- Blood Banks:These facilities utilize antithrombin III testing primarily for screening plasma donations, ensuring product safety and quality for transfusion purposes.
The largest segment, Hospitals, continues to drive demand, supported by expanding services in specialized Laboratories.
Distribution Channel:
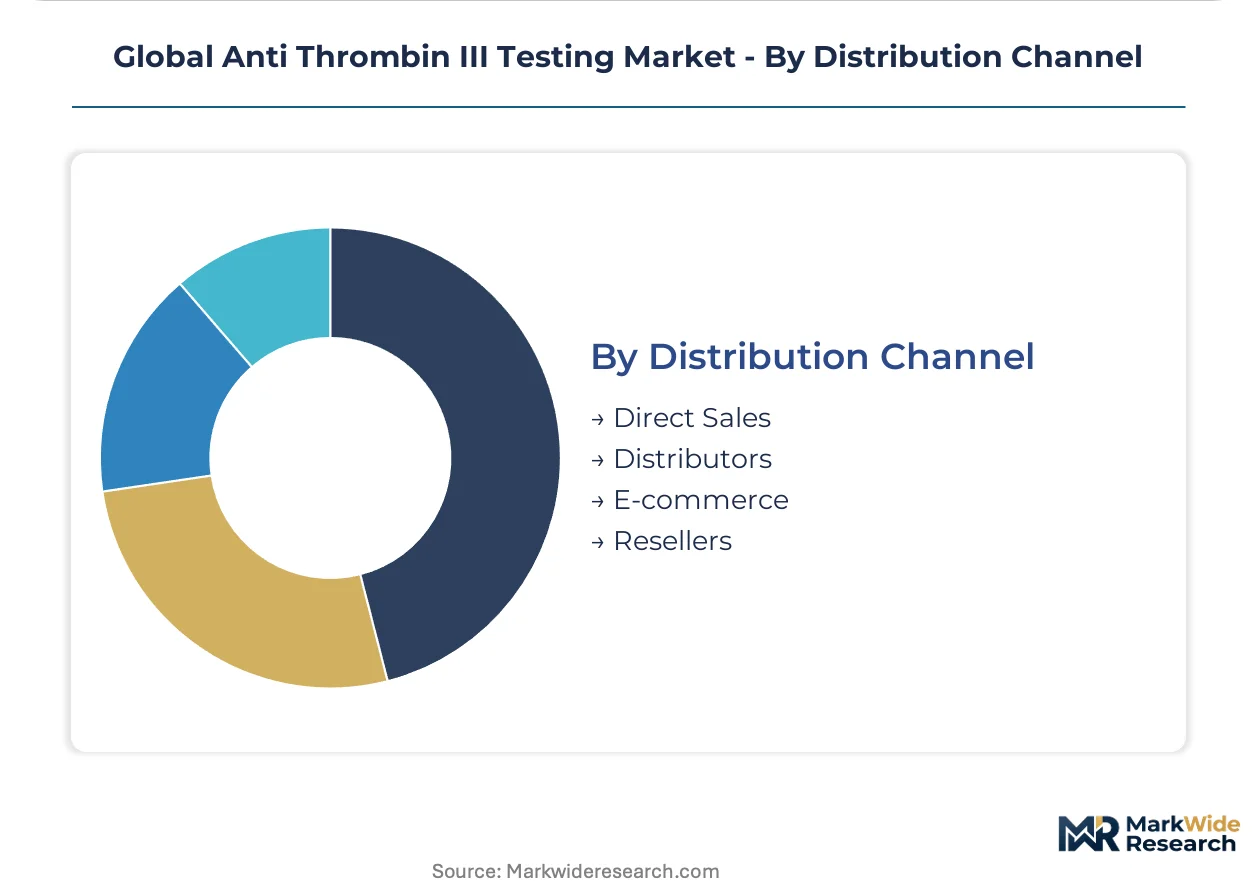
Supply concentration for antithrombin III testing products varies significantly across established and emerging distribution channels.
- Direct Sales:Manufacturers directly sell and provide support for their instruments and high-volume reagent contracts to large hospital systems and major commercial laboratories. This channel facilitates complex negotiations and long-term service agreements.
- Distributors:Independent distributors handle sales and logistics for a broader range of products, reaching smaller laboratories, clinics, and regional healthcare networks. Distributors offer localized support and market access for manufacturers.
- E-commerce:Online platforms facilitate the purchase of reagents, kits, and consumables, particularly for smaller orders or specialized research products. E-commerce offers convenience and broader product accessibility.
- Resellers:These entities often provide value-added services, bundling antithrombin III testing products with other diagnostic solutions or integrating them into broader laboratory platforms.
Traditional channels like Direct Sales and Distributors remain foundational for market reach, while E-commerce offers new avenues for niche products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The push for standardized diagnostic quality and improved patient outcomes drives regional market dynamics for antithrombin III testing. Governments and healthcare systems prioritize accurate thrombotic disorder diagnosis to reduce healthcare burdens. This focus stimulates investment in advanced testing infrastructure across developed and emerging economies globally.
United States
Demand for antithrombin III testing in the United States stems from high procedural volumes and a well-established healthcare infrastructure. The US FDA's stringent premarket approval process ensures high quality and performance for diagnostic assays. Major hospital networks in cities like New York and Los Angeles drive significant adoption of automated coagulation analyzers.
Germany
Aging populations and a rising prevalence of venous thromboembolism fuel the need for antithrombin III testing in Germany. Europe's IVDR mandates rigorous clinical validation and post-market surveillance for diagnostic products. Specialized hemostasis laboratories in regions such as Bavaria and North Rhine-Westphalia actively integrate advanced testing platforms.
Japan
Japan's market for antithrombin III testing benefits from its rapidly aging demographic and a strong emphasis on preventive healthcare. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures strict regulatory oversight for in vitro diagnostics. Major medical centers in Tokyo and Osaka are early adopters of high-throughput automated systems for coagulation analysis.
China
Modernizing healthcare infrastructure and a growing middle class in China stimulate new demand for advanced diagnostic testing. The National Medical Products Administration (NMPA) governs market access with evolving requirements for diagnostic assays. Large commercial laboratories in cities like Shanghai and Beijing are expanding their capabilities for specialized coagulation panels.
Brazil
Brazil represents an emerging market with significant potential for antithrombin III testing, driven by healthcare modernization initiatives. ANVISA, the national health surveillance agency, regulates diagnostic products to ensure safety and efficacy. Major urban centers such as São Paulo and Rio de Janeiro are witnessing increased investment in advanced laboratory equipment.
Global Anti Thrombin III Testing Market Key Industry Players
On the supply side, the industry is characterized by a mix of large, diversified diagnostic corporations and specialized hemostasis players. The market structure favors companies offering integrated diagnostic platforms that consolidate multiple testing modalities. Strategic archetypes include broad portfolio providers, niche assay developers, and instrument-focused manufacturers. Companies are engaging in strategic partnerships and portfolio diversification to enhance their market presence and product offerings.
Large diagnostic corporations, such as Siemens Healthineers AG and Abbott Laboratories, exemplify providers with extensive portfolios of automated coagulation analyzers. Siemens Healthineers AG leverages its broad instrument base to secure long-term contracts with high-volume hospitals. Abbott Laboratories integrates coagulation tests into its core lab offerings, addressing a wide range of diagnostic needs across its broad platform. bioMerieux SA occupies a position as a specialized assay and system provider, focusing on complex hemostasis testing solutions tailored for specific clinical requirements. These entities collectively anchor significant market share through their established distribution networks and advanced technological capabilities.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers AG |
| Abbott Laboratories |
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Sysmex Corporation |
| bioMerieux SA |
| Horiba Abx SAS |
| HemoSonics LLC |
| Others |
Cost & Logistics Intelligence
Underutilized specialized instrument capacity in smaller laboratories influences supplier behavior, driving flexible pricing and leasing models to maximize platform adoption. This dynamic ensures manufacturers maintain market presence while addressing budget constraints of diverse healthcare providers.
Pricing Analysis
Certification level (FDA/IVDR compliance) creates the primary spread in the Anti Thrombin III testing market, differentiating products by regulatory approval and validated performance. The dominant pricing structure is a hybrid of contract-based long-term agreements for instruments and per-unit transactional models for reagents. Pricing softness stems from inconsistent reimbursement rates for specialized assays across national healthcare systems. Smaller clinical laboratories exhibit the highest price sensitivity, driven by constrained budgets and significant initial investment costs.
Supply Chain Analysis
Export controls on precision electronic components for advanced diagnostic instruments could restrict global supply flows for Anti Thrombin III testing platforms. Manufacturing concentration for these complex systems resides primarily in North America, Europe, and East Asia. The supply chain relies on specialized enzymes for chromogenic assays and precision electronic components for automated analyzers. Single-source vulnerability for critical reagents presents a structural risk. Distribution runs through direct sales to large hospital networks and independent distributors serving smaller clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Anti Thrombin III testing market represents a high-growth disruption driven by the ongoing shift towards total laboratory automation. This technological inflection reshapes diagnostic workflows and system requirements.
For Market Incumbents: Entrench existing market share by deepening integration of Anti Thrombin III assays into consolidated, multi-disciplinary diagnostic platforms. Secure long-term contracts with high-volume hospital systems through reagent rental and instrument leasing models, mitigating high capital costs. This strategy counters the threat posed by specialized skill gaps in laboratories and evolving regulatory standards like Europe's IVDR. Invest in advanced automation and data integration with electronic health records for enhanced clinical utility.
For New Entrants and Emerging Players: Point-of-care (POC) antithrombin tests for critical care settings represent a highly penetrable entry point, addressing rapid diagnostic needs beyond central labs. Developing specialized assays tailored for complex hemostasis testing also offers white space against broad platform providers. Targeting modernizing healthcare infrastructure in emerging markets like Brazil and India provides significant growth opportunities. A go-to-market strategy focusing on user-friendly, reliable POC solutions can capture early adoption.
For Investors and Strategic Acquirers: Long-term, this sits as a critical diagnostic consolidation play because of increasing clinical need for thrombotic disorder diagnosis and the drive towards laboratory automation. Acquisition targets should include specialized hemostasis assay developers with unique intellectual property or companies pioneering reliable point-of-care testing solutions. Integrating data management software providers also offers strategic value. The signal to watch is the expansion of antithrombin testing into new clinical indications, particularly within personalized medicine.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate Coagulation into Core Lab Platforms | Consolidates test menus for high-volume hospitals, improving efficiency and reducing vendor complexity. |
| Develop Point-of-Care (POC) Assays | Enables rapid diagnostics in critical care, expanding testing beyond central laboratory environments. |
| Invest in Data Integration Solutions | Contextualizes antithrombin levels within EHRs, enhancing clinical decision support and patient management. |
| Expand into Emerging Markets | Addresses unmet demand in regions modernizing healthcare infrastructure, like Brazil and India. |
| Advance Multiplex Assay Technologies | Combines multiple measurement principles for comprehensive patient profiling from single samples. |
Research Approach
Operator-level perspectives from hospital lab directors, hemostasis specialists, and diagnostic instrument engineers anchored the qualitative base for this analysis. Primary interviews with these industry stakeholders provided crucial insights, validated against extensive secondary research. Secondary data sources included US FDA filings, Europe's IVDR guidance documents, and scientific literature from coagulation journals. A rigorous bottom-up and top-down triangulation approach ensured data consistency and accuracy.
Scenario-based modeling framed the market projection across the analysis window, considering various growth trajectories. The analytical framework segmented the market by product type, application, end-user, distribution channel, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected market drivers. Key industry-specific forecast inputs included the rising prevalence rates of venous thromboembolism and the increasing adoption rates of automated coagulation platforms.
Practitioners should monitor evolving regulatory frameworks and technological breakthroughs in alternative diagnostics for early signals of market shifts. These forecasts reflect underlying assumptions regarding clinical practice and healthcare infrastructure development. Material shifts in reimbursement policies or assay standardization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Leukocyte Count Testing Market
Testing Services
Alcohol Breathalyzer and Drug Testing Equipment Market
Testing Services
Europe Mass Spectrometry Market
Testing Services
Tuberculosis Testing Market
Testing Services
Pyrogen Testing Market
Testing Services
Cholesterol Testing Services Market
Testing Services
Aerospace and Life Science Testing Certification Market
Testing Services
Toxicity Testing Outsourcing Market
Testing Services
Hemotransmissive Infections Testing Market
Testing Services
Preclinical Medical Device Testing Services Market
Testing Services
Active B12 Test Market
Testing Services
Thrombophilia Testing Market
Testing Services
Ferritin Testing Market
Testing Services
Fecal Occult Testing Market
Testing Services
Global Bilirubin Colorimeter Assay Market
Testing Services
Allergy Skin Test Market