
 Global CA 125 Test Market | 2026-2036
Global CA 125 Test Market Size, Share, and Industry Trends Forecast 2026-2036
Global CA 125 Test Market Foresight
CE marking under the EU In Vitro Diagnostic Regulation is reorganizing competitive access across Europe, raising compliance costs for smaller manufacturers while favoring scaled participants. Roche Diagnostics leverages integrated analyzer-platform ecosystems to sustain laboratory loyalty across high-throughput settings. Abbott Laboratories anchors its position through point-of-care connectivity that extends test accessibility beyond centralized labs. Siemens Healthineers competes on automated workflow density, occupying premium installed-base positions in health system networks.
CA 125 testing measures carbohydrate antigen 125 protein levels in blood serum, typically via chemiluminescence immunoassay or enzyme-linked immunosorbent assay methods, to detect and monitor epithelial ovarian cancer progression. The assay quantifies a mucin-like glycoprotein elevated in malignancy, serving gynecologic oncology and fertility assessment workflows. Chemiluminescence immunoassay platforms command the dominant share of test type revenue due to throughput advantages and detection sensitivity. Oncology centers represent the fastest-growing end user category as integrated cancer networks consolidate diagnostic services under single stewardship. Point of care devices remain nascent but attract development investment for remote monitoring applications.
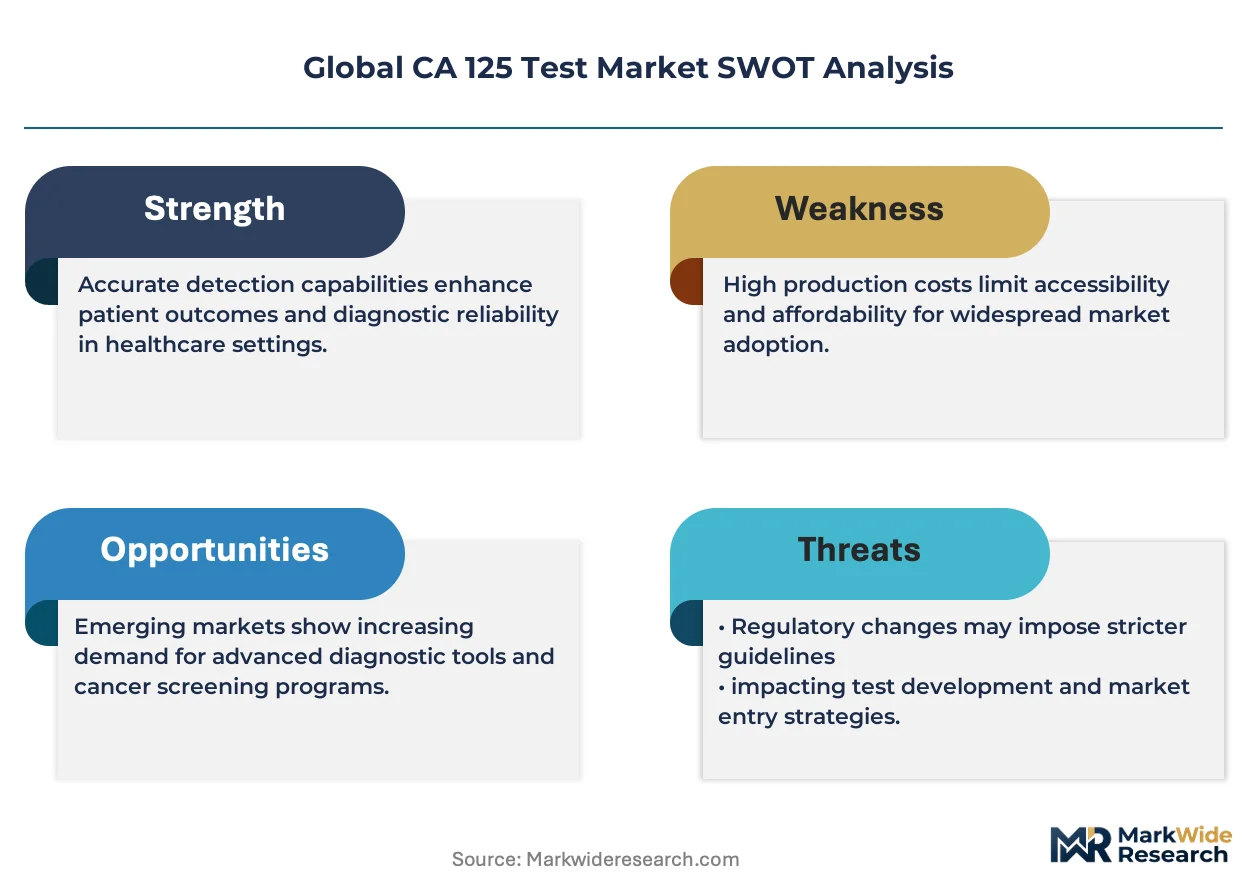
The FDA's 510(k) premarket notification framework governs U.S. test commercialization, while the EU IVDR imposes stricter clinical evidence requirements that reshape product lifecycle economics. Japan's PMDA enforces QMS conformity for imported reagents, creating additional documentation burdens for non-domestic suppliers. China's NMPA tumor marker registration pathway demands local clinical trials, conditioning market entry timelines. Stakeholders must monitor evolving evidentiary thresholds across these jurisdictions to align R&D allocation with approval feasibility.
Market Dynamics
Oncology center consolidation is compressing purchasing timelines and favoring integrated analyzer-platform contracts over standalone reagent procurement. The shift toward centralized cancer network stewardship is decomposing legacy distributed testing models.
Growth Catalysts
- EU IVDR CE marking acceleration:Scaled manufacturers with established quality management systems capture shelf space as smaller competitors exit due to clinical evidence burdens. German oncology centers expand testing volumes under consolidated procurement.
- Chemiluminescence immunoassay platform upgrades:High-throughput laboratories prioritize detection sensitivity and workflow automation. Japan's METI-backed screening programs drive analyzer deployment across prefectural health systems.
- FDA 510(k) pathway efficiency:Premarket notification frameworks compress commercialization timelines for tumor marker assays. US reference laboratories accelerate validation cycles for new reagent introductions.
Market Restraints
- Reagent supply concentration:Critical antibody and calibrator production clusters in limited manufacturing geographies. Disruption risk elevates inventory carrying costs for hospital laboratories.
- EU IVDR compliance cost inflation:Stricter clinical performance studies and post-market surveillance requirements reshape product lifecycle economics. Mid-tier manufacturers face capital constraints for notified body engagement.
- Serum biomarker specificity limitations:CA 125 elevation in benign gynecologic conditions and non-ovarian malignancies generates false-positive rates. Clinical guidelines mandate multimarker panels for diagnostic confirmation.
Strategic Opportunities
- Point-of-care device development:Remote monitoring applications for post-treatment surveillance attract engineering investment. Fingerstick sampling formats target ambulatory oncology settings.
- China NMPA local trial pathway:Domestic clinical study requirements condition entry timelines but reward first-movers with exclusive distribution windows. Shanghai and Beijing cancer centers drive validation partnerships.
- Multiplex biomarker convergence:CA 125 integration with HE4, ROMA algorithm, and liquid biopsy platforms enables risk stratification workflows. Gynecologic oncology practices adopt algorithmic diagnostic support.
Industry Challenges
- IVDR technical documentation expertise scarcity:Competent regulatory affairs specialists command premium compensation. Manufacturers compete for limited notified body audit capacity.
- Legacy analyzer interoperability friction:Proprietary reagent-analyzer lock-in complicates third-party assay validation. Health system networks face switching costs for platform migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global CA 125 Test Market |
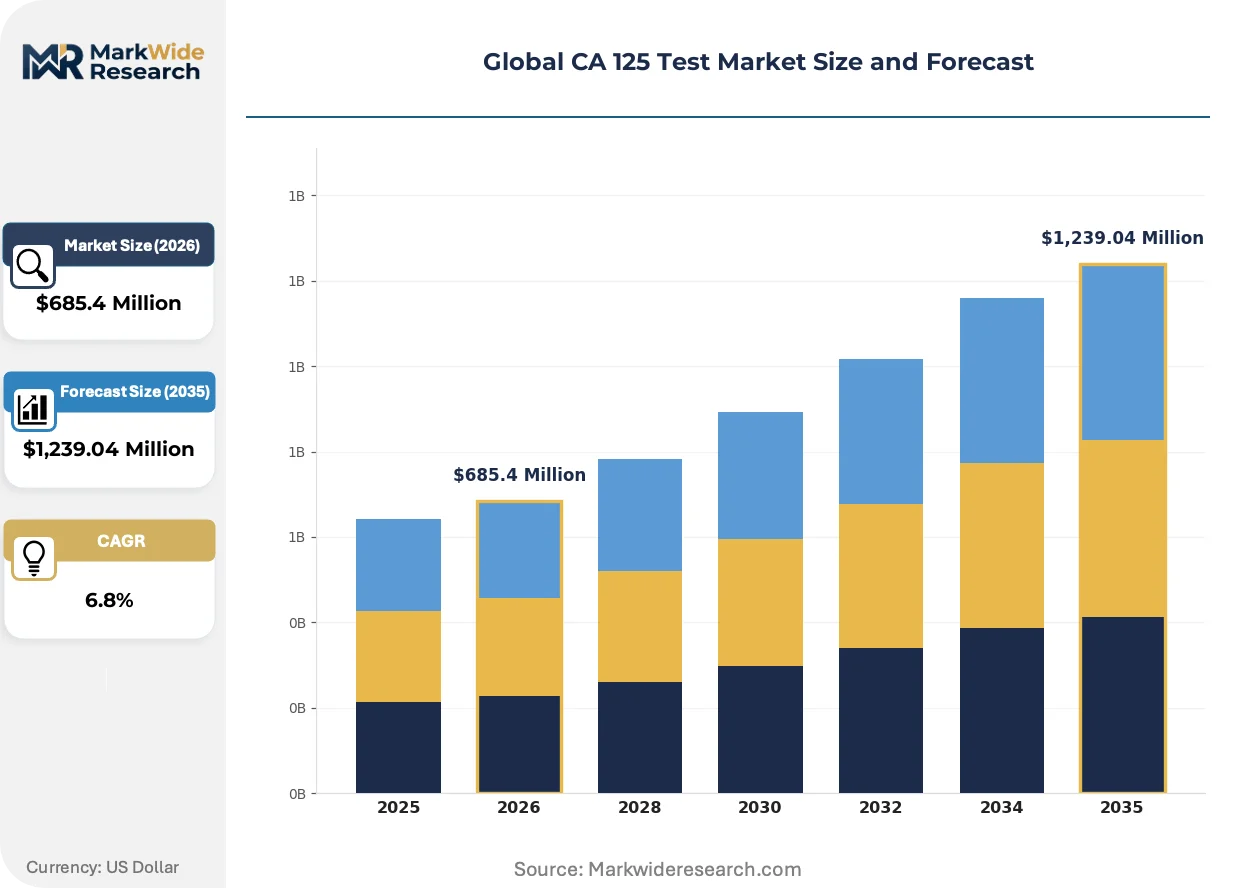
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Quantitative, Qualitative, Semi-Quantitative, Rapid Diagnostic, Enzyme-Linked Immunosorbent Assay, Chemiluminescence Immunoassay Application: Ovarian Carcinoma Detection, Endometriosis Diagnosis, Monitoring of Cancer Recurrence, Early Stage Screening, Fertility Assessment, Tumor Marker Analysis End User: Diagnostic Laboratories, Specialty Clinics, Research Institutes, Oncology Centers, Independent Testing Facilities, Pathology Laboratories Delivery Mode: Manual Testing, Automated Analyzers, Point of Care Devices, Laboratory Information Systems, Remote Testing Services, Telepathology Platforms |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Siemens Healthineers, Thermo Fisher Scientific, Bayer, Allergan plc, Amgen Inc., Merck & Co., Inc., Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global CA 125 Test Market Shifts & Advancements
Automated workflow density and regulatory evidence requirements are simultaneously elevating technical barriers and consolidating competitive positions. Three forces are actively restructuring how CA 125 testing is developed, approved, and deployed.
Digital pathology integration is decomposing traditional histology-immunohistochemistry-serology silos. Comprehensive cancer centers in the Netherlands and Sweden adopt unified data architectures. Pathology informatics platforms now embed serum biomarker trajectories alongside tissue morphology for treatment response assessment.
Japan's PMDA QMS conformity enforcement for imported reagents intensifies documentation scrutiny. Foreign suppliers face extended review cycles for manufacturing site inspections. Tokyo metropolitan hospital procurement offices now require Japanese-language stability data packages as standard tender elements.
Consolidated cancer network purchasing is compressing supplier rosters to single-source or dual-source frameworks. Integrated delivery networks in Texas and California negotiate multi-year reagent commitments with capital equipment placement. Community oncology practices lose negotiating leverage as testing migrates to centralized reference laboratories.
Global CA 125 Test Market Segmentation
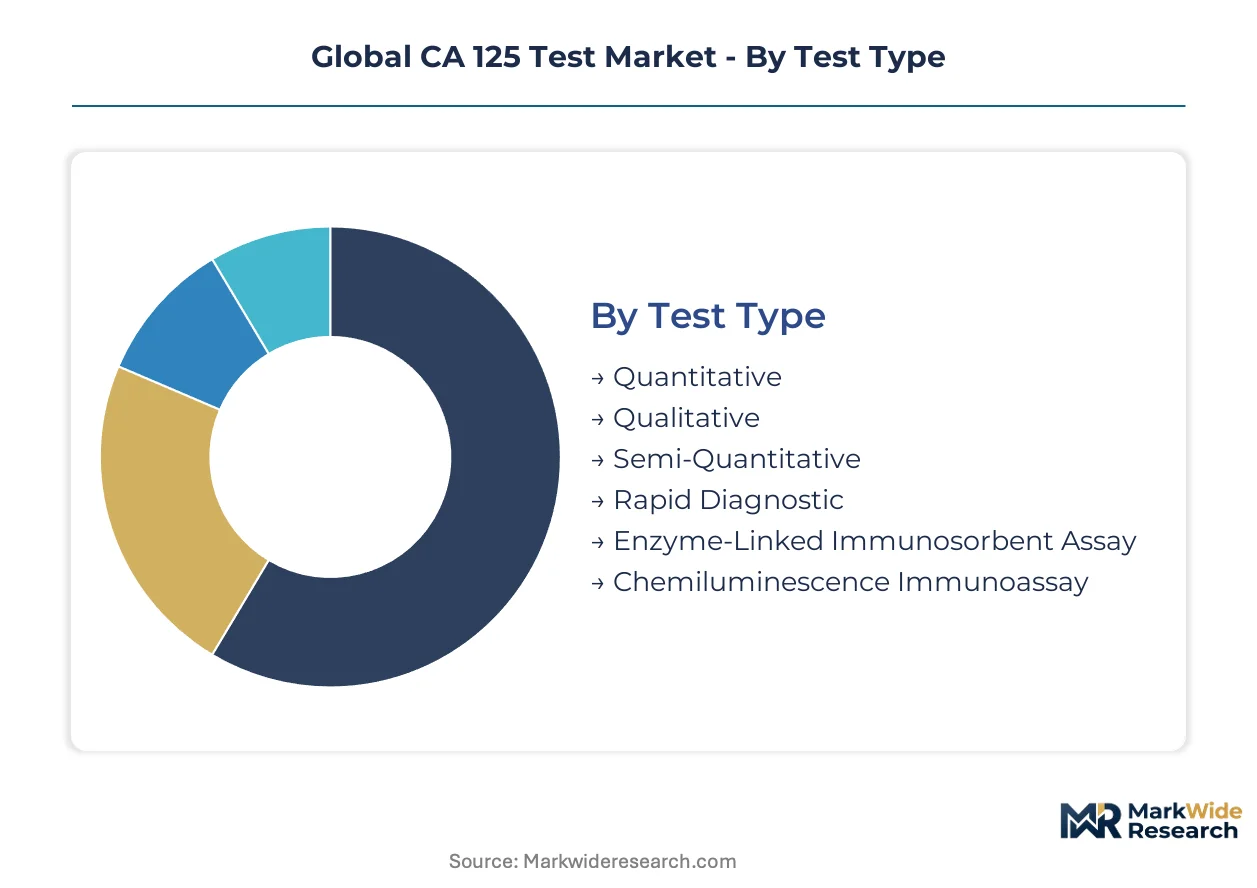
Segmentation reveals how CA 125 testing value pools concentrate across methodological, clinical, and operational dimensions. Each category carries distinct substitution pressures from competing biomarker platforms and diagnostic modalities reshaping purchasing decisions.
Test Type:
Chemiluminescence immunoassay platforms face intensifying substitution pressure from multiplex liquid biopsy panels entering ovarian cancer surveillance workflows.
- Chemiluminescence Immunoassay:These platforms deploy acridinium ester or alkaline phosphatase conjugates to detect CA 125 with femtomolar sensitivity. German oncology centers and Japanese prefectural health systems anchor demand through high-throughput analyzer procurement under consolidated tenders. Detection precision justifies premium reagent pricing in tertiary care settings.
- Enzyme-Linked Immunosorbent Assay:ELISA formats utilize horseradish peroxidase-mediated colorimetric detection for batch-processed serum analysis. Research institutes and mid-tier pathology laboratories in India and Brazil sustain volumes where capital constraints limit automated platform acquisition. Manual workflow requirements compress throughput ceilings.
- Quantitative:Numerical reporting formats enable serial trend monitoring for treatment response assessment.
- Qualitative:Binary result outputs serve screening triage in resource-constrained clinical environments.
- Semi-Quantitative:Range-based reporting balances diagnostic granularity with simplified interpretation.
- Rapid Diagnostic:Lateral flow and immunochromatographic formats target emergency department and ambulatory deployment.
Chemiluminescence immunoassay retains volume leadership; rapid diagnostic holds the steepest expansion curve.
Application:
Cost tier stratification separates premium surveillance monitoring from commoditized screening applications with divergent reimbursement profiles.
- Ovarian Carcinoma Detection:Primary diagnostic application measuring mucin-like glycoprotein elevation in epithelial malignancies. US gynecologic oncology practices and UK National Health Service screening programs anchor procedural volumes. FDA 510(k) pathway efficiency accelerates assay validation for new reagent introductions.
- Monitoring of Cancer Recurrence:Post-treatment surveillance tracks CA 125 trajectory for early relapse identification. Netherlands and Sweden comprehensive cancer centers embed biomarker data within digital pathology platforms for unified treatment response assessment. Serial testing frequency drives recurring revenue concentration.
- Endometriosis Diagnosis:Benign gynecologic condition assessment where CA 125 elevation lacks specificity.
- Early Stage Screening:Asymptomatic population testing constrained by false-positive rates in low-prevalence cohorts.
- Fertility Assessment:Ovarian reserve evaluation alongside anti-Müllerian hormone and follicle-stimulating hormone panels.
- Tumor Marker Analysis:Multiplex panel inclusion for differential diagnosis across malignancy types.
Ovarian carcinoma detection commands the largest addressable base; monitoring of cancer recurrence generates the highest lifetime value per patient.
End User:
Customer type consolidation is compressing supplier rosters toward integrated network contracts with embedded analyzer placement.
- Oncology Centers:Integrated cancer networks consolidate diagnostic services under single stewardship with standardized assay menus. Texas and California integrated delivery networks negotiate multi-year reagent commitments. Centralized procurement displaces distributed community practice testing.
- Diagnostic Laboratories:Reference laboratory chains process high-volume CA 125 panels for health system outsourcing contracts.
- Pathology Laboratories:Hospital-affiliated anatomic pathology units integrate serology with histopathology workflows.
- Specialty Clinics:Gynecologic and reproductive endocrinology practices perform point-of-care testing for immediate clinical decision-making.
- Research Institutes:Academic medical centers validate novel biomarker combinations and algorithmic risk stratification tools.
- Independent Testing Facilities:Standalone laboratories compete on turnaround time and direct-to-consumer access models.
Diagnostic laboratories process the highest absolute test volumes; oncology centers are climbing the fastest in per-site consumption intensity.
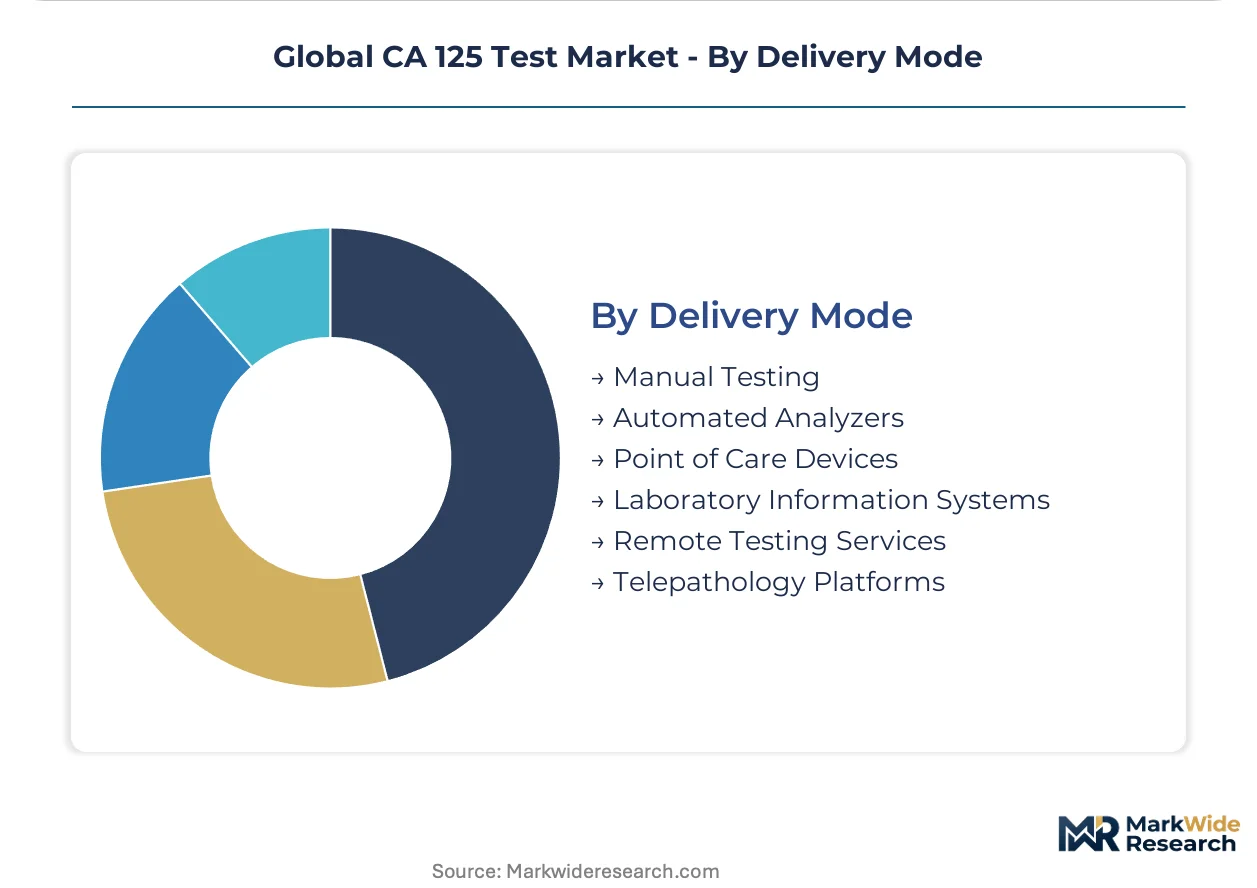
Delivery Mode:
Supply concentration in automated analyzer manufacturing geographies shapes regional deployment feasibility and service coverage economics.
- Automated Analyzers:Random-access platforms integrate CA 125 with comprehensive metabolic and hormonal panels. Siemens Healthineers and Roche Diagnostics occupy premium installed-base positions in health system networks. Workflow density justifies capital equipment investment at throughput thresholds exceeding 100 tests daily.
- Point of Care Devices:Fingerstick sampling formats target ambulatory oncology and remote monitoring applications. Abbott Laboratories extends test accessibility beyond centralized lab infrastructure through portable connectivity. Development investment concentrates on post-treatment surveillance use cases.
- Manual Testing:Labor-intensive formats persist where analyzer capital is unavailable or batch sizes are irregular.
- Laboratory Information Systems:Software-mediated order entry and result distribution embedded within enterprise EHR architectures.
- Remote Testing Services:Home collection kits with centralized laboratory processing for geographically dispersed patients.
- Telepathology Platforms:Digital consultation infrastructure enabling specialist interpretation of correlated histopathology and serology.
Automated analyzers dominate current deployment; point of care devices are gaining share fastest in ambulatory network extensions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam anchors European reagent distribution networks serving German and Dutch oncology networks. Automated analyzer shipments through this hub supply consolidated cancer centers across the Rhine-Ruhr corridor and Randstad metropolitan region.
United States
Texas Medical Center and MD Anderson Cancer Network drive analyzer procurement for high-throughput ovarian carcinoma surveillance. FDA 510(k) premarket notification frameworks compress validation timelines for new tumor marker assays. Houston and Dallas integrated delivery networks negotiate multi-year reagent commitments with embedded capital equipment placement.
Germany
Consolidated oncology centers in Munich and Heidelberg expand CA 125 testing volumes under unified procurement stewardship. EU IVDR CE marking requirements reshape competitive access, favoring scaled manufacturers with established quality management systems. The Rhine-Main and Upper Bavaria regions concentrate reference laboratory capacity for gynecologic malignancy monitoring.
Japan
METI-backed cancer screening programs drive automated analyzer deployment across prefectural health systems. PMDA QMS conformity enforcement for imported reagents intensifies documentation scrutiny for foreign suppliers. Tokyo metropolitan hospital procurement offices require Japanese-language stability data packages as standard tender elements.
China
Shanghai and Beijing cancer centers anchor validation partnerships for NMPA tumor marker registration pathways demanding local clinical trials. Domestic clinical study requirements condition entry timelines but reward first-movers with exclusive distribution windows. The Yangtze River Delta region concentrates gynecologic oncology research institute demand for biomarker panel development.
Netherlands
Comprehensive cancer centers in Amsterdam and Utrecht adopt unified data architectures integrating serum biomarker trajectories with digital pathology platforms. EMA-aligned clinical evidence standards support IVDR technical documentation for cross-border reagent supply. The Randstad cluster leads European adoption of algorithmic diagnostic support combining CA 125 with HE4 and ROMA scores.
Global CA 125 Test Market Competitive Landscape
Listed diagnostics conglomerates compete with private specialists across analyzer-platform ecosystems and point-of-care connectivity. Market structure concentrates around three strategic archetypes: integrated system vendors bundling reagents with capital equipment, standalone assay developers targeting reference laboratory outsourcing contracts, and emerging point-of-care device engineers pursuing remote monitoring applications. Dominant competitive moves include multi-year reagent commitment negotiations with health system networks and strategic partnerships for multiplex biomarker algorithm development.
Among Switzerland-based and Germany-anchored diagnostics conglomerates, Roche Diagnostics and Siemens Healthineers occupy positions exemplifying integrated analyzer-platform stewardship. US-based Abbott Laboratories represents the point-of-care connectivity archetype extending test accessibility beyond centralized laboratory infrastructure. These three entities anchor competitive positioning across high-throughput chemiluminescence immunoassay deployment, automated workflow density optimization, and ambulatory network extension strategies respectively.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Bayer |
| Allergan plc |
| Amgen Inc. |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Others |
Supply & Pricing Matrix
Multi-year reagent commitment contracts with embedded capital equipment placement lock in supply access and price visibility for German oncology centers and Texas integrated delivery networks negotiating consolidated procurement frameworks.
Pricing Analysis
Volume-discount tiering structures separate high-throughput laboratory networks receiving preferential reagent pricing from mid-tier pathology laboratories paying standard rates. Three-tier pricing stratifies across premium chemiluminescence immunoassay platforms, standard ELISA formats, and economy rapid diagnostic strips. Cost compression in the economy tier intensifies as Indian and Brazilian laboratories prioritize capital-constrained batch processing. Reference laboratory chains exhibit lowest price sensitivity due to reimbursement pass-through mechanics, while community oncology practices face margin pressure from centralized network migration.
Supply Chain Analysis
Inventory carrying costs for critical antibody and calibrator stocks have elevated as reagent supply concentrates in Germany, Japan, and the United States. Manufacturing draws from acridinium ester conjugates, alkaline phosphatase enzymes, and monoclonal antibody cell lines as core inputs. Single-source vulnerability for specialized chemiluminescence substrates creates disruption exposure for hospital laboratories. Distribution runs through regional reference laboratory hubs serving consolidated cancer networks with scheduled replenishment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recurring reagent revenue streams attached to installed analyzer bases expand faster than hardware sales, positioning service-contract penetration as the primary value-capture mechanism in this market.
For Market Incumbents: Consolidate laboratory loyalty through integrated analyzer-platform ecosystems that embed multi-year reagent commitments with capital equipment placement. Roche Diagnostics and Siemens Healthineers defend against multiplex liquid biopsy substitution by deepening workflow automation density. Priority rests on IVDR technical documentation expertise acquisition to accelerate notified body engagement.
For New Entrants and Emerging Players: FDA 510(k) premarket notification fast-tracks offer the most penetrable regulatory pathway for point-of-care device developers targeting ambulatory oncology surveillance. White-space concentrates in fingerstick sampling formats for post-treatment remote monitoring and China's NMPA local trial pathway for first-mover distribution windows. Go-to-market angles should prioritize partnerships with Shanghai and Beijing cancer centers for validation study execution.
For Investors and Strategic Acquirers: Capital is best deployed toward point-of-care connectivity specialists with fingerstick-format platforms and established regulatory affairs capabilities across FDA and PMDA jurisdictions. Long-term viability over a five-to-ten year window hinges on algorithmic diagnostic support integration with HE4 and ROMA scores. The signal to watch is consolidation velocity among Texas and California integrated delivery networks compressing supplier rosters.
| Strategic Initiative | Industry Significance |
|---|---|
| IVDR CE Marking Pathway | Accelerated notified body engagement captures shelf space as smaller competitors exit. |
| Hospital System Partnership | Multi-year reagent commitments with embedded analyzer placement secure installed-base positions. |
| Software Companion Development | Algorithmic diagnostic support combining CA 125 with HE4 and ROMA scores differentiates offerings. |
| Reimbursement Strategy | CMS and private payer coverage expansion for serial surveillance testing drives recurring revenue. |
| Point-of-Care Platform Launch | Fingerstick sampling formats extend test accessibility beyond centralized laboratory infrastructure. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with regulatory affairs specialists, hospital procurement managers, gynecologic oncologists, and reference laboratory directors; and secondary validation against FDA 510(k) filings, EMA clinical evidence guidelines, PMDA QMS documentation requirements, and hospital procurement database records. Bottom-up test volume modeling triangulated with top-down market sizing across the projection horizon.
Across the modeling period, segmentation dimensions included test type methodology, application clinical use case, end-user facility category, and delivery mode infrastructure. CAGRs derived from analyzer shipment trajectories, reagent consumption patterns, and screening program expansion schedules. Forecast inputs incorporated METI-backed cancer screening deployment timelines and NMPA local clinical trial completion rates.
Underlying assumptions cover regulatory approval pathway efficiency and consolidated procurement adoption velocity, with deviation risk concentrated in IVDR notified body audit capacity constraints and antibody supply chain disruption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Bioprocess Integrity Testing Systems Market
Testing Services
Blood Testing Market
Testing Services
Global Direct to Consumer Laboratory Testing Market
Testing Services
Antimicrobial Susceptibility Testing Market
Testing Services
Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market
Testing Services
Ready-To-Use Laboratory Test Kits Market
Testing Services
Global Endocrine Testing Market
Testing Services
Global Virology Testing Market
Testing Services
Antibiotic Residue Test Kits Market
Testing Services
Global Forensic Testing Services Market
Testing Services
Phenytoin Testing Market
Testing Services
Pharmaceutical Quality Control Market
Testing Services
Medical Device Testing Services Market
Testing Services
US at-Home Testing Kits Market
Testing Services
Global GMP Testing Service Market
Testing Services
Sickle Cell Anemia Testing and Screening Market