
 Self-Urinary Infection Testing Market | 2026-2036
Self-Urinary Infection Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Urinary Infection Testing Market Analytics
Subscription-based result interpretation and remote clinician connectivity is rebalancing the value proposition away from standalone hardware. Abbott leverages its diagnostic platform breadth to anchor home-testing ecosystems across multiple assay formats. Siemens Healthcare competes through integrated laboratory-to-home data pipelines that sustain clinical credibility in consumer channels. bioMérieux SA specializes in molecular specificity, positioning its R&D intensity toward higher-sensitivity strip chemistries that differentiate against commodity dipsticks.
Self-urinary infection testing encompasses immunoassay and chromatographic methods performed without professional supervision, typically detecting leukocyte esterase, nitrite, or bacterial antigens in urine specimens with sensitivity thresholds ranging from 10² to 10⁴ colony-forming units per milliliter. The primary purpose is enabling rapid triage of suspected urinary tract infections to reduce unnecessary clinic visits and accelerate appropriate antimicrobial intervention. Dipstick Tests occupy the largest volume tier due to lowest unit cost and broad pharmacy availability, though margin pools concentrate in Urinary Tract Panels that bundle multiplex pathogen detection. Point-of-Care Testing represents the fastest structural expansion as telehealth platforms integrate cartridge-based readers into remote consultation workflows.
FDA 510(k) clearance requirements for over-the-counter diagnostic devices shape product development timelines and predicate device selection for manufacturers seeking US market access. CLIA waiver pathways and state laboratory licensing frameworks further determine where testing can legally occur outside traditional facilities. Stakeholders must monitor evolving FDA guidance on software-as-medical-device classifications for AI-enabled result interpretation, as this regulatory boundary will determine which platform layers capture sustainable value.
Market Dynamics
Telehealth integration is compressing the diagnostic pathway from specimen collection to clinical decision, collapsing traditional laboratory intermediaries and forcing manufacturers to embed connectivity into device architecture.
Growth Catalysts
- FDA 510(k) OTC Pathway Expansion:The FDA's streamlined clearance for over-the-counter diagnostic devices accelerates commercialization timelines for smartphone-integrated readers.
- Recurrent UTI Patient Cohorts:Women experiencing three or more infections annually drive repeat purchase velocity and subscription-based monitoring adoption.
- Leukocyte Esterase-Nitrite Multiplexing:Advanced chromatographic chemistries improve sensitivity thresholds to 10² colony-forming units per milliliter, reducing false-negative rates.
Market Restraints
- CLIA Waiver State-by-State Variability:Inconsistent laboratory licensing frameworks create compliance fragmentation that limits national rollout of point-of-care testing networks.
- Commodity Dipstick Price Compression:Generic strip manufacturers in India and China erode margin pools at the high-volume tier of the market.
- Antibiotic Stewardship Counterpressure:Hospital formulary restrictions on empirical prescribing reduce the clinical utility of rapid positive results without culture confirmation.
Strategic Opportunities
- Software-as-Medical-Device Classification:FDA guidance on AI-enabled result interpretation creates value capture opportunities for algorithm developers independent of hardware.
- Subscription Result Interpretation:Remote clinician connectivity transforms one-time test sales into recurring revenue through telehealth platform partnerships.
- Germany's Digital Health Act:Reimbursement codes for home diagnostics under the DVG accelerate insured population penetration in Europe's largest healthcare market.
Industry Challenges
- Predicate Device Scarcity for Novel Formats:Manufacturers seeking 510(k) clearance struggle to identify appropriate comparison devices for cartridge-based molecular assays.
- Cross-Platform Data Interoperability:Telehealth systems demand HL7 FHIR compliance that legacy reader hardware cannot support without firmware overhaul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Urinary Infection Testing Market |
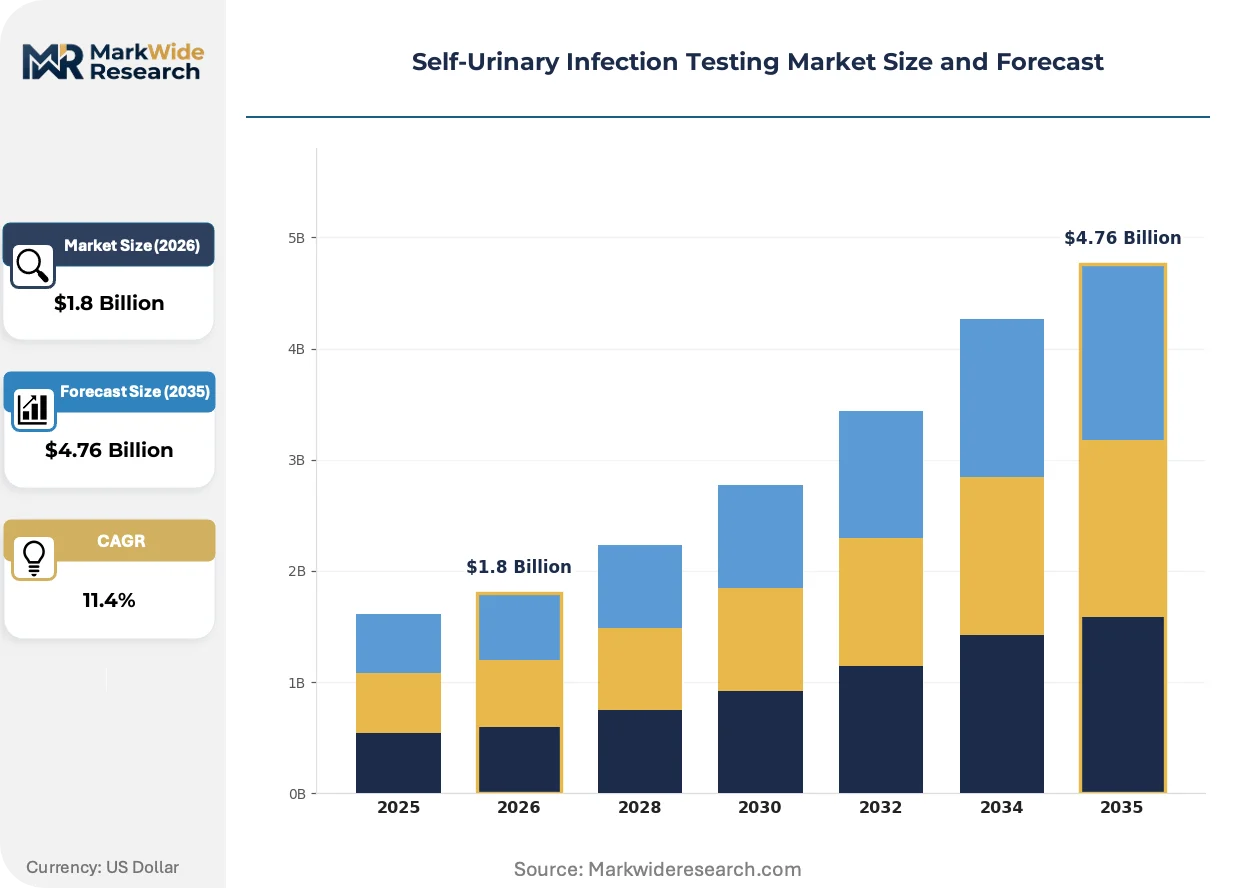
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dipstick Tests, Strip Tests, Midstream Tests, Urinary Tract Panels Usage Mode: Home Testing, Clinical Settings, Telehealth Solutions, Point-of-Care Testing Target Demographic: Women, Elderly, Children, High-Risk Groups Distribution Channel: Online Retail, Pharmacies, Healthcare Facilities, Direct Sales |
| Companies Covered | Abbott, Siemens Healthcare, F. Hoffmann-La Roche Ltd, Cardinal Health, bioMérieux SA, Beckman Coulter, Quidel Corporation, Bio-Rad Laboratories, ACON Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Urinary Infection Testing Market Evolving Landscape
Diagnostic hardware is dissolving into software layers, with value migrating from physical test strips to algorithmic interpretation and clinical workflow integration.
Smartphone-integrated colorimetric analysis is unifying image capture, result quantification, and electronic health record transmission into single-application workflows. Retail pharmacy chains deploy these systems to support same-day telehealth consultations. This convergence compresses the traditional three-step diagnostic pathway into a fifteen-minute consumer experience.
EU MDR recertification requirements for in-vitro diagnostic devices impose clinical evidence burdens that favor established manufacturers with post-market surveillance infrastructure. Smaller developers face capital requirements that delay CE marking by eighteen to twenty-four months. The regulatory friction concentrates market share among firms with pre-2017 legacy device portfolios.
Direct-to-consumer pharmacy distribution is displacing clinician-mediated prescribing as the primary acquisition channel for urinary infection diagnostics. Major retailers now position test kits adjacent to feminine hygiene and pain relief categories to capture symptomatic purchase intent. This channel shift is most pronounced in the United States, where CVS and Walgreens have dedicated shelf space to telehealth-linked diagnostic bundles.
Self-Urinary Infection Testing Market Segmentation
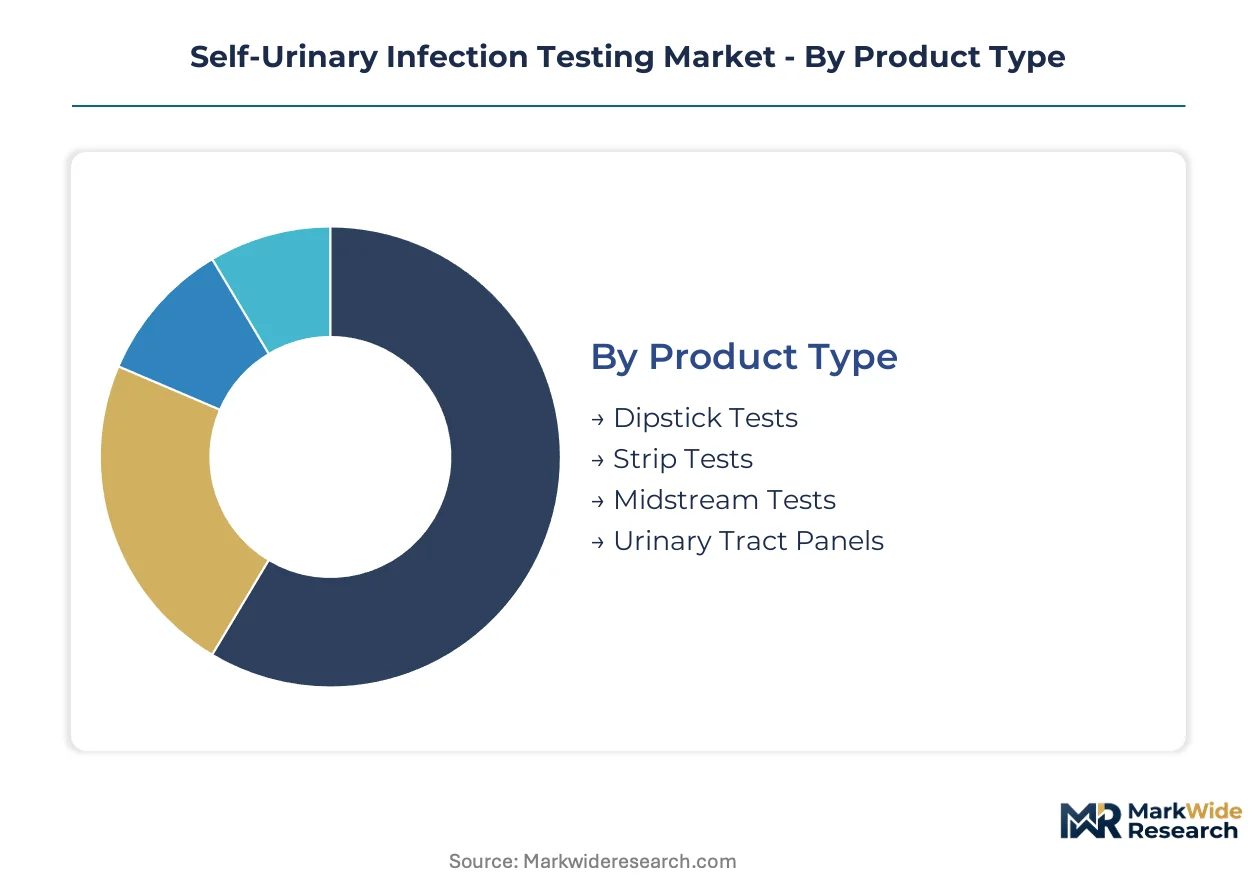
Segmentation in self-urinary infection testing reveals how purchasing decisions split between price-sensitive convenience buyers and clinically engaged monitoring patients. Manufacturers must align formulation sophistication with channel economics and reimbursement access across each tier.
Product Type:
Cost tier determines margin structure and regulatory pathway complexity for manufacturers entering this market.
- Dipstick Tests:Single-layer chromatographic strips detecting leukocyte esterase and nitrite through colorimetric change. Mass pharmacy distribution in the United States sustains volume leadership despite commodity pricing pressure from Asian contract manufacturers.
- Urinary Tract Panels:Multiplex cartridge systems combining bacterial antigen detection with smartphone-read quantification. Telehealth platform integration in Germany and the United States drives subscription-based revenue models with higher per-test economics.
- Strip Tests:Simplified single-parameter formats for cost-constrained markets.
- Midstream Tests:Integrated collection and analysis devices reducing handling steps for home users.
Dipstick Tests lead on scale; Urinary Tract Panels lead on momentum.
Usage Mode:
Application context dictates connectivity requirements and clinical validation depth for device developers.
- Home Testing:Unsupervised specimen collection with consumer-interpreted results or app-guided analysis. FDA 510(k) OTC clearance requirements shape product architecture for US market entry.
- Telehealth Solutions:Reader-integrated workflows transmitting results to remote clinicians during synchronous consultations. Germany's Digital Health Act reimbursement codes accelerate insured population penetration.
- Clinical Settings:Provider-mediated testing with immediate result availability.
- Point-of-Care Testing:Non-laboratory diagnostic sites requiring CLIA waiver compliance.
Home Testing dominates unit volume; Telehealth Solutions expand most quickly through platform integration.
Target Demographic:
Customer type determines purchase frequency, price elasticity, and the need for result interpretation services.
- Women:Primary demand cohort with recurrent UTI profiles driving repeat purchase velocity. Direct-to-consumer pharmacy placement adjacent to feminine hygiene categories captures symptomatic purchase intent in US retail.
- High-Risk Groups:Immunocompromised and catheter-dependent patients requiring monitoring protocols. Clinical workflow integration and remote clinician connectivity justify premium positioning.
- Elderly:Age-related susceptibility with caregiver-mediated purchasing patterns.
- Children:Pediatric specimen collection challenges favoring midstream and panel formats.
Women anchor volume concentration; High-Risk Groups generate the steepest expansion trajectory through monitoring subscriptions.
Distribution Channel:
Supply concentration among retail pharmacy chains and telehealth platforms is reshaping manufacturer go-to-market requirements.
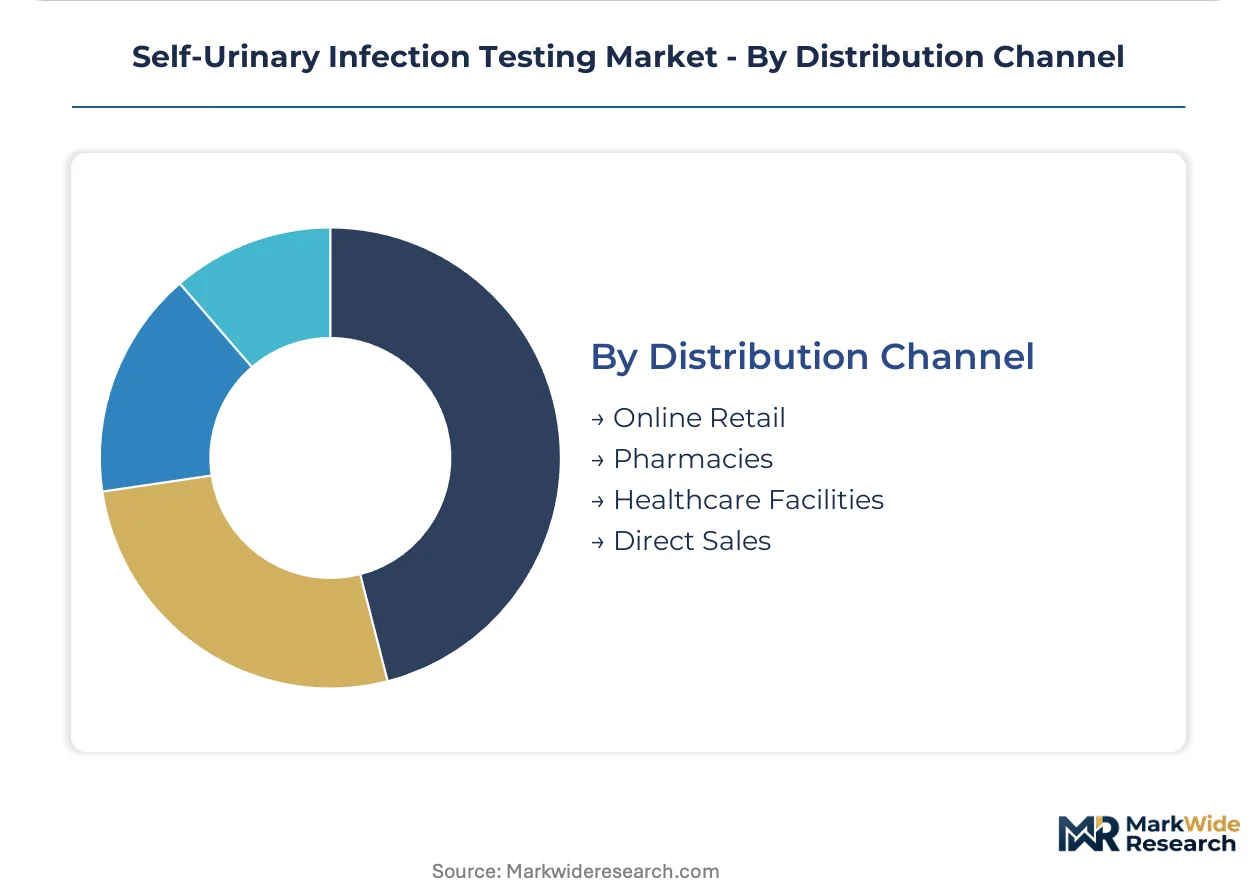
- Pharmacies:CVS and Walgreens in the United States dedicate shelf space to telehealth-linked diagnostic bundles, creating the most mature self-testing infrastructure globally.
- Online Retail:Amazon and specialized health platforms enabling subscription replenishment for recurrent users. EU MDR recertification burdens favor established manufacturers with post-market surveillance infrastructure.
- Healthcare Facilities:Institutional procurement with formulary committee oversight.
- Direct Sales:Manufacturer-controlled channels for premium panel systems.
Pharmacies command the largest transaction volume; Online Retail gains share fastest through subscription mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where self-urinary infection testing manufacturers establish production, with EU MDR compliance costs pushing some assembly toward lower-certification jurisdictions while US FDA 510(k) pathways anchor premium product development in established regulatory environments.
United States
Direct-to-consumer pharmacy distribution through CVS and Walgreens sustains the most mature self-testing infrastructure globally, with dedicated shelf space for telehealth-linked diagnostic bundles. FDA 510(k) OTC clearance requirements shape product architecture and predicate device selection for market entry. The Boston-Cambridge corridor concentrates digital health platform development, with smartphone-integrated reader startups clustering near academic medical centers.
Germany
Reimbursement codes under the Digital Health Act accelerate insured population penetration for home diagnostics, creating Europe's most favorable payment environment. BfArM oversight of in-vitro diagnostic devices maintains stringent quality requirements that favor established manufacturers with post-market surveillance infrastructure. The Munich-Stuttgart axis hosts major diagnostic manufacturers integrating laboratory-to-home data pipelines.
China
Domestic contract manufacturers supply generic dipstick chemistries that erode margin pools at the high-volume tier through cost-competitive production. NMPA regulatory pathways for Class II medical devices determine market access timelines for imported and locally manufactured test kits. The Yangtze River Delta region concentrates diagnostic reagent production, with Suzhou and Shanghai hosting major IVD manufacturing facilities.
United Kingdom
NHS England procurement frameworks increasingly incorporate home-testing options for recurrent UTI patient pathways, driving institutional demand for validated self-test formats. MHRA post-Brexit regulatory autonomy has streamlined some device registration timelines while maintaining alignment with EU safety standards. The Oxford-Cambridge-London golden triangle anchors digital health platform development and telehealth integration startups.
India
Domestic manufacturers compete aggressively on strip chemistry pricing, supplying commodity dipsticks to global markets through cost-optimized production. CDSCO medical device rules for in-vitro diagnostics create compliance thresholds that differentiate quality-tier suppliers from unregulated market entrants. The Mumbai-Pune corridor and Bangalore cluster host contract manufacturing operations serving European and North American distributors.
Self-Urinary Infection Testing Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in multiplex panel systems contrasting fragmented supply for commodity dipstick chemistries. Three archetypes dominate: diversified diagnostic conglomerates leveraging platform breadth, specialized IVD players focusing on molecular specificity, and Asian contract manufacturers competing on unit economics. Strategic moves concentrate on telehealth platform partnerships and regulatory pathway navigation for OTC clearance.
Within the diversified diagnostic tier, Abbott and Siemens Healthcare exemplify platform-scale competitors, with Abbott anchoring home-testing ecosystems across multiple assay formats and Siemens sustaining clinical credibility through integrated laboratory-to-home data pipelines. bioMérieux SA occupies a specialized position, representing the molecular specificity archetype with R&D intensity directed toward higher-sensitivity strip chemistries. These three companies illustrate how competitive positioning diverges between breadth-driven and depth-driven strategies in self-urinary infection testing.
| Leading Market Players |
|---|
| Abbott |
| Siemens Healthcare |
| F. Hoffmann-La Roche Ltd |
| Cardinal Health |
| bioMérieux SA |
| Beckman Coulter |
| Quidel Corporation |
| Bio-Rad Laboratories |
| ACON Laboratories |
| Others |
Value Network & Pricing Analysis
Retail pharmacy chains in the United States anchor procurement volume and impose contract-based pricing that rewards scale and telehealth integration capabilities. This buyer concentration compresses margin pools for standalone dipstick manufacturers while elevating subscription-linked panel systems.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for commodity dipstick chemistries. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared smartphone-integrated panels from CLIA-waived point-of-care cartridges and unregulated generic strips. Cost compression in the economy tier stems from Asian contract manufacturers competing on unit economics. High-risk patient monitoring segments show lowest price sensitivity due to reimbursement coverage and clinical workflow integration requirements.
Supply Chain Analysis
Domestic-content mandates in China's NMPA Class II device pathways and India's PLI scheme for medical devices are reshaping sourcing patterns for multinational manufacturers. Manufacturing concentrates in China, India, and Germany. Nitrocellulose membrane chemistries, antibody conjugates, and plastic cartridge housings constitute critical input dependencies. Single-source vulnerability in specialized chromatographic substrates creates supply chain risk. Distribution runs through retail pharmacy chains in the United States and telehealth platform partnerships in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The self-urinary infection testing market functions as a stable compounder, with recurrent UTI patient cohorts driving predictable repeat purchase velocity and subscription retention.
For Market Incumbents: Deepen telehealth platform integration to defend against standalone hardware commoditization. Prioritize backward integration into chromatographic chemistry production to secure input cost control. Expand CLIA waiver coverage across state licensing frameworks to limit compliance fragmentation exposure. For New Entrants and Emerging Players: Enter via Germany's Digital Health Act reimbursement pathways, where insured population penetration offers lower competitive density than saturated US pharmacy channels. Target high-risk group monitoring subscriptions as the most penetrable segment. Pursue white-label partnerships with established telehealth platforms to bypass predicate device scarcity for novel cartridge formats. For Investors and Strategic Acquirers: Diversified diagnostic conglomerates are the most active acquirer in this space, seeking algorithm developers with FDA software-as-medical-device clearance pathways. The 5-10 year viability window favors platforms with embedded clinician connectivity over standalone test hardware. Target acquisition archetypes include smartphone-integrated reader startups with established predicate device relationships. The signal to watch is FDA guidance finalization on AI-enabled result interpretation classifications.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) OTC Clearance Pathway | Accelerates commercialization timelines for smartphone-integrated readers in US pharmacy channels. |
| Telehealth Platform Partnership | Transforms one-time test sales into recurring revenue through remote clinician connectivity. |
| Backward Integration into Chemistries | Secures supply control over nitrocellulose membranes and antibody conjugates against Asian cost competition. |
| Software-as-Medical-Device Development | Captures value migration from physical strips to algorithmic interpretation layers. |
| EU MDR Recertification Investment | Maintains market access amid clinical evidence burdens that favor established post-market surveillance infrastructure. |
Research Methodology
Coverage spans the United States, Germany, China, India, and the United Kingdom, with primary inputs from each regional cluster. The research combines interviews with regulatory affairs leads at diagnostic manufacturers, telehealth platform product managers, hospital GPO contracts managers, and pharmacy chain category buyers with secondary validation. Sources include FDA 510(k) filings, BfArM device registrations, NMPA Class II approvals, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up unit economics and top-down market sizing were triangulated to produce volume and value estimates.
Granularity-level modeling addressed product type, usage mode, target demographic, and distribution channel dimensions across the projection horizon. CAGRs were derived from segment-level growth trajectory analysis incorporating regulatory pathway timelines, reimbursement expansion patterns, and telehealth platform adoption curves. Industry-specific forecast inputs included FDA software-as-medical-device guidance evolution and EU MDR recertification completion rates.
Inputs from regulatory filings and hospital procurement databases were available through the study window; gaps in real-time telehealth platform transaction data introduce uncertainty bands around subscription revenue projections. Forecasts reflect assumptions regarding FDA clearance pathway efficiency and state-level CLIA waiver harmonization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Endocrine Testing Market
Testing Services
Hospital Microbiology Testing Market
Testing Services
Anderson Cascade Impactor Market
Testing Services
Host Cell Protein Testing Market
Testing Services
Medical Device Testing Services Market
Testing Services
Employer and Workplace Drug Testing Market
Testing Services
Active B12 Test Market
Testing Services
Global C-Reactive Protein Testing Market
Testing Services
Irradiation Sterilization Services Market
Testing Services
Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market
Testing Services
Global Vitamin D Testing Market
Testing Services
Healthcare Analytical Testing Services Market
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
Activated Partial Thromboplastin Test Market
Testing Services
Global ADME Toxicology Testing Market
Testing Services
South America Endotoxin and Pyrogen Testing Market