
 Atherectomy Systems Market | 2026-2036
Atherectomy Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Atherectomy Systems Market Outlook
The capital-intensity divergence between integrated device manufacturers and focused catheter specialists is unwinding competitive stability across the atherectomy landscape. Medtronic leverages its broad interventional portfolio to bundle atherectomy with guidewire and balloon offerings in hospital purchasing agreements. Cardiovascular Systems Inc. sustains concentrated R&D spending on orbital diamond-coated crown technology, anchoring its position in calcified peripheral lesions. Abbott Laboratories competes through vascular closure integration, reducing procedural complexity for operators in high-throughput labs.
Atherectomy systems are percutaneous interventional devices employing mechanical cutting, laser ablation, or orbital sanding to remove atherosclerotic plaque from arterial lumens, typically operating through 6-8 French catheter delivery platforms with rotational speeds exceeding 80,000 RPM for mechanical variants. These systems restore vessel patency in peripheral and coronary territories where balloon angioplasty alone yields suboptimal results due to elastic recoil or dissection. Orbital atherectomy commands premium positioning in heavily calcified lesions where conventional approaches fail, while directional systems retain share in bifurcation anatomy requiring targeted plaque excision. Laser platforms occupy a narrower niche in saphenous vein graft disease and thrombotic occlusions, with electrical and radiofrequency modalities emerging as alternatives for soft plaque modulation.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements are elevating bench-testing and clinical evidence thresholds for new atherectomy entrants, compressing timelines for commercialization in both jurisdictions. ISO 13485 quality management systems and Japan PMDA foreign manufacturer registration create additional compliance layers for multinational device firms seeking broad geographic registration. Stakeholders must monitor evolving debris-embolization standards and real-world evidence mandates as payers link reimbursement to procedural safety metrics rather than device acquisition costs alone.
Market Dynamics
Orbital atherectomy platforms are fragmenting procedural economics in cardiac catheterization laboratories, forcing purchasing committees to weigh crown consumable costs against reduced bailout stenting rates in heavily calcified lesions.
Growth Catalysts
- EU MDR conformity assessments:Elevated bench-testing documentation for debris-capture mechanisms is filtering out marginal competitors and concentrating procurement among validated manufacturers in German vascular centers.
- Peripheral artery disease prevalence:Aging demographics in Japan and the United States are expanding addressable patient pools for directional atherectomy in below-the-knee interventions.
- Real-time intravascular imaging:Integration of OCT guidance with atherectomy catheters is improving operator precision and driving upgrade cycles in high-throughput labs.
Market Restraints
- Single-use crown economics:Diamond-coated orbital consumables carry per-procedure costs that strain fixed DRG reimbursement ceilings in US hospital systems.
- Nitinol supply concentration:Superelastic tubing for catheter shafts sources primarily from specialized US and European metallurgical suppliers, creating vulnerability to alloying element price swings.
- Laser platform substitution:Excimer systems for saphenous vein graft disease face compression from drug-coated balloon alternatives with simpler workflow requirements.
Strategic Opportunities
- Outpatient-based labs:Ambulatory surgical centers in Texas and Florida are expanding atherectomy volumes as site-of-service payment differentials reward lower-acuity settings.
- AI-integrated lesion assessment:Machine learning algorithms analyzing calcification patterns are converging with robotic catheter advancement to enable autonomous plaque modification.
- Japan PMDA foreign manufacturer registration:Streamlined pathways for quality-system-certified firms are opening direct market access without domestic distributor intermediaries.
Industry Challenges
- Cross-trained interventionalists:Shortage of operators proficient in both coronary and peripheral orbital techniques limits procedural expansion in community hospitals.
- ISO 13485 surveillance audits:Sustained compliance for multi-site manufacturing demands dedicated quality infrastructure that absorbs disproportionate overhead at smaller device firms.
- Legacy EMR integration:Procedural data capture from atherectomy consoles into hospital information systems requires custom interface development that delays fleet deployment.
Report Scope
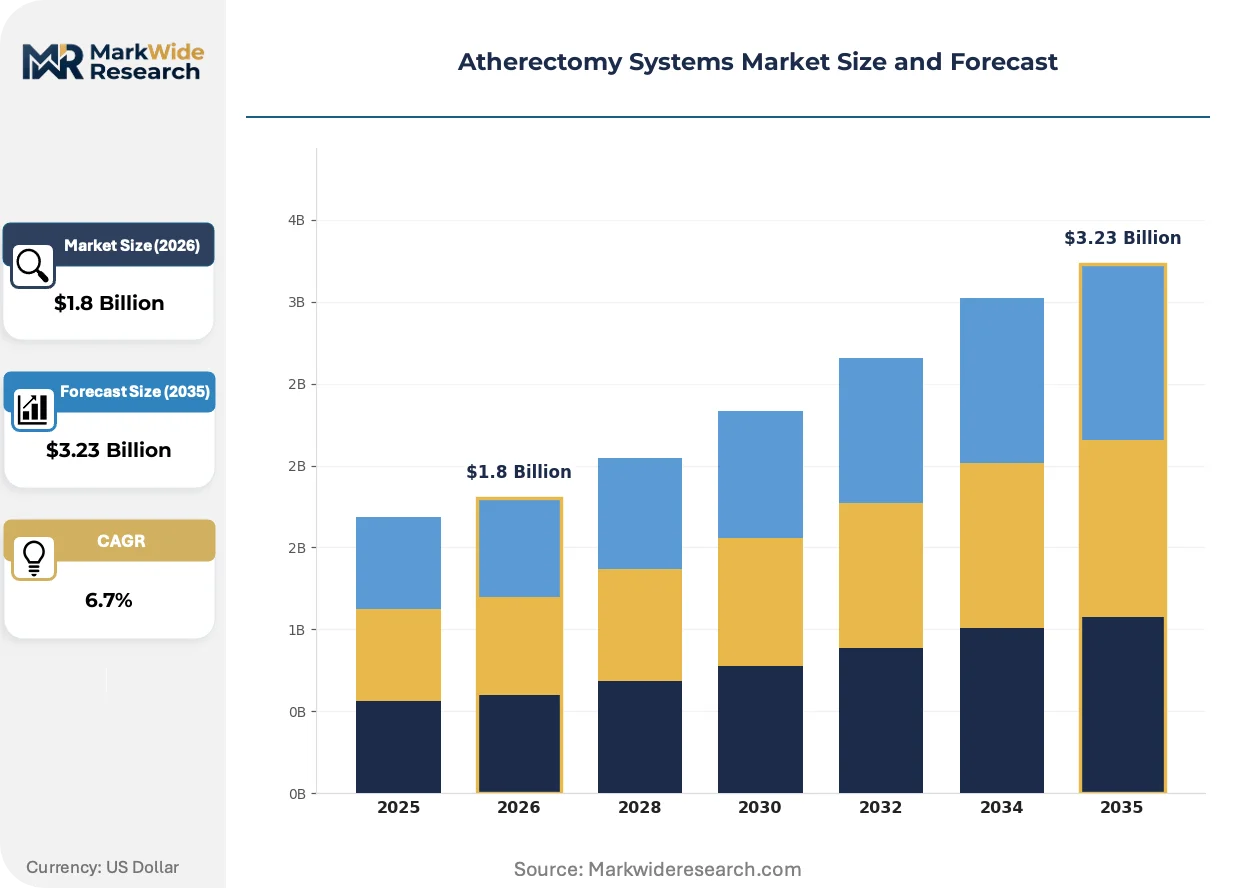
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atherectomy Systems Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Directional Atherectomy, Orbital Atherectomy, Laser Atherectomy, Rotational Atherectomy End User: Hospitals, Ambulatory Surgical Centers, Cardiac Catheterization Laboratories, Specialty Clinics Application: CVD, Peripheral Artery Disease, Coronary Artery Disease, Dialysis Access Treatment Technology: Mechanical, Laser, Radiofrequency, Electrical |
| Companies Covered | Cardiovascular Systems Inc., Boston Scientific Corporation, Medtronic, Abbott Laboratories, Koninklijke Philips N.V., Becton Dickinson and Company, AngioDynamics, Avinger Inc., Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atherectomy Systems Market Strategic Shifts
Debris management protocols and crown material science are redefining competitive differentiation, with manufacturers racing to demonstrate capture efficiency under increasingly stringent embolization monitoring standards.
Next-generation orbital crowns with variable grit diamond coatings are decomposing the historical trade-off between aggressive plaque modification and distal embolization risk. Academic medical centers in Cleveland and Rotterdam are adopting these platforms for nodular calcium cases previously deemed prohibitive. The technology is decomposing referral patterns by enabling successful intervention in patient cohorts that previously bypassed endovascular options for surgical bypass.
FDA 510(k) premarket notification requirements are tightening clinical evidence thresholds for new atherectomy entrants, demanding larger bench-test matrices and extended follow-up registries. The agency's renewed scrutiny of particulate generation data is extending review timelines and compressing commercialization windows. Startups are responding by front-loading predicate-device equivalence arguments and engaging the FDA's pre-submission pathway earlier in development cycles.
Hospital purchasing committees are consolidating vendor relationships through bundled device agreements that link atherectomy system procurement to guidewire and balloon catheter volume commitments. This behavior is displacing standalone catheter specialists from preferred vendor status in integrated delivery networks. The shift is most visible in US multi-hospital systems where supply chain standardization overrides individual physician preference.
Atherectomy Systems Market Segmentation
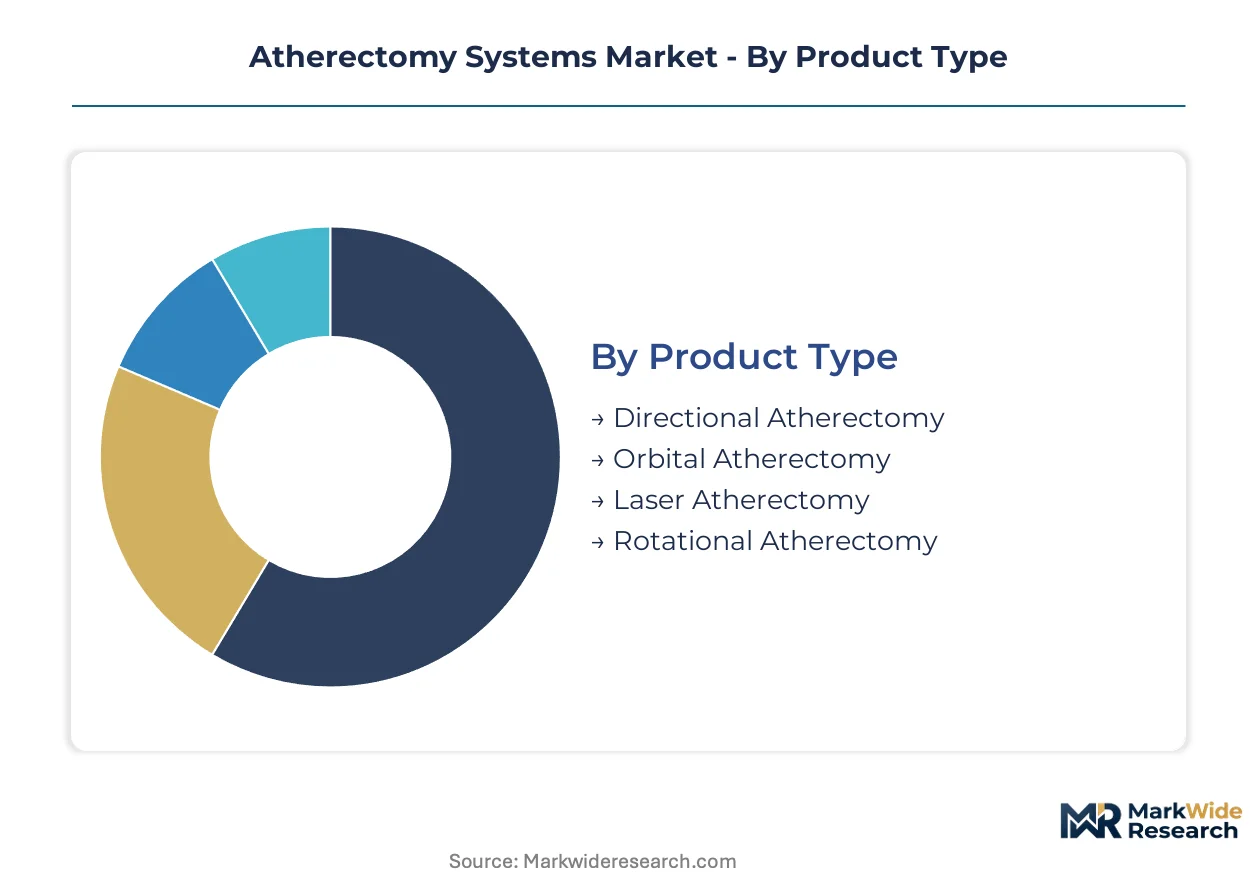
Segmentation in atherectomy systems reveals how procedure economics and reimbursement patterns concentrate value across technology platforms and care settings. Understanding where margin pools sit within each dimension enables manufacturers to prioritize R&D allocation and commercial deployment.
Product Type:
Margin pools concentrate in orbital and directional platforms where consumable recurring revenue and premium positioning in calcified lesions sustain pricing power.
- Orbital Atherectomy:Diamond-coated crown technology operating at rotational speeds exceeding 80,000 RPM enables plaque modification in heavily calcified coronary and peripheral lesions. Demand concentrates in German vascular centers and US academic medical centers where operators manage nodular calcium cases previously routed to surgical bypass.
- Directional Atherectomy:Cutting blade mechanisms with differential cutting action target eccentric plaque in bifurcation anatomy and below-the-knee interventions. Adoption is rotating up in Japan as aging demographics expand peripheral artery disease procedural volumes.
- Laser Atherectomy:Excimer laser platforms ablate thrombotic occlusions and saphenous vein graft disease through photochemical decomposition.
- Rotational Atherectomy:Burr-based systems using olive-shaped diamond chips maintain niche positioning in coronary calcified lesions.
Orbital atherectomy holds installed capacity in high-throughput cardiac catheterization laboratories. Directional atherectomy is rotating up the share rankings as below-the-knee indications expand.
End User:
Procurement authority and volume concentration determine competitive access across facility types with divergent capital and consumable purchasing patterns.
- Hospitals:Integrated delivery networks leverage bundled purchasing agreements linking atherectomy systems to guidewire and balloon catheter volume commitments. Demand concentrates in multi-hospital systems where supply chain standardization overrides individual physician preference.
- Cardiac Catheterization Laboratories:Dedicated interventional suites generate high procedural throughput with specialized operator expertise in orbital and directional techniques. Facilities in Cleveland and Rotterdam are adopting next-generation crown platforms for complex calcification patterns.
- Ambulatory Surgical Centers:Site-of-service payment differentials in Texas and Florida are expanding outpatient-based atherectomy volumes.
- Specialty Clinics:Focused vascular centers concentrate procedural expertise in peripheral interventions.
Cardiac catheterization laboratories hold installed capacity for premium platform deployment. Ambulatory surgical centers are rotating up the share rankings as payment differentials reward lower-acuity settings.
Application:
Clinical indication severity and lesion complexity drive technology selection and reimbursement tiering across vascular territories.
- Peripheral Artery Disease:Below-the-knee and femoropopliteal interventions dominate directional atherectomy utilization where elastic recoil limits balloon angioplasty efficacy. Demand concentrates in Japan and the United States as diabetes prevalence and aging populations expand addressable patient pools.
- Coronary Artery Disease:Calcified lesion modification in left main and bifurcation anatomy commands premium orbital platform positioning. Academic medical centers are expanding indications for nodular calcium previously deemed prohibitive.
- CVD:Broader cardiovascular disease management integrates atherectomy within comprehensive revascularization strategies.
- Dialysis Access Treatment:Arteriovenous fistula maintenance represents a specialized peripheral application.
Peripheral artery disease holds installed capacity across established vascular centers. Coronary artery disease is rotating up the share rankings as calcified lesion techniques advance.
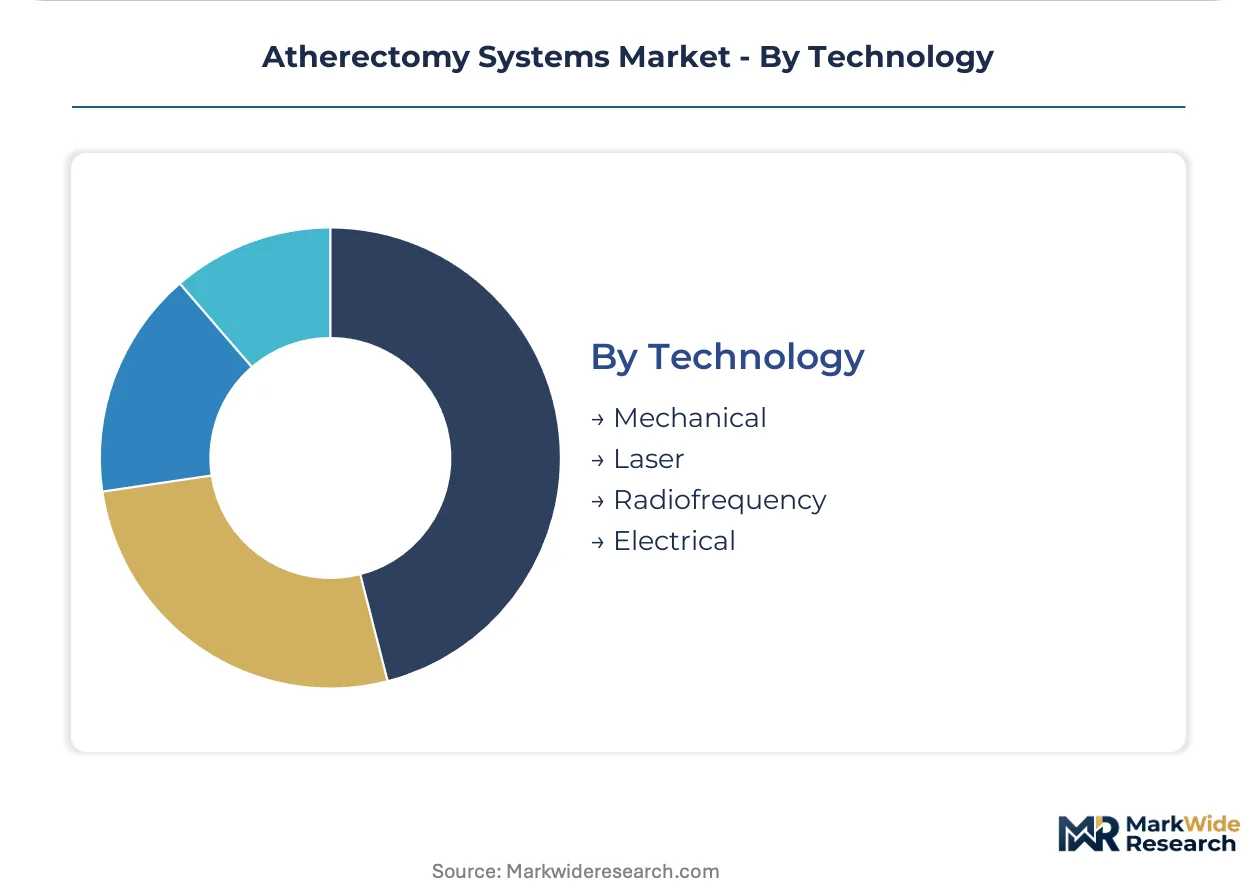
Technology:
Energy delivery mechanisms and material science differentiation determine competitive positioning and regulatory evidence requirements.
- Mechanical:Rotational and orbital systems using diamond-coated crowns or cutting blades command the majority of procedural volume through established clinical evidence and operator familiarity. FDA 510(k) pathways and EU MDR conformity assessments favor predicate-device equivalence arguments for mechanical platforms.
- Laser:Excimer systems occupy specialized niches in thrombotic and graft disease where photochemical ablation offers unique tissue interaction.
- Radiofrequency:Emerging modalities for soft plaque modulation are gaining regulatory attention.
- Electrical:Novel energy delivery approaches are entering bench-testing and early clinical evaluation phases.
Mechanical technology holds installed capacity with established reimbursement and operator training pathways. Laser platforms are rotating up the share rankings in specialized graft disease applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing for orbital platforms in calcified lesions while the United States absorbs higher per-procedure consumable costs under fixed DRG ceilings. This asymmetry concentrates margin capture in European vascular centers and compresses profitability for US hospital systems.
United States
Ambulatory surgical centers in Texas and Florida are expanding atherectomy volumes as site-of-service payment differentials reward lower-acuity settings. FDA 510(k) premarket notification requirements are tightening clinical evidence thresholds for particulate generation data. Cleveland Clinic anchors adoption of next-generation crown platforms for nodular calcium cases previously routed to surgical bypass.
Germany
Specialized vascular centers in Bavaria and North Rhine-Westphalia drive procedural volumes for orbital and directional platforms. EU MDR conformity assessments are filtering out marginal competitors through elevated bench-testing documentation for debris-capture mechanisms. The Rhine-Ruhr metropolitan cluster concentrates procurement authority among validated manufacturers with established quality management systems.
Japan
Aging demographics are expanding addressable patient pools for directional atherectomy in below-the-knee interventions. PMDA foreign manufacturer registration pathways are streamlining direct market access for quality-system-certified firms without domestic distributor intermediaries. Tokyo and Osaka academic medical centers are integrating OCT guidance with atherectomy catheters to improve operator precision.
United Kingdom
NHS procurement frameworks are consolidating vendor relationships through bundled device agreements linking atherectomy systems to guidewire and balloon catheter volume commitments. MHRA post-Brexit regulatory alignment with EU MDR technical documentation requirements is maintaining compliance continuity. London and Manchester integrated delivery networks are standardizing supply chains across multi-hospital systems.
China
Domestic manufacturers are gaining NMPA approval for mechanical atherectomy platforms through predicate-device equivalence arguments. National reimbursement catalog updates are expanding coverage for peripheral artery disease interventions in tier-one cities. Shanghai and Beijing cardiac catheterization laboratories are upgrading interventional suites with integrated imaging and atherectomy capabilities.
Atherectomy Systems Market Competitive Environment
Concentration sits with diversified cardiovascular device conglomerates that leverage broad interventional portfolios to bundle atherectomy with complementary catheter offerings. Three archetypes define competitive positioning: integrated device manufacturers with hospital purchasing agreements, focused catheter specialists with concentrated R&D on crown material science, and diversified medtech conglomerates with vascular closure integration. Dominant competitive moves include strategic bundling of consumables with capital equipment and backward integration into nitinol tubing supply chains.
Among US-based diversified manufacturers, Medtronic, Boston Scientific Corporation, and Abbott Laboratories exemplify the integrated device archetype. Medtronic occupies a position leveraging broad interventional portfolio breadth. Boston Scientific Corporation represents the catheter platform specialist tier with concentrated orbital technology development. Abbott Laboratories anchors the vascular closure integration vector, reducing procedural complexity for high-throughput laboratory operators.
| Leading Market Players |
|---|
| Cardiovascular Systems Inc. |
| Boston Scientific Corporation |
| Medtronic |
| Abbott Laboratories |
| Koninklijke Philips N.V. |
| Becton Dickinson and Company |
| AngioDynamics |
| Avinger Inc. |
| Terumo Corporation |
| Others |
Value Chain & Pricing Dynamics
Variable-grit diamond coatings replacing uniform-crown abrasives are redistributing procurement leverage toward specialized German and Japanese metallurgical suppliers while compressing margin capture for US hospital systems locked into fixed DRG reimbursement ceilings. This substitution dynamic concentrates premium pricing power in validated manufacturers with captive superelastic tubing supply chains.
Pricing Analysis
The customization-premium spread separates configured-to-order orbital crowns with patient-specific calcification mapping from standard catalog offerings. Per-procedure consumable economics dominate hospital purchasing decisions, with diamond-coated orbital crowns commanding substantial premiums over directional cutting blades. Price differentiation rests on debris-capture efficiency certification tiers and crown longevity metrics. Cost compression in standard-tier mechanical platforms is intensifying because of bundled purchasing agreements linking atherectomy systems to guidewire volume commitments. Ambulatory surgical centers in Texas and Florida exhibit the highest price sensitivity, while German vascular centers demonstrate lowest sensitivity due to outcome-based reimbursement frameworks.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port clusters constrain just-in-time delivery of nitinol superelastic tubing from specialized US and European metallurgical suppliers. Manufacturing concentration centers on Germany, the United States, and Japan for finished catheter systems. Raw material dependencies include nickel-titanium alloys, synthetic diamond abrasives, and precision polymer extrusions. Single-source vulnerability in nitinol alloying element supply creates exposure to commodity price swings in nickel and titanium feedstocks. Distribution runs through integrated delivery network procurement committees and specialized cardiovascular device distributors serving cardiac catheterization laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proficiency in both coronary and peripheral orbital techniques represents a scarce operator capability that constrains procedural expansion and concentrates value capture among training-intensive academic medical centers. Bridging this skill gap determines competitive positioning across community hospital settings.
For Market Incumbents: Consolidate backward integration into nitinol tubing supply chains to secure captive access against alloying element price volatility. Lock in multi-year hospital purchasing agreements bundling atherectomy capital equipment with consumable volume commitments to displace standalone catheter specialists. Prioritize ISO 13485 quality infrastructure investment to sustain compliance through EU MDR surveillance audits and compress competitor commercialization timelines. For New Entrants and Emerging Players: Post-procedure debris management services represent an under-served layer where incumbents lack dedicated clinical support infrastructure. Target ambulatory surgical centers in Texas and Florida where site-of-service payment differentials reward lower-acuity settings and purchasing committees lack incumbent loyalty. Deploy direct-to-facility technical training programs as the primary go-to-market angle, building operator proficiency that differentiates against bundled vendor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed catheter specialists holding concentrated orbital crown R&D portfolios and established FDA 510(k) predicate pathways. Long-term viability hinges on reimbursement durability as payers shift from device acquisition costs toward procedural safety metrics. Monitor real-world evidence mandates linking debris-embolization rates to coverage decisions as the critical inflection indicator for portfolio valuation trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Notification | Accelerated clearance pathways compress commercialization timelines for predicate-device equivalence arguments. |
| EU MDR Conformity Assessment | Elevated bench-testing documentation filters marginal competitors from German vascular center procurement. |
| Hospital System Partnership | Bundled agreements linking atherectomy to guidewire volumes displace standalone catheter specialists. |
| Software Companion Development | AI-integrated lesion assessment algorithms converge with robotic catheter advancement for autonomous plaque modification. |
| Reimbursement Strategy | Outcome-based contracts with CMS and commercial payers align device economics with procedural safety metrics. |
Study Parameters
Cross-validation between primary interviews with interventional cardiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up procedural volume modeling triangulates with top-down market sizing across the analysis window.
Sensitivity analysis around nitinol supply concentration and DRG reimbursement ceiling adjustments tests forecast robustness. Segmentation dimensions include product type, end user facility category, clinical application, and energy delivery technology across the projection horizon. CAGRs derive from installed base expansion rates and per-procedure consumable attach rates, with inputs from aging demographic trajectories and diabetes prevalence curves.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EU MDR conformity assessments; material policy shifts in debris-embolization standards or real-world evidence mandates would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Neurovascular Coiling Assist Devices Market
Cardiovascular Devices
Disposable Blood Pressure Cuffs Market
Cardiovascular Devices
Dual Therapy Stent Market
Cardiovascular Devices
Intra-Aortic Balloon Pump (IABP) Market
Cardiovascular Devices
Global Catheters Market
Cardiovascular Devices
Vascular Access Catheters Market
Cardiovascular Devices
Global External Ventricular Drain Market
Cardiovascular Devices
Ventricular Drainage Sets Market
Cardiovascular Devices
Peripheral Intravenous Catheters Market
Cardiovascular Devices
South Korea Cardiovascular Devices Market
Cardiovascular Devices
Cardiac Catheters Market
Cardiovascular Devices
Interventional Cardiology Market
Cardiovascular Devices
Global Heart Valve Repair and Replacement Market
Cardiovascular Devices
Cardiac Surgery Devices Market
Cardiovascular Devices
Global Vascular Stents Market
Cardiovascular Devices
Australia Cardiovascular Devices Market