
 Artificial Corneal Implants Market | 2026-2036
Artificial Corneal Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Corneal Implants Market Intelligence
Hospital procurement of keratoprosthesis devices is hardening as tertiary care centers consolidate ophthalmology service lines. CorNeat Vision leverages synthetic collagen integration to anchor its position in high-acuity surgical settings. Alcon Inc. sustains manufacturing scale across its ophthalmic implant portfolio through captive supply chains. Carl Zeiss Meditec AG differentiates via laser-assisted surgical workstation bundling with corneal implant procedures.
Artificial corneal implants are synthetic or bioengineered devices designed to replace damaged corneal tissue, typically manufactured from medical-grade polymers such as poly(methyl methacrylate) or porous collagen scaffolds engineered to promote stromal cell ingrowth. Their primary purpose is restoring optical clarity in patients with corneal blindness where donor tissue is unavailable or contraindicated. Bioengineered cornea segments occupy the fastest-expanding margin pool as tissue engineering platforms advance toward off-the-shelf availability. Synthetic implants still dominate procedural volume due to established reimbursement pathways and longer clinical track records. 3D bioprinting technology is reshaping manufacturing economics by enabling patient-specific stromal architecture.
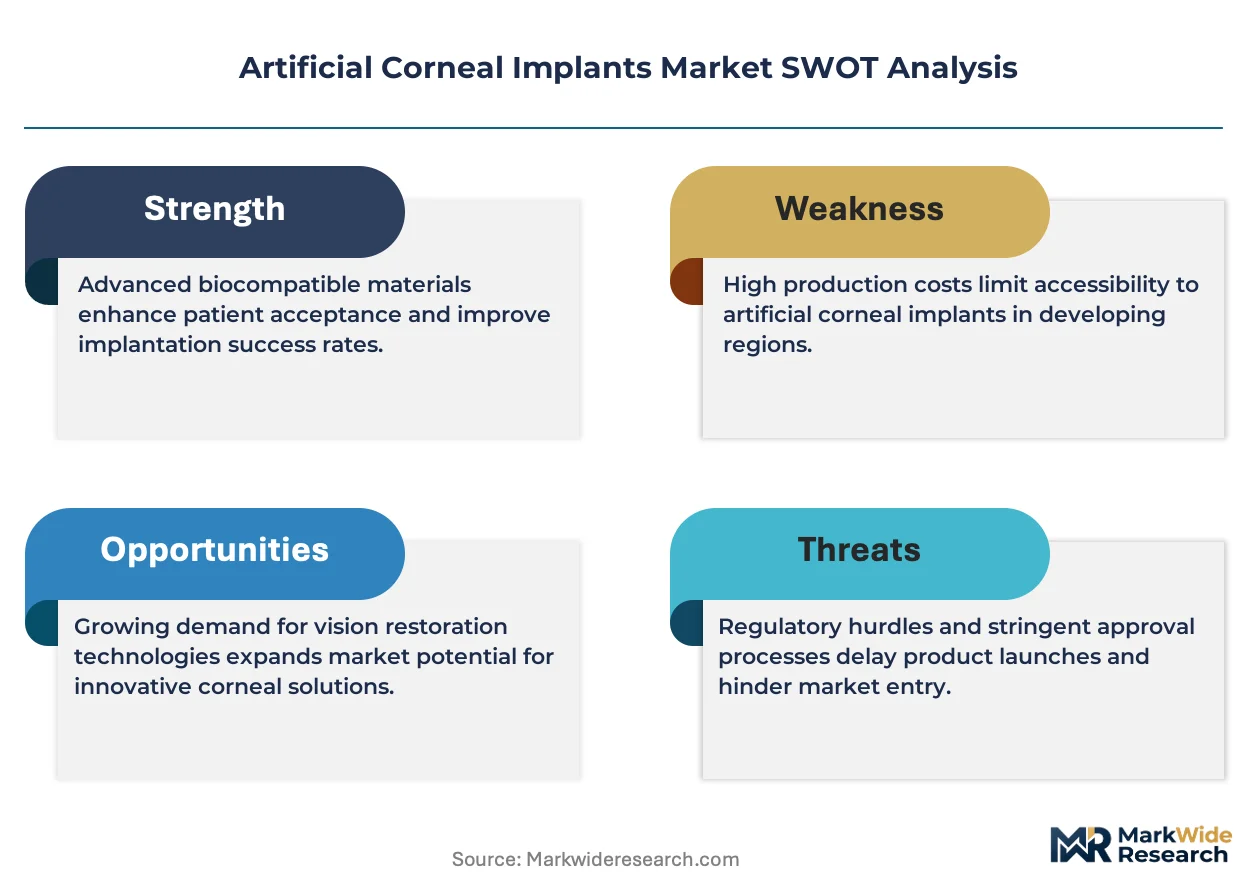
FDA breakthrough device designation and EU MDR Class III implant pathways shape market access timelines and clinical evidence requirements for new entrants. ISO 14155 and ISO 10993 biocompatibility standards govern preclinical validation protocols across all major commercial jurisdictions. Stakeholders must monitor how FDA and EMA convergence on real-world evidence requirements for ophthalmic implants will alter post-market study obligations and competitive positioning.
Market Dynamics
Corneal donor tissue scarcity is compressing procurement timelines for tertiary ophthalmology centers and accelerating synthetic platform validation. This supply-constraint pressure is restructuring device economics and clinical trial prioritization across all major commercial jurisdictions.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways compress regulatory validation timelines for keratoprosthesis platforms seeking initial market authorization.
- EU MDR Class III Implant Pathway:Harmonized conformity assessment procedures enable faster cross-border commercialization for synthetic cornea manufacturers.
- 3D Bioprinting:Patient-specific stromal architecture fabrication reduces material waste and enables geometric customization previously impossible with subtractive manufacturing.
Market Restraints
- Medical-Grade PMMA Cost Volatility:Petrochemical feedstock fluctuations compress margin stability for synthetic implant producers dependent on polymer supply chains.
- EU MDR Clinical Evidence Requirements:Expanded post-market surveillance obligations extend reimbursement negotiation timelines and increase regulatory compliance expenditure.
- Allogeneic Transplant Substitution:Improved eye banking logistics and donor recruitment in select markets preserve biological tissue preference for eligible candidates.
Strategic Opportunities
- Japan PMDA Priority Review:Designated orphan medical device status offers fee reductions and consultation acceleration for keratoprosthesis innovators.
- Teleophthalmology Triage Integration:Remote screening protocols expand addressable patient pools by identifying surgical candidates in underserved rural prefectures.
- Collagen-PMMA Hybrid Convergence:Bioengineered scaffolds combining synthetic durability with biological integration capture premium positioning in high-acuity surgical settings.
Industry Challenges
- Ocular Biomechanics Simulation Expertise:Finite element modeling of corneal load distribution requires specialized computational talent scarce outside academic ophthalmology departments.
- ISO 10993 Cytotoxicity Certification:Extended biocompatibility testing timelines delay product launches even after functional validation completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Corneal Implants Market |
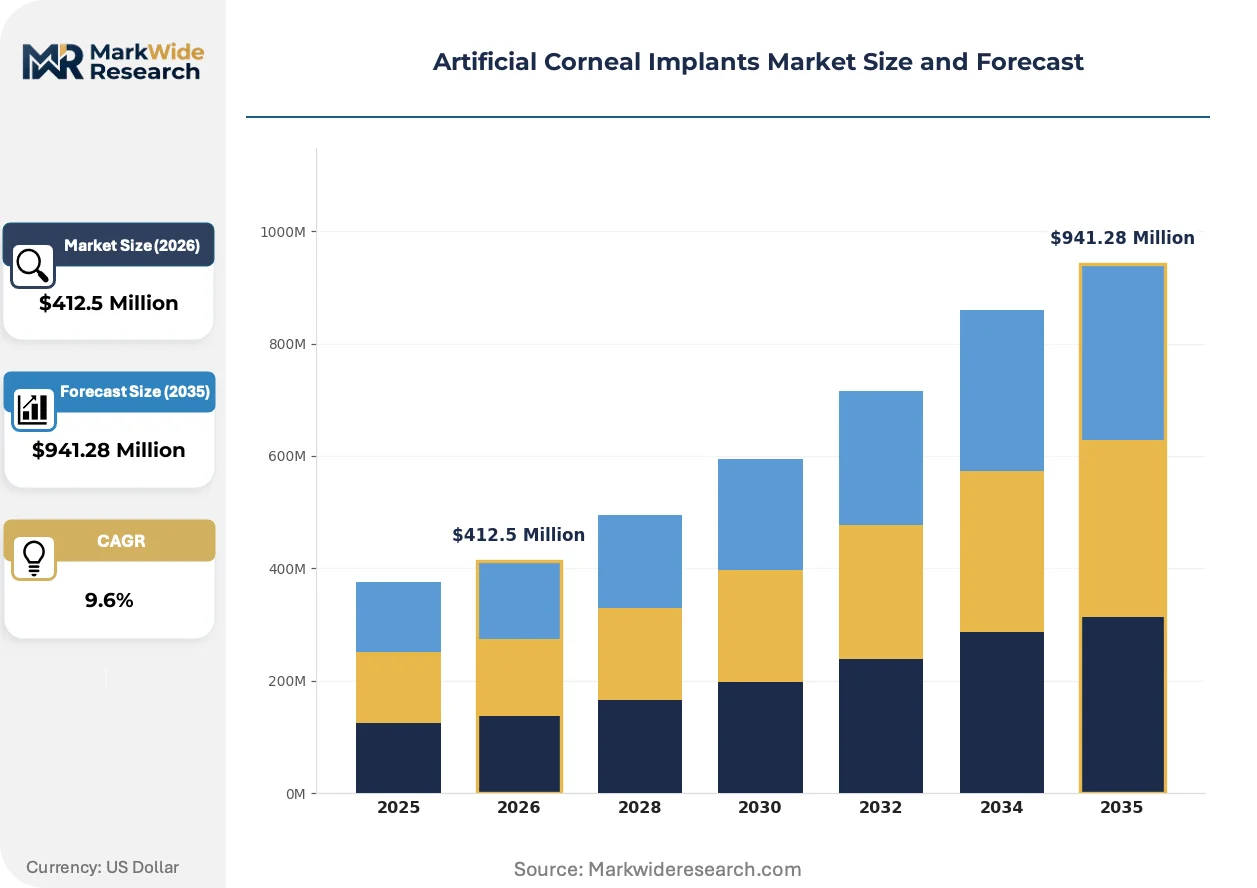
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $941.28 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artificial Cornea, Bioengineered Cornea, Synthetic Implants, Stem Cell-derived Implants Delivery Mode: Surgical Procedure, Outpatient Procedure, Intraoperative Method, Post-surgical Care End User: Hospitals, Eye Clinics, Ambulatory Surgical Centers, Research Institutes Technology: Tissue Engineering, Laser-Assisted Techniques, Micro-invasive Techniques, 3D Bioprinting |
| Companies Covered | CorNeat Vision, EyeYon Medical, LinkoCare Life Sciences AB, Presbia plc, CorneaGen Inc., Aurolab, Alcon Inc., Carl Zeiss Meditec AG, AJL Ophthalmic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Corneal Implants Market Strategic Shifts & Innovations
Manufacturing platforms and clinical validation protocols are converging around patient-specific geometries and real-world evidence generation. These shifts are compressing traditional development cycles while expanding treatable indications.
Porous collagen scaffolds engineered for stromal cell ingrowth are overtaking solid polymer implants in preclinical pipeline volume. Tertiary care centers in Germany and Japan are prioritizing these platforms for complex revision cases where synthetic integration has failed. The technology is overtaking established PMMA dominance by enabling biological anchoring without immunosuppression protocols.
EU MDR real-world evidence requirements for Class III implants are reshaping post-market study design across ophthalmic device portfolios. Manufacturers must now integrate clinical registries into commercial infrastructure rather than treating follow-up as episodic regulatory obligation. Synthetic cornea segments face the steepest compliance cost escalation due to limited historical surveillance datasets.
Hospital service line consolidation is compressing vendor qualification lists and lengthening contract renewal cycles. Integrated delivery networks in the United States are bundling keratoprosthesis procurement with laser-assisted surgical workstation packages. Germany exhibits the most pronounced concentration, with university hospitals centralizing high-complexity anterior segment surgery into designated excellence centers.
Artificial Corneal Implants Market Segmentation
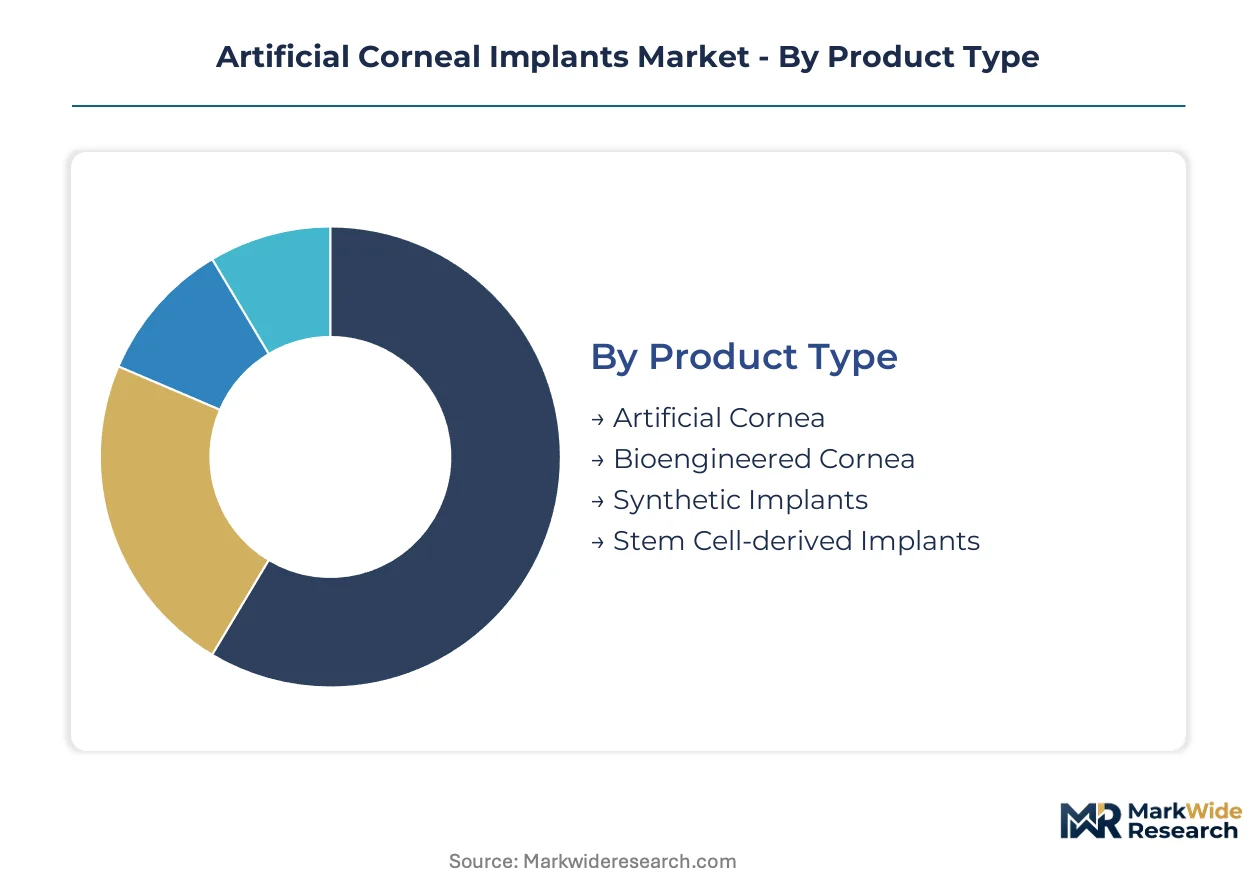
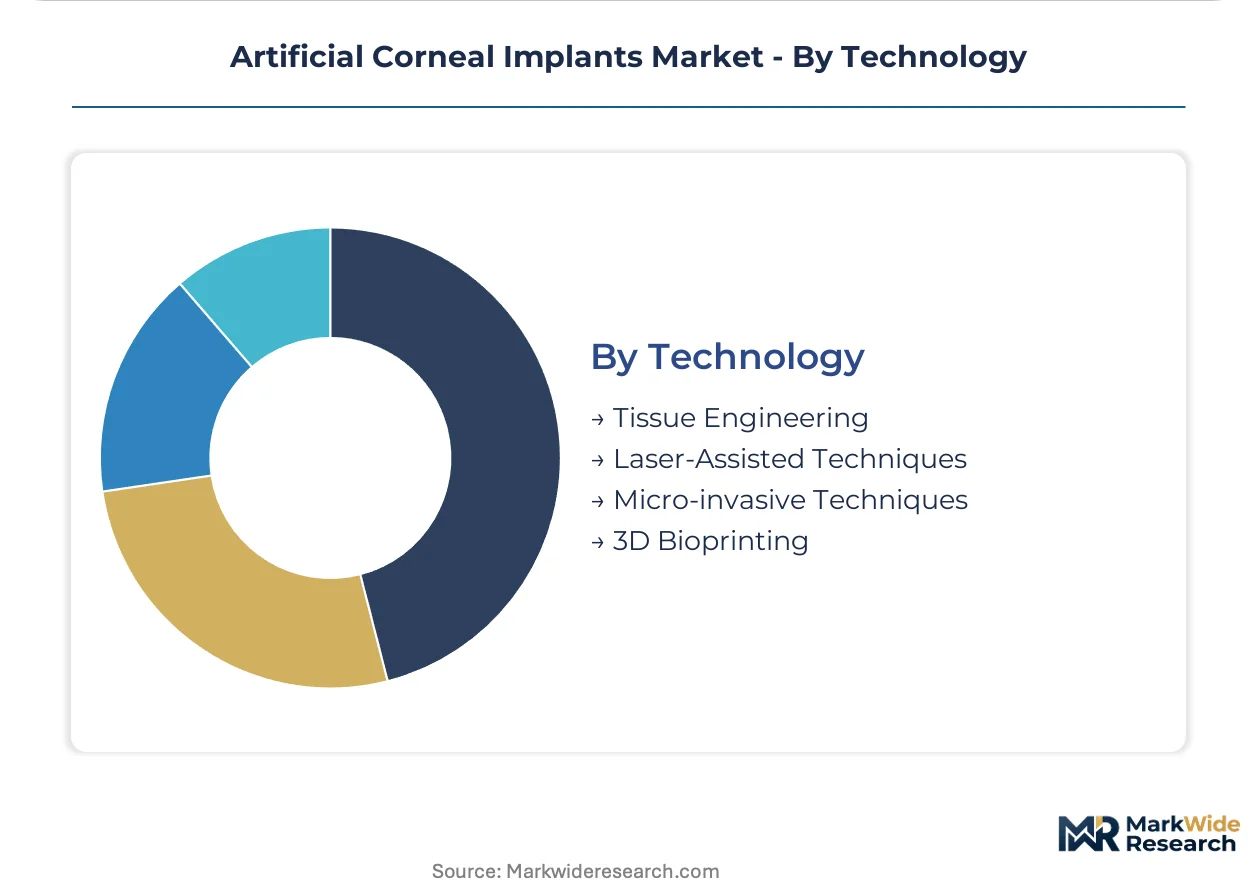
Artificial corneal implant procurement patterns diverge sharply across clinical settings and technological platforms. Manufacturers must align product development with distinct reimbursement pathways and surgical workflow requirements that vary by segment.
Product Type:
Cost tier separates emergency keratoplasty candidates from elective restoration cases.
- Artificial Cornea:PMMA-based optical cylinders with titanium fixation rings dominate high-acuity surgical settings. United States tertiary centers prioritize these devices for chemical burn and autoimmune-mediated corneal melt cases where biological integration carries excessive failure risk.
- Bioengineered Cornea:Porous collagen scaffolds engineered for stromal cell ingrowth enable biological anchoring without immunosuppression. German university hospitals are concentrating procurement of these platforms for complex revision surgeries where synthetic integration has previously failed.
- Synthetic Implants:Established reimbursement codes and longer clinical track records sustain procedural volume in conventional keratoprosthesis.
- Stem Cell-derived Implants:Laboratory-cultured autologous constructs remain investigational with limited commercial availability.
Volume sits with Synthetic Implants; growth tilts toward Bioengineered Cornea.
Delivery Mode:
Application setting determines anesthesia requirements and facility fee structures.
- Surgical Procedure:Full-thickness keratoplasty under general anesthesia occupies dedicated operating theaters. Japanese ophthalmology departments reserve these slots for combined procedures incorporating laser-assisted workstation integration.
- Outpatient Procedure:Local anesthesia protocols with same-day discharge compress total episode cost. Ambulatory surgical centers in the United States are expanding capacity for these cases to capture bundled reimbursement margins.
- Intraoperative Method:Device insertion during concurrent anterior segment reconstruction.
- Post-surgical Care:Scheduled follow-up protocols for device monitoring and complication management.
Facility economics favor Outpatient Procedure; complexity premiums attach to Surgical Procedure.
End User:
Customer type dictates purchasing authority and vendor qualification requirements.
- Hospitals:Integrated delivery networks negotiate multi-year contracts bundling keratoprosthesis with capital equipment. Consolidated ophthalmology service lines in the United States are hardening vendor lists and extending renewal cycles.
- Eye Clinics:Specialized anterior segment practices concentrate high-complexity referral volumes. German university-affiliated clinics are centralizing into designated excellence centers with concentrated procurement leverage.
- Ambulatory Surgical Centers:Cost-sensitive settings prioritizing outpatient-compatible devices.
- Research Institutes:Preclinical validation and clinical trial coordination for emerging platforms.
Procurement authority concentrates in Hospitals; agility concentrates in Eye Clinics.
Technology:
Maturity curves separate validated manufacturing from experimental platforms.
- Tissue Engineering:Collagen scaffold fabrication with controlled porosity dominates bioengineered segment advancement. PMDA priority review designation in Japan is accelerating consultation timelines for orphan medical device innovators in this category.
- Laser-Assisted Techniques:Femtosecond trephination and stromal bed preparation integrate with surgical workstation ecosystems. Carl Zeiss Meditec AG bundles these capabilities with corneal implant procedures to differentiate positioning.
- Micro-invasive Techniques:Reduced-incision insertion methods for select synthetic platforms.
- 3D Bioprinting:Patient-specific stromal architecture fabrication compresses material waste and enables geometric customization.
Clinical validation concentrates in Tissue Engineering; manufacturing disruption concentrates in 3D Bioprinting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States, Germany, and Japan concentrate demand for artificial corneal implants due to persistent corneal donor shortages and advanced tertiary ophthalmology infrastructure. Procurement patterns vary sharply across regulatory jurisdictions and reimbursement frameworks.
United States
FDA breakthrough device designation accelerates market access for keratoprosthesis innovators targeting chemical burn and autoimmune-mediated corneal melt cases. Medicare bundled payment pilots for anterior segment surgery reshape hospital procurement economics. Tertiary care centers in Massachusetts and California consolidate ophthalmology service lines into designated excellence hubs.
Germany
EU MDR Class III implant pathways harmonize conformity assessment for synthetic cornea manufacturers seeking cross-border commercialization. University hospitals in Bavaria and North Rhine-Westphalia centralize high-complexity anterior segment surgery into excellence centers with concentrated procurement leverage. German eye banks report chronic donor tissue deficits exceeding surgical waitlist capacity.
Japan
PMDA orphan medical device priority review offers fee reductions and consultation acceleration for keratoprosthesis innovators. Japan's aging demographic compresses corneal donor availability while expanding surgical candidacy pools. Tokyo and Osaka metropolitan clusters concentrate specialized anterior segment practices with laser-assisted surgical workstation integration.
India
CDSCO medical device rules govern import licensing for synthetic cornea platforms while domestic manufacturing incentives expand local production capacity. Corneal blindness prevalence exceeds donor tissue supply by an order of magnitude in Maharashtra and Tamil Nadu. Chennai and Hyderabad host emerging tissue engineering research clusters targeting off-the-shelf bioengineered cornea development.
United Kingdom
MHRA post-Brexit regulatory autonomy enables accelerated market access pathways for breakthrough ophthalmic implants while maintaining ISO 14155 clinical trial standards. NHS England specialized commissioning frameworks concentrate keratoprosthesis procedures into designated supra-regional centers. London and Manchester ophthalmology departments prioritize bioengineered collagen scaffold platforms for complex revision cases.
Artificial Corneal Implants Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue bioengineered scaffold differentiation and 3D bioprinting manufacturing disruption. The vendor base stratifies across three maturity tiers: multinational ophthalmic device conglomerates with captive supply chains; mid-cap specialists leveraging tissue engineering platforms; and pre-revenue innovators targeting regulatory fast-track designations. Dominant competitive moves include strategic partnerships with tertiary care centers for clinical validation and technology licensing agreements for patient-specific manufacturing capabilities.
Among Israel-based innovators, CorNeat Vision exemplifies the bioengineered scaffold archetype through synthetic collagen integration positioning. Alcon Inc. and Carl Zeiss Meditec AG represent contrasting scale-driven strategies—the former sustaining manufacturing breadth across ophthalmic implant portfolios, the latter differentiating via laser-assisted surgical workstation bundling with corneal procedures. These three anchors illustrate how competitive positioning diverges across technological maturity curves and customer integration depth.
| Leading Market Players |
|---|
| CorNeat Vision |
| EyeYon Medical |
| LinkoCare Life Sciences AB |
| Presbia plc |
| CorneaGen Inc. |
| Aurolab |
| Alcon Inc. |
| Carl Zeiss Meditec AG |
| AJL Ophthalmic |
| Others |
Cost & Logistics Intelligence
Tertiary care center consolidation across United States integrated delivery networks is compressing vendor lists and hardening procurement leverage, driving a contract-based pricing model where multi-year agreements bundle keratoprosthesis devices with laser-assisted surgical workstation packages. This buyer concentration is reshaping how manufacturers structure volume discounts and service-level commitments.
Pricing Analysis
Volume sits with synthetic PMMA implants sustained by established reimbursement codes, while margins concentrate in bioengineered collagen scaffolds capturing premium positioning for complex revision cases. Pricing stratifies across premium bioengineered tiers, standard synthetic platforms, and economy imported alternatives, with differentiation driven by FDA breakthrough designation status and ISO 10993 biocompatibility certification grade. Cost compression in the synthetic tier is intensifying as petrochemical feedstock volatility squeezes polymer-dependent producers. Ambulatory surgical centers exhibit highest price sensitivity due to bundled reimbursement constraints, while German university hospital excellence centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
India's PLI scheme for medical device manufacturing and domestic-content preferences in Japan's PMDA procurement frameworks are reshaping sourcing strategies for multinational ophthalmic implant producers. Medical-grade PMMA polymer production concentrates in the United States, Germany, and Japan, with porous collagen scaffold fabrication drawing from Israeli and Swedish tissue engineering clusters. Single-source vulnerability in medical-grade polymer feedstocks creates exposure to petrochemical price swings. Distribution runs through hospital GPO contracts in North America, direct university hospital agreements in Germany, and specialized anterior segment clinic networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR Class III implant pathways have erected a cost-of-compliance barrier that favors incumbents with established clinical registries and post-market surveillance infrastructure, creating a defensive moat against undercapitalized entrants lacking real-world evidence generation capabilities.
For Market Incumbents: Anchor market position through captive supply chain control over medical-grade PMMA polymer sources and backward integration into collagen scaffold fabrication. Prioritize certification investment in ISO 14155 clinical trial standards to accelerate EU MDR conformity assessment timelines. Defend against bioengineered scaffold substitution by bundling synthetic implants with laser-assisted surgical workstation partnerships. For New Entrants and Emerging Players: Capture white-space opportunity in India's CDSCO-regulated domestic manufacturing corridor, where corneal blindness prevalence exceeds donor tissue supply by an order of magnitude. Target Japan's PMDA orphan medical device priority review pathway for fee-reduced consultation acceleration. Pursue teleophthalmology triage integration as a go-to-market angle to identify surgical candidates in underserved rural prefectures. For Investors and Strategic Acquirers: The window for entry favors tissue engineering platform specialists with 3D bioprinting manufacturing capabilities and pre-revenue innovators holding FDA breakthrough device designation. Acquisition target archetype: mid-cap specialists with EU MDR technical documentation packages already assembled. Watch for PMDA priority review designations as inflection indicators of regulatory de-risking.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated review pathways compress regulatory validation timelines for keratoprosthesis innovators. |
| EU MDR Class III Technical Documentation | Harmonized conformity assessment enables cross-border commercialization for synthetic cornea manufacturers. |
| Hospital System Partnership | Integrated delivery network bundling secures multi-year procurement contracts with ophthalmology service lines. |
| Collagen Scaffold Manufacturing Scale-Up | Controlled porosity fabrication capacity captures premium positioning in German university hospital excellence centers. |
| Reimbursement Strategy | Medicare bundled payment pilot alignment reshapes hospital procurement economics for anterior segment surgery. |
Research Approach
FDA 510(k) and PMA filings, EU MDR notified body documentation, and CMS Medicare reimbursement databases formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with corneal surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers validated procedural volume estimates and procurement pattern shifts. Top-down triangulation against ophthalmic device industry reports and bottom-up build from hospital service line data ensured cross-verification of market estimates.
Bottom-up modeling of keratoprosthesis procedure volumes by product type, delivery mode, and end-user category anchored value projections across the analysis window. Segmentation dimensions included synthetic versus bioengineered platform technology, surgical versus outpatient procedure setting, and tertiary hospital versus ambulatory surgical center customer type. CAGRs were derived from regression analysis of historical procedural growth rates adjusted for regulatory approval timelines and reimbursement expansion patterns. Forecast inputs incorporated corneal donor shortage severity indices and 3D bioprinting technology maturation curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR post-market surveillance cost escalation and breakthrough device designation grant rates. Forecasts reflect documented assumptions regarding ophthalmology service line consolidation velocity and teleophthalmology screening penetration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Vaginal Speculum Market
Medical Devices
Cranial Navigation Systems Market
Medical Devices
Global Amniocentesis Needle Market
Medical Devices
Pectus Bar Market
Medical Devices
Pleural Catheters Market
Medical Devices
Drainage Catheters Market
Medical Devices
Global Extremities Market
Medical Devices
Global Holter ECG Market
Medical Devices
Abdominal Closure Systems Market
Medical Devices
Penile Prosthesis Market
Medical Devices
Anti-Snore Device Market
Medical Devices
South Korea Artificial Organs and Bionics Market
Medical Devices
External Nasal Dilator Market
Medical Devices
Global Robotic Flight Simulator Surgery Market
Medical Devices
Global Hemostasis Valves Market
Medical Devices
Ventricular Restoration Systems Market