
 Peripheral Artery Disease Market | 2026-2036
Peripheral Artery Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Peripheral Artery Disease Market Intelligence
Hospital procurement channels for endovascular devices is rewriting competitive access rules across the Peripheral Artery Disease landscape. Medtronic leverages its integrated cath lab ecosystem to sustain premium positioning in drug-eluting stent categories. Abbott Laboratories anchors its presence through vascular closure and optical coherence tomography systems that tie into peripheral workflows. Boston Scientific Corporation competes on atherectomy and balloon platforms, differentiating through specialized sales teams focused on interventional cardiologists and vascular surgeons.
Peripheral artery disease denotes atherosclerotic narrowing of arteries supplying the lower extremities, typically diagnosed through ankle-brachial index testing and confirmed via duplex ultrasonography or angiography, with endovascular revascularization serving as the primary interventional remedy for lifestyle-limiting claudication and critical limb ischemia. Stents and angioplasty balloons constitute the procedural backbone, with margin pools concentrating in drug-coated platforms that command premium reimbursement relative to bare-metal alternatives. Diagnostic catheters and atherectomy devices represent faster-growing adjunct categories, as operators pursue lesion-specific strategies combining plaque modification with balloon angioplasty. End users cluster heavily in hospital catheterization laboratories, though ambulatory surgical centers are capturing share for straightforward femoropopliteal interventions as site-of-service economics shift.
The FDA governs device approval through the 510(k) and PMA pathways, while the Centers for Medicare and Medicaid Services determines reimbursement codes that directly shape procedure economics and manufacturer revenue cycles. Professional societies including the Society for Vascular Surgery and American College of Cardiology issue guideline documents that influence physician training, device selection, and institutional purchasing criteria. Stakeholders must monitor upcoming national coverage determinations for novel atherectomy indications and track state-level certificate-of-need regulations affecting cath lab expansion.
Market Dynamics
Drug-coated balloon technologies are compressing the addressable stent market as interventional cardiologists adopt plaque-modification-first strategies that reduce metal implant dependence and repeat intervention rates.
Growth Catalysts
- CMS reimbursement expansion:Medicare coverage determinations for peripheral interventions in ambulatory surgical centers are pulling procedures out of hospital catheterization laboratories and expanding treatable patient volumes.
- Lesion complexity escalation:Rising diabetes prevalence is generating more calcified infrapopliteal disease, forcing adoption of atherectomy and specialty balloon platforms capable of tackling previously untreatable anatomy.
- FDA breakthrough pathway:The premarket notification track for novel device categories is compressing time-to-market for drug-coated platforms and intravascular imaging adjuncts.
Market Restraints
- Reimbursement compression:Medicare's site-neutral payment policies are narrowing margins on femoropopliteal interventions performed in hospital outpatient departments.
- Supply concentration in nitinol:Shape-memory alloy sourcing for self-expanding stents depends on a limited supplier base concentrated in specialized metallurgical facilities.
- Restenosis biology:Neointimal hyperplasia remains the fundamental limitation of bare-metal stent performance, capping their utility in long-segment disease.
Strategic Opportunities
- Below-the-knee penetration:Critical limb ischemia interventions in tibial vessels represent an underpenetrated segment where drug-coated balloons are displacing bypass surgery.
- Optical coherence tomography integration:Intravascular imaging systems are converging with therapeutic delivery platforms to enable lesion-specific device selection and optimize acute results.
- India procedural growth:Private hospital chains in Mumbai and Delhi are building dedicated peripheral vascular programs to capture rising diabetic foot syndrome volumes.
Industry Challenges
- Operator training deficits:Interventional cardiologists transitioning from coronary work require proctored experience in calcified peripheral anatomy and chronic total occlusion techniques.
- 510(k) evidentiary burden:FDA demands for predicate device equivalence are extending development timelines for next-generation atherectomy systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peripheral Artery Disease Market |
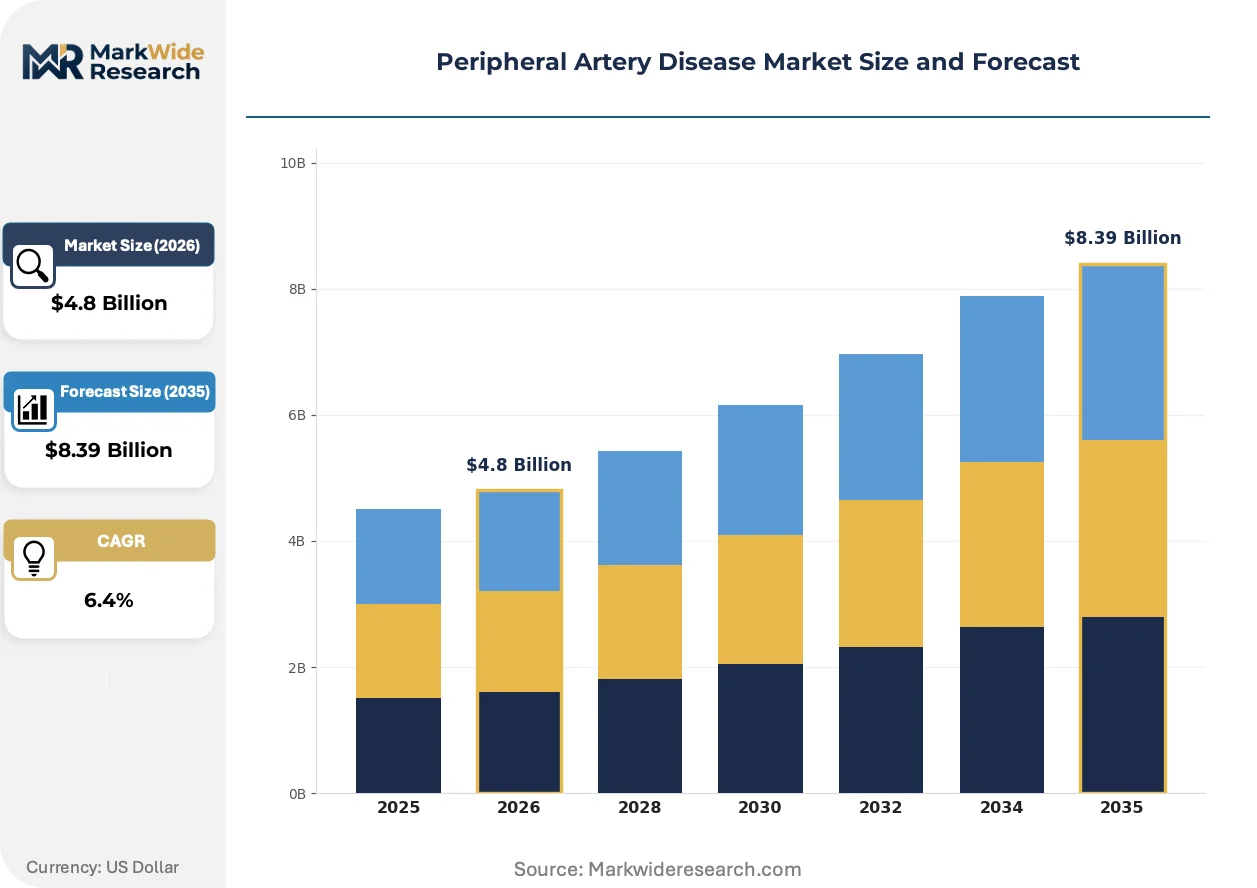
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Angioplasty Balloons, Diagnostic Catheters, Atherectomy Devices End User: Hospitals, Ambulatory Surgical Centers, Cardiac Rehabilitation Centers, Home Healthcare Technology: Interventional Radiology, Endovascular Surgery, Imaging Techniques, Vascular Ultrasonography Delivery Mode: Invasive, Non-invasive, Surgical Procedures, Outpatient Services |
| Companies Covered | Medtronic, Abbott Laboratories, Boston Scientific Corporation, Becton, Dickinson and Company, Cook Medical, Cardinal Health, Terumo Corporation, Philips Healthcare, BIOTRONIK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peripheral Artery Disease Market Strategic Shifts & Innovations
Endovascular workflows are fragmenting into lesion-specific toolkits that combine plaque modification, vessel preparation, and drug delivery in single-procedure sequences tailored to individual anatomy.
Intravascular lithotripsy is collapsing the distinction between calcified and non-calcified lesion treatability by enabling controlled micro-fracture of calcium without vessel trauma. Vascular surgeons in high-volume centers are adopting the technology for femoropopliteal disease previously requiring surgical bypass. The modality is collapsing referral patterns for surgical revascularization as interventionalists gain confidence in heavily calcified anatomy.
The European Union's Medical Device Regulation is imposing clinical evidence requirements that exceed prior CE-marking standards for peripheral stent and balloon categories. Manufacturers are restructuring post-market surveillance systems to capture real-world performance data across diverse European hospital settings. German notified bodies are processing certification applications at reduced throughput, compressing launch timelines for novel platforms.
Hospital value-analysis committees are consolidating vendor contracts around integrated catheterization laboratory ecosystems rather than discrete device categories. Procurement teams in United States health systems are bundling stent, balloon, and imaging purchases with single-source agreements that lock out specialized competitors. The pattern concentrates purchasing power in integrated suppliers and compresses margins for standalone device manufacturers.
Peripheral Artery Disease Market Segmentation
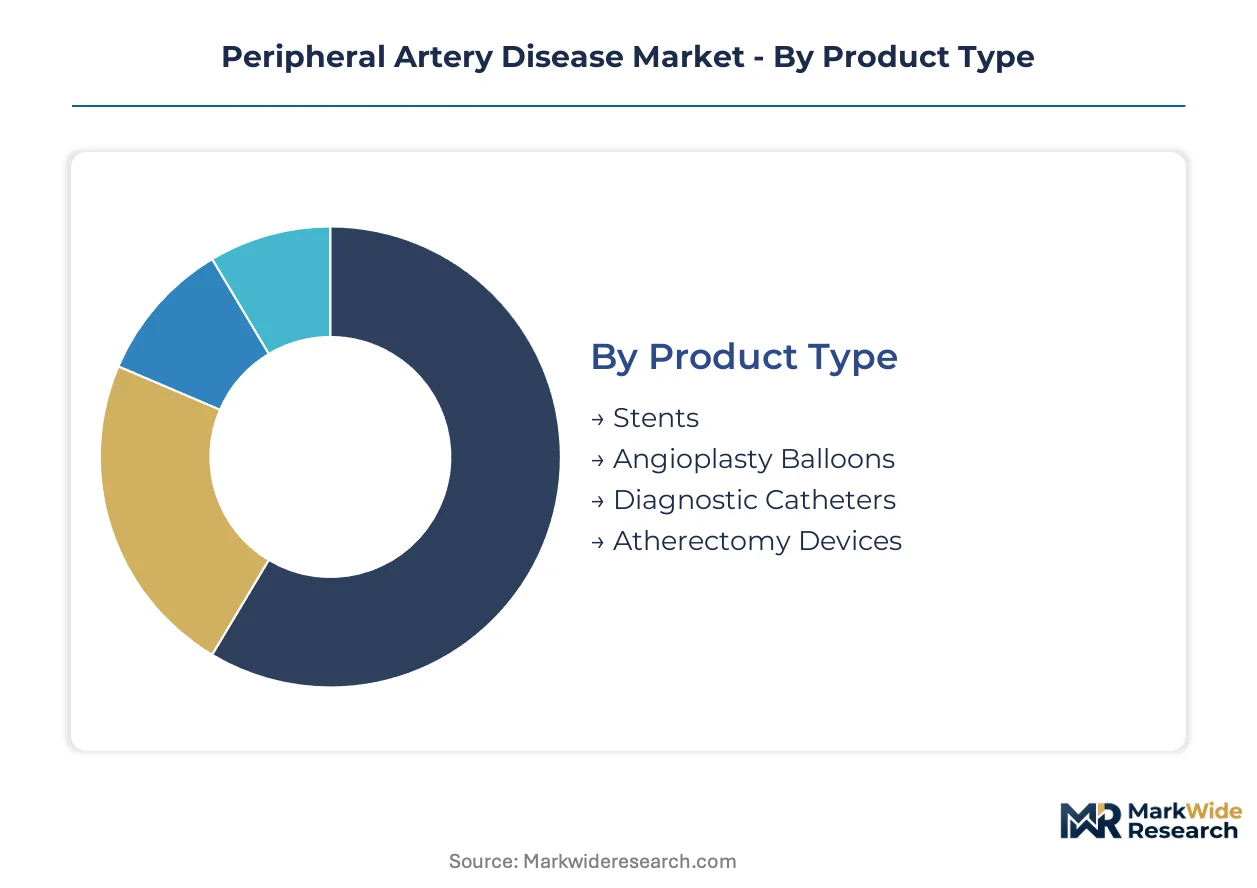
Peripheral artery disease device purchasing follows distinct procurement logics across clinical settings and procedural workflows. Manufacturers must align product portfolios with reimbursement codes, site-of-service economics, and operator training levels to secure commercial traction.
Product Type:
Mature metal platforms coexist with emerging drug-delivery technologies as interventionalists recalibrate implant strategies.
- Stents:Self-expanding nitinol scaffolds dominate femoropopliteal revascularization, with drug-eluting variants commanding premium reimbursement in United States hospital outpatient departments. Cleveland Clinic and Mayo Clinic catheterization laboratories anchor demand for long-segment lesion coverage.
- Angioplasty Balloons:Drug-coated balloon platforms are compressing bare-metal stent utilization through plaque-modification-first approaches that reduce repeat intervention rates. German and United States reimbursement pathways favor these technologies for below-the-knee applications.
- Diagnostic Catheters:Pressure-sensing and imaging-enabled catheters enable physiological lesion assessment prior to intervention selection.
- Atherectomy Devices:Orbital and laser systems address heavily calcified anatomy previously requiring surgical bypass.
Stents retain volume leadership; atherectomy devices hold the steepest expansion curve.
End User:
Site-of-service economics are fragmenting procedure volumes across institutional settings with divergent reimbursement profiles.
- Hospitals:Catheterization laboratories in tertiary centers handle complex multilevel disease and critical limb ischemia cases requiring hybrid operating room capabilities. United States academic medical centers maintain the highest per-procedure device utilization rates.
- Ambulatory Surgical Centers:CMS reimbursement expansion for peripheral interventions is pulling straightforward femoropopliteal cases into freestanding settings with lower overhead structures. Texas and Florida certificate-of-need regulations are accelerating ASC cath lab licensing.
- Cardiac Rehabilitation Centers:Post-interventional monitoring and exercise therapy programs support functional outcome optimization.
- Home Healthcare:Wound care and vascular nursing services extend management for chronic limb-threatening ischemia patients.
Hospitals retain volume leadership; ambulatory surgical centers hold the steepest expansion curve.
Technology:
Procedural approaches stratify by operator specialty training and lesion complexity requirements.
- Interventional Radiology:Fluoroscopy-guided endovascular techniques leverage cross-sectional imaging for chronic total occlusion crossing. United States radiology-trained operators are expanding into peripheral territory traditionally served by vascular surgeons.
- Endovascular Surgery:Hybrid open-convertible approaches combine percutaneous access with surgical bailout options for calcified infrapopliteal disease. German vascular surgery departments pioneered these workflows.
- Imaging Techniques:Intravascular ultrasound and optical coherence tomography enable lesion-specific device selection.
- Vascular Ultrasonography:Duplex surveillance protocols guide restenosis detection and reintervention timing.
Interventional radiology retains volume leadership; imaging techniques hold the steepest expansion curve.
Delivery Mode:
Acuity levels and reimbursement classification determine procedural venue and device bundling economics.
- Invasive:Percutaneous transluminal angioplasty with provisional stenting constitutes the procedural backbone for lifestyle-limiting claudication. United States Medicare severity-adjusted diagnosis-related groups shape hospital reimbursement for these encounters.
- Non-invasive:Exercise therapy and pharmacological management serve as first-line interventions for asymptomatic or mild disease. United Kingdom National Institute for Health and Care Excellence guidelines prioritize supervised exercise programs.
- Surgical Procedures:Bypass grafting and endarterectomy remain indicated for extensive calcification or failed endovascular approaches.
- Outpatient Services:Same-day discharge protocols are expanding for uncomplicated femoropopliteal interventions.
Invasive delivery retains volume leadership; outpatient services hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Transatlantic cable network and EU-US data corridors underpin the United States' central role in peripheral vascular device innovation and reimbursement policy setting.
United States
Medicare's site-neutral payment reforms are accelerating ambulatory surgical center adoption for femoropopliteal interventions. The FDA's breakthrough device designation pathway compresses premarket timelines for drug-coated balloon technologies. Cleveland Clinic and Mayo Clinic catheterization laboratories anchor demand for complex multilevel disease cases requiring hybrid capabilities.
Germany
The statutory health insurance system's procedure volume incentives support endovascular intervention growth for critical limb ischemia. The EU Medical Device Regulation imposes enhanced clinical evidence requirements exceeding prior CE-marking standards for peripheral stent categories. Berlin and Munich academic medical centers pioneer hybrid open-convertible workflows combining percutaneous access with surgical bailout options.
Japan
Aging demographics and diabetes prevalence are expanding the addressable patient pool for below-the-knee revascularization procedures. The Pharmaceuticals and Medical Devices Agency maintains stringent post-market surveillance requirements for nitinol self-expanding stent platforms. Tokyo and Osaka metropolitan hospital networks concentrate the highest per-procedure device utilization rates in the Asia-Pacific region.
India
Private hospital chains in Mumbai and Delhi are constructing dedicated peripheral vascular programs to capture rising diabetic foot syndrome volumes. The Central Drugs Standard Control Organization regulates device importation and local manufacturing certification for endovascular platforms. Apollo Hospitals and Fortis Healthcare networks in Maharashtra and Karnataka are expanding catheterization laboratory capacity for revascularization procedures.
Peripheral Artery Disease Market Key Industry Players
On the supply side, the industry is consolidating around integrated catheterization laboratory ecosystems that bundle stent, balloon, and imaging purchases into single-source agreements. Tiered competitive positioning separates diversified cardiovascular conglomerates from specialized peripheral device manufacturers. Strategic archetypes include cath lab ecosystem integrators, lesion-specific technology specialists, and geographic market consolidators. Dominant competitive moves encompass hospital value-analysis committee contract consolidation and ambulatory surgical center distribution channel expansion.
Within the diversified cardiovascular technology tier, Medtronic plc and Abbott Laboratories exemplify integrated platform strategies spanning drug-eluting stents through vascular closure systems. Boston Scientific Corporation occupies a position as a lesion-specific specialist anchoring competitive presence through atherectomy and balloon platform differentiation. These three entities collectively represent the archetype of cath lab ecosystem dominance that procurement teams increasingly favor for vendor consolidation.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Becton, Dickinson and Company |
| Cook Medical |
| Cardinal Health |
| Terumo Corporation |
| Philips Healthcare |
| BIOTRONIK |
| Others |
Cost & Logistics Intelligence
Transpacific freight corridors connecting German nitinol foundries to United States catheterization laboratories impose cost volatility that amplifies price stratification between integrated cath lab vendors and standalone device manufacturers. This logistics tension concentrates margin leverage in manufacturers with captive metallurgical supply while forcing tiered pricing concessions from import-dependent competitors.
Pricing Analysis
Volume-discount tiering structures separate integrated cath lab ecosystem contracts from spot purchases by ambulatory surgical centers. Pricing stratifies across premium drug-eluting platforms, standard bare-metal stents, and economy balloon catheter categories. Cost compression in the standard tier intensifies as Medicare site-neutral payment policies narrow hospital outpatient margins. Ambulatory surgical centers exhibit the highest price sensitivity; academic medical centers with value-analysis committees command the deepest volume discounts.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for nitinol raw material sourcing. Shape-memory alloy production concentrates in Germany, the United States, and Japan, with finished device assembly anchored in Ireland, Costa Rica, and Malaysia. Supply vulnerability rests on single-source dependencies for specialized catheter extrusions and drug-coating chemistries. Distribution runs through hospital value-analysis committees and group purchasing organizations rather than direct-to-physician channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peripheral artery disease device procurement fragmentation creates entry niches as site-of-service economics splinter demand across hospital catheterization laboratories, ambulatory surgical centers, and hybrid operating rooms.
For Market Incumbents: Harden cath lab ecosystem lock-in by bundling imaging, therapeutic, and closure systems into single-source contracts that resist disaggregation. Expand backward integration into nitinol metallurgy to neutralize raw material cost volatility. Defend against drug-coated balloon substitution by embedding stent platforms into physician training curricula and institutional protocols. For New Entrants and Emerging Players: Below-the-knee drug-coated balloon applications in Indian private hospital chains represent the most penetrable entry point for specialized interventional platforms. Ambulatory surgical center distribution channels in Texas and Florida offer lower competitive density than saturated academic medical center procurement committees. Pursue direct contracting with regional ASC networks bypassing consolidated GPO structures. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified cardiovascular conglomerates seeking to divest non-core peripheral vascular assets. Long-term viability hinges on reimbursement code capture and FDA breakthrough pathway navigation rather than pure technology differentiation. Monitor CMS national coverage determinations for novel atherectomy indications as the critical inflection signal for platform valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated premarket review compresses time-to-revenue for drug-coated platforms. |
| Hospital System Partnership | Integrated cath lab contracts with Cleveland Clinic and Mayo Clinic anchor premium positioning. |
| CE Marking Pathway | EU MDR compliance enables access to German statutory health insurance reimbursement. |
| Software Companion Development | Intravascular imaging integration with therapeutic delivery optimizes lesion-specific outcomes. |
| Reimbursement Strategy | Medicare ASC coverage expansion captures site-of-service shift in femoropopliteal interventions. |
Research Approach
A spread of perspectives from interventional cardiologists, vascular surgeons, hospital purchasing committee members, GPO contracts managers, and biomedical engineers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) and PMA filings, CMS Medicare reimbursement databases, hospital procurement records, and professional society guideline documents. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions encompassed product type, end-user setting, procedural technology, and delivery mode. CAGRs derived from fitted growth curves applied to historical procedure volumes and device utilization rates. Forecast inputs incorporated diabetes prevalence trajectories, cath lab capacity expansion pipelines, and regulatory approval timelines for novel platforms.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rates, nitinol commodity pricing, or trade policy would shift the trajectory. Forecasts reflect documented assumptions regarding procedure migration to ambulatory settings and drug-coated technology adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Heart Health Products Market
Cardiovascular
Heterozygous Familial Hypercholesterolemia (HEFH) Management Market
Cardiovascular
Stable Angina Management Market
Cardiovascular
Myocardial Ischemia Market
Cardiovascular
Eisenmenger Syndrome Treatment Market
Cardiovascular
Myocardial Infarction Therapeutics Market
Cardiovascular
Endocarditis Therapeutics Market
Cardiovascular
Carotid Artery Disease Market
Cardiovascular
Carotid Artery Stenosis Market
Cardiovascular
Atrial Fibrillation Stroke Treatment Market
Cardiovascular
Fractional Flow Reserve Market
Cardiovascular
Endothelial Dysfunction Market
Cardiovascular
Global Deep Vein Thrombosis Market
Cardiovascular
Chronic Pulmonary Hypertension Treatment Market
Cardiovascular
Cardiac Troponin Market
Cardiovascular
Cardiac Arrhythmia Therapeutics Market