
 Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market | 2026-2036
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market Analytics
Drug-eluting balloon specifications is rotating toward higher-margin therapeutic tiers as interventional cardiologists demand superior restenosis prevention. Boston Scientific Corporation leverages integrated manufacturing capabilities across its cardiovascular portfolio to sustain supply chain reliability for complex catheter assemblies. Abbott Laboratories anchors its competitive stance through specialized coating technologies that differentiate performance in calcified lesion interventions. Medtronic plc dominates geographic distribution networks across North American hospital purchasing consortia.
Percutaneous transluminal coronary angioplasty balloon catheters are semi-compliant or non-compliant balloon-tipped devices mounted on catheter shafts, typically constructed from nylon or polyethylene terephthalate materials and inflated to 8-20 atmospheres to dilate stenotic coronary lesions. Their primary commercial purpose is to restore coronary blood flow during percutaneous coronary intervention procedures, often serving as standalone therapy or adjunct to stent deployment. Rapid exchange catheter designs command substantial volume share due to their procedural efficiency in single-operator settings, while over-the-wire configurations retain preference for complex distal lesion navigation where guidewire control is paramount. Nylon balloon material segments face margin pressure from thermoplastic elastomer alternatives that offer enhanced puncture resistance and thinner wall profiles.
FDA premarket notification requirements under 21 CFR 870.5100 shape product development timelines and clinical evidence thresholds for balloon catheter innovators seeking US market access. CE marking under the EU Medical Device Regulation imposes stricter post-market surveillance obligations on manufacturers distributing across European cardiac centers. Japan's PMDA reviews demand localized clinical data packages that extend registration timelines for foreign device manufacturers. Stakeholders must monitor evolving reimbursement thresholds for intracoronary lithotripsy procedures as Shockwave Medical's technology creates new competitive dynamics in calcified lesion management.
Market Dynamics
Intracoronary lithotripsy technology is fragmenting established calcified lesion treatment protocols and forcing PTCA balloon catheter manufacturers to defend procedural relevance through enhanced deliverability specifications.
Growth Catalysts
- US FDA 510(k) Pathway Streamlining:Expedited premarket notification reviews for Class II cardiovascular devices compress time-to-market for innovative balloon catheter designs.
- German Specialized Cardiac Center Expansion:Concentrated demand from high-volume interventional cardiology programs drives adoption of advanced PTCA technologies with superior trackability.
- Thermoplastic Elastomer Material Migration:Enhanced puncture resistance and thinner wall profiles in next-generation balloon materials enable safer treatment of complex coronary anatomies.
Market Restraints
- Nylon Raw Material Cost Volatility:Petrochemical feedstock price fluctuations compress margins for semi-compliant balloon segments dependent on traditional polymer supply chains.
- EU MDR Post-Market Surveillance Burden:Stricter clinical evidence requirements and enhanced vigilance obligations extend compliance timelines and inflate regulatory overhead for European distribution.
- Intracoronary Lithotripsy Substitution Threat:Shockwave Medical's acoustic pressure wave technology captures calcified lesion cases previously requiring high-pressure balloon dilatation.
Strategic Opportunities
- Japan PMDA Localization Gap:Extended registration timelines for foreign device manufacturers create first-mover advantage for firms investing in localized clinical data packages.
- Drug-Eluting Balloon Premium Tier Expansion:Superior restenosis prevention capabilities command pricing power in cardiac centers prioritizing long-term patient outcomes over procedural cost.
- Single-Operator Rapid Exchange Configuration Demand:Procedural efficiency requirements in high-throughput catheterization laboratories favor streamlined catheter designs reducing assistant dependency.
Industry Challenges
- Interventional Cardiologist Training Bottleneck:Complex distal lesion navigation techniques require specialized skills that outpace fellowship program output in emerging markets.
- CE Marking Technical Documentation Intensity:EU Medical Device Regulation mandates exhaustive design dossiers and clinical evaluation reports that strain smaller manufacturer resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market |
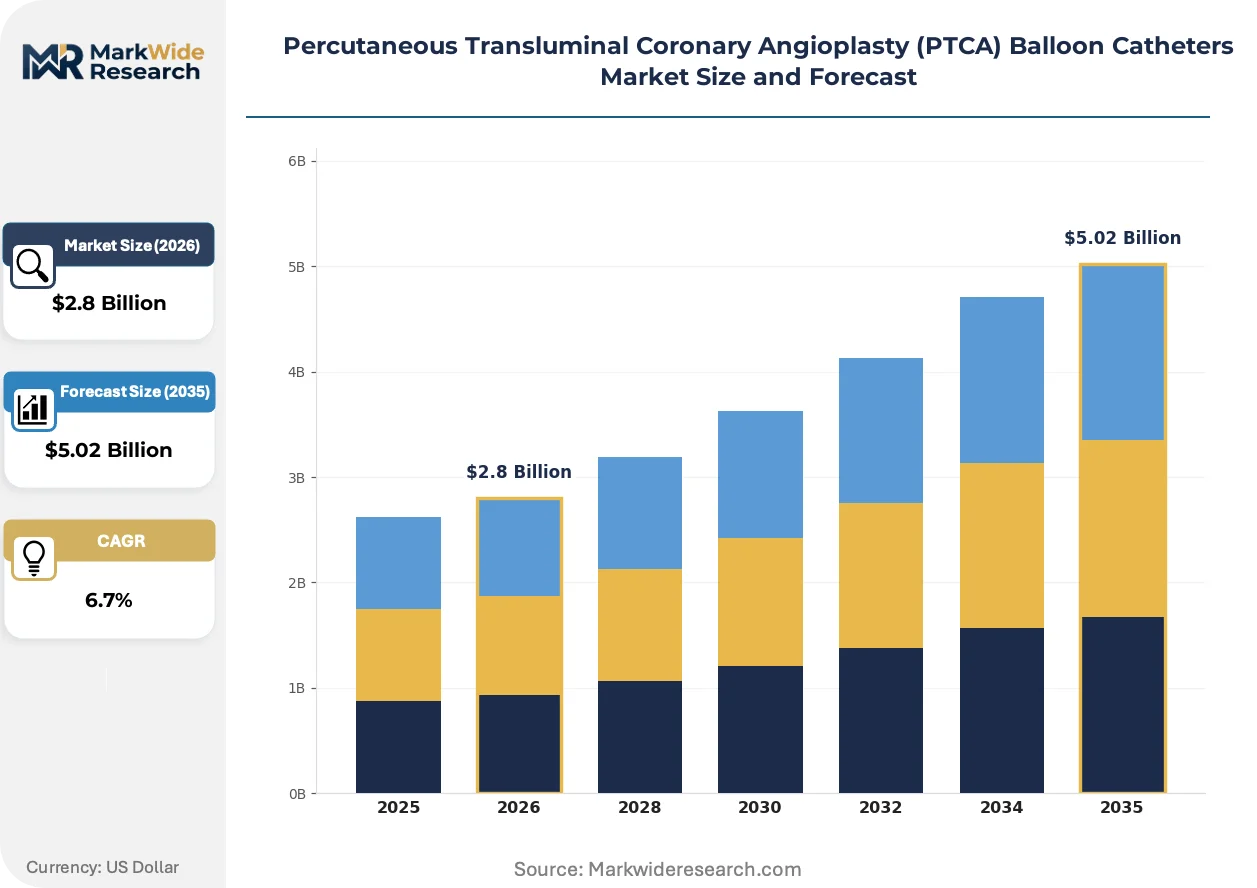
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Over-the-Wire, Rapid Exchange, Dual Lumen, Single Lumen Balloon Material: Nylon, Polyethylene Terephthalate, Thermoplastic Elastomer, Silicone Application: Coronary Artery Disease, Peripheral Artery Disease, Renal Artery Stenosis, Carotid Artery Intervention End User: Cardiac Centers, Specialty Clinics, Diagnostic Laboratories, Ambulatory Surgical Centers |
| Companies Covered | Boston Scientific Corporation, Abbott Laboratories, Medtronic plc, B. Braun Melsungen AG, Terumo Corporation, BIOTRONIK SE & Co. KG, MicroPort Scientific Corporation, Shockwave Medical, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market Evolving Landscape
Material science breakthroughs and procedural workflow optimization are reshaping competitive differentiation in coronary intervention devices, with coating technologies and catheter architecture commanding disproportionate R&D investment.
Drug-eluting balloon coating formulations are fragmenting the therapeutic landscape as paclitaxel and sirolimus analogues compete for dominance in restenosis prevention. Academic medical centers in the United States are validating novel excipient combinations that enhance tissue retention without compromising deliverability. This fragmentation is compressing market share for bare balloon alternatives in high-risk patient populations.
CE marking under the EU Medical Device Regulation imposes stricter post-market surveillance obligations that reshape product lifecycle management for manufacturers distributing across European cardiac centers. Clinical evidence thresholds now extend beyond premarket validation into continuous safety monitoring. German and French regulators are enforcing these mandates most aggressively, forcing portfolio rationalization among multi-product cardiovascular device firms.
Hospital purchasing consortia in North America are consolidating procurement authority and demanding outcome guarantees from balloon catheter suppliers. Traditional distributor relationships face displacement by direct manufacturer contracts with integrated delivery networks. This concentration is most visible in United States metropolitan markets where catheterization laboratory standardization programs favor single-source agreements.
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market Segmentation
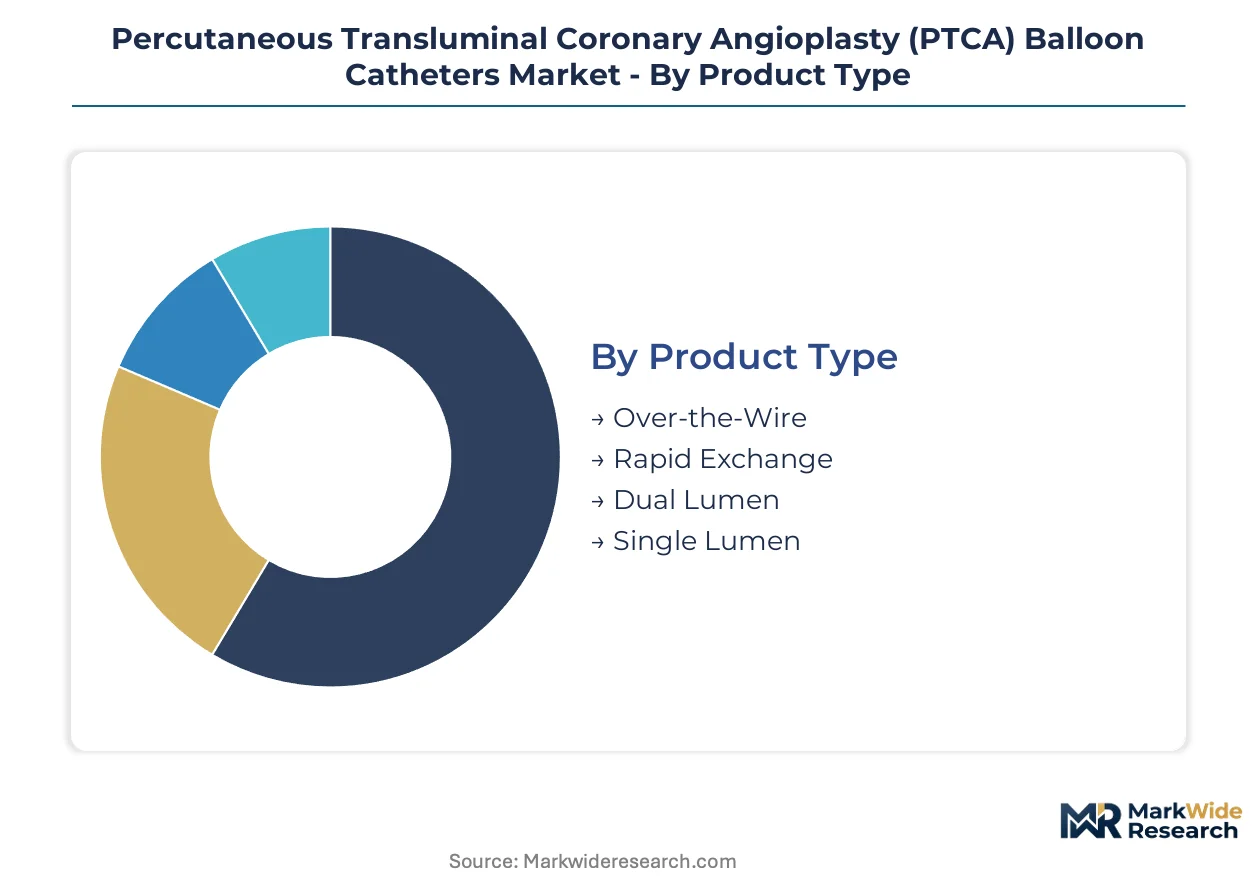
PTCA balloon catheter segmentation reveals how procedural workflow preferences and material science advances reshape procurement decisions across interventional cardiology settings. Distinct catheter architectures command premium positioning based on lesion complexity and operator training levels.
Product Type:
Domestic demand in the United States and Germany concentrates in rapid exchange configurations, while over-the-wire systems retain stronger export orientation toward emerging interventional cardiology programs.
- Over-the-Wire:Extended guidewire lumen running the full catheter length enables independent wire manipulation and torque control during complex distal lesion navigation. German specialized cardiac centers and US academic medical centers concentrate procurement for bifurcation and chronic total occlusion cases where wire stability determines procedural success.
- Rapid Exchange:Short guidewire exit port positioned 25-30cm from the distal tip permits single-operator control with reduced assistant dependency. United States community hospital catheterization laboratories drive volume adoption for straightforward lesion interventions where throughput efficiency governs capital allocation.
- Dual Lumen:Parallel inflation and guidewire channels enable simultaneous contrast injection during balloon positioning. Japanese cardiac centers specify this architecture for precise lesion assessment in calcified anatomies.
- Single Lumen:Simplified construction reduces manufacturing cost for high-volume standard lesion applications. Emerging market distributors in Brazil and India favor this configuration for price-sensitive procurement tenders.
Rapid exchange configurations hold the largest share; momentum sits with over-the-wire systems as calcified lesion prevalence rises.
Balloon Material:
Cost tier stratification separates premium thermoplastic elastomer formulations from commodity nylon segments facing margin compression.
- Nylon:Semi-compliant balloon construction from polyamide polymers delivers predictable expansion characteristics at 8-12 atmospheres for standard coronary dilatation. Petrochemical feedstock volatility compresses margins for manufacturers dependent on traditional polymer supply chains serving European and North American markets.
- Thermoplastic Elastomer:Block copolymer structures achieve thinner wall profiles with superior puncture resistance for high-pressure calcified lesion dilatation. United States cardiac centers and German interventional programs concentrate adoption where 20+ atmosphere rated burst strength justifies premium positioning.
- Polyethylene Terephthalate:High tensile strength polyester enables non-compliant balloon behavior with minimal radial growth beyond rated diameter. French and Italian manufacturers specialize in PET formulations for precise stent deployment sizing.
- Silicone:Elastomeric properties suit specialty applications requiring extreme flexibility for tortuous anatomical navigation. Niche demand concentrates in pediatric interventional programs and research catheterization laboratories.
Nylon maintains volume leadership across cost-sensitive procurement segments; thermoplastic elastomer is climbing the fastest as high-pressure indication expansion accelerates.
Application:
Volume concentration tracks cardiovascular disease epidemiology, with coronary interventions commanding procedural priority in reimbursement frameworks.
- Coronary Artery Disease:Dominant indication encompassing stable angina, acute coronary syndrome, and post-infarction revascularization procedures. United States Medicare reimbursement rates and German DRG classifications concentrate investment in coronary-specific catheter development programs.
- Peripheral Artery Disease:Lower extremity and renal artery interventions utilizing modified coronary platform technologies. Specialty clinics in Florida and Arizona expansion markets drive peripheral application growth as diabetic population prevalence rises.
- Renal Artery Stenosis:Resistant hypertension management through transluminal dilatation of fibromuscular dysplasia and atherosclerotic lesions. Academic medical centers in Massachusetts and California concentrate procedural expertise.
- Carotid Artery Intervention:Cerebrovascular revascularization with embolic protection requirements distinct from coronary workflows. Tertiary referral centers in Pennsylvania and Ohio maintain specialized operator certification programs.
Coronary artery disease applications hold the largest share; momentum sits with peripheral artery disease as outpatient procedure migration accelerates.
End User:
Customer type segmentation reflects capital intensity gradients and reimbursement model differences across care delivery settings.
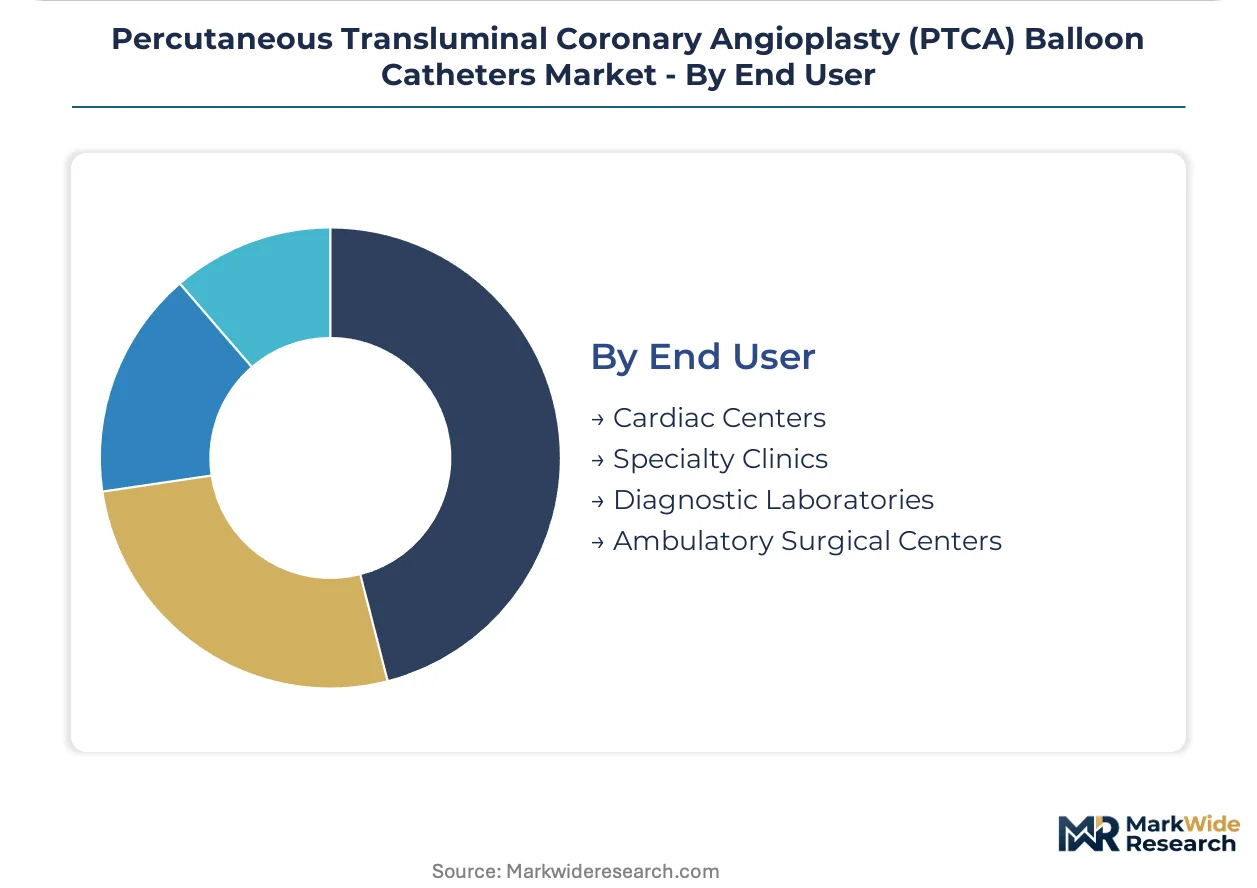
- Cardiac Centers:High-volume interventional cardiology programs with dedicated catheterization laboratory infrastructure and 24-hour primary PCI capabilities. United States metropolitan hospital systems and German university hospitals concentrate procurement of advanced PTCA technologies with outcome guarantee requirements.
- Specialty Clinics:Focused cardiovascular practices performing elective diagnostic and interventional procedures without full emergency surgical backup. Texas and California ambulatory settings drive demand for rapid exchange configurations enabling efficient single-operator workflows.
- Diagnostic Laboratories:Facilities emphasizing physiological assessment and imaging with limited therapeutic intervention scope. Italian and Spanish public health system networks concentrate diagnostic-focused procurement.
- Ambulatory Surgical Centers:Medicare-certified outpatient settings capturing migration of stable elective PCI procedures from hospital-based environments. United States ASC payment rate differentials versus hospital outpatient departments concentrate volume growth in Florida and Tennessee markets.
Cardiac centers hold the largest share; momentum sits with ambulatory surgical centers as site-of-service payment reform accelerates procedural migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from German and United States manufacturing clusters supply cardiac centers across Europe and Asia-Pacific, while import dependency characterizes emerging interventional cardiology programs in Brazil and India seeking advanced balloon catheter technologies.
United States
FDA 510(k) premarket notification pathways compress registration timelines for innovative balloon catheter designs entering the world's largest interventional cardiology market. Medicare reimbursement rates for percutaneous coronary intervention procedures concentrate investment in coronary-specific catheter development programs. The Minneapolis-St. Paul corridor anchors manufacturing operations for multiple cardiovascular device firms serving North American hospital purchasing consortia.
Germany
Specialized cardiac centers in Bavaria and North Rhine-Westphalia drive concentrated procurement of advanced PTCA technologies with superior trackability specifications. CE marking under the EU Medical Device Regulation imposes stricter post-market surveillance obligations that reshape product lifecycle management for manufacturers distributing across European markets. The B. Braun Melsungen AG headquarters in Melsungen anchors a cardiovascular device cluster supplying high-volume interventional programs.
Japan
PMDA review timelines demand localized clinical data packages that extend registration periods for foreign device manufacturers seeking market access. Aging demographics and coronary artery disease prevalence concentrate procedural volume in Tokyo and Osaka metropolitan cardiac centers. Domestic manufacturers leverage JIS standards compliance to defend market position against imported balloon catheter alternatives.
China
NMPA regulatory reforms accelerate approval pathways for innovative cardiovascular devices while maintaining requirements for domestic clinical trials. Provincial hospital tier classification systems concentrate advanced interventional capabilities in tertiary facilities across Beijing, Shanghai, and Guangzhou. Local manufacturers capture procurement tenders through price-competitive positioning in standard lesion applications.
India
CDSCO medical device regulations impose quality standards that foreign manufacturers must navigate for market entry into expanding private cardiac center networks. Maharashtra and Karnataka states concentrate interventional cardiology infrastructure in Mumbai and Bangalore metropolitan clusters. Import dependency persists for drug-eluting balloon technologies while domestic assembly operations grow for standard PTCA catheter configurations.
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market Competitive Landscape
Concentration sits with diversified cardiovascular device conglomerates possessing integrated manufacturing capabilities and established hospital purchasing relationships. The vendor base stratifies across three tiers: global conglomerates with full cardiovascular portfolios, mid-scale specialists focusing on interventional technologies, and regional fabricators serving price-sensitive procurement segments. Dominant competitive moves include portfolio diversification into adjacent coronary intervention technologies and strategic partnerships with hospital purchasing consortia seeking outcome guarantees.
Among diversified cardiovascular device conglomerates, Boston Scientific Corporation, Abbott Laboratories, and Medtronic plc exemplify archetypes leveraging scale and geographic reach. Boston Scientific Corporation represents integrated manufacturing capabilities across cardiovascular portfolios. Abbott Laboratories occupies a position emphasizing specialized coating technologies. Medtronic plc anchors distribution network dominance across North American hospital purchasing consortia. These three firms collectively illustrate how diversified scale creates defensive positioning against emerging technology substitution threats.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Abbott Laboratories |
| Medtronic plc |
| B. Braun Melsungen AG |
| Terumo Corporation |
| BIOTRONIK SE & Co. KG |
| MicroPort Scientific Corporation |
| Shockwave Medical |
| Cardinal Health |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with balloon material suppliers lock in both polymer feedstock access and cost visibility for catheter manufacturers navigating petrochemical price swings. These arrangements concentrate pricing power with integrated device conglomerates while forcing smaller competitors into spot-market exposure for nylon and thermoplastic elastomer inputs.
Pricing Analysis
Hospital purchasing consortia anchor tiered pricing structures across premium drug-eluting balloon, standard semi-compliant, and economy single-lumen configurations. Price differentiation rests on coating technology sophistication and FDA 510(k) clearance tier, with academic medical centers least sensitive and emerging market distributors most price-responsive. Cost compression in nylon-based segments intensifies because petrochemical volatility erodes margins for non-integrated manufacturers.
Supply Chain Analysis
Inventory buffers for balloon catheter assemblies stretch 90-180 days due to sterilization validation cycles and just-in-time hospital delivery requirements. Manufacturing concentrates in the United States, Germany, and Japan, drawing from specialized polymer compounding in Belgium and precision extrusion in Switzerland. Single-source vulnerability sits with medical-grade nylon suppliers serving semi-compliant balloon tiers. Distribution runs through direct manufacturer contracts with integrated delivery networks displacing traditional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intracoronary lithotripsy fragmentation is splintering calcified lesion treatment protocols and creating niche positioning opportunities for catheter specialists with differentiated deliverability specifications.
For Market Incumbents: Shield coronary balloon portfolios by deepening coating technology moats against Shockwave Medical's acoustic pressure wave substitution threat. Prioritize backward integration into thermoplastic elastomer compounding to capture margin from high-pressure calcified lesion segments. Lock in exclusive supply agreements with German and United States cardiac centers through outcome guarantee contracts that lithotripsy competitors cannot yet match.
For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for Class II cardiovascular devices offer regulatory entry points without full PMA burden. Target ambulatory surgical center procurement in Florida and Tennessee where site-of-service payment reform concentrates volume growth and incumbent relationships remain unsettled. Lead with rapid exchange configurations emphasizing single-operator efficiency in high-throughput catheterization laboratories.
For Investors and Strategic Acquirers: Coating technology specialists with proprietary paclitaxel or sirolimus excipient platforms represent acquisition targets with defensible IP positions. Long-term viability hinges on whether drug-eluting balloon restenosis prevention maintains procedural relevance against stent optimization and intravascular imaging integration. Monitor PMDA localization investments by foreign manufacturers as signal of committed Japan market entry versus opportunistic export positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Expedited Class II clearance compresses time-to-market for innovative balloon catheter designs. |
| CE Marking Pathway | EU MDR compliance opens German and French cardiac center procurement to compliant manufacturers. |
| Hospital System Partnership | Direct contracts with United States integrated delivery networks displace distributor intermediaries. |
| Coating Technology Investment | Proprietary excipient platforms differentiate drug-eluting balloon performance in restenosis prevention. |
| Reimbursement Strategy | Medicare ASC payment rate optimization captures procedural migration from hospital outpatient departments. |
Research Methodology
Operator-level perspectives from interventional cardiologists, catheterization laboratory directors, hospital purchasing committee members, and GPO contracts managers anchored the qualitative base for this analysis. Primary interview findings combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR technical documentation. Bottom-up catheter shipment estimates triangulated against top-down cardiovascular device market sizing.
Sensitivity analysis tested forecast outputs across alternative scenarios for intracoronary lithotripsy penetration rates and drug-eluting balloon coating technology adoption curves. Segmentation modeling spanned catheter architecture, balloon material, application indication, and end-user facility type across the projection horizon. CAGRs derived from fitted growth curves incorporating procedural volume trends, reimbursement trajectory assumptions, and regulatory pathway timelines.
Decision-makers should treat outputs as directional under base assumptions of stable FDA review timelines and continued Medicare PCI reimbursement; material deviation would warrant model refresh. Specific risks include PMDA localization requirement tightening, EU MDR post-market surveillance cost inflation, and Shockwave Medical technology expansion beyond calcified lesions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Shock Wave Therapy Devices Market
Cardiovascular Devices
Congestive Heart Failure Treatment Devices Market
Cardiovascular Devices
Global Atrial Fibrillation Surgery Market
Cardiovascular Devices
Peripheral Vascular Interventions Market
Cardiovascular Devices
Global Abdominal Aortic Aneurysm Treatment Market
Cardiovascular Devices
Wearable Cardiac Devices Market
Cardiovascular Devices
Percutaneous Coronary Intervention Guidance Devices Market
Cardiovascular Devices
Global Aortic Repair Devices Market
Cardiovascular Devices
Sweden Cardiovascular Devices Market
Cardiovascular Devices
Global Advanced Balloon Catheter Market
Cardiovascular Devices
Global Arterial Stents Market
Cardiovascular Devices
LAMEA Cardiac Surgical Devices Market
Cardiovascular Devices
Europe Cardiac Assist Devices Market
Cardiovascular Devices
North America Interventional Cardiology and Peripheral Vascular Devices Market
Cardiovascular Devices
Cardiovascular Anastomosis Devices Market
Cardiovascular Devices
Cardiovascular Ultrasound Market