
 Ventricular Fibrillation Treatment Market | 2026-2036
Ventricular Fibrillation Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Ventricular Fibrillation Treatment Market Analytics
A shift from single-source procurement to multi-source contracting for defibrillator hardware is repositioning how hospital systems manage cardiac emergency inventories. Medtronic plc leverages its integrated manufacturing footprint to sustain supply security across implantable and external device categories. Boston Scientific Corporation competes through catheter ablation specialization, while ZOLL Medical Corporation dominates the automated external defibrillator channel with direct-to-emergency-service distribution.
Ventricular fibrillation treatment encompasses electrical intervention and pharmacological protocols designed to terminate chaotic ventricular rhythms and restore perfusing cardiac output, typically involving biphasic waveform delivery at 150–200 joules for external devices or programmed anti-tachycardia pacing for implantable systems. The technology dimension shows radiofrequency catheter ablation capturing mature margin pools in electrophysiology labs, whereas automated external defibrillator platforms represent the fastest-growing segment as public access deployment expands beyond traditional clinical settings. Emergency services as an end user category anchors volume demand through municipal fleet upgrades, while hospital-based implantable device procedures sustain premium pricing.
FDA premarket notification and EU MDR conformity assessment shape device commercialization timelines and clinical evidence requirements for manufacturers seeking multi-territory approval. Japan's PMDA and South Korea's MFDS impose additional localization testing that filters market access for non-domestic suppliers. Stakeholders must monitor evolving reimbursement thresholds for subcutaneous implantable cardioverter-defibrillator alternatives versus transvenous systems as health technology assessment bodies recalibrate value frameworks.
Market Dynamics
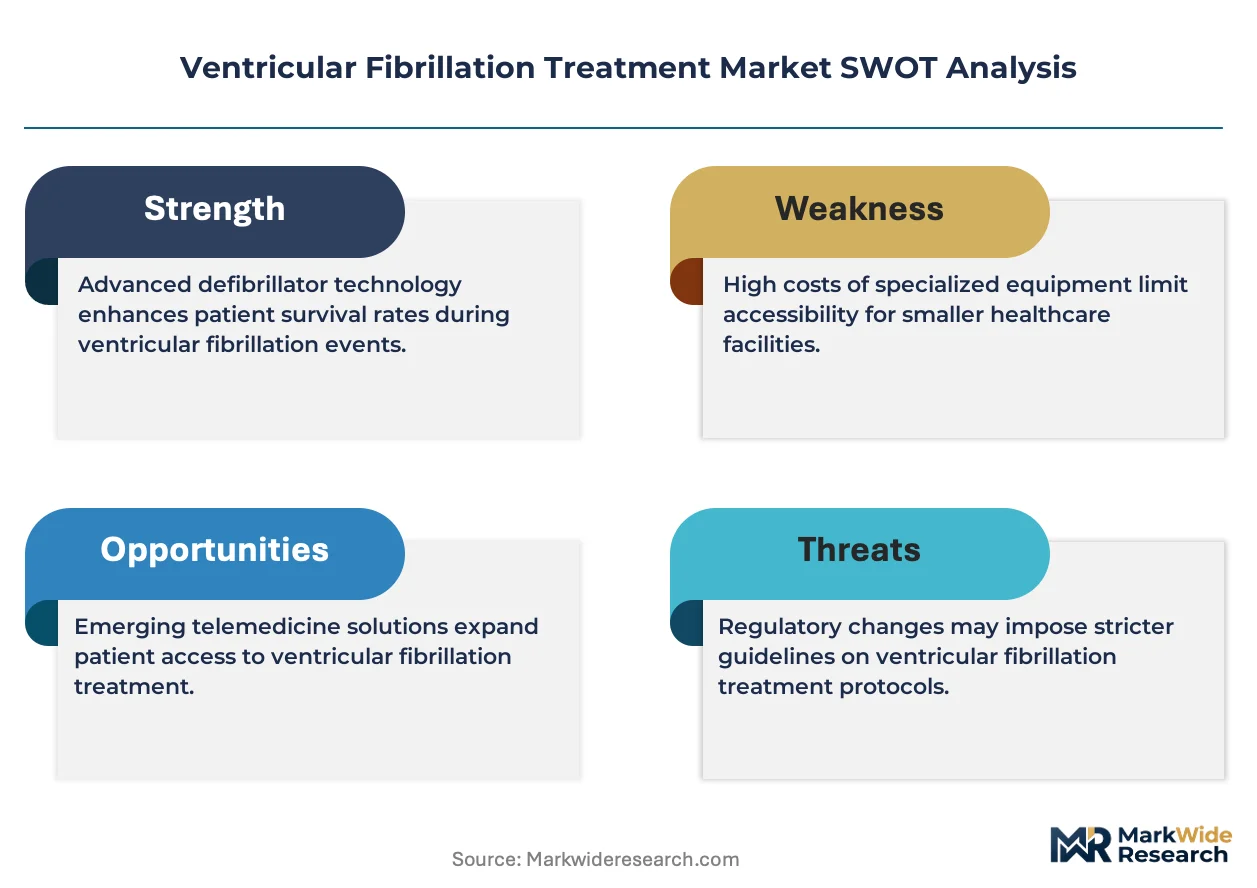
Hospital emergency departments are consolidating defibrillator procurement under multi-source contracting frameworks, forcing manufacturers to demonstrate supply chain resilience alongside clinical performance benchmarks.
Growth Catalysts
- FDA premarket approval pathways:The FDA's tightened quality benchmarks for implantable cardioverter devices are elevating clinical evidence standards, filtering out marginal competitors and rewarding established manufacturers with robust trial infrastructure.
- Public access deployment:Automated external defibrillator platforms are expanding beyond traditional clinical settings into airports, sports stadiums, and corporate campuses, creating new volume channels distinct from hospital-based procurement.
- Aging demographics in Japan:Japan's elderly population density supports sustained procedure volumes for implantable systems, with cardiac care infrastructure concentrated in Tokyo, Osaka, and Nagoya metropolitan clusters.
Market Restraints
- EU MDR conformity assessment:The European Union's Medical Device Regulation imposes extended clinical evidence requirements and notified body bottlenecks, delaying commercialization timelines by 12-24 months for non-domestic suppliers.
- Supply concentration in semiconductor components:Biphasic waveform generators and battery management systems rely on concentrated Asian foundry capacity, exposing device manufacturers to input volatility and allocation constraints.
- Transvenous lead complications:Long-term reliability issues with transvenous implantable cardioverter-defibrillator leads, including fracture and extraction risks, are driving cautious physician adoption and extended evaluation periods.
Strategic Opportunities
- Subcutaneous implantable systems:Subcutaneous implantable cardioverter-defibrillator alternatives bypass transvenous lead risks entirely, opening addressable markets among younger patients and those with venous access limitations.
- South Korea's MFDS localization testing:Manufacturers establishing domestic testing partnerships can accelerate regulatory clearance and capture share in Seoul's concentrated cardiac care network.
- Radiofrequency catheter ablation convergence:Integration of electroanatomic mapping with robotic navigation systems is creating premium procedure tiers in electrophysiology labs, absorbing margin pools from conventional device implantation.
Industry Challenges
- Electrophysiologist training pipelines:Complex ablation procedures and device implantation techniques require specialized fellowship training, with accredited programs concentrated in academic medical centers and insufficient to match procedural demand growth.
- Health technology assessment recalibration:Value frameworks from Germany's IQWiG and England's NICE are tightening reimbursement thresholds for device categories, demanding real-world evidence generation alongside randomized trial data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ventricular Fibrillation Treatment Market |
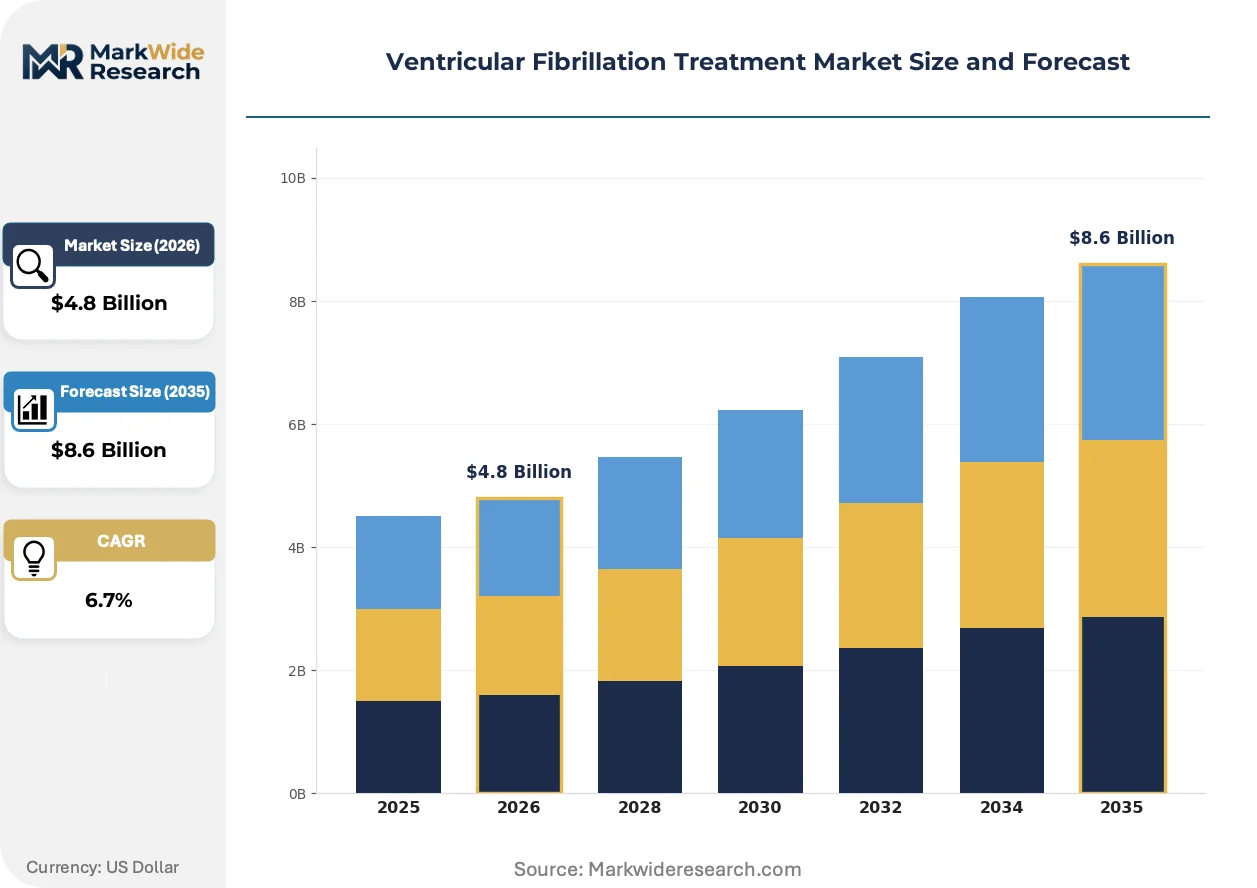
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Defibrillators, Antiarrhythmic Drugs, Catheter Ablation, Implantable Devices Technology: Radiofrequency, Cryoablation, Synchronous Shock, Automated External End User: Hospitals, Clinics, Research Institutions, Emergency Services Delivery Mode: Intravenous, Oral, Transvenous, Transcutaneous |
| Companies Covered | Medtronic plc, Abbott Laboratories, Boston Scientific Corporation, ZOLL Medical Corporation, Biotronik, Philips Healthcare, GE Healthcare Technologies Inc., Johnson & Johnson, St. Jude Medical Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ventricular Fibrillation Treatment Market Evolving Landscape
Device miniaturization and algorithmic rhythm detection are converging to reshape competitive positioning across external and implantable defibrillator categories.
Biphasic truncated exponential waveforms are absorbing market preference from monophasic alternatives in automated external defibrillator platforms. Emergency medical services in the United States and Germany are completing fleet-wide upgrades to biphasic systems, compressing residual demand for legacy hardware and accelerating obsolescence cycles for single-source suppliers.
Japan's PMDA has implemented strengthened post-market surveillance requirements for implantable cardioverter-defibrillators, mandating systematic registry participation and adverse event reporting. This regulatory tightening is elevating compliance costs disproportionately for smaller manufacturers, concentrating market access among entities with dedicated regulatory affairs infrastructure in Tokyo.
Hospital systems are unbundling device procurement from long-term service contracts, separating hardware acquisition from preventive maintenance and remote monitoring subscriptions. This disintermediation is most visible in United States integrated delivery networks, where supply chain executives are negotiating standalone pricing for implantable devices while sourcing monitoring services through competing digital health platforms.
Ventricular Fibrillation Treatment Market Segmentation
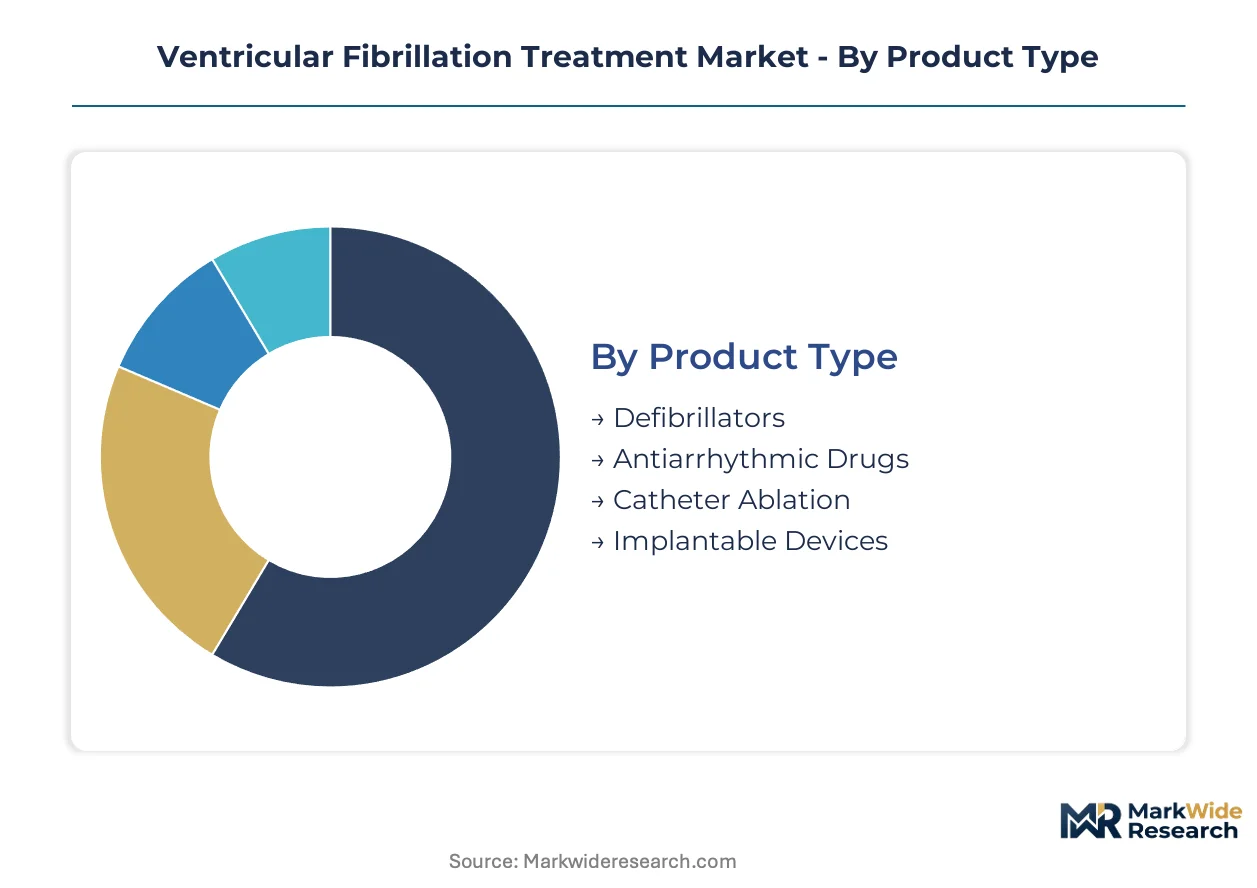
Ventricular fibrillation treatment modalities span electrical, pharmacological, and procedural interventions with distinct reimbursement pathways and clinical deployment settings. Each segment category reflects divergent technology maturity curves and capital intensity requirements that reshape competitive positioning across hospital systems and emergency response networks.
Product Type:
Technical specifications governing energy delivery, drug mechanism, and invasiveness define the product architecture landscape for cardiac rhythm management.
- Defibrillators:External and automated devices deliver biphasic truncated exponential waveforms at 150–200 joules to terminate chaotic ventricular rhythms. Hospital emergency departments in the United States and Germany are consolidating procurement under multi-source contracting frameworks, forcing manufacturers to demonstrate supply chain resilience alongside clinical performance benchmarks.
- Implantable Devices:Transvenous and subcutaneous implantable cardioverter-defibrillators provide programmed anti-tachycardia pacing and high-voltage shock therapy for sustained ventricular arrhythmias. Japan's aging demographics and concentrated cardiac care infrastructure in Tokyo, Osaka, and Nagoya metropolitan clusters sustain premium procedure volumes for these systems.
- Antiarrhythmic Drugs:Pharmacological agents including amiodarone and lidocaine stabilize myocardial membrane potential to prevent recurrence after electrical cardioversion.
- Catheter Ablation:Minimally invasive electrophysiology procedures isolate arrhythmogenic substrate through energy delivery via transvenous access.
Defibrillators lead on scale across emergency deployment channels; implantable devices lead on momentum as subcutaneous alternatives bypass transvenous lead complications.
Technology:
Energy delivery mechanisms and waveform characteristics differentiate clinical efficacy profiles and capital equipment requirements across treatment settings.
- Automated External:Biphasic waveform platforms with algorithmic rhythm detection enable layperson operation through voice prompts and automated shock advisory. Public access deployment is expanding beyond traditional clinical settings into airports, sports stadiums, and corporate campuses, creating volume channels distinct from hospital-based procurement.
- Radiofrequency:Thermal energy delivery through electroanatomic mapping systems creates linear lesions to interrupt re-entrant circuits in electrophysiology labs. Integration with robotic navigation systems is creating premium procedure tiers, absorbing margin pools from conventional device implantation in United States academic medical centers.
- Synchronous Shock:R-wave synchronized cardioversion delivers timed electrical impulses to avoid vulnerable periods of the cardiac cycle.
- Cryoablation:Cryothermal energy application creates reversible lesions for testing and permanent substrate modification in arrhythmia substrates.
Radiofrequency dominates revenue concentration in specialized electrophysiology settings; automated external platforms are expanding most quickly through municipal fleet upgrades and public access mandates.
End User:
Capital availability, procedure complexity, and regulatory oversight intensity vary substantially across institutional settings.
- Hospitals:Comprehensive cardiac care infrastructure encompassing emergency departments, catheterization laboratories, and electrophysiology suites anchors premium pricing for implantable systems. United States integrated delivery networks are unbundling device procurement from long-term service contracts, separating hardware acquisition from preventive maintenance and remote monitoring subscriptions.
- Emergency Services:Municipal ambulance fleets and fire department first responders drive automated external defibrillator volume through standardized equipment protocols. Fleet-wide upgrades to biphasic systems in the United States and Germany are compressing residual demand for legacy hardware.
- Clinics:Outpatient cardiology practices focus on diagnostic evaluation and post-implantation device interrogation with limited intervention capability.
- Research Institutions:Academic medical centers generate clinical evidence for regulatory submissions and train electrophysiology fellows in advanced ablation techniques.
Hospitals lead on scale through procedure-based revenue; emergency services lead on momentum as public access deployment extends beyond clinical boundaries.
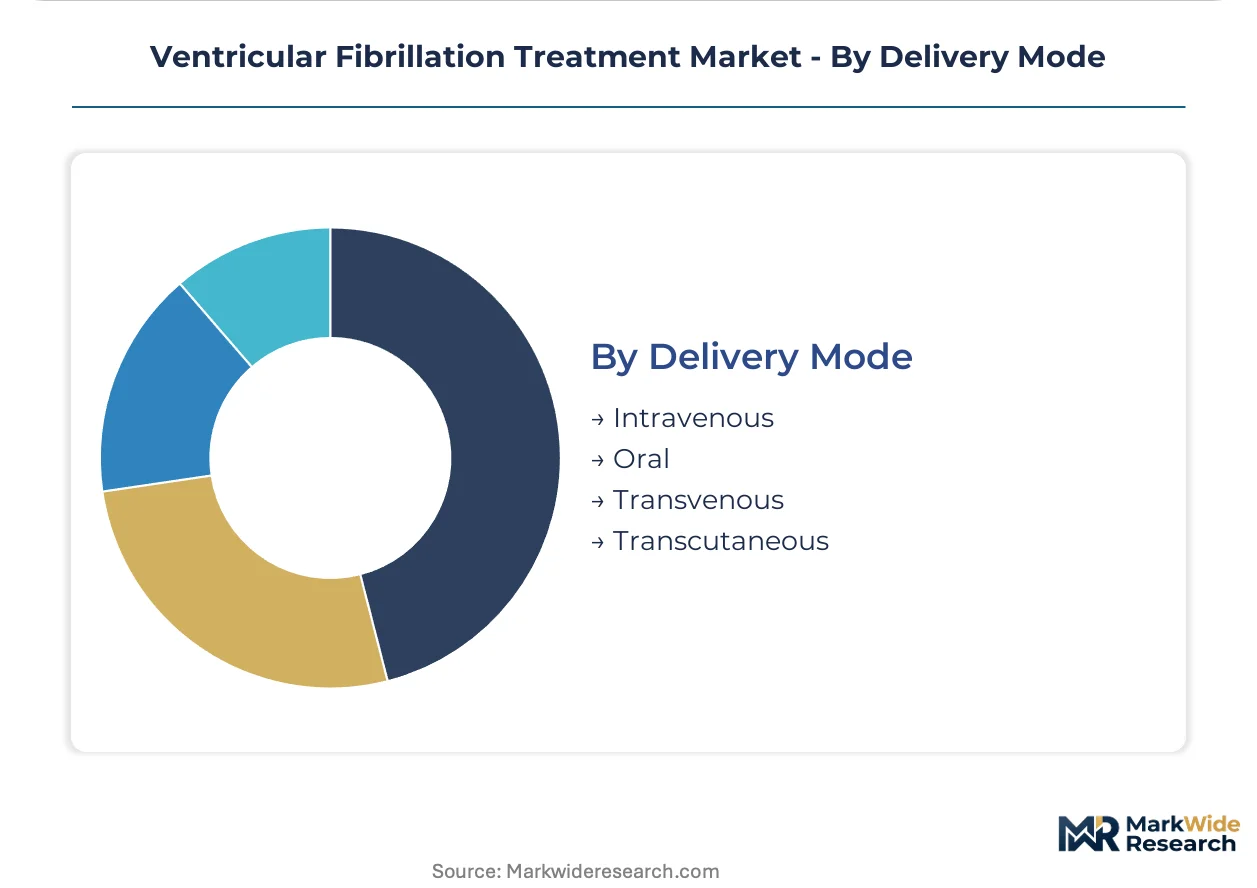
Delivery Mode:
Route of administration or energy transmission determines invasiveness profile, patient selection criteria, and complication risk stratification.
- Transvenous:Lead systems advanced through venous access into cardiac chambers enable sensing, pacing, and defibrillation energy delivery. Long-term reliability issues including fracture and extraction risks are driving cautious physician adoption and extended evaluation periods for these implantable systems.
- Transcutaneous:External electrode pads applied to the chest wall deliver biphasic energy without vascular access, enabling rapid deployment in pre-hospital settings. Emergency medical services reliance on these systems creates demand concentration in municipal procurement channels.
- Intravenous:Parenteral antiarrhythmic administration achieves rapid therapeutic plasma concentrations during acute resuscitation scenarios.
- Oral:Chronic outpatient pharmacological suppression maintains sinus rhythm following successful cardioversion or ablation procedures.
Transvenous systems lead on scale through established reimbursement for implantable devices; transcutaneous delivery leads on momentum as pre-hospital emergency protocols standardize biphasic external platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost disparities between jurisdictions are redirecting device manufacturing toward markets with streamlined conformity pathways, while procurement concentration in aging economies sustains premium demand clusters.
United States
Hospital emergency departments and integrated delivery networks anchor device procurement through multi-source contracting frameworks. FDA premarket approval pathways for implantable cardioverter devices impose rigorous clinical evidence standards that filter marginal competitors. The Boston-Cambridge corridor concentrates electrophysiology training programs and ablation procedure innovation.
Germany
Municipal ambulance fleets drive automated external defibrillator volume through standardized biphasic system protocols. EU MDR conformity assessment creates extended commercialization timelines, favoring manufacturers with dedicated regulatory affairs infrastructure. The Rhine-Ruhr metropolitan cluster hosts concentrated cardiac care infrastructure and electrophysiology lab networks.
Japan
Aging demographics in Tokyo, Osaka, and Nagoya sustain premium procedure volumes for implantable systems. PMDA post-market surveillance requirements mandate systematic registry participation, elevating compliance costs disproportionately for smaller manufacturers. The Kanto region anchors domestic device distribution and clinical training capacity.
South Korea
Seoul's concentrated cardiac care network generates demand for advanced implantable and external defibrillator platforms. MFDS localization testing requirements filter market access for non-domestic suppliers lacking domestic testing partnerships. The Seoul Capital Area hosts the country's primary electrophysiology fellowship programs and device evaluation centers.
United Kingdom
NICE value frameworks tighten reimbursement thresholds for implantable device categories, demanding real-world evidence alongside trial data. Public access defibrillator deployment extends into transport hubs and corporate campuses beyond traditional clinical settings. The Greater London area concentrates private cardiac care facilities and emergency medical service procurement decisions.
Ventricular Fibrillation Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue subcutaneous implantable alternatives and algorithmic rhythm detection. The market structure consolidates around integrated manufacturers with captive supply chains and specialized electrophysiology players with catheter ablation expertise. Three archetypes dominate: diversified medical technology conglomerates with multi-category cardiac portfolios, pure-play defibrillator specialists with emergency service distribution depth, and electrophysiology-focused innovators with robotic navigation integration. Competitive moves center on supply chain resilience demonstrations and unbundling of hardware procurement from remote monitoring subscriptions.
Among diversified medical technology conglomerates, Medtronic plc and Abbott Laboratories exemplify integrated manufacturing footprints spanning implantable and external device categories. Boston Scientific Corporation occupies a position within the electrophysiology specialization tier, while ZOLL Medical Corporation anchors the automated external defibrillator channel with direct-to-emergency-service distribution strength. These entities represent distinct competitive vectors: supply security, catheter-based intervention expertise, and pre-hospital deployment scale respectively.
| Leading Market Players |
|---|
| Medtronic plc |
| Abbott Laboratories |
| Boston Scientific Corporation |
| ZOLL Medical Corporation |
| Biotronik |
| Philips Healthcare |
| GE Healthcare Technologies Inc. |
| Johnson & Johnson |
| St. Jude Medical Inc. |
| Others |
Value Network & Pricing Analysis
Captive manufacturing of biphasic waveform generators and battery management systems anchors supply security for implantable and external defibrillator categories, concentrating pricing power among integrated producers with in-house semiconductor fabrication partnerships in Taiwan and South Korea.
Pricing Analysis
Direct-to-emergency-service distribution compresses distributor margins for automated external defibrillator platforms, while hospital procurement unbundling separates hardware acquisition from remote monitoring subscriptions. Three-tier pricing structure across premium, standard, and economy levels differentiates implantable cardioverter-defibrillators by FDA premarket approval tier and clinical evidence depth. Pricing pressure stems from multi-source contracting frameworks as integrated delivery networks consolidate vendor panels. Emergency services exhibit highest price sensitivity due to municipal budget constraints, whereas electrophysiology labs absorb premium tiers for robotic navigation integration.
Supply Chain Analysis
Electrophysiologist training pipeline constraints in United States academic medical centers and German university hospitals limit production scaling for complex ablation systems. Semiconductor foundry capacity concentrates in Taiwan, South Korea, and Japan for waveform generation components. Raw material dependencies include lithium-ion cells, medical-grade titanium, and biocompatible polymers. Single-source vulnerability in Asian foundry exposure threatens allocation stability during supply shocks. Distribution runs through GPO contracts for hospital systems and municipal procurement channels for emergency services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ventricular fibrillation treatment functions as a stable compounder, with aging demographics in Japan, Germany, and the United States delivering procedure volume growth irrespective of macroeconomic cycles.
For Market Incumbents: Deepen backward integration into semiconductor component supply by securing dedicated foundry allocation in Taiwan and South Korea, insulating against supply shocks that disrupt biphasic waveform generator production. Fortify regulatory affairs infrastructure in Tokyo to satisfy PMDA post-market surveillance mandates that filter smaller competitors. Prioritize unbundling resistance by embedding remote monitoring algorithms into hardware architecture, complicating hospital procurement separation of device and service contracts. For New Entrants and Emerging Players: Begin with subcutaneous implantable cardioverter-defibrillator alternatives, where transvenous lead complication risks have created physician demand without entrenched incumbent lock-in. South Korea's MFDS localization testing partnerships offer the most penetrable regulatory pathway for non-domestic suppliers lacking legacy infrastructure. Pursue direct-to-municipality sales for automated external defibrillator fleet upgrades, bypassing hospital GPO concentration. For Investors and Strategic Acquirers: Roll-up economics work for electrophysiology-focused innovators with robotic navigation integration because catheter ablation convergence is absorbing margin pools from conventional device implantation in academic medical centers. Five-to-ten year viability hinges on sustained reimbursement for premium procedure tiers. Target acquisition archetypes include subcutaneous implantable system specialists and algorithmic rhythm detection software platforms. Watch FDA premarket approval pathway tightening as inflection indicator for competitive filtering acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-source contracting frameworks favor vendors with demonstrated supply chain resilience across implantable and external device categories. |
| FDA Submission | Premarket approval pathways for implantable cardioverter devices filter marginal competitors through rigorous clinical evidence requirements. |
| CE Marking Pathway | EU MDR conformity assessment extends commercialization timelines, rewarding manufacturers with dedicated regulatory affairs infrastructure. |
| Software Companion Development | Algorithmic rhythm detection and remote monitoring integration embed service revenue into hardware procurement relationships. |
| Reimbursement Strategy | Health technology assessment recalibration by Germany's IQWiG and England's NICE demands real-world evidence alongside randomized trial data. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, PMDA approval databases, CMS Medicare procedure data, and hospital procurement records. Bottom-up segment sizing and top-down market triangulation cross-validated volume and value estimates.
Segment-weighting approaches applied differential growth assumptions across product type, technology, end user, and delivery mode dimensions over the projection horizon. CAGRs derived from procedure volume trajectories, pricing trend analysis, and technology substitution curves. Forecast inputs incorporated aging demographic projections, regulatory approval pipeline tracking, and reimbursement threshold evolution from health technology assessment bodies.
Several conditions sit outside the modeled scope, including pandemic-related procedure deferrals, semiconductor supply allocation crises, and radical breakthroughs in pharmacological arrhythmia suppression. Forecasts reflect documented assumptions about regulatory pathway stability and reimbursement continuity. Material deviation in FDA enforcement posture, EU MDR notified body capacity, or Japan's PMDA registry participation mandates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Blood Fluid Warming System Market
Cardiovascular Devices
Implantable Drug Infusion Pumps Market
Cardiovascular Devices
China Vascular Grafts Market
Cardiovascular Devices
Hypertension Management Devices Market
Cardiovascular Devices
Acute Surgical Mechanical Circulatory Support System Market
Cardiovascular Devices
Cardiovascular Ultrasound Market
Cardiovascular Devices
Patient-Controlled Injectors Market
Cardiovascular Devices
Japan Cardiovascular Devices Market
Cardiovascular Devices
Global Non-Vascular Stents Market
Cardiovascular Devices
Global Embolotherapy Market
Cardiovascular Devices
Global Pediatric Interventional Cardiology Market
Cardiovascular Devices
Europe Heart Valve Repair and Replacement Market
Cardiovascular Devices
Endovascular Stent Market
Cardiovascular Devices
Drug Eluting Stent (DES) Market
Cardiovascular Devices
Global Cardiovascular Ultrasound System Market
Cardiovascular Devices
Abdominal Stent Graft System Market