
 Veterinary Molecular Diagnostics Market | 2026-2036
Veterinary Molecular Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Molecular Diagnostics Market Intelligence
Equipment leasing and reagent rental programs is fragmenting competitive access across mid-sized veterinary hospital chains. IDEXX Laboratories leverages captive assay menus to sustain recurring revenue per installed instrument. Thermo Fisher Scientific anchors its position through applied biosystems thermal cyclers deployed in university veterinary schools. Zoetis competes by bundling molecular panels with its broader vaccine and pharmaceutical portfolio.
Veterinary molecular diagnostics encompasses nucleic acid amplification, hybridization, and sequencing technologies used to detect pathogens, genetic mutations, and antimicrobial resistance markers in animal specimens, typically requiring extraction of DNA or RNA from blood, tissue, or swab samples followed by target-specific amplification with sensitivity thresholds reaching single-copy detection. The field serves clinical decision-making in livestock health management, companion animal infectious disease control, and breeding program optimization. Real-Time PCR occupies the dominant technology position due to its established validation across OIE reference laboratories and commercial veterinary panels. Next Generation Sequencing represents the fastest-expanding segment as metagenomic approaches enable untargeted pathogen discovery in outbreak investigations. Digital PCR is carving out a premium niche in oncology applications where absolute quantification of circulating tumor DNA supports therapeutic monitoring in canine cancer models.
USDA-APHIS regulates interstate movement testing for reportable diseases such as avian influenza and bovine tuberculosis, creating mandated demand windows for validated molecular assays. FDA Center for Veterinary Medicine oversees diagnostic kit premarket pathways while EPA evaluates environmental DNA monitoring applications in aquaculture disease surveillance. Stakeholders must track evolving harmonization between national reference laboratory standards and commercial kit manufacturers as trade barriers hinge on mutual recognition of molecular test performance specifications.
Market Dynamics
Automated nucleic acid extraction platforms are compressing turnaround times from days to hours, forcing diagnostic laboratories to retool workflows or lose reference testing contracts to faster competitors. This velocity pressure cascades through equipment procurement, staff retraining, and assay validation protocols.
Growth Catalysts
- USDA-APHIS interstate movement mandates:Mandatory molecular testing for reportable diseases such as avian influenza and bovine tuberculosis creates recurring demand windows for validated PCR assays in livestock export corridors.
- Companion animal hospital consolidation:Mid-sized veterinary chains in the United States and Germany are centralizing diagnostic spend, generating volume pull for automated platforms with captive reagent contracts.
- Digital PCR oncology applications:Absolute quantification of circulating tumor DNA in canine cancer models is opening premium service tiers in university veterinary teaching hospitals.
Market Restraints
- Reagent cost volatility:Proprietary master mix formulations and fluorophore-conjugated probes lock laboratories into single-source supply, exposing margins to polymerase enzyme price swings.
- Reference laboratory concentration:Diagnostic volume in the United States concentrates among three national networks, constraining pricing power for independent regional labs.
- Sample integrity windows:RNA degradation in field-collected swabs limits molecular assay sensitivity, requiring cold chain infrastructure that rural veterinary clinics lack.
Strategic Opportunities
- Point-of-care decentralization:Battery-operated thermal cycler platforms are penetrating mobile veterinary units and remote livestock operations previously served only by mail-out reference testing.
- EU Animal Health Law harmonization:Standardized molecular workflow requirements across member states reduce validation burden for assay manufacturers seeking multi-country registration.
- Metagenomic outbreak surveillance:Next Generation Sequencing adoption in Japan and Germany enables untargeted pathogen discovery in aquaculture and wildlife disease investigations.
Industry Challenges
- Molecular diagnostics specialist scarcity:Veterinary schools graduate fewer laboratory-trained pathologists than diagnostic laboratories require, inflating salaries for PCR validation and quality control roles.
- Multi-platform integration complexity:Laboratories running concurrent Real-Time PCR, digital PCR, and sequencing workflows face incompatible data formats and fragmented laboratory information management systems.
- OIE-to-WOAH transition friction:Renaming of the World Organisation for Animal Health disrupts assay labeling, regulatory submissions, and laboratory accreditation documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Molecular Diagnostics Market |
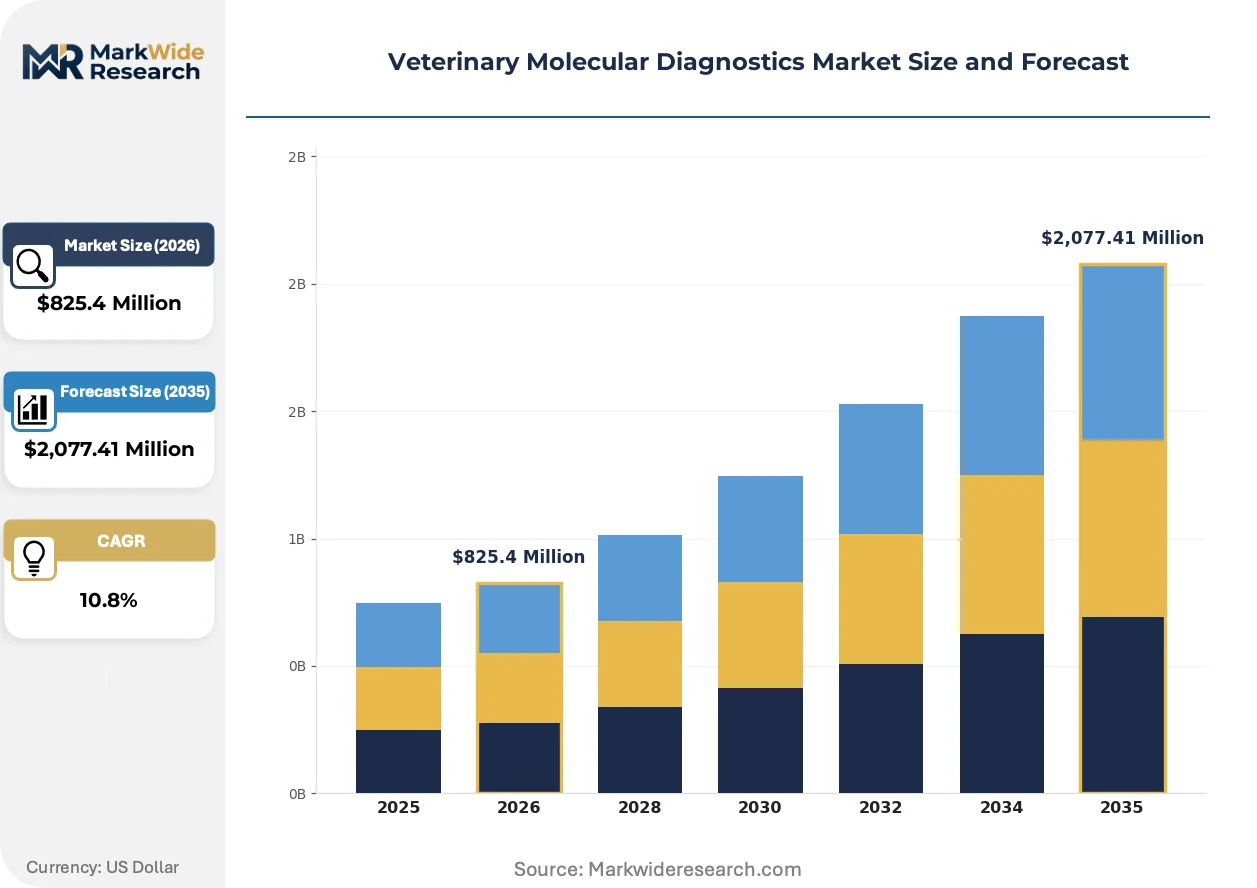
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $2,077.41 Million |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCR Kits, DNA Sequencers, Microarrays, Isothermal Amplification Systems, Reagents Application: Pathogen Detection, Genetic Disorder Screening, Breed Identification, Drug Resistance Analysis, Disease Surveillance End User: Veterinary Hospitals, Diagnostic Laboratories, Research Institutes, Animal Breeding Centers, Pharmaceutical Companies Technology: Real-Time PCR, Next Generation Sequencing, Loop-Mediated Isothermal Amplification, Microarray Hybridization, Digital PCR |
| Companies Covered | Zoetis, IDEXX Laboratories, Antech Diagnostics, Thermo Fisher Scientific, Neogen Corporation, Bio-Rad Laboratories, QIAGEN, bioMérieux, Gold Standard Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Molecular Diagnostics Market Strategic Shifts & Innovations
Workflow automation and portable instrumentation are redistributing molecular diagnostic capability from centralized reference laboratories toward point-of-care settings. These shifts compress service delivery timelines while raising new questions about assay standardization and result interpretation training.
Lyophilized reagent cartridges are collapsing cold chain dependencies for field-deployed PCR systems. Mobile veterinary units in remote livestock regions are adopting these ambient-stable formats to process samples at collection sites rather than shipping to distant labs. This compression eliminates degradation risk and accelerates therapeutic decision windows for infectious disease outbreaks.
EU Animal Health Law implementation is harmonizing molecular test validation standards across member states. Laboratories in Germany, France, and the Netherlands now operate under unified performance specifications, reducing redundant assay verification for manufacturers seeking multi-country market access. Commercial kit developers are consolidating EU-specific product lines into single regulatory submissions.
Reagent rental contracts are displacing capital purchase models in mid-sized veterinary hospital chains. Equipment suppliers in the United States bundle thermal cyclers with multi-year consumable commitments, locking in recurring revenue while lowering upfront barriers for clinic expansion. This financing shift concentrates procurement authority at chain headquarters rather than individual practice veterinarians.
Veterinary Molecular Diagnostics Market Segmentation
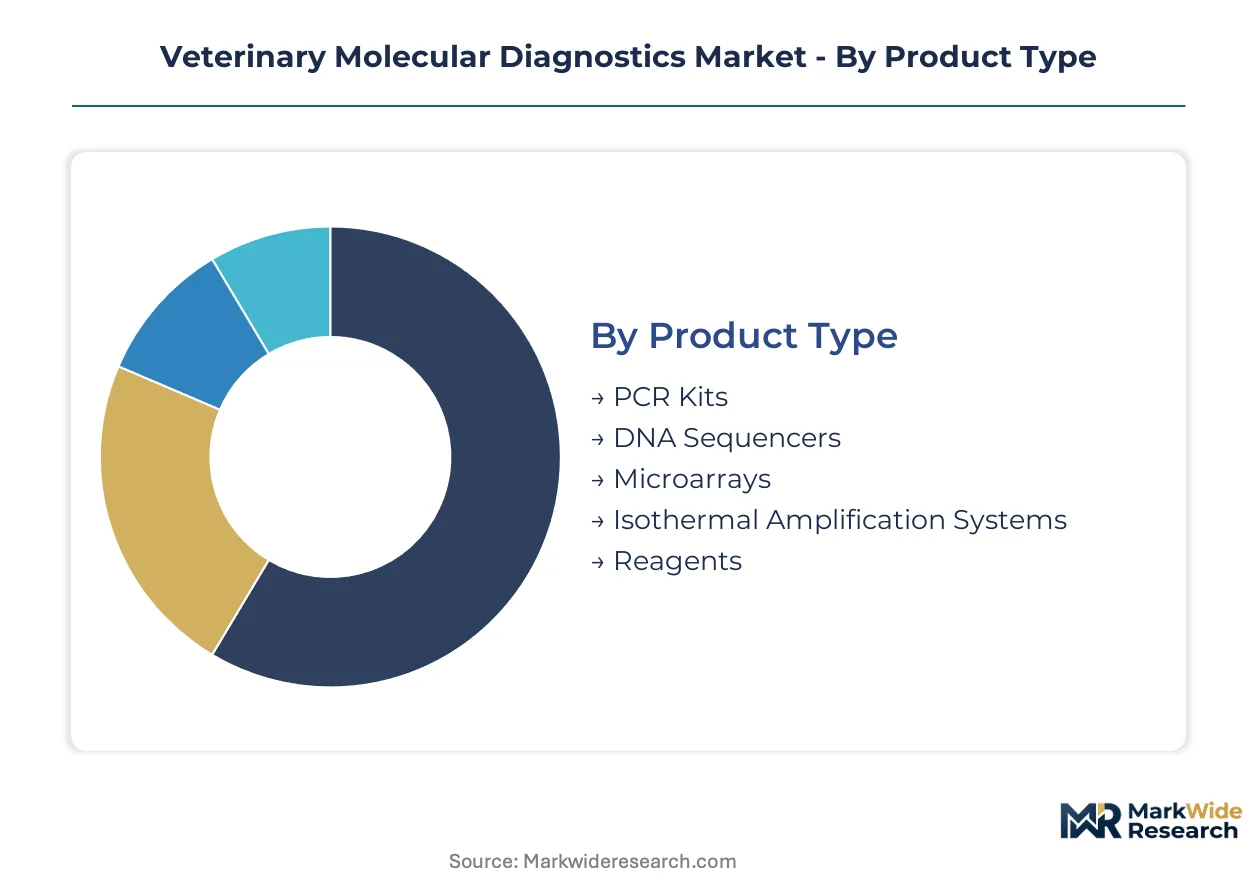
Molecular diagnostic platforms serve distinct workflow requirements across veterinary settings. Equipment specifications, throughput demands, and regulatory validation burdens fragment procurement patterns by use case.
Product Type:
Cost tiers separate capital-intensive platforms from consumable-driven recurring revenue models.
- PCR Kits:Pre-formulated master mixes and pathogen-specific primer-probe sets dominate consumable spend. Veterinary hospital chains in the United States negotiate multi-year supply agreements tied to thermal cycler placements.
- DNA Sequencers:Benchtop NGS platforms enable untargeted metagenomic screening in university veterinary schools. Germany and Japan lead adoption for aquaculture pathogen discovery applications.
- Microarrays:Solid-phase hybridization panels support high-plex genetic disorder screening in canine breeding programs.
- Isothermal Amplification Systems:Battery-operated field units eliminate thermal cycling infrastructure for remote livestock operations.
- Reagents:Extraction buffers, enzymes, and fluorophore-conjugated probes lock laboratories into vendor ecosystems through proprietary formulations.
The dominant share belongs to PCR Kits, while DNA Sequencers is closing the gap fastest.
Application:
Volume concentrates where regulatory mandates intersect with clinical decision urgency.
- Pathogen Detection:Real-time PCR panels for canine parvovirus, feline leukemia, and avian influenza drive routine diagnostic throughput. USDA-APHIS interstate movement rules sustain demand in livestock export corridors.
- Genetic Disorder Screening:Hereditary disease panels for purebred dogs and cats support breeding program decisions. Kennel clubs in Germany and the United Kingdom require documented carrier status for registration.
- Breed Identification:SNP-based ancestry testing resolves mixed-breed phenotyping for insurance and adoption protocols.
- Drug Resistance Analysis:Antimicrobial resistance gene detection guides therapeutic selection in production animal settings.
- Disease Surveillance:Environmental DNA monitoring in aquaculture and wildlife reservoirs supports outbreak containment.
Pathogen Detection commands the largest share, though Genetic Disorder Screening is expanding most quickly in companion animal segments.
End User:
Customer type determines equipment sophistication and service delivery expectations.
- Veterinary Hospitals:Mid-sized chains centralize molecular spend through automated platforms with captive reagent contracts. Point-of-care thermal cyclers compress turnaround for infectious disease workups.
- Diagnostic Laboratories:Reference networks in the United States consolidate volume across three national providers, constraining independent regional lab pricing power.
- Research Institutes:University veterinary schools anchor applied biosystems deployments for teaching and outbreak investigation protocols.
- Animal Breeding Centers:Equine and canine facilities prioritize genetic disorder panels and parentage verification.
- Pharmaceutical Companies:Preclinical toxicology and vaccine efficacy studies drive contract molecular service demand.
Veterinary Hospitals hold the leading position, while Diagnostic Laboratories are gaining share through reference network consolidation.
Technology:
Maturity curves separate established validation from emerging capability expansion.
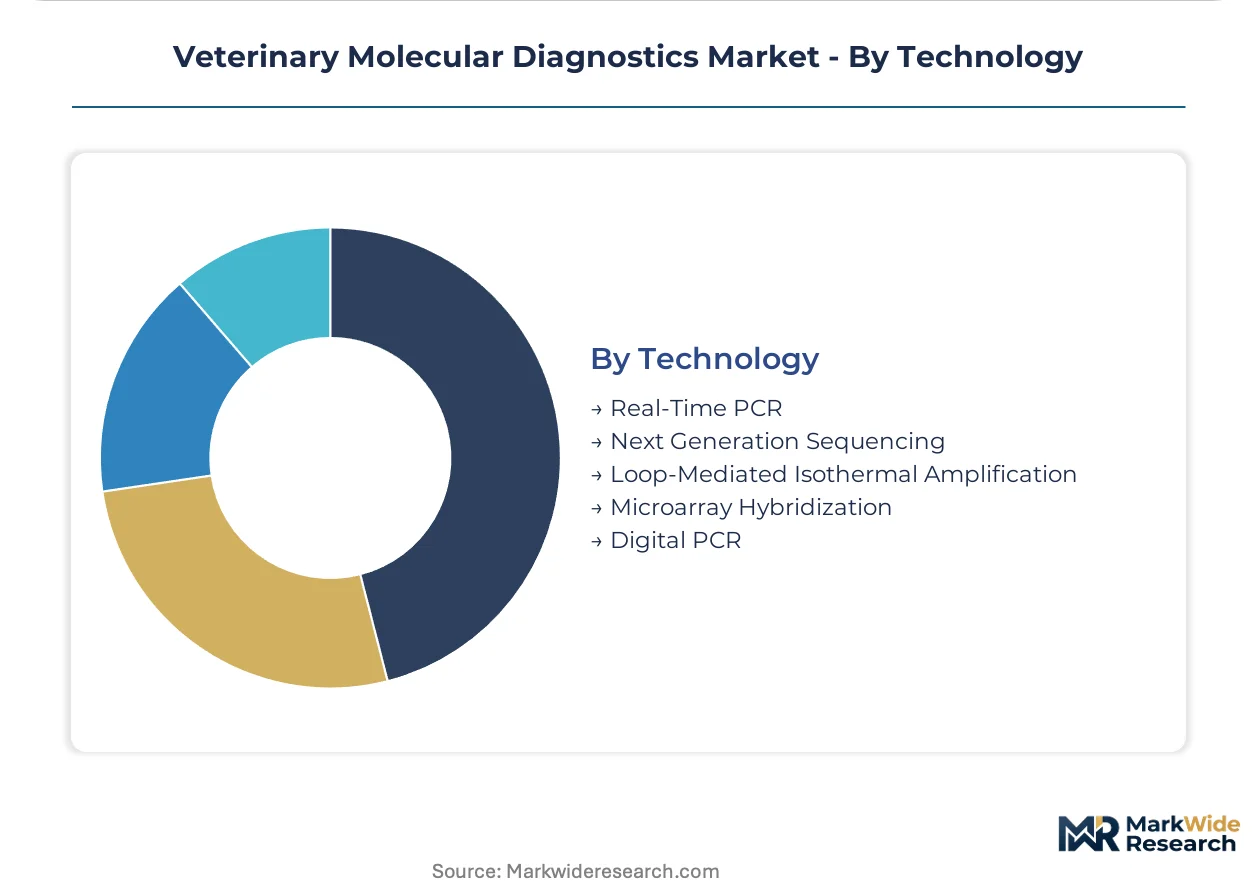
- Real-Time PCR:Gold-standard sensitivity with single-copy detection thresholds dominates commercial veterinary panels. OIE reference laboratory validation underpins regulatory acceptance across USDA-APHIS jurisdictions.
- Next Generation Sequencing:Metagenomic approaches enable untargeted pathogen discovery in outbreak investigations. Japan's aquaculture sector drives platform adoption for environmental surveillance.
- Loop-Mediated Isothermal Amplification:Field-deployable formats operate without thermal cyclers in resource-limited settings.
- Microarray Hybridization:Solid-phase multiplexing supports high-throughput genetic screening in breeding applications.
- Digital PCR:Absolute quantification of circulating tumor DNA opens premium oncology services in university veterinary teaching hospitals.
Real-Time PCR maintains the dominant technology position, while Next Generation Sequencing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented livestock economies drive molecular diagnostic demand through USDA-APHIS interstate movement mandates and EU Animal Health Law compliance requirements. Importing nations with stringent veterinary health protocols create secondary demand for validated PCR assays at border inspection points.
United States
Mid-sized veterinary hospital chains in Texas and California centralize procurement through automated nucleic acid platforms with captive reagent contracts. USDA-APHIS interstate movement rules sustain demand for avian influenza and bovine tuberculosis testing in livestock export corridors. The I-35 corridor from Dallas to Kansas City anchors reference laboratory consolidation among three national diagnostic networks.
Germany
EU Animal Health Law harmonization reduces validation burden for assay manufacturers seeking multi-country registration across member states. The country's national pharmaceutical regulator enforces standardized molecular workflow specifications that laboratories in Bavaria and North Rhine-Westphalia must follow. Munich and Stuttgart host university veterinary schools deploying benchtop NGS platforms for aquaculture pathogen discovery.
Japan
METI funding for aquaculture biosecurity accelerates next-generation sequencing adoption for environmental DNA monitoring in marine disease surveillance. The country's national pharmaceutical regulator evaluates diagnostic kit premarket pathways for companion animal infectious disease panels. Tokyo and Osaka veterinary teaching hospitals pioneer digital PCR oncology applications for canine circulating tumor DNA quantification.
United Kingdom
Kennel club mandates for documented genetic carrier status drive hereditary disease panel demand among canine breeding programs in England and Scotland. The country's national pharmaceutical regulator aligns with EU Animal Health Law transition protocols post-Brexit. Cambridge and Edinburgh research clusters anchor applied biosystems deployments for outbreak investigation protocols.
Canada
Health Canada and PMRA oversight of veterinary biologics creates parallel validation requirements for molecular diagnostic kits entering the livestock sector. Prairie province feedlot operations require bovine respiratory pathogen PCR testing for antibiotic stewardship compliance. The Calgary-Edmonton corridor concentrates veterinary diagnostic laboratory capacity serving Alberta's cattle export industry.
Veterinary Molecular Diagnostics Market Key Industry Players
On the supply side, the industry is consolidating around three strategic archetypes: diversified animal health conglomerates with captive assay menus, life sciences instrumentation specialists with thermal cycler platforms, and reference laboratory networks with centralized molecular workflows. Competitive positioning depends on reagent rental contract penetration and multi-year consumable lock-in arrangements. M&A activity targets regional diagnostic laboratories to expand reference network coverage, while technology licensing agreements accelerate assay menu expansion without internal R&D investment.
Among diversified animal health conglomerates, Zoetis exemplifies the pharmaceutical-diagnostic bundling archetype through its broader vaccine and therapeutic portfolio integration. IDEXX Laboratories anchors the reference laboratory consolidation model with recurring revenue structures tied to installed instrument bases. Thermo Fisher Scientific occupies the instrumentation specialist tier through applied biosystems thermal cycler deployments in university veterinary schools. These three entities represent distinct competitive vectors: pharmaceutical bundling, laboratory network scale, and platform technology dominance.
| Leading Market Players |
|---|
| Zoetis |
| IDEXX Laboratories |
| Antech Diagnostics |
| Thermo Fisher Scientific |
| Neogen Corporation |
| Bio-Rad Laboratories |
| QIAGEN |
| bioMérieux |
| Gold Standard Diagnostics |
| Others |
Cost & Logistics Intelligence
Polymerase enzyme production concentration in Germany and the United States determines where margin pools accumulate across reagent supply tiers. Diagnostic manufacturers with captive master mix formulations extract premium pricing from laboratories locked into proprietary probe-fluorophore ecosystems.
Pricing Analysis
Veterinary hospital chains anchor consumable pricing through multi-year reagent rental contracts that bundle thermal cycler placements with minimum volume commitments. Three-tier pricing structure across premium, standard, and economy levels separates validated USDA-APHIS assay kits from research-use-only panels and unvalidated import alternatives. Pricing pressure stems from reference laboratory consolidation among three national networks that squeeze independent regional labs on turnaround-based contracts. Mid-sized clinic groups show highest price sensitivity, while university teaching hospitals absorb premium digital PCR oncology service tiers.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for fluorophore-conjugated probe manufacturing. Upstream polymerase enzyme production draws from Germany, the United States, and Japan, while thermal cycler hardware sources from Malaysia and Mexico assembly facilities. Single-source vulnerability concentrates in proprietary extraction buffer formulations that lock laboratories into vendor ecosystems. Distribution runs through captive reagent logistics networks serving consolidated veterinary hospital chains, with secondary channels supplying independent clinics through distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward mid-sized veterinary hospital chains as procurement centralization concentrates volume among fewer decision-makers. Three national reference laboratory networks now dictate terms to regional independents.
For Market Incumbents: Build switching-cost moats through lyophilized reagent cartridge ecosystems that eliminate cold chain dependencies for field-deployed units. Deepen backward integration into polymerase enzyme production to buffer margin compression from raw material volatility. Anchor positions by securing exclusive USDA-APHIS assay validation contracts before regulatory harmonization completes. For New Entrants and Emerging Players: Build out point-of-care thermal cycler penetration in mobile veterinary units and remote livestock operations previously captive to mail-out reference testing. Target aquaculture environmental DNA monitoring in Japan and Germany where metagenomic NGS adoption outpaces assay menu depth. Enter through battery-operated isothermal amplification platforms that bypass thermal cycling infrastructure requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional diagnostic laboratory networks ripe for rollup into national reference platforms. Long-term viability hinges on automated nucleic acid extraction throughput scale and multi-year reagent contract renewal rates. Watch digital PCR oncology service tier expansion in university veterinary teaching hospitals as inflection signal for premium platform migration.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Rental Contract Expansion | Captive consumable commitments from IDEXX Laboratories lock veterinary chains into multi-year revenue streams. |
| EU Animal Health Law Harmonization | Consolidated regulatory submissions reduce validation burden for assay manufacturers seeking multi-country registration. |
| Point-of-Care Platform Deployment | Battery-operated thermal cyclers from Thermo Fisher Scientific penetrate mobile units previously served by mail-out testing. |
| Digital PCR Oncology Service Launch | Absolute quantification of circulating tumor DNA opens premium tiers in university veterinary teaching hospitals. |
| Reference Laboratory Network Consolidation | Antech Diagnostics and national platforms squeeze independent regional labs through turnaround-based contract competition. |
Research Approach
Operator-level perspectives from veterinary diagnostic laboratory directors, PCR validation specialists, reference network procurement managers, and thermal cycler platform engineers anchored the qualitative base. Primary interviews combined with secondary validation against USDA-APHIS assay approval databases, EU Animal Health Law implementation directives, and university veterinary school equipment procurement records. Bottom-up segmentation modeling triangulated with top-down macro veterinary expenditure trends.
Scenario-bracketing framed analytical approaches across the projection horizon, with sensitivity testing for regulatory harmonization timing and reference laboratory consolidation pace. Segmentation dimensions spanned technology maturity curves, end-user procurement centralization levels, application regulatory mandate intensity, and geographic adoption pattern clusters. CAGRs derived from installed instrument base growth trajectories and reagent consumption per thermal cycler metrics, incorporating aquaculture biosecurity funding flows and companion animal hospital chain expansion plans.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified animal health conglomerates into point-of-care instrumentation would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
In-Vitro Diagnostics (IVD) Packaging Market
Diagnostics
LDL Test Market
Diagnostics
Global Saliva Collection and Diagnosis Market
Diagnostics
Treponema Pallidum Tests Market
Diagnostics
Fertility Testing Devices Market
Diagnostics
North America Molecular Diagnostics Market
Diagnostics
Immunodiagnostics Market
Diagnostics
South Korea in Vitro Diagnostics Market
Diagnostics
Mexico in-Vitro Diagnostics Market
Diagnostics
Latex Agglutination Test Market
Diagnostics
Europe in Vitro Diagnostics (IVD) Market
Diagnostics
Viral Disease Diagnosis Market
Diagnostics
Europe Ovarian Cancer Diagnostics Market
Diagnostics
Urinary Protein Reagents Market
Diagnostics
Global Lyme Disease Diagnostic Market
Diagnostics
Influenza Diagnostic Tests Market