
 Global Pediatric Interventional Cardiology Market | 2026-2036
Global Pediatric Interventional Cardiology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pediatric Interventional Cardiology Market Intelligence
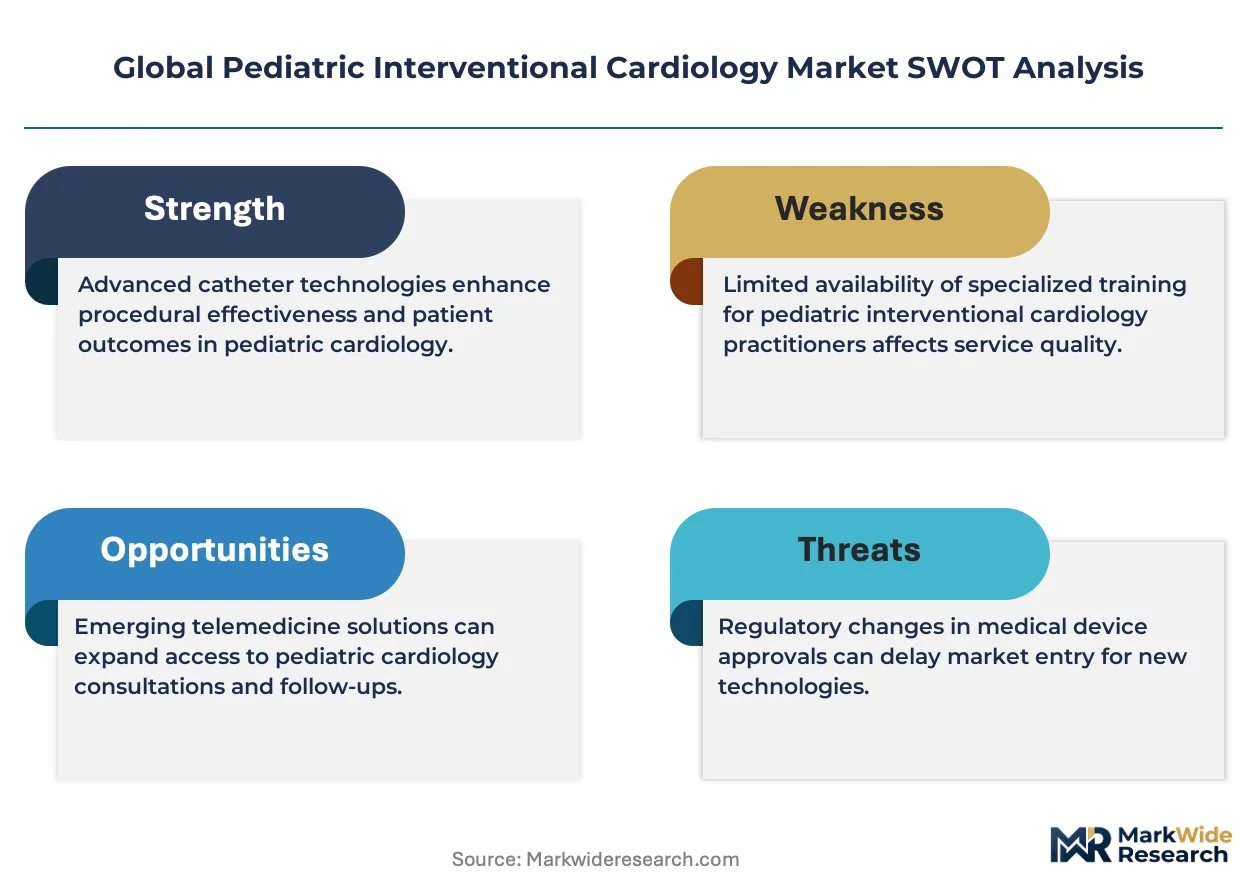
The push for smaller, MRI-compatible device profiles is unwinding previous design limitations for pediatric implants. Medtronic leverages its extensive R&D in catheter technology to address complex congenital cases. Edwards Lifesciences specializes in transcatheter heart valves adapted for pediatric anatomies. Abbott Laboratories competes through its portfolio of advanced occluders for septal defects.
Pediatric interventional cardiology encompasses minimally invasive, catheter-based procedures to treat structural heart diseases in neonates, infants, and children. These interventions utilize specialized devices, such as low-profile catheters and nitinol-frame occluders, to repair defects without open-heart surgery. Procedures for congenital heart defects, particularly atrial septal defect closure, constitute a primary application area. Within the device landscape, occluders and specialized balloons represent high-value segments, while guidewires remain a foundational, volume-driven category.
Regulatory pathways are stringent, with the US FDA's Humanitarian Device Exemption (HDE) and the EU's Medical Device Regulation (MDR) setting high safety and efficacy evidence standards. Approval processes under agencies like Japan's PMDA also require extensive clinical data specific to pediatric cohorts. Stakeholders must navigate the trade-offs between developing highly specialized, low-volume devices and securing viable reimbursement pathways from payers.
Market Dynamics
The convergence of advanced material science with imaging compatibility is the central force redefining device design. This allows for the creation of smaller, MRI-safe implants that address the unique anatomical challenges of neonatal and pediatric patients, pushing the boundaries of minimally invasive treatment.
Growth Catalysts
- Bioresorbable Materials:Innovations in polymers for stents and occluders eliminate the need for future surgeries to remove permanent implants, improving long-term patient outcomes.
- Demand Concentration:High procedural volumes in specialized pediatric cardiac centers in the United States and Germany create a focused demand pool for advanced devices.
- Dedicated Regulatory Pathways:The FDA's Humanitarian Device Exemption (HDE) provides a viable route for bringing low-volume devices for rare pediatric conditions to market.
Market Restraints
- Reimbursement Uncertainty:High development costs for low-volume devices often face inconsistent reimbursement from payers, creating financial risk for manufacturers.
- Technical Miniaturization Limits:The physical constraints of shrinking complex devices like transcatheter heart valves for neonatal anatomies remain a significant technical barrier.
- EU Regulatory Hurdles:The EU's Medical Device Regulation (MDR) requires extensive pediatric-specific clinical data, which can significantly delay or block market access.
Strategic Opportunities
- Emerging Market Penetration:Expanding access to interventional procedures in large economies like India and Brazil addresses a significant unmet clinical need in their pediatric populations.
- Advanced Imaging Integration:Converging 4D MRI with catheter navigation systems offers an opportunity to enhance procedural accuracy and safety for complex congenital heart repairs.
- New Device Applications:Developing percutaneous pulmonary valves for smaller pediatric patients opens a new, high-value clinical segment beyond current device capabilities.
Industry Challenges
- Specialized Talent Shortage:A scarcity of interventional cardiologists trained in complex neonatal and pediatric procedures limits the capacity of health systems to adopt new techniques.
- Extended Approval Timelines:Navigating the data-intensive approval processes of regulators like Japan's PMDA for novel pediatric devices creates significant operational delays for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pediatric Interventional Cardiology Market |
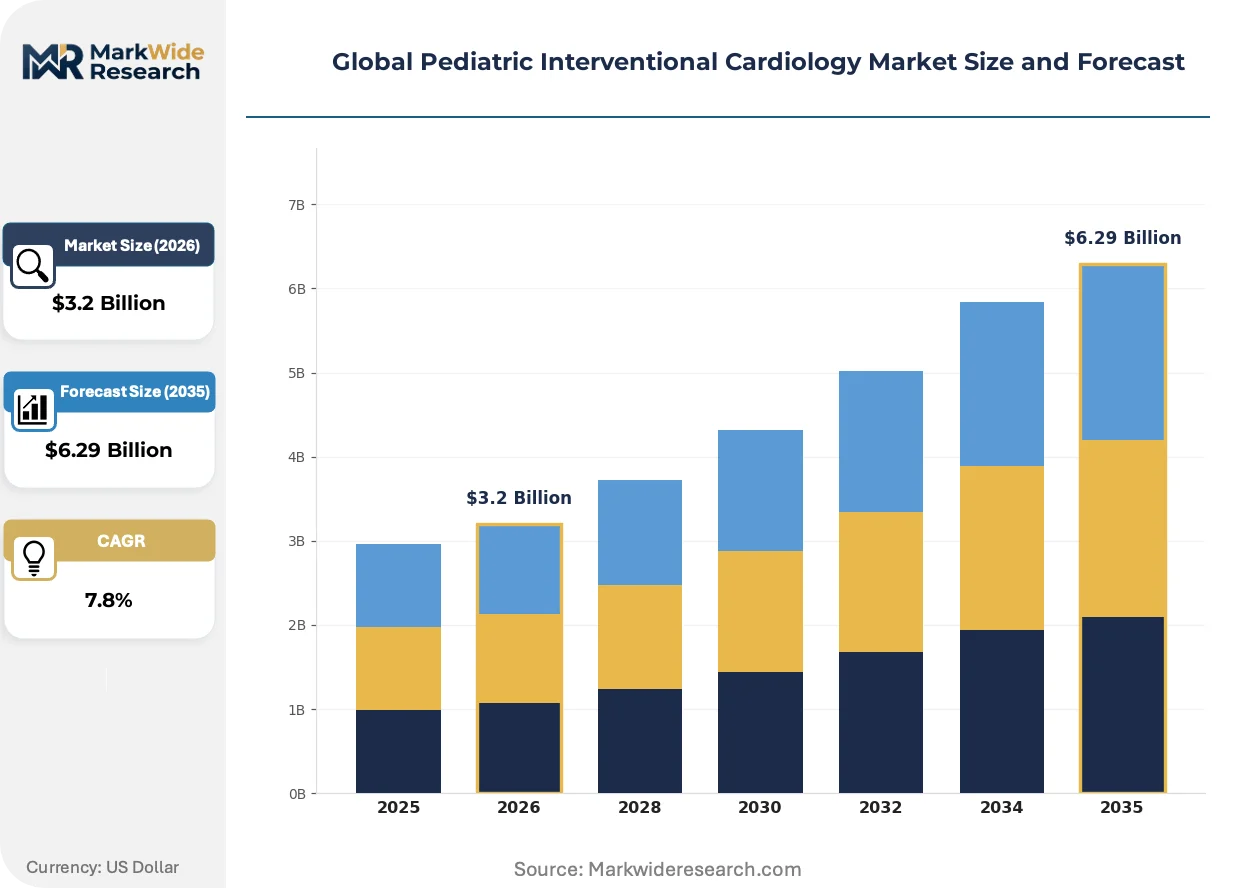
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
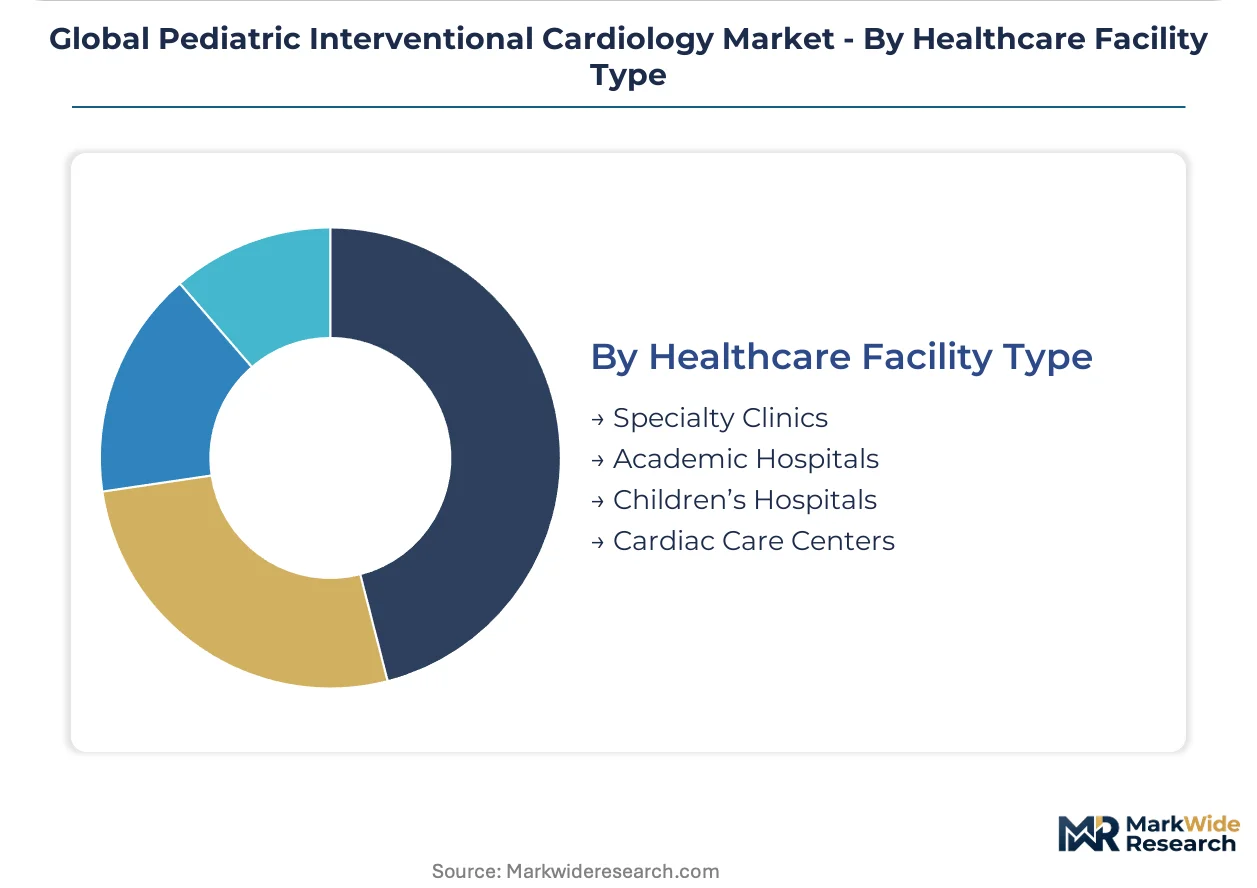
| Segmentation | Procedure Type: Balloon Angioplasty, Device Closure, Stent Implantation, Atherectomy, Catheter Ablation Device Type: Guidewires, Catheters, Occluders, Balloons, Stents Patient Condition: Congenital Heart Defects, Arrhythmias, Valvular Disorders, Pulmonary Stenosis, Atrial Septal Defect Healthcare Facility Type: Specialty Clinics, Academic Hospitals, Children’s Hospitals, Cardiac Care Centers |
| Companies Covered | Medtronic, Abbott Laboratories, Boston Scientific, Edwards Lifesciences, Terumo, W. L. Gore & Associates, NuMed, Cook Medical, Biotronik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pediatric Interventional Cardiology Market Strategic Shifts & Innovations
A fundamental shift toward less invasive and more biocompatible solutions is redefining product development. This evolution prioritizes long-term patient outcomes by minimizing the number of interventions required over a child's lifetime, influencing both device design and clinical practice.
Bioresorbable scaffolds, made from materials like polylactide, provide temporary structural support before safely degrading within the body. Specialized pediatric cardiac centers are adopting these for septal defect occluders to avoid permanent implants in growing children. This advancement is bifurcating the device market into permanent metallic implants and temporary bioresorbable solutions, altering long-term patient management.
Japan's PMDA has increased its emphasis on post-market surveillance and real-world evidence for pediatric medical devices. This requirement compels manufacturers to invest in long-term data collection infrastructure beyond initial clinical trials. The occluder and transcatheter valve segments are most affected, as performance data in growing anatomies is critical for maintaining authorization.
Hospital procurement for common procedures like atrial septal defect closure is moving away from buying individual components toward acquiring comprehensive procedural kits. This shift disrupts the sales model for standalone guidewires, favoring suppliers who can bundle all necessary devices. This trend is most visible in high-volume cardiac centers in the United States and Germany.
Global Pediatric Interventional Cardiology Market Segmentation
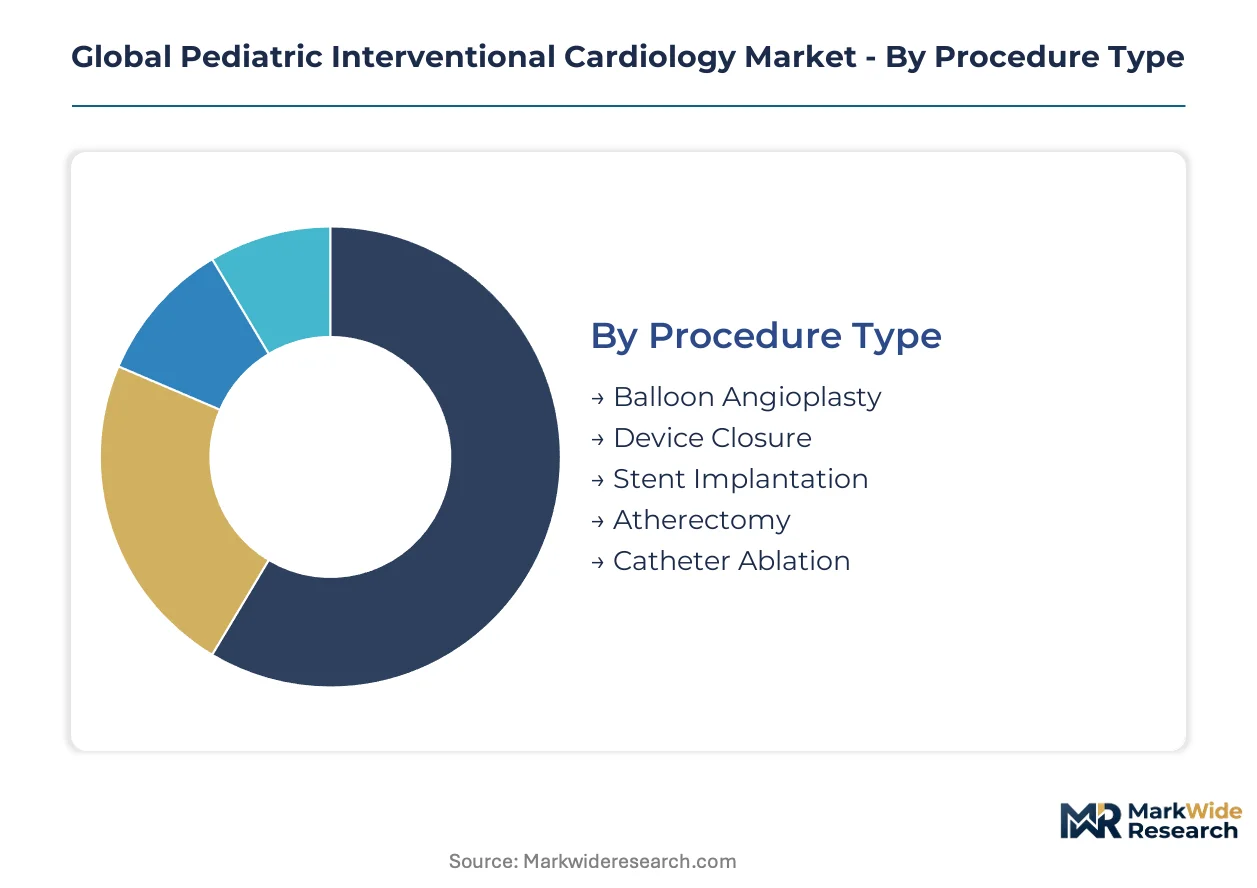
The Global Pediatric Interventional Cardiology Market delineates distinct operational areas, revealing where specialized resources and investment generate the highest clinical impact. Understanding these segments helps manufacturers tailor device development and market entry strategies for specific procedural needs and patient populations. This granular view informs resource allocation across the complex pediatric cardiac care ecosystem.
Procedure Type:
Margin pools within this category center on complex, high-value interventions requiring advanced device technology and specialized clinician training. These procedures address structural heart defects and rhythm disorders in pediatric patients, often presenting unique anatomical challenges.
- Device Closure:This minimally invasive procedure uses specialized occluders to repair congenital heart defects like atrial septal defects or patent ductus arteriosus. Demand concentrates in specialized pediatric cardiac centers in the United States, driven by improved patient outcomes and reduced recovery times.
- Stent Implantation:Stents provide structural support to narrowed vessels or ducts, maintaining patency in conditions such as pulmonary artery stenosis or coarctation of the aorta. Innovations in bioresorbable materials are advancing this segment, particularly in Germany.
- Balloon Angioplasty:Catheter-based balloon inflation opens narrowed blood vessels or valves, restoring proper blood flow. This technique serves as a foundational intervention for various congenital heart conditions.
- Atherectomy:This procedure removes plaque from blood vessels using a catheter with a cutting device. It targets specific vascular obstructions, though less common in pediatric applications.
- Catheter Ablation:Radiofrequency or cryoenergy delivered via catheter corrects irregular heart rhythms in pediatric patients. This technique offers a less invasive alternative to open-heart surgery for arrhythmias.
Device Closure holds installed capacity. Stent Implantation is rotating up the share rankings.
Device Type:
Application diversity shapes this segment, with devices ranging from foundational tools used in nearly every procedure to highly specialized implants for specific repairs. Each device type addresses distinct clinical requirements within pediatric interventional cardiology.
- Occluders:These devices permanently close structural defects like atrial septal defects or ventricular septal defects, preventing abnormal blood flow. Abbott Laboratories develops advanced occluders, finding significant application in children’s hospitals.
- Stents:Expandable mesh tubes restore blood flow in narrowed arteries or veins, often made from nitinol or bioresorbable polymers. Medtronic leverages extensive R&D in catheter technology for stent delivery, particularly for complex congenital cases.
- Guidewires:Flexible wires navigate catheters through the vascular system to the heart. These are foundational, high-volume components in all interventional procedures.
- Catheters:Thin, flexible tubes deliver devices, diagnostic tools, or therapeutic agents into the heart. Smaller, MRI-compatible profiles are critical for neonatal and infant anatomies.
- Balloons:Inflatable devices on catheters dilate stenotic vessels or valves. Specialized balloons are essential for angioplasty and valvuloplasty procedures.
Occluders are expanding most quickly. Guidewires maintain broad adoption.
Patient Condition:
Procedural volume heavily influences this category, with congenital heart defects representing the most frequent indications for intervention. Each condition requires tailored approaches and specialized devices.
- Congenital Heart Defects:Structural problems with the heart present at birth, ranging from simple holes to complex malformations. Device closure procedures for these defects constitute a primary application area across global pediatric cardiac centers.
- Atrial Septal Defect:A hole in the wall separating the heart's upper chambers, often treated with minimally invasive device closure. Hospital procurement for this common procedure increasingly favors comprehensive procedural kits, especially in the United States.
- Arrhythmias:Irregular heartbeats caused by electrical signal malfunctions. Catheter ablation procedures address these conditions, particularly in older pediatric patients.
- Valvular Disorders:Malfunctions of the heart valves, such as stenosis or regurgitation. Balloon valvuloplasty or transcatheter valve implantation can treat these conditions.
- Pulmonary Stenosis:Narrowing of the pulmonary valve, restricting blood flow to the lungs. Percutaneous pulmonary valves for smaller pediatric patients offer a significant strategic opportunity.
Congenital Heart Defects represents a foundational segment. Pulmonary Stenosis is gaining clinical traction.
Healthcare Facility Type:
Customer type defines this segment, reflecting the specialized infrastructure and expertise required for pediatric interventional cardiology. High procedural volumes concentrate in facilities equipped for complex cases.
- Children’s Hospitals:Dedicated facilities with specialized pediatric cardiac units, offering comprehensive care for complex congenital heart defects. These hospitals drive significant demand for advanced devices due to their high procedural volumes.
- Academic Hospitals:University-affiliated medical centers performing research and training, often housing leading pediatric cardiology departments. These institutions contribute to device innovation and clinical adoption, especially in Germany.
- Specialty Clinics:Outpatient facilities focusing on specific cardiac conditions or follow-up care. These clinics may perform less invasive diagnostic procedures or post-interventional monitoring.
- Cardiac Care Centers:Facilities providing diagnosis, treatment, and rehabilitation for heart conditions. Some centers have specialized units for pediatric patients, though capacity varies.
Children’s Hospitals drive specialized demand. Academic Hospitals provide broader access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies significantly across regional markets, with highly specialized procedures in developed economies exhibiting lower price sensitivity due to critical patient needs. Conversely, expanding access in emerging markets often necessitates more cost-effective solutions for widespread adoption. This dynamic shapes investment priorities for device manufacturers globally.
United States
High procedural volumes for congenital heart defects drive demand for advanced interventional devices within the United States. The FDA's Humanitarian Device Exemption (HDE) pathway supports market entry for low-volume devices addressing rare pediatric conditions. Boston's extensive medical technology cluster fosters innovation in pediatric catheter and implant design.
Germany
Specialized pediatric cardiac centers in Germany exhibit strong demand for bioresorbable materials in stents and occluders, pushing innovation in less invasive treatments. The EU's Medical Device Regulation (MDR) sets stringent safety and efficacy standards for all pediatric devices entering the market. Munich's academic hospitals actively contribute to clinical research and advanced device adoption.
Japan
Japan's market emphasizes long-term patient outcomes, with the PMDA requiring extensive post-market surveillance and real-world evidence for pediatric medical devices. This regulatory environment encourages investment in durable and biocompatible solutions for growing anatomies. Tokyo's research institutions are central to developing novel pediatric interventional techniques.
India
A significant unmet clinical need for pediatric interventional procedures drives market penetration efforts in large economies like India. The Central Drugs Standard Control Organization (CDSCO) regulates medical device approvals, focusing on accessibility and safety for its pediatric population. Bangalore's burgeoning medical device sector aims to develop locally tailored solutions.
Global Pediatric Interventional Cardiology Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the global pediatric interventional cardiology market. The market structure is tiered, with specialized innovators coexisting alongside broad portfolio providers and niche solution developers. Portfolio diversification into advanced materials and geographic expansion into underserved markets are common competitive moves.
Innovators focusing on miniaturization and biocompatibility, such as Edwards Lifesciences, exemplify the high-value segment for transcatheter heart valves adapted for pediatric anatomies. Broad portfolio providers, including Medtronic and Abbott Laboratories, anchor the market with extensive R&D in catheter technology and advanced occluders for septal defects respectively. These companies occupy positions across various device types, leveraging their scale and clinical expertise.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Boston Scientific |
| Edwards Lifesciences |
| Terumo |
| W. L. Gore & Associates |
| NuMed |
| Cook Medical |
| Biotronik |
| Others |
Cost & Logistics Intelligence
The EU's Medical Device Regulation (MDR) gates both supply qualification and price differentiation for pediatric interventional devices. This regulatory stringency drives higher development costs, impacting final product pricing and influencing supplier selection.
Pricing Analysis
After-sales service contracts drive lifetime value in pediatric interventional cardiology, ensuring device longevity and performance. The pricing model primarily follows a value-based, per-unit transactional structure for specialized implants. Price differentiation stems from device miniaturization capabilities and the specific certification level achieved, such as FDA HDE approval. Pricing pressure stems from inconsistent reimbursement policies from payers, particularly for low-volume devices. Children's hospitals, often operating on fixed budgets, exhibit higher price sensitivity compared to academic hospitals investing in cutting-edge research.
Supply Chain Analysis
Germany and the United States anchor the production of specialized bioresorbable materials and complex nitinol components for pediatric devices. Raw material dependencies include medical-grade polymers like polylactide and specialized metal alloys. Single-source vulnerability for highly specialized components poses a significant structural risk. Distribution runs through a direct sales model to specialized pediatric cardiac centers and academic hospitals, often involving dedicated clinical support teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity, with recurring maintenance and software integration expanding faster than initial hardware sales. Device longevity in growing patients necessitates ongoing support and potential future interventions.
For Market Incumbents:
Compound R&D investments in miniaturization and bioresorbable materials to counter the threat of emerging niche innovators. Leverage existing clinical trial infrastructure to meet stringent regulatory requirements like the EU MDR. Expand into emerging markets like India to address unmet clinical needs and diversify revenue streams. Control key intellectual property for advanced catheter navigation systems.
For New Entrants and Emerging Players:
Differentiate on advanced imaging compatibility and patient-specific customization, targeting underserved regions like India. Focus on developing cost-effective, high-quality occluders for common congenital heart defects, which represent a penetrable segment. Partner with specialized pediatric cardiac centers to gain early clinical adoption and generate crucial real-world evidence. Offer comprehensive procedural kits to streamline hospital procurement processes.
For Investors and Strategic Acquirers:
The US FDA's Humanitarian Device Exemption (HDE) reshapes the acquisition landscape for specialized pediatric device manufacturers. Long-term viability rests on portfolios addressing rare, high-need conditions with strong reimbursement pathways. Target vertically integrated mid-cap specialists with proprietary bioresorbable technologies. A signal to watch is the increasing integration of 4D MRI with catheter navigation systems, indicating a shift towards advanced procedural accuracy.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Bioresorbable Materials R&D | Minimizes repeat interventions and improves long-term outcomes for pediatric patients. |
| Expand into Emerging Markets | Addresses significant unmet clinical needs in pediatric populations in large economies. |
| Integrate Advanced Imaging Technologies | Enhances procedural accuracy and safety for complex congenital heart repairs. |
| Develop Percutaneous Pulmonary Valves | Opens a new, high-value clinical segment for smaller pediatric patients. |
| Offer Comprehensive Procedural Kits | Streamlines hospital procurement and improves efficiency for common procedures. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and robust secondary validation. Clinicians, hospital procurement managers, regulatory affairs leads, and R&D executives provided critical insights. Secondary sources included regulatory filings from the FDA, PMDA, and EU MDR, academic publications, and industry association reports. This approach ensured bottom-up and top-down triangulation for data accuracy.
The forecast window spans the mid-term, employing a comprehensive analytical framework. Segmentation dimensions modeled include procedure type, device type, patient condition, and regional regulatory compliance. Compound annual growth rates were derived through a proprietary econometric model, incorporating historical trends and projected technological advancements. Key inputs included clinical trial success rates for novel devices and healthcare expenditure patterns in major economies.
Material uncertainties — including shifts in global healthcare spending and evolving regulatory interpretations — sit outside the modeled envelope. Forecasts reflect assumptions documented through iterative expert consensus. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Neurovascular Stent Retrievers Market
Cardiovascular Devices
Intravascular Stents Market
Cardiovascular Devices
Cerebral Vascular Stent Market
Cardiovascular Devices
Fluid Aspiration System Market
Cardiovascular Devices
Stent Grafts Market
Cardiovascular Devices
Fractional Flow Reserve-Computed Tomography (FFR-CT) Market
Cardiovascular Devices
China Vascular Grafts Market
Cardiovascular Devices
Arterial Stabilization Device Market
Cardiovascular Devices
Global Valvular Heart Disease Treatment Market
Cardiovascular Devices
Atherectomy Systems Market
Cardiovascular Devices
Cardiovascular Repair and Reconstruction Devices Market
Cardiovascular Devices
Surgical Heart Valves Market
Cardiovascular Devices
Implantable Drug Infusion Pumps Market
Cardiovascular Devices
Canada Cardiovascular Devices Market
Cardiovascular Devices
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market
Cardiovascular Devices
Cardiovascular Prosthetic Devices Market