
 Europe Heart Valve Repair and Replacement Market | 2026-2036
Europe Heart Valve Repair and Replacement Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Heart Valve Repair and Replacement Market Foresight
Multi-source procurement of bioprosthetic leaflets and transcatheter delivery systems is consolidating around European cardiac device suppliers with certified manufacturing footprints. Edwards Lifesciences Corporation leverages its pericardial tissue processing capabilities to sustain premium positioning across German and French hospital networks. Medtronic anchors its European presence through localized valve production and direct cardiac surgeon training programs. Abbott Laboratories differentiates via its transcatheter mitral repair platform, competing for shelf space in high-volume interventional cardiology departments.
Europe Heart Valve Repair and Replacement encompasses mechanical, bioprosthetic, and transcatheter valve devices manufactured from pyrolytic carbon, bovine or porcine pericardium, or nickel-titanium alloys, designed to restore unidirectional blood flow across diseased cardiac valves. These devices undergo fatigue testing to ISO 5840 standards and serve patients with stenotic or regurgitant valves who require surgical or catheter-based intervention. Transcatheter valves now command the fastest expansion trajectory, while mechanical valves retain durable utility in younger patient cohorts with longer life expectancy. Bioprosthetic tissue valves capture substantial margin pools in the aortic valve replacement segment due to favorable hemodynamics and avoidance of lifelong anticoagulation.
The EU Medical Device Regulation (MDR) and CE marking framework govern premarket clinical evaluation and post-market surveillance, compelling manufacturers to generate Europe-specific safety and performance data for valve devices. Germany's Federal Institute for Drugs and Medical Devices (BfArM) and France's National Agency for Food, Environmental and Occupational Health Safety (ANSES) enforce national vigilance reporting that shapes product liability exposure and reimbursement negotiations. Stakeholders must monitor evolving Health Technology Assessment outcomes across France, Germany, and Italy to anticipate access restrictions for novel transcatheter interventions.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing clinical evidence timelines while German and French hospital systems simultaneously expand transcatheter valve programs, creating a structural squeeze between regulatory burden and procedural demand acceleration.
Growth Catalysts
- Transcatheter delivery platforms:Catheter-based aortic valve replacement eliminates sternotomy recovery periods, pulling eligible patients toward interventional cardiology suites in tertiary German centers.
- CE marking pathway modernization:Notified body capacity expansion under MDR implementation timelines is restoring predictable market access for novel bioprosthetic designs.
- France:Health Technology Assessment alignment across ANSM and HAS is streamlining reimbursement for mitral repair procedures in high-volume Parisian cardiac centers.
Market Restraints
- Bovine pericardium supply concentration:Tissue processing capacity clusters in specific Alpine and Bavarian facilities, exposing manufacturers to single-source biological material risk.
- MDR clinical evidence requirements:Europe-specific safety data mandates extend premarket timelines by 18-24 months for mechanical valve submissions.
- Surgical valve substitution:Transcatheter platforms capture intermediate-risk patients previously routed to open surgical replacement, compressing mechanical valve addressable volume.
Strategic Opportunities
- Italy:Regional cardiac surgery networks in Lombardy and Emilia-Romagna remain underpenetrated for transcatheter mitral repair, presenting first-mover expansion potential.
- Digital twin simulation:Pre-procedural valve sizing algorithms converge with AI-enabled imaging analytics to reduce paravalvular leak rates in complex anatomies.
- EU Green Deal medical device circularity:Remanufacturing frameworks for delivery system components create regulatory-compliant cost reduction pathways.
Industry Challenges
- Interventional cardiologist training pipelines:Proctoring capacity for transcatheter mitral edge-to-edge repair limits program rollout speed across mid-tier European hospitals.
- ISO 5840 fatigue testing bottlenecks:Third-party validation queue times extend device development cycles for novel nickel-titanium frame geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Heart Valve Repair and Replacement Market |
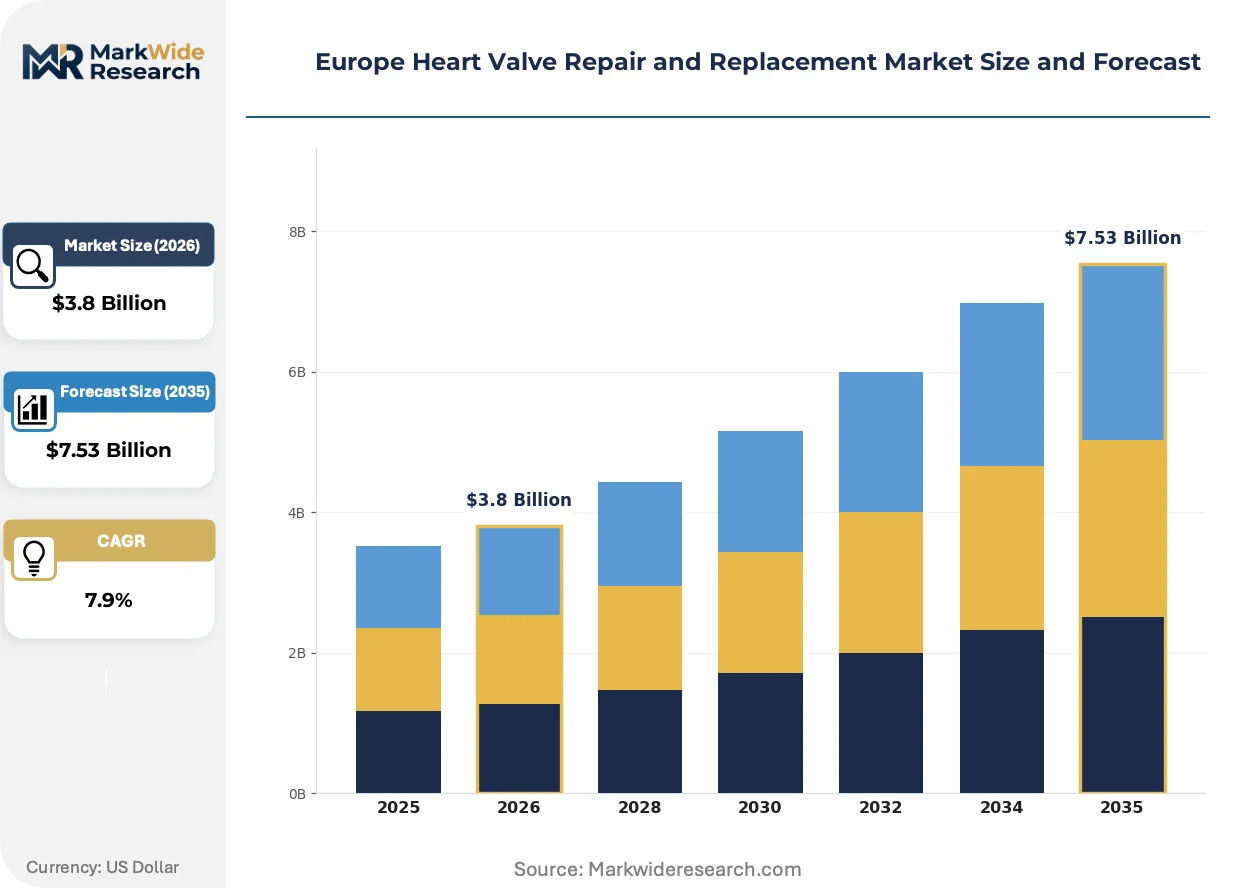
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.53 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Valves, Bioprosthetic Valves, Transcatheter Valves, Tissue Valves End User: Hospitals, Cardiac Clinics, Surgical Centers, Specialty Clinics Delivery Mode: Open-Heart Surgery, Minimally Invasive Surgery, Transcatheter Approach, Hybrid Techniques Application: Mitral Valve Repair, Aortic Valve Replacement, Tricuspid Valve Surgery, Pulmonary Valve Intervention |
| Companies Covered | Edwards Lifesciences Corporation, Medtronic, Boston Scientific Corporation, Abbott Laboratories, JenaValve Technology, Artivion, LivaNova, Symetis, Bracco, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Heart Valve Repair and Replacement Market Shifts & Advancements
Device architecture is converging toward tissue-engineered solutions that eliminate anticoagulation trade-offs, while regulatory data requirements and procurement centralization reshape how manufacturers engage hospital systems.
Polymeric valve leaflets synthesized from supramolecular hydrogels are unifying durability and biocompatibility in a single material platform. Early adopters in Swiss and Dutch university hospitals are integrating these into compassionate-use protocols for patients with contraindications to anticoagulation. The technology is unifying previously separate patient cohorts—those needing mechanical valve longevity and those requiring bioprosthetic hemodynamics—into a single addressable segment.
MDR Article 120 transition deadlines are forcing manufacturers to resubmit legacy device certificates under strengthened clinical evidence standards. The regulation is diverting R&D expenditure toward post-market surveillance infrastructure and notified body relationship management. Class III implantable cardiac devices face the steepest compliance burden, with German manufacturers accelerating PMCF study recruitment to maintain CE marking continuity.
Hospital procurement consortia in France and Germany are consolidating valve purchasing through centralized tender frameworks that bundle device, training, and complication coverage into multi-year agreements. Traditional distributor relationships face disintermediation as manufacturers establish direct contracting with GPOs. The shift is most visible in the Rhône-Alpes and Bavaria regions, where cardiac center networks negotiate as unified entities rather than individual institutions.
Europe Heart Valve Repair and Replacement Market Segmentation
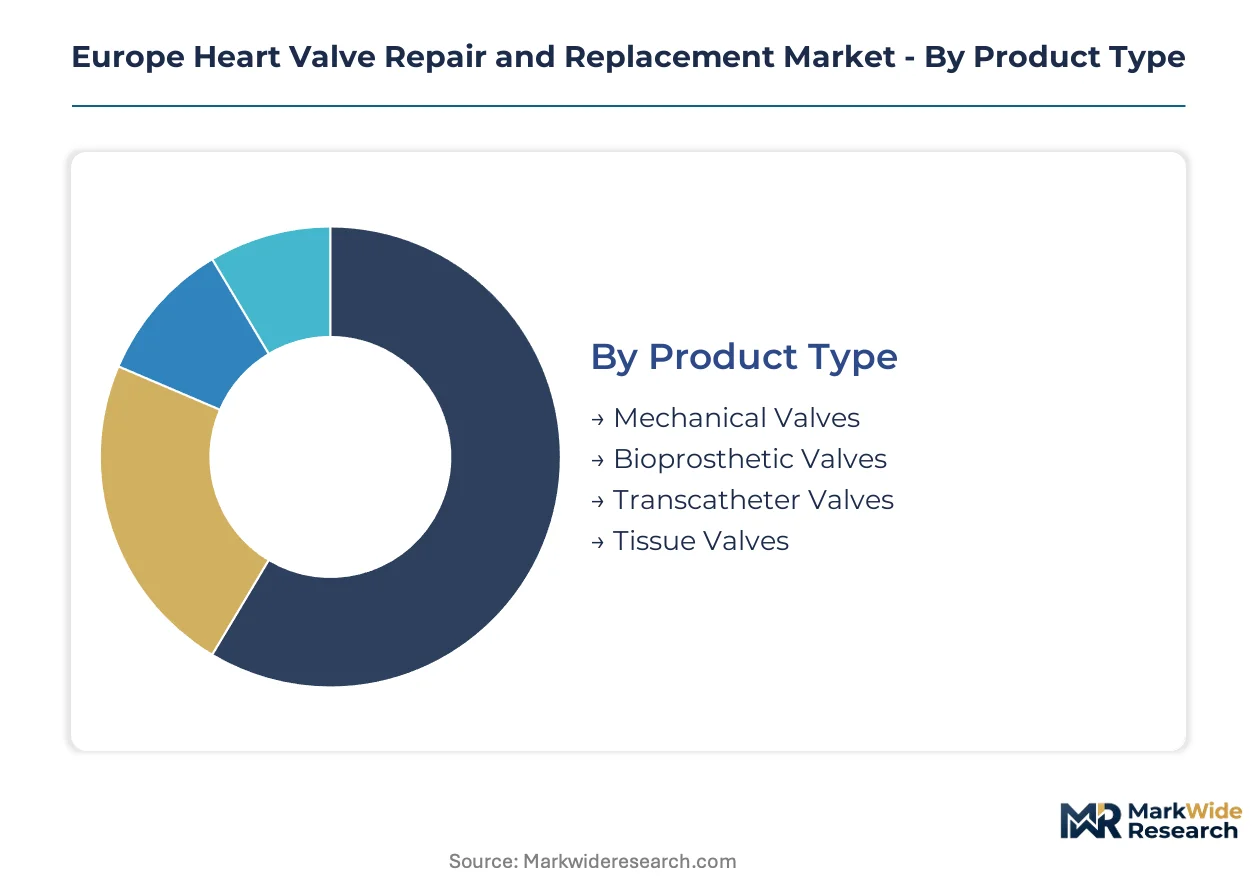
Segmentation reveals how capital deployment, reimbursement pathways, and clinical training infrastructure vary sharply across valve technologies and care settings. Manufacturers must align product portfolios with the specific investment thresholds and regulatory requirements of each segment.
Product Type:
Transcatheter platforms demand the steepest upfront capital commitment, combining nickel-titanium alloy frame development with ISO 5840 fatigue testing infrastructure and proctored physician training networks.
- Mechanical Valves:Pyrolytic carbon leaflets mounted on titanium or cobalt-chromium housings deliver lifetime durability exceeding 25 years. German cardiac centers in Munich and Berlin route younger patients with longer life expectancy toward these devices to avoid reintervention, though lifelong anticoagulation with vitamin K antagonists limits eligibility.
- Bioprosthetic Valves:Bovine or porcine pericardium treated with glutaraldehyde fixation provides favorable hemodynamics without chronic anticoagulation. French hospital networks in Paris and Lyon prioritize these for patients over 65, aligning with HAS reimbursement frameworks that favor tissue valves in older cohorts.
- Transcatheter Valves:Self-expanding or balloon-expandable nickel-titanium frames with pericardial leaflets deployed via femoral access.
- Tissue Valves:Decellularized xenograft or allograft materials processed for enhanced biocompatibility.
Bioprosthetic valves absorb the bulk of installed capacity across Western European tertiary centers; transcatheter platforms are expanding most quickly as catheterization labs proliferate.
End User:
Procurement concentration varies by procedure complexity, with high-volume valve programs consolidating purchasing power through multi-year device-and-training bundles.
- Hospitals:Tertiary cardiac centers with dedicated heart valve surgery volumes exceeding 200 procedures annually anchor European demand. German university hospitals in Heidelberg and Hamburg negotiate directly with manufacturers for transcatheter program support, bypassing traditional distributors.
- Cardiac Clinics:Specialized interventional cardiology suites co-located with diagnostic imaging infrastructure. Milan and Barcelona cardiac clinics drive outpatient transcatheter procedures, leveraging streamlined ANSM and AEMPS regulatory pathways for same-day discharge protocols.
- Surgical Centers:Ambulatory facilities equipped for minimally invasive valve repair.
- Specialty Clinics:Boutique practices focusing on complex redo operations or congenital valve defects.
Hospitals command the dominant share of valve procurement spend; cardiac clinics are climbing the fastest as outpatient transcatheter volumes rise.
Delivery Mode:
Technology maturation and reimbursement alignment determine which access routes capture patient flow across European healthcare systems.
- Open-Heart Surgery:Median sternotomy with cardiopulmonary bypass remains the reference standard for complex multivalve disease and concomitant coronary revascularization. Italian cardiac surgery networks in Lombardy maintain substantial open surgical volumes for younger patients with bicuspid aortic valve anatomy.
- Minimally Invasive Surgery:Right thoracotomy or partial sternotomy approaches reduce recovery time. Dutch university hospitals in Rotterdam and Leiden pioneered mini-sternotomy aortic valve replacement, achieving shorter ICU stays that align with Diagnose Behandeling Combinatie reimbursement optimization.
- Transcatheter Approach:Femoral or alternative vascular access eliminating thoracotomy.
- Hybrid Techniques:Combined surgical and interventional procedures in hybrid operating rooms.
Open-heart surgery retains the largest installed procedural base; transcatheter approaches are gaining share fastest as intermediate-risk indications expand.
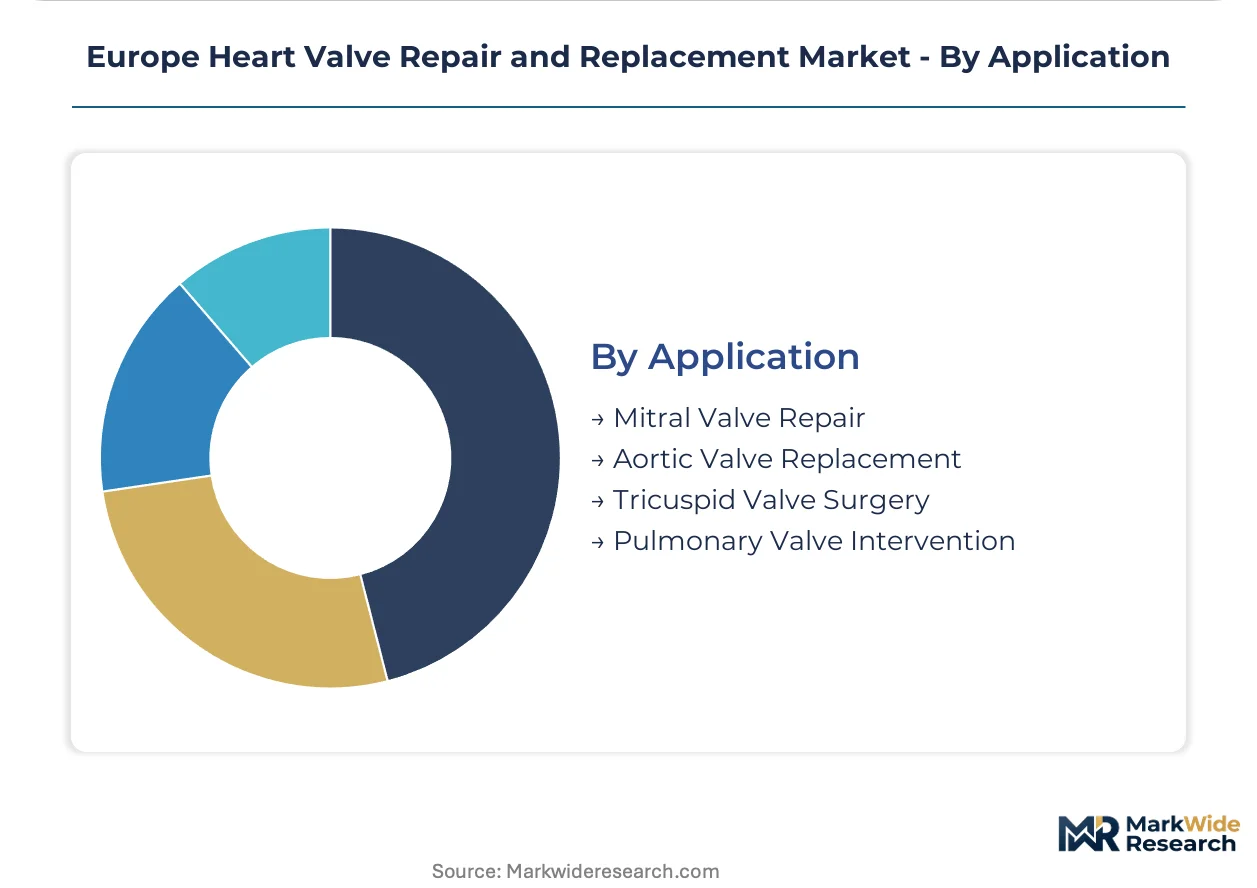
Application:
Anatomical complexity and competitive intensity diverge across valve positions, with regulatory evidence requirements and device approval timelines varying substantially.
- Mitral Valve Repair:Edge-to-edge leaflet approximation or annuloplasty ring implantation preserves native valve geometry. French high-volume centers in Paris deploy transcatheter mitral repair under streamlined HAS assessment, though proctoring bottlenecks constrain program rollout speed.
- Aortic Valve Replacement:Surgical or transcatheter intervention for stenotic or regurgitant aortic valves. German centers in Frankfurt and Cologne drive transcatheter aortic valve replacement volumes, with BfArM vigilance reporting shaping post-market surveillance obligations for device manufacturers.
- Tricuspid Valve Surgery:Surgical repair or replacement for functional regurgitation.
- Pulmonary Valve Intervention:Transcatheter or surgical management of congenital defects.
Aortic valve replacement dominates procedural volumes; mitral valve repair is expanding most quickly as transcatheter platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bovine pericardium processing clusters in Alpine and Bavarian facilities anchor European bioprosthetic valve supply chains. German cardiac centers in Munich and Berlin drive transcatheter program expansion while French hospital networks consolidate procurement through HAS-aligned tender frameworks.
Germany
Heidelberg and Hamburg university hospitals negotiate direct manufacturer contracts for transcatheter program support, bypassing traditional distribution channels. BfArM vigilance reporting shapes post-market surveillance obligations and reimbursement negotiations for novel devices. Bavarian manufacturing clusters near Munich concentrate nickel-titanium frame production and biological tissue processing for regional supply security.
France
Parisian cardiac centers deploy transcatheter mitral repair under streamlined ANSM and HAS assessment pathways. Health Technology Assessment alignment accelerates reimbursement decisions for high-volume interventional cardiology departments. The Rhône-Alpes region consolidates valve purchasing through centralized GPO frameworks that bundle device, training, and complication coverage.
Italy
Lombardy and Emilia-Romagna regional cardiac surgery networks remain underpenetrated for transcatheter mitral repair, presenting first-mover expansion potential. Italian cardiac centers maintain substantial open surgical volumes for younger patients with bicuspid aortic valve anatomy. Milan cardiac clinics drive outpatient transcatheter procedures leveraging streamlined regulatory pathways.
Switzerland
Swiss university hospitals pioneer polymeric valve leaflet integration into compassionate-use protocols for anticoagulation-contraindicated patients. Swissmedic oversight maintains stringent clinical evidence requirements for novel device market entry. Zurich and Basel medical centers anchor tissue-engineered valve research consortiums with Alpine biological material suppliers.
Netherlands
Rotterdam and Leiden university hospitals achieved shorter ICU stays through mini-sternotomy aortic valve replacement, aligning with Diagnose Behandeling Combinatie reimbursement optimization. Dutch cardiac surgery networks emphasize minimally invasive approaches to reduce recovery periods and system costs. Eindhoven-region medical technology clusters support catheter-based delivery system component manufacturing.
Europe Heart Valve Repair and Replacement Market Competitive Landscape
Global majors compete with regional champions across transcatheter platform development and biological tissue processing capabilities. The market structure concentrates around integrated manufacturers with certified MDR compliance infrastructure and established proctored physician training networks. Three archetypes dominate: vertically integrated tissue processors controlling pericardium supply chains, diversified cardiovascular conglomerates with multi-modality valve portfolios, and transcatheter specialists betting on catheter-based displacement of open surgery. Competitive moves center on M&A to secure biological material sources and strategic partnerships with hospital GPOs for multi-year procurement bundling.
Within the diversified cardiovascular tier, Edwards Lifesciences Corporation and Medtronic exemplify scale-driven manufacturers with European production footprints and direct hospital contracting capabilities. Abbott Laboratories occupies a transcatheter specialist position competing for shelf space in high-volume interventional cardiology departments. Boston Scientific Corporation represents the catheter-based platform archetype with established European regulatory pathways and cardiac surgeon training infrastructure. JenaValve Technology anchors the regional European specialist segment with localized valve development and CE marking expertise.
| Leading Market Players |
|---|
| Edwards Lifesciences Corporation |
| Medtronic |
| Boston Scientific Corporation |
| Abbott Laboratories |
| JenaValve Technology |
| Artivion |
| LivaNova |
| Symetis |
| Bracco |
| Others |
Supply & Pricing Matrix
Bovine pericardium processing costs cascade from Alpine tissue facilities through three-tier pricing structures that bundle device, training, and complication coverage for German and French hospital consortia. Nickel-titanium alloy frame fabrication in Bavarian manufacturing clusters anchors premium tier positioning, while glutaraldehyde fixation chemistry and ISO 5840 fatigue testing infrastructure differentiate mid-tier from economy valve offerings.
Pricing Analysis
Extended warranty and proctored physician training bundles separate premium transcatheter valve contracts from unbundled surgical valve transactions. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking tier, pericardium sourcing pedigree, and after-sales surveillance commitment. Cost compression in economy mechanical valves intensifies as transcatheter platforms capture intermediate-risk patients previously routed to open surgical replacement. French GPOs exhibit highest price sensitivity due to HAS reimbursement ceilings, while Swiss university hospitals prioritize hemodynamic performance over procurement cost.
Supply Chain Analysis
Dual-sourcing mandates from German BfArM and French ANSM require manufacturers to qualify secondary pericardium processors in Austria and Switzerland. Biological tissue supply draws from Alpine and Bavarian facilities, nickel-titanium alloy frames from German precision metalworking clusters, and catheter delivery components from Dutch medical technology hubs. Single-source vulnerability concentrates in bovine pericardium supply chains where glutaraldehyde fixation capacity clusters geographically. Distribution runs through hospital procurement consortia in Rhône-Alpes and Bavaria that negotiate multi-year device-and-training agreements directly with manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance timelines are forcing consolidation as smaller manufacturers lack capital for Europe-specific clinical evidence generation and post-market surveillance infrastructure.
For Market Incumbents: Cement market position through backward integration into Alpine pericardium processing facilities and captive supply of nickel-titanium alloy frame production near Munich. Acquire notified body relationship management capabilities to accelerate CE marking continuity for legacy device portfolios. Defend against transcatheter specialists by embedding AI-enabled imaging analytics into pre-procedural valve sizing workflows. For New Entrants and Emerging Players: MDR Article 120 transition deadlines in Europe open a window for novel polymeric valve leaflet platforms that unify mechanical durability with bioprosthetic hemodynamics. Target Swiss and Dutch university hospitals running compassionate-use protocols for anticoagulation-contraindicated patients. Enter through digital twin simulation partnerships that reduce paravalvular leak rates in complex anatomies, bypassing capital-intensive tissue processing infrastructure. For Investors and Strategic Acquirers: Accelerated PMCF study recruitment by German manufacturers is the leading indicator that Class III implantable cardiac device portfolios face imminent valuation pressure from compliance cost burdens. Five-to-ten year viability favors vertically integrated tissue processors with certified MDR infrastructure over pure-play transcatheter platform developers. Monitor Health Technology Assessment alignment across ANSM and HAS as the signal for reimbursement-driven demand inflection in mitral repair segments.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Article 120 resubmission secures market access continuity for legacy bioprosthetic valves in German networks. |
| Hospital System Partnership | Direct contracting with Rhône-Alpes and Bavaria GPOs bundles device, training, and complication coverage. |
| Backward Integration | Alpine pericardium processing acquisition eliminates single-source biological material risk for tissue valve portfolios. |
| Software Companion Development | AI-enabled pre-procedural sizing algorithms reduce paravalvular leak rates in complex transcatheter deployments. |
| Reimbursement Strategy | HAS alignment accelerates transcatheter mitral repair access in Parisian high-volume interventional cardiology departments. |
Research Methodology
EMA submissions, BfArM vigilance databases, and hospital procurement records formed the secondary backbone, supplemented by CMS Medicare data and GPO contract repositories. Primary interviews with cardiac surgeons, interventional cardiologists, biomedical engineers, and GPO contracts managers validated procedural volume assumptions and pricing tier structures. Bottom-up device shipment analysis and top-down healthcare expenditure triangulation anchored market sizing across mechanical, bioprosthetic, and transcatheter valve segments.
Historical trendline analysis of valve replacement procedures and device ASP movements informed projection modeling across the analysis window. Segmentation dimensions included product type, delivery mode, valve position, and end-user facility tier. CAGRs derived from procedure volume elasticity to aging demographics, regulatory approval timelines, and reimbursement pathway expansion. Forecast inputs incorporated MDR transition compliance costs and transcatheter indication expansion curves.
The model assumes a particular technology adoption path; alternative pathways for polymeric valve leaflets would alter the outlook if supramolecular hydrogel durability exceeds current bioprosthetic tissue benchmarks. Forecasts reflect assumptions regarding HAS and BfArM reimbursement stability, pericardium supply chain continuity, and proctoring capacity expansion for transcatheter mitral repair. Deviation in EU MDR notified body capacity or Health Technology Assessment stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Arteriovenous (Av) Fistula Needle Market
Cardiovascular Devices
Intravascular Ultrasound Market
Cardiovascular Devices
Global Intravascular Temperature Management Market
Cardiovascular Devices
Hypertension Management Devices Market
Cardiovascular Devices
Brazil Cardiovascular Devices Market
Cardiovascular Devices
Global Angio Suites Market
Cardiovascular Devices
Australia Cardiovascular Devices Market
Cardiovascular Devices
Anticoagulation Market
Cardiovascular Devices
Intravenous Catheters Market
Cardiovascular Devices
Pulmonary Stents Market
Cardiovascular Devices
North America Interventional Cardiology and Peripheral Vascular Devices Market
Cardiovascular Devices
Arrhythmogenic Right Ventricular Dysplasia Treatment Market
Cardiovascular Devices
Pressure Infusion Bags Market
Cardiovascular Devices
Global Blood Pressure Cuffs Market
Cardiovascular Devices
Cardiac Ablation Catheter Market
Cardiovascular Devices
Transcatheter Heart Valve Replacement (THVR) Market