
 Europe Renal Denervation Devices Market | 2026-2036
Europe Renal Denervation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Renal Denervation Devices Market Foresight
Procedure outcome monitoring and long-term patient tracking services is broadening what European hospitals purchase beyond the initial device. Medtronic leverages its integrated hypertension management platforms to sustain recurring revenue relationships with cardiology departments. Boston Scientific Corporation anchors its European position through deep clinical trial partnerships with university hospitals in Germany and the Netherlands. ReCor Medical differentiates through ultrasound-based technology leadership that occupies a distinct niche against radiofrequency competitors.
Renal denervation devices are catheter-delivered systems that ablate sympathetic nerves surrounding renal arteries using radiofrequency energy, ultrasound waves, or cryothermal delivery at temperatures typically ranging from 50°C to 70°C for thermal modalities, permanently disrupting overactive neural signaling to lower blood pressure in resistant hypertension patients. Catheters and radiofrequency devices currently dominate installed base and reimbursement pathways across European health systems, while ultrasound technology segments are gaining fastest procedural traction where operators prioritize deeper tissue penetration and reduced arterial injury risk. End users cluster heavily in hospitals and Specialty Heart Centers where interventional cardiologists perform these procedures under fluoroscopic guidance with dedicated electrophysiology lab infrastructure.
The European Medicines Agency (EMA) and EU Medical Device Regulation (MDR) enforce stringent clinical evidence standards and post-market surveillance requirements that shape product development timelines and commercialization strategies for device manufacturers. CE marking under MDR Article 52 now demands expanded clinical investigation data for class III devices, directly influencing how companies prioritize trial sites and regulatory submissions across member states. Stakeholders must monitor national reimbursement decisions by health technology assessment bodies in France, Germany, and England as these determinations will gate patient access and volume scalability regardless of regulatory approval status.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing product development timelines and forcing manufacturers to rebuild clinical evidence portfolios for CE marking renewal, fundamentally reshaping how renal denervation technologies reach European patients.
Growth Catalysts
- EMA pathway clarity:The European Medicines Agency's structured guidance on hypertension device trials has reduced regulatory uncertainty for sponsors designing pivotal studies across Germany, France, and the Netherlands.
- Specialty Heart Center expansion:Interventional cardiology hubs in Munich, Paris, and London are installing dedicated renal denervation suites to capture referral flows from resistant hypertension clinics.
- Ultrasound ablation maturation:Deeper tissue penetration capabilities without arterial heating are attracting operators seeking reduced restenosis rates in complex renal anatomies.
Market Restraints
- MDR Article 52 compliance costs:Expanded clinical investigation requirements for class III devices have extended time-to-market by 18-36 months for manufacturers without existing post-market surveillance infrastructure.
- Reimbursement fragmentation:Health technology assessment bodies in France (HAS), Germany (G-BA), and England (NICE) operate independent evaluation timelines, creating patchy patient access across member states.
- Catheter supply concentration:Single-source dependencies for specialized electrode arrays and balloon components expose European distributors to allocation risks during manufacturing disruptions.
Strategic Opportunities
- Poland and Czech Republic penetration:Underdeveloped interventional cardiology networks in Central Europe offer first-mover positioning before reimbursement frameworks mature.
- Remote patient monitoring integration:Pairing renal denervation procedures with ambulatory blood pressure telemetry creates recurring revenue streams beyond the index hospitalization.
- EU Green Deal procurement incentives:Hospitals receiving sustainability-linked capital grants are prioritizing device vendors with validated carbon footprint reductions in manufacturing and sterilization processes.
Industry Challenges
- Electrophysiology lab scheduling bottlenecks:Competition for fluoroscopy suite time between atrial fibrillation ablation and renal denervation procedures constrains procedural volume growth in capacity-constrained NHS trusts.
- MDR notified body capacity shortages:Fewer than fifteen designated bodies currently handle class III cardiovascular device reviews, creating submission backlogs that delay commercial launches regardless of clinical data quality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Renal Denervation Devices Market |
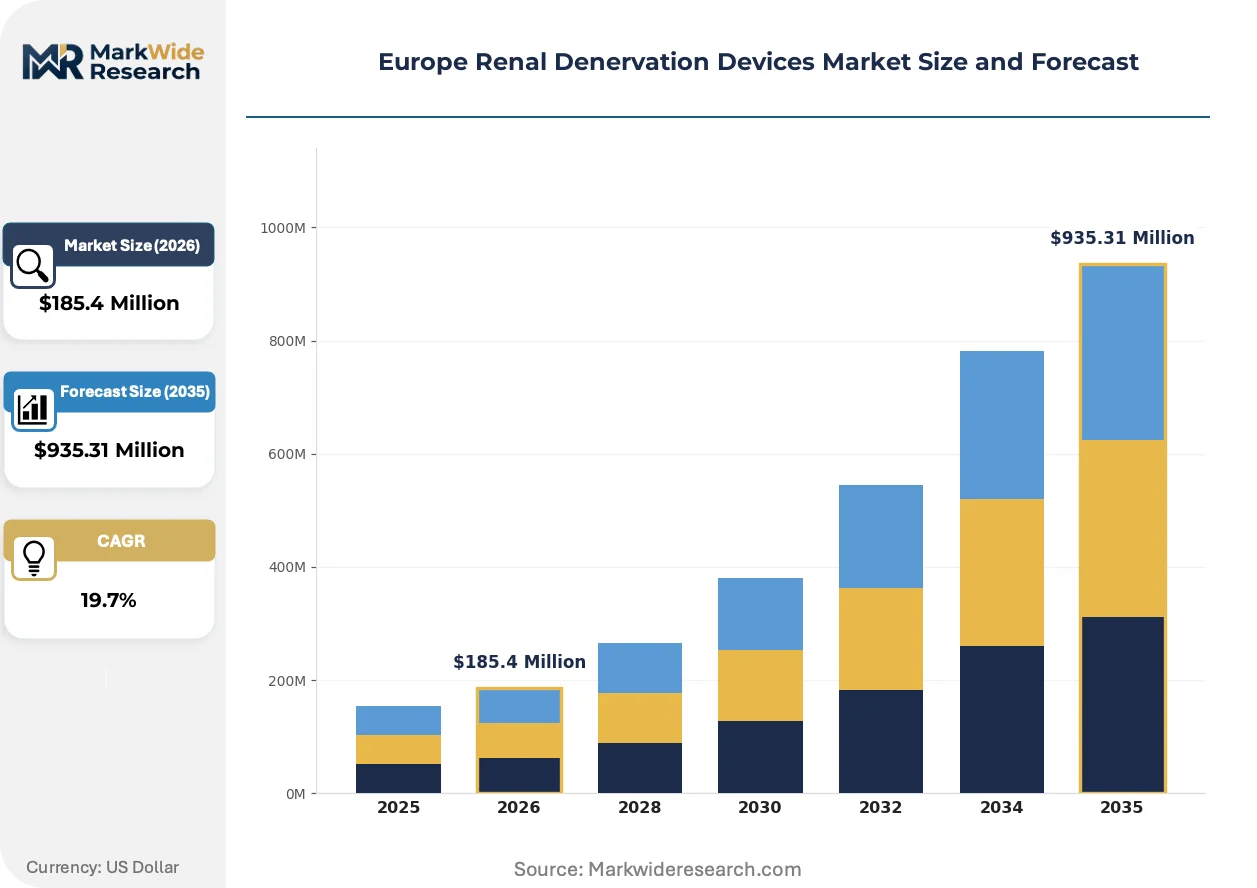
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $935.31 Million |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Radiofrequency Devices, Ultrasound Devices, Cryoablation Devices End User: Hospitals, Clinics, Ambulatory Surgical Centers, Specialty Heart Centers Technology: Radiofrequency Energy, Ultrasound Technology, Laser Technology, Electrical Stimulation Application: Hypertension Treatment, Heart Failure Management, Arrhythmia Control, Renal Transplant Support |
| Companies Covered | Medtronic, Boston Scientific Corporation, ReCor Medical, Ablative Solutions, Mercator MedSystems, Abbott Laboratories, Terumo Corporation, Symple Surgical, Johnson & Johnson, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Renal Denervation Devices Market Shifts & Advancements
Technology convergence between energy delivery systems and procedural guidance software is compressing the learning curve for interventional cardiologists while raising the performance floor for clinical outcomes across European centers.
Radiofrequency-based renal denervation is consolidating its position as the reference technology for resistant hypertension treatment. German university hospitals are standardizing catheter designs that integrate temperature-controlled ablation with impedance monitoring. This consolidation is compressing market space for first-generation unipolar systems that lack real-time feedback mechanisms.
CE marking under MDR Article 52 now demands prospective registries capturing five-year patient outcomes, fundamentally altering post-market surveillance obligations. Manufacturers must fund extended follow-up studies through contracted clinical research organizations. Smaller device sponsors without existing European trial infrastructure face disproportionate compliance burdens compared to established cardiovascular players.
Service unbundling is separating device procurement from procedure outcome guarantees in English NHS contracting. Integrated care systems are negotiating risk-sharing arrangements where device payments tie to documented blood pressure reductions at six and twelve months. This behavioral shift is most visible in Greater Manchester and West Midlands sustainability and transformation partnerships.
Europe Renal Denervation Devices Market Segmentation
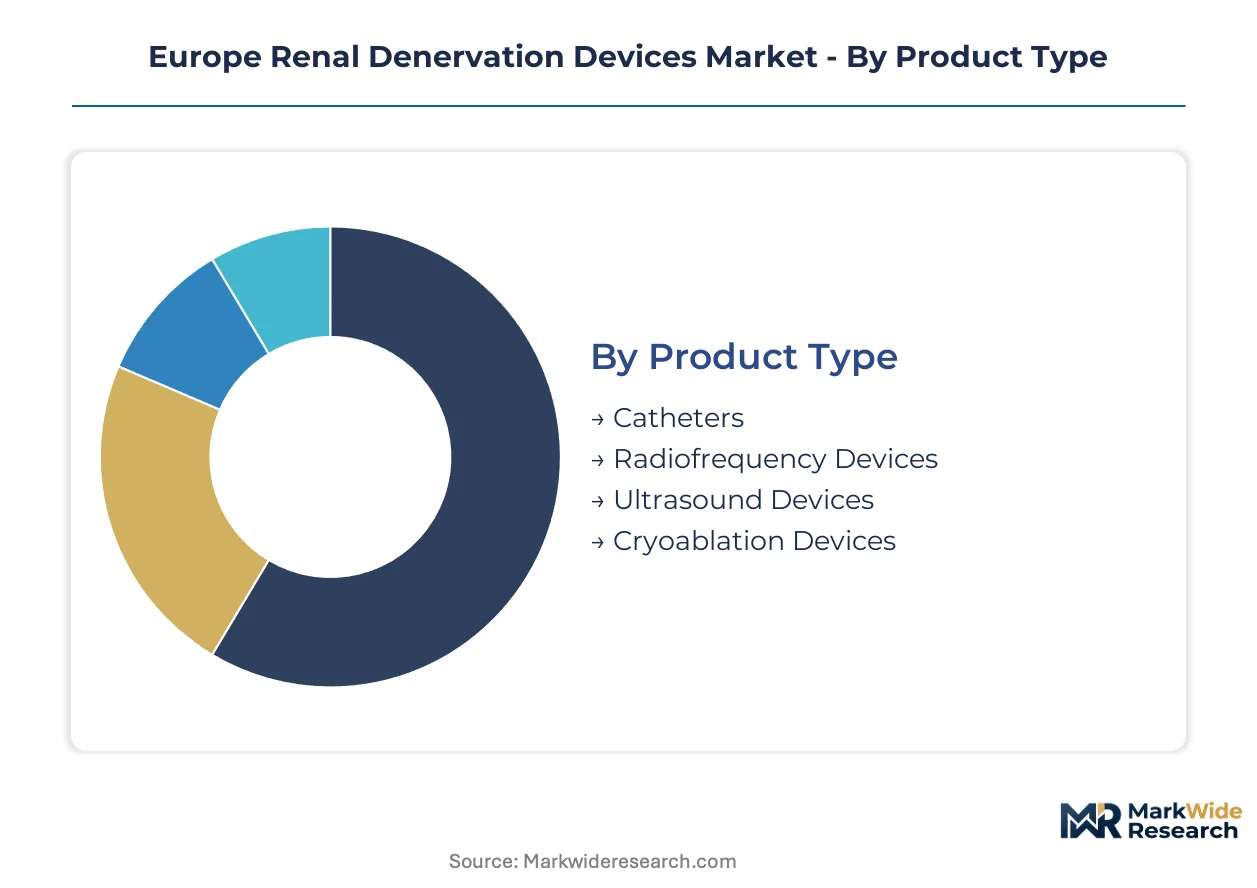
Segmentation in renal denervation devices reveals how procedural economics and clinical workflow integration shape purchasing decisions across European health systems. Device configurations range from standalone disposable catheters to capital-intensive integrated platforms, with each tier commanding distinct procurement pathways and operator training requirements.
Product Type:
Standalone disposable catheters dominate high-volume throughput environments, while integrated console-and-catheter systems anchor premium tier positioning in university hospital networks.
- Catheters:Single-use electrode-bearing catheters with steerable shafts and multi-electrode arrays enable point-by-point ablation mapping. Demand concentrates in Germany's interventional cardiology hubs where procedure volume justifies disposable-heavy operational models and inventory turnover accelerates capital recovery.
- Radiofrequency Devices:Temperature-controlled generators with impedance feedback circuits deliver precise thermal energy modulation. French and English NHS trusts favor these systems for their established reimbursement coding and predictable per-procedure costing that aligns with fixed episode payment structures.
- Ultrasound Devices:High-intensity focused ultrasound consoles with balloon-mounted transducers achieve circumferential nerve ablation without arterial heating.
- Cryoablation Devices:Nitrous oxide-based cooling systems deliver cryothermal nerve disruption at sub-zero temperatures.
Volume placements concentrate in Catheters; the faster expansion belongs to Ultrasound Devices.
End User:
Procurement authority and clinical specialization determine how device vendors structure sales engagement and service bundling across European care settings.
- Hospitals:General acute care facilities with interventional cardiology programs represent the baseline installed base for renal denervation adoption. German Klinikum networks and French CHU systems drive standardization through centralized purchasing consortia that negotiate multi-year supply agreements.
- Specialty Heart Centers:Dedicated cardiovascular institutes with electrophysiology lab infrastructure capture complex case referrals and command premium device pricing. Munich, Paris, and London clusters anchor European procedural volume and shape technology preference through influential operator networks.
- Clinics:Outpatient cardiology practices with limited fluoroscopy capacity focus on patient screening and referral coordination.
- Ambulatory Surgical Centers:Same-day procedure facilities are emerging in Netherlands and Switzerland where streamlined regulatory pathways enable outpatient renal denervation.
Installed base tilts toward Hospitals; Specialty Heart Centers are climbing the fastest as referral consolidation accelerates.
Technology:
Energy delivery modality selection directly impacts lesion depth predictability, procedure duration, and operator learning curve in European clinical practice.
- Radiofrequency Energy:Resistive heating through bipolar or multipolar electrode configurations creates thermal lesions at 50-70°C with real-time temperature monitoring. German university hospitals have standardized on temperature-controlled systems with impedance feedback, cementing this modality's reference technology status across European training curricula.
- Ultrasound Technology:Acoustic energy penetration beyond the arterial wall achieves deeper neural plexus ablation without luminal heating. Dutch and Belgian operators are adopting ultrasound platforms fastest where complex renal anatomies and prior vascular interventions elevate restenosis risk concerns.
- Laser Technology:Photonic energy delivery through fiber-optic catheter systems enables precise spatial control.
- Electrical Stimulation:Pulsed electric field ablation represents an emerging non-thermal alternative.
Radiofrequency Energy retains volume dominance; Ultrasound Technology shows the steepest expansion trajectory as penetration depth advantages convert procedural preference.
Application:
Clinical indication breadth determines addressable patient populations and shapes regulatory labeling strategy for CE marking submissions.
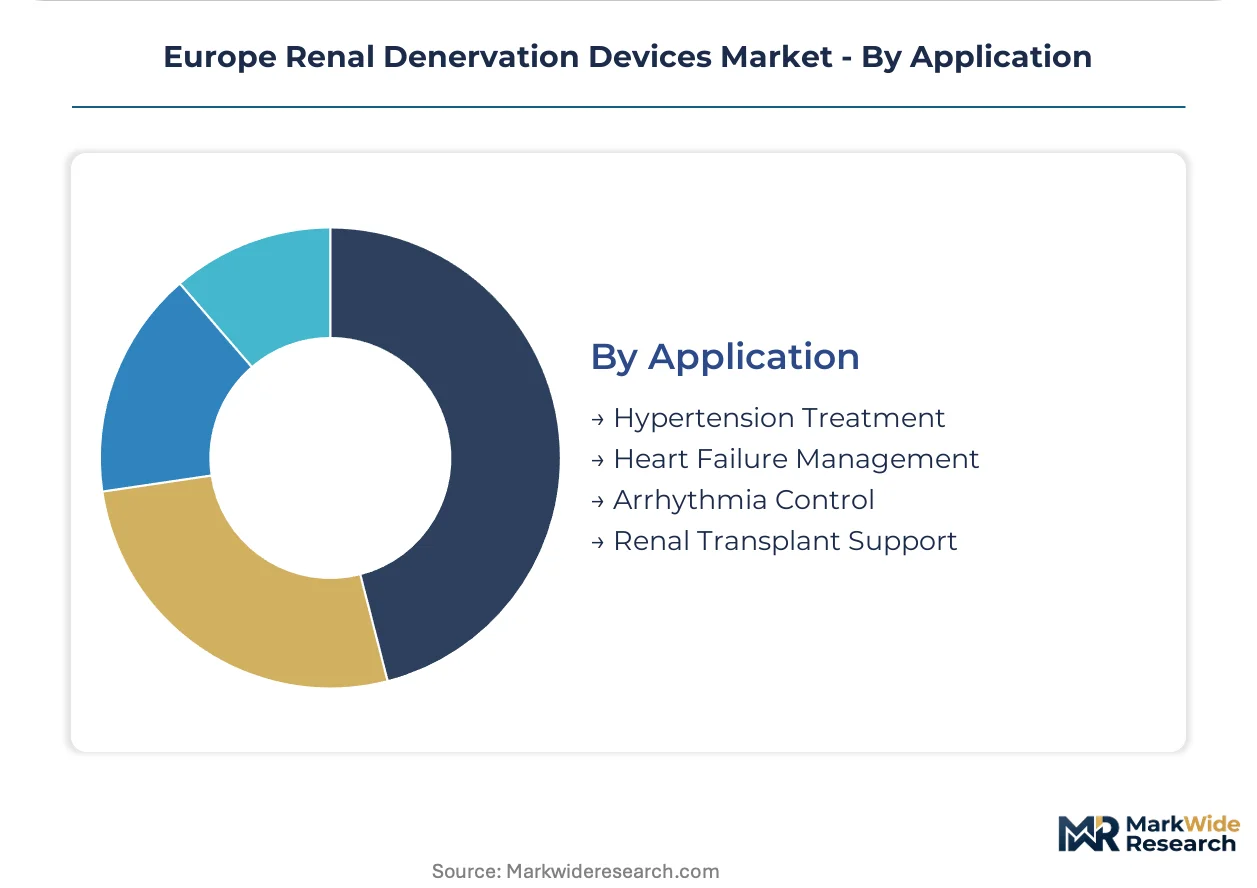
- Hypertension Treatment:Resistant hypertension in patients failing three or more antihypertensive medications constitutes the core approved indication driving commercialization. England's NICE evaluation pathways and Germany's G-BA benefit assessment processes gate reimbursement specifically for this patient population.
- Heart Failure Management:Sympathetic nervous system modulation for heart failure with preserved or reduced ejection fraction represents an expansion indication. French and Italian centers are generating registry data for this application through investigator-initiated studies outside formal labeling.
- Arrhythmia Control:Adjunctive renal denervation to reduce atrial fibrillation recurrence after catheter ablation.
- Renal Transplant Support:Blood pressure management in post-transplant patients with calcineurin inhibitor-resistant hypertension.
Procedure volume clusters in Hypertension Treatment; Heart Failure Management is gaining share fastest as sympathetic modulation mechanisms attract expanded research investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European renal denervation device demand concentrates in established interventional cardiology hubs while supply chains stretch across medtech manufacturing clusters in Germany, Ireland, and Switzerland. Production of catheter components and energy delivery systems remains concentrated near regulatory expertise centers.
Germany
German university hospitals in Munich and Heidelberg drive procedural volume through standardized radiofrequency protocols. The G-BA benefit assessment process gates reimbursement for resistant hypertension indications, forcing manufacturers to generate health economic evidence before volume scaling. Bavaria's Klinikum networks anchor centralized purchasing that shapes device standardization across federal states.
United Kingdom
NHS specialist networks in Greater Manchester and West Midlands negotiate risk-sharing contracts tying device payments to documented blood pressure outcomes. NICE technology appraisals create patchy access across integrated care systems despite regulatory approval. London's Barts Health and Guy's and St Thomas' NHS Foundation Trusts capture complex referrals that influence European operator training curricula.
France
French CHU systems in Paris and Lyon generate investigator-initiated registry data expanding renal denervation into heart failure applications. HAS evaluation timelines lag EMA approval by 12-18 months, creating reimbursement uncertainty that constrains hospital procurement. Auvergne-Rhône-Alpes clusters host catheter manufacturing facilities serving Southern European distribution networks.
Netherlands
Dutch interventional cardiologists in Amsterdam and Rotterdam adopt ultrasound platforms fastest where complex renal anatomies elevate procedural risk concerns. Streamlined outpatient regulatory pathways enable same-day renal denervation in ambulatory surgical centers. Leiden and Utrecht university medical centers anchor clinical trial infrastructure for pan-European device studies.
Poland
Polish interventional cardiology networks in Warsaw and Krakow offer first-mover positioning before reimbursement frameworks mature. Underdeveloped electrophysiology lab density constrains procedural volume despite growing resistant hypertension prevalence. EU structural funds are financing cath lab expansion in regional hospitals that will reshape Central European access patterns.
Europe Renal Denervation Devices Market Competitive Landscape
Capital-heavy integrated device manufacturers compete with specialized technology developers that outsource manufacturing to contract producers. The European market structure tilts toward consolidated control by cardiovascular giants with established MDR compliance infrastructure, while ultrasound and cryoablation specialists carve protected niches through differentiated energy modalities. Strategic archetypes include full-platform hypertension managers, single-modality technology leaders, and emerging pulsed-field innovators. Competitive positioning depends on clinical trial partnerships with German university hospitals and MDR Article 52 submission readiness.
Among the established cardiovascular technology groups, Medtronic and Boston Scientific Corporation exemplify integrated platform strategies that bundle device procurement with long-term patient monitoring services. ReCor Medical occupies a distinct position as the ultrasound technology anchor against radiofrequency-dominated competitive dynamics. Abbott Laboratories represents the diversified medtech conglomerate archetype with cross-learnings from structural heart and electrophysiology portfolios.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| ReCor Medical |
| Ablative Solutions |
| Mercator MedSystems |
| Abbott Laboratories |
| Terumo Corporation |
| Symple Surgical |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Interventional cardiologist concentration in Germany's university hospital clusters and Ireland's medtech manufacturing corridors drives labor-cost differentials that widen pricing-tier spreads between premium integrated platforms and economy catheter-only configurations. CE marking under MDR Article 52 imposes compliance cost burdens that manufacturers pass differentially across product tiers, compressing margins at the economy end while protecting premium pricing for systems with validated post-market surveillance infrastructure.
Pricing Analysis
Margin tightening in economy catheter tiers reflects MDR compliance cost absorption struggles by smaller manufacturers lacking scale efficiencies. Three-tier pricing structure across premium console-integrated systems, standard generator-catheter bundles, and economy single-use catheters stratifies by certification depth and outcome-guarantee bundling. Cost-down pressure on standard-tier configurations accelerates as NHS trusts and German Klinikum networks consolidate procurement through multi-year framework agreements. Price sensitivity concentrates in general acute hospitals with limited electrophysiology lab throughput, while Specialty Heart Centers in Munich and Paris exhibit reduced elasticity for systems with validated long-term patient tracking.
Supply Chain Analysis
Dual-sourcing requirements mandated by major European hospital purchasing consortia are reshaping supplier qualification patterns for critical catheter components. Manufacturing concentration rests on Germany for precision electrode arrays, Ireland for sterilization and final assembly, and Switzerland for high-reliability generator systems. Raw material dependencies center on nitinol tubing for steerable shafts, platinum-iridium alloys for electrode tips, and specialized balloon membranes for ultrasound transducer mounting. Single-source vulnerability in electrode array supply exposes distributors to allocation risk during manufacturing disruptions. Distribution runs through authorized dealer networks serving national hospital systems, with direct manufacturer relationships reserved for high-volume Specialty Heart Center accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's renal denervation device market sits in a technology-transition phase as ultrasound-based systems displace first-generation radiofrequency platforms that lack real-time feedback mechanisms. This displacement is compressing market space for unipolar thermal systems while rewarding integrated platforms with deeper tissue penetration capabilities.
For Market Incumbents: Lock in procedural volume at German university hospitals through exclusive clinical trial partnerships that generate registry data for MDR Article 52 compliance renewal. Secure backward integration into electrode array manufacturing to reduce single-source supply risk exposure. Channel control through dedicated renal denervation suite installations at Paris and London referral centers protects against ultrasound technology substitution. For New Entrants and Emerging Players: The premium-economy price-point gap in catheter-only configurations creates entry space for MDR-compliant manufacturers with streamlined quality systems. Poland and Czech Republic interventional cardiology networks offer the most penetrable geography before reimbursement frameworks mature. Outpatient regulatory pathway expertise in Netherlands ambulatory surgical centers provides a differentiated go-to-market angle against hospital-centric incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with ultrasound technology specialists given EMA pathway clarity on hypertension device trials and faster procedural adoption in complex renal anatomies. Acquisition target archetype: mid-scale device sponsors with existing European trial infrastructure and MDR notified body relationships. Signal to watch: NICE technology appraisal timelines converging with EMA approval schedules as inflection indicator for NHS volume scaling.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Article 52 compliance accelerates market access for class III cardiovascular devices in Germany and France. |
| Hospital System Partnership | Exclusive supply agreements with Munich and London Specialty Heart Centers anchor European procedural volume. |
| Reimbursement Strategy | G-BA and NICE health technology assessment alignment determines patient access scalability across member states. |
| Software Companion Development | Integrated ambulatory blood pressure telemetry creates recurring revenue beyond index hospitalization. |
| Manufacturing Scale-Up | Electrode array production expansion in Ireland reduces supply concentration risk for European distribution. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contracts, and EMA regulatory filings underwrites the qualitative findings on device adoption patterns. Primary interviews with interventional cardiologists, hospital purchasing committee members, biomedical engineers, and MDR regulatory consultants combined with secondary validation from CE marking notifications, clinical trial registries, and national reimbursement authority determinations. Bottom-up procedure volume estimates triangulate against top-down market sizing derived from manufacturer revenue disclosures and distributor shipment data.
Rate-of-change decomposition across the projection horizon separates volume growth from price-mix effects and technology substitution dynamics. Segmentation dimensions modeled include energy delivery modality, product configuration tier, end-user facility type, and national reimbursement status. CAGRs derive from logistic diffusion curves fitted to procedural adoption data, with technology-specific penetration rates calibrated against historical cardiovascular device analogs. Forecast inputs incorporate MDR notified body capacity constraints and health technology assessment timeline assumptions.
Underlying measurement precision varies by segment; catheter volume estimates carry tighter precision than emerging ultrasound platform projections due to reimbursement coding consolidation. Forecasts reflect documented assumptions regarding EMA regulatory pathway stability and national reimbursement convergence. Deviation in G-BA or NICE evaluation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cytology Brush Market
Medical Devices
Single-Lead ECG Monitors Market
Medical Devices
Global Concussion Market
Medical Devices
Global Medical Dynamometer Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Interface Devices Market
Medical Devices
Carpal Tunnel Release Systems Market
Medical Devices
Eye Sphere Implants Market
Medical Devices
Hyperpigmentation Treatment Devices Market
Medical Devices
Otoacoustic Emissions Hearing Screener Market
Medical Devices
Handheld Ultrasound Devices Market
Medical Devices
Ultrasonic Diathermy Market
Medical Devices
Global Nebuliser Market
Medical Devices
Asia-Pacific Smart Medical Devices Market
Medical Devices
United States Anesthesia Devices Market
Medical Devices
X-Ray Positioning Devices Market
Medical Devices
Global Soft Tissue Allografts Market