
 Alagille Syndrome Treatment Market | 2026-2036
Alagille Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Alagille Syndrome Treatment Market Analysis
Small-molecule bile acid modulation is consolidating around synthetic farnesoid X receptor agonists that displace older choleretic agents. Mirum Pharmaceuticals anchors the clinical pipeline with its specialized focus on progressive familial intrahepatic cholestasis and Alagille overlap populations. Albireo Pharma competes through sustained R&D intensity in ileal bile acid transporter inhibition. Teva Pharmaceutical Industries leverages its manufacturing scale to supply generic ursodeoxycholic acid formulations across hospital formularies.
Alagille syndrome treatment encompasses pharmacologic and nutritional interventions targeting cholestasis, pruritus, and malabsorption in patients with JAG1 or NOTCH2 mutations, with liver transplantation reserved for end-stage hepatic dysfunction. Combination therapy regimens pairing FXR agonists with fat-soluble vitamin supplementation command premium positioning due to compounded clinical benefit in growth retardation. Injectable delivery modes serve the most severe cardiac and hepatic presentations where oral bioavailability fails, while home care channels expand as stable patients transition from hospital-based infusion to subcutaneous self-administration.
FDA orphan drug designations and EMA's Committee for Orphan Medicinal Products shape development incentives and market exclusivity timelines for developers. The EU's Paediatric Regulation mandates juvenile investigation plans that extend pre-approval requirements but broaden labeled indications. Reimbursement authorities in Germany through the G-BA and England through NICE apply distinct health technology assessment thresholds for ultra-rare diseases, fragmenting commercial access strategies. Stakeholders must monitor evolving real-world evidence requirements that determine post-approval pricing sustainability across these divergent regulatory environments.
Market Dynamics
FDA's Rare Pediatric Disease Priority Review Voucher program is accelerating orphan drug development timelines for ultra-rare cholestatic disorders, compressing the pathway from clinical validation to commercial launch and reshaping investment allocation across hepatology pipelines.
Growth Catalysts
- EMA Paediatric Regulation:Mandatory juvenile investigation plans extend pre-approval requirements but broaden labeled indications, creating commercial incentives for developers to pursue early-age cohorts.
- Home care channels:Stable patients transitioning from hospital-based infusion to subcutaneous self-administration expand addressable patient populations beyond tertiary care centers.
- Synthetic FXR agonists:Next-generation farnesoid X receptor modulation displaces older choleretic agents in clinical protocols, driving protocol updates at specialized cholestasis centers.
Market Restraints
- Ultra-small patient populations:JAG1 and NOTCH2 mutation prevalence limits trial enrollment velocity and stretches development timelines across all pipeline candidates.
- Reimbursement fragmentation:Germany's G-BA and England's NICE apply divergent health technology assessment thresholds for ultra-rare diseases, complicating pan-European pricing strategies.
- Liver transplantation capacity:End-stage hepatic dysfunction management depends on scarce donor organ availability and specialized surgical infrastructure concentrated at pediatric transplant centers.
Strategic Opportunities
- Combination therapy regimens:Pairing FXR agonists with fat-soluble vitamin supplementation commands premium positioning through compounded clinical benefit in growth retardation.
- Injectable delivery modes:Severe cardiac and hepatic presentations where oral bioavailability fails represent underserved acute-care segments within hospital formularies.
- Real-world evidence frameworks:Post-approval pricing sustainability increasingly depends on structured observational studies that demonstrate long-term pediatric outcomes to payers.
Industry Challenges
- Pediatric hepatology specialist scarcity:Qualified principal investigators and clinical coordinators concentrate at a limited number of tertiary care institutions, constraining trial site activation.
- Biomarker validation timelines:Surrogate endpoints for cholestasis progression lack standardized regulatory acceptance across FDA and EMA review divisions, prolonging label negotiations.
- Multi-systemic disease management:Cardiac, renal, and skeletal manifestations require coordination across pediatric subspecialties, fragmenting care pathways and complicating endpoint selection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alagille Syndrome Treatment Market |
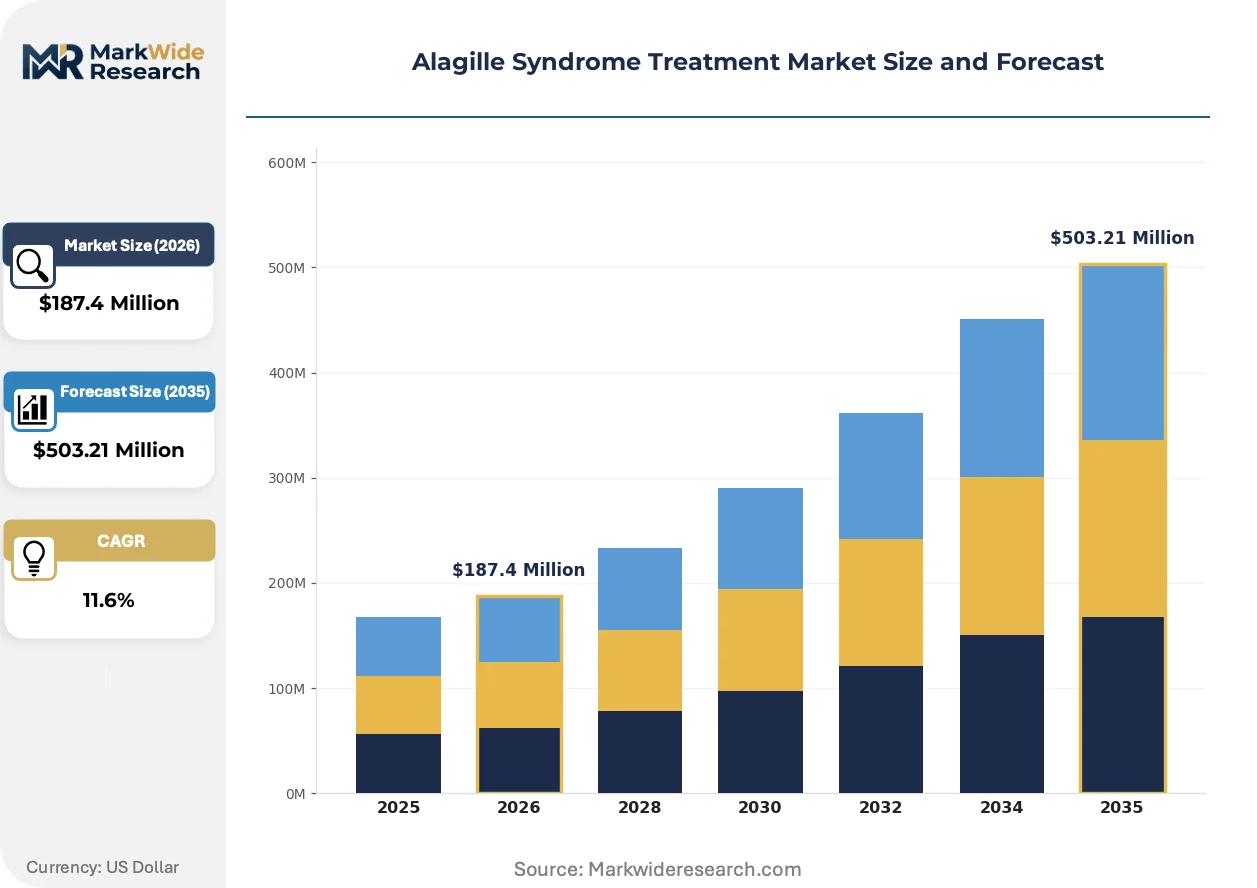
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monotherapy, Combination Therapy, Nutritional Support, Enzyme Replacement Delivery Mode: Oral, Injectable, Infusion, Transdermal End User: Hospitals, Clinics, Home Care, Research Institutions Indication: Cholestasis, Growth Retardation, Cardiac Defects, Liver Dysfunction |
| Companies Covered | Teva Pharmaceutical Industries, Pfizer, Mirum Pharmaceuticals, Fresenius Kabi, Lannett, Albireo Pharma, Novartis, Hikma Pharmaceuticals, Travere Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alagille Syndrome Treatment Market Emerging Trajectories
Orphan drug development for cholestatic disorders is pivoting from symptom management toward disease-modifying mechanisms, with synthetic biology and patient-centric delivery formats reshaping how therapies reach pediatric populations.
Subcutaneous infusion systems is decentralizing administration of bile acid modulators from hospital-based hepatology units to home care settings. Caregivers of stable Alagille patients are adopting these devices under remote monitoring protocols. This shift is decentralizing treatment access geography and reducing dependence on specialized tertiary center capacity.
REACH authorization requirements for novel pharmaceutical substances are tightening impurity thresholds for synthetic bile acid derivatives entering European supply chains. Manufacturers must demonstrate enhanced analytical characterization and toxicological profiling. Pediatric formulation developers targeting EU markets are responding by integrating quality-by-design principles earlier in process development.
Caregiver-administered therapy protocols are replacing clinic-dependent infusion schedules for patients with stable hepatic function. Home nursing services and specialty pharmacy distribution networks are capturing volume previously managed through hospital outpatient departments. This behavioral shift is most visible in United States markets with established reimbursement for home-based rare disease management.
Alagille Syndrome Treatment Market Segmentation
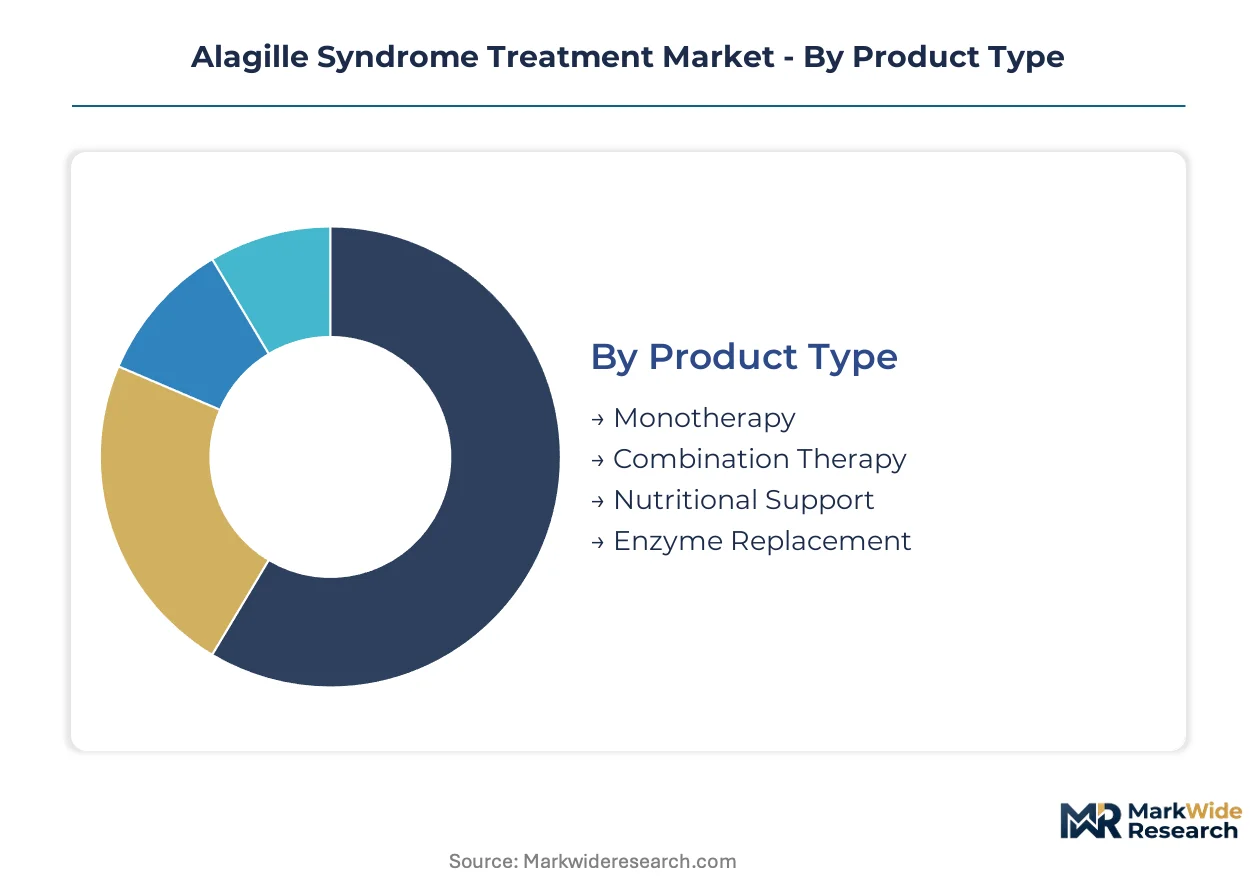
Alagille syndrome treatment segments reflect the tension between acute institutional care and decentralized chronic management. Product and delivery configurations determine whether therapies anchor in tertiary hepatology centers or migrate toward home-based administration.
Product Type:
Standalone pharmacologic interventions compete with embedded multi-agent protocols across pediatric hepatology practice patterns.
- Monotherapy:Single-agent bile acid modulation using synthetic FXR agonists delivers targeted cholestasis control. Demand clusters at specialized pediatric centers in the United States where orphan drug reimbursement pathways are established. FDA Rare Pediatric Disease designations accelerate development timelines for monotherapy candidates.
- Combination Therapy:Paired regimens of FXR agonists with fat-soluble vitamin supplementation address compounded growth retardation. German cholestasis centers and English NHS trusts increasingly favor this approach for multi-systemic presentations. EMA Paediatric Regulation mandates drive juvenile investigation plans for combination protocols.
- Nutritional Support:MCT-based formulas and micronutrient replacement manage malabsorption in JAG1 mutation patients.
- Enzyme Replacement:Pancreatic enzyme supplementation addresses exocrine insufficiency in subset populations with severe hepatic dysfunction.
Monotherapy leads volumes today; combination therapy is gaining share fastest.
Delivery Mode:
Route selection tracks disease severity gradients and caregiver capability thresholds across care settings.
- Oral:First-line administration for stable cholestasis management with preserved gastrointestinal function. Home care channels in the United States and Western Europe expand oral therapy access beyond hospital boundaries. Pediatric formulation developers optimize palatability and dosing precision for compliance in young patients.
- Injectable:Subcutaneous delivery serves severe cardiac and hepatic presentations where oral bioavailability fails. Tertiary care hospitals in France and Italy maintain injectable capacity for acute decompensation episodes. Specialty pharmacy networks capture volume through caregiver training programs.
- Infusion:Hospital-based administration reserved for end-stage hepatic dysfunction pre-transplant.
- Transdermal:Emerging patch-based systems for pruritus control in development pipelines.
Oral formulations dominate current prescribing; injectable modes are expanding most quickly into home settings.
End User:
Site of care determines reimbursement mechanics and regulatory oversight intensity for therapy delivery.
- Hospitals:Pediatric hepatology departments at tertiary centers manage complex multi-systemic presentations. United States children's hospitals anchor referral networks for JAG1 and NOTCH2 mutation confirmation. Liver transplantation evaluation and surgical intervention require institutional infrastructure.
- Home Care:Stable patients transition to subcutaneous self-administration under remote monitoring protocols. Medicare and commercial payers in the United States reimburse home nursing for rare disease management. Caregiver-administered protocols reduce dependence on specialized center capacity.
- Clinics:Community pediatric practices handle routine monitoring between tertiary visits.
- Research Institutions:Academic medical centers conduct natural history studies and interventional trials.
Hospitals retain the highest patient acuity; home care channels are climbing the fastest.
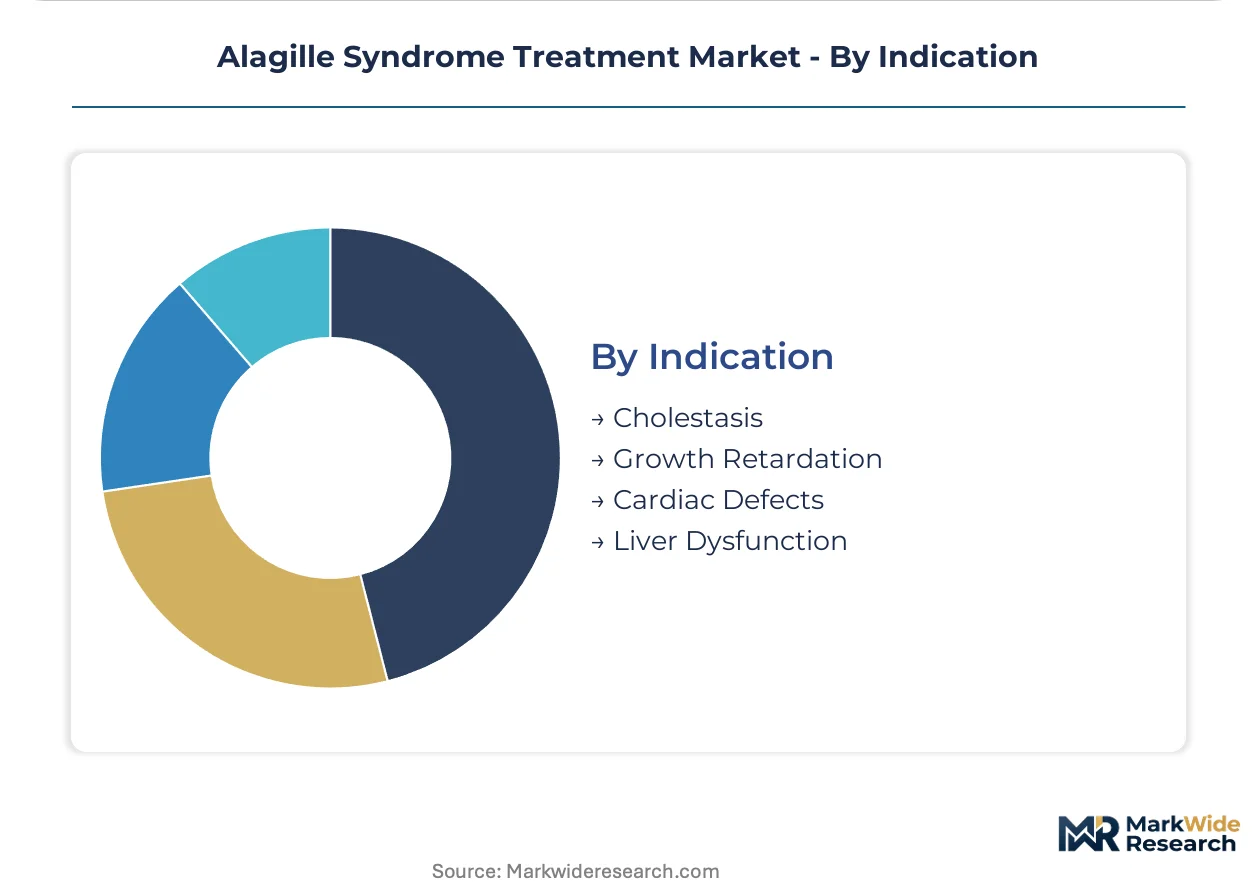
Indication:
Targeted organ manifestations drive therapy selection and endpoint design across clinical development programs.
- Cholestasis:Pruritus and bile acid accumulation represent the primary addressable pathology in Alagille syndrome. Synthetic FXR agonists displace ursodeoxycholic acid in protocols at leading United States cholestasis centers. Biomarker validation for bile acid reduction remains contested between FDA and EMA review divisions.
- Growth Retardation:Fat-soluble vitamin deficiency and malabsorption stunt linear growth in pediatric patients. German G-BA assessments weigh nutritional intervention outcomes in pediatric quality-of-life metrics. Combination therapy with vitamin supplementation commands premium positioning.
- Cardiac Defects:Peripheral pulmonary stenosis and structural anomalies require cardiology-hepatology coordination.
- Liver Dysfunction:Progressive fibrosis and portal hypertension define transplant candidacy thresholds.
Cholestasis indications anchor current treatment volumes; growth retardation protocols are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States cholestasis centers anchor therapeutic innovation for Alagille syndrome, with specialized pediatric hepatology departments driving clinical protocol development and patient referral networks.
United States
FDA Rare Pediatric Disease Priority Review Vouchers compress development timelines for ultra-rare cholestatic disorders. Children's hospitals in Philadelphia and Boston maintain the densest concentrations of JAG1 mutation specialists. Home care reimbursement pathways expand subcutaneous self-administration beyond tertiary center boundaries.
Germany
G-BA health technology assessments apply distinct valuation thresholds for ultra-rare pediatric conditions. EMA Paediatric Regulation mandates shape juvenile investigation plans for combination therapy protocols. Heidelberg and Hamburg anchor specialized cholestasis centers coordinating cardiac-hepatology care pathways.
United Kingdom
NICE applies divergent cost-effectiveness frameworks for ultra-rare diseases compared to German counterparts. NHS England's specialized commissioning funds designated pediatric hepatology networks. London and Birmingham concentrate transplant evaluation capacity and natural history study enrollment.
France
ANSM oversight aligns with EMA orphan drug incentives for pediatric cholestasis indications. National rare disease plans coordinate multi-systemic care across cardiology and hepatology subspecialties. Paris and Lyon maintain referral networks for JAG1 mutation confirmation and surgical intervention.
Japan
PMDA Sakigake designation accelerates review timelines for pediatric hepatology innovations. METI funding supports bile acid modulation research through academic-industrial partnerships. Tokyo and Osaka pediatric centers participate in international natural history registries for NOTCH2 mutation cohorts.
Alagille Syndrome Treatment Market Vendor Landscape
Global majors compete with regional champions across orphan drug development and distribution infrastructure. The vendor base stratifies between specialized biopharmaceutical developers and diversified pharmaceutical manufacturers supplying generic formulations. Three archetypes dominate: synthetic FXR agonist specialists, bile acid modulation generalists, and transplant-support service providers. Capacity expansion into home care channels and strategic partnerships with specialty pharmacy networks represent the dominant competitive vectors reshaping patient access geography.
Among specialized biopharmaceutical developers, Mirum Pharmaceuticals and Albireo Pharma occupy positions anchoring the synthetic FXR agonist and ileal bile acid transporter inhibition segments respectively. Teva Pharmaceutical Industries exemplifies the diversified manufacturer archetype, leveraging manufacturing scale across hospital formulary supply chains. These three entities represent distinct strategic postures: targeted orphan disease focus, sustained R&D intensity in specific modulation mechanisms, and operational scale in generic formulation distribution.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries |
| Pfizer |
| Mirum Pharmaceuticals |
| Fresenius Kabi |
| Lannett |
| Albireo Pharma |
| Novartis |
| Hikma Pharmaceuticals |
| Travere Therapeutics |
| Others |
Supply Flow & Price Mechanics
Synthetic bile acid precursor costs cascade through pharmaceutical manufacturing tiers into differentiated pricing structures for Alagille syndrome therapies. Hospital procurement managers at tertiary hepatology centers negotiate contract terms that reflect raw material volatility and formulation complexity premiums.
Pricing Analysis
Input-cost pass-through from specialty chemical intermediates shapes three-tier pricing structure across premium, standard, and economy levels in orphan drug markets. FDA Rare Pediatric Disease designation tiers command premium positioning against generic ursodeoxycholic acid formulations supplied by scaled manufacturers. Price differentiation hinges on clinical trial endpoint achievement and EMA Paediatric Regulation compliance status. Cost compression in standard-tier synthetic FXR agonists is intensifying because REACH authorization requirements for novel pharmaceutical substances have tightened impurity thresholds. Pediatric hepatology departments at United States children's hospitals exhibit lowest price sensitivity due to established orphan drug reimbursement pathways, while community clinics in fragmented European markets face highest budget constraint pressure.
Supply Chain Analysis
Active pharmaceutical ingredient production for bile acid modulators rests on Swiss and German specialty chemical producers with validated pediatric formulation capabilities. Synthetic farnesoid X receptor agonist precursors draw from Italian and Spanish contract manufacturing organizations with EMA-inspected facilities. Supply chain risk centers on single-source vulnerability for ultra-rare disease APIs where batch scale economics limit qualified supplier pools. Distribution runs through specialty pharmacy networks in the United States and hospital-centric procurement consortia in Germany and England.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between United States orphan drug reimbursement premiums and European manufacturing cost bases creates margin expansion opportunities for developers with cross-Atlantic regulatory capabilities.
For Market Incumbents: Extend home care channel penetration through caregiver training infrastructure and remote monitoring protocol development to defend against emerging subcutaneous infusion device specialists. Backward integration into synthetic bile acid precursor manufacturing secures supply continuity amid REACH authorization tightening. For New Entrants and Emerging Players: Capture growth retardation indication segments where combination therapy protocols with fat-soluble vitamin supplementation remain underpenetrated relative to cholestasis monotherapy. German G-BA assessment pathways offer most penetrable reimbursement entry point through pediatric quality-of-life metric alignment. For Investors and Strategic Acquirers: Asymmetric upside sits with synthetic FXR agonist developers possessing FDA Rare Pediatric Disease Priority Review Voucher eligibility and EMA Paediatric Regulation-compliant juvenile investigation plans. Watch real-world evidence framework adoption rates as inflection indicator for post-approval pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Home Care Channel Expansion | Specialty pharmacy networks capture volume previously managed through hospital outpatient departments. |
| Juvenile Investigation Plan Compliance | EMA Paediatric Regulation mandates broaden labeled indications for early-age cohort commercialization. |
| Biomarker Validation Investment | Surrogate endpoint standardization accelerates FDA and EMA label negotiation timelines. |
| Combination Therapy Development | Paired FXR agonist and vitamin regimens command premium positioning in growth retardation. |
| Real-World Evidence Framework | Structured observational studies demonstrate long-term pediatric outcomes to reimbursement authorities. |
Methodological Framework
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Drug development executives, regulatory affairs leads, formulary directors at children's hospitals, and payer access specialists provided qualitative intelligence. FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases supplied secondary benchmarks. Bottom-up patient population estimates and top-down orphan drug spending patterns underwent triangulation.
Rate-of-change decomposition across the analysis window separated volume drivers from price mix effects in the Alagille syndrome treatment forecast. Segmentation dimensions modeled include treatment line, administration route, patient age cohort, and regional regulatory cluster. CAGRs derived from epidemiology-adjusted prevalence projections and therapy penetration curve analysis. Clinical trial advancement timelines and reimbursement pathway maturation served as industry-specific forecast inputs.
Regulatory approval delays, biomarker validation setbacks, and liver transplantation capacity constraints are the dominant revision risks to projection assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Aspergillosis Treatment Market
Medical Treatment
Pelvic Organ Prolapse Repair Market
Medical Treatment
Mesotherapy Market
Medical Treatment
Angioedema Treatment Market
Medical Treatment
Scabies Treatment Market
Medical Treatment
Stereotactic Radiation Therapy Market
Medical Treatment
Hyperammonemia Treatment Market
Medical Treatment
Intensity Modulated Radiation Therapy Market
Medical Treatment
Behcet's Disease Treatment Market
Medical Treatment
Goodpasture Syndrome Treatment Market
Medical Treatment
Bloch-Sulzberger Treatment Market
Medical Treatment
Radiation Therapy Market
Medical Treatment
Phototherapy Treatment Market
Medical Treatment
Porphyria Treatment Market
Medical Treatment
Anaphylaxis Treatment Market
Medical Treatment
Anti-Fungal Treatment Market