
 Absorbable PGLA Surgical Sutures Market | 2026-2036
Absorbable PGLA Surgical Sutures Market Size, Share, and Industry Trends Forecast 2026-2036
Absorbable PGLA Surgical Sutures Market Insights
Polyglycolide is recalibrating product economics across absorbable suture portfolios as manufacturers shift from conventional catgut to synthetic glycolide-lactide copolymers with predictable tensile decay profiles. Johnson & Johnson leverages its Ethicon heritage to dominate braided PGLA production at scale across North American and European distribution networks. Medtronic sustains technology leadership through proprietary polymer extrusion systems that yield consistent molecular weight distribution in monofilament constructions. B. Braun SE anchors its European manufacturing base with backward integration into polymer resin synthesis, reducing raw material cost volatility.
Absorbable PGLA surgical sutures comprise synthetic copolymers of polyglycolic acid and polylactic acid, typically extruded as monofilament or braided constructs with absorption profiles ranging from 56 to 90 days depending on glycolide-to-lactide ratio and surface coating chemistry. Their primary commercial purpose centers on soft-tissue approximation where predictable wound support duration eliminates the need for suture removal, reducing follow-up care burden in high-volume surgical settings. Braided PGLA configurations command the largest share of current volume owing to superior knot security and handling characteristics favored by general surgeons, while barbed variants represent the fastest-expanding segment as laparoscopic and robotic platforms demand knotless closure efficiency. Hospitals absorb the dominant share of procurement value given case volume concentration, though ambulatory surgical centers are gaining share as outpatient hernia repair and orthopedic arthroscopy migrate from inpatient settings.
FDA 510(k) clearance pathways and EMA Medical Device Regulation conformity assessments govern market access for new PGLA suture introductions, with both agencies intensifying scrutiny of degradation-byproduct cytotoxicity documentation. ISO 10993 biocompatibility testing series and USP absorbable suture monograph standards establish baseline material qualification thresholds that differentiate premium-tier suppliers from commodity entrants. Stakeholders must monitor evolving sterilization validation requirements for copolymer sutures, as gamma irradiation dose thresholds and ethylene oxide residual limits tighten under revised international standards, directly impacting production economics and supplier qualification timelines.
Market Dynamics
Hospital procurement consolidation is compressing supplier margins across absorbable suture portfolios as integrated delivery networks demand multi-year volume commitments in exchange for sole-source contracts. This buyer concentration is forcing manufacturers to restructure pricing architectures and absorb sterilization validation costs previously passed through to accounts.
Growth Catalysts
- EMA Medical Device Regulation:Stricter biocompatibility documentation requirements under MDR Annex I are filtering out low-grade competitors and expanding addressable market share for validated premium suppliers.
- Outpatient migration:Ambulatory surgical centers in Germany and Japan are converting hernia repair and arthroscopy cases to same-day discharge protocols, generating incremental suture consumption outside traditional hospital purchasing.
- Barbed monofilament extrusion:Knotless closure technology is reducing operative time in laparoscopic platforms, driving preference shifts among robotic surgery adopters in high-volume United States health systems.
Market Restraints
- Glycolide monomer price volatility:Petroleum-derived feedstock costs for polyglycolic acid resin synthesis fluctuate with crude oil benchmarks, compressing copolymer margin structures for non-integrated manufacturers.
- Gamma irradiation capacity concentration:Sterilization service providers cluster in the United States Midwest and Rhine-Ruhr corridor, creating geographic bottlenecks that extend lead times for Asia-Pacific distributors.
- Catgut residual demand:Certain emerging market hospital systems continue specifying natural absorbable sutures for cost-sensitive procedures, limiting synthetic conversion rates in price-elastic procurement environments.
Strategic Opportunities
- India's CDSCO fast-track pathway:Streamlined 510(k)-equivalent clearance for absorbable polymer devices is lowering regulatory entry costs for manufacturers targeting South Asia's expanding private hospital sector.
- Veterinary orthopedics:Companion animal surgery volumes in Japan and Germany are creating adjacent demand for smaller-gauge PGLA constructs with modified absorption profiles.
- Ethylene oxide alternative validation:Emerging e-beam sterilization protocols for synthetic absorbables offer compliance arbitrage as EPA residual gas limits tighten for traditional EtO facilities.
Industry Challenges
- Polymer extrusion engineering talent:Specialized expertise in molecular weight distribution control for medical-grade copolymers concentrates at legacy Ethicon and B. Braun facilities, constraining new entrant scale-up velocity.
- ISO 10993-18 chemical characterization:Degradation byproduct identification studies for novel glycolide-lactide ratios require 18-24 month validation cycles, delaying product line extensions.
- Legacy ERP integration:Hospital supply chain systems in Japan retain proprietary EDI protocols that complicate automated replenishment implementation for multinational suture suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Absorbable PGLA Surgical Sutures Market |
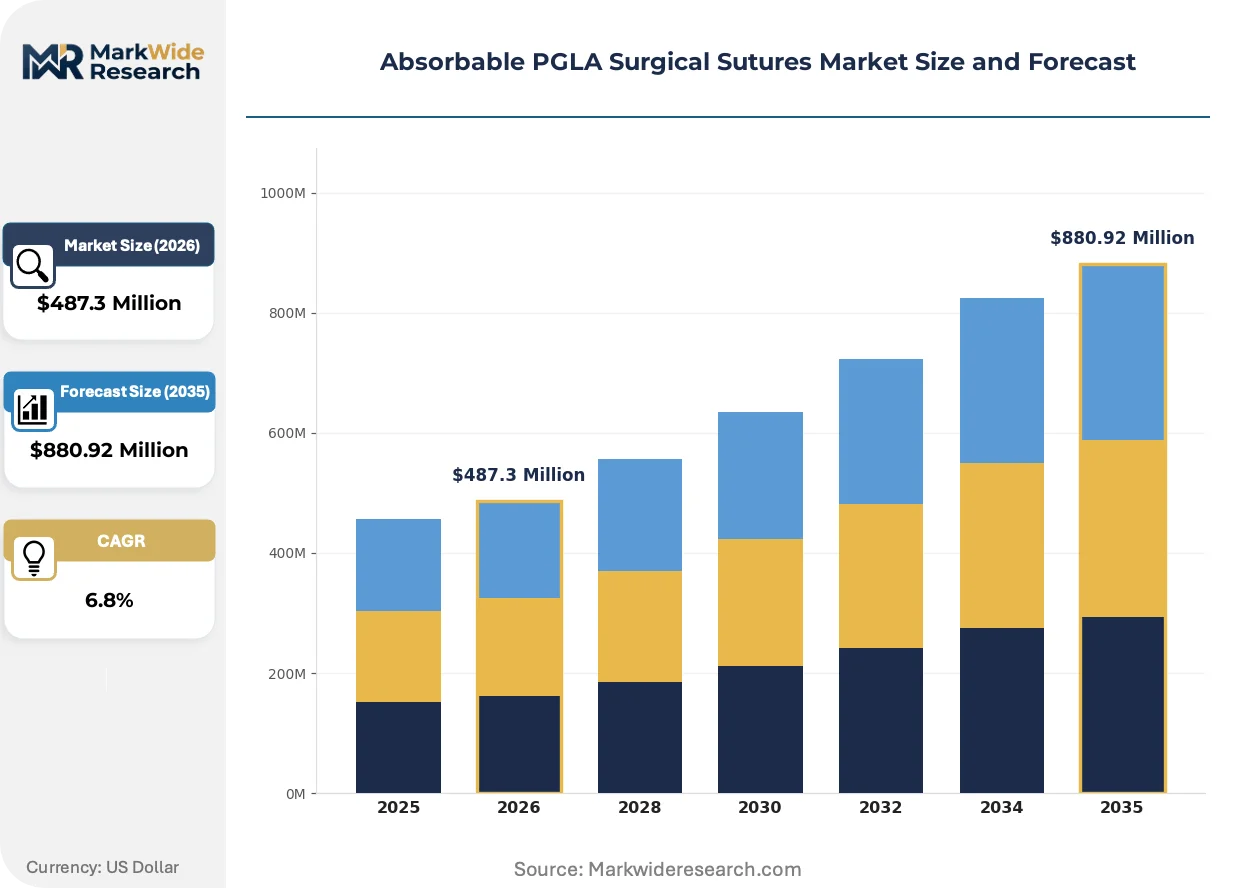
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monofilament, Braided, Coated, Barbed Application: General Surgery, Orthopedics, Gynecology, Cardiovascular End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Academic Medical Centers Packaging Type: Sterile Pouches, Blister Packs, Bulk Packs, Coil Packs |
| Companies Covered | Johnson & Johnson, Medtronic, B. Braun SE, Teleflex Incorporated, Advanced Medical Solutions Group, Healthium Medtech, Smith & Nephew, DemeTECH Corporation, Corza Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Absorbable PGLA Surgical Sutures Market Trends and Innovations
Absorbable suture technology is fragmenting into application-specific constructs as manufacturers abandon universal product platforms in favor of procedure-optimized designs. This specialization is rewriting competitive boundaries between monofilament and braided architectures.
Antimicrobial surface coating chemistry is modularizing PGLA suture portfolios through triclosan and chlorhexidine integration that suppresses surgical site infection rates in colorectal and bariatric procedures. United States academic medical centers are piloting these constructs in bundled payment environments where readmission penalties concentrate buyer attention on infection prevention. The technology is modularizing supplier R&D roadmaps around indication-specific efficacy claims rather than generic tensile performance benchmarks.
Japan's PMDA revised its QMS ministerial ordinance in 2023, mandating real-time adverse event reporting for Class III absorbable devices with novel degradation profiles. Manufacturers must now maintain domestic pharmacovigilance infrastructure as a condition of market access, elevating compliance costs for European and United States exporters. Small-gauge ophthalmic and cardiovascular suture lines face the steepest documentation burden under these tightened post-market surveillance protocols.
Hospital buying committees are consolidating suture procurement into single-source agreements that bundle absorbable and non-absorbable portfolios under multi-year performance contracts. Integrated delivery networks in Germany and the United States are displacing traditional distributor intermediaries with direct manufacturer relationships that exchange volume commitments for price transparency and consignment inventory terms. This channel restructuring is most visible in orthopedic and general surgery service lines where standardized procedure kits predominate.
Absorbable PGLA Surgical Sutures Market Segmentation
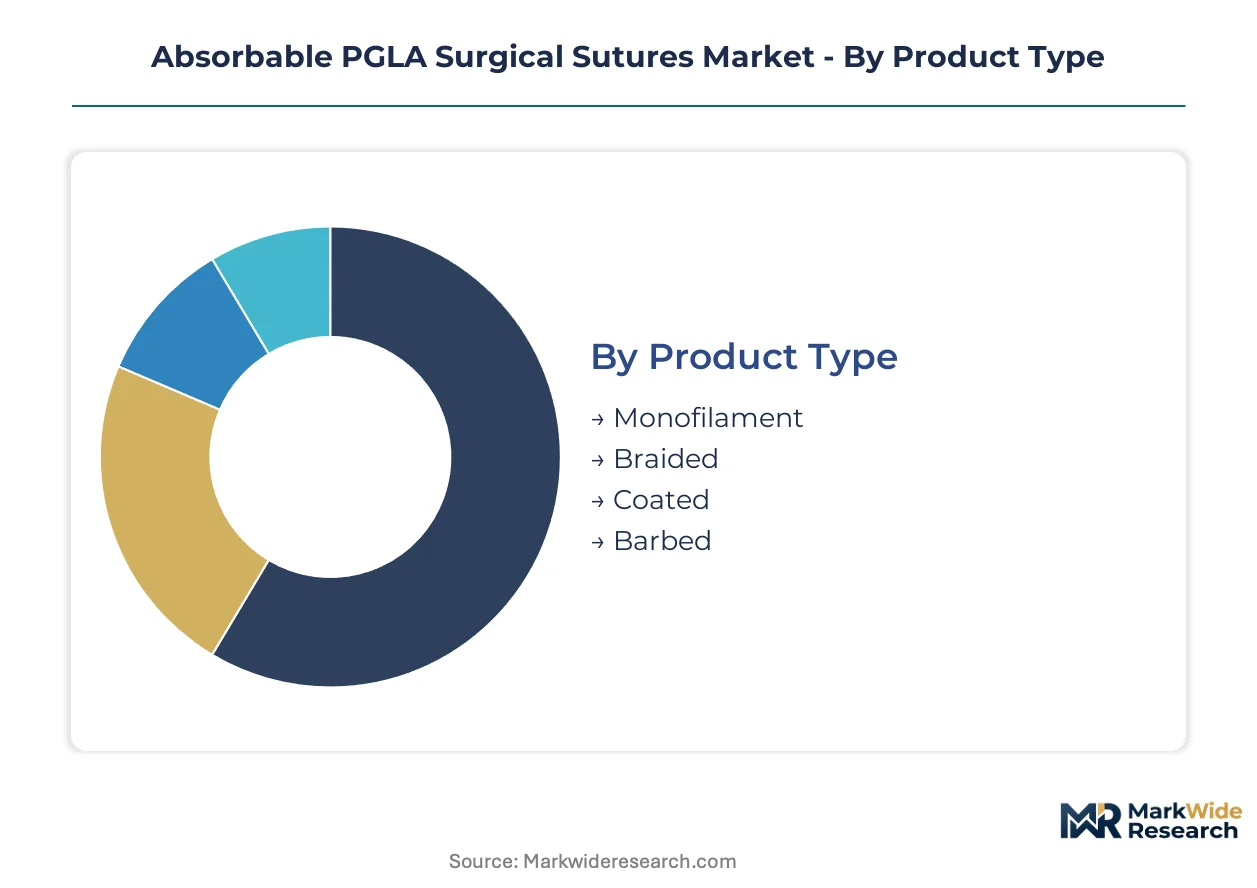
PGLA suture portfolios fragment across four commercial axes. Product architecture determines handling characteristics and absorption kinetics. Application focus shapes regulatory pathways and reimbursement codes. End-user concentration dictates procurement leverage and inventory terms. Packaging format influences sterilization validation costs and shelf-life economics.
Product Type:
Upgrade cycles from catgut to synthetic absorbables are accelerating as surgeons recalibrate preferences around knot security versus tissue drag.
- Braided:Multifilament glycolide-lactide constructs with interwoven fiber architecture deliver superior knot security and pliability. General surgery departments in United States hospital systems specify braided configurations for soft-tissue approximation where handling precision reduces operative time.
- Barbed:Monofilament extrusions with bidirectional surface projections enable knotless wound closure. Laparoscopic surgery adopters in Germany's university hospitals are converting to barbed variants as robotic platforms demand efficiency gains in minimally invasive procedures.
- Monofilament:Single-strand copolymer with smooth surface reduces tissue trauma and bacterial adherence. Cardiovascular and ophthalmic microsurgery applications favor this architecture for delicate anatomical sites.
- Coated:Surface-modified braids with caprolactone or calcium stearate lubricants improve suture passage through dense fascia. Orthopedic soft-tissue repair protocols increasingly specify coated constructs for tendon and ligament approximation.
Braided configurations sit at the top of the volume ranking, with barbed variants climbing the fastest.
Application:
Procedure reimbursement differentials are concentrating manufacturer R&D investment toward service lines with favorable episode-based payment structures.
- General Surgery:Abdominal wall closure, bowel anastomosis, and skin approximation account for the largest procedural volume. United States integrated delivery networks bundle absorbable suture consumption into standardized laparotomy and hernia repair kits, compressing supplier margins through volume commitments.
- Orthopedics:Soft-tissue reattachment to bone and tendon repair procedures require high tensile strength retention. Sports medicine specialists in Japan's private hospital sector are specifying PGLA constructs with extended absorption profiles for rotator cuff and ACL reconstruction protocols.
- Gynecology:Hysterectomy, myomectomy, and pelvic floor repair applications demand fine-gauge sutures with minimal tissue reactivity. Outpatient migration of gynecologic procedures is expanding ambulatory surgical center procurement outside traditional hospital supply chains.
- Cardiovascular:Vascular anastomosis and cardiac valve repair require specialized monofilament constructs with precise diameter tolerances. EMA MDR Annex I biocompatibility documentation requirements impose steep validation costs for cardiovascular-grade product lines.
General surgery dominates current volume, with orthopedics gaining share fastest in premium-tier pricing tiers.
End User:
Customer concentration patterns are restructuring channel economics as procurement authority migrates from individual surgeons to centralized supply committees.
- Hospitals:Integrated delivery networks and public hospital systems absorb the dominant share of procurement value. Multi-year sole-source contracts in Germany's Rhine-Ruhr hospital clusters exchange volume guarantees for consignment inventory terms and price transparency mechanisms.
- Ambulatory Surgical Centers:Same-day discharge protocols for hernia repair and arthroscopy are generating incremental consumption outside inpatient settings. United States Medicare ASC payment rate adjustments are accelerating site-of-service migration for qualifying procedures.
- Specialty Clinics:Dermatologic and plastic surgery practices maintain direct purchasing relationships for cosmetic and reconstructive applications. Smaller order quantities and premium product specifications sustain higher per-unit pricing outside consolidated procurement frameworks.
- Academic Medical Centers:Teaching hospitals with residency programs drive early adoption of novel constructs through investigator-initiated trials. Pilot programs for antimicrobial-coated sutures in bundled payment environments concentrate in United States academic institutions with readmission penalty exposure.
Hospitals retain volume leadership, with ambulatory surgical centers expanding most quickly as outpatient migration accelerates.
Packaging Type:
Sterilization validation costs and shelf-life requirements are forcing packaging format decisions that ripple through distribution economics.
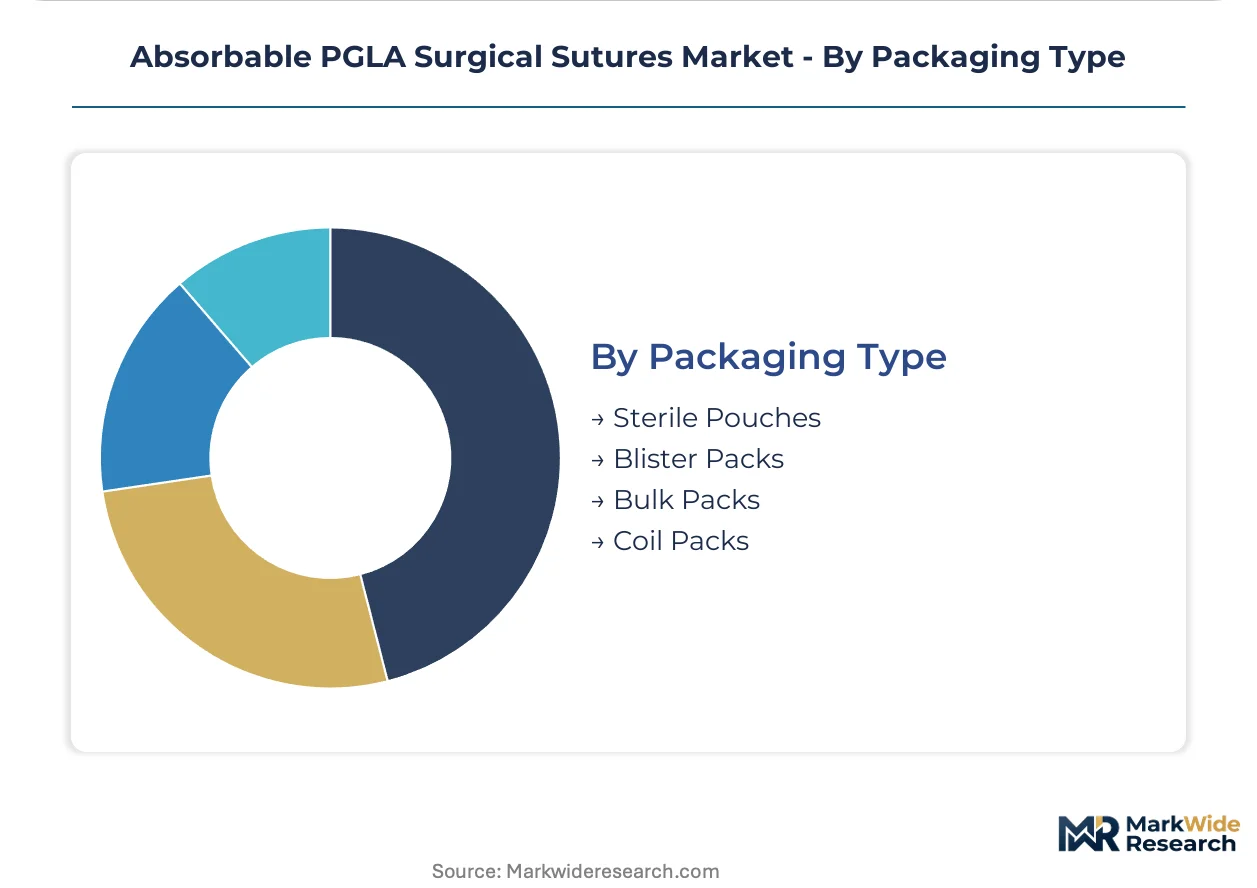
- Sterile Pouches:Individual Tyvek-laminated packages with ethylene oxide or gamma irradiation certification support aseptic technique in operating rooms. United States ASCs prefer unit-of-use packaging to minimize waste in high-turnover procedural settings.
- Blister Packs:Thermoformed trays with peelable lidding organize multiple suture sizes and needle configurations into procedure-matched sets. Orthopedic and general surgery kit manufacturers specify blister formats for standardized instrument trays.
- Bulk Packs:Large-quantity containers with validated sterile barriers serve high-volume hospital systems with automated dispensing systems. Cost-per-unit advantages must offset inventory carrying costs and expiration risk in slow-moving gauge specifications.
- Coil Packs:Continuous suture lengths on spools or reels support custom cutting for specialized applications. Veterinary and research laboratory procurement favors coil formats where standardized packaging does not match procedural requirements.
Sterile pouches command the highest unit volume, with blister packs gaining traction fastest in kit-integrated procurement models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor anchors European absorbable suture manufacturing with concentrated polymer extrusion capacity serving hospital networks across Germany and neighboring markets.
United States
Aging demographics and robotic surgery platform proliferation drive procedural volumes in abdominal and orthopedic applications. FDA 510(k) clearance pathways govern market entry for novel glycolide-lactide copolymer constructs. The Minneapolis-St. Paul corridor hosts sterilization service clusters that process sutures for distribution throughout Midwestern integrated delivery networks.
Germany
University hospital systems in Bavaria and North Rhine-Westphalia specify premium-tier braided configurations for laparoscopic hernia repair protocols. EMA Medical Device Regulation Annex I biocompatibility documentation requirements filter supplier qualification. The Tuttlingen surgical instrument cluster integrates suture procurement into standardized procedure kits for export throughout Europe.
Japan
PMDA's 2023 QMS ministerial ordinance revision mandates real-time adverse event reporting for Class III absorbable devices with novel degradation profiles. Private hospital chains in Tokyo and Osaka convert outpatient arthroscopy cases to same-day discharge protocols. The Kansai region's medical device distribution infrastructure channels PGLA sutures to aging population centers across western Honshu.
India
CDSCO fast-track clearance pathways lower regulatory entry costs for manufacturers targeting South Asia's expanding private hospital sector. Maharashtra and Gujarat host contract manufacturing facilities supplying braided absorbables to domestic and export markets. Mumbai's corporate hospital chains drive specification upgrades from catgut to synthetic absorbables in cost-sensitive procurement environments.
United Kingdom
NHS supply chain consolidation concentrates procurement authority at integrated care system level, compressing supplier margins through multi-year volume commitments. MHRA post-Brexit regulatory autonomy maintains alignment with EMA MDR standards for absorbable polymer biocompatibility. London's academic medical centers pilot antimicrobial-coated sutures in bundled payment environments with readmission penalty exposure.
Absorbable PGLA Surgical Sutures Market Competitive Landscape
Backward integration into polymer resin synthesis dominates the current landscape as manufacturers seek captive supply of glycolide monomer to buffer petroleum feedstock volatility. The vendor base concentrates around three legacy medical device conglomerates with decades of suture manufacturing heritage, supplemented by regional specialists and emerging contract manufacturers. Two strategic archetypes prevail: diversified multinational health care suppliers with full surgical portfolio breadth, and focused suture specialists leveraging application-specific expertise. Competitive intensity centers on sterilization validation partnerships and direct hospital contracting relationships that displace traditional distributor intermediaries.
Within the diversified multinational tier, Johnson & Johnson, Medtronic, and B. Braun SE exemplify contrasting geographic and structural positioning. Johnson & Johnson's New Jersey-based heritage anchors North American distribution dominance through established surgeon training relationships and hospital system sole-source agreements. Medtronic's Irish-registered, operationally dispersed structure reflects the tax and supply chain optimization strategies common among large-cap health care device manufacturers. B. Braun SE's German GmbH configuration represents European-centric manufacturing with backward integration into polymer chemistry that reduces raw material cost volatility exposure.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Medtronic |
| B. Braun SE |
| Teleflex Incorporated |
| Advanced Medical Solutions Group |
| Healthium Medtech |
| Smith & Nephew |
| DemeTECH Corporation |
| Corza Medical |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement consolidation across United States integrated delivery networks and Germany's Rhine-Ruhr hospital clusters is forcing manufacturers to absorb sterilization validation costs and restructure pricing architectures around multi-year volume commitments, compressing margins for non-integrated suppliers while rewarding backward-integrated producers with captive glycolide monomer supply.
Pricing Analysis
Petroleum-derived glycolide monomer costs pass through directly to copolymer pricing, creating margin volatility for manufacturers without in-house resin synthesis. Three-tier pricing structure across premium, standard, and economy levels differentiates by FDA 510(k) clearance tier and ISO 10993 documentation depth. Cost compression in economy tiers is intensifying because catgut residual demand in emerging markets limits synthetic conversion rates. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare reimbursement constraints, while cardiovascular-grade monofilament purchasers show lowest sensitivity given procedural criticality.
Supply Chain Analysis
Regional distribution centers in Minneapolis-St. Paul and the Rhine-Ruhr corridor operate hub-and-spoke patterns that channel sterilized sutures to hospital networks across North America and Europe. Manufacturing concentrates in the United States, Germany, and Japan, with polymer extrusion capacity anchored at legacy facilities. Raw material supply draws from petroleum feedstock derivatives, medical-grade polymer resins, and specialized coating chemistries. Single-source vulnerability in gamma irradiation capacity creates geographic bottlenecks extending lead times for Asia-Pacific distributors. Distribution runs through direct manufacturer relationships displacing traditional distributor intermediaries in consolidated procurement environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The absorbable PGLA surgical sutures market reads as a late-cycle quality story where EMA MDR Annex I biocompatibility documentation requirements and FDA tightening on degradation-byproduct cytotoxicity are filtering demand toward premium-tier suppliers with validated sterilization protocols and complete regulatory dossiers.
For Market Incumbents: Deepen backward integration into polymer resin synthesis to buffer petroleum feedstock volatility exposure, while consolidating sterilization validation partnerships with regional service clusters to defend against emerging entrants lacking gamma irradiation capacity access. Lock in multi-year sole-source contracts with integrated delivery networks before CDSCO fast-track pathways enable low-cost competitors to penetrate price-sensitive procurement environments. For New Entrants and Emerging Players: Capture India's CDSCO fast-track pathway for streamlined 510(k)-equivalent clearance, targeting Maharashtra and Gujarat private hospital chains upgrading from catgut to synthetic absorbables. Veterinary orthopedics in Japan and Germany offers adjacent white-space with modified absorption profile requirements and lower regulatory barriers than human cardiovascular applications. Partner with established sterilization service providers to circumvent geographic capacity concentration bottlenecks. For Investors and Strategic Acquirers: Asymmetric upside sits with contract manufacturers possessing polymer extrusion engineering talent and existing ISO 10993-18 chemical characterization capabilities, positioned for acquisition by multinationals seeking regional manufacturing footprints. Long-term viability hinges on compliance infrastructure for real-time adverse event reporting under Japan's PMDA QMS ministerial ordinance revisions. Monitor sterilization validation backlog durations as an inflection indicator for supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Annex I Compliance Investment | Biocompatibility documentation depth filters low-grade competitors from premium hospital procurement pools. |
| Gamma Irradiation Capacity Expansion | Regional sterilization bottlenecks in Asia-Pacific create arbitrage for Midwestern and Rhine-Ruhr service providers. |
| Antimicrobial Coating R&D Program | Triclosan and chlorhexidine integration targets bundled payment readmission penalties in United States academic centers. |
| Barbed Monofilament Extrusion Scale-Up | Knotless closure efficiency aligns with robotic surgery platform proliferation in German university hospitals. |
| Direct Hospital System Partnership | Consignment inventory terms and price transparency displace distributor intermediaries in orthopedic kit integration. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committee chairs, biomedical engineers, GPO contracts managers, and sterilization service operations leads with secondary validation against FDA 510(k) filings, EMA MDR submissions, hospital procurement databases, and CMS Medicare ASC payment data. Bottom-up suture consumption modeling by procedure type and end-user channel triangulated against top-down manufacturer revenue segmentation.
Historical reference periods anchored the forecast window to procedural volume trends across general surgery, orthopedics, and cardiovascular service lines. The analytical framework modeled product architecture, application focus, end-user concentration, and packaging format dimensions throughout the forecast period. CAGRs derived from procedure volume elasticity to aging demographic shifts, robotic surgery platform penetration rates, and outpatient migration velocity in ambulatory surgical centers.
Regulatory timeline delays, petroleum feedstock price shocks, and sterilization capacity constraints are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Pregnancy Detection Kits Market
Medical Devices
Allergic Rhinitis Treatment Device Market
Medical Devices
Tumour Ablation Devices Market
Medical Devices
Intra-Abdominal Pressure Measurement Devices (IPMD) Market
Medical Devices
Contact Cast Systems Market
Medical Devices
Ultrasound Skin Tightening Devices Market
Medical Devices
Collateral Ligament Stabilizer System Market
Medical Devices
Asia-Pacific Refractive Surgery Devices Market
Medical Devices
Rib Fracture Repair Systems Market
Medical Devices
Oxygen Conservers Market
Medical Devices
Electrophysiology Ablation Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Pelvic Floor Electrical Stimulation Devices Market
Medical Devices
Bone Conduction Hearing Devices Market
Medical Devices
Implantable Medical Devices Market
Medical Devices
Vortex Mixer Market