
 Global Animal Intestinal Health Market | 2026-2036
Global Animal Intestinal Health Market Size, Share, and Industry Trends Forecast 2026-2036
Global Animal Intestinal Health Market Foresight
EU Regulation 2019/6 on veterinary medicinal products is restructuring the cost-of-entry calculus for additive suppliers serving European livestock operations. Cargill leverages its integrated supply chain from strain development to feed formulation to sustain competitive positioning across multiple geographies. Kemin Industries specializes in precision-delivery technologies for organic acids and essential oils, while Chr. Hansen Holding A/S dominates microbial strain banking and fermentation scale-up for probiotic applications.
Animal intestinal health encompasses the maintenance of optimal gut microbiome composition, mucosal barrier integrity, and digestive enzyme activity through exogenous supplementation of live microorganisms, fermentable substrates, or bioactive compounds, typically administered via feed or drinking water at concentrations ranging from 10^6 to 10^9 CFU per gram for probiotics. Probiotics occupy the largest value share as established Lactobacillus and Bacillus formulations command premium pricing in poultry and swine diets, while enzymes represent the fastest-expanding category as phytase and non-starch polysaccharide hydrolases displace inorganic phosphate and reduce feed conversion ratios. Prebiotics and organic acids attract growing investment from feed manufacturers seeking dual-function solutions that simultaneously support gut flora balance and acidification.
The US FDA Center for Veterinary Medicine enforces feed additive approval pathways under the Food Additive Petition process, while China's Ministry of Agriculture and Rural Affairs maintains the national feed additive catalog that determines market access for probiotic and enzyme products. The EU F-Gas Regulation and REACH framework indirectly shape ingredient sourcing by restricting certain chemical carriers and processing aids used in additive manufacturing. Stakeholders must monitor evolving regulatory divergence between jurisdictions as divergent approval timelines and residue testing protocols determine which formulation technologies achieve commercial scale.
Market Dynamics
Antibiotic growth promoter bans under EU Regulation 2019/6 and US FDA guidance are forcing livestock producers to rebuild intestinal health management around microbial feed additives, enzymes, and organic acids.
Growth Catalysts
- EU veterinary medicinal product frameworks:The 2022 enforcement of complete antibiotic growth promoter prohibition in European swine and poultry operations creates immediate substitution demand for probiotic and enzyme formulations.
- Feed conversion ratio optimization:Phytase and non-starch polysaccharide hydrolases enable producers to reduce inorganic phosphate inclusion while maintaining growth performance, cutting input costs per kilogram of live weight.
- China's national feed additive catalog expansion:Ministry of Agriculture and Rural Affairs approvals for novel microbial strains accelerate domestic production capacity and reduce import dependency for enzyme and probiotic products.
Market Restraints
- Strain banking concentration:Commercial-scale probiotic production depends on access to characterized microbial libraries held by a limited set of fermentation technology specialists, creating supply bottleneck risk.
- Fermentation substrate cost volatility:Molasses, whey permeate, and soy-based growth media face price swings tied to dairy and oilseed commodity markets, compressing additive manufacturer margins.
- REACH chemical carrier restrictions:The EU framework limits certain processing aids and encapsulation materials used in precision-delivery organic acid formulations, forcing reformulation investments.
Strategic Opportunities
- Precision fermentation scale-up:Synthetic biology-enabled strain engineering combined with continuous fermentation technology promises tenfold productivity gains in Bacillus spore production.
- Brazilian integrated poultry operations:Underpenetrated adoption of multi-enzyme complexes in Latin America's largest broiler production market offers volume expansion potential for suppliers with local manufacturing.
- Postbiotic metabolite commercialization:Cell-free supernatants containing short-chain fatty acids and bacteriocins bypass live culture stability challenges while delivering targeted gut modulation benefits.
Industry Challenges
- Fermentation scale-up talent scarcity:Industrial microbiologists capable of translating laboratory strain performance to 100,000+ liter bioreactor consistency command premium compensation and limited availability.
- Dual regulatory dossier requirements:Suppliers seeking simultaneous EU EFSA and US FDA approvals face divergent efficacy demonstration protocols and residue testing standards, extending time-to-market.
- Legacy feed mill equipment compatibility:Heat-labile probiotic formulations require pelleting temperature modifications or post-pelleting liquid application systems that many existing facilities lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Animal Intestinal Health Market |
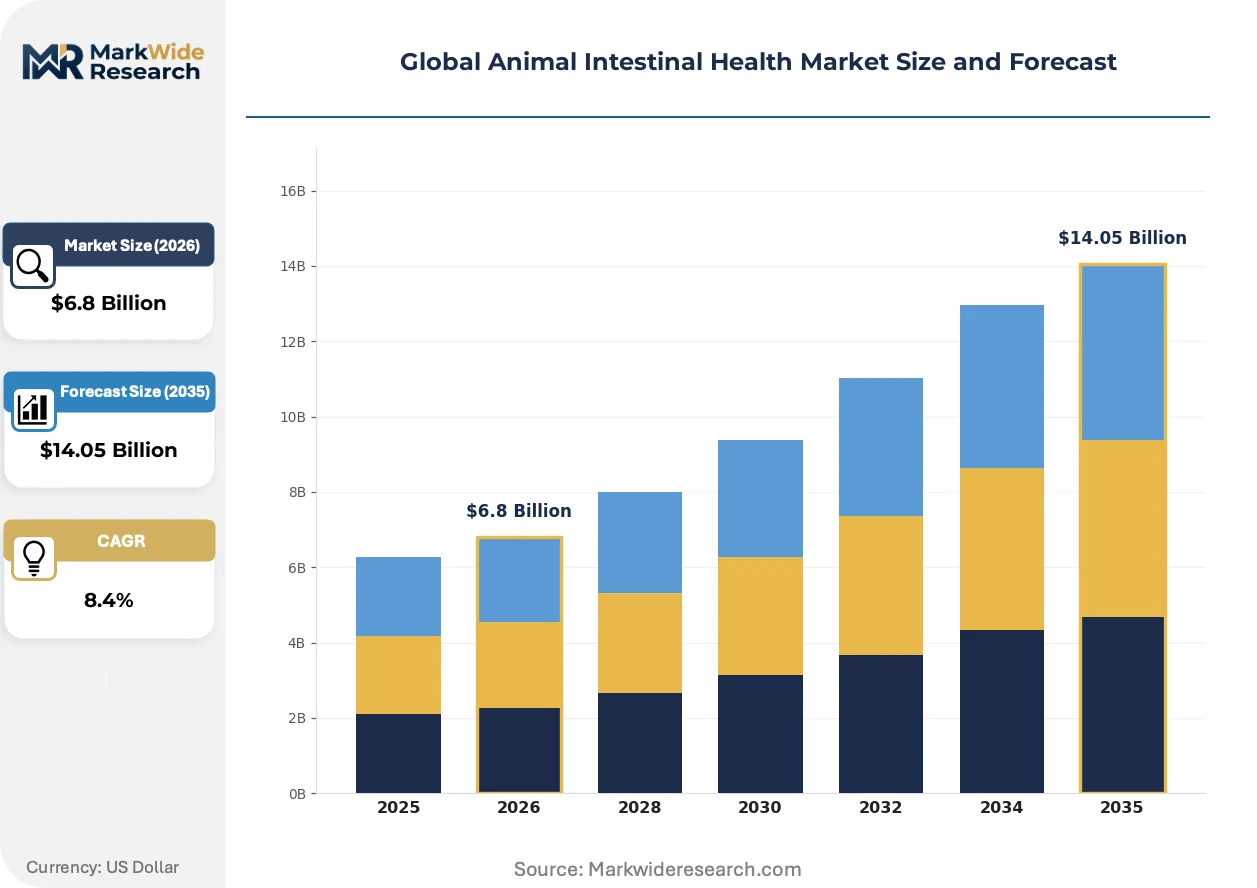
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
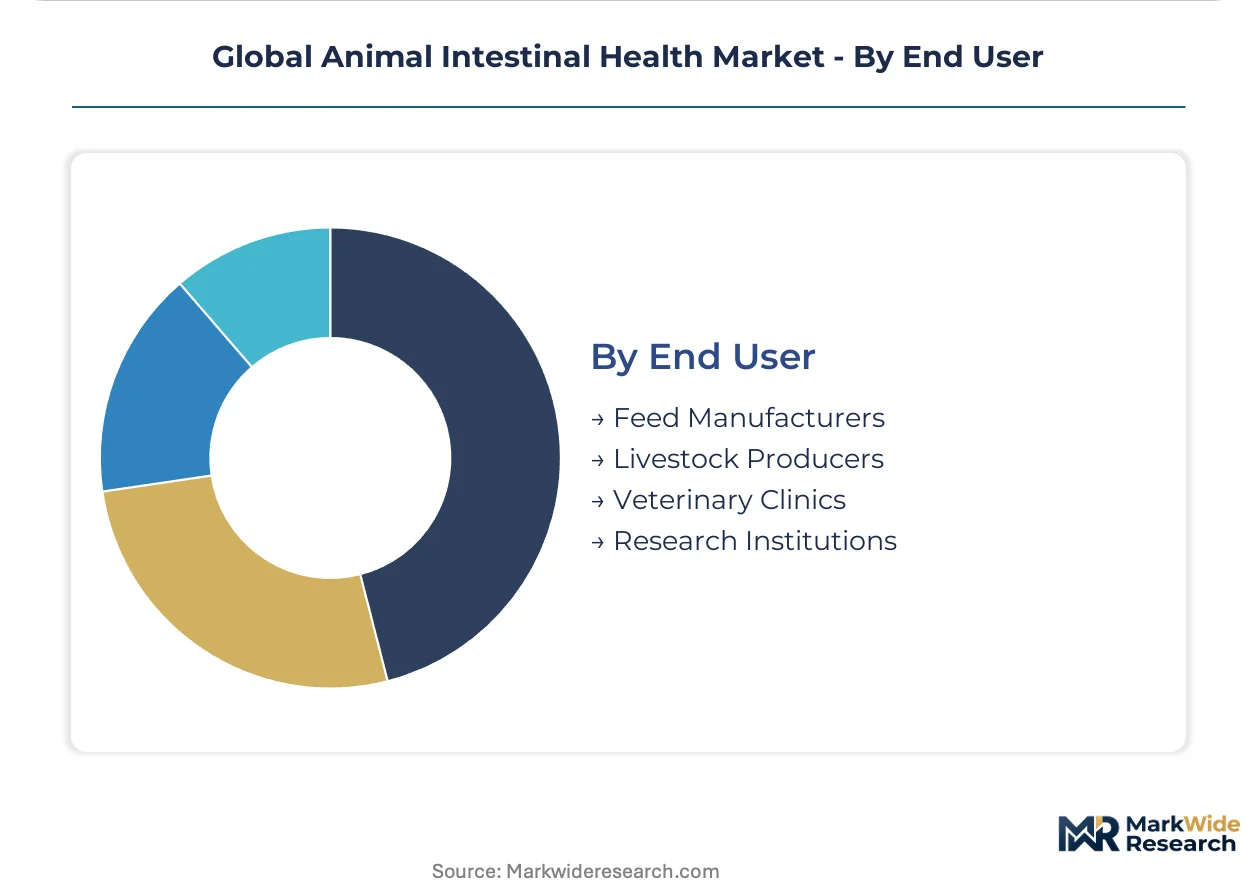
| Segmentation | Product Type: Probiotics, Prebiotics, Enzymes, Organic Acids, Herbal Supplements, Antimicrobials Animal Species: Poultry, Swine, Aquaculture, Ruminants, Equine, Pet Animals Application: Growth Promotion, Disease Prevention, Feed Efficiency, Nutrient Absorption, Immune Support, Gut Flora Balance End User: Feed Manufacturers, Livestock Producers, Veterinary Clinics, Research Institutions |
| Companies Covered | Cargill, Koninklijke DSM N.V., Archer Daniels Midland Company, Kemin Industries, DuPont de Nemours, Evonik Industries, Chr. Hansen Holding A/S, Novozymes, Alltech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Animal Intestinal Health Market Shifts & Advancements
Livestock producers are abandoning one-size-fits-all additive programs in favor of microbiome-targeted interventions that align with specific production stressors, pathogen pressure profiles, and dietary energy density levels.
Multi-strain synbiotic formulations combining Lactobacillus, Bacillus, and Saccharomyces with specific prebiotic substrates are electrifying the premium poultry segment in Western Europe and Southeast Asia. Large integrators in Thailand and the Netherlands have transitioned 40% of their breeder and layer operations to these combinations within eighteen months. This convergence is compressing the market share of single-ingredient probiotic suppliers while rewarding integrated fermentation and formulation capabilities.
China's GB standards for feed additive quality and the Ministry of Agriculture's updated national catalog are tightening strain identification, viability count verification, and contamination screening requirements. Domestic manufacturers face forced consolidation as compliance costs eliminate smaller fermentation operations. Multinational suppliers with established quality management systems are capturing displaced volume from de-listed local competitors.
Contract research organizations specializing in gut health biomarker analysis now offer commercial poultry and swine operations real-time microbiome profiling services that inform additive program adjustments. Large US integrators in the Southeast and Midwest have integrated these diagnostics into quarterly nutrition reviews, replacing static annual formulation protocols. This behavioral shift concentrates purchasing influence with technically sophisticated buyers capable of interpreting metagenomic data and demanding performance-guaranteed supply agreements.
Global Animal Intestinal Health Market Segmentation
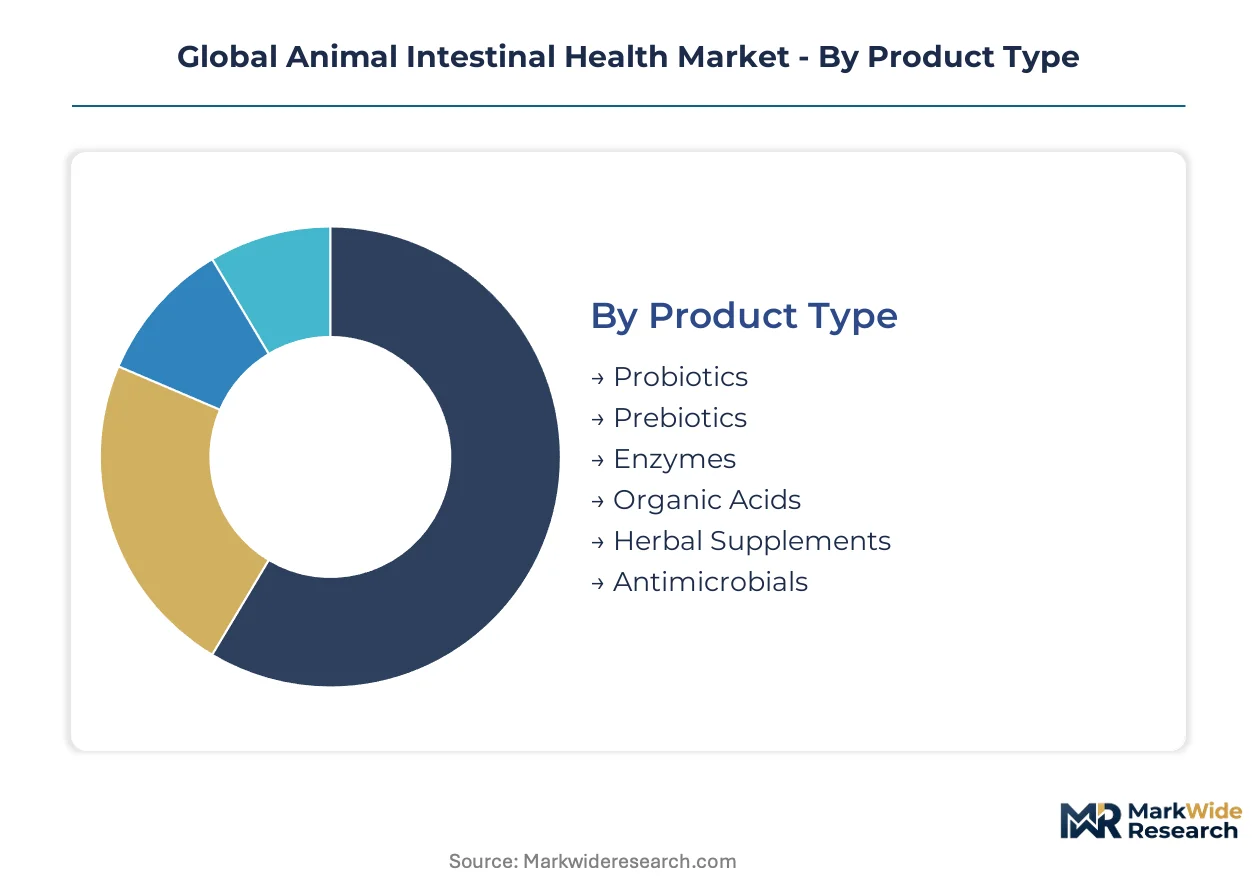
Product differentiation in animal intestinal health hinges on fermentation scalability, regulatory approval pathways, and compatibility with existing feed mill infrastructure. Suppliers align R&D investments with species-specific gut physiology and production stressor profiles to capture premium positioning.
Product Type:
Supply concentration clusters around fermentation-derived categories where strain banking and bioreactor capacity create defendable moats.
- Probiotics:Live microbial cultures of Lactobacillus, Bacillus, and Saccharomyces administered at 10^6 to 10^9 CFU per gram dominate value capture in poultry and swine operations. EU antibiotic growth promoter bans under Regulation 2019/6 have redirected procurement budgets toward documented viable count guarantees and strain-specific efficacy dossiers.
- Enzymes:Phytase and non-starch polysaccharide hydrolases displace inorganic phosphate and reduce feed conversion ratios across integrated broiler operations. Chinese feed manufacturers are expanding domestic production capacity for these products as the Ministry of Agriculture and Rural Affairs accelerates national catalog approvals.
- Prebiotics:Fermentable oligosaccharides and inulin derivatives selectively nourish beneficial gut flora.
- Organic Acids:Formic, propionic, and butyric acid formulations acidify gut environments and suppress pathogenic colonization.
- Herbal Supplements:Plant-derived bioactives including essential oils and saponins offer residue-free alternatives.
- Antimicrobials:Remaining antibiotic applications face tightening residue monitoring and withdrawal period enforcement.
Probiotics absorb the bulk of installed fermentation capacity; enzymes are expanding most quickly.
Animal Species:
Volume distribution tracks intensive production system density and regulatory pressure intensity across commercial operations.
- Poultry:Broiler and layer integrators in the US Southeast, Netherlands, and Thailand deploy multi-strain synbiotics to manage coccidiosis pressure and heat stress. Contract research organizations now offer real-time microbiome profiling to inform quarterly additive program adjustments.
- Swine:Post-weaning diarrhea management drives probiotic and organic acid adoption in European and Chinese farrow-to-finish systems. Precision-delivery technologies protect acidifiers from premature absorption in the stomach.
- Aquaculture:Shrimp and salmon producers in Vietnam and Norway apply gut health solutions to reduce antibiotic dependency in high-density pond and cage systems.
- Ruminants:Dairy and beef operations utilize yeast cultures and direct-fed microbials to stabilize rumen pH during high-grain finishing.
- Equine:Performance horse stables and breeding facilities adopt targeted supplementation for gastric ulcer prevention.
- Pet Animals:Premium dog and cat food manufacturers incorporate probiotics for digestive sensitivity positioning.
Poultry commands the largest absolute volume; aquaculture is climbing the fastest as antibiotic restrictions tighten in export-oriented production.
Application:
Functional positioning determines pricing tier and technical support intensity required from suppliers.
- Growth Promotion:Microbial feed additives and enzyme complexes replace antibiotic growth promoters in weight gain optimization. Brazil's integrated poultry operations represent underpenetrated expansion potential for multi-enzyme suppliers with local manufacturing.
- Disease Prevention:Competitive exclusion cultures and organic acid blends reduce pathogenic Salmonella and E. coli colonization. EU veterinary medicinal product frameworks mandate efficacy documentation for disease claims.
- Feed Efficiency:Phytase and carbohydrase inclusion enables reduced-cost formulation while maintaining metabolizable energy density.
- Nutrient Absorption:Gut barrier integrity solutions improve amino acid and mineral uptake in challenged production environments.
- Immune Support:Beta-glucans and specific microbial cell wall components modulate innate immune responses.
- Gut Flora Balance:Synbiotic combinations target dysbiosis following antibiotic therapy or dietary transitions.
Growth promotion retains the deepest supplier technical engagement; disease prevention is gaining share fastest under regulatory substitution pressure.
End User:
Procurement sophistication and formulation control vary sharply across customer types, dictating sales channel and service bundling.
- Feed Manufacturers:Compound feed mills in Germany, China, and the US Midwest specify additive inclusion rates and strain viability guarantees for branded product lines. Heat-labile probiotic formulations require pelleting temperature modifications or post-pelleting liquid application systems.
- Livestock Producers:Large integrators in Thailand and the Netherlands have transitioned substantial breeder and layer operations to multi-strain synbiotics within compressed timelines. These buyers demand performance-guaranteed supply agreements informed by metagenomic data.
- Veterinary Clinics:Practitioners prescribe therapeutic probiotic regimens for individual animal digestive disorders.
- Research Institutions:Universities and contract research organizations validate novel strain efficacy and gut health biomarker correlations.
Feed manufacturers concentrate the largest procurement volumes; livestock producers are consolidating purchasing influence fastest through technical capability investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hainan Free Trade Port tax incentives are pulling fermentation capacity toward southern coastal zones, concentrating probiotic manufacturing near export-oriented feed mill clusters.
China
Domestic feed additive manufacturers are scaling precision fermentation for Bacillus and Lactobacillus strains as the Ministry of Agriculture and Rural Affairs accelerates national catalog approvals. GB standards for feed additive quality now mandate strain identification and viability count verification. Guangdong and Shandong provinces host the densest concentrations of integrated fermentation facilities serving poultry and swine integrators.
United States
Large integrators in the Southeast and Midwest have integrated real-time microbiome profiling into quarterly nutrition reviews, replacing static annual formulation protocols. The FDA Center for Veterinary Medicine enforces feed additive approval pathways under the Food Additive Petition process. Iowa and North Carolina concentrate the highest volumes of probiotic and enzyme procurement for commercial broiler and swine operations.
Germany
Compound feed mills specify additive inclusion rates and strain viability guarantees for branded product lines under tightening EU veterinary medicinal product frameworks. The 2022 enforcement of complete antibiotic growth promoter prohibition creates immediate substitution demand. Lower Saxony and Bavaria host the primary manufacturing clusters for multi-strain synbiotic formulations serving Dutch and Polish integrators.
Brazil
Integrated poultry operations in São Paulo and Paraná represent underpenetrated expansion potential for multi-enzyme suppliers with local manufacturing capabilities. ANVISA maintains feed additive registration pathways that determine market access for imported probiotic products. The southern region concentrates the fastest-growing demand for phytase and carbohydrase complexes in Latin America's largest broiler production market.
Netherlands
Large integrators have transitioned substantial breeder and layer operations to multi-strain synbiotics within compressed eighteen-month timelines. EFSA efficacy documentation requirements mandate rigorous strain-specific dossiers for disease prevention claims. The Gelderland and Noord-Brabant provinces anchor the densest clusters of technically sophisticated buyers capable of interpreting metagenomic data and demanding performance-guaranteed supply agreements.
Global Animal Intestinal Health Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across strain banking, fermentation scale-up, and precision-delivery formulation tiers. The supplier base clusters around three strategic archetypes: integrated agribusinesses with captive feed formulation channels, dedicated microbial technology specialists with proprietary strain libraries, and precision-chemistry houses with encapsulation expertise. Competitive moves concentrate on backward integration into fermentation substrate supply and geographic licensing partnerships for regulatory dossier sharing.
Within the integrated agribusiness tier, Cargill and Archer Daniels Midland Company occupy positions spanning strain development through feed formulation. Among microbial technology specialists, Chr. Hansen Holding A/S exemplifies the strain banking and fermentation scale-up archetype, while Kemin Industries represents precision-delivery technology capabilities for organic acids and essential oils. These three anchors illustrate how competitive positioning separates suppliers with captive distribution from those dependent on third-party feed mill relationships.
| Leading Market Players |
|---|
| Cargill |
| Koninklijke DSM N.V. |
| Archer Daniels Midland Company |
| Kemin Industries |
| DuPont de Nemours |
| Evonik Industries |
| Chr. Hansen Holding A/S |
| Novozymes |
| Alltech |
| Others |
Supply & Pricing Matrix
EU Regulation 2019/6's complete antibiotic growth promoter prohibition redirects procurement budgets toward documented viable count guarantees and strain-specific efficacy dossiers, forcing additive suppliers to absorb fermentation substrate cost volatility and reformulation investments that compress margins across premium and standard tiers.
Pricing Analysis
Short lead-time premiums for validated Bacillus spore concentrates command pricing advantages over spot inventory of generic Lactobacillus formulations. Three-tier pricing structure across premium, standard, and economy levels separates multi-strain synbiotics with metagenomic performance guarantees from single-ingredient probiotics and commodity organic acid blends. Cost compression in standard-tier enzymes intensifies because Chinese domestic manufacturers expand phytase capacity under accelerated national catalog approvals. Large integrators in Thailand and the Netherlands exhibit least price sensitivity due to performance-guaranteed supply agreements, while Brazilian integrated poultry operations remain most price-sensitive given underpenetrated multi-enzyme adoption.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised probiotic shipments drive rework protocols at regional distribution hubs, with compromised batches diverted to aquaculture or ruminant applications where viability thresholds are less stringent. Fermentation capacity concentrates in China, Denmark, and the United States, with Guangdong and Shandong provinces hosting densest integrated facilities. Commercial-scale production draws from molasses, whey permeate, and soy-based growth media facing dairy and oilseed commodity price swings. Single-source vulnerability in characterized microbial strain banking held by limited fermentation technology specialists creates supply bottleneck risk. Distribution runs through compound feed mill specifications in Germany, China, and the US Midwest, with post-pelleting liquid application systems required for heat-labile formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial microbiologist scarcity capable of translating laboratory strain performance to 100,000+ liter bioreactor consistency props pricing for fermentation scale-up services, constraining capacity expansion timelines.
For Market Incumbents: Anticipate consolidation pressure from synthetic biology-enabled entrants by securing captive fermentation substrate supply through backward integration into molasses and whey permeate sourcing. Prioritize certification investment under China's GB standards for feed additive quality to capture volume displaced from de-listed domestic competitors. Defend channel control through performance-guaranteed supply agreements with technically sophisticated integrators capable of interpreting metagenomic data. For New Entrants and Emerging Players: Direct-to-feed-mill digital platforms bypass established distributor relationships in Brazil's underpenetrated integrated poultry operations, offering multi-enzyme complexes with local technical support. Target postbiotic metabolite commercialization as the most penetrable white space, bypassing live culture stability challenges while delivering targeted gut modulation benefits. Pursue precision fermentation scale-up partnerships with contract research organizations to accelerate Bacillus spore production timelines. For Investors and Strategic Acquirers: The window for entry favors strain banking specialists with proprietary microbial libraries and established EFSA/FDA regulatory dossiers. Long-term viability hinges on synthetic biology-enabled productivity gains and geographic licensing partnerships for regulatory dossier sharing. Monitor divergence between EU EFSA and US FDA approval timelines as the inflection indicator for formulation technology commercial scale potential.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Synthetic biology-enabled Bacillus spore production promises tenfold productivity gains for probiotic suppliers. |
| Backward Integration into Substrates | Captive molasses and whey permeate supply buffers margin compression from dairy commodity volatility. |
| Multi-Strain Synbiotic Formulation | Lactobacillus-Bacillus-Saccharomyces combinations capture premium positioning in Western European poultry. |
| Postbiotic Metabolite Commercialization | Cell-free supernatants bypass live culture stability challenges while delivering gut modulation benefits. |
| Regulatory Dossier Harmonization | Shared EU-US approval pathways reduce time-to-market for novel microbial strain introductions. |
Research Methodology
Document review covered EU veterinary medicinal product frameworks, FDA Center for Veterinary Medicine guidance documents, and China's Ministry of Agriculture national feed additive catalog updates, complemented by interviews with fermentation technology specialists, compound feed mill procurement directors, and large integrator nutritionists. Secondary validation drew from EFSA strain-specific efficacy dossiers, SEC filings of diversified agribusiness conglomerates, and customs data on fermentation substrate trade flows. Bottom-up capacity modeling triangulated against top-down procurement spend analysis across poultry, swine, and aquaculture operations.
Historical fermentation capacity expansion patterns cross-referenced against panel input from industrial microbiologists and bioreactor engineering specialists informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, animal species intensity, application functional positioning, and end-user procurement sophistication. CAGRs derived from elasticity-adjusted adoption curves incorporating regulatory substitution timelines and feed conversion ratio optimization incentives. Forecast inputs incorporated strain banking concentration metrics and precision-delivery technology penetration rates.
The model holds under stable EU veterinary medicinal product enforcement and continued Chinese national catalog expansion; deviation in F-Gas Regulation chemical carrier restrictions or REACH framework processing aid limitations would shift reformulation investment burdens and compress additive manufacturer margins. Practitioners should monitor divergence between EFSA and FDA approval timelines and fermentation substrate commodity price indices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Supplements Market
Veterinary
Veterinary Biologicals Biobank Market
Veterinary
Global Livestock Vaccines Market
Veterinary
Veterinary Tables Market
Veterinary
North America Veterinary Healthcare Market
Veterinary
Global Veterinary Hematology Analyzers Market
Veterinary
Clostridium Vaccine (Animal Health) Market
Veterinary
Veterinary Consumables Market
Veterinary
Global Veterinary Point of Care Market
Veterinary
Veterinary Immunodiagnostics Market
Veterinary
CBD Pet Market
Veterinary
Global Veterinary Telemetry Systems Market
Veterinary
Global Swine Vaccines Market
Veterinary
ASEAN Poultry Vaccines Market
Veterinary
Asia-Pacific Veterinary Vaccine Market
Veterinary
US Surgical Pet Collar Market