
 Tinea Pedis Treatment Market | 2026-2036
Tinea Pedis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Tinea Pedis Treatment Market Outlook
Subscription-based refill programs for topical antifungal creams is recalibrating how manufacturers monetize chronic tinea pedis cases. Johnson & Johnson leverages its consumer health infrastructure to sustain direct-to-patient delivery models. Bayer AG anchors pharmacy shelf presence through established clotrimazole formulations. GlaxoSmithKline plc differentiates via clinician-education programs that drive prescription-to-OTC transitions.
Tinea pedis treatment encompasses pharmaceutical interventions targeting dermatophyte fungi colonizing plantar skin, with topical azoles and allylamines typically formulated at concentrations between one and two percent to achieve fungicidal or fungistatic action against Trichophyton rubrum and Epidermophyton floccosum. The primary commercial purpose centers on resolving symptomatic infection while preventing recurrence in populations with compromised skin barrier function or communal exposure risks. Topical antifungals dominate volume due to favorable safety profiles and OTC accessibility, though oral antifungals capture disproportionate value in refractory or moccasin-type infections requiring systemic therapy. Homecare settings represent the fastest-expanding end-user channel as telehealth prescribing and direct-to-consumer platforms reduce clinic dependency for standard cases.
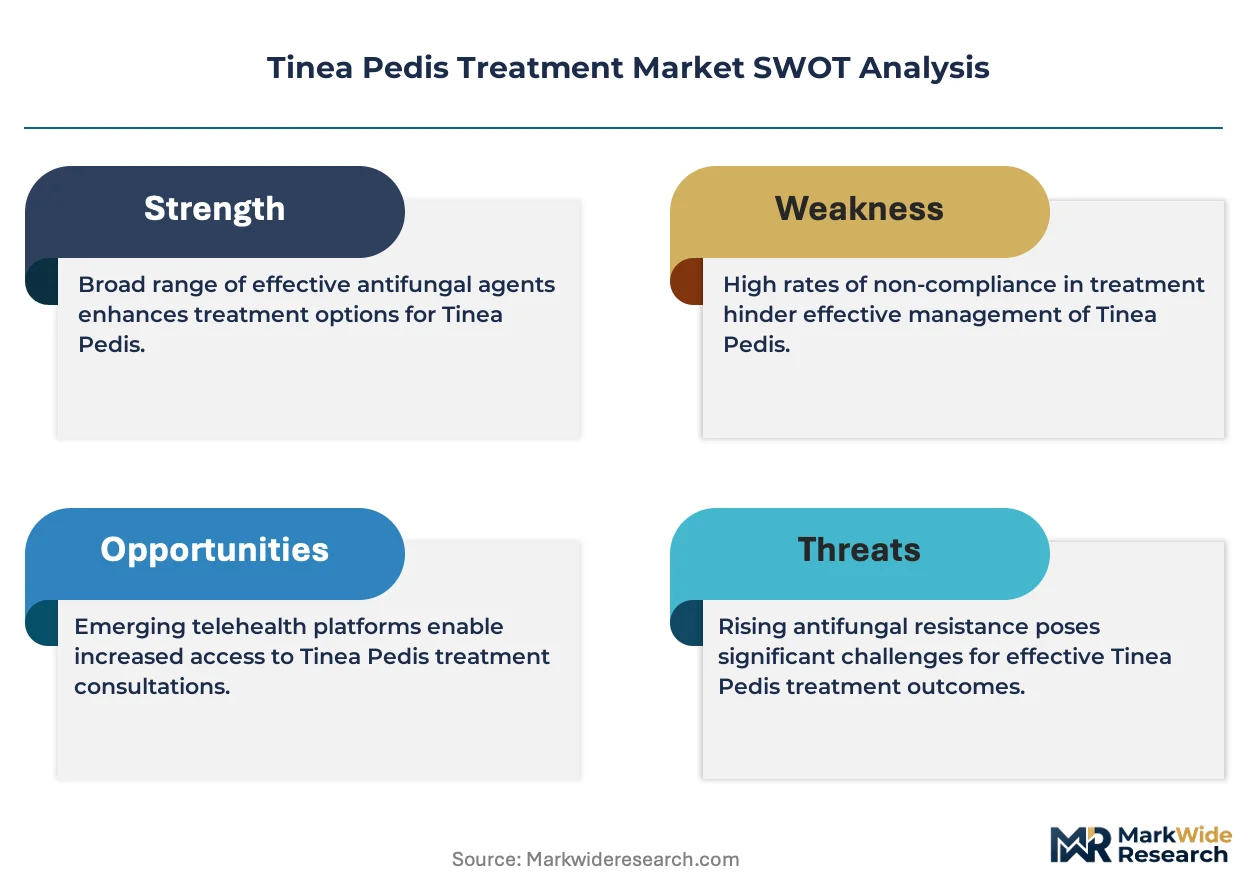
FDA OTC monograph reforms streamline active-ingredient determinations for topical antifungals, compressing time-to-market for new entrants while maintaining bioequivalence standards. EMA pharmacovigilance frameworks for topical dermatological products shape post-market surveillance obligations across European distribution networks. Health Canada and WHO prequalification pathways influence procurement criteria for public-sector formulary inclusion in emerging markets. Stakeholders must monitor evolving resistance patterns to terbinafine and azole compounds, as microbiological surveillance data will increasingly determine formulary positioning and R&D prioritization.
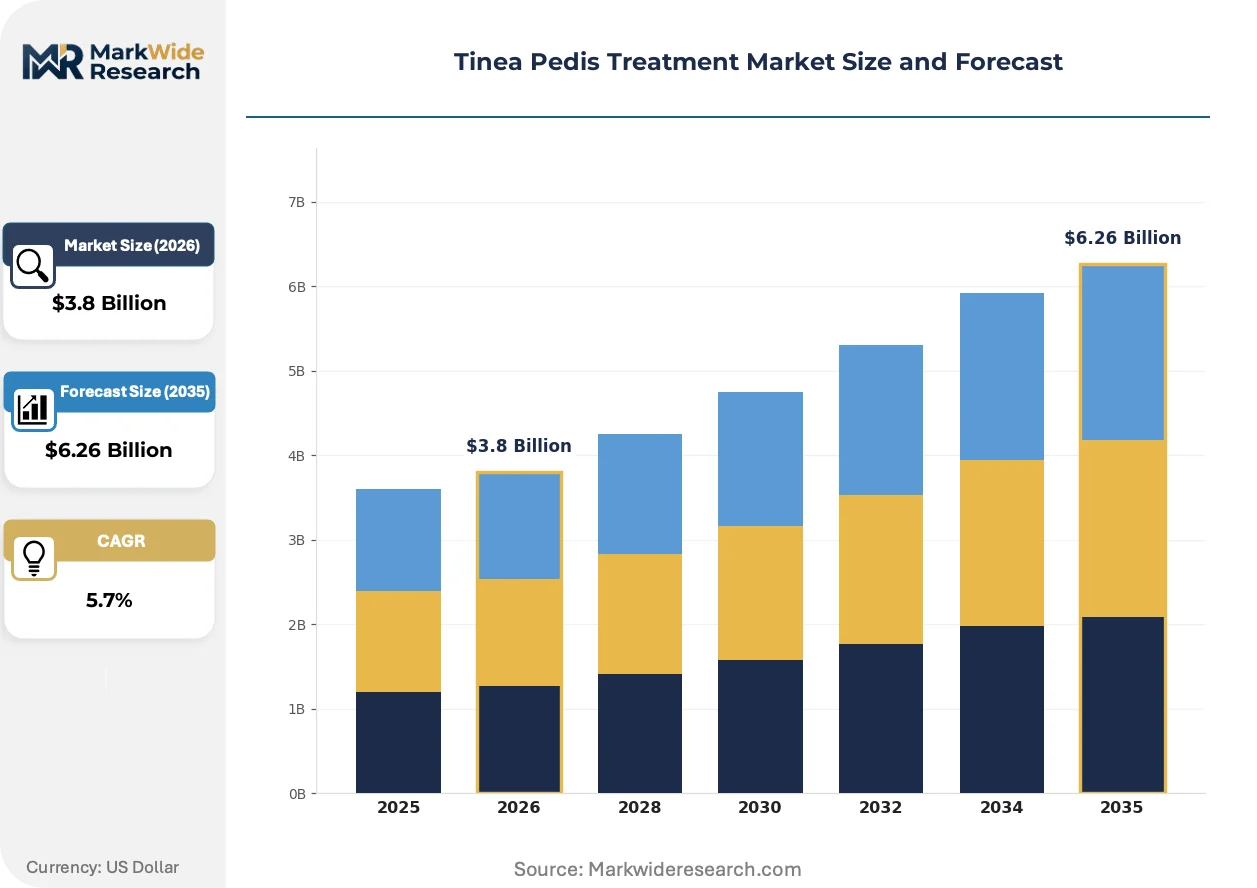
Market Dynamics
The FDA's OTC monograph reform is compressing approval timelines for topical antifungals while retail pharmacy chains expand private-label portfolios to capture self-treating patients with recurrent tinea pedis.
Growth Catalysts
- Preventive diabetic foot protocols:United States clinical guidelines now mandate antifungal prophylaxis for high-risk diabetic populations, embedding treatment into standard chronic care workflows.
- Telehealth prescribing platforms:Remote dermatology consultations reduce clinic dependency for standard cases, expanding addressable patient pools beyond traditional healthcare access points.
- Allylamine formulation advances:Improved terbinafine delivery systems achieve higher drug concentration at infection sites, shortening treatment duration and improving patient compliance metrics.
Market Restraints
- Active pharmaceutical ingredient concentration:Three Chinese manufacturers control bulk azole production, creating supply vulnerability for Western formulators during geopolitical trade disruptions.
- Terbinafine resistance surveillance:Microbiological monitoring networks document rising Trichophyton rubrum resistance patterns in Southeast Asian clinical isolates, threatening first-line therapy efficacy.
- Reimbursement compression:Medicare Part D formulary exclusions for topical antifungals shift cost burden to cash-paying patients, limiting access in fixed-income demographics.
Strategic Opportunities
- Subscription refill automation:Direct-to-patient delivery platforms capture chronic recurrence cases through algorithmic replenishment tied to treatment cycle completion.
- Combination barrier-repair formulations:Ceramide-enriched antifungal creams address compromised skin barrier function in elderly populations, differentiating beyond pure antimycotic action.
- EMA decentralized clinical trial frameworks:Streamlined post-authorization study requirements reduce evidence-generation costs for novel topical delivery technologies seeking European market entry.
Industry Challenges
- Formulation stability engineering:Maintaining azole potency across temperature-variable retail distribution chains requires enhanced excipient screening and packaging investment.
- Pharmacovigilance signal detection:EMA's strengthened topical dermatological surveillance mandates impose post-market reporting obligations that strain mid-tier manufacturer regulatory infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tinea Pedis Treatment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Antifungals, Oral Antifungals, Combination Therapies, Others End User: Pharmacies, Hospitals, Clinics, Homecare Settings Delivery Mode: Creams, Sprays, Powders, Tablets Treatment Duration: Short-term, Long-term, Maintenance Therapy, Acute Treatment |
| Companies Covered | Johnson & Johnson, GlaxoSmithKline plc, Bayer AG, Teva Pharmaceutical Industries Ltd., Glenmark Pharmaceuticals Limited, Bausch Health Companies Inc., Novartis AG, Sun Pharmaceutical Industries Ltd, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tinea Pedis Treatment Market Strategic Shifts
Topical antifungal development is pivoting toward patient adherence optimization through sensory engineering and connected packaging, while regulatory pathways fragment across harmonization efforts and regional stringency divergence.
Nanostructured lipid carriers for terbinafine delivery is expanding into standard topical formulations, enabling deeper stratum corneum penetration without occlusive vehicle requirements. Dermatology clinics in Germany and South Korea are adopting these carriers for moccasin-type infections previously requiring oral therapy. The technology is expanding into over-the-counter segments as manufacturing costs decline below conventional formulation thresholds.
EMA's revised guidance on quality and equivalence of topical products is tightening bioequivalence demonstration requirements for generic antifungal approvals. European manufacturers must now submit in vitro release testing and dermatopharmacokinetic studies previously exempted under abridged applications. Smaller generic sponsors in Italy and Spain are consolidating regulatory affairs capabilities to meet enhanced documentation burdens.
Patient-initiated treatment cycles are compressing the traditional physician-intermediated diagnostic pathway for tinea pedis, with smartphone-enabled symptom recognition tools replacing clinic visits for classic presentations. Pharmacy chains in the United Kingdom and Australia are deploying AI-guided shelf advisors that match lesion patterns to appropriate OTC selections. This behavioral shift concentrates volume in retail channels while reducing prescription antifungal utilization for uncomplicated cases.
Tinea Pedis Treatment Market Segmentation
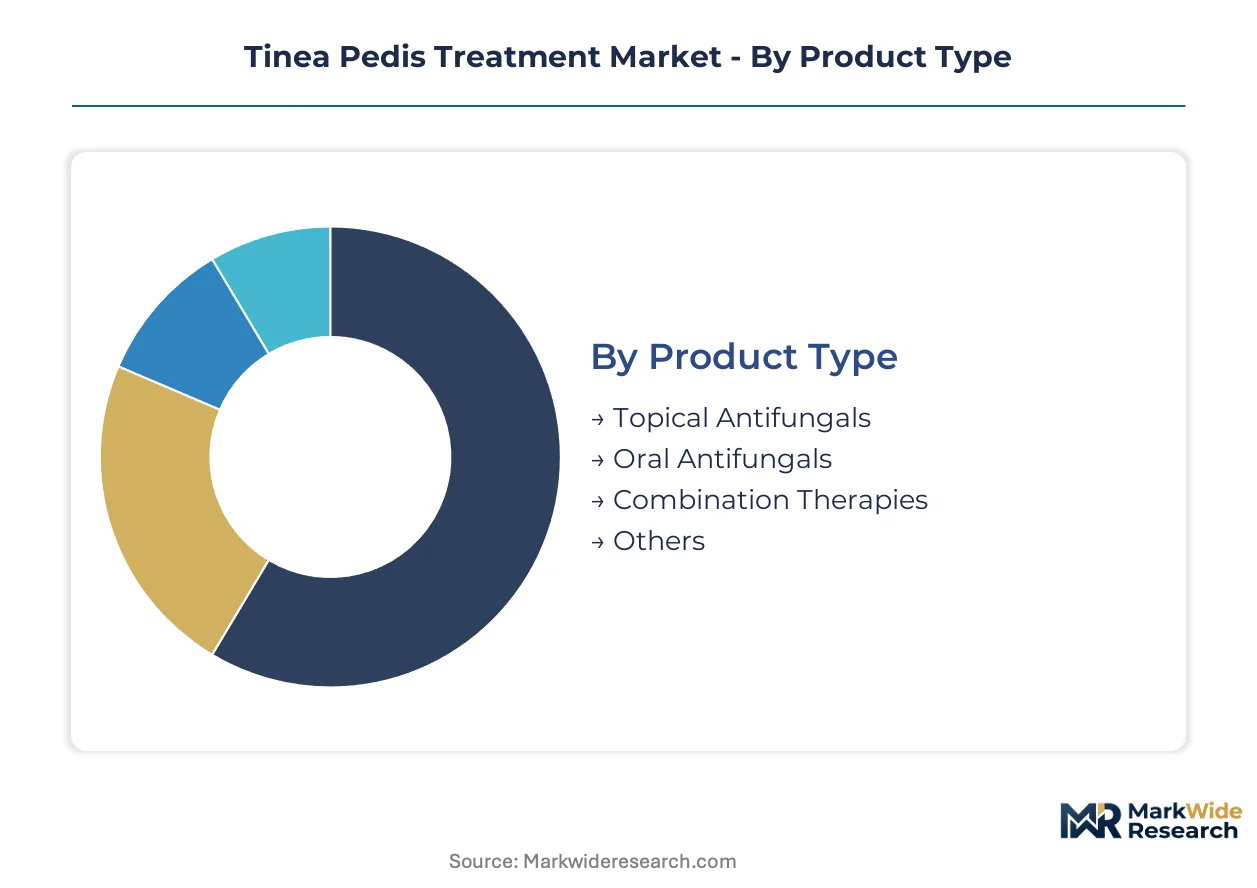
Tinea pedis treatment markets fragment across formulation technologies, care settings, and patient compliance requirements. Each segmentation axis reveals distinct capital deployment patterns and margin structures that determine competitive positioning.
Product Type:
Topical antifungal manufacturing demands substantial formulation R&D investment for skin penetration optimization, while oral therapy production requires GMP-compliant facilities with higher regulatory compliance costs.
- Topical Antifungals:Azole and allylamine formulations at one to two percent concentration achieve fungicidal action against Trichophyton rubrum through direct stratum corneum application. United States retail pharmacy chains capture the majority of volume through OTC shelf placement driven by diabetic foot protocol integration.
- Oral Antifungals:Systemic terbinafine and itraconazole tablets target refractory moccasin-type infections with hepatotoxicity monitoring requirements. Hospital formularies in Germany and South Korea concentrate demand where topical penetration fails.
- Combination Therapies:Antifungal-corticosteroid or antifungal-barrier repair hybrids address inflammation and recurrence simultaneously.
- Others:Adjunctive physical therapies and botanical preparations occupy niche positioning.
Topical antifungals absorb the bulk of installed capacity; combination therapies are expanding most quickly.
End User:
Channel selection determines pricing power and patient adherence monitoring capabilities, with direct-to-patient platforms disrupting traditional pharmacy intermediation.
- Pharmacies:Retail chains and independent dispensaries dominate OTC volume through pharmacist-guided selection and private-label portfolio expansion.
- Hospitals:Inpatient and emergency departments manage severe secondary bacterial complications in immunocompromised populations.
- Clinics:Dermatology and podiatry practices handle diagnostic confirmation and refractory case management with prescription authority.
- Homecare Settings:Telehealth-prescribed direct delivery eliminates clinic dependency for standard cases, with algorithmic refill automation capturing chronic recurrence revenue.
Pharmacies command the largest patient touchpoint volume; homecare settings show the steepest expansion trajectory.
Delivery Mode:
Vehicle engineering investments vary dramatically, with spray technology requiring specialized propellant systems versus conventional cream manufacturing.
- Creams:Semi-solid emulsions with ceramide or urea enrichment address barrier dysfunction in elderly diabetic populations, commanding premium positioning in Japanese and Australian markets.
- Sprays:Aerosol and pump systems enable interdigital application without manual spreading, reducing reinfection risk in communal settings.
- Powders:Absorbent talc or starch-based formulations target moisture control in occlusive footwear environments.
- Tablets:Oral solid dosage forms for systemic therapy require bioequivalence demonstration under tightened EMA quality guidance.
Creams retain the majority of manufacturing throughput; sprays are gaining share fastest among new product launches.
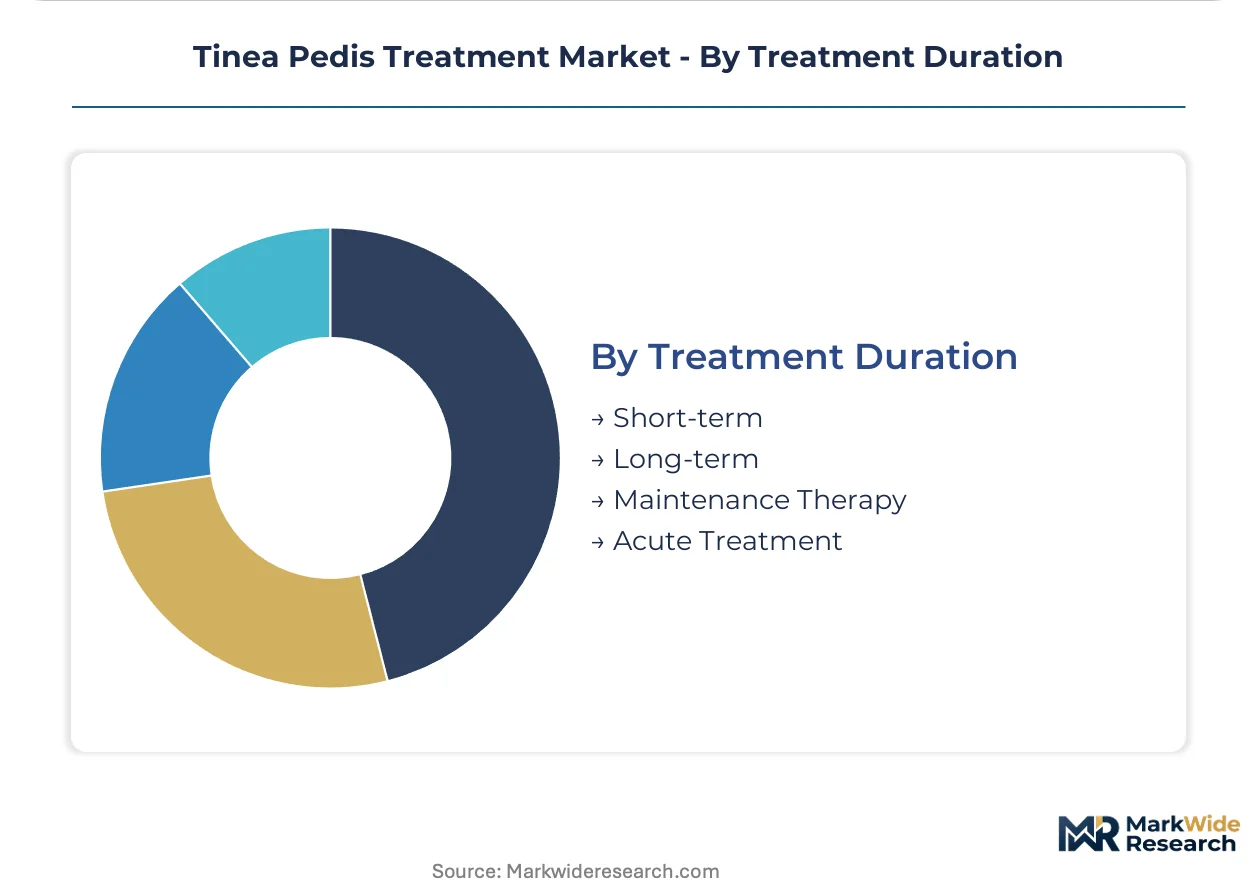
Treatment Duration:
Regulatory labeling and reimbursement categorization hinge on defined therapy lengths, with maintenance protocols requiring distinct clinical evidence packages.
- Short-term:One to two week topical courses for interdigital infections with rapid symptom resolution.
- Long-term:Extended oral therapy for nail matrix involvement or moccasin-type plantar spread.
- Maintenance Therapy:Prophylactic regimens for diabetic patients under United States preventive foot care protocols, embedding antifungal use into chronic disease management workflows.
- Acute Treatment:Episodic intervention for first-occurrence or sporadic cases without recurrence history.
Short-term protocols handle the greatest prescription volume; maintenance therapy is climbing the fastest as diabetic population screening expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Philadelphia's pharmaceutical corridor anchors North American antifungal manufacturing capacity, with FDA regulatory pathways shaping commercialization timelines across topical and oral therapy segments.
United States
Diabetic foot care protocols in Medicare Advantage plans embed preventive antifungal regimens into chronic disease management workflows. FDA OTC monograph reforms compress approval timelines for new topical entrants while maintaining bioequivalence standards. New Jersey and Pennsylvania host concentrated manufacturing infrastructure serving retail pharmacy chains.
Germany
EMA pharmacovigilance frameworks for topical dermatological products impose stringent post-market surveillance obligations on German distributors. Nanostructured lipid carrier adoption in dermatology clinics addresses moccasin-type infections previously requiring oral therapy. Bavaria's medical device and pharmaceutical cluster drives formulation innovation for barrier-repair combination products.
Japan
PMDA streamlined review pathways for reformulated topical antifungals accelerate market entry for ceramide-enriched cream variants. METI industrial policy supports domestic manufacturing of advanced delivery vehicles. Osaka-Kobe pharmaceutical production corridor supplies premium positioning products across Asia-Pacific markets.
United Kingdom
Telehealth-prescribed direct delivery platforms expand patient access beyond traditional clinic dependency in NHS and private channels. MHRA alignment with EMA quality guidance tightens generic approval requirements. London and Southeast England concentrate digital health infrastructure enabling algorithmic refill automation.
South Korea
MFDS regulatory harmonization with ICH standards facilitates parallel submission strategies for novel topical delivery technologies. Dermatology clinics in Seoul Capital Area adopt nanostructured carriers for refractory plantar infections. Busan-Ulsan chemical manufacturing base supplies excipient inputs for temperature-stable formulations.
Tinea Pedis Treatment Market Competitive Environment
Capital-heavy pharmaceutical manufacturers compete with asset-light brand licensors across the tinea pedis treatment landscape. Market structure tilts toward consolidated OTC segments where retail pharmacy chains wield shelf-space leverage, while prescription oral therapy remains concentrated among established systemic antifungal producers. Three archetypes dominate: integrated consumer health conglomerates with direct-to-patient infrastructure; specialty dermatology-focused formulators with clinician-education capabilities; and generic manufacturers competing on EMA bioequivalence demonstration. Competitive moves center on subscription-based refill automation capturing chronic recurrence revenue, and combination formulation development addressing barrier dysfunction in elderly diabetic populations.
Among integrated consumer health conglomerates, Johnson & Johnson and Bayer AG occupy positions leveraging established retail pharmacy relationships and private-label manufacturing scale. GlaxoSmithKline plc represents the clinician-education archetype, with pharmaceutical heritage supporting prescription-to-OTC transition strategies. These three entities anchor competitive dynamics across North American and European distribution networks, with each exemplifying distinct approaches to patient adherence optimization and regulatory pathway navigation.
| Leading Market Players |
|---|
| Johnson & Johnson |
| GlaxoSmithKline plc |
| Bayer AG |
| Teva Pharmaceutical Industries Ltd. |
| Glenmark Pharmaceuticals Limited |
| Bausch Health Companies Inc. |
| Novartis AG |
| Sun Pharmaceutical Industries Ltd |
| Sanofi |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap formulators in Italy and Spain anchor European supply for topical antifungal creams, their conservative capital structures limiting aggressive price competition while sustaining quality-focused positioning against private-label entrants from retail pharmacy chains.
Pricing Analysis
Value-based pricing anchored to treatment duration reduction commands premium positioning for nanostructured lipid carrier formulations in Germany and South Korea. Three-tier pricing structure across premium, standard, and economy levels stratifies by delivery technology complexity and barrier-repair ingredient inclusion. Pricing pressure stems from Medicare Part D formulary exclusions shifting cost burden to cash-paying patients in the United States. Retail pharmacy private-label portfolios exhibit highest price sensitivity; dermatology clinics prescribing novel delivery systems show lowest.
Supply Chain Analysis
Temperature-controlled freight costs for azole active pharmaceutical ingredients concentrate supply chain investment on China, India, and the United States distribution nodes. Bulk terbinafine and clotrimazole production draws from three Chinese manufacturers controlling global azole synthesis capacity. Single-source vulnerability in Chinese API supply creates tariff exposure risk during geopolitical trade disruptions. Distribution runs through retail pharmacy chain consolidation centers and direct-to-patient delivery platforms for homecare settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EMA pharmacovigilance mandates and FDA OTC monograph reforms strain mid-tier manufacturer regulatory infrastructure, forcing weaker players toward exit or acquisition.
For Market Incumbents: To counter terbinafine resistance surveillance data from Southeast Asian clinical networks, Johnson & Johnson and Bayer AG should deepen backward integration into ceramide-enriched formulation R&D and secure subscription refill automation technology through captive supply arrangements with telehealth platforms. For New Entrants and Emerging Players: Begin with maintenance therapy protocols for diabetic foot care in United States Medicare Advantage plans, the most penetrable segment where preventive antifungal regimens embed into chronic disease management workflows. Pursue direct-to-patient delivery partnerships with algorithmic replenishment capabilities as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor clinician-education specialists with European regulatory affairs consolidation capabilities in Germany and the United Kingdom. Long-term viability over a multi-year horizon hinges on capturing prescription-to-OTC transition revenue streams. Watch EMA decentralized clinical trial framework adoption rates as the signal for novel topical delivery technology inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Consolidation | EMA pharmacovigilance mandates strain mid-tier Italian and Spanish manufacturers, creating acquisition targets. |
| Subscription Refill Automation | Algorithmic replenishment tied to treatment cycles captures chronic tinea pedis recurrence revenue from retail pharmacy diversion. |
| Nanostructured Carrier Manufacturing Scale-Up | South Korean and German dermatology clinic adoption signals OTC segment cost threshold breakeven. |
| Barrier-Repair Formulation Development | Ceramide-enriched creams address elderly diabetic populations in Japanese and Australian premium positioning. |
| Telehealth Platform Partnership | Remote prescribing infrastructure eliminates clinic dependency for standard United States cases. |
Study Parameters
Document review covered FDA OTC monograph filings, EMA pharmacovigilance databases, and ClinicalTrials.gov records, complemented by interviews with dermatology formulary directors, retail pharmacy chain procurement managers, and telehealth platform operations leads. Secondary validation drew from CMS Medicare Part D utilization data, Japanese PMDA approval summaries, and South Korean MFDS regulatory harmonization reports. Bottom-up patient-flow modeling and top-down pharmaceutical market sizing were triangulated to establish volume baselines.
Cross-referencing historical topical antifungal prescription patterns against expert panel input on diabetic foot protocol expansion shaped the analytical framework across the projection horizon. Segmentation dimensions included product type, end user channel, delivery mode, and treatment duration protocol. CAGRs were derived from epidemiological prevalence projections and therapy penetration rate assumptions, with terbinafine resistance surveillance data and OTC-to-prescription shift velocities as key forecast inputs.
Underlying measurement precision varies by segment; maintenance therapy and homecare setting projections carry tighter precision than oral antifungal hospital formulary estimates. Forecasts reflect assumptions on regulatory pathway timelines and reimbursement policy continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Non-Invasive Surgery Market
Medical Treatment
Thyroid Deficiency Treatment Market
Medical Treatment
Global Sex Reassignment Surgery Market
Medical Treatment
Dementia Treatment Market
Medical Treatment
Mast Cell Tumors Treatment Market
Medical Treatment
Precocious Puberty Treatment Market
Medical Treatment
Tendonitis Treatment Market
Medical Treatment
Otoplasty Market
Medical Treatment
Yellow Fever Treatment Market
Medical Treatment
Brazilian Hemorrhagic Fever (Bzhf) Treatment Market
Medical Treatment
Nose Reconstruction Market
Medical Treatment
Hypercoagulability Treatment Market
Medical Treatment
Pelvic Organ Prolapse Repair Market
Medical Treatment
Dementia and Alzheimers Disease Treatment Market
Medical Treatment
Tissue Repair Technologies Market
Medical Treatment
Radioactive Iodine Ablation Therapy Market