
 Nerve Repair Market | 2026-2036
Nerve Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Nerve Repair Market Outlook
ISO 13485 certification is rotating the competitive landscape toward manufacturers with established quality management systems for active implantable devices. Medtronic leverages its vertically integrated neuromodulation infrastructure to dominate high-complexity nerve stimulation systems. Abbott sustains R&D intensity across its electrophysiology portfolio, anchoring its position in peripheral nerve targeting. Stryker competes through specialized orthopedic-nerve crossover instrumentation, occupying a distinct surgical workflow niche.
Nerve repair encompasses surgical and device-based interventions to restore structural continuity and functional signaling in damaged peripheral or cranial nerves, utilizing bioresorbable polymers, autograft harvesting techniques, or electrical pulse delivery with impedance-controlled output parameters. The primary purpose spans restoration of motor control, sensory perception, and autonomic function following transection, compression, or disease-mediated degeneration. Nerve conduit products lead current revenue pools due to their off-the-shelf availability and lower surgical complexity, while stem cell therapy segments attract accelerated development investment despite remaining pre-commercial. Neurostimulation devices command premium positioning in chronic neuropathy applications where pharmaceutical alternatives prove inadequate.
The FDA's 510(k) clearance framework and the EU Medical Device Regulation (MDR) establish divergent compliance burdens that filter market entry for novel biomaterial constructs. The FDA's Breakthrough Devices Program accelerates review timelines for nerve regeneration products targeting irreversible morbidity, while MDR clinical evidence requirements extend certification cycles for European market access. Stakeholders must monitor reimbursement coding decisions for bioelectronic medicine categories, as these determine whether hospital procurement committees classify nerve repair devices as capital equipment or procedure-bundled supplies.
Market Dynamics
The nerve repair market pivots on Medicare reimbursement coding decisions that determine whether hospitals classify neurostimulation devices as capital equipment or procedure-bundled supplies, directly altering procurement committee evaluation criteria and vendor sales cycles.
Growth Catalysts
- FDA Breakthrough Devices Program:The accelerated review pathway for nerve regeneration products targeting irreversible morbidity compresses time-to-market for novel biomaterial constructs. Trauma centers gain earlier access to interventions.
- Peripheral nerve targeting:Academic medical centers expand adoption of electrophysiology-guided surgical techniques. This drives demand for impedance-controlled output parameters in chronic neuropathy applications.
- Bioresorbable polymers:Off-the-shelf nerve conduit availability reduces surgical complexity. Autograft harvesting morbidity declines as synthetic alternatives mature.
Market Restraints
- EU MDR clinical evidence requirements:Extended certification cycles for European market access delay revenue recognition. Small manufacturers face disproportionate compliance burdens.
- Silicon wafer supply concentration:Neurostimulation device fabrication depends on concentrated Asian substrate suppliers. Input cost volatility compresses gross margins for active implantable producers.
- Stem cell therapy pre-commercial status:Accelerated development investment outpaces regulatory clarity. Reimbursement uncertainty stalls hospital procurement decisions.
Strategic Opportunities
- India PLI scheme for medical devices:Domestic manufacturing incentives attract contract development partners. Cost-advantaged production supports price-competitive nerve conduit exports.
- Bioelectronic medicine category creation:Novel coding pathways for electrical pulse delivery devices enable premium positioning. Hospital committees recategorize neurostimulation as distinct from pharmaceutical alternatives.
- Orthopedic-nerve crossover instrumentation:Surgical workflow integration opportunities emerge at specialized centers. Distinct positioning captures cases requiring simultaneous bone and neural reconstruction.
Industry Challenges
- ISO 13485 quality management certification:Active implantable device standards require specialized auditor expertise. Manufacturer capability scarcity extends implementation timelines.
- Neurostimulation firmware integration:Impedance-controlled output systems must interface with legacy hospital IT infrastructure. Compatibility testing prolongs sales cycles.
- Biomaterial construct standardization:Absence of unified performance benchmarks complicates comparative effectiveness research. Payer evidence requirements fragment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nerve Repair Market |
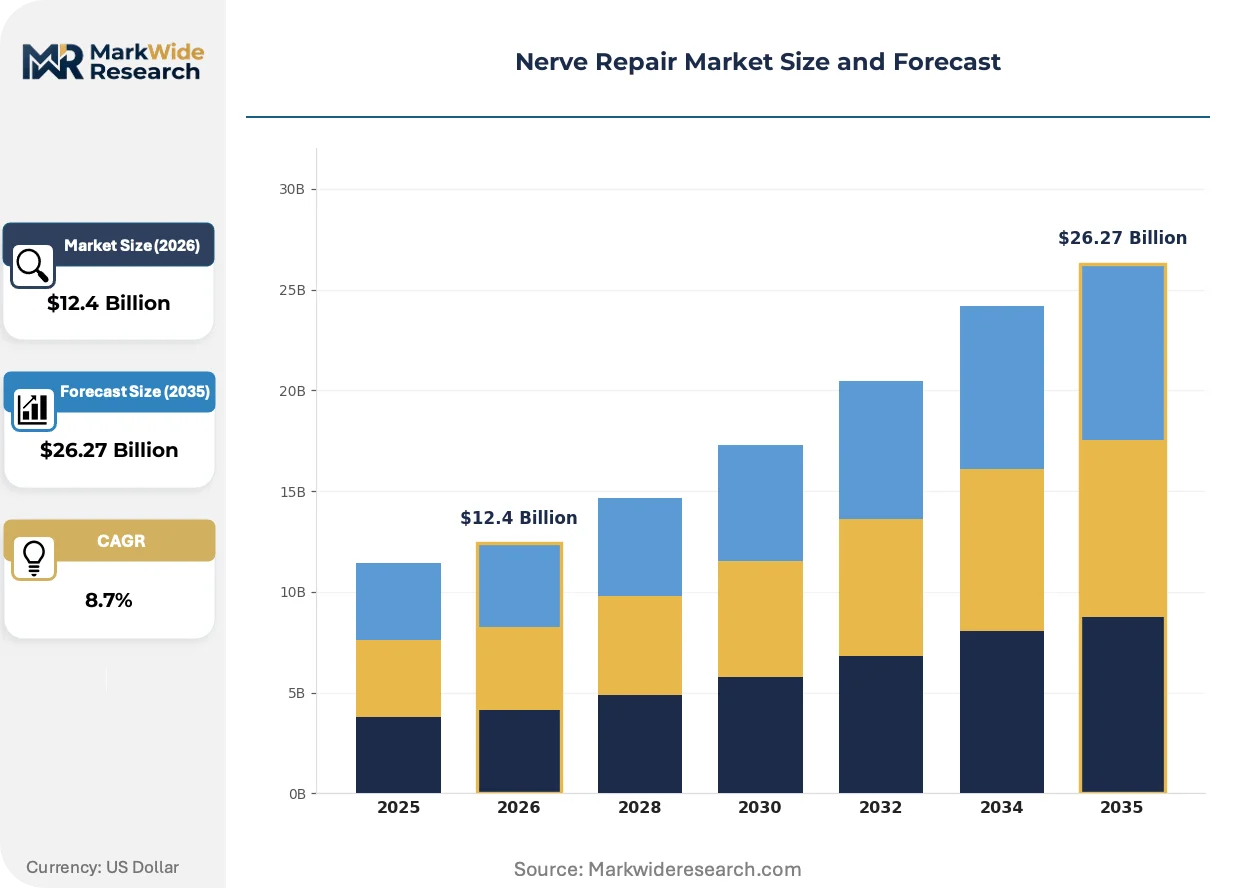
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nerve Conduit, Nerve Graft, Nerve Growth Factor, Neurostimulation Devices Application: Traumatic Injury, Neuropathy, Surgical Repair, Regenerative Medicine Technology: Biomaterials, Electrical Stimulation, Tissue Engineering, Stem Cell Therapy End User: Hospitals, Specialty Clinics, Research Centers, Rehabilitation Centers |
| Companies Covered | Medtronic plc, Abbott Laboratories, Boston Scientific Corporation, Integra LifeSciences Corporation, AxoGen Inc., Stryker Corporation, LivaNova PLC, Polyganics B.V., B. Braun SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nerve Repair Market Strategic Shifts
Biomaterial science and electrical engineering are converging to redefine therapeutic boundaries in peripheral nerve intervention, with regulatory frameworks struggling to keep pace with hybrid device-biological product classifications.
Nerve conduit technology is bifurcating into synthetic polymer and biological scaffold branches. Trauma centers adopt synthetic variants for routine transection repairs, while academic medical centers reserve biological constructs for complex brachial plexus reconstruction. This split is compressing autograft harvesting procedure volumes and redirecting surgical training emphasis.
The EU Medical Device Regulation's clinical evidence requirements for novel biomaterial constructs have extended European certification cycles. Manufacturers redirect development resources toward FDA 510(k) pathway optimization. Active implantable segments concentrate regulatory strategy investment in pre-submission meetings with CDRH.
Hospital procurement committees now demand procedure-bundled supply contracts rather than capital equipment purchases for nerve repair devices. This displaces traditional neurostimulation sales models in United States academic medical centers. Vendor response concentrates on outcomes-based contracting with shared risk structures.
Nerve Repair Market Segmentation
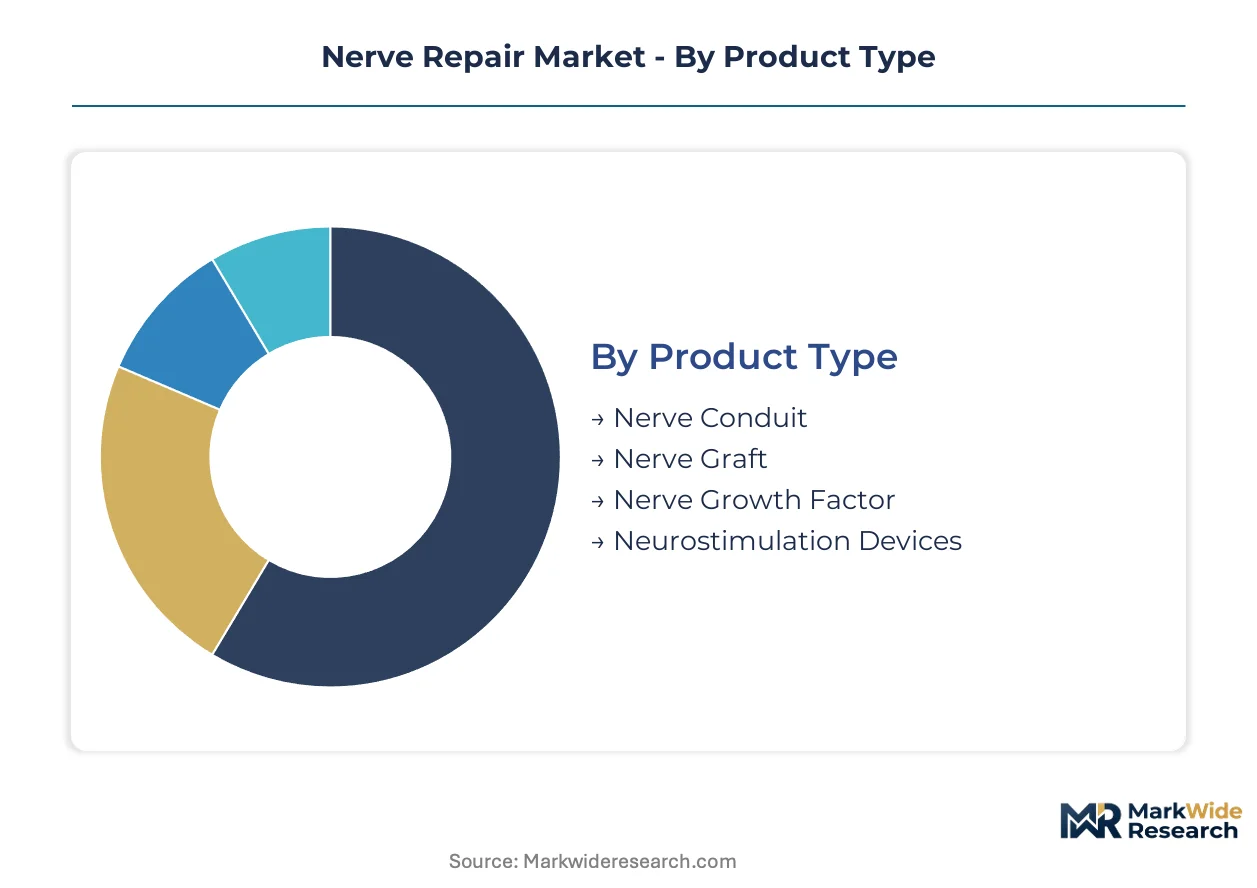
Nerve repair market segmentation reveals where substitution pressures and reimbursement dynamics create divergent growth trajectories across product categories. Understanding these divisions exposes which segments command premium positioning versus commodity exposure.
Product Type:
Substitution pressure from synthetic alternatives and pharmaceutical options reshapes competitive intensity most acutely in absorbable scaffold categories.
- Nerve Conduit:Synthetic polymer and collagen-based hollow tubes bridge transection gaps without autograft morbidity. Trauma centers in the United States favor off-the-shelf availability for routine peripheral nerve repairs, though Medicare bundled payment limits pricing flexibility.
- Nerve Graft:Autograft harvesting from sural or medial antebrachial cutaneous nerves maintains gold-standard functional outcomes for gaps exceeding 3 centimeters. Academic medical centers sustain demand despite donor site morbidity and operative time extension.
- Nerve Growth Factor:Recombinant protein therapies target molecular signaling pathways to accelerate axonal regeneration.
- Neurostimulation Devices:Implantable pulse generators with impedance-controlled output parameters address chronic neuropathy refractory to conventional intervention.
Nerve Conduit anchors the volume base while Neurostimulation Devices gains share at the steepest rate.
Application:
Cost tier stratification separates acute surgical intervention from chronic management, with reimbursement coding determining hospital procurement prioritization.
- Traumatic Injury:Acute transection and crush injuries from industrial accidents, motor vehicle collisions, and combat trauma drive emergency surgical volume. Level I trauma centers in the United States generate concentrated demand for immediate nerve reconstruction.
- Neuropathy:Diabetic peripheral neuropathy and chemotherapy-induced neural dysfunction create chronic patient populations requiring longitudinal management. Medicare reimbursement for neurostimulation implantation shapes addressable market expansion.
- Surgical Repair:Iatrogenic nerve injury during orthopedic, oncologic, or vascular procedures necessitates secondary reconstruction.
- Regenerative Medicine:Stem cell and gene therapy approaches target previously irreversible neural degeneration.
Traumatic Injury commands the largest procedure volume while Regenerative Medicine climbs the fastest despite pre-commercial status.
Technology:
Volume concentration in mature biomaterial platforms contrasts with supply-constrained emergence of biological engineering approaches.
- Biomaterials:Collagen, polyglycolic acid, and polycaprolactone constructs dominate commercial availability with established 510(k) clearance pathways. Synthetic conduit manufacturing scales efficiently for routine trauma applications.
- Electrical Stimulation:Implantable and transcutaneous systems deliver targeted pulses to modulate neural signaling and promote regeneration. FDA Breakthrough Device designation accelerates review for closed-loop impedance monitoring systems.
- Tissue Engineering:Acellular nerve allografts and decellularized biological scaffolds preserve extracellular matrix architecture.
- Stem Cell Therapy:Mesenchymal and induced pluripotent stem cell approaches remain investigational with IND-enabling studies ongoing.
Biomaterials sustains the revenue foundation while Electrical Stimulation expands most quickly through chronic indication penetration.
End User:
Customer type determines purchasing authority structure, with capital equipment committees diverging from procedure-bundled supply procurement.
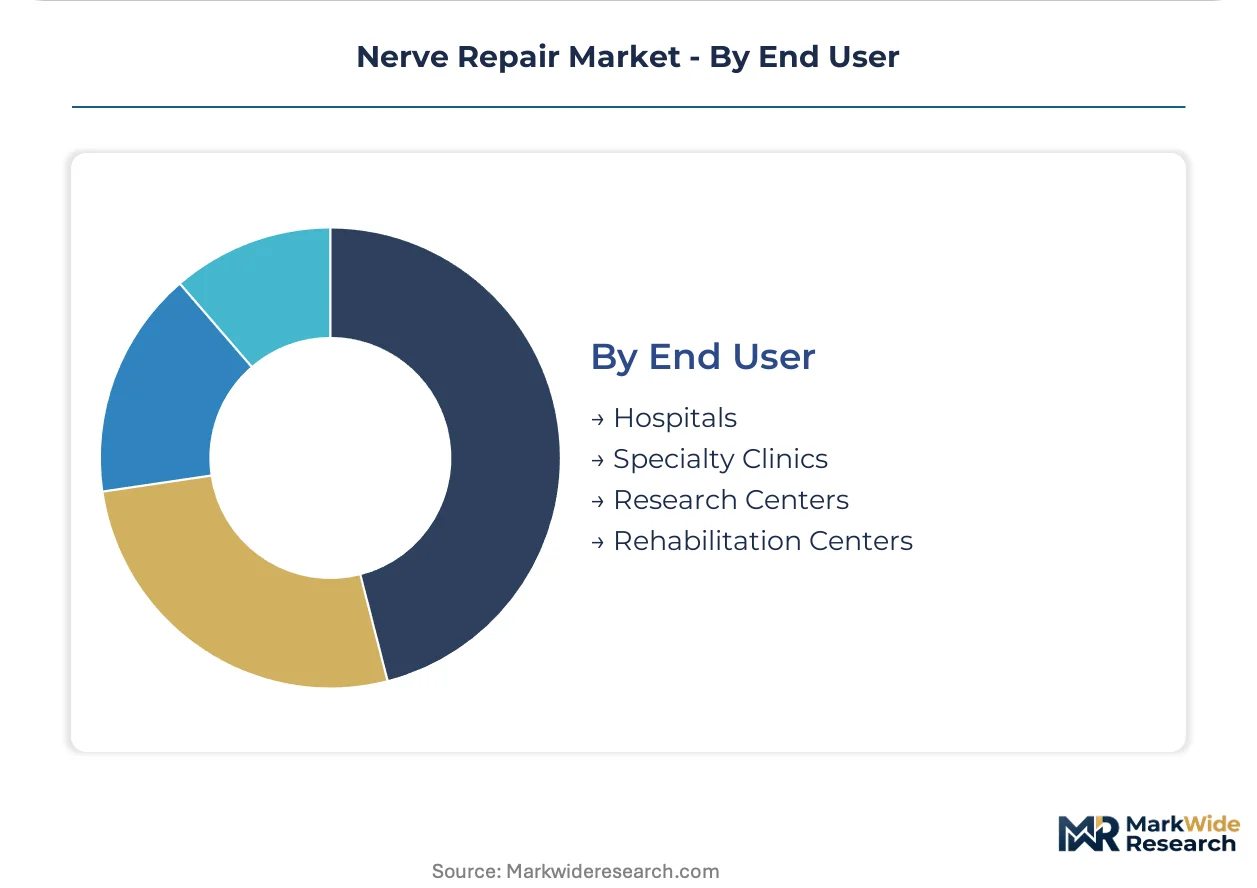
- Hospitals:Academic medical centers and community hospital systems integrate nerve repair into orthopedic, plastic surgery, and neurosurgical service lines. Value analysis committees evaluate total cost of ownership for implantable devices.
- Specialty Clinics:Ambulatory surgery centers and hand surgery focused practices concentrate high-volume peripheral nerve procedures. Outpatient prospective payment system reimbursement influences site-of-care migration.
- Research Centers:University laboratories and contract research organizations conduct preclinical and clinical investigation for novel constructs.
- Rehabilitation Centers:Post-acute facilities implement electrical stimulation protocols for neuromuscular re-education.
Hospitals retain the dominant procurement position while Specialty Clinics capture volume fastest through outpatient migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement policies in the United States and the EU MDR certification framework in Europe are redirecting manufacturer investment toward regulatory pathways with faster commercialization timelines. Trauma center density and academic medical center concentration determine regional adoption velocity for advanced nerve repair interventions.
United States
Level I trauma centers in Texas, Florida, and California generate concentrated surgical volume for peripheral nerve reconstruction. The FDA's Breakthrough Devices Program accelerates review timelines for novel biomaterial constructs targeting irreversible morbidity. Minneapolis and Boston anchor neurostimulation device development clusters with vertically integrated neuromodulation infrastructure.
Germany
Academic medical centers in Bavaria and Baden-Württemberg sustain demand for complex brachial plexus reconstruction using biological scaffolds. The EU MDR's clinical evidence requirements extend certification cycles for novel constructs, redirecting some development resources toward FDA pathways. Tübingen and Heidelberg host specialized surgical training programs emphasizing electrophysiology-guided techniques.
China
Industrial trauma volume in the Yangtze River Delta and Pearl River Delta drives emergency nerve repair procedure growth. The NMPA's regulatory framework for active implantable medical devices shapes market entry timelines for neurostimulation systems. Shanghai and Shenzhen concentrate domestic manufacturing capacity for synthetic polymer nerve conduits.
India
Road traffic trauma and industrial accidents in Maharashtra and Gujarat create substantial peripheral nerve injury caseloads. The PLI scheme for medical devices attracts contract development partners for cost-advantaged nerve conduit production. Mumbai and Ahmedabad host emerging manufacturing clusters targeting export markets.
Japan
Aging-related neuropathy prevalence in the Kanto region expands addressable markets for chronic pain management devices. The PMDA's consultation framework for regenerative medical products provides regulatory clarity for stem cell therapy development. Tokyo and Osaka concentrate hospital procurement authority for high-value implantable devices.
Nerve Repair Market Competitive Environment
Player mix skews toward diversified medical technology conglomerates with neuromodulation portfolios, mid-cap orthopedic crossover specialists, and pre-commercial regenerative medicine ventures. Market structure concentrates revenue among three strategic archetypes: vertically integrated active implantable producers, biomaterial scaffold specialists, and surgical instrumentation vendors with nerve repair adjacencies. Dominant competitive moves include strategic partnerships for combined device-biological product development and geographic expansion through distributor relationships in trauma center networks.
Within the diversified conglomerate tier, Medtronic plc and Abbott Laboratories exemplify players leveraging electrophysiology infrastructure across peripheral nerve targeting applications. Among specialized biomaterial developers, AxoGen Inc. and Polyganics B.V. occupy positions emphasizing off-the-shelf conduit availability and synthetic polymer innovation respectively. These named entities anchor archetype discussions without constraining competitive dynamics to specific company actions.
| Leading Market Players |
|---|
| Medtronic plc |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Integra LifeSciences Corporation |
| AxoGen Inc. |
| Stryker Corporation |
| LivaNova PLC |
| Polyganics B.V. |
| B. Braun SE |
| Others |
Value Chain & Pricing Dynamics
Procedure-bundled supply contracts lock in multi-year procurement commitments for trauma centers while anchoring price visibility against Medicare reimbursement fluctuations. This structure concentrates purchasing power among United States academic medical centers and forces manufacturers to absorb cost volatility from silicon wafer supply markets.
Pricing Analysis
Certification level (ISO 13485/FDA-grade versus CE-marked standard) creates the primary spread between premium neurostimulation systems and commodity nerve conduits. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and impedance-controlled output complexity. Price erosion runs through synthetic polymer conduit categories as Indian PLI-subsidized manufacturing expands export capacity. Academic medical centers exhibit lowest price sensitivity due to bundled payment insulation, while ambulatory surgery centers face acute margin pressure from outpatient prospective payment system rates.
Supply Chain Analysis
Port congestion on trans-Pacific lanes elevates inbound logistics costs for Asian-manufactured neurostimulation substrates destined for Minneapolis and Boston development clusters. Fabrication draws from concentrated silicon wafer supply in Taiwan and South Korea, with secondary biomaterial polymer sourcing from Germany and the Netherlands. Single-source vulnerability in semiconductor-grade substrate supply threatens active implantable device production schedules. Distribution runs through specialized medical device distributors with trauma center network relationships rather than broad-line hospital supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nerve repair market is cycling through post-pandemic surgical backlog normalization, with trauma procedure volumes driving recovery momentum across United States Level I centers.
For Market Incumbents: Consolidate procurement committee relationships through outcomes-based contracting with shared risk structures. Defend against orthopedic-nerve crossover instrumentation specialists by deepening electrophysiology infrastructure in academic medical centers. Prioritize ISO 13485 certification maintenance as auditor scarcity extends competitor implementation timelines. For New Entrants and Emerging Players: Differentiate on bioresorbable polymer customization for complex brachial plexus reconstruction cases that academic medical centers reserve for biological constructs. Target India PLI scheme contract manufacturing partnerships to achieve cost-advantaged positioning for synthetic conduit exports. Pursue hospital system partnership go-to-market models that bypass traditional capital equipment sales cycles. For Investors and Strategic Acquirers: Capital is best deployed toward pre-commercial regenerative medicine ventures with IND-enabling study completion and clear FDA Breakthrough Device designation pathways. Five-to-ten year viability hinges on reimbursement coding decisions for bioelectronic medicine categories. Watch for Medicare coverage determination signals for closed-loop impedance monitoring systems as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated review compresses time-to-market for novel biomaterial constructs targeting irreversible morbidity. |
| Hospital System Partnership | Outcomes-based contracting with shared risk structures displaces traditional capital equipment procurement models. |
| CE Marking Pathway Optimization | EU MDR clinical evidence requirements extend certification cycles, redirecting resources toward FDA 510(k) pathways. |
| Software Companion Development | Impedance-controlled output systems require firmware integration with legacy hospital IT infrastructure. |
| Reimbursement Strategy | Medicare coding decisions determine whether neurostimulation devices classify as capital equipment or procedure-bundled supplies. |
Study Parameters
Initial hypotheses were tested against primary input from trauma surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) clearance databases, CMS Medicare reimbursement coding decisions, hospital procurement contract filings, and EU MDR certification registries. Bottom-up nerve repair procedure volume estimates triangulated with top-down manufacturer revenue attribution across product categories.
Variance decomposition across the projection horizon isolates volume drivers (trauma incidence, surgical backlog normalization) from value drivers (product mix shift toward neurostimulation, reimbursement rate adjustments). Segmentation modeling incorporates product type, application, technology platform, and end-user purchasing authority structure. CAGRs derive from logarithmic trend fitting of annual procedure and revenue estimates, with sensitivity testing against silicon wafer supply disruption scenarios and Medicare coverage determination timelines.
Material uncertainties — regulatory approval delays, reimbursement coding reversals, supply chain disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about FDA review pathway efficiency and EU MDR certification cycle duration that material shifts could invalidate. Recalibration cycles align with material shifts in Medicare coverage determinations and trauma center procedure volume reporting.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
AIDS Related Primary CNS Lymphoma Market
Neurology
Bell Palsy Treatment Market
Neurology
Aneurysmal Subarachnoid Hemorrhage Market
Neurology
Lewy Body Dementia Treatment Market
Neurology
Intracranial Aneurysm Market
Neurology
Ulnar Nerve Treatment Market
Neurology
Optic Neuropathy Management Market
Neurology
Vocal Cord Paralysis Market
Neurology
Global Neuromarketing Market
Neurology
Amnestic Disorders Therapeutics Market
Neurology
Occipital Nerve Block Treatment Market
Neurology
Saudi Arabia Neurology Devices Market
Neurology
Neuropsychiatric Disorders and Treatment Market
Neurology
Multiple Sclerosis Therapies Market
Neurology
Netherlands Neurology Devices Market
Neurology
Spasticity Treatment Market