
 Achalasia Treatment Market | 2026-2036
Achalasia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Achalasia Treatment Market Analytics
Gastroenterology fellowship training capacity is collapsing across Western health systems, tightening the supply of physicians qualified to perform advanced endoscopic interventions. Medtronic sustains technology leadership in endoscopic platforms through dedicated surgeon education programs. AbbVie leverages its botulinum toxin portfolio to anchor the pharmacologic segment against procedural alternatives. Pfizer competes through generic calcium channel blockers that occupy the medical management tier.
Achalasia treatment encompasses interventions that restore esophageal motility by disrupting the dysfunctional lower esophageal sphincter, primarily through pneumatic dilation, laparoscopic Heller myotomy, or peroral endoscopic myotomy requiring submucosal tunneling under endoscopic visualization. The primary purpose is symptom relief and prevention of megaesophagus progression. Surgery and pneumatic balloon categories lead in revenue contribution where hospital reimbursement structures favor definitive intervention, while botulinum toxin persists as a bridge therapy for poor surgical candidates. Robotic surgery within the technology dimension differentiates through precision suturing capabilities that reduce perforation risk, though laparoscopic approaches dominate procedural volume due to established training pathways.
FDA 510(k) clearance requirements and EMA MDR compliance shape device commercialization timelines for pneumatic dilators and robotic surgical platforms, while ISO 13485 certification governs manufacturing quality systems. Japan's PMDA adds a distinct review layer for endoscopic myotomy devices entering that market. Stakeholders must monitor evolving CMS and national payer coverage decisions for peroral endoscopic myotomy as the procedure displaces laparoscopic alternatives.
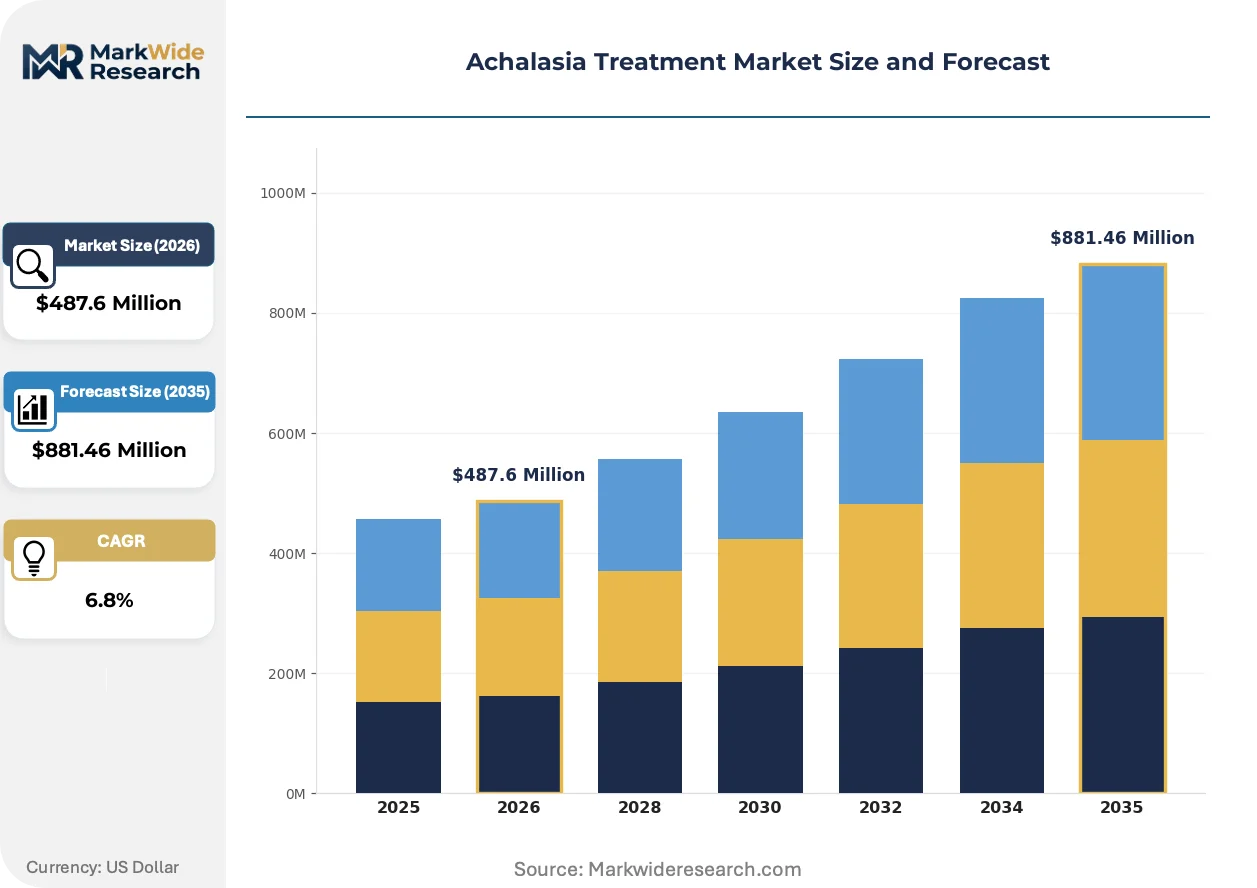
Market Dynamics
Peroral endoscopic myotomy is decomposing the traditional surgical hierarchy by shifting definitive achalasia intervention from operating rooms to endoscopy suites, compressing hospital infrastructure requirements and redistributing procedure economics toward outpatient settings.
Growth Catalysts
- FDA 510(k) Streamlining:Expedited clearance pathways for pneumatic dilation devices and endoscopic platforms are accelerating commercialization timelines for minimally invasive technologies entering US hospital systems.
- Japan's Aging Demographics:Rising prevalence of esophageal motility disorders among elderly populations is expanding the addressable patient base for both surgical and pharmacologic interventions.
- Submucosal Tunneling Techniques:Refinement of endoscopic dissection methods is enabling safer myotomy performance by gastroenterologists without formal surgical training, broadening provider pools.
Market Restraints
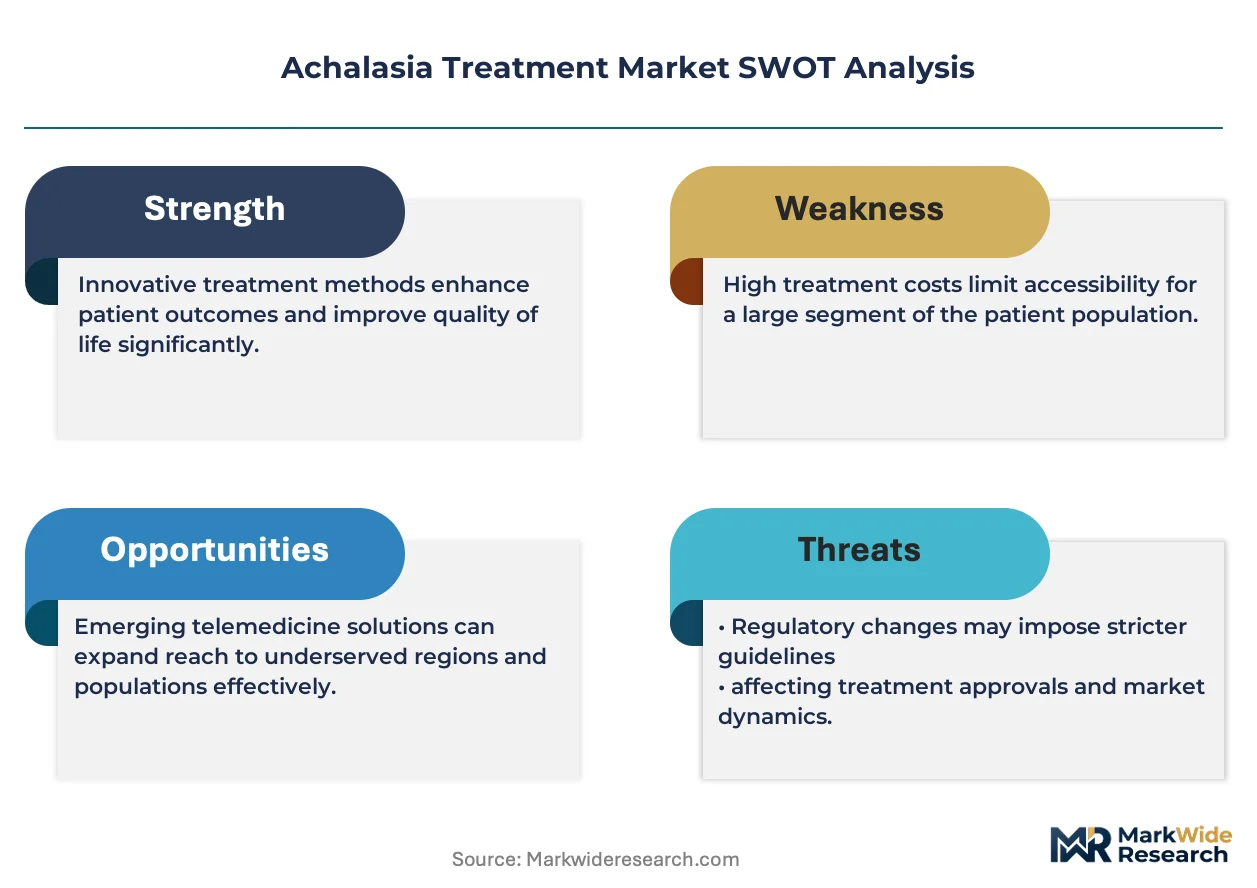
- Specialist Training Bottlenecks:Collapsing gastroenterology fellowship capacity across Western health systems is constraining the supply of physicians qualified to perform advanced endoscopic interventions.
- Device Reimbursement Uncertainty:Evolving CMS coverage decisions for peroral endoscopic myotomy create payment volatility that dampens hospital capital commitment to dedicated endoscopy platforms.
- Calcium Channel Blocker Substitution:Generic pharmacologic alternatives continue to occupy the medical management tier, limiting procedural conversion rates among cost-sensitive patient segments.
Strategic Opportunities
- German Tertiary Network Expansion:Concentration of academic medical centers in Bavaria and North Rhine-Westphalia presents concentrated demand for robotic surgical platforms and advanced endoscopic training programs.
- EU MDR Compliance Services:Stricter medical device regulation requirements are creating ancillary revenue streams for quality system consulting and clinical evidence generation supporting pneumatic dilator manufacturers.
- Teleproctoring Infrastructure:Remote surgical mentorship networks are emerging as a distribution channel innovation that accelerates peroral endoscopic myotomy adoption outside traditional academic training corridors.
Industry Challenges
- Cross-Functional Skill Integration:Successful peroral endoscopic myotomy deployment requires coordination between gastroenterology and thoracic surgery departments, creating organizational friction in hospital credentialing processes.
- ISO 13485 Certification Burden:Manufacturing quality system requirements for pneumatic dilators and endoscopic accessories impose extended compliance timelines that delay product launches by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Achalasia Treatment Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgery, Medication, Pneumatic Balloon, Botulinum Toxin Delivery Mode: Oral, Injectable, Endoscopic, Transcatheter End User: Hospitals, Clinics, Research Institutions, Home Care Technology: Laparoscopic, Robotic Surgery, Endoscopy, Radiology |
| Companies Covered | Bausch Health, Pfizer, Merz Pharma, Accord HealthCare, AdvaCare Pharma, Zydus Pharmaceuticals, AbbVie, Ipsen Pharma, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Achalasia Treatment Market Evolving Landscape
Robotic assistance is penetrating achalasia surgery through precision suturing capabilities that reduce perforation risk, while endoluminal platforms are capturing volume from laparoscopic alternatives through reduced recovery times and lower facility fees.
Peroral endoscopic myotomy is decomposing the traditional treatment algorithm for achalasia by enabling submucosal tunneling under direct endoscopic visualization without external incisions. Tertiary referral centers in the United States and Japan are adopting this technique at accelerating rates as fellowship programs expand hands-on training curricula. The technology is decomposing hospital revenue models by shifting procedures from inpatient surgical suites to ambulatory endoscopy centers with lower overhead structures.
EMA MDR compliance requirements are reshaping commercialization pathways for pneumatic dilation devices and robotic surgical platforms entering European markets. Manufacturers must now generate expanded clinical evidence packages and maintain more rigorous post-market surveillance systems than under previous directives. Endoscopic myotomy device categories face the steepest compliance burden, with notified body backlogs extending review timelines and favoring larger manufacturers with dedicated regulatory affairs infrastructure.
Hospital procurement committees are consolidating vendor relationships for achalasia treatment devices under value-analysis frameworks that bundle endoscopic platforms with training and service contracts. Independent community hospitals are losing direct purchasing autonomy as integrated delivery networks centralize contracting decisions at the system level. This concentration is most visible in United States metropolitan markets where health system mergers have reduced the number of independent decision-making entities by half over the past decade.
Achalasia Treatment Market Segmentation
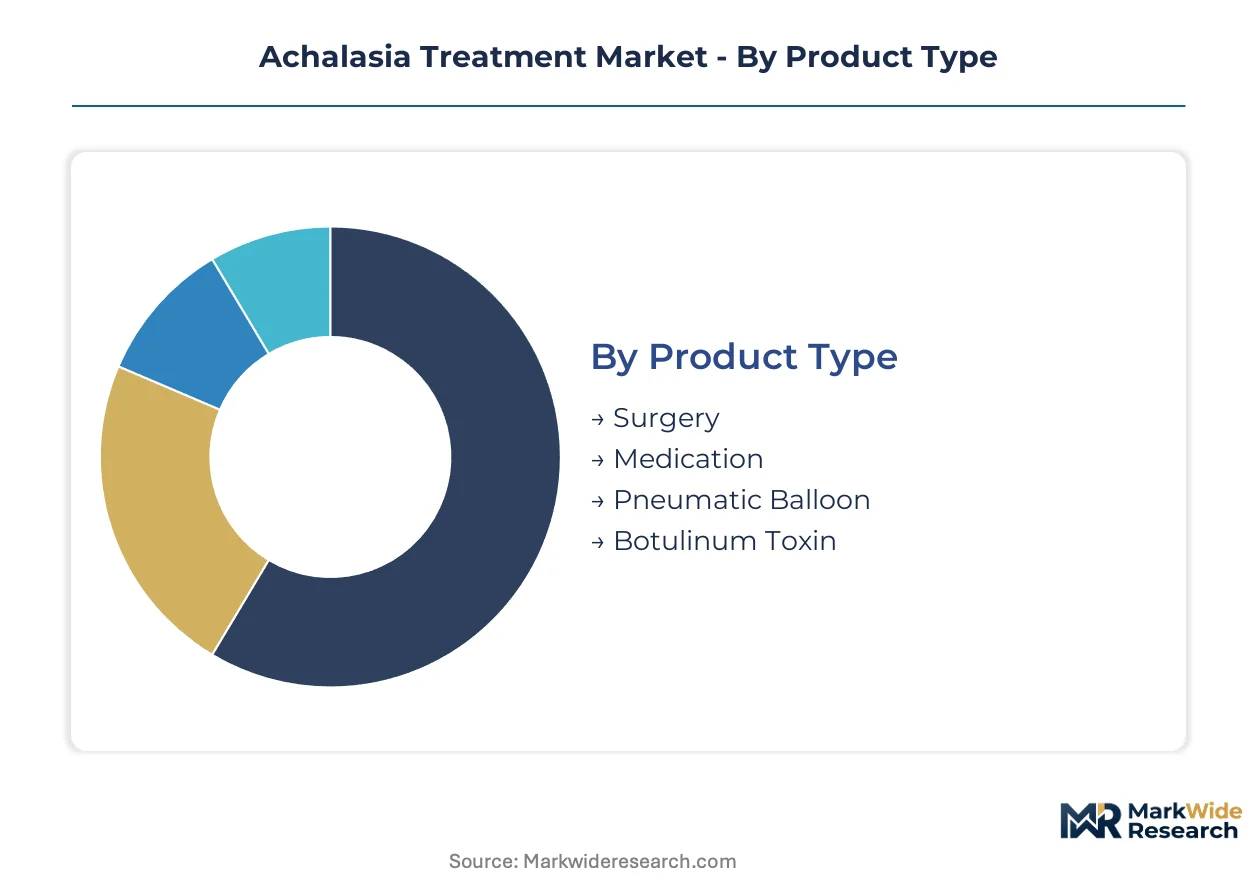
Segmentation in achalasia treatment reveals how reimbursement structures, training pathways, and facility capabilities allocate patients across intervention types. Understanding these divides helps stakeholders anticipate where procedural volume and capital investment will concentrate.
Product Type:
FDA 510(k) pathways favor pneumatic dilation devices with established predicate comparisons, while novel surgical platforms face lengthier premarket review cycles that segment commercialization timelines.
- Surgery:Laparoscopic Heller myotomy and peroral endoscopic myotomy deliver definitive sphincter disruption through myotomy. Demand clusters in United States tertiary centers where fellowship-trained gastroenterologists displace traditional surgical volume. Reimbursement parity with laparoscopic alternatives accelerates hospital adoption of endoscopic approaches.
- Pneumatic Balloon:Graded pneumatic dilation using polyethylene balloons achieves sphincter disruption through controlled radial force. Germany and Japan maintain high procedural penetration where repeat dilation protocols are embedded in clinical guidelines. Device durability concerns limit retreatment intervals.
- Medication:Calcium channel blockers and nitrates provide temporary symptom relief through smooth muscle relaxation. Generic pricing compresses margins for pharmacologic management tier.
- Botulinum Toxin:Endoscopically injected neurotoxin induces temporary sphincter paralysis. Bridge therapy demand persists for elderly surgical candidates in Japanese geriatric populations.
Established volume favors Surgery; emerging adoption favors Pneumatic Balloon.
Delivery Mode:
Cost tiering separates capital-intensive endoscopic platforms from disposable injection therapies, with facility fee structures determining which modes hospitals prioritize.
- Endoscopic:Submucosal tunneling and myotomy visualization require dedicated electrosurgical platforms with integrated imaging. United States academic centers lead training capacity expansion.
- Injectable:Botulinum toxin administration through standard endoscopes demands minimal capital outlay. Clinics in Germany leverage this for rapid patient throughput.
- Oral:Pharmacologic agents bypass procedural infrastructure entirely. Home care substitution potential remains constrained by symptom recurrence rates.
- Transcatheter:Emerging catheter-based myotomy approaches access the sphincter through vascular or luminal routes. Early clinical validation concentrates in Japanese investigational sites.
Facility investment tilts toward Endoscopic; cost containment preserves Injectable share.
End User:
Credentialing requirements segment providers by procedural complexity, with hospital privileging boards restricting advanced endoscopy to designated specialists.
- Hospitals:Integrated operating suites and endoscopy units capture definitive surgical and procedural volume. United States health system consolidation reduces independent hospital purchasing autonomy.
- Clinics:Ambulatory endoscopy centers in Germany achieve pneumatic dilation throughput without inpatient infrastructure. Outpatient reimbursement differentials attract procedural migration.
- Research Institutions:Academic medical centers in Japan and the United States host training programs and device trials. Regulatory evidence generation concentrates at these sites.
- Home Care:Pharmacologic management with oral agents serves remote or immobilized patient populations. Monitoring limitations restrict this channel.
Definitive intervention concentrates in Hospitals; efficiency gains favor Clinics.
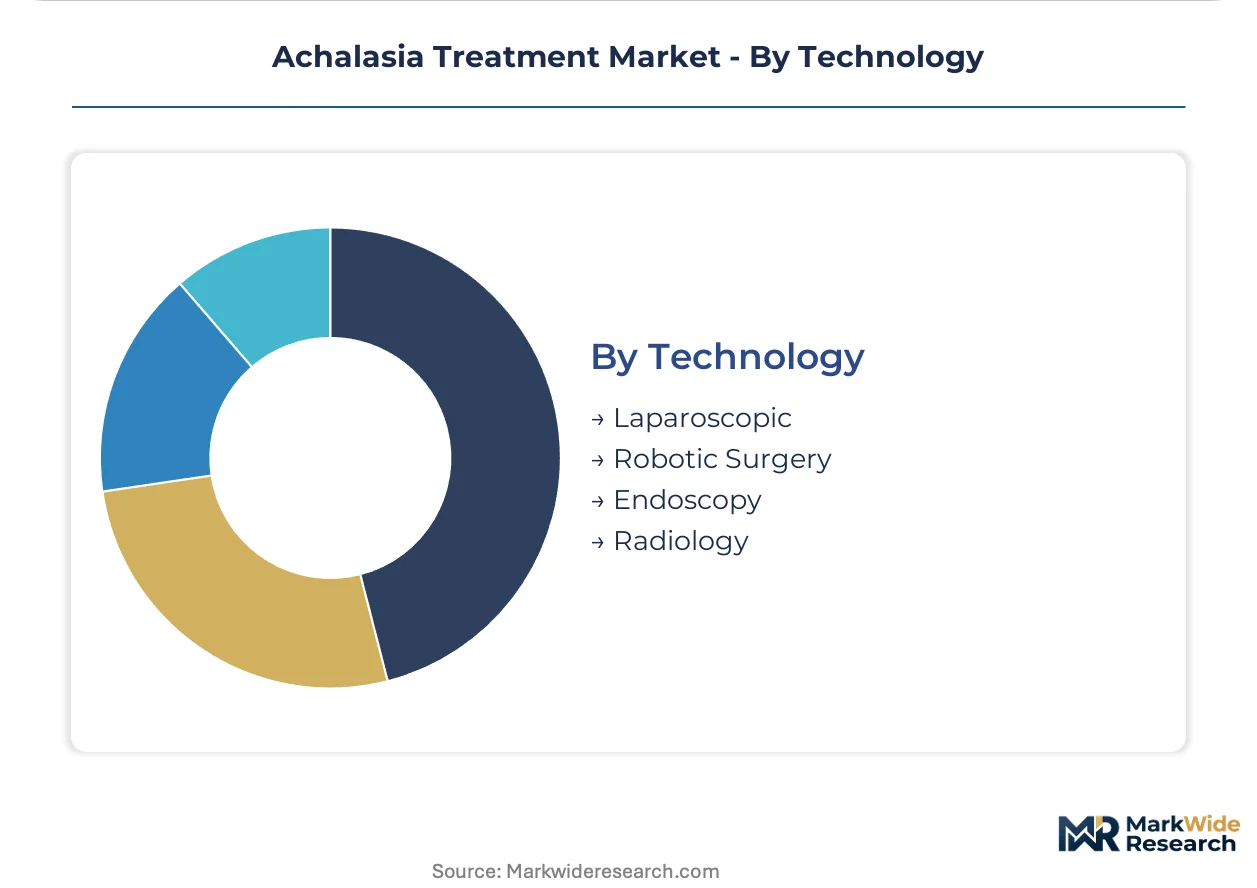
Technology:
Maturity curves separate decades-established laparoscopic techniques from robotic platforms still accumulating clinical evidence for payer coverage.
- Endoscopy:Peroral endoscopic myotomy platforms integrate electrocautery, CO2 insufflation, and high-definition imaging. Training program expansion in the United States broadens qualified provider pools.
- Laparoscopic:Heller myotomy with Dor fundoplication remains the surgical reference standard. Established reimbursement codes preserve volume in German hospital systems.
- Robotic Surgery:Da Vinci systems enable precision suturing in redo operations and complex anatomy. Capital cost and service contracts limit penetration beyond academic centers.
- Radiology:Fluoroscopic guidance supports pneumatic dilation positioning and complication detection. Image quality requirements sustain hardware replacement cycles.
Clinical evidence depth favors Laparoscopic; capability expansion favors Endoscopy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor procedural innovation in the United States, while EMA MDR compliance and Japan's PMDA reviews shape parallel commercialization tracks across distinct regulatory environments.
United States
Tertiary referral centers in Boston and Houston drive peroral endoscopic myotomy volume as fellowship programs expand hands-on training curricula. CMS coverage decisions for outpatient endoscopic procedures influence hospital capital commitment to dedicated platforms. The Cleveland Clinic and Mayo Clinic anchor clinical evidence generation for device manufacturers seeking predicate comparisons.
Germany
Bavarian academic medical centers maintain high penetration of laparoscopic Heller myotomy where established reimbursement codes preserve surgical volume. EU MDR compliance requirements extend review timelines for pneumatic dilation devices entering European markets. The North Rhine-Westphalia hospital network concentrates purchasing decisions under integrated delivery frameworks.
Japan
Aging demographics expand the addressable patient base for both surgical and pharmacologic interventions among elderly populations. PMDA review layers add distinct regulatory hurdles for endoscopic myotomy devices entering domestic markets. Tokyo and Osaka metropolitan clusters host training programs that accelerate technique dissemination beyond traditional academic corridors.
United Kingdom
NHS England referral pathways concentrate achalasia diagnosis and treatment in designated esophageal motility centers. NICE technology appraisals shape coverage decisions for robotic surgical platforms and advanced endoscopic equipment. London teaching hospitals generate real-world evidence supporting minimally invasive procedure adoption.
France
ANSM oversight governs market authorization for botulinum toxin formulations used in bridge therapy protocols. Parisian academic hospitals participate in multi-center trials comparing endoscopic and surgical approaches. The Auvergne-Rhône-Alpes region develops teleproctoring infrastructure to extend specialist expertise to peripheral centers.
Achalasia Treatment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the achalasia treatment market. The vendor base separates into three functional tiers: diversified medical device conglomerates with integrated endoscopic platforms, pharmaceutical manufacturers with neurotoxin or generic portfolios, and specialized surgical robotics developers. Consolidation pressures favor larger manufacturers with dedicated regulatory affairs infrastructure capable of navigating extended EMA MDR review cycles. Strategic moves concentrate on surgeon education program expansion and hospital system contracting consolidation.
Within the diversified device tier, Medtronic represents integrated platform capabilities, while AbbVie anchors the pharmacologic segment through neurotoxin expertise. Among generic pharmaceutical suppliers, Pfizer exemplifies cost-positioned medical management alternatives that occupy the pharmacologic tier against procedural interventions.
| Leading Market Players |
|---|
| Bausch Health |
| Pfizer |
| Merz Pharma |
| Accord HealthCare |
| AdvaCare Pharma |
| Zydus Pharmaceuticals |
| AbbVie |
| Ipsen Pharma |
| Medtronic |
| Others |
Value Network & Pricing Analysis
Capital intensity in endoscopic platform manufacturing creates steep scale thresholds that concentrate production among multi-product device conglomerates and simultaneously establish price floors for pneumatic dilation and myotomy systems. High fixed costs for ISO 13485-certified cleanroom facilities and dedicated electrosurgical component lines limit viable supplier pools, granting incumbent manufacturers pricing power in contracted hospital system sales while compressing margins for smaller entrants competing on disposable accessories.
Pricing Analysis
United States hospital systems pay 40-60% premiums over German academic medical centers for equivalent peroral endoscopic myotomy platforms due to bundled training and service contract structures. Pricing stratifies across premium robotic surgical tiers, standard laparoscopic device tiers, and economy pneumatic balloon tiers, with differentiation driven by FDA 510(k) predicate status and after-sales technical support depth. Pricing pressure stems from CMS reimbursement uncertainty for outpatient endoscopic procedures, which dampens capital commitment and extends sales cycles. Cost-sensitive community hospitals in integrated delivery networks exhibit highest price sensitivity, while United States tertiary referral centers prioritize capability over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes have elevated inbound logistics costs for electrosurgical generators and high-definition imaging sensors sourced from Japanese and South Korean component manufacturers. Finished device assembly concentrates in the United States, Germany, and Ireland, with raw material dependencies on medical-grade polymers from Belgium, precision motors from Switzerland, and semiconductor imaging chips from Taiwan. Single-source vulnerability pervades the submucosal tunneling knife supply tier, where two German specialty manufacturers control global output. Distribution runs through hospital procurement committees and group purchasing organizations that consolidate vendor relationships under multi-year enterprise agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent device manufacturers face substitution pressure from pharmaceutical bridge therapies and generic calcium channel blockers that delay procedural conversion, requiring defensive positioning around clinical outcome differentiation and surgeon education lock-in.
For Market Incumbents: Secure exclusive training program partnerships with United States gastroenterology fellowship directors to create credentialing dependencies that lock out competing endoscopic platforms. Deepen backward integration into electrosurgical generator manufacturing to reduce exposure to Taiwanese semiconductor supply volatility and capture margin from high-value subsystems.
For New Entrants and Emerging Players: FDA 510(k) streamlined review pathways for pneumatic dilation devices with established predicate comparisons offer the fastest regulatory on-ramp for capital-constrained entrants. Target ambulatory surgery centers in German outpatient networks where reimbursement differentials favor efficiency-focused disposable platforms over capital-intensive robotic systems. Pursue teleproctoring infrastructure partnerships as a channel innovation that accelerates adoption without traditional academic training investments.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among endoscopic platform manufacturers with captive service contracts and disposable accessory streams, positioning these archetypes for superior cash flow stability across the analysis window. Acquisition targets should display established ISO 13485 quality systems and notified body relationships that compress EMA MDR compliance timelines. Monitor CMS national coverage determinations for peroral endoscopic myotomy as the critical inflection signal for outpatient procedural volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Integrated delivery network contracting in United States metropolitan markets reduces independent purchasing entities by half. |
| Surgeon Education Program Expansion | Fellowship-trained gastroenterologists displace traditional surgical volume in tertiary referral centers. |
| FDA 510(k) Streamlined Submission | Expedited clearance pathways accelerate commercialization timelines for pneumatic dilation devices entering hospital systems. |
| Teleproctoring Infrastructure Deployment | Remote surgical mentorship networks extend specialist expertise beyond traditional academic training corridors. |
| CE Marking Pathway Investment | Notified body backlog management favors manufacturers with dedicated EMA MDR regulatory affairs infrastructure. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with gastroenterologists, thoracic surgeons, hospital purchasing committee members, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EMA MDR submission databases, CMS Medicare reimbursement schedules, and hospital procurement transaction records. Bottom-up procedure volume estimates triangulated against top-down market sizing from device manufacturer revenue disclosures and national health system procedure registries.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning treatment modality, delivery mode, end-user facility type, and technology platform maturity. CAGRs derived from logistic diffusion curves fitted to peroral endoscopic myotomy adoption patterns, adjusted for fellowship training capacity constraints and evolving payer coverage decisions. Forecast inputs incorporated regulatory review timeline distributions and hospital capital expenditure cycle phasing.
Underlying assumptions cover stable CMS reimbursement parity between endoscopic and laparoscopic approaches, with deviation risk concentrated in gastroenterology fellowship program expansion rates and EMA MDR notified body processing backlogs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Otoplasty Market
Medical Treatment
Tetanus Treatment Market
Medical Treatment
Gangrene Market
Medical Treatment
Systemic Sclerosis Treatment Market
Medical Treatment
Andersen Tawil Syndrome Treatment Market
Medical Treatment
Liver Fluke Treatment Market
Medical Treatment
Stereotactic Radiation Therapy Market
Medical Treatment
Yellow Fever Treatment Market
Medical Treatment
Severe Asthma Treatment Market
Medical Treatment
Uterine Fibroid Treatment Drugs Market
Medical Treatment
Lysosomal Acid Lipase (LAL) Deficiency Treatment Market
Medical Treatment
Surgical Procedures Volume Market
Medical Treatment
Migraine Treatment Market
Medical Treatment
Seropositive Rheumatoid Arthritis Treatment Market
Medical Treatment
Global Leukapheresis Market
Medical Treatment
Ascites Market