
 Perfusion Systems Market | 2026-2036
Perfusion Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Perfusion Systems Market Intelligence
The gap between conventional cardiopulmonary bypass platforms and integrated organ-specific perfusion technologies is narrowing, forcing manufacturers to unify mechanical circulatory support with real-time metabolic monitoring. Getinge leverages its critical care portfolio to anchor hospital-wide perfusion workflows across Nordic and North American accounts. Medtronic sustains technology leadership through deep R&D investment in minimally invasive perfusion architectures. TransMedics specializes in portable normothermic perfusion, competing directly with static cold storage protocols for organ transport.
Perfusion systems are electromechanical platforms that circulate oxygenated blood or preservation solutions through isolated organs, tissues, or the entire body during surgical procedures or transport, typically operating at flow rates of 0.5 to 6.0 liters per minute with integrated heat exchangers maintaining temperatures between 4°C and 37°C depending on clinical indication. Their primary purpose is to sustain viable physiology when natural circulation is interrupted or when organs require ex-vivo metabolic support. Heart-lung machines still occupy the largest installed base in cardiac surgery, though margin pools are shifting toward organ preservation devices as transplant volumes expand. Extracorporeal membrane oxygenation represents the fastest-growing product category, with intensive care units driving replacement cycles and geographic expansion into secondary hospitals.
The FDA enforces premarket notification and quality system regulation for perfusion devices under 21 CFR Part 870, while the EU MDR requires notified body certification and post-market surveillance for all extracorporeal circulation systems placed on the European market. Japan's PMDA maintains distinct clinical trial requirements for novel perfusion platforms, creating staggered launch timelines across major jurisdictions. Stakeholders must monitor evolving reimbursement codes for ECMO and normothermic perfusion, as payer decisions will determine whether these modalities penetrate community hospitals or remain concentrated at academic transplant centers.
Market Dynamics
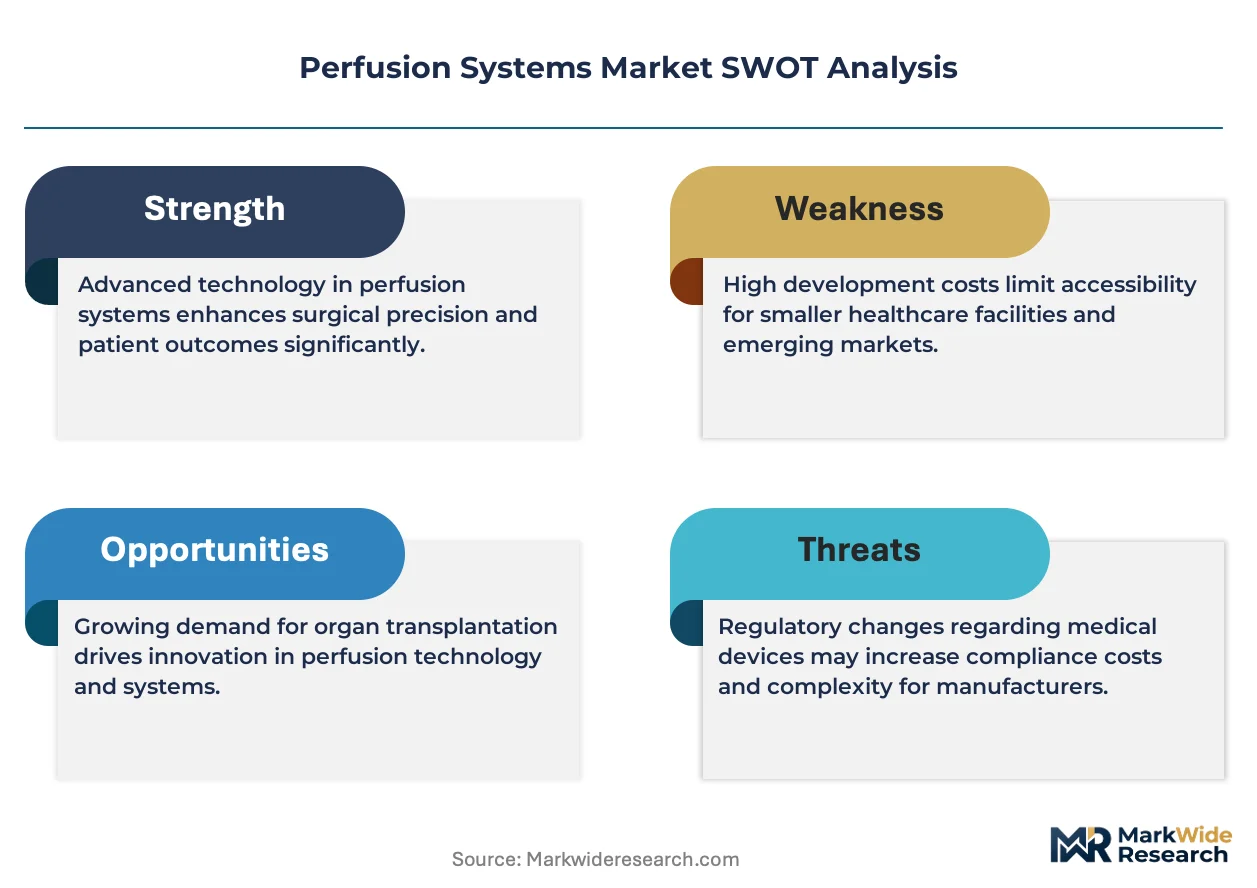
The EU Medical Device Regulation is compressing certification timelines for extracorporeal circulation systems while transplant volumes accelerate demand for organ-specific perfusion platforms, forcing manufacturers to consolidate hardware and metabolic monitoring capabilities.
Growth Catalysts
- ECMO Adoption in Community ICUs:Intensive care units at secondary hospitals are acquiring membrane oxygenation systems for respiratory failure management, expanding the installed base beyond academic centers.
- REACH Substance Restrictions:European chemical safety rules on phthalates and sterilants are accelerating material transitions in pump tubing and oxygenator housings, creating upgrade cycles for compliant hardware.
- Normothermic Transport Protocols:Specialized transplant logistics providers are replacing static cold storage with portable perfusion units for extended organ viability windows.
Market Restraints
- Polymer Supply Concentration:Medical-grade silicone and polycarbonate production clusters in Germany and Japan create vulnerability for oxygenator membrane and pump housing supply.
- PMDA Clinical Trial Requirements:Japan's pharmaceutical and medical device agency mandates extended local validation studies for novel perfusion architectures, delaying revenue recognition.
- Capital Equipment Replacement Cycles:Cardiopulmonary bypass machines operate on 10-15 year depreciation schedules, constraining upgrade velocity at budget-constrained hospitals.
Strategic Opportunities
- Pediatric ECMO Underpenetration:Neonatal and pediatric intensive care units in India and Brazil lack dedicated miniaturized circuits sized for low-flow applications.
- IRA Hospital Infrastructure Funding:US inflation Reduction Act allocations for rural healthcare facilities include provisions for critical care equipment procurement.
- Perfusion-Monitoring Convergence:Integration of near-infrared spectroscopy and microdialysis sensors into disposable circuits enables real-time metabolic feedback during isolated organ perfusion.
Industry Challenges
- Perfusionist Workforce Scarcity:Certified clinical perfusionists require 2-4 years of specialized training, with US program graduation rates failing to match ECMO service expansion.
- Legacy System Integration:New organ preservation devices must interface with institutional IT infrastructure and electronic health record systems built around cardiopulmonary bypass documentation protocols.
- Notified Body Capacity Bottlenecks:EU MDR designation shortages are extending technical documentation review timelines for Class III extracorporeal devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Perfusion Systems Market |
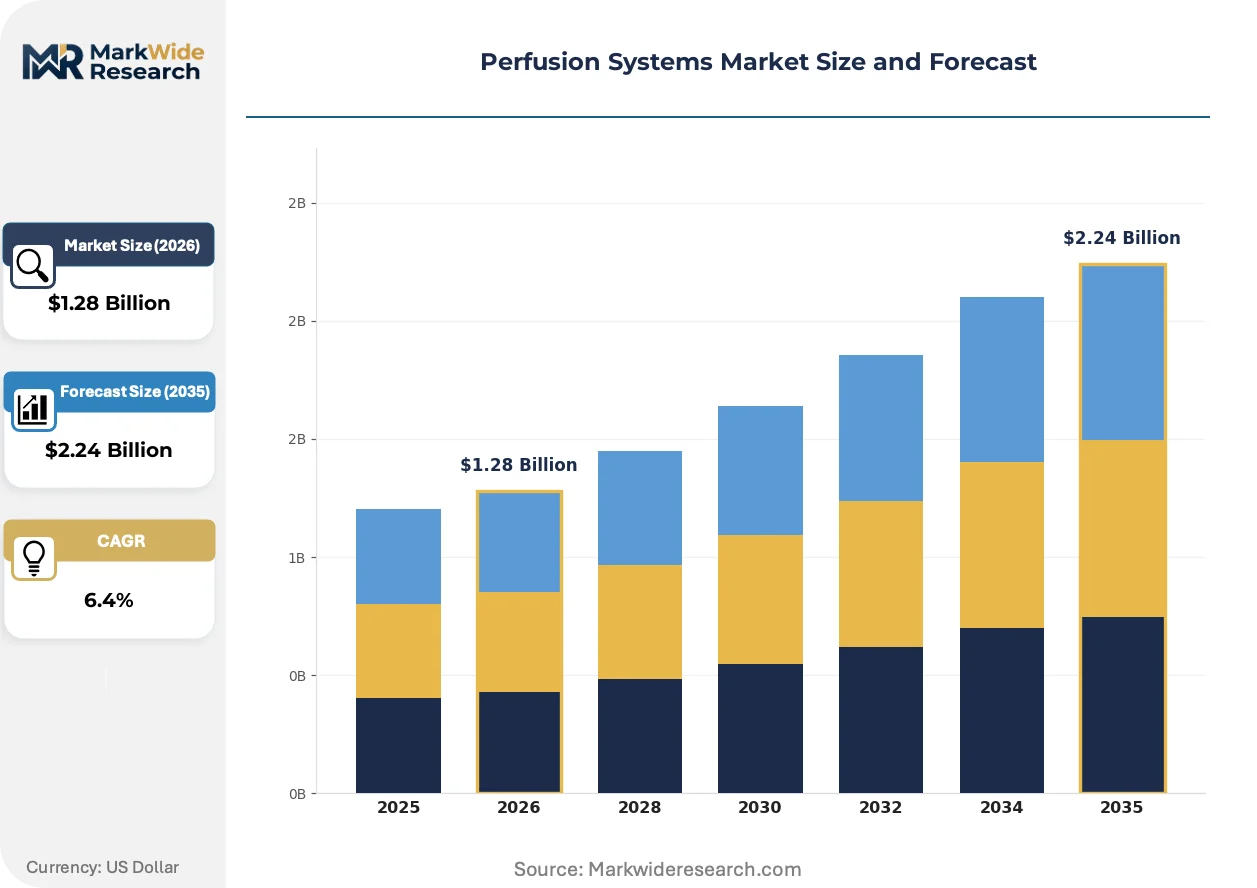
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heart-Lung Machines, Organ Preservation Devices, Extracorporeal Membrane Oxygenation, Apheresis Machines, Blood Purification Systems Application: Cardiac Surgery, Organ Transplantation, Blood Treatment, Critical Care, Research Laboratories End User: Cardiothoracic Centers, Transplant Clinics, Dialysis Centers, Intensive Care Units, Biomedical Research Facilities Deployment: Hospital Based, Ambulatory Care, Mobile Units, Specialty Clinics, Research Institutes |
| Companies Covered | Getinge, Medtronic, LivaNova, Terumo Corporation, XVIVO Perfusion, TransMedics, Nipro Corporation, Merck KGaA, Repligen Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perfusion Systems Market Strategic Shifts & Innovations
Perfusion technology is converging around real-time metabolic feedback and disposable circuit miniaturization, with regulatory pressure and procurement centralization accelerating hardware-software integration.
Sensor-embedded oxygenators are digitizing hemodynamic monitoring by integrating fiber-optic pressure transducers and inline blood gas analyzers directly into disposable circuits. Academic transplant centers are piloting these platforms for ex-vivo liver and heart perfusion. This architecture is digitizing the gap between mechanical circulatory support and diagnostic imaging, compressing the feedback loop between physiological change and clinical response.
MDR post-market surveillance requirements are mandating systematic collection of clinical performance data for all extracorporeal circulation systems sold in Europe. Manufacturers must now maintain electronic systems for traceability and periodic safety reporting. High-risk organ preservation devices face the strictest scrutiny, with notified bodies demanding extended follow-up protocols for normothermic perfusion outcomes.
Hospital procurement departments are consolidating perfusion equipment purchasing through multi-year managed service agreements rather than capital acquisition. Academic medical centers in Germany and the Netherlands are leading this transition, bundling device placement with disposable supply and preventive maintenance. This model is most visible in cardiac surgery programs where case volume predictability supports outcome-based contracting structures.
Perfusion Systems Market Segmentation
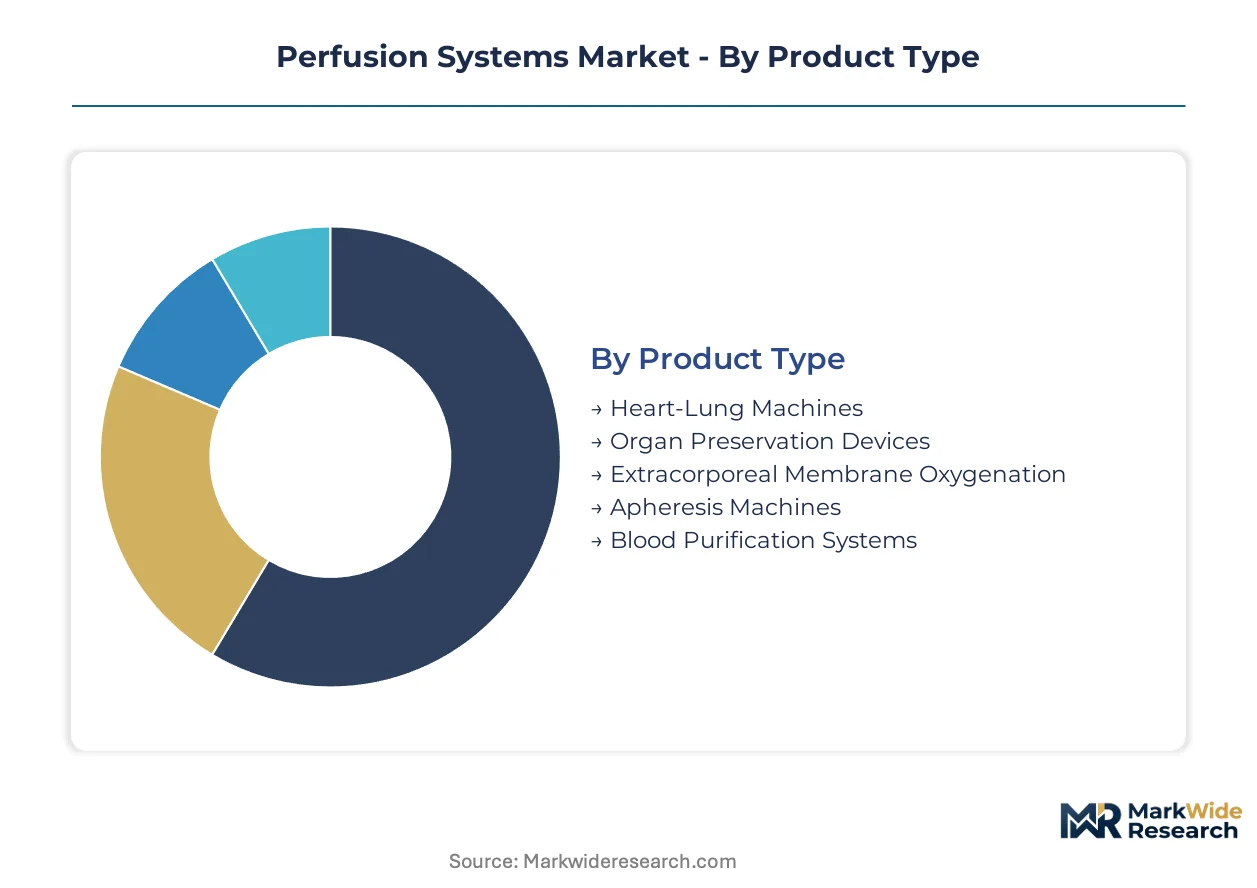
Perfusion systems serve heterogeneous clinical workflows ranging from acute intraoperative support to extended organ transport, making segment-specific configuration and service protocols essential for manufacturer competitiveness. Each category reflects distinct capital intensity, regulatory pathways, and aftermarket revenue potential that shape portfolio prioritization.
Product Type:
After-sales-service intensity varies sharply across hardware categories, with membrane oxygenation systems requiring 24/7 field engineering support while organ preservation devices demand specialized training and disposable replenishment logistics.
- Heart-Lung Machines:Electromechanical platforms integrating roller or centrifugal pumps with oxygenators and heat exchangers for intraoperative cardiopulmonary bypass. Demand clusters at German university hospital networks where cardiac surgery volumes sustain dedicated perfusionist teams and preventive maintenance contracts. Service revenue often exceeds hardware margins over the 10-15 year equipment lifecycle.
- Organ Preservation Devices:Portable or stationary systems maintaining normothermic or hypothermic perfusion during organ transport and ex-vivo assessment. Transplant logistics providers in the United States and specialized retrieval organizations in France are replacing static cold storage, driven by extended viability windows for marginal donor organs. These systems generate recurring revenue through single-use perfusate circuits and metabolic monitoring sensors.
- Extracorporeal Membrane Oxygenation:Circuit configurations for respiratory and cardiac failure management in intensive care settings.
- Apheresis Machines:Automated cell separation platforms for therapeutic plasma exchange and stem cell collection.
- Blood Purification Systems:Continuous renal replacement and adsorption technologies for toxin removal in critical illness.
By volume, Heart-Lung Machines leads. By growth pace, Organ Preservation Devices is ahead.
Application:
Cost tier stratification separates high-acuity surgical applications with bundled reimbursement from research and diagnostic segments with capital-constrained procurement.
- Cardiac Surgery:Intraoperative circulatory support for coronary artery bypass grafting, valve replacement, and aortic procedures. German and Dutch cardiothoracic centers maintain the highest procedure density in Europe, with perfusion platforms integrated into hybrid operating room infrastructure. Reimbursement stability through diagnosis-related group coding supports premium equipment placement.
- Organ Transplantation:Perfusion for donor organ recovery, transport, and ex-vivo functional assessment prior to implantation. United States transplant centers and French agence de biomédecine-coordinated networks are expanding normothermic machine perfusion for liver and heart allografts, displacing static cold storage protocols. Regulatory scrutiny from FDA and ANSM intensifies with novel preservation claims.
- Blood Treatment:Therapeutic apheresis and immunomodulation procedures.
- Critical Care:ECMO and hemodynamic support for respiratory and circulatory failure.
- Research Laboratories:Ex-vivo organ perfusion for pharmacokinetic and toxicology studies.
Cardiac Surgery commands the largest installed base. Organ Transplantation shows the steepest expansion trajectory.
End User:
Customer type determines purchasing authority, with academic medical centers leveraging centralized procurement while independent clinics negotiate device placement through disposable supply agreements.
- Cardiothoracic Centers:High-volume surgical programs with dedicated perfusion departments and in-house biomedical engineering support. University hospital networks in Germany and the Netherlands consolidate purchasing through multi-year managed service agreements bundling equipment, disposables, and preventive maintenance. These accounts prioritize interoperability with existing operating room infrastructure.
- Transplant Clinics:Specialized retrieval and implantation facilities requiring portable perfusion for organ transport logistics. United States organ procurement organizations and French transplant coordination centers are acquiring mobile normothermic systems to extend donor radius and reduce ischemia time. Procurement decisions hinge on perfusate supply chain reliability and 24/7 technical support availability.
- Dialysis Centers:Outpatient facilities for chronic renal replacement therapy.
- Intensive Care Units:Secondary and tertiary hospitals expanding ECMO capability for respiratory failure.
- Biomedical Research Facilities:Academic and contract research organizations utilizing isolated organ perfusion for drug development.
Cardiothoracic Centers dominate capital expenditure. Transplant Clinics are gaining share fastest.
Deployment:
Geography of deployment shapes regulatory jurisdiction and service logistics, with mobile configurations requiring multi-country certification and rapid-response field engineering networks.
- Hospital Based:Fixed installations within integrated health systems with centralized biomedical engineering and infection control protocols. German Krankenhaus networks and United States academic medical centers standardize on single-vendor perfusion platforms to simplify training and spare parts inventory. These deployments anchor long-term disposable supply contracts.
- Ambulatory Care:Outpatient surgical and infusion centers with limited perfusion support for apheresis and minor procedures. French chirurgie ambulatoire clinics and United States ambulatory surgery centers prioritize compact, transportable systems with simplified operator interfaces. Capital constraints favor leasing and equipment-as-a-service arrangements.
- Mobile Units:Vehicle-mounted or portable systems for organ retrieval and emergency ECMO deployment.
- Specialty Clinics:Independent dialysis and apheresis centers with focused therapeutic offerings.
- Research Institutes:Non-clinical facilities with customized perfusion configurations for experimental protocols.
Hospital Based deployment holds the largest equipment base. Mobile Units are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial perfusion systems trade surplus driven by advanced manufacturing of membrane oxygenators and portable preservation platforms, while Germany and Japan remain net importers of high-end cardiac surgery hardware despite strong domestic production bases.
United States
Academic transplant centers in Pittsburgh and Houston are expanding normothermic machine perfusion programs for extended-criteria donor organs. The FDA's premarket notification pathway under 21 CFR Part 870 shapes device launch timelines, with recent guidance emphasizing real-time metabolic monitoring integration. Boston's medical device corridor anchors ECMO circuit manufacturing, with specialized firms supplying oxygenator membranes to domestic and international accounts.
Germany
University hospital networks in Berlin and Munich maintain Europe's highest density of cardiopulmonary bypass procedures, driving demand for integrated perfusion platforms. The EU MDR's tightened quality system requirements for Class III extracorporeal devices are compressing certification timelines for manufacturers serving German accounts. The Baden-Württemberg industrial cluster around Freiburg and Stuttgart concentrates precision pump component fabrication for European OEM supply chains.
Japan
Tokyo and Osaka metropolitan area hospitals are adopting membrane oxygenation systems for respiratory failure management in aging patient populations. PMDA mandates extended local clinical validation studies for novel perfusion architectures, creating staggered launch timelines compared to US and European markets. The Kansai region's biomedical manufacturing base produces heat exchanger components and specialized tubing for domestic device assemblers.
France
The Agence de la biomédecine coordinates expanding national protocols for normothermic liver and heart perfusion, displacing static cold storage in retrieval logistics. ANSM post-market surveillance requirements align with EU MDR frameworks, intensifying scrutiny of high-risk organ preservation claims. The Paris-Saclay hospital cluster pilots sensor-embedded disposable circuits for real-time metabolic feedback during ex-vivo organ assessment.
United Kingdom
NHS England's specialized commissioning frameworks concentrate perfusion service provision at designated cardiothoracic centers in London, Manchester, and Birmingham. MHRA recognition of EU MDR certificates facilitates parallel market access, though divergence risks are monitored post-Brexit. The Cambridge-Oxford medical technology corridor hosts development programs for miniaturized pediatric ECMO circuits addressing underpenetrated neonatal intensive care segments.
Perfusion Systems Market Key Industry Players
On the supply side, the industry is consolidating around integrated platform providers capable of bundling hardware, disposable circuits, and preventive maintenance services. The vendor base stratifies into three archetypes: diversified critical care conglomerates with hospital-wide workflow anchoring capabilities, specialized organ preservation technology firms competing on transport logistics innovation, and component-focused suppliers of oxygenator membranes and pump subsystems. Dominant competitive moves include multi-year managed service agreements replacing capital equipment sales, and backward integration into medical-grade polymer compounding to secure silicone and polycarbonate supply.
Among diversified critical care providers, Getinge and Medtronic occupy positions anchoring hospital-wide perfusion workflows across Nordic and North American accounts, while TransMedics exemplifies the specialized preservation technology archetype with portable normothermic systems competing directly against static cold storage protocols. These three firms represent distinct strategic postures within a market where technology leadership increasingly depends on unifying mechanical circulatory support with real-time metabolic monitoring capabilities.
| Leading Market Players |
|---|
| Getinge |
| Medtronic |
| LivaNova |
| Terumo Corporation |
| XVIVO Perfusion |
| TransMedics |
| Nipro Corporation |
| Merck KGaA |
| Repligen Corporation |
| Others |
Cost & Logistics Intelligence
Undercapacity in medical-grade silicone compounding across Baden-Württemberg is tightening input availability for oxygenator membrane production, compressing margins for disposable circuit manufacturers while elevating pricing leverage for polymer suppliers serving Class III device assemblers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that bundle hardware placement with disposable replenishment and preventive maintenance. Price differentiation separates FDA-cleared premium tiers from CE-marked standard configurations, with after-sales service intensity widening spreads between integrated platform providers and component specialists. Pricing pressure stems from REACH substance restrictions accelerating material transitions in pump tubing and oxygenator housings. Academic medical centers exhibit lowest price sensitivity due to bundled reimbursement stability, while ambulatory surgery centers face capital constraints favoring equipment-as-a-service arrangements.
Supply Chain Analysis
Contract manufacturing for precision pump components concentrates in Freiburg-Stuttgart industrial corridors and Kansai region fabrication facilities. Geographic supply concentration centers on Germany, Japan, and the United States for heat exchanger assemblies and specialized tubing. Raw material dependencies draw from medical-grade silicone, polycarbonate resins, and fiber-optic sensor substrates. Single-source vulnerability in silicone membrane supply creates exposure to polymer production disruptions. Distribution runs through hospital procurement departments consolidating multi-year managed service agreements with integrated critical care conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Static cold storage protocols for organ transport represent the substitution threat that portable normothermic perfusion platforms must displace to justify premium positioning and secure long-term revenue streams.
For Market Incumbents: Entrench technology leadership through backward integration into medical-grade polymer compounding and captive supply of silicone membranes for oxygenator production. Deepen hospital-wide workflow anchoring by unifying mechanical circulatory support platforms with real-time metabolic monitoring capabilities. Defend against specialized preservation technology firms by accelerating sensor-embedded disposable circuit development and securing multi-year managed service agreements at German university hospital networks. For New Entrants and Emerging Players: Establish a beachhead in pediatric ECMO segments where miniaturized circuits for low-flow applications remain underpenetrated across Indian and Brazilian neonatal intensive care units. Target transplant logistics providers replacing static cold storage with portable normothermic systems for extended-criteria donor organs. Pursue outcome-based contracting structures that align device placement with viability window improvements and reduced ischemia time. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across organ preservation device manufacturing as MDR post-market surveillance requirements mandate systematic clinical performance data collection and extended follow-up protocols. Long-term viability favors platforms capable of bundling hardware, disposable circuits, and software-enabled metabolic feedback. Acquisition targets should demonstrate notified body relationships and EU MDR technical documentation capabilities. Monitor notified body capacity bottlenecks as inflection indicator for certification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | Accelerated certification timelines for Class III extracorporeal devices hinge on notified body relationship depth. |
| Sensor-Embedded Disposable Circuit Development | Integration of near-infrared spectroscopy and microdialysis sensors compresses feedback loops between physiological change and clinical response. |
| Managed Service Agreement Expansion | German and Dutch academic medical centers are consolidating procurement through multi-year bundles replacing capital acquisition. |
| Pediatric ECMO Miniaturization Program | Neonatal and pediatric intensive care units in emerging markets lack dedicated low-flow circuit configurations. |
| Polymer Compounding Backward Integration | Captive supply of medical-grade silicone and polycarbonate secures oxygenator membrane and pump housing input availability. |
Research Approach
A spread of perspectives from perfusionist program directors, hospital purchasing committee members, biomedical engineering leads, and transplant logistics coordinators converged on the working assumptions. Primary interviews with GPO contracts managers and regulatory affairs specialists at extracorporeal device manufacturers were cross-referenced against secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement codes, and hospital procurement records. Bottom-up installed base modeling and top-down market sizing triangulated volume and value estimates across the analysis window.
Demand-supply balance framing anchored the analytical approach, with segmentation dimensions spanning product type, application workflow, end-user purchasing authority, and deployment geography. CAGRs were derived from procedure volume trajectories, replacement cycle dynamics, and penetration rate assumptions for normothermic perfusion protocols. Industry-specific forecast inputs incorporated perfusionist workforce graduation rates, transplant center expansion plans, and REACH substance restriction implementation timelines.
Sensitivities concentrate around notified body capacity constraints extending EU MDR certification timelines, polymer supply disruptions affecting oxygenator membrane production, and payer reimbursement decisions determining ECMO penetration into community hospitals. Quarterly review of transplant volume data, notified body designation announcements, and REACH regulatory updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Drug Eluting Stent (DES) Market
Cardiovascular Devices
Normal Balloon Catheter Market
Cardiovascular Devices
Argentina Cardiovascular Devices Market
Cardiovascular Devices
Cerebral Vascular Stent Market
Cardiovascular Devices
Neuroendovascular Coil Market
Cardiovascular Devices
Atrial Fibrillation (AF) Ablation Market
Cardiovascular Devices
Heart Beat Irregularity Detection Device Market
Cardiovascular Devices
Peripheral Intravenous Catheters Market
Cardiovascular Devices
Global 3D Vascular Ultrasound Imaging Market
Cardiovascular Devices
Global Coil Wound Devices Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Tricuspid Valve Repair Market
Cardiovascular Devices
Patient-Controlled Injectors Market
Cardiovascular Devices
Vascular Screening Market
Cardiovascular Devices
Mobile Stroke Unit (MSTU) Market
Cardiovascular Devices
Ischemic Stroke Aspiration Systems Market