
 Heart Beat Irregularity Detection Device Market | 2026-2036
Heart Beat Irregularity Detection Device Market Size, Share, and Industry Trends Forecast 2026-2036
Heart Beat Irregularity Detection Device Market Foresight
Modular sensor-and-software bundling is broadening buyer choice across cardiac monitoring portfolios. Medtronic plc leverages its implantable device pipeline to anchor high-acuity hospital contracts. Abbott Laboratories sustains competitive pressure through wearable patch specialization. iRhythm Technologies, Inc. differentiates via cloud-connected diagnostic workflows that reduce clinician interpretation burden.
Heart beat irregularity detection devices integrate biosignal acquisition hardware with algorithmic analysis engines to flag arrhythmias including atrial fibrillation, ventricular tachycardia, and bradycardia episodes; photoplethysmography wearables now achieve clinical-grade pulse waveform resolution previously restricted to multi-lead systems. Electrocardiogram-based wearable monitors occupy the largest revenue pool as ambulatory prescribing expands, while artificial intelligence-enabled analysis layers command premium pricing through automated rhythm classification that reduces cardiologist review time. Holter monitors retain stable demand in medicolegal and post-ablation monitoring protocols where continuous multi-day recording remains non-negotiable.
FDA premarket notification pathways and CE marking under the EU MDR govern hardware safety and algorithm validation requirements for arrhythmia detection claims, with FDA breakthrough device designations accelerating review timelines for AI-native entrants. The country's national pharmaceutical regulator in Japan, the PMDA, imposes additional local clinical data requirements that filter market access for foreign manufacturers. Stakeholders must monitor evolving reimbursement codes for remote physiological monitoring as payer decisions will determine whether home-based detection scales beyond early-adopter health systems.
Market Dynamics
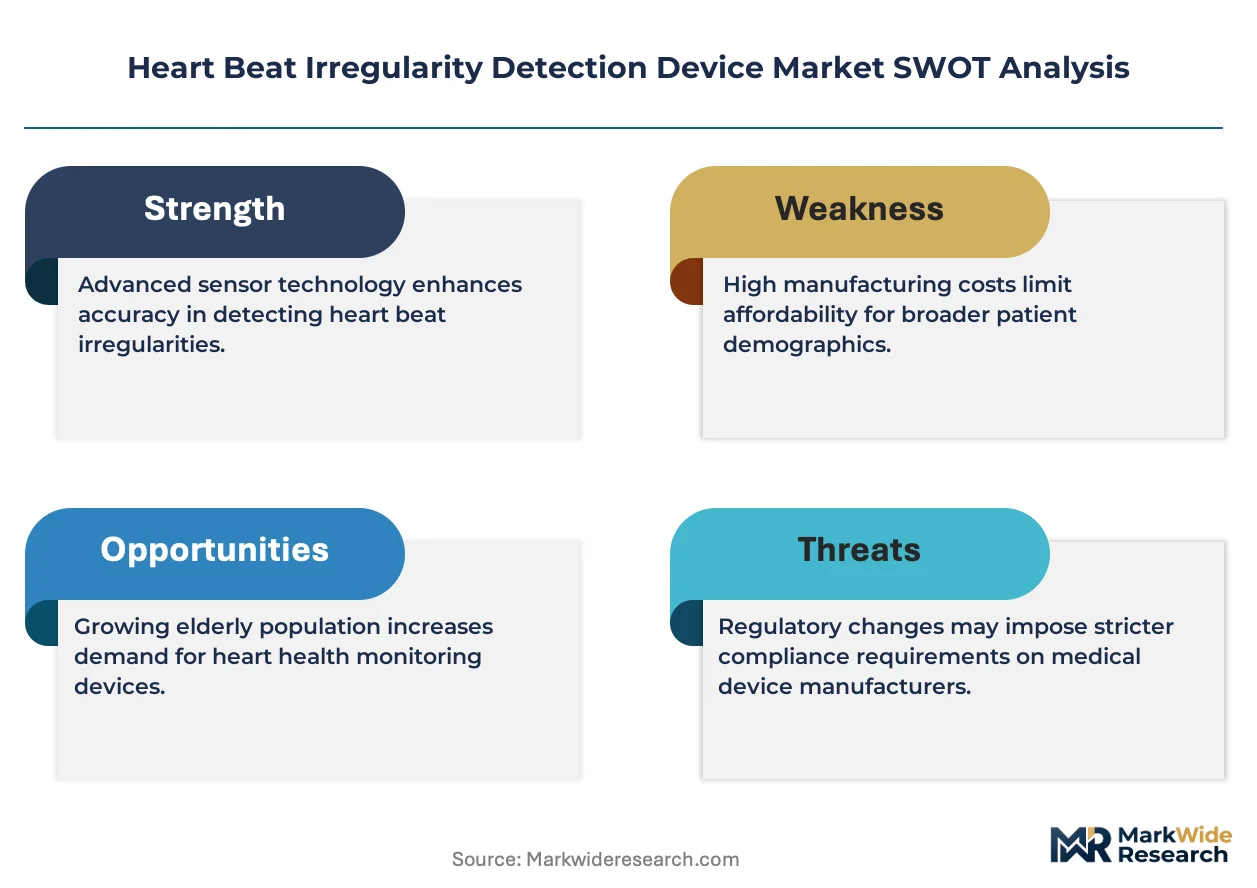
FDA breakthrough device designations are compressing review timelines for AI-native entrants while hospital systems simultaneously expand remote patient monitoring programs, creating dual pressure on hardware-software bundling economics.
Growth Catalysts
- Remote patient monitoring expansion:Hospital systems in the United States are scaling ambulatory cardiac programs that prescribe wearable ECG monitors for post-discharge surveillance, embedding devices into value-based care contracts.
- CE marking under EU MDR:Streamlined conformity assessment pathways for Class IIa diagnostic software are accelerating European market entry for algorithm-based arrhythmia detection systems.
- Photoplethysmography resolution advances:Optical sensor miniaturization now delivers clinical-grade pulse waveform fidelity previously restricted to multi-lead systems, enabling consumer-accessible form factors.
Market Restraints
- Specialized semiconductor supply concentration:Discrete analog front-end components for biosignal acquisition concentrate among a limited supplier base in Taiwan and South Korea, exposing device manufacturers to allocation risk.
- PMDA local clinical data requirements:Japan's national pharmaceutical regulator mandates domestic trial evidence for algorithm validation, filtering market access for foreign manufacturers without Japanese development partners.
- Holter monitor substitution ceiling:Continuous multi-day recording protocols in medicolegal and post-ablation monitoring resist displacement by patch-based intermittent systems due to evidentiary standards.
Strategic Opportunities
- Germany's DiGA fast-track pathway:The national reimbursement framework for digital health applications creates expedited market access for CE-marked diagnostic algorithms prescribed by statutory health insurers.
- AI-enabled automated rhythm classification:Machine learning inference at the edge is unifying biosignal acquisition and real-time analysis within single wearable units, eliminating cloud latency for critical arrhythmia alerts.
- Direct-to-employer contracting:Self-insured corporations in the United States are purchasing population-scale cardiac screening programs that bypass traditional hospital procurement channels.
Industry Challenges
- Cardiac electrophysiologist interpretation bottleneck:Automated rhythm classification reduces review burden but requires specialized clinician validation for ambiguous waveforms, constraining scalable deployment.
- Algorithm retraining cadence:FDA premarket notification pathways mandate locked algorithm versions for cleared devices, complicating continuous learning updates that improve detection accuracy over time.
- Multi-jurisdiction quality management system complexity:Simultaneous compliance with FDA 21 CFR Part 820, EU MDR Annex IX, and PMDA Ministerial Ordinance 169 imposes documentation overhead on lean development teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heart Beat Irregularity Detection Device Market |
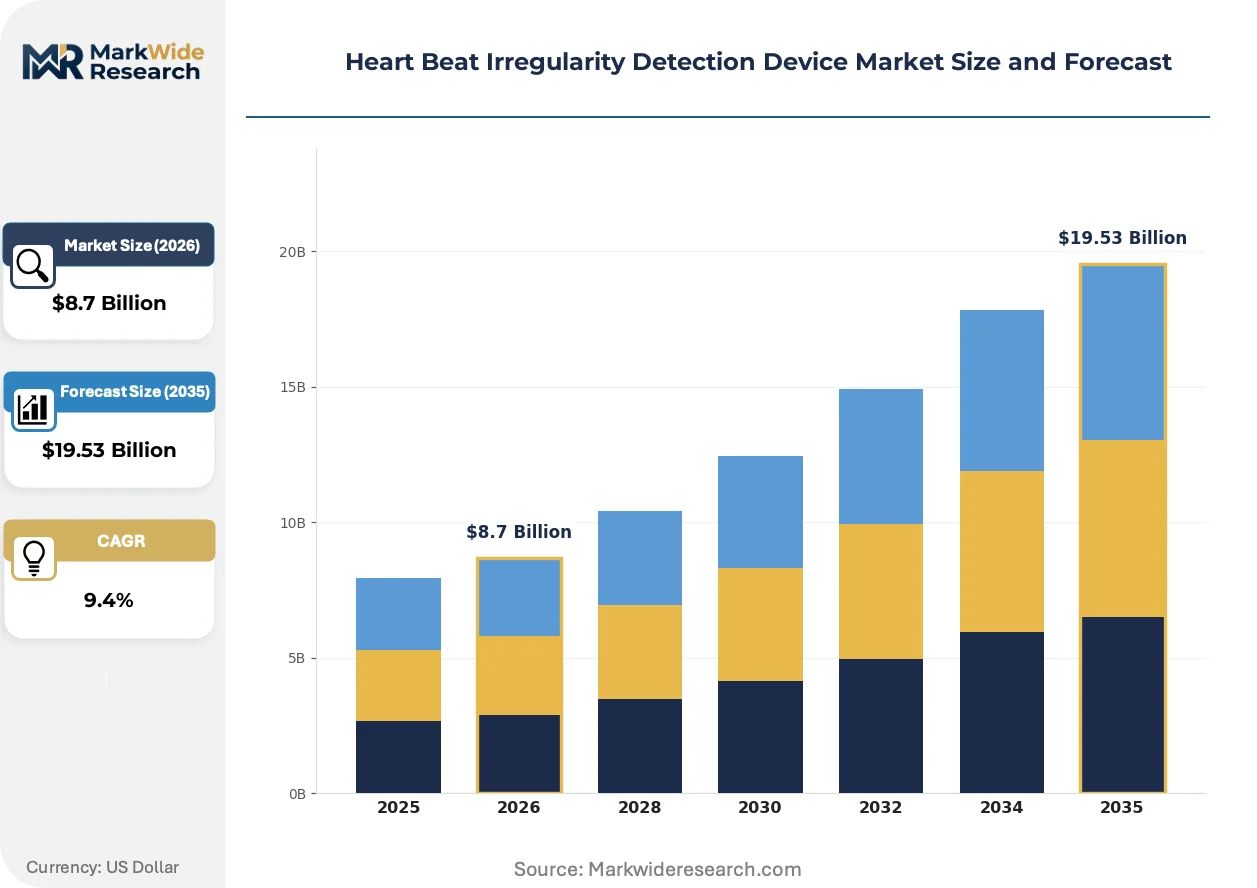
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Monitors, Implantable Devices, Smartphone Apps, Holter Monitors Technology: Electrocardiogram, Photoplethysmography, Ultrasound, Artificial Intelligence End User: Home Care, Hospitals, Outpatient Clinics, Telehealth Services Application: Cardiology, Emergency Medicine, Home Health Monitoring, Sports Medicine |
| Companies Covered | Medtronic plc, Abbott Laboratories, Boston Scientific Corporation, Koninklijke Philips N.V., GE Healthcare, iRhythm Technologies, Inc., Biotronik, Nihon Kohden Corporation, AliveCor, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heart Beat Irregularity Detection Device Market Shifts & Advancements
Algorithm-hardware co-design is collapsing the traditional separation between biosignal acquisition and diagnostic interpretation, compressing development cycles and redefining competitive differentiation around real-time inference latency.
Edge artificial intelligence is unifying photoplethysmography signal processing with on-device arrhythmia classification, eliminating cloud dependency for time-critical alerts. Cardiology departments in integrated delivery networks are piloting these systems for ambulatory patients with paroxysmal atrial fibrillation, prioritizing sub-30-second detection-to-notification latency. The structural consequence is unifying what were previously distinct hardware and software procurement decisions into single-vendor evaluation frameworks that favor vertically integrated platform providers.
EU MDR's classification rule 11 for software-as-a-medical-device is elevating clinical evidence requirements for algorithm-based arrhythmia detection claims previously cleared under lighter predicate pathways. Notified bodies in Germany and the Netherlands are demanding prospective validation studies with predefined performance thresholds for sensitivity and specificity. Wearable patch manufacturers targeting European distribution are responding by front-loading clinical trial investment and establishing quality management systems that satisfy Annex IX technical documentation scrutiny.
Self-insured employers are contracting directly with device-software platform vendors for population cardiac screening, disintermediating traditional hospital-based procurement. These arrangements bundle wearable provision, algorithmic analysis, and cardiologist overread into per-member-per-month fees rather than capital equipment purchases. The United States exhibits the most visible shift, where large employers in manufacturing and logistics sectors prioritize early detection programs that reduce catastrophic cardiovascular event costs within high-claims employee cohorts.
Heart Beat Irregularity Detection Device Market Segmentation
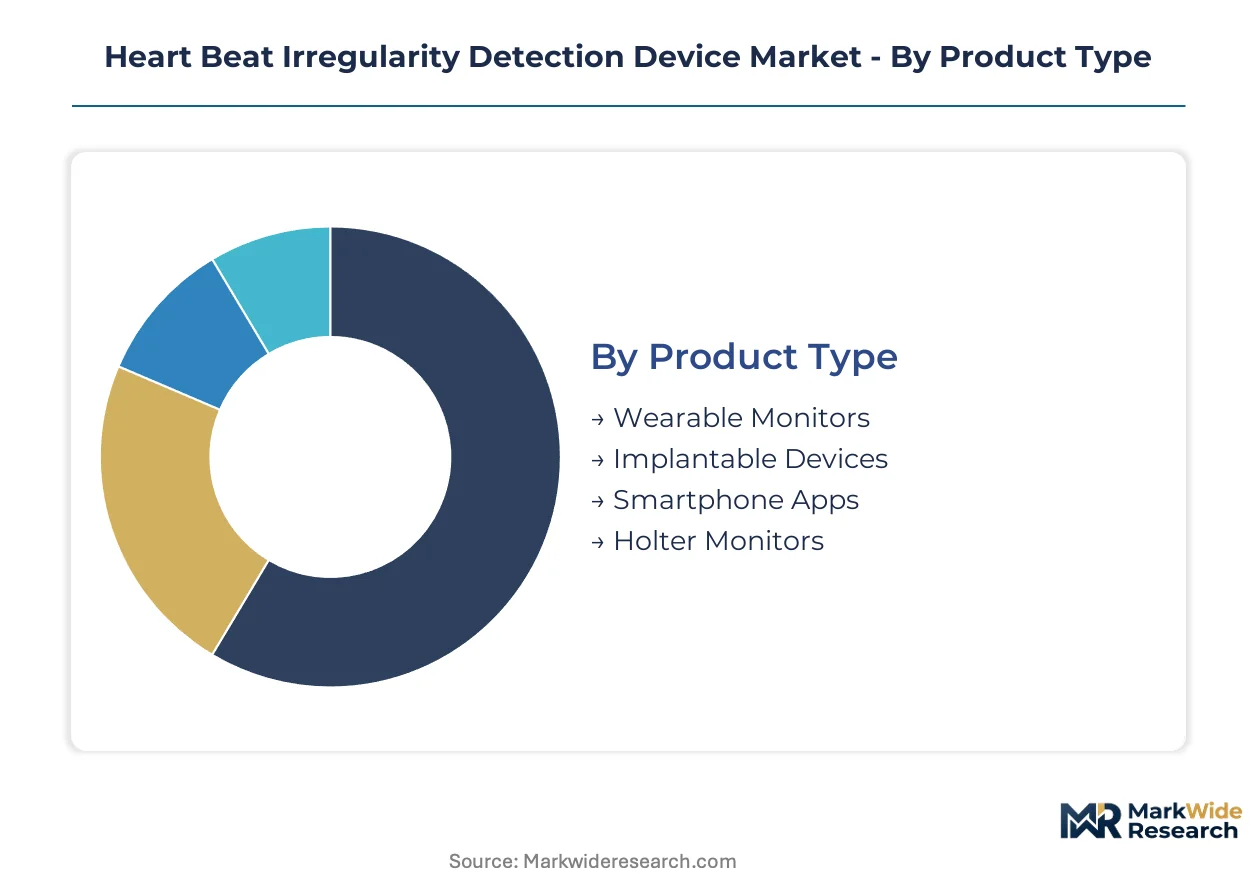
Segmentation in cardiac monitoring reveals divergent buyer priorities across clinical versus consumer channels. Hardware form factors, algorithm sophistication, and reimbursement pathways create distinct purchasing logic that shapes vendor positioning.
Product Type:
Buyer differentiation hinges on acuity level and duration of monitoring required.
- Wearable Monitors:Patch-based ECG systems with adhesive electrodes capture multi-day ambulatory data. Demand concentrates in United States outpatient cardiology practices where remote patient monitoring reimbursement codes support prescription volume.
- Implantable Devices:Subcutaneous loop recorders provide continuous monitoring for cryptogenic stroke and unexplained syncope patients. Japanese hospital systems drive procurement volume through PMDA-cleared devices with extended battery longevity.
- Smartphone Apps:Consumer-facing applications leveraging camera-based photoplethysmography for pulse irregularity screening.
- Holter Monitors:Multi-lead portable systems retaining dominance in medicolegal documentation and post-ablation surveillance protocols.
Volume sits with wearable monitors; growth tilts toward implantable devices as stroke prevention protocols expand.
Technology:
Signal fidelity requirements separate clinical-grade from wellness-oriented deployments.
- Electrocardiogram:Multi-electrode voltage measurement remains the diagnostic gold standard for arrhythmia classification. German statutory health insurers mandate ECG-based confirmation before AFib treatment initiation under DiGA pathways.
- Photoplethysmography:Optical pulse waveform analysis enables consumer-scalable form factors. United States direct-to-employer screening programs favor PPG wearables for population-scale deployment cost efficiency.
- Ultrasound:Echocardiography-integrated rhythm assessment for structural heart disease contexts.
- Artificial Intelligence:Machine learning inference layers automating rhythm classification and reducing cardiologist interpretation burden.
Revenue concentrates in ECG hardware; algorithmic AI layers command premium pricing fastest.
End User:
Procurement authority and reimbursement structure determine channel economics.
- Home Care:Patient-directed monitoring for chronic AFib management and anticoagulation therapy surveillance. United States Medicare remote physiological monitoring codes are expanding eligibility criteria for home-based prescribing.
- Hospitals:Integrated delivery networks anchor high-acuity contracts for implantable and patch-based systems. Japanese tertiary centers prioritize PMDA-cleared devices with local clinical validation.
- Outpatient Clinics:Community cardiology practices driving ambulatory ECG monitor prescription volume.
- Telehealth Services:Virtual-first care models bundling device shipment with remote clinician oversight.
Hospital procurement dominates current revenue; telehealth services are climbing the fastest as virtual cardiology scales.
Application:
Clinical specialty requirements dictate performance thresholds and regulatory pathway selection.
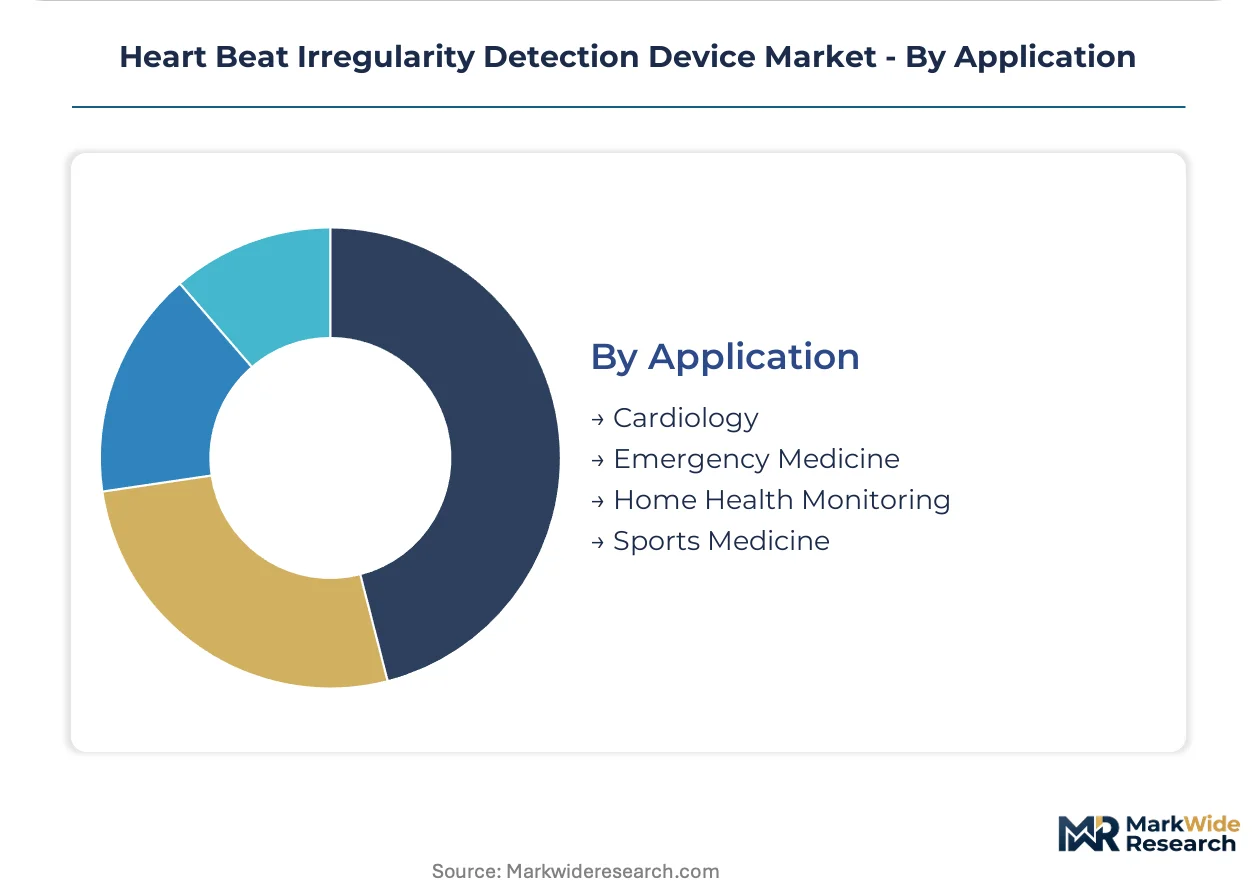
- Cardiology:Specialist-led arrhythmia diagnosis and treatment monitoring. German outpatient cardiology practices leverage DiGA fast-track reimbursement for algorithm-based detection tools.
- Emergency Medicine:Rapid atrial fibrillation identification in acute presentation contexts. United States emergency departments prioritize FDA-cleared devices with sub-60-second diagnostic output.
- Home Health Monitoring:Post-discharge surveillance for heart failure and stroke patients.
- Sports Medicine:Athlete cardiac screening and exercise-induced arrhythmia detection.
Cardiology generates the largest procedure volume; emergency medicine applications are gaining share fastest through point-of-care integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in established medical technology corridors while consumption patterns diverge across reimbursement environments. The United States, Germany, and Japan anchor procurement volume through aligned payment structures, whereas production capabilities cluster near semiconductor supply chains and precision manufacturing ecosystems.
United States
Medicare remote physiological monitoring reimbursement codes are expanding eligibility for home-based cardiac surveillance. FDA breakthrough device designations compress review timelines for algorithm-native entrants. Minneapolis anchors implantable device manufacturing through vertically integrated production facilities serving hospital system contracts.
Germany
Statutory health insurers prescribe CE-marked diagnostic algorithms through the DiGA fast-track pathway for digital health applications. EU MDR Annex IX technical documentation requirements elevate clinical evidence thresholds for software-as-a-medical-device claims. The Munich-Stuttgart corridor concentrates wearable ECG development teams serving outpatient cardiology practices.
Japan
Aging demographics drive cryptogenic stroke monitoring protocols through tertiary hospital networks. PMDA mandates domestic trial evidence for algorithm validation, filtering market access for foreign manufacturers. Tokyo-Osaka metropolitan areas host local clinical validation partnerships required for device clearance.
South Korea
MFDS regulatory harmonization with FDA pathways accelerates approval timelines for biosignal acquisition hardware. Discrete analog front-end component suppliers concentrate in Hsinchu-adjacent ecosystems, exposing device manufacturers to allocation risk. Seoul anchors regional headquarters for multinational cardiac monitoring vendors targeting Asia-Pacific expansion.
Switzerland
Swissmedic maintains alignment with EU MDR conformity assessment while preserving independent sovereign approval pathways for implantable loop recorders. Precision sensor manufacturing clusters in the Lake Geneva region supply photoplethysmography components to wearable patch developers. Basel-Zurich corridor hosts quality management system auditors serving dual FDA-EU compliance requirements.
Heart Beat Irregularity Detection Device Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware-software bundling decisions. Medtronic plc leverages its implantable device pipeline to anchor high-acuity hospital contracts, while Abbott Laboratories sustains competitive pressure through wearable patch specialization. The vendor base fragments across three strategic archetypes: vertically integrated platform providers, algorithm-native software vendors, and component-specialist hardware fabricators. Dominant competitive moves include strategic partnerships between semiconductor suppliers and device OEMs, plus portfolio diversification into adjacent cardiac rhythm management segments.
Within the diversified medical technology tier, Medtronic plc and Abbott Laboratories exemplify scale-driven platform consolidation. iRhythm Technologies, Inc. occupies a position among algorithm-native specialists emphasizing cloud-connected diagnostic workflows. These three companies represent contrasting strategic bets on hardware-software integration depth versus modular component specialization.
| Leading Market Players |
|---|
| Medtronic plc |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Koninklijke Philips N.V. |
| GE Healthcare |
| iRhythm Technologies, Inc. |
| Biotronik |
| Nihon Kohden Corporation |
| AliveCor, Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up algorithm specialists anchor pricing discipline through recurring SaaS revenue streams while simultaneously locking in multi-year analog front-end supply contracts with Taiwanese semiconductor fabricators. This ownership structure concentrates procurement leverage among scaled platforms that can absorb FDA validation costs while passing through component inflation via subscription tier adjustments.
Pricing Analysis
Cost-down pressure on wearable patch tiers accelerates because United States Medicare reimbursement compression forces outpatient cardiology practices toward lower per-test economics. Pricing stratifies across premium AI-enabled diagnostic platforms, standard cloud-connected monitors, and economy-grade Holter substitutes. FDA breakthrough designation tier commands 40-60% subscription premiums over predicate-cleared devices. United States hospital systems exhibit highest price sensitivity due to value-based care contract exposure, while Japanese tertiary centers absorb premium pricing for PMDA-cleared implantable loop recorders.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from United States integrated delivery networks while specialized distributors serve German outpatient cardiology practices requiring EU MDR technical documentation support. Discrete analog front-end components concentrate in Taiwan and South Korea, with photoplethysmography optical sensors sourcing from Swiss precision manufacturing clusters. Biosignal acquisition ASICs and medical-grade adhesive electrodes constitute critical input dependencies. Single-source vulnerability in Taiwan semiconductor fabrication exposes device manufacturers to allocation risk during foundry capacity constraints. Distribution runs through hospital GPO contracts in the United States and statutory health insurer procurement frameworks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized semiconductor foundry capacity constraints prop pricing power for vertically integrated device manufacturers that captive-source analog front-end components. Component allocation bottlenecks in Taiwanese fabrication facilities limit supply elasticity, sustaining margin structures for scaled incumbents with forward supply commitments.
For Market Incumbents: Cement hospital system anchor contracts through bundled hardware-software procurement frameworks that lock out modular competitors. Deepen backward integration into analog front-end semiconductor design to reduce Taiwan foundry exposure. Prioritize FDA breakthrough device designation maintenance as cloud-native entrants threaten algorithmic differentiation. Capacity expansion in United States-based quality management system auditing reduces multi-jurisdiction compliance overhead. For New Entrants and Emerging Players: Edge AI inference-on-chip architectures offer white-space entry against cloud-dependent incumbents in paroxysmal atrial fibrillation ambulatory monitoring. Target United States direct-to-employer screening programs as the most penetrable channel bypassing hospital procurement gatekeepers. Germany's DiGA fast-track reimbursement pathway enables rapid European market entry for CE-marked diagnostic algorithms. Pursue cardiologist overread service bundling as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor algorithm-native specialists with locked FDA 510(k) clearances but constrained working capital in United States coastal technology corridors. Five-to-ten year viability hinges on continuous learning algorithm architectures that circumvent premarket notification version-lock constraints. Acquisition target archetype: edge AI hardware-software platforms with sub-30-second detection latency and existing hospital pilot contracts. Monitor FDA guidance document releases on predetermined change control plans as inflection indicator for scalable algorithm update economics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates review timelines for AI-native entrants competing against predicate-cleared systems. |
| CE Marking Pathway under EU MDR | Unlocks German DiGA reimbursement access for algorithm-based arrhythmia detection tools. |
| Hospital System Partnership | Secures multi-year remote patient monitoring contracts embedding devices into value-based care. |
| Software Companion Development | Enables locked-algorithm version updates within FDA premarket notification constraints. |
| Reimbursement Strategy | Aligns device prescribing with United States Medicare remote physiological monitoring codes. |
Research Methodology
FDA 510(k) premarket notification filings, CMS Medicare reimbursement code databases, and EU MDR notified body technical documentation formed the secondary backbone. Primary interviews with cardiac electrophysiologists, hospital biomedical engineers, GPO contracts managers, and regulatory affairs specialists at algorithm-native device developers supplied qualitative validation. Bottom-up and top-down triangulation cross-checked unit shipment estimates against reimbursement claim volume data.
Bottom-up modeling segmented revenue across hardware form factors, algorithm sophistication tiers, and end-user procurement channels throughout the forecast period. Top-down validation referenced macro healthcare expenditure patterns and cardiac monitoring procedure growth assumptions. CAGRs derived from fitted growth curves applied to base-year sizing with sensitivity testing around reimbursement policy scenarios. Forecast inputs included PMDA clinical trial completion timelines and semiconductor foundry capacity expansion announcements.
Several conditions sit outside the modeled scope, including hypothetical FDA algorithm update guidance revisions, Taiwan semiconductor supply disruptions exceeding six-month duration, and statutory health insurer DiGA delisting events. Forecasts reflect documented assumptions regarding reimbursement code stability and regulatory pathway continuity. Periodic stress-testing of base assumptions is recommended against PMDA local clinical data requirement enforcement patterns and United States value-based care contract penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Intravascular Catheters Market
Cardiovascular Devices
Global Catheters Market
Cardiovascular Devices
Peripheral Vascular Devices Market
Cardiovascular Devices
Drug-Coated Balloon Catheter Market
Cardiovascular Devices
Neurovascular Coiling Assist Devices Market
Cardiovascular Devices
Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
Germany Cardiovascular Devices Market
Cardiovascular Devices
Arteriotomy Closure Devices Market
Cardiovascular Devices
Continuous Blood Pressure Monitoring Devices Market
Cardiovascular Devices
Global Non-Vascular Stents Market
Cardiovascular Devices
Pulmonary Artery Catheter Market
Cardiovascular Devices
Cardiac Valve Market
Cardiovascular Devices
Global Atrial Fibrillation Surgery Market
Cardiovascular Devices
Microsclerotherapy Treatment Market
Cardiovascular Devices
Global Intravascular Temperature Management Market
Cardiovascular Devices
Integrated Cardiology Devices Market