
 Global 3D Vascular Ultrasound Imaging Market | 2026-2036
Global 3D Vascular Ultrasound Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3D Vascular Ultrasound Imaging Market Foresight
The buyer base for 3D vascular ultrasound systems is broadening beyond hospital radiology departments to encompass outpatient cardiology clinics and mobile diagnostic services. GE Healthcare leverages its installed base of cardiac imaging platforms to cross-sell vascular configurations, while Philips Healthcare sustains R&D intensity in vector flow algorithms that reduce operator dependence. Siemens Healthineers anchors its vascular portfolio on automated measurement protocols that accelerate exam throughput in high-volume European centers.
3D vascular ultrasound imaging employs high-frequency transducer arrays and beamforming algorithms to reconstruct volumetric blood-flow maps with spatial resolution down to sub-millimeter scales, primarily serving non-invasive diagnosis of stenosis, thrombosis, and aneurysmal disease. Doppler ultrasound dominates current revenue contribution due to entrenched reimbursement codes and clinician familiarity, though contrast-enhanced ultrasound represents the fastest-expanding segment as microbubble agents improve visualization of low-flow venous structures. Capacitive micromachined ultrasound transducers are displacing legacy piezoelectric crystals in next-generation probes, enabling miniaturization for point-of-care deployment without sacrificing bandwidth.
FDA 510(k) pathways and EU MDR conformity assessments govern commercial access, with both frameworks tightening clinical evidence requirements for quantitative flow measurements that inform surgical intervention decisions. The WHO's diagnostic imaging guidelines and IEC 60601-2-37 electrical safety standards further constrain design specifications for multi-country product platforms. Stakeholders must monitor reimbursement recalibrations for peripheral artery disease screening as Medicare coverage determinations and Germany's G-BA benefit assessments set precedents for comparable health systems.
Market Dynamics
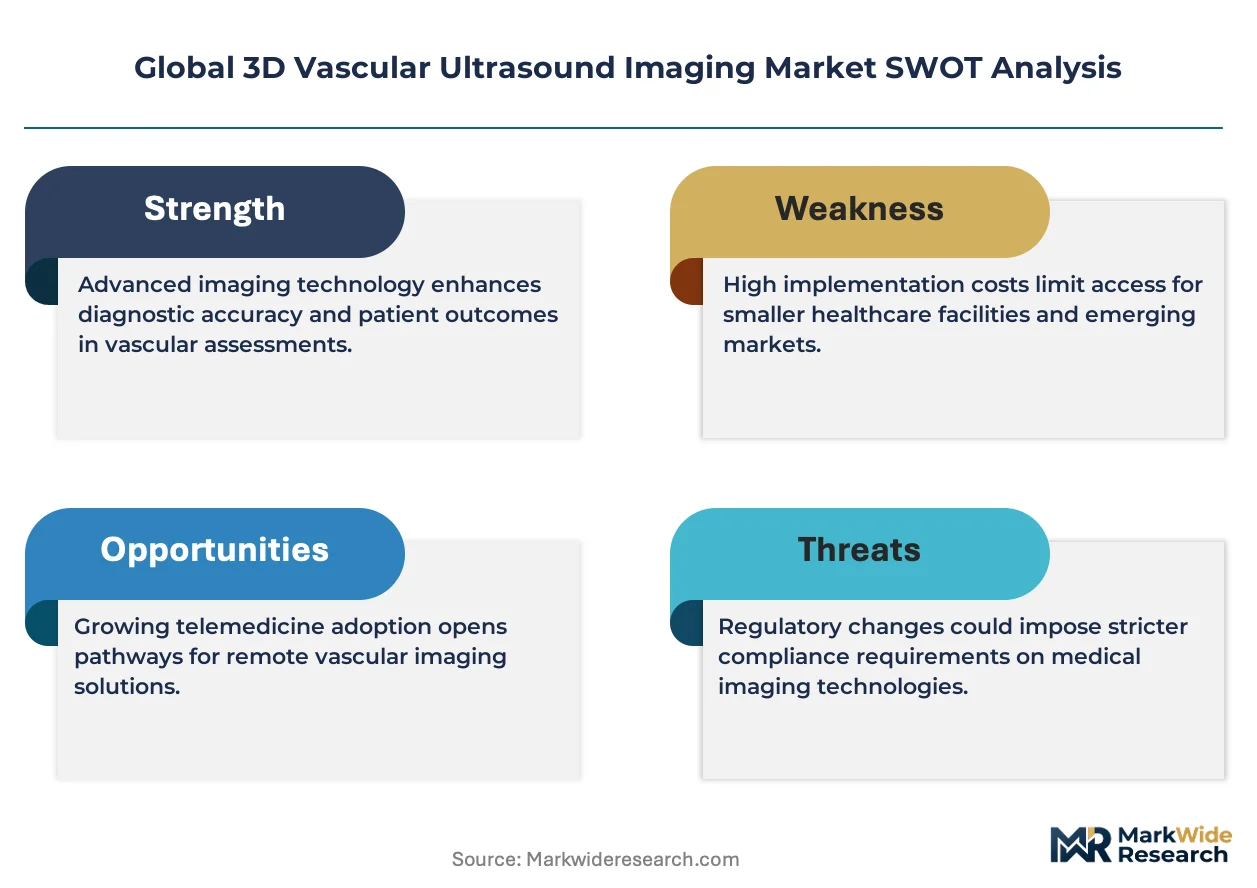
Capacitive micromachined ultrasound transducers are compressing probe manufacturing costs while EU MDR conformity assessments extend product development cycles, creating simultaneous margin pressure and compliance burden for manufacturers.
Growth Catalysts
- Peripheral artery disease screening mandates:Medicare coverage determinations in the United States now reimburse non-invasive vascular assessment, accelerating replacement of conventional angiography workflows in outpatient settings.
- Contrast-enhanced ultrasound protocols:Microbubble agent improvements enable visualization of low-flow venous structures previously requiring CT angiography, expanding addressable diagnostic categories.
- Japan's aging demographic profile:METI-directed healthcare infrastructure investments prioritize non-invasive modalities for elderly populations with surgical risk factors, concentrating demand for point-of-care vascular systems.
Market Restraints
- Piezoelectric crystal supply concentration:Legacy transducer material sourcing depends on specialized ceramic processing capabilities concentrated in East Asian manufacturing clusters.
- EU MDR clinical evidence requirements:Quantitative flow measurement claims now require prospective validation studies, extending time-to-market by 18-24 months for algorithm-dependent features.
- CT angiography substitution threat:Slice-count improvements in computed tomography systems retain institutional preference for complex aortic assessments despite radiation exposure trade-offs.
Strategic Opportunities
- Mobile diagnostic service channels:Capital-light deployment models enable vascular screening penetration into rural Germany where fixed imaging infrastructure remains underdeveloped.
- Vector flow-Doppler convergence:Algorithmic integration of angle-independent velocity mapping with spectral Doppler is unifying diagnostic confidence and operator efficiency in single-exam protocols.
- WHO diagnostic imaging guidelines:Standardization of non-invasive vascular assessment protocols in emerging health systems creates regulatory tailwind for pre-qualified equipment platforms.
Industry Challenges
- Operator-dependent image acquisition:Sub-millimeter spatial resolution requirements demand specialized sonographer training that outpaces educational program expansion in high-volume markets.
- Legacy PACS integration complexity:Volumetric data formats from 3D vascular systems require middleware adaptation for compatibility with hospital-wide archiving infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3D Vascular Ultrasound Imaging Market |
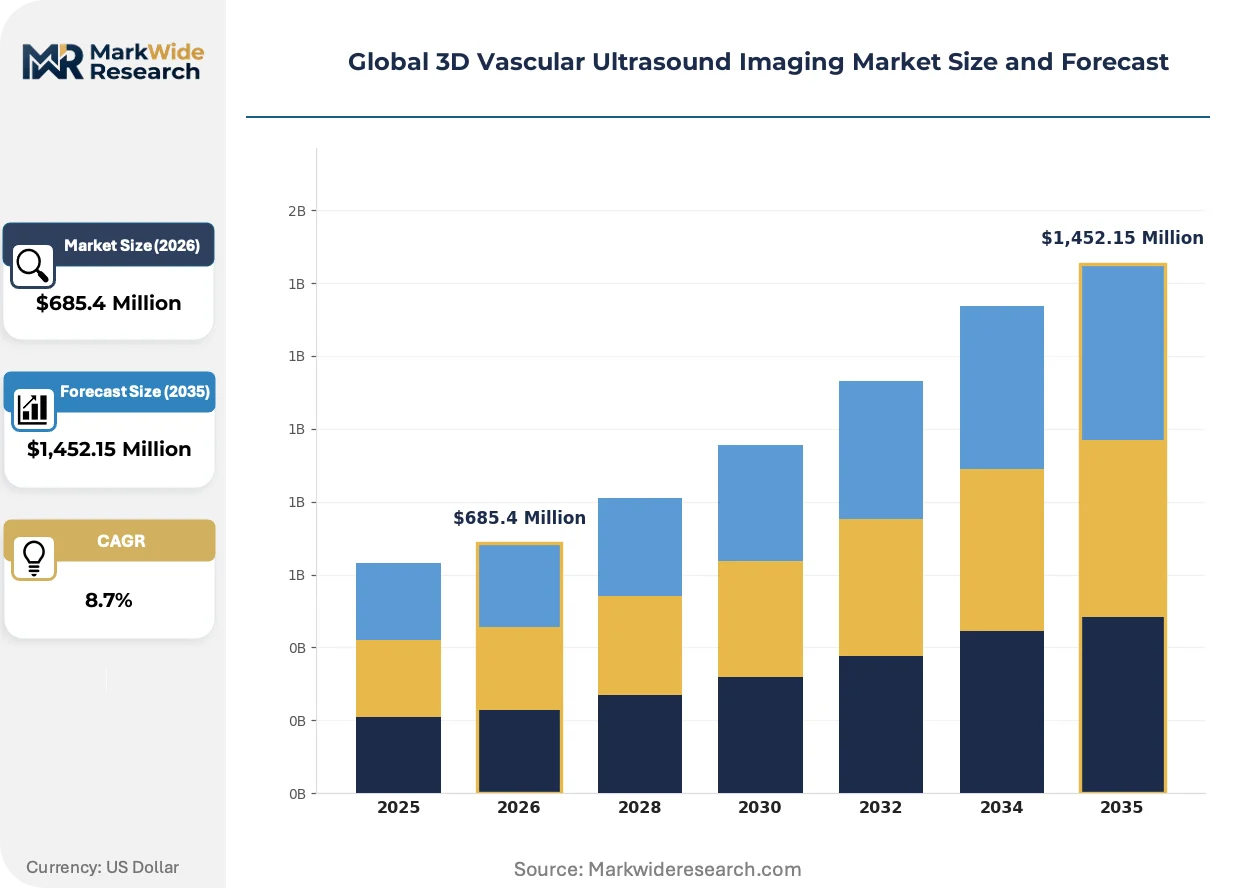
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Ultrasound, 3D Ultrasound, Doppler Ultrasound, Contrast-Enhanced Ultrasound, High-Frequency Ultrasound Technology: Piezoelectric, Capacitive Micromachined Ultrasound Transducers, Vector Flow Imaging, Elastography, Harmonic Imaging Application: Peripheral Artery Disease, Carotid Artery Evaluation, Venous Thrombosis Diagnosis, Aneurysm Detection, Stroke Risk Assessment End User: Diagnostic Imaging Centers, Cardiology Clinics, Radiology Departments, Vascular Surgery Units, Research Institutes |
| Companies Covered | Canon Medical Systems Corporation, Hitachi, GE Healthcare, Esaote SpA, Mindray Medical International Limited, Philips Healthcare, Fujifilm Holdings Corporation, Samsung Medison Co., Ltd., Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3D Vascular Ultrasound Imaging Market Shifts & Advancements
Beamforming algorithm advances and transducer miniaturization are compressing the performance gap between cart-based and point-of-care systems, while regulatory frameworks tighten evidence standards for quantitative diagnostic outputs.
Capacitive micromachined ultrasound transducers are unifying bandwidth performance with probe miniaturization by replacing piezoelectric crystal arrays in next-generation devices. Cardiology clinics in Germany and Japan are adopting these platforms for bedside vascular assessment without sacrificing diagnostic fidelity. This unification is enabling point-of-care deployment models that bypass traditional radiology department workflows entirely.
EU MDR conformity assessment procedures now mandate clinical performance studies for software-as-medical-device features that inform surgical intervention decisions. Manufacturers face expanded notified body scrutiny of algorithm validation datasets, particularly for automated stenosis grading protocols. High-volume European centers are responding by consolidating procurement around vendors with established MDR technical documentation.
After-sales service unbundling is fragmenting traditional equipment purchasing into modular subscription components across the United States. Hospital systems now separately negotiate transducer replacement pools, software update entitlements, and remote technical support tiers. This pattern is most visible in integrated delivery networks seeking operational expenditure flexibility over capital commitment concentration.
Global 3D Vascular Ultrasound Imaging Market Segmentation
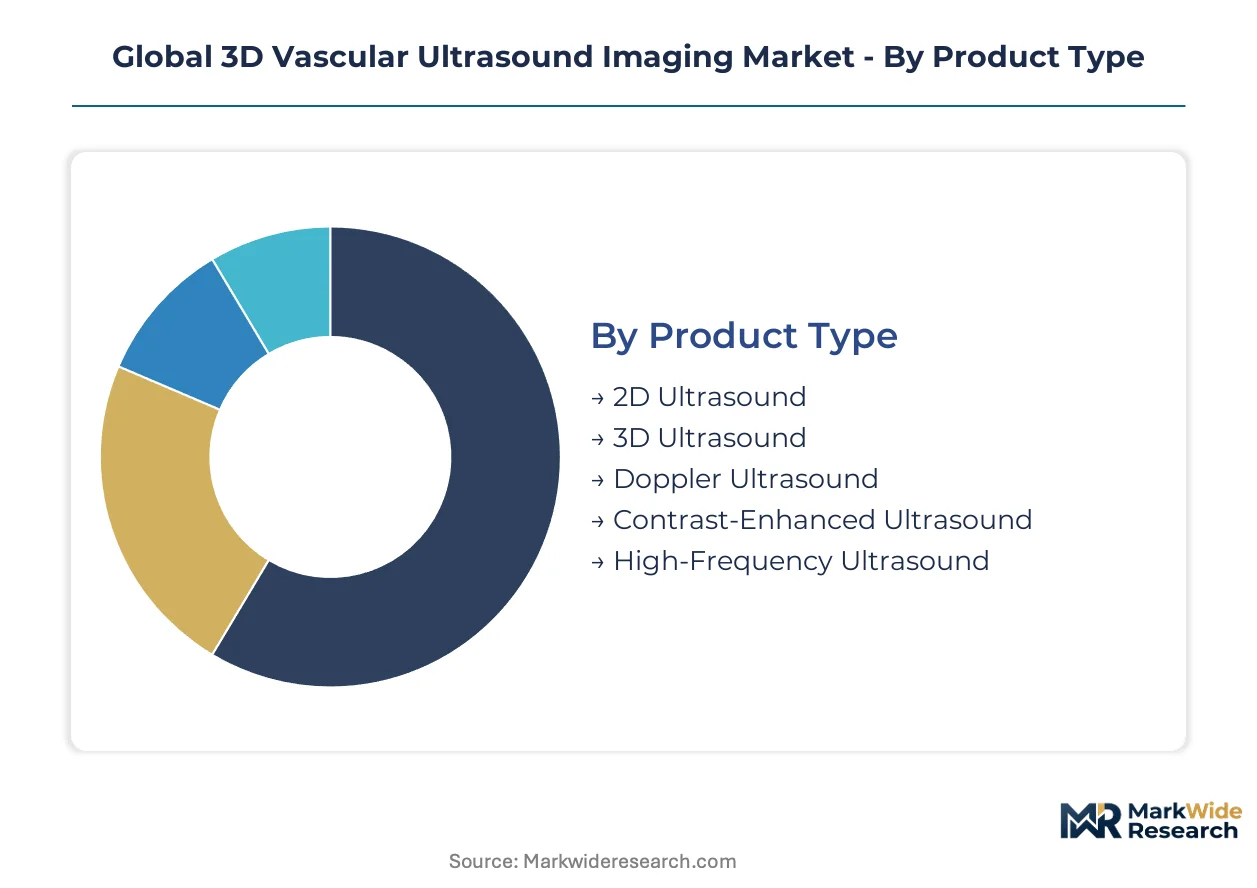
Technology differentiation and clinical workflow integration define procurement decisions across the 3D vascular ultrasound imaging landscape. Buyers prioritize modality configurations that align with reimbursement codes and staff training profiles.
Product Type:
Procurement teams evaluate capital intensity against diagnostic throughput requirements when selecting imaging configurations.
- 2D Ultrasound:Legacy grayscale imaging remains the volume foundation in budget-constrained outpatient settings where reimbursement rates favor established procedural codes.
- 3D Ultrasound:Volumetric reconstruction capabilities command premium positioning in tertiary referral centers performing complex aortic assessments. German university hospitals prioritize these systems for surgical planning workflows.
- Doppler Ultrasound:Spectral velocity mapping dominates current installed bases due to entrenched clinician familiarity and direct Medicare reimbursement alignment in the United States.
- Contrast-Enhanced Ultrasound:Microbubble agent protocols enable visualization of low-flow venous structures that previously required CT angiography, expanding diagnostic categories in Japanese geriatric populations.
- High-Frequency Ultrasound:Sub-millimeter resolution transducers serve superficial vascular assessments in dermatology and plastic surgery crossover applications.
Volume sits with Doppler configurations; growth tilts toward contrast-enhanced protocols.
Technology:
Transducer architecture decisions determine probe longevity, bandwidth performance, and total cost of ownership across deployment models.
- Piezoelectric:Ceramic crystal arrays anchor legacy installed bases with established supply chains concentrated in East Asian manufacturing clusters.
- Capacitive Micromachined Ultrasound Transducers:MEMS fabrication enables probe miniaturization without bandwidth sacrifice. Cardiology clinics in Japan deploy these for bedside vascular assessment.
- Vector Flow Imaging:Angle-independent velocity mapping reduces operator dependence in high-throughput European centers where sonographer availability constrains exam volume.
- Elastography:Tissue stiffness quantification adds diagnostic specificity for plaque characterization in research-oriented vascular surgery units.
- Harmonic Imaging:Frequency-domain filtering improves signal-to-noise ratios in technically difficult patients with body habitus challenges.
Revenue concentrates in piezoelectric platforms; steepest expansion trajectory belongs to capacitive micromachined transducers.
Application:
Screening mandate expansions and surgical referral patterns shape demand concentration across diagnostic categories.
- Peripheral Artery Disease:Medicare coverage determinations now reimburse non-invasive ankle-brachial index protocols, accelerating replacement of conventional angiography in United States outpatient cardiology clinics.
- Carotid Artery Evaluation:Stroke prevention programs in Germany's G-BA reimbursement framework prioritize duplex ultrasound for asymptomatic stenosis surveillance in elderly populations.
- Venous Thrombosis Diagnosis:Emergency department protocols favor compression ultrasound for deep vein thrombosis exclusion, driving point-of-care system adoption.
- Aneurysm Detection:Abdominal aortic screening programs in Japan's METI-directed infrastructure investments concentrate demand for portable systems in community health settings.
- Stroke Risk Assessment:Integrated cerebrovascular evaluation protocols combine carotid and transcranial Doppler in specialized stroke centers.
Exam volume clusters in peripheral artery disease screening; fastest share gains appear in aneurysm detection applications.
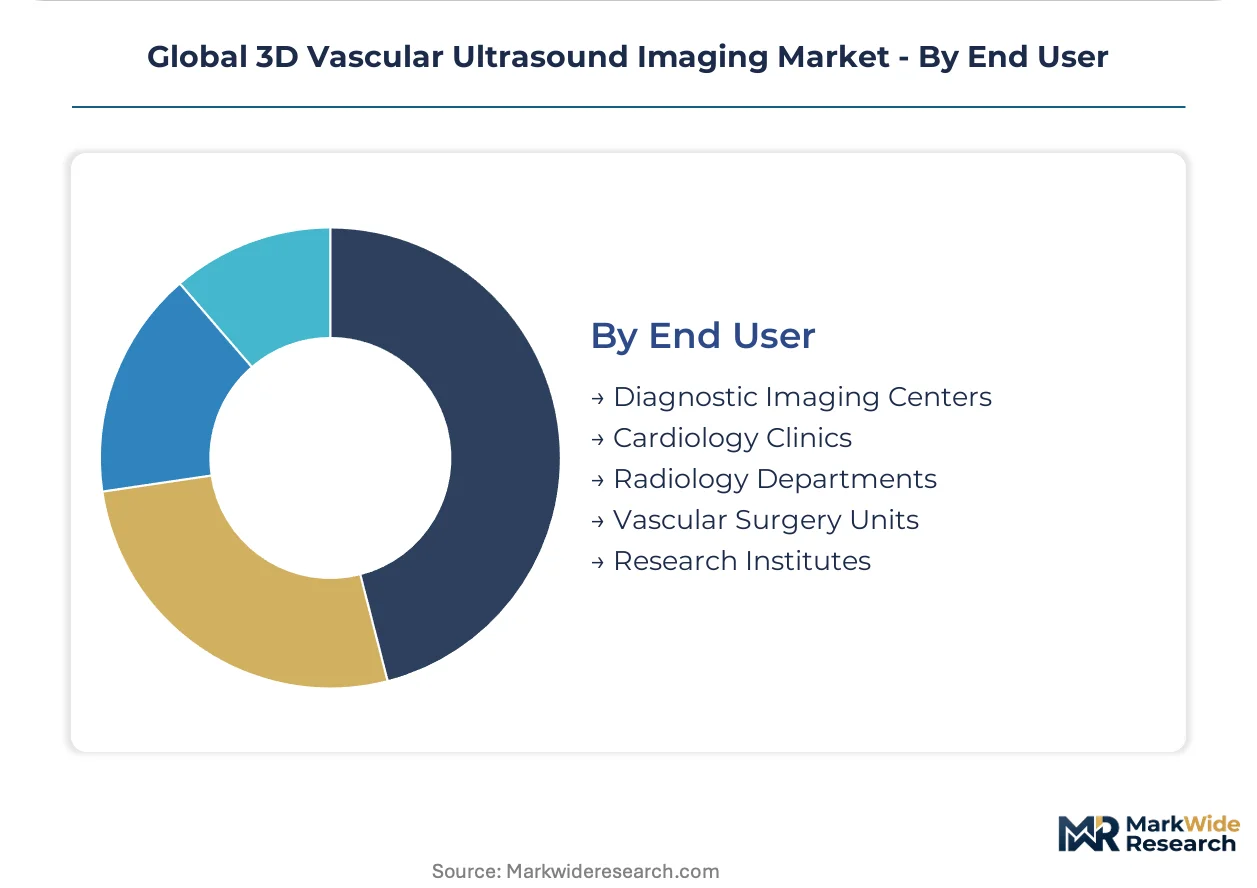
End User:
Capital availability and procedural reimbursement rates segment buyer behavior across institutional categories.
- Diagnostic Imaging Centers:Independent facilities prioritize throughput-optimized systems with automated measurement protocols to maximize exam volume per sonographer shift.
- Cardiology Clinics:Outpatient vascular assessment workflows in the United States replace conventional angiography referrals, concentrating demand for compact systems with PACS integration.
- Radiology Departments:Hospital-based imaging units maintain multi-modality portfolios where 3D vascular ultrasound complements CT and MR angiography for radiation-sensitive patients.
- Vascular Surgery Units:Preoperative planning requirements in German tertiary centers drive demand for high-resolution volumetric systems with surgical navigation compatibility.
- Research Institutes:Algorithm validation studies for EU MDR conformity assessments create specialized demand for research-grade platforms with raw data export capabilities.
Installed base dominance rests with radiology departments; procurement momentum shifts toward cardiology clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized ceramic processing capabilities in East Asian manufacturing clusters supply piezoelectric crystal arrays that anchor transducer production for vascular ultrasound systems worldwide.
United States
Medicare coverage determinations now reimburse non-invasive ankle-brachial index protocols, accelerating replacement of conventional angiography in outpatient cardiology clinics. FDA 510(k) pathways govern commercial access for quantitative flow measurement features. The Minneapolis medical device corridor concentrates probe manufacturing operations serving domestic demand.
Germany
Germany's G-BA reimbursement framework prioritizes duplex ultrasound for asymptomatic carotid stenosis surveillance in elderly populations. EU MDR conformity assessments mandate clinical performance studies for software-as-medical-device features. The Baden-Württemberg region hosts high-volume European centers consolidating procurement around established technical documentation.
Japan
METI-directed healthcare infrastructure investments prioritize non-invasive modalities for elderly populations with surgical risk factors. PMDA regulatory timelines align with METI strategic priorities for point-of-care deployment. The Kansai region surrounding Osaka concentrates demand for portable vascular systems in community health settings.
China
Domestic manufacturing clusters in the Yangtze River Delta are developing capacitive micromachined ultrasound transducer fabrication capabilities. NMPA regulatory pathways increasingly reference IEC 60601-2-37 electrical safety standards for multi-country product platforms. Shanghai-based research institutes drive algorithm validation for automated measurement protocols.
Global 3D Vascular Ultrasound Imaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue MEMS-based miniaturization and point-of-care deployment models. The vendor base stratifies across diversified imaging conglomerates, specialized ultrasound pure-plays, and emerging Asian challengers. Three archetypes dominate: integrated healthcare technology conglomerates with cross-selling capabilities, dedicated ultrasound specialists with algorithmic differentiation, and scale-driven manufacturers compressing probe costs through vertical integration. Competitive moves concentrate on M&A for algorithm portfolios and strategic partnerships for regulatory pre-qualification in emerging health systems.
Among diversified imaging conglomerates, GE Healthcare and Philips Healthcare exemplify the cross-selling archetype leveraging installed bases of cardiac imaging platforms. Siemens Healthineers anchors the European premium tier through automated measurement protocols. These three entities represent distinct strategic positions: GE Healthcare through North American reimbursement alignment, Philips Healthcare through vector flow R&D intensity, and Siemens Healthineers through MDR technical documentation depth.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Hitachi |
| GE Healthcare |
| Esaote SpA |
| Mindray Medical International Limited |
| Philips Healthcare |
| Fujifilm Holdings Corporation |
| Samsung Medison Co., Ltd. |
| Siemens Healthineers |
| Others |
Supply & Pricing Matrix
Captive transducer fabrication in East Asian manufacturing clusters anchors supply positions for tier-one vendors while simultaneously constraining pricing flexibility for mid-tier competitors dependent on outsourced probe sourcing. This integration pattern concentrates cost advantages with conglomerates controlling ceramic processing capabilities, forcing unbundled procurement models elsewhere.
Pricing Analysis
After-sales service unbundling now separates transducer replacement pools from software entitlements and remote support tiers across United States hospital systems. Three-tier pricing structure across premium, standard, and economy levels differentiates by MDR technical documentation depth and automated measurement protocol sophistication. Pricing pressure stems from capacitive micromachined ultrasound transducer cost compression enabling point-of-care deployment at reduced capital intensity. Diagnostic imaging centers exhibit highest price sensitivity due to throughput-dependent margin structures; German tertiary centers demonstrate lowest sensitivity where surgical navigation compatibility commands premium positioning.
Supply Chain Analysis
Specialized sonographer training program expansion in Germany and Japan lags behind probe manufacturing capacity growth, creating workforce bottlenecks that constrain downstream system deployment regardless of upstream component availability. Ceramic crystal processing draws from concentrated East Asian manufacturing clusters while MEMS fabrication capacity expands in the Yangtze River Delta. Single-source vulnerability persists for high-frequency piezoelectric arrays essential to superficial vascular assessments. Distribution runs through direct hospital system contracts in North America and specialized medical device distributors serving European outpatient clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capacitive micromachined ultrasound transducers are displacing legacy piezoelectric crystals, compressing the performance gap between cart-based and point-of-care systems while fragmenting established procurement patterns.
For Market Incumbents: To counter MEMS-based miniaturization threats from emerging Asian challengers, deepen algorithm validation datasets for EU MDR conformity assessments while consolidating procurement relationships with high-volume European centers through automated measurement protocol standardization. Prioritize technical documentation depth as the defensive lever against notified body scrutiny expansion. For New Entrants and Emerging Players: Vector flow imaging convergence with spectral Doppler offers entry wedge into angle-independent velocity mapping segments where operator dependence constrains exam volume in European high-throughput centers. Target rural German mobile diagnostic services where fixed imaging infrastructure remains underdeveloped, deploying capital-light subscription models that bypass traditional radiology department procurement. For Investors and Strategic Acquirers: Exit pathways concentrate in algorithm portfolio acquisitions by diversified imaging conglomerates seeking MDR pre-qualified software capabilities. Five-to-ten year viability hinges on reimbursement alignment for quantitative flow measurements informing surgical intervention decisions. Monitor Medicare coverage determinations for peripheral artery disease screening protocols as inflection indicator for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Notified body pre-qualification accelerates algorithm-dependent feature commercialization in European centers. |
| Vector Flow Algorithm Development | Angle-independent velocity mapping reduces operator dependence and expands exam volume per sonographer shift. |
| Capacitive MEMS Transducer Manufacturing Scale-Up | Miniaturization without bandwidth sacrifice enables point-of-care deployment bypassing radiology workflows. |
| Hospital System Partnership for PACS Integration | Volumetric data format compatibility resolves middleware adaptation barriers in tertiary referral centers. |
| Reimbursement Strategy for Contrast-Enhanced Protocols | Microbubble agent visualization of low-flow venous structures expands diagnostic categories beyond Doppler limitations. |
Research Methodology
Document review covered FDA 510(k) clearance databases, EU MDR notified body technical documentation, and CMS Medicare coverage determination records, complemented by interviews with vascular surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from PMDA regulatory filings, METI healthcare infrastructure investment disclosures, and IEC 60601-2-37 electrical safety standards. Bottom-up equipment procurement modeling triangulated against top-down demographic screening mandate projections.
Market sizing outputs reflect installed base analysis across cart-based and point-of-care configurations, segmented by transducer technology, application category, and end-user institutional type throughout the projection horizon. CAGRs derive from procedure volume elasticity to reimbursement expansion, technology substitution curves for MEMS displacement of piezoelectric platforms, and EU MDR conformity assessment timeline impacts on algorithm-dependent feature launches. Forecast inputs incorporate METI-directed elderly care infrastructure investments and G-BA benefit assessment precedents for asymptomatic stenosis surveillance.
Several conditions sit outside the modeled scope, including unforeseen IEC standard revisions, abrupt ceramic supply chain disruptions, and radical CT angiography slice-count improvements altering substitution economics. Forecasts reflect assumptions of stable reimbursement alignment and progressive MDR implementation timelines. Material deviation in Medicare coverage determinations or notified body capacity constraints warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Atherectomy Devices Market
Cardiovascular Devices
Aortic Stents Grafts Market
Cardiovascular Devices
Endovascular Aneurysm Repair Market
Cardiovascular Devices
Iliac Artery Stents Market
Cardiovascular Devices
Percutaneous Coronary Intervention Market
Cardiovascular Devices
Pressure Infusion Cuffs Market
Cardiovascular Devices
Intra-Aortic Balloon Pump (IABP) Market
Cardiovascular Devices
Heart Valves Market
Cardiovascular Devices
Continuous Cardiac Monitoring Systems Market
Cardiovascular Devices
Integrated Cardiology Devices Market
Cardiovascular Devices
Global Heart Pump Devices Market
Cardiovascular Devices
Pressure Infusion Bags Market
Cardiovascular Devices
Pulmonary Artery Catheter Market
Cardiovascular Devices
Latin America Compression Therapy Market
Cardiovascular Devices
Transcatheter Aortic Valve Replacement Market
Cardiovascular Devices
Chronic Venous Occlusions Treatment Market