
 Argentina Cardiovascular Devices Market | 2026-2036
Argentina Cardiovascular Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Cardiovascular Devices Market Outlook
The capability gap between capital-heavy imaging-integrated platforms and conventional device portfolios is rotating competitive priorities across Argentina's cardiovascular sector. Medtronic leverages its structural cardiac portfolio to anchor high-acuity hospital contracts in Buenos Aires. Abbott Laboratories sustains catheterization lab presence through drug-eluting stent specialization. Siemens Healthineers competes on diagnostic imaging integration with interventional workflows.
Cardiovascular devices encompass implantable and interventional instruments engineered from biocompatible alloys, polymers, and biological tissues, typically requiring hemodynamic compatibility thresholds below 5% thrombogenicity risk, designed to restore or monitor cardiac and vascular function. Stent segments dominate procurement volume while bioabsorbable technology platforms capture expanding margin pools from teaching hospitals pursuing next-generation revascularization protocols. Catheter systems lead minimally invasive delivery mode adoption as optical imaging integration redefines real-time procedural guidance standards.
Argentina's national pharmaceutical regulator ANMAT governs device registration and clinical evidence requirements while the Ministry of Health oversees public procurement pricing frameworks that shape hospital access patterns. ANMAT's convergence with Mercosur harmonization standards is streamlining cross-border regulatory pathways for imported cardiovascular technologies. Stakeholders must monitor reimbursement rate negotiations between provincial health ministries and device suppliers as these determine effective market penetration beyond capital corridor institutions.
Market Dynamics
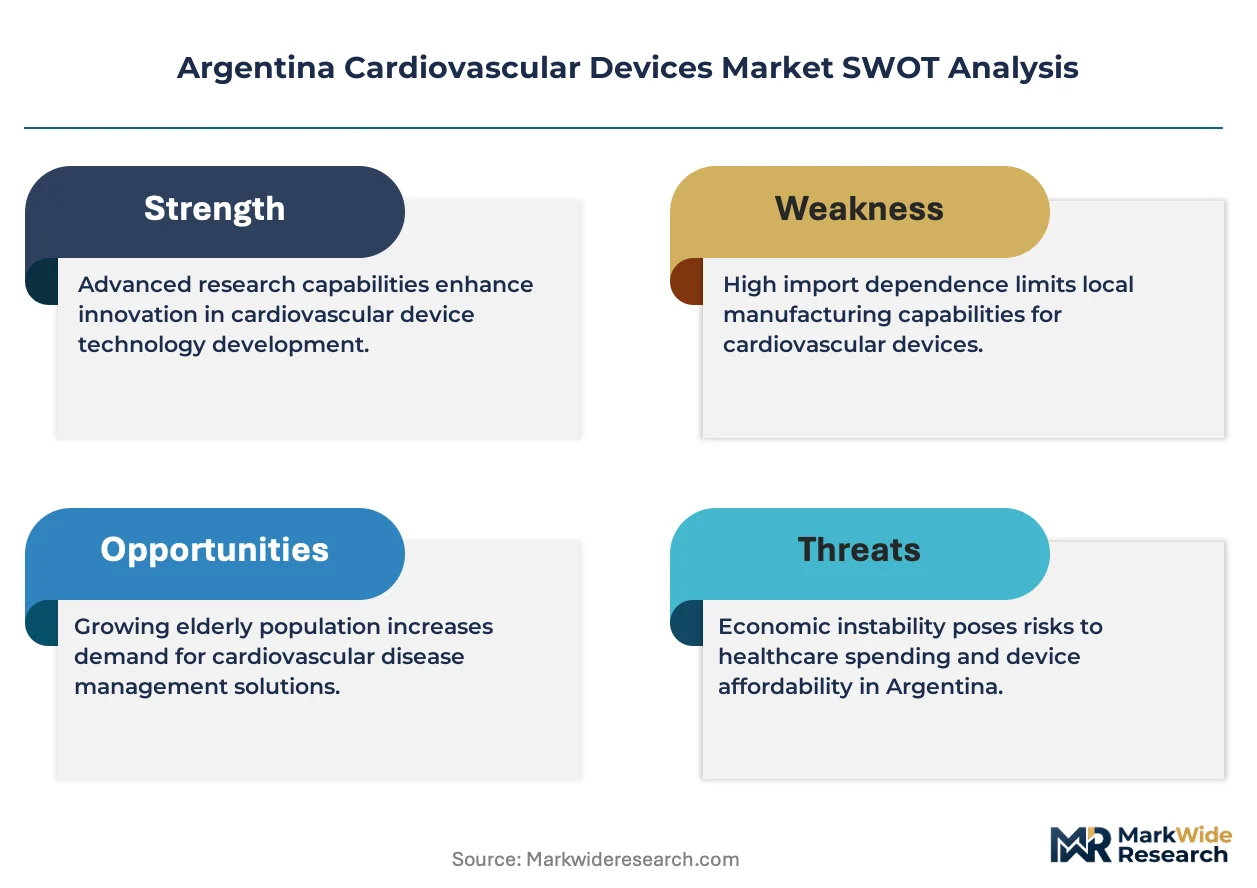
Bioabsorbable polymer technology is fragmenting established coronary stent procurement patterns across Argentina's public hospital network. The shift from permanent metallic implants to resorbable scaffolds is forcing catheterization labs to retrain interventional cardiologists and renegotiate supplier contracts under ANMAT's evolving clinical evidence framework.
Growth Catalysts
- ANMAT-Mercosur harmonization:Streamlined cross-border registration pathways accelerate imported cardiovascular technology access for Buenos Aires teaching hospitals.
- Interventional cardiology residency expansion:Training program growth in Córdoba and Rosario generates sustained device utilization from emerging specialists.
- National health insurance procurement:Public hospital purchasing under Argentina's integrated health system expands stent and catheter volume commitments.
Market Restraints
- Import dependency concentration:Heavy reliance on foreign-manufactured bioabsorbable scaffolds exposes supply chains to currency volatility and foreign exchange restrictions.
- Provincial reimbursement fragmentation:Negotiations between device suppliers and individual provincial health ministries create pricing inconsistency and access gaps outside metropolitan Buenos Aires.
- Bioresorbable magnesium alloy limitations:Mechanical performance constraints and extended resorption timelines limit adoption in complex multivessel cases.
Strategic Opportunities
- Optical coherence tomography integration:Real-time intravascular imaging convergence with stent deployment systems enables precision positioning in high-acuity interventions.
- Peripheral vascular expansion:Underdeveloped limb revascularization programs in Mendoza and Tucumán provinces offer untapped catheter and balloon utilization potential.
- Telecardiology-enabled remote monitoring:Implantable cardiac device follow-up via provincial health networks reduces urban hospital congestion.
Industry Challenges
- Interventional imaging technologist scarcity:Specialized training requirements for intravascular ultrasound and OCT system operation outpace educational program output.
- Legacy electronic health record incompatibility:Procedural data integration from new imaging-integrated platforms encounters friction with hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Cardiovascular Devices Market |
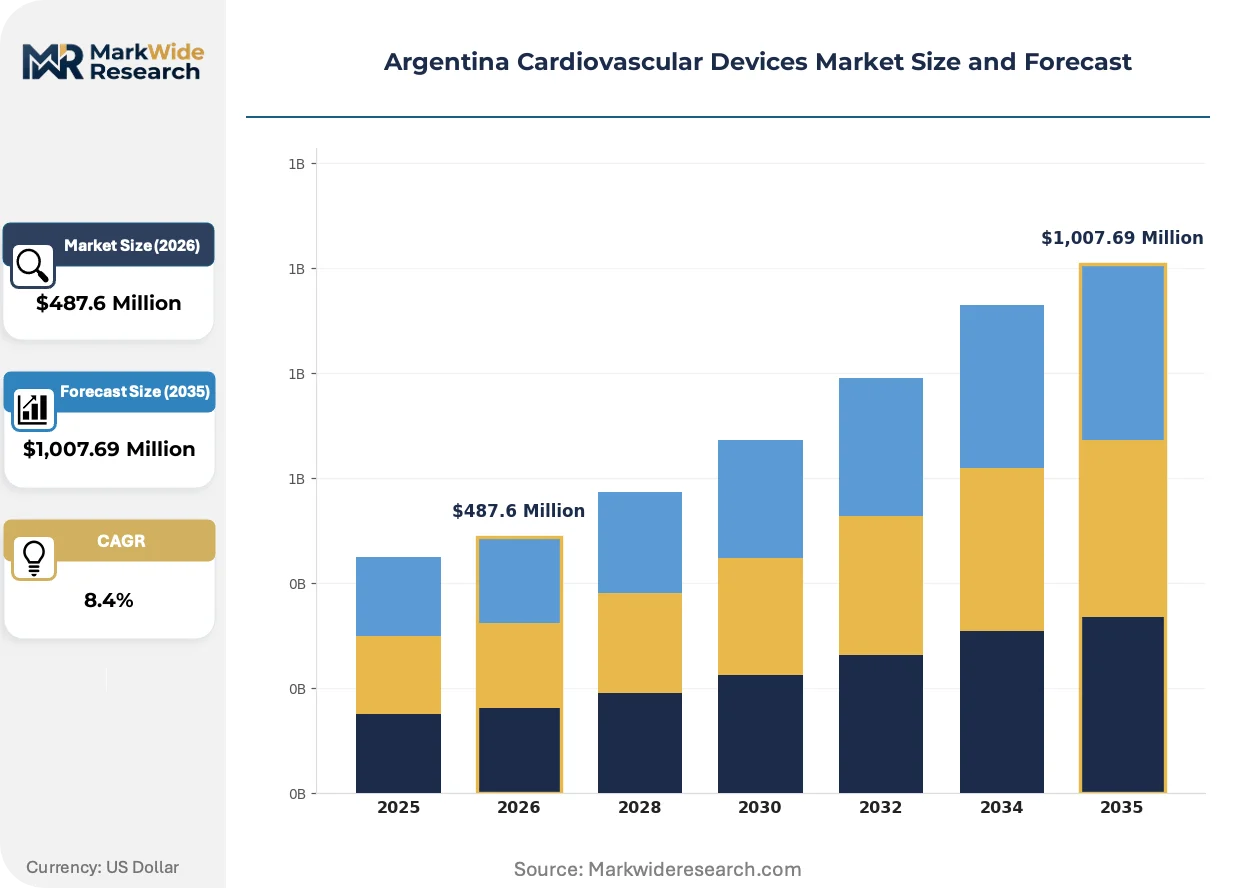
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,007.69 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Pacemakers, Catheters, Valves Technology: Bioabsorbable, Drug-Eluting, Optical Imaging, Pressure Measurement End User: Cardiology Clinics, Hospitals, Research Institutions, Rehabilitation Centers Delivery Mode: Invasive, Minimally Invasive, Remote Monitoring, Surgical |
| Companies Covered | Medtronic, Abbott Laboratories, Boston Scientific Corporation, Siemens Healthineers, Edwards Lifesciences Corporation, W. L. Gore & Associates, Philips Healthcare, Biotronik, Terumo Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Cardiovascular Devices Market Strategic Shifts
Device-software convergence is redefining procedural standards across Argentina's cardiovascular sector. Three developments are compressing traditional competitive boundaries between hardware manufacturers and digital health platforms.
Drug-eluting stent platforms incorporating bioabsorbable polymer coatings are fragmenting market share concentration among metallic bare-metal legacy suppliers. Buenos Aires teaching hospitals are adopting magnesium-based scaffolds at accelerated cadence for single-vessel interventions. The technology is fragmenting procurement committees into imaging-integrated versus conventional device factions.
ANMAT's alignment with Mercosur harmonization standards is compressing registration timelines for imported cardiovascular technologies. The convergence eliminates redundant clinical evidence submissions across Argentina, Brazil, and Uruguay. Stent manufacturers are consolidating regional regulatory strategies around Buenos Aires as the southern cone approval hub.
Public hospital purchasing committees are unbundling device procurement from mandatory technical service contracts. Provincial health ministries in Santa Fe and Córdoba are negotiating direct equipment acquisitions separate from multi-year maintenance agreements. The disaggregation is most visible in catheterization lab expansions where hospitals source imaging systems from Siemens Healthineers while contracting independent biomedical engineering support.
Argentina Cardiovascular Devices Market Segmentation
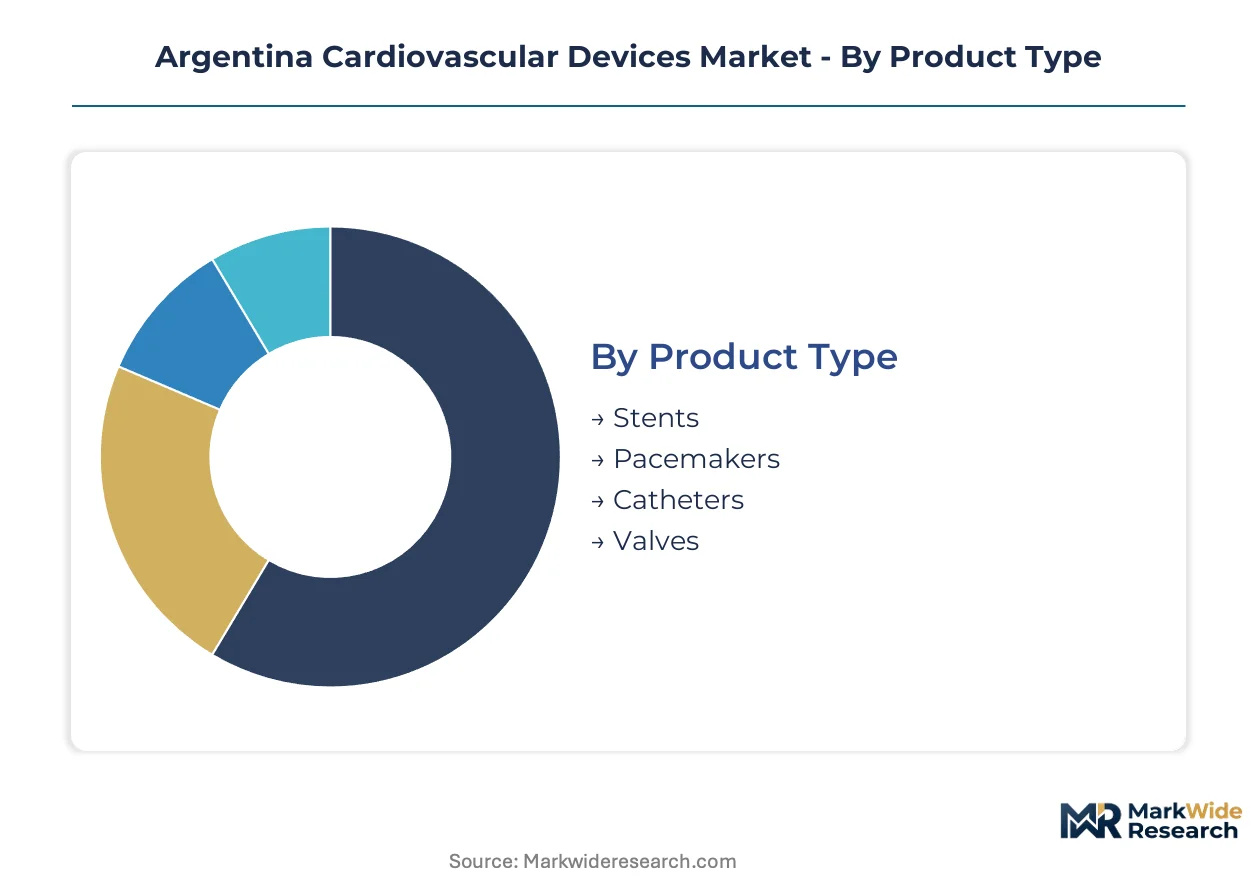
Argentina's cardiovascular device procurement patterns diverge sharply between public hospital networks and private cardiology clinics. Channel concentration in metropolitan Buenos Aires reshapes how each segment reaches end-users across provincial health systems.
Product Type:
Public procurement channels favor stent and catheter volume commitments, while private clinics concentrate pacemaker and valve placements through direct manufacturer relationships.
- Stents:Metallic and bioabsorbable scaffolds engineered from cobalt-chromium alloys or magnesium polymers for coronary revascularization. Buenos Aires teaching hospitals drive demand through interventional cardiology residency programs performing complex multivessel interventions.
- Catheters:Flexible delivery systems combining hydrophilic coatings with torque-responsive shafts for guidewire navigation. Córdoba and Rosario catheterization labs are expanding utilization as optical imaging integration redefines procedural guidance standards.
- Pacemakers:Implantable pulse generators with lithium-iodine batteries and transvenous leads for arrhythmia management.
- Valves:Bioprosthetic and mechanical replacements for aortic and mitral valve dysfunction.
Stents dominate installed base. Catheters are where expansion concentrates.
Technology:
Cost tier stratification separates premium imaging-integrated platforms from standard drug-eluting devices in hospital procurement budgets.
- Bioabsorbable:Magnesium-based scaffolds with controlled resorption timelines eliminating permanent metallic implants. ANMAT's evolving clinical evidence framework constrains adoption to single-vessel cases in high-acuity Buenos Aires institutions.
- Drug-Eluting:Polymer-coated metallic stents releasing antiproliferative agents to suppress neointimal hyperplasia. Provincial health ministries negotiate volume pricing for public hospital networks outside the capital corridor.
- Optical Imaging:Intravascular coherence tomography systems enabling real-time lumen assessment.
- Pressure Measurement:Fractional flow reserve guidewires for physiological lesion assessment.
Drug-eluting platforms anchor current revenue. Bioabsorbable scaffolds are climbing the fastest.
End User:
Volume distribution concentrates in hospital catheterization labs, while margin capture shifts toward specialized cardiology clinics in affluent Buenos Aires neighborhoods.
- Hospitals:Public and private acute-care facilities with catheterization labs performing percutaneous coronary intervention. National health insurance procurement frameworks expand stent and catheter commitments across Argentina's integrated health system.
- Cardiology Clinics:Outpatient facilities specializing in diagnostic electrophysiology and device implantation. Metropolitan Buenos Aires corridors concentrate demand where interventional cardiologists maintain private practices alongside academic appointments.
- Research Institutions:Teaching hospitals conducting clinical trials for ANMAT registration pathways.
- Rehabilitation Centers:Post-intervention cardiac recovery facilities monitoring implanted device function.
Hospitals dominate installed base. Cardiology clinics are gaining share fastest.
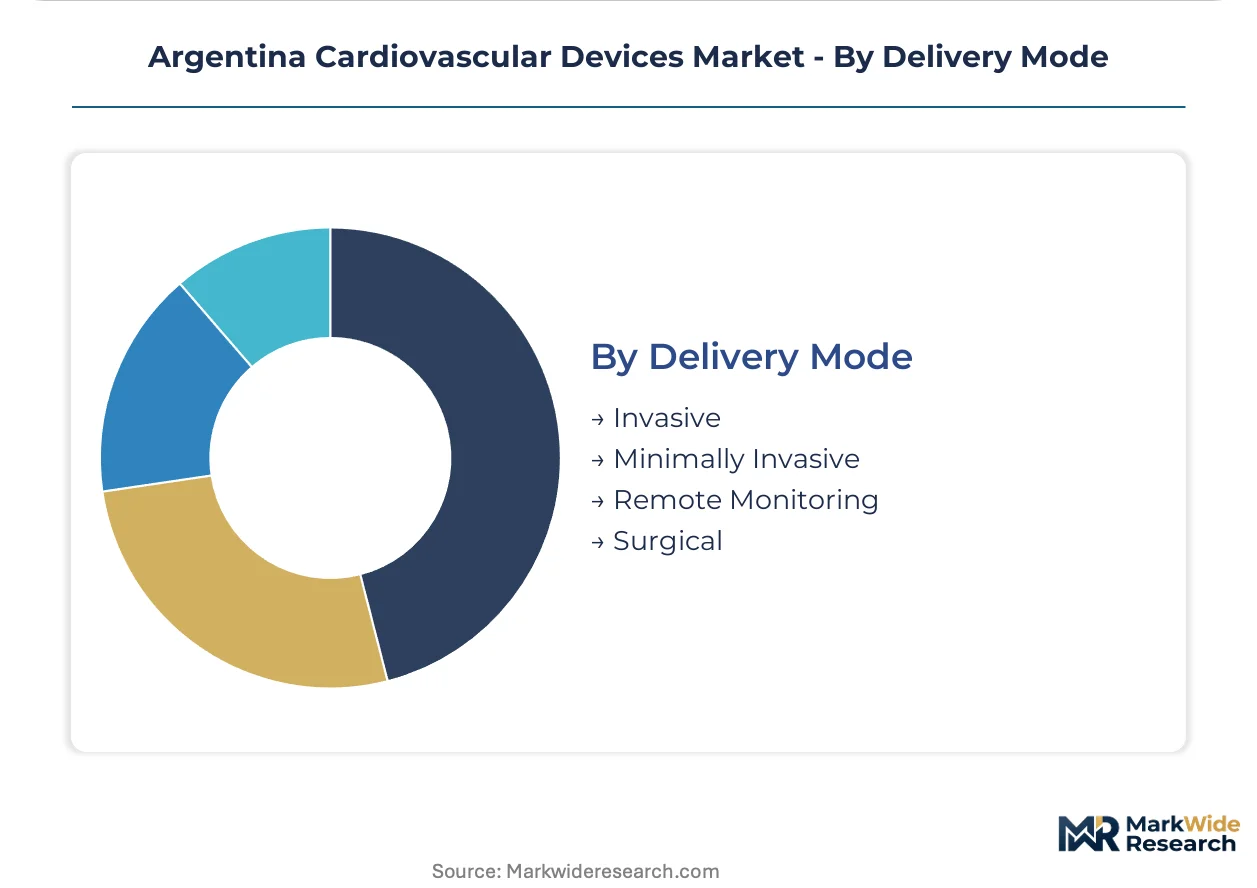
Delivery Mode:
Application requirements stratify between acute intervention settings demanding invasive access and chronic management programs adopting remote monitoring infrastructure.
- Minimally Invasive:Percutaneous techniques via femoral or radial artery access reducing recovery timelines. Teaching hospitals in Buenos Aires and Córdoba are standardizing transradial approaches for diagnostic catheterization and stent deployment.
- Invasive:Surgical sternotomy and thoracotomy for valve replacement and complex congenital repairs. High-acuity cases requiring cardiopulmonary bypass concentrate in capital corridor institutions with specialized perfusion teams.
- Remote Monitoring:Telemetric surveillance of implantable cardiac devices via cellular and satellite networks.
- Surgical:Open-chest procedures for structural cardiac reconstruction.
Minimally invasive approaches dominate installed base. Remote monitoring is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan Buenos Aires exhibits the lowest price elasticity for premium cardiovascular devices, while provincial health ministries in the interior demonstrate acute sensitivity to reimbursement rate fluctuations. This demand-elasticity contrast shapes procurement patterns across Argentina's integrated health system.
Metropolitan Buenos Aires
Interventional cardiology residency programs at teaching hospitals drive concentrated demand for bioabsorbable scaffolds and imaging-integrated platforms. ANMAT's clinical evidence framework receives priority attention from regulators headquartered in the capital. The Córdoba Avenue medical corridor anchors catheterization lab expansions where public and private institutions compete for specialist talent.
Córdoba Province
Provincial health ministry negotiations focus on volume pricing for drug-eluting stents amid constrained reimbursement budgets. The national pharmaceutical regulator ANMAT maintains a regional office facilitating device registration for interior teaching hospitals. The Córdoba city cluster standardizes transradial catheterization approaches across its public hospital network.
Santa Fe Province
Rosario's expanding interventional cardiology training programs generate sustained catheter utilization from emerging specialists. Provincial procurement committees unbundle device purchases from mandatory technical service contracts under revised public purchasing guidelines. The Rosario metropolitan area concentrates private cardiology clinic investment alongside public hospital catheterization lab modernization.
Mendoza Province
Underdeveloped peripheral vascular intervention programs create latent demand for limb revascularization devices as provincial health networks expand coverage. Reimbursement rate negotiations with device suppliers lag capital corridor benchmarks, constraining access to premium technologies. The Greater Mendoza area hosts emerging telecardiology infrastructure connecting remote cardiac patients to Buenos Aires specialists.
Tucumán Province
Public hospital procurement concentrates on essential stent and catheter volumes under national health insurance frameworks with limited margin for innovation adoption. Provincial health ministry pricing negotiations reflect persistent currency volatility exposure for imported device supply chains. The San Miguel de Tucumán metropolitan corridor depends on Buenos Aires-based distributors for device logistics and technical support.
Argentina Cardiovascular Devices Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in Argentina's cardiovascular device sector. The upper tier commands catheterization lab contracts through bundled imaging-platform portfolios, while mid-scale specialists compete on discrete device categories. Two archetypes dominate: diversified medical technology conglomerates leveraging structural cardiac portfolios, and focused interventional device specialists anchoring stent and catheter procurement. Competitive moves concentrate on strategic partnerships with provincial health ministries and technology licensing arrangements for bioabsorbable scaffold distribution.
Among diversified medical technology conglomerates, Medtronic and Abbott Laboratories occupy positions exemplifying integrated portfolio strategies. Medtronic represents the structural cardiac anchor archetype securing high-acuity hospital contracts. Abbott Laboratories exemplifies drug-eluting stent specialization sustaining catheterization lab presence. Siemens Healthineers sits within the diagnostic imaging integration tier, competing on workflow convergence rather than discrete device categories.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Siemens Healthineers |
| Edwards Lifesciences Corporation |
| W. L. Gore & Associates |
| Philips Healthcare |
| Biotronik |
| Terumo Corporation |
| Others |
Value Chain & Pricing Dynamics
Bioabsorbable magnesium alloy substitution for permanent metallic stents is redrawing supplier geography toward German and Japanese polymer specialists while compressing procurement budgets across Argentina's provincial health networks. This material transition simultaneously elevates after-sales technical service premiums and fragments volume pricing power previously concentrated among legacy metallic scaffold manufacturers.
Pricing Analysis
After-sales service contracts and technical training bundles now drive lifetime value capture for catheterization lab equipment suppliers. Three-tier pricing structure across premium imaging-integrated platforms, standard drug-eluting systems, and economy bare-metal devices stratifies procurement committees. Price differentiation hinges on ANMAT registration tier and optical coherence tomography compatibility certification. Pricing pressure stems from provincial health ministry reimbursement rate compression. Public hospital networks exhibit acute price sensitivity; private Buenos Aires cardiology clinics demonstrate lowest elasticity.
Supply Chain Analysis
Germany and Japan anchor bioabsorbable polymer and magnesium alloy production for coronary scaffold manufacturing. Argentina's device imports draw from cobalt-chromium alloy feedstock concentrated in United States and German specialty metal foundries. Supply chain risk centers on single-source vulnerability for optical imaging catheter components. Distribution runs through Buenos Aires-based authorized distributors with provincial logistics partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's cardiovascular device market sits in a post-currency-crisis recovery phase where interventional cardiology residency expansion drives cyclical demand normalization. Provincial health insurance reimbursement negotiations represent the recovery's pacing mechanism.
For Market Incumbents: Consolidate catheterization lab contract bundling around imaging-integrated platforms to defend against unbundling pressure from provincial procurement committees. Deepen backward integration into optical coherence tomography catheter component supply to offset foreign exchange volatility exposure. Anchor high-acuity hospital relationships through interventional cardiologist training program sponsorships. For New Entrants and Emerging Players: Differentiate on telecardiology-enabled remote monitoring platforms for peripheral provinces lacking specialist density. Target Mendoza and Tucumán catheterization lab expansions where incumbent imaging-platform presence remains underdeveloped. Pursue ANMAT-Mercosur harmonization pathway acceleration through Buenos Aires teaching hospital clinical trial partnerships. For Investors and Strategic Acquirers: The market sits at an infrastructure-upgrade phase that favors imaging-integrated platform specialists over discrete device manufacturers. Long-term viability over the next decade hinges on software-hardware convergence capabilities and provincial reimbursement rate stability. Acquisition target archetype: mid-scale catheter specialists with optical imaging integration roadmaps. Signal to watch: ANMAT bioabsorbable scaffold approval velocity for multivessel indications.| Strategic Initiative | Industry Significance |
|---|---|
| ANMAT-Mercosur Harmonization Pathway | Accelerates cross-border registration for Buenos Aires teaching hospital technology access. |
| Hospital System Partnership | Secures catheterization lab expansion contracts in Córdoba and Rosario metropolitan corridors. |
| Software Companion Development | Enables optical imaging integration with stent deployment platforms for precision positioning. |
| Reimbursement Strategy | Aligns provincial health ministry pricing negotiations with national insurance framework expansion. |
| CE Marking Pathway | Supports Mercosur convergence standards for streamlined southern cone market entry. |
Study Parameters
The analysis maps stent and catheter systems, bioabsorbable platforms, and imaging-integrated delivery modes, each validated through interventional cardiologists, hospital purchasing committee members, biomedical engineering directors, and provincial health ministry procurement officers. Primary interview intelligence combined with ANMAT registration databases, GPO contract repositories, and Mercosur harmonization filing records. Bottom-up device utilization modeling and top-down health expenditure triangulation anchored volume estimates.
Consistency checks against hospital procurement database benchmarks and provincial reimbursement rate disclosures validated projection outputs across the analysis window. Segmentation dimensions modeled include technology tier, end-user channel, delivery mode invasiveness, and metropolitan versus provincial geography. CAGRs derived from fitted growth curves incorporating interventional cardiology residency expansion rates and ANMAT approval timelines. Forecast inputs incorporated bioabsorbable scaffold clinical trial progression and optical imaging catheter adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained ANMAT-Mercosur harmonization progress or stabilized provincial reimbursement frameworks would require recalibration. Forecasts reflect documented assumptions regarding interventional cardiologist training program growth and bioabsorbable polymer mechanical performance evolution. Recalibration cycles align with material shifts in ANMAT regulatory guidance and national health insurance procurement policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Single-Use Hemoperfusion Device Market
Cardiovascular Devices
Global Drug Eluting Balloon Catheters Market
Cardiovascular Devices
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market
Cardiovascular Devices
Wearable Cardiac Devices Market
Cardiovascular Devices
Global Blood Pressure Cuffs Market
Cardiovascular Devices
3D Cardiac Mapping Systems Market
Cardiovascular Devices
Brazil Cardiovascular Devices Market
Cardiovascular Devices
Renovascular Hypertension Treatment Market
Cardiovascular Devices
Global Cardiovascular Ultrasound System Market
Cardiovascular Devices
Cardiac Catheters Market
Cardiovascular Devices
US Ventricular Assist Devices Market
Cardiovascular Devices
Human Non-Invasive Blood Pressure (NIBP) Recording System Market
Cardiovascular Devices
Global Intracranial Stents Market
Cardiovascular Devices
Cardiovascular Ultrasound Imaging Systems Market
Cardiovascular Devices
Europe Heart Valve Repair and Replacement Market
Cardiovascular Devices
Pulmonary Stents Market