
 Drug Eluting Stent (DES) Market | 2026-2036
Drug Eluting Stent (DES) Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Eluting Stent (DES) Market Intelligence
Manufacturing expansion in Ireland and China is fragmenting the established supply base for drug eluting stents. Boston Scientific Corporation leverages its extensive clinical trial data to support new product indications for complex patient anatomies. Medtronic specializes in cobalt-chromium platforms with advanced polymer coatings that ensure controlled drug delivery. Abbott Laboratories sustains a strong market presence through its portfolio of everolimus-eluting stents, which are widely adopted in major healthcare systems.
A drug eluting stent is a small, expandable mesh tube used to treat narrowed or weakened arteries in patients with coronary artery disease. It is coated with a slow-release medication, typically an antiproliferative drug like sirolimus or everolimus, to prevent the re-narrowing of the vessel, known as restenosis. Polymer-based stents constitute the largest product segment, while innovation in bioabsorbable materials represents the fastest-growing category. Demand from specialty hospitals for treating complex coronary artery disease continues to drive procedural volume.
Product approvals and market access are governed by stringent regulatory bodies such as the US FDA, the European Union's MDR framework, and China's NMPA. These regulations mandate extensive clinical evidence for safety and efficacy, influencing device design and material selection. Navigating the evolving reimbursement policies and demonstrating long-term clinical value are critical decisions for all device manufacturers seeking to maintain market access and profitability.
Market Dynamics
The convergence of stringent regulatory frameworks like the EU's MDR with advancements in bioabsorbable materials is the central force shaping device design. This pressure dictates both innovation pathways and global market access strategies for manufacturers.
Growth Catalysts
- Bioabsorbable Polymers:Innovation in bioresorbable and biocompatible polymer coatings enhances long-term safety profiles, meeting demands from cardiology clinics for improved patient outcomes post-procedure.
- Aging Demographics:An expanding elderly population in countries like China and Japan increases the prevalence of complex Coronary Artery Disease, directly fueling procedural volume for interventional cardiology.
- Healthcare Access:Government initiatives in emerging economies to expand health insurance coverage and build catheterization lab infrastructure are broadening the patient base for DES procedures.
Market Restraints
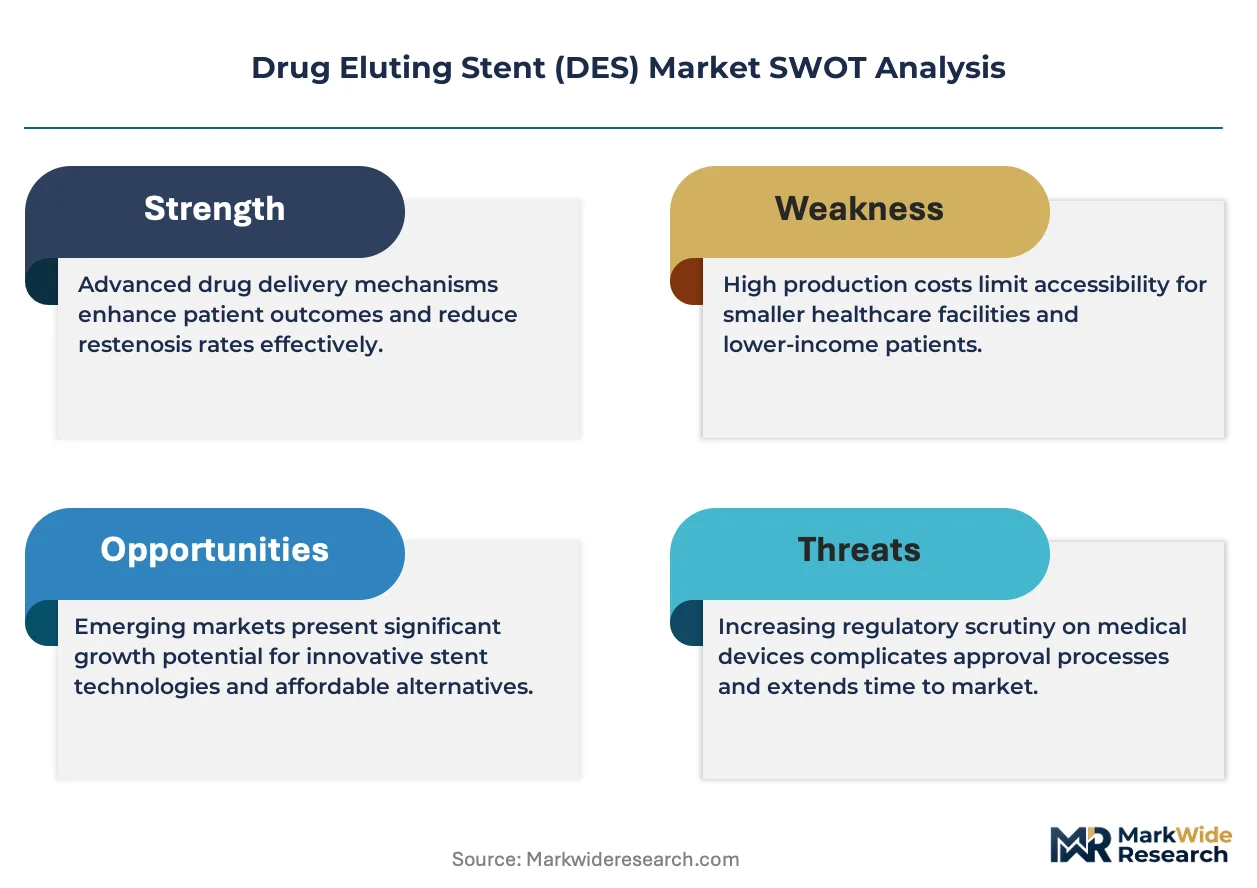
- Regulatory Hurdles:Extensive and costly clinical trial requirements mandated by bodies like the US FDA and China's NMPA create significant barriers to entry and delay new product introductions.
- High Development Costs:The substantial investment needed for research, development, and multi-year clinical follow-up studies for novel DES technologies limits participation to well-capitalized firms.
- Thrombosis Risk:Persistent concerns over the risk of late stent thrombosis with first-generation devices necessitate long-term antiplatelet therapy, a contraindication for some patient cohorts.
Strategic Opportunities
- Peripheral Artery Disease:Adapting DES technology for the treatment of peripheral artery disease (PAD) in leg arteries represents a significant procedural expansion beyond the coronary market.
- Bioresorbable Scaffolds:Development of fully bioresorbable vascular scaffolds (BVS) that dissolve completely after vessel healing offers an opportunity to eliminate permanent implants and associated long-term complications.
- Underpenetrated Regions:Focusing on market entry in Latin America and Southeast Asia, where cardiovascular disease is rising and interventional cardiology infrastructure is developing, provides new growth avenues.
Industry Challenges
- Post-Market Surveillance:The operational burden of complying with the EU MDR's rigorous post-market surveillance and clinical follow-up requirements demands significant investment in data collection systems.
- Reimbursement Pressure:Navigating price controls and competitive bidding processes, such as China's volume-based procurement, challenges manufacturer profitability and investment in next-generation R&D.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Eluting Stent (DES) Market |
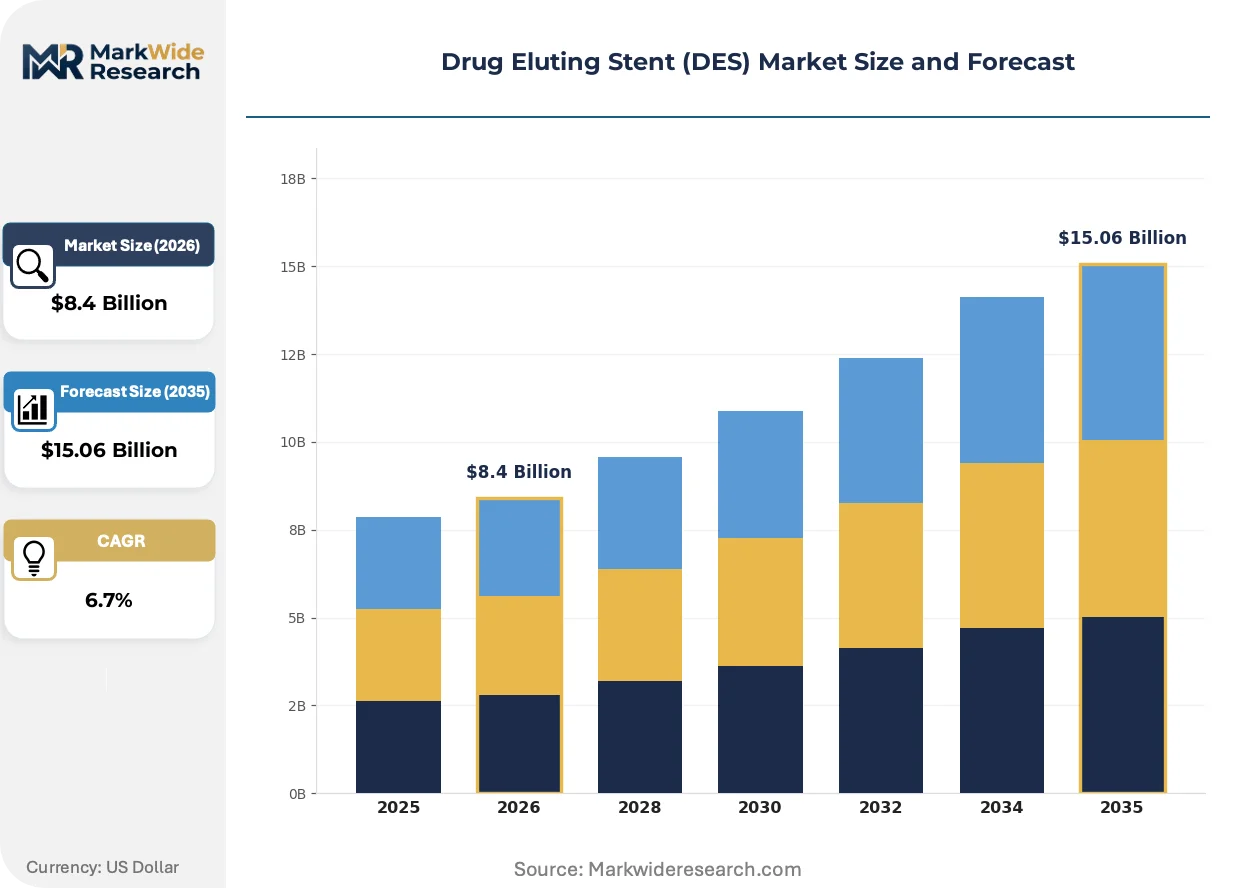
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer-based, Metallic, Bioabsorbable, Ceramic-coated Therapy Area: Coronary Artery Disease, Peripheral Artery Disease, Carotid Artery Disease, Renal Artery Stenosis End User: Cardiology Clinics, Interventional Radiology Centers, Specialty Hospitals, Ambulatory Surgical Centers Deployment: Hospital-based, Outpatient Centers, Catheterization Labs, Cardiac Care Units |
| Companies Covered | Abbott Laboratories, Boston Scientific Corporation, Medtronic, Terumo Corporation, B. Braun Melsungen AG, Biotronik SE & Co. KG, Cook Medical, Biosensors International Group, Ltd., Lepu Medical Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Eluting Stent (DES) Market Strategic Shifts & Innovations
Material science innovations and the integration of real-world clinical data define the next generation of drug eluting stents. This evolution moves beyond simple mechanical scaffolding toward smarter, more biocompatible devices for improved long-term outcomes.
Newer stent platforms feature bio-engineered surfaces or special coatings designed to promote faster healing and reduce the need for potent drugs. These devices are being adopted by interventional cardiologists for patients with a high bleeding risk or contraindications to long-term dual antiplatelet therapy. This technological evolution is hybridizing treatment strategies, combining mechanical support with a more biologically targeted approach to prevent restenosis.
The European Union's Medical Device Regulation (MDR) mandates more stringent pre-market clinical evidence and continuous post-market lifecycle surveillance for all medical devices. This regulation significantly increases the time and cost required to bring new stents to the European market, raising the compliance bar for all manufacturers. The bioabsorbable stent segment is particularly impacted, as companies must now furnish more robust long-term data to notified bodies to prove material safety and performance.
Purchasing decisions are migrating from individual physician preference to centralized value analysis committees within large hospital networks. This shift disrupts the traditional sales model reliant on direct relationships with cardiologists, replacing it with a data-driven procurement process focused on health economics. The trend is most prominent in the United States' integrated delivery networks and across national health systems in Europe, where clinical and cost-effectiveness data are paramount.
Drug Eluting Stent (DES) Market Segmentation
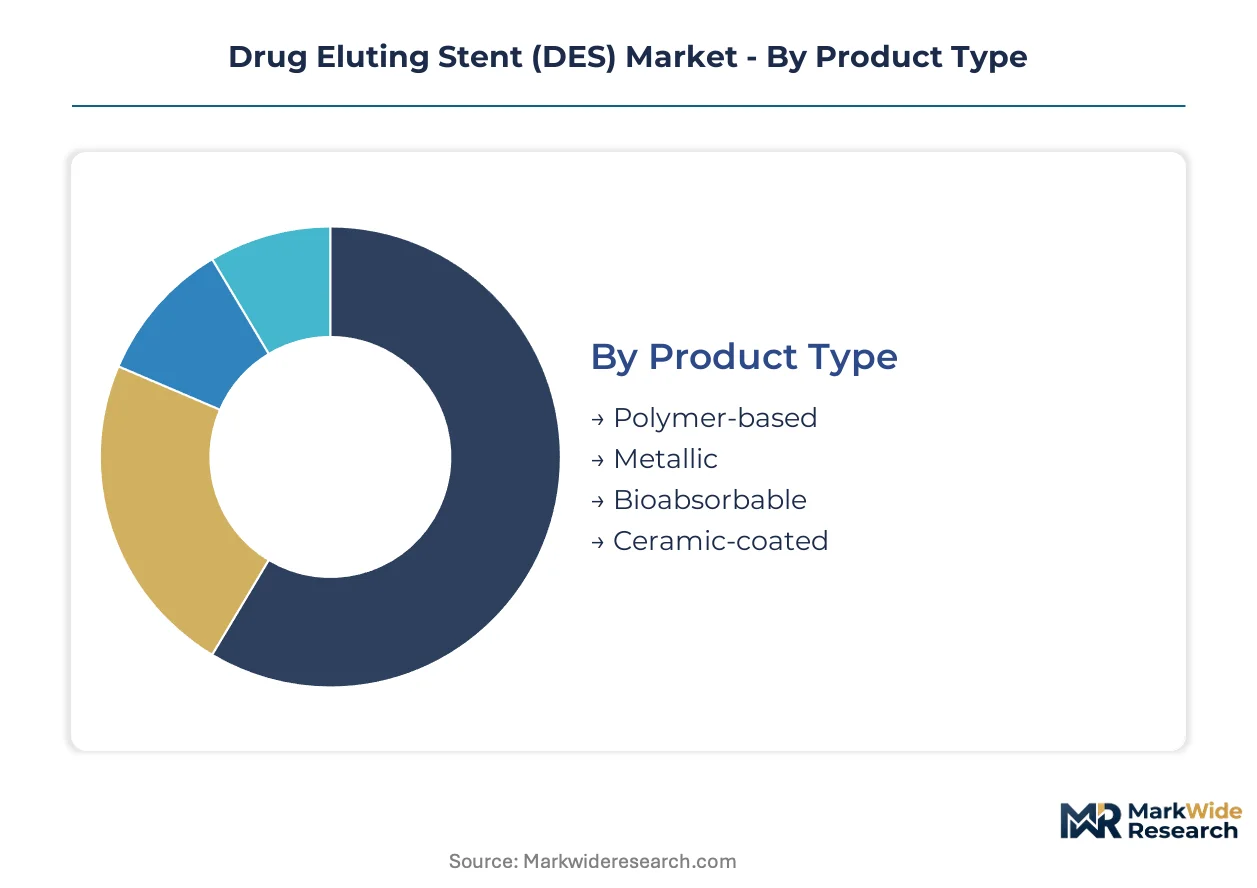
The Drug Eluting Stent (DES) market segmentation delineates the diverse product technologies, clinical applications, and operational settings that define its commercial landscape. Understanding these distinct segments provides clarity on demand drivers and technological evolution across the interventional cardiology sector.
Product Type:
The product type segmentation reflects the diverse clinical applications and material science advancements in drug eluting stents.
- Polymer-based:These stents feature a metallic scaffold coated with a polymer layer that slowly releases antiproliferative drugs, preventing restenosis. Demand is concentrating in established healthcare systems like Germany and Japan due to long-term clinical data supporting their efficacy.
- Bioabsorbable:Designed to dissolve completely after vessel healing, these stents eliminate permanent implants and associated long-term complications. This category is expanding most quickly, driven by patient preference for non-permanent solutions and advancements in material science.
- Metallic:These stents consist of bare metal alloys without drug-eluting coatings, primarily serving as mechanical scaffolds. Clinical use has declined significantly with the advent of drug-eluting technologies, though they retain niche applications.
- Ceramic-coated:These stents incorporate ceramic materials onto their surface, aiming to improve biocompatibility and reduce inflammatory responses. This technology is still in early development phases with limited commercial availability.
The dominant share belongs to Polymer-based, while Bioabsorbable is closing the gap fastest.
Therapy Area:
The therapy area classification highlights the primary medical conditions addressed by drug eluting stents, each requiring specific device adaptations.
- Coronary Artery Disease:This segment involves the treatment of narrowed or blocked arteries supplying blood to the heart, representing the largest procedural volume globally. Demand is consistently high across all developed economies due to the prevalence of cardiovascular risk factors.
- Peripheral Artery Disease:This category targets blockages in arteries outside the heart, particularly in the legs, offering a significant expansion opportunity for DES technology. Procedural growth is notable in countries like the United States as awareness and diagnostic capabilities improve.
- Carotid Artery Disease:These procedures address narrowing of the carotid arteries in the neck, which supply blood to the brain. Stenting in this area requires specific device designs to minimize embolic risk.
- Renal Artery Stenosis:This segment focuses on treating blockages in the arteries supplying the kidneys, often associated with hypertension. Specialized stents are used to restore blood flow and manage blood pressure.
Coronary Artery Disease procedures continue to represent the largest volume, with Peripheral Artery Disease expanding into new patient cohorts.
End User:
The end user segmentation delineates the primary healthcare facilities where drug eluting stent procedures are performed, reflecting specialized infrastructure requirements.
- Cardiology Clinics:These specialized outpatient facilities provide diagnostic, interventional, and follow-up care for cardiac patients. They are a primary point of contact for patient referrals and post-procedure management in many European countries.
- Specialty Hospitals:These institutions focus exclusively on specific medical fields, such as cardiac care, offering comprehensive services and advanced interventional capabilities. Their demand is driven by the management of complex coronary artery disease cases.
- Interventional Radiology Centers:These centers utilize image-guided techniques for minimally invasive procedures, including peripheral artery stenting. Their role is expanding, particularly for non-coronary applications.
- Ambulatory Surgical Centers:These facilities provide same-day surgical care, with a growing trend towards performing less complex interventional procedures. Cost-efficiency drives their increasing utilization for suitable patients.
Cardiology Clinics and Specialty Hospitals collectively account for the majority of stent implantations, driven by their specialized expertise.
Deployment:
The deployment setting categorizes where drug eluting stent procedures occur, influenced by patient acuity and available interventional cardiology infrastructure.
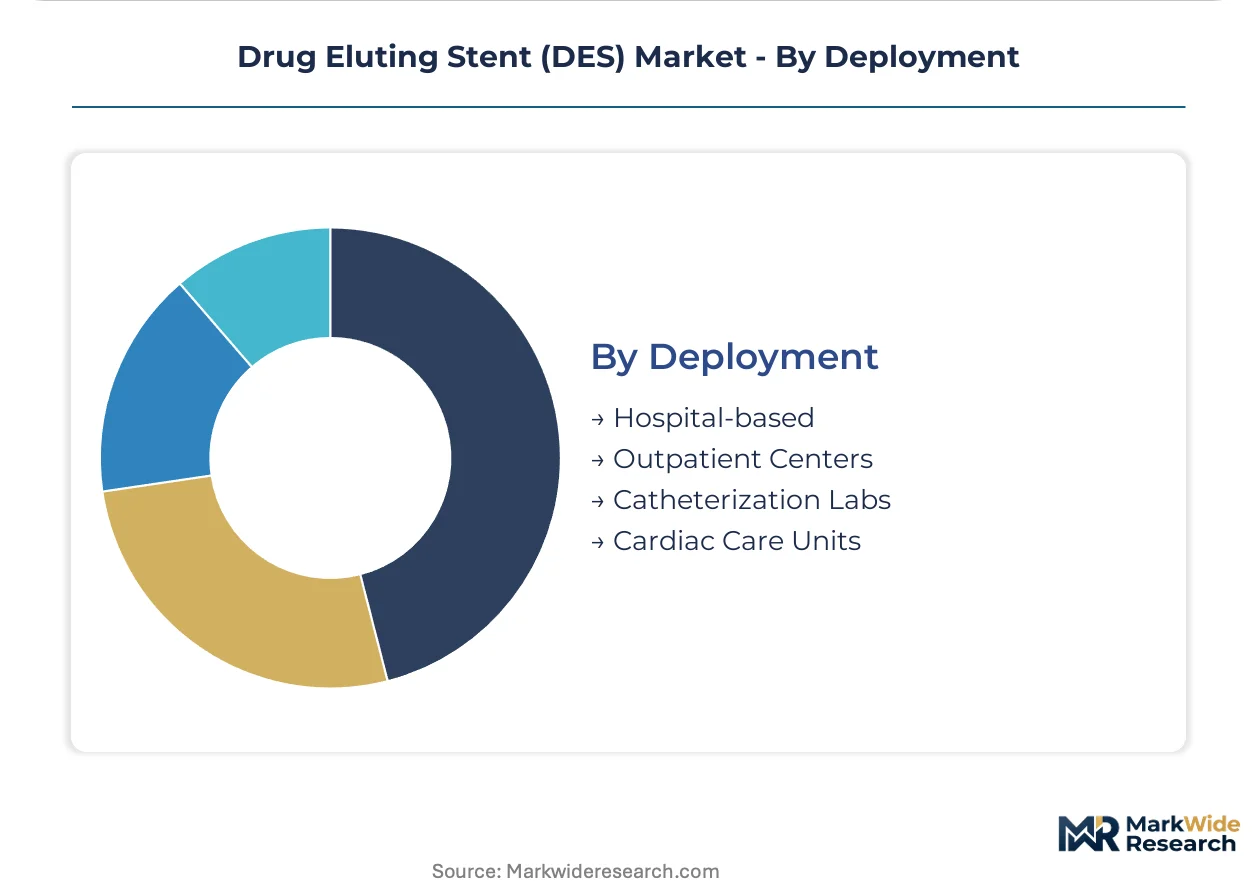
- Hospital-based:These procedures are performed within a traditional hospital setting, providing access to extensive support services and emergency care. Most complex and high-risk DES implantations occur in this environment globally.
- Catheterization Labs:These dedicated units within hospitals or standalone centers are equipped for minimally invasive cardiac and vascular procedures. The expansion of catheterization lab infrastructure in China and India directly fuels procedural volume.
- Outpatient Centers:These facilities offer procedures that do not require an overnight hospital stay, focusing on patient convenience and cost reduction. Selection of patients for these settings is carefully managed.
- Cardiac Care Units:These specialized hospital units provide intensive monitoring and care for patients with severe heart conditions, including post-procedure recovery. They manage patients requiring close observation immediately after stent placement.
Hospital-based interventions remain the standard for complex cases, while Catheterization Labs are increasingly central to routine procedures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for drug-eluting stents varies significantly across global markets. Established economies prioritize advanced polymer-based and bioabsorbable solutions, while emerging regions expand access to basic DES technologies. Regulatory frameworks and aging demographics heavily influence product adoption.
China
China's aging population and government initiatives are fueling demand for DES procedures. The NMPA mandates rigorous clinical evidence for device approvals, influencing local product development. Manufacturing expansion in cities like Shanghai supports the domestic supply chain.
United States
The United States market exhibits high demand for advanced DES, driven by complex coronary artery disease and integrated delivery networks. US FDA regulations impose extensive clinical trial requirements, shaping device design. Medical device clusters in Boston focus on developing novel polymer coatings.
Germany
Germany's established healthcare system and preference for proven clinical data sustain demand for polymer-based DES. The EU MDR framework significantly increases compliance costs and market access hurdles. Cardiology clinics in Munich lead the adoption of advanced interventional techniques.
Japan
Japan's rapidly aging demographics contribute to a high prevalence of coronary artery disease, driving consistent demand. The PMDA ensures strict regulatory oversight, emphasizing product quality and long-term patient safety. Advanced medical centers in Tokyo are actively involved in clinical trials for bioresorbable scaffolds.
India
India's expanding health insurance coverage and government initiatives are broadening the patient base for DES. The CDSCO governs medical device approvals, ensuring quality standards and affordability. Major cities such as Mumbai are developing into significant hubs for interventional cardiology procedures.
Drug Eluting Stent (DES) Market Key Industry Players
Capability concentration sits with one tier of device manufacturers, while scale advantage sits with another, creating a tiered market structure. The market for drug-eluting stents is dominated by established multinational corporations with extensive R&D capabilities and global distribution networks. These firms exemplify archetypes ranging from innovation-driven specialists to broad-portfolio providers. Strategic partnerships for technology licensing and continuous portfolio diversification are common competitive moves among these players.
Within the established multinational archetype, Abbott Laboratories, Boston Scientific Corporation, and Medtronic exemplify global market leadership. These companies, often US-based or with significant global operations, occupy a position characterized by extensive clinical trial data and robust regulatory compliance across diverse geographies. Their market presence is anchored by a history of continuous product innovation and widespread adoption within major healthcare systems worldwide. These firms consistently leverage their comprehensive cardiovascular offerings to maintain market access and profitability amidst evolving regulatory landscapes. Such players typically invest heavily in next-generation material science and controlled drug delivery systems.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Boston Scientific Corporation |
| Medtronic |
| Terumo Corporation |
| B. Braun Melsungen AG |
| Biotronik SE & Co. KG |
| Cook Medical |
| Biosensors International Group, Ltd. |
| Lepu Medical Technology Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Shanghai's expanding manufacturing capacity for drug-eluting stents influences global pricing power, particularly for standard polymer-based devices. This localized production capability creates competitive dynamics across diverse healthcare systems.
Pricing Analysis
Geographic price spreads for drug-eluting stents reflect varying reimbursement policies and market maturity. The dominant pricing model incorporates contract-based long-term agreements with major hospital networks, alongside value-based pricing for innovative bioabsorbable solutions. Price differentiation stems from extensive clinical evidence supporting efficacy and the complexity of advanced polymer coatings. Cost compression in China intensifies due to volume-based procurement policies. Centralized value analysis committees in developed economies exhibit high price sensitivity, while specialty hospitals prioritize clinical outcomes.
Supply Chain Analysis
Upstream feedstock for drug-eluting stents, such as cobalt-chromium alloys and specialized bioabsorbable polymers, primarily originates from highly specialized chemical and metallurgical suppliers. Supply chain concentration exists across manufacturing hubs in China, Ireland, and the United States. A structural risk involves regulatory restrictions imposed by bodies like the EU MDR on material biocompatibility and long-term degradation profiles. Distribution runs through direct sales forces engaging hospital procurement and specialized cardiology clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Navigating the drug-eluting stent market demands specialized expertise in complex material science and stringent regulatory compliance. This market is defined by a scarcity of deep capabilities in developing and validating next-generation bioabsorbable polymer coatings.
For Market Incumbents: Build a regulatory moat through continuous investment in extensive clinical trials that meet US FDA and EU MDR requirements. Diversify product portfolios by adapting DES technology for peripheral artery disease and fully bioresorbable scaffolds. This defends against margin pressure from volume-based procurement and competition from emerging specialists. Leverage R&D in advanced polymer coatings to maintain product differentiation.
For New Entrants and Emerging Players: Latin America and Southeast Asia represent significant underpenetrated regions for drug-eluting stents, driven by rising cardiovascular disease and developing healthcare infrastructure. Target these white spaces with cost-effective, clinically validated polymer-based stents and bioabsorbable solutions. The most penetrable segment involves countries expanding health insurance coverage and catheterization lab infrastructure. A go-to-market angle focusing on local clinical evidence and affordability can accelerate market entry.
For Investors and Strategic Acquirers: Long-term, this sits as a technology-driven consolidation play because persistent cardiovascular disease ensures sustained demand for innovative interventional devices. Acquisition targets should focus on niche firms specializing in bioabsorbable material science or advanced drug delivery systems. The acceleration of bioresorbable scaffold approvals by regulatory bodies like the NMPA would serve as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Clinical Trial Investment | Secures new product indications for complex patient anatomies, satisfying US FDA and EU MDR mandates. |
| Bioabsorbable Material R&D | Develops next-generation stents that eliminate permanent implants, meeting patient and clinician preferences. |
| Peripheral Artery Disease Expansion | Extends drug-eluting stent technology beyond coronary applications, broadening procedural volume. |
| Emerging Market Entry | Captures new patient cohorts in regions like Latin America with developing interventional cardiology infrastructure. |
| Hospital System Partnership | Ensures product adoption and market access through centralized value analysis committees in major healthcare networks. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to build a robust understanding of the drug-eluting stent market. Primary interviews with interventional cardiologists, hospital procurement managers, regulatory affairs specialists, and medical device engineers provided qualitative insights. These were triangulated with secondary data from US FDA filings, EU MDR guidance documents, NMPA approval databases, and industry association reports. A combination of bottom-up and top-down approaches validated market sizing.
The quantitative model was calibrated through a multi-stage process, integrating historical market performance with future growth drivers across the analysis window. Segmentation dimensions included product type, therapy area, end-user, deployment, and regional regulatory frameworks. Compound annual growth rates were derived from a synthesis of supply-side capacity expansions and demand-side procedural volume projections. Key inputs included the prevalence of coronary artery disease and adoption rates of bioabsorbable materials.
The forecast holds incumbent behavior within observed patterns; aggressive moves by innovation-driven specialists or broad-portfolio providers would shift outcomes. Forecasts reflect documented assumptions regarding regulatory stability and technological evolution. Material shifts in regulatory approval pathways or unforeseen material science breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Medical Devices Cuffs Market
Cardiovascular Devices
Global Intravascular Catheters Market
Cardiovascular Devices
LAMEA Cardiac Surgical Devices Market
Cardiovascular Devices
Cardiovascular Repair and Reconstruction Devices Market
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
Chronic Total Occlusion Catheter Market
Cardiovascular Devices
Integrated Cardiology Devices Market
Cardiovascular Devices
Cardiovascular CT Systems Market
Cardiovascular Devices
Single-Use Hemoperfusion Device Market
Cardiovascular Devices
Latin America Compression Therapy Market
Cardiovascular Devices
US Ventricular Assist Devices Market
Cardiovascular Devices
Europe Cardiac Assist Devices Market
Cardiovascular Devices
Global Coil Wound Devices Market
Cardiovascular Devices
Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
Global Aortic Repair Devices Market
Cardiovascular Devices
Global Heart Pump Devices Market