
 Neuroendovascular Coil Market | 2026-2036
Neuroendovascular Coil Market Size, Share, and Industry Trends Forecast 2026-2036
Neuroendovascular Coil Market Intelligence
Microcatheter technology is reshaping how neuroendovascular coils navigate distal cerebral anatomy during endovascular aneurysm repair. Medtronic leverages its integrated neurovascular portfolio to sustain leadership in detachable coil systems across major stroke centers. Stryker anchors its competitive position through R&D intensity in hydrophilic coating platforms that reduce friction during coil delivery. Penumbra differentiates via specialization in aspiration-compatible coil technologies that address complex wide-neck aneurysm morphologies.
Neuroendovascular coils are platinum-tungsten or nitinol-based embolic devices delivered through microcatheters to occlude cerebral aneurysms and arteriovenous malformations by promoting thrombosis within the target lesion. Detachable coils dominate procedural volume due to their controlled deployment mechanism and established safety profile in intracranial aneurysm treatment. Pushable coils occupy a narrower margin pool primarily in cost-constrained settings where simpler aneurysm geometries permit less expensive embolization approaches. Hospital end users concentrate purchasing power through bundled procurement contracts that favor suppliers with broad neurointerventional device portfolios.
FDA premarket notification requirements and ISO 13485 quality management standards govern coil design validation and clinical testing protocols for U.S. market access. EMA Medical Device Regulation compliance shapes European commercialization timelines through enhanced clinical evidence requirements for Class III implantable devices. Japan's PMDA enforces stringent biocompatibility and fatigue testing standards that filter market entrants. Stakeholders must monitor evolving real-world evidence requirements that regulators increasingly demand for long-term aneurysm occlusion durability claims.
Market Dynamics
Stroke center consolidation across tertiary hospitals is concentrating purchasing power into fewer procurement committees, forcing coil manufacturers to bundle neurovascular portfolios or face exclusion from catheter-to-coil system contracts.
Growth Catalysts
- EMA MDR compliance pathways:Enhanced clinical evidence requirements for Class III implantable devices are accelerating real-world data collection infrastructure that improves long-term occlusion tracking.
- Hydrophilic coating platforms:Friction-reducing surface treatments are expanding treatable aneurysm geometries by enabling navigation through tortuous middle cerebral artery branches.
- Japan's aging demographics:PMDA reimbursement pathways for endovascular aneurysm repair are supporting procedural volume expansion in metropolitan stroke centers.
Market Restraints
- Platinum-tungsten alloy supply:Concentrated mining and refining operations in select geographies create input cost volatility for coil raw materials.
- FDA premarket notification timelines:Extended 510(k) review periods for modified coil designs delay commercialization of incremental delivery system improvements.
- Flow diversion catheters:Stent-based aneurysm exclusion technologies are capturing select large-neck aneurysm cases previously treated with dense coil packing.
Strategic Opportunities
- Germany's bundled reimbursement pilots:Diagnosis-related group carve-outs for stroke care are creating integrated device procurement opportunities across hospital networks.
- AI-enabled procedural planning:Computational fluid dynamics integration with coil sizing algorithms is virtualizing pre-operative aneurysm modeling workflows.
- Ambulatory surgical centers:Selected elective aneurysm cases are migrating to outpatient settings with streamlined device logistics requirements.
Industry Challenges
- Neurointerventionalist training pipelines:Fellowship program capacity constraints limit the pool of physicians qualified for complex aneurysm embolization procedures.
- ISO 13485 audit cycles:Recertification timelines for quality management systems disrupt manufacturing schedule coordination across multi-site coil production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neuroendovascular Coil Market |
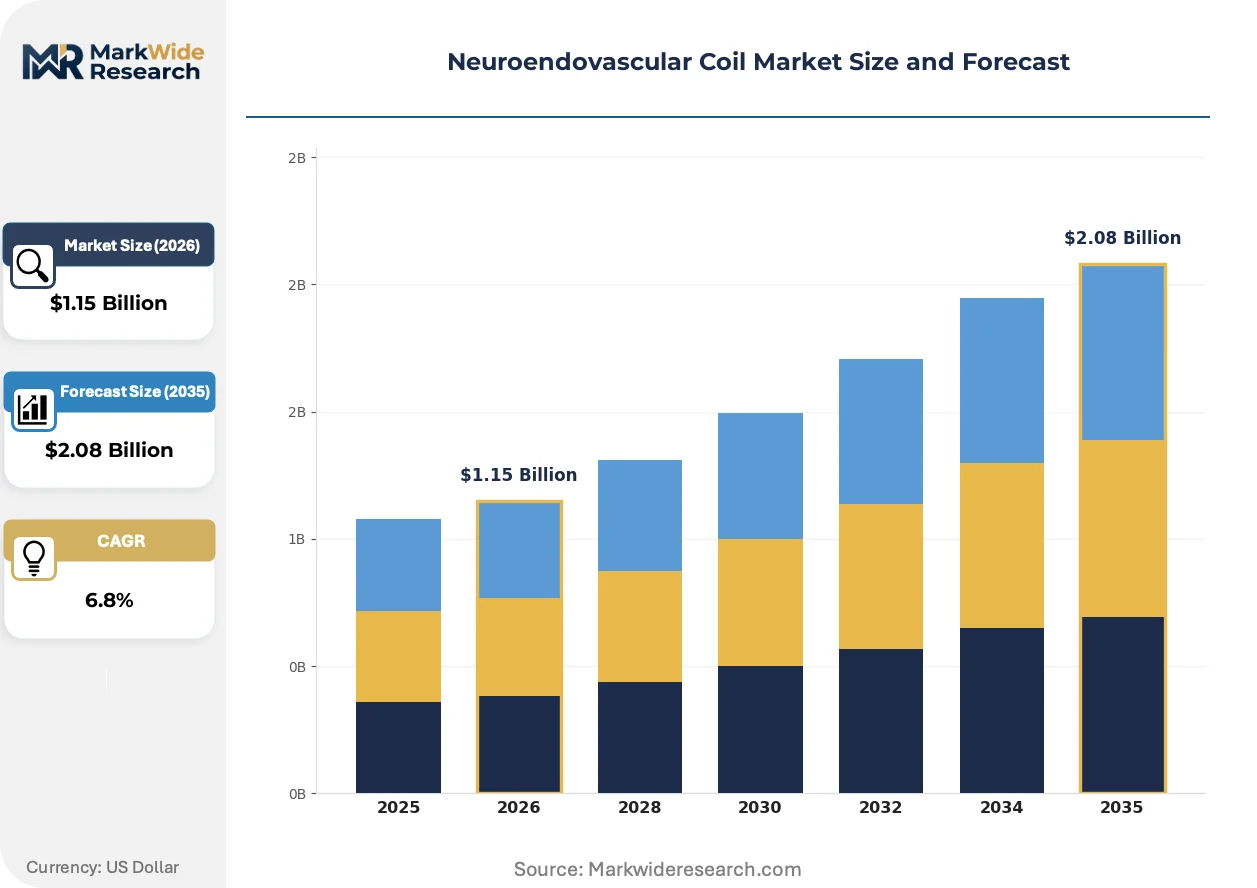
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.08 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Detachable Coils, Pushable Coils, Stent Coils, Other Coils End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Academic Research Institutions Application: Cerebral Aneurysms, Arteriovenous Malformations, Intracranial Aneurysms, Other Applications Technology: Hydrophilic Coating, Biodegradable Materials, Microcatheter Technology, Other Technologies |
| Companies Covered | Medtronic, Stryker, Penumbra, MicroVention, Terumo Corporation, Johnson & Johnson, Balt, Boston Scientific Corporation, DePuy Synthes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neuroendovascular Coil Market Strategic Shifts & Innovations
Computational modeling and surface engineering are converging to redefine how coil systems interact with aneurysm hemodynamics, shifting competitive advantage toward integrated device-data platforms rather than standalone mechanical performance.
Bioactive polymer coatings are virtualizing the thrombogenic response timeline by accelerating endothelialization across coil surfaces. Academic stroke centers in the United States are piloting these modified devices for previously untreatable wide-neck morphologies. The structural consequence is compressing the window between initial deployment and durable aneurysm exclusion, reducing retreatment rates.
Japan's PMDA has tightened biocompatibility testing protocols for nitinol-based implantables, extending preclinical validation requirements by six to nine months. Domestic manufacturers are absorbing these compliance costs through dedicated Yokohama testing facilities. European coil suppliers without Japan-specific regulatory infrastructure are ceding share to local competitors with established PMDA relationships.
Hospital procurement committees are unbundling coil purchasing from legacy catheter supply agreements, creating direct vendor relationships for high-volume embolization centers. This disintermediation favors suppliers with standalone coil portfolios and dedicated clinical specialist teams. The shift is most visible in United States academic medical centers where value-analysis committees now separate device categories for competitive bidding.
Neuroendovascular Coil Market Segmentation
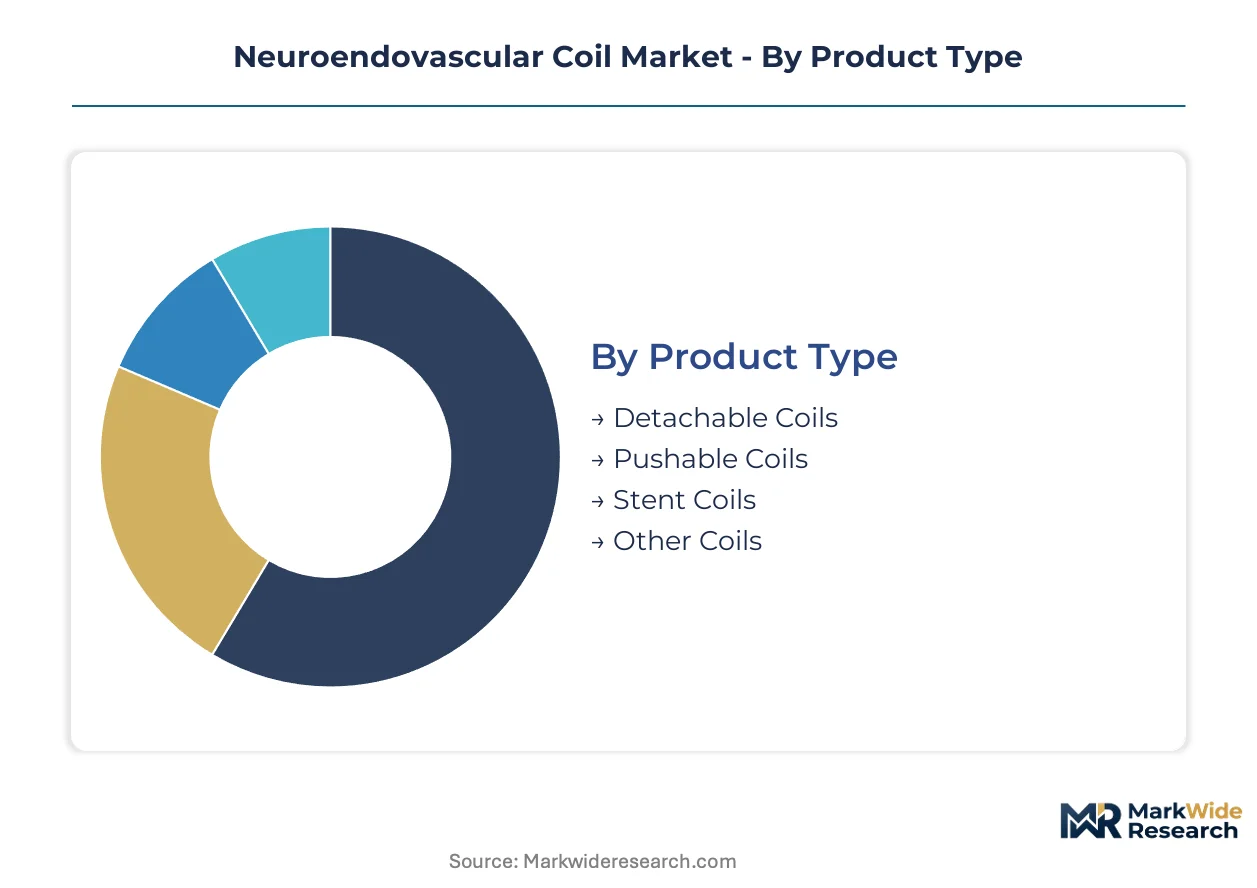
Neuroendovascular coil segmentation reflects divergent clinical workflows across stroke centers and research institutions. Product architecture, delivery technology, and care setting economics create distinct procurement patterns that manufacturers must navigate simultaneously.
Product Type:
Mature platinum-based systems anchor procedural volume while emerging configurations address unmet anatomical challenges.
- Detachable Coils:Platinum-tungsten alloy constructs with electrolytic or mechanical detachment mechanisms enable controlled deployment within intracranial aneurysms. Stroke centers in the United States, Germany, and Japan concentrate demand through bundled catheter-to-coil procurement contracts that favor established safety profiles.
- Pushable Coils:Simpler mechanical deployment without detachment capability reduces per-procedure costs for straightforward aneurysm morphologies. Cost-constrained hospital systems in select European markets deploy these for eligible cases to preserve reimbursement margins under diagnosis-related group frameworks.
- Stent Coils:Hybrid constructs combining flow-diverting stent platforms with embolic coil delivery.
- Other Coils:Specialty configurations including liquid embolic adjuncts and experimental bioabsorbable prototypes.
Detachable Coils handle the majority of throughput; Pushable Coils are expanding most quickly in cost-sensitive procurement environments.
End User:
Care setting economics stratify purchasing authority from high-acuity hospital networks to distributed outpatient facilities.
- Hospitals:Tertiary stroke centers with 24/7 neurointerventional coverage dominate coil consumption through value-analysis committees that negotiate multi-year device agreements. Academic medical centers in the United States and Germany drive adoption of next-generation hydrophilic coating platforms through investigator-initiated trials.
- Ambulatory Surgical Centers:Outpatient settings with streamlined logistics requirements are capturing selected elective aneurysm cases previously hospitalized overnight. United States reimbursement carve-outs for same-day discharge are accelerating site-of-service migration for uncomplicated procedures.
- Specialty Clinics:Focused neurovascular practices with hybrid angiography suites.
- Academic Research Institutions:University-affiliated centers conducting FDA and EMA premarket clinical trials.
Hospitals retain dominant purchasing leverage; Ambulatory Surgical Centers are climbing the fastest on procedure volume share.
Application:
Anatomical target selection determines device specification requirements and reimbursement pathway eligibility.
- Cerebral Aneurysms:Saccular and fusiform dilations of intracranial arteries represent the primary indication for coil embolization. Middle cerebral artery and anterior communicating artery locations in aging patient populations across Japan and Western Europe sustain procedural demand.
- Arteriovenous Malformations:High-flow nidus structures require dense packing with specialized framing and finishing coil configurations. United States academic centers with multidisciplinary cerebrovascular programs handle complex AVM cases through staged embolization protocols.
- Intracranial Aneurysms:Subarachnoid hemorrhage presentations with ruptured aneurysm morphology.
- Other Applications:Dural arteriovenous fistulas and select tumor embolization procedures.
Cerebral Aneurysms command the largest procedure base; Arteriovenous Malformations are gaining share fastest among high-complexity referral centers.
Technology:
Surface engineering and delivery system advances are redefining treatable anatomy and procedural efficiency benchmarks.
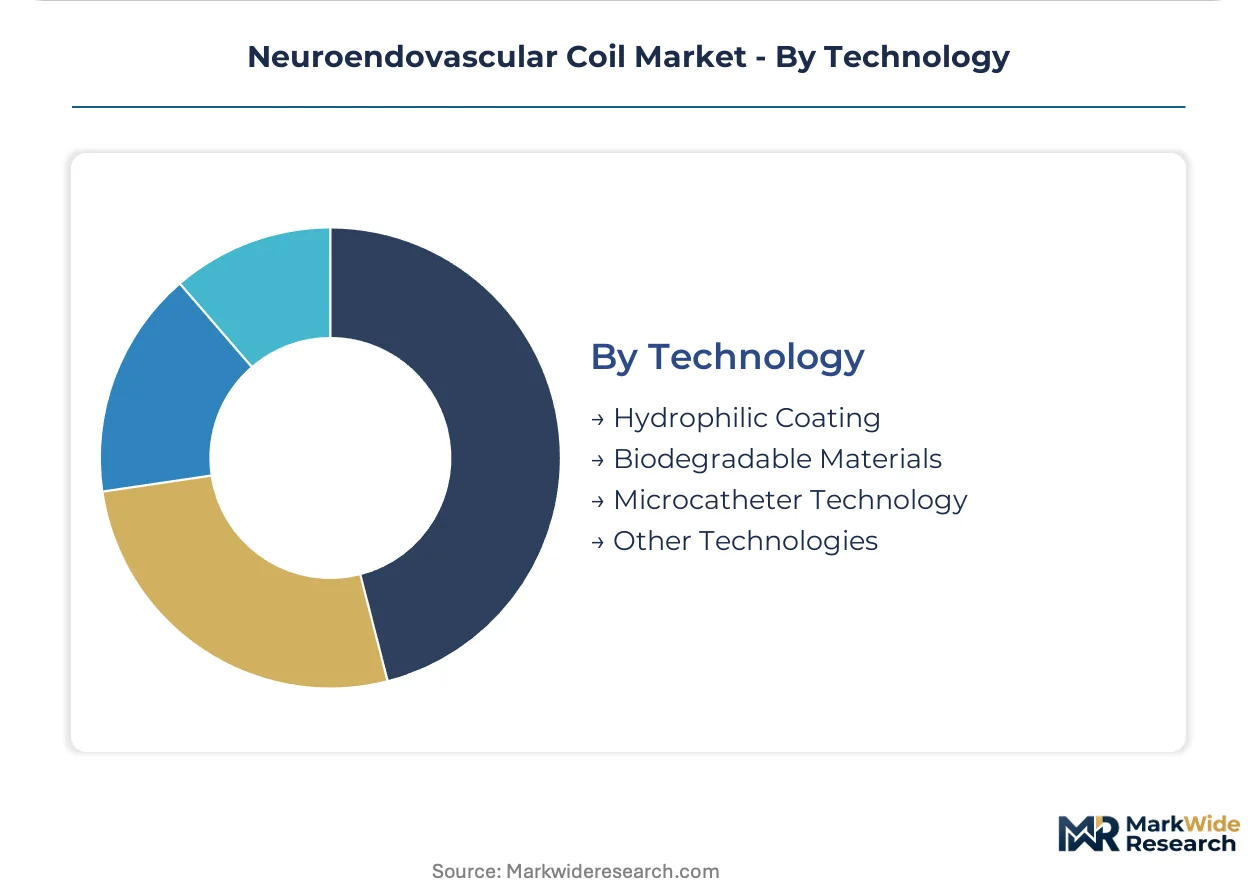
- Hydrophilic Coating:Polymer surface treatments reduce friction coefficients between coil and microcatheter, enabling navigation through tortuous M1 and M2 segment anatomy. Stryker and Medtronic platforms with proprietary coating chemistries are expanding treatable aneurysm geometries previously considered inaccessible.
- Microcatheter Technology:Distal access catheter designs with variable stiffness profiles optimize coil delivery through sharp vascular angles. Japanese manufacturers with Yokohama-based production facilities leverage PMDA-compliant quality systems to supply domestic stroke centers.
- Biodegradable Materials:Experimental polymers designed to accelerate endothelialization and reduce late retreatment rates.
- Other Technologies:Shape-memory alloys and robotic-assisted deployment systems in preclinical development.
Hydrophilic Coating underpins current commercial differentiation; Microcatheter Technology is the steepest expansion trajectory as delivery precision becomes the competitive battleground.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tertiary stroke centers concentrate purchasing power in aging metropolitan regions where reimbursement pathways for endovascular aneurysm repair have matured. Hospital procurement committees in these markets negotiate bundled catheter-to-coil contracts that favor suppliers with integrated neurovascular portfolios.
United States
Academic medical centers in Boston and Baltimore drive adoption of hydrophilic coating platforms through investigator-initiated trials. FDA premarket notification pathways govern 510(k) submissions for modified coil designs. The Cleveland Clinic and Mayo Clinic stroke networks concentrate procedural volume for complex wide-neck aneurysm cases.
Germany
Diagnosis-related group carve-outs for stroke care create integrated device procurement opportunities across hospital networks. EMA Medical Device Regulation compliance shapes commercialization timelines through enhanced clinical evidence requirements. The Rhine-Ruhr metropolitan region anchors coil consumption through consolidated tertiary stroke center purchasing.
Japan
PMDA reimbursement pathways support procedural volume expansion in Tokyo and Osaka metropolitan stroke centers. Stringent biocompatibility and fatigue testing standards filter market entrants through extended preclinical validation. Yokohama-based production facilities supply domestic manufacturers with PMDA-compliant quality systems.
United Kingdom
NHS England specialized commissioning frameworks concentrate coil purchasing through designated neuroscience centers in London and Manchester. MHRA post-market surveillance requirements track long-term aneurysm occlusion durability. The Oxford-Cambridge corridor hosts clinical trial infrastructure for next-generation bioactive polymer coatings.
France
ANSM oversight of Class III implantable devices aligns with EMA MDR transition timelines for coil manufacturers. Regional hospital groupings in Île-de-France and Auvergne-Rhône-Alpes consolidate neurointerventional purchasing through GHT governance structures. Parisian academic centers pilot computational fluid dynamics integration with coil sizing algorithms.
Neuroendovascular Coil Market Key Industry Players
Channel-controlling players compete with product-specialist players across procurement tiers defined by portfolio breadth versus technical depth. The market structure concentrates around integrated medical device conglomerates with catheter-to-coil system offerings alongside focused neurovascular specialists. Three archetypes dominate: full-spectrum neurointerventional suppliers, coil-delivery technology specialists, and aspiration-compatible device innovators. M&A activity targets microcatheter technology assets while strategic partnerships address EMA MDR compliance cost-sharing.
Among diversified medical technology conglomerates, Medtronic and Stryker exemplify channel-controlling archetypes with integrated neurovascular portfolios spanning access catheters through embolic devices. Penumbra occupies a specialist position focused on aspiration-compatible coil technologies for complex anatomies. These three companies anchor the competitive landscape through differentiated approaches to stroke center procurement relationships.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Penumbra |
| MicroVention |
| Terumo Corporation |
| Johnson & Johnson |
| Balt |
| Boston Scientific Corporation |
| DePuy Synthes |
| Others |
Cost & Logistics Intelligence
Yokohama's PMDA-compliant manufacturing cluster concentrates coil production capacity for Japanese and select Asia-Pacific markets, translating regulatory compliance investments into pricing power for domestic suppliers serving metropolitan stroke centers.
Pricing Analysis
Cost-plus contracts with platinum-tungsten alloy indexation dominate procurement agreements between tertiary stroke centers and coil manufacturers. Three-tier pricing structure across premium hydrophilic-coated systems, standard platinum-tungsten platforms, and economy pushable configurations stratifies the market by clinical complexity and reimbursement tier. Pricing pressure stems from hospital value-analysis committees unbundling catheter-to-coil agreements and demanding standalone coil competitive bidding. Cost-constrained European hospital systems under diagnosis-related group frameworks exhibit highest price sensitivity, while United States academic medical centers prioritize clinical performance over per-unit cost.
Supply Chain Analysis
Contract manufacturing concentrates with specialized nitinol wire drawing facilities in Japan, platinum-tungsten alloy processors in Germany, and polymer coating applicators in the United States. Raw material dependencies center on platinum-group metal refining from South African and Russian mining operations, nitinol shape-memory alloy from domestic Japanese foundries, and hydrophilic polymer feedstocks from specialty chemical producers. Single-source vulnerability in platinum-tungsten alloy supply creates exposure to geopolitical disruption and commodity price volatility. Distribution runs through GPO-negotiated contracts directly to hospital procurement committees, bypassing traditional distributor intermediaries for high-volume stroke centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neuroendovascular coil market fragmentation creates entry niches as hospital procurement committees disintermediate legacy bundled contracts and unbundle coil purchasing from catheter supply agreements.
For Market Incumbents: Insulate market position through backward integration into nitinol wire drawing and hydrophilic polymer coating capabilities to capture margin compression from unbundled procurement. Deepen PMDA and FDA regulatory infrastructure investments to extend compliance cost barriers against emerging competitors. Prioritize microcatheter technology R&D partnerships that preserve system-level contracting leverage with stroke center networks. For New Entrants and Emerging Players: Pursue white-space opportunities in aspiration-compatible coil technologies for wide-neck aneurysm morphologies underserved by incumbent platforms. Target ambulatory surgical center channels in United States markets where reimbursement carve-outs for same-day discharge create procurement flexibility outside hospital value-analysis committee control. Position through AI-enabled procedural planning software integration as a differentiated entry angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors microcatheter delivery specialists with proprietary hydrophilic coating intellectual property over diversified conglomerates facing portfolio rationalization pressure. Five-to-ten year viability hinges on computational fluid dynamics integration capabilities and real-world evidence generation infrastructure for long-term occlusion durability claims. Monitor FDA 510(k) clearance velocity for modified coil designs as an inflection indicator for competitive R&D productivity.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Regulatory Infrastructure Investment | Yokohama-based testing facilities accelerate Japan market access for compliant manufacturers. |
| AI-Enabled Procedural Planning Development | Computational fluid dynamics integration virtualizes aneurysm modeling workflows for complex cases. |
| Ambulatory Surgical Center Channel Entry | United States reimbursement carve-outs enable same-day discharge procedure capture outside hospital systems. |
| Microcatheter Technology Acquisition | Distal access catheter capabilities preserve bundled contracting leverage with stroke center procurement committees. |
| Real-World Evidence Infrastructure Buildout | Long-term aneurysm occlusion tracking satisfies evolving EMA MDR and FDA post-market surveillance requirements. |
Research Approach
Cross-validation between neurointerventionalist interviews and hospital procurement database analysis anchors the qualitative findings in documented purchasing behavior. Primary fieldwork engaged stroke center medical directors, GPO contracts managers, biomedical engineers, and neurovascular device specialists across tertiary hospital networks. Secondary validation drew from FDA 510(k) filings, EMA MDR submission databases, PMDA approval records, and hospital value-analysis committee documentation. Bottom-up procedural volume estimates triangulate with top-down manufacturer revenue segmentation across the analysis window.
Calibration against historical procedural growth rates and reimbursement pathway changes shapes the analytical framework. Segmentation dimensions span product architecture, delivery technology, care setting economics, and regional regulatory cluster. CAGRs derive from trend extrapolation adjusted for technology substitution effects and training pipeline constraints. Forecast inputs incorporate neurointerventionalist fellowship capacity expansion, PMDA reimbursement pathway evolution, and flow diversion catheter competitive displacement.
Macroeconomic conditions sit as an overlay; deviation in platinum-group metal commodity prices, yen-euro exchange rate volatility, or United States Medicare reimbursement rates would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline stability and procedural volume migration to outpatient settings. Quarterly review of FDA 510(k) clearance cadence, EMA MDR transition compliance announcements, and hospital GPO contract award disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Transcatheter Aortic Valve Replacement Market
Cardiovascular Devices
Pressure Infusion Bags Market
Cardiovascular Devices
Global Vascular Plugs Market
Cardiovascular Devices
Global Coil Wound Devices Market
Cardiovascular Devices
Stent Grafts Market
Cardiovascular Devices
Non-Invasive Pulse Wave Tonometer Market
Cardiovascular Devices
Arrhythmogenic Right Ventricular Dysplasia Treatment Market
Cardiovascular Devices
Italy Cardiovascular Devices Market
Cardiovascular Devices
North America Cardiac Assist Devices Market
Cardiovascular Devices
Endovascular Stent Market
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Ventricular Fibrillation Treatment Market
Cardiovascular Devices
Percutaneous Coronary Intervention Guidance Devices Market
Cardiovascular Devices
Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
Cardiovascular Diagnostic and Monitoring Devices Market
Cardiovascular Devices
Implantable Drug Infusion Pumps Market