
 Normal Balloon Catheter Market | 2026-2036
Normal Balloon Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Normal Balloon Catheter Market Analytics
European catheter manufacturers is rebalancing supply chains toward dual-source polymer extrusion to reduce dependency on single-origin silicone and nylon suppliers. Boston Scientific leverages in-house balloon molding capabilities across Massachusetts and Ireland facilities to sustain margin control on rapid-exchange platforms. Medtronic anchors its coronary portfolio through integrated catheter-sheath systems, while Abbott differentiates via proprietary compliance technology that competes on lesion-crossing performance in complex PCI cases.
A normal balloon catheter is a minimally invasive device comprising a polymer balloon membrane bonded to a flexible catheter shaft, typically constructed from nylon, polyethylene terephthalate, or polyurethane, designed to dilate stenotic vessels or deploy stents at controlled inflation pressures. The device serves interventional physicians by restoring luminal diameter in obstructed coronary, peripheral, or urological anatomies without open surgery. Rapid-exchange balloon catheters dominate procedure volume in cardiology due to shortened guidewire exchange times and reduced operator radiation exposure, while over-the-wire configurations retain share in complex chronic total occlusion interventions where rail support and device deliverability determine outcomes. Specialty balloon catheters, including cutting and scoring platforms, command premium positioning in calcified lesion subsets where conventional balloons face compliance limitations.
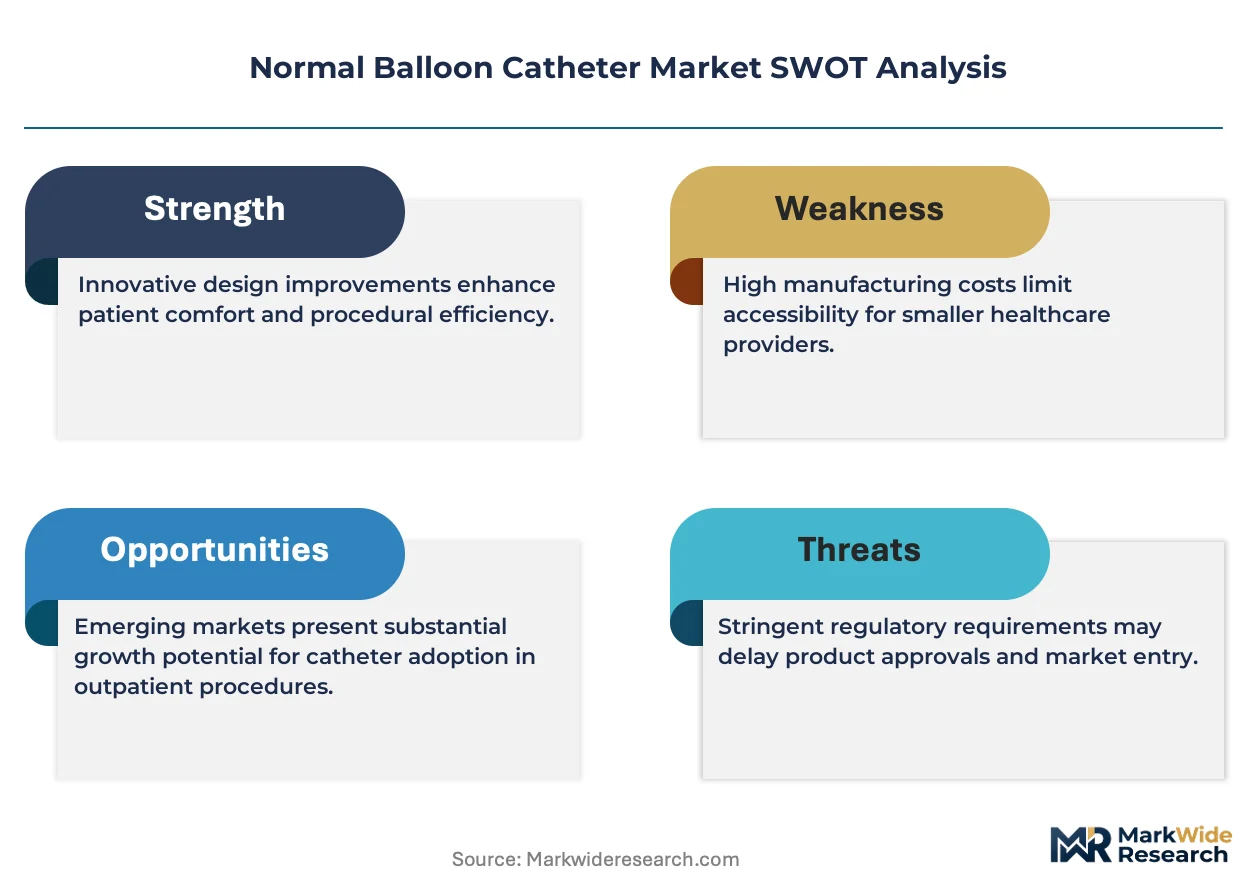
FDA 510(k) clearance requirements and EU MDR technical documentation mandates govern balloon rated burst pressure, fatigue testing, and biocompatibility validation, effectively raising capital barriers for new entrants and consolidating procurement around established quality systems. ISO 13485 certification and Japan PMDA foreign manufacturer registration further segment market access, with notified body audits in Europe extending timelines for design-dossier approvals. Stakeholders must monitor evolving FDA guidance on physiologic lesion assessment and reimbursement coding shifts that will determine whether balloon angioplasty retains procedural priority against intravascular lithotripsy and atherectomy alternatives.
Market Dynamics
Interventional cardiology departments are consolidating balloon catheter procurement around integrated catheter-sheath systems, compressing standalone balloon margins while elevating performance benchmarks for lesion-crossing deliverability.
Growth Catalysts
- EU MDR conformity pathways:Tightened quality benchmarks for balloon compliance and burst pressure testing are filtering out subscale manufacturers, concentrating procurement around established quality systems in Germany and France.
- Rapid-exchange platform adoption:Cardiology suites in the United States and Japan are standardizing on rapid-exchange configurations to reduce operator radiation exposure and shorten guidewire exchange times.
- Calcified lesion prevalence:Aging demographics across developed markets are expanding the addressable pool of complex PCI cases requiring specialty balloon platforms with cutting or scoring capabilities.
Market Restraints
- Polymer feedstock concentration:Single-origin dependency on specialized silicone and nylon extrusion suppliers in East Asia creates vulnerability to input cost volatility and logistics disruptions.
- ISO 13485 certification timelines:Extended notified body audit durations in Europe are stretching design-dossier approval cycles, delaying market entry for new product iterations.
- Intravascular lithotripsy substitution:Emerging calcium modification technologies are capturing procedural share in heavily calcified vessels where conventional balloons face compliance limitations.
Strategic Opportunities
- Peripheral artery disease expansion:Underpenetrated femoropopliteal intervention volumes in India and Brazil present white space for balloon catheter platforms adapted to cost-sensitive procurement environments.
- Dual-source polymer strategies:European manufacturers are rebalancing extrusion supply chains toward qualified secondary sources, creating partnership opportunities for regional polymer compounders.
- Japan PMDA foreign manufacturer registration:Streamlined registration pathways for ISO 13485-certified facilities are opening access to the world's second-largest coronary intervention market.
Industry Challenges
- Biocompatibility validation complexity:Evolving FDA guidance on physiologic lesion assessment is forcing recalibration of fatigue testing protocols and extending product development cycles.
- Polymer bonding expertise scarcity:Specialized knowledge in nylon-to-shaft thermal bonding and PET blow-molding is concentrating among veteran technicians in Massachusetts and Ireland facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Normal Balloon Catheter Market |
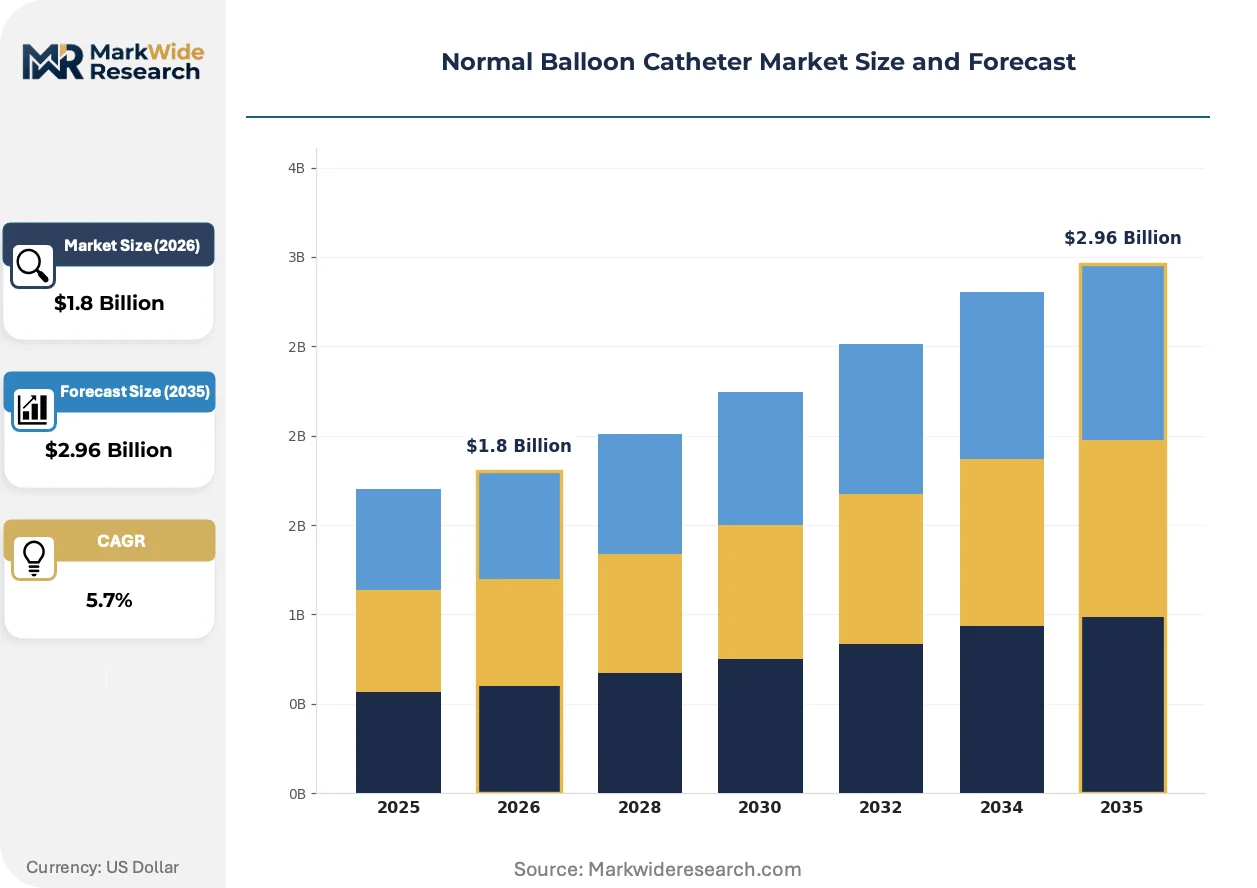
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Over-the-Wire, Rapid Exchange, Dual-Lumen, Specialty Delivery Mode: Balloon Expandable, Non-Balloon Expandable, Hydrophilic Coated, Coaxial End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Diagnostic Labs Application: Angioplasty, Urological Procedures, Gastroenterology, Cardiology |
| Companies Covered | Boston Scientific, Medtronic, Abbott, Terumo, B. Braun, BD, Cordis, Cook Medical, Teleflex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Normal Balloon Catheter Market Evolving Landscape
Balloon catheter engineering is converging on compliance precision and deliverability optimization, with material science advances and regulatory stringency jointly elevating performance thresholds for market participation.
Polyurethane-nylon hybrid balloon membranes are unifying the previously separate performance profiles of high-compliance and high-pressure platforms. Interventional cardiologists in complex PCI centers are adopting these dual-layer configurations for their ability to cross tortuous anatomy while maintaining rated burst pressure integrity. This unification is compressing the addressable market for single-material balloons and forcing portfolio rationalization among manufacturers lacking hybrid extrusion capabilities.
FDA premarket notification pathways are intensifying documentation requirements for fatigue testing and rated burst pressure validation. The agency's evolving guidance on physiologic lesion assessment is extending 510(k) review timelines and elevating capital requirements for new entrants. Coronary balloon catheter submissions are experiencing the most pronounced friction, with sponsors investing in expanded bench testing and clinical validation to support indications in calcified lesion subsets.
Hospital system procurement committees are consolidating vendor relationships around integrated catheter-sheath offerings that bundle balloon platforms with vascular access devices. Cardiology departments in integrated delivery networks are displacing standalone balloon purchasing in favor of multi-year supply agreements covering entire procedure kits. This concentration is most visible in the United States, where health system consolidation has reduced the number of independent purchasing decision points by half over the past decade.
Normal Balloon Catheter Market Segmentation
Balloon catheter segmentation reflects divergent technical requirements across coronary, peripheral, and specialty interventions. Manufacturers configure platform architectures to match procedural complexity, vascular access constraints, and reimbursement pathways that vary by care setting.
Product Type:
Customization intensifies from standardized rapid-exchange platforms toward engineered specialty configurations for lesion-specific demands.
- Over-the-Wire:Full-length guidewire lumen runs the entire catheter shaft, delivering superior rail support and device exchange capability in chronic total occlusion interventions. Demand concentrates in Japanese complex PCI centers where retrograde approaches require robust wire manipulation. Operators accept longer procedure times for the deliverability advantages in calcified tortuous anatomy.
- Rapid Exchange:Short guidewire lumen exits 20-30cm from the distal tip, enabling single-operator handling and reduced radiation exposure. United States cardiology suites have standardized on this configuration for routine coronary interventions, compressing procedure throughput times and supporting same-day discharge protocols.
- Dual-Lumen:Parallel lumens permit simultaneous contrast injection and balloon inflation. Compact design suits diagnostic-therapeutic hybrid procedures in European ambulatory settings.
- Specialty:Cutting, scoring, and lithotripsy-integrated balloons address calcified lesion subsets. Premium positioning reflects material complexity and indication-specific regulatory validation.
Most installed capacity flows through Rapid Exchange. Expansion is steepest in Specialty as calcified lesion prevalence rises across aging populations.
Delivery Mode:
Cost tier stratification separates commodity balloon platforms from coated and coaxial configurations commanding procurement premiums.
- Balloon Expandable:Conventional inflation mechanism using radiopaque markers and rated burst pressure specifications. Standard configuration for coronary stent deployment across hospital systems in Germany and France.
- Non-Balloon Expandable:Self-expanding stent delivery without balloon dependency. Niche positioning in carotid and neurovascular applications where vessel tortuosity exceeds balloon deliverability limits.
- Hydrophilic Coated:Polyvinylpyrrolidone surface treatment reduces friction coefficient for lesion crossing in tortuous peripheral anatomy. Japanese manufacturers lead coating chemistry expertise for femoropopliteal interventions.
- Coaxial:Nested shaft construction optimizes pushability and torque response. Complex manufacturing elevates unit economics for chronic total occlusion specialty cases.
Procurement volume clusters in Balloon Expandable. Hydrophilic Coated platforms are climbing the fastest as peripheral artery disease intervention expands.
End User:
Customer type determines packaging, sterilization, and technical service requirements that segment manufacturing economics.
- Hospitals:Integrated catheter-sheath procurement and consignment inventory models dominate interventional cardiology department purchasing. United States health system consolidation has compressed vendor relationships toward multi-year supply agreements.
- Ambulatory Surgical Centers:Cost-sensitive procurement with preference for rapid-exchange platforms enabling efficient patient throughput. Reimbursement differentials favor same-day discharge protocols.
- Specialty Clinics:Urological and gastroenterology-focused facilities require indication-specific balloon configurations with dedicated training support.
- Diagnostic Labs:Lower procedural volumes prioritize single-use disposables and minimal inventory carrying costs.
Revenue concentration sits with Hospitals. Ambulatory Surgical Centers are gaining share fastest as coronary intervention migrates to outpatient settings.
Application:
Maturity gradients separate established cardiology volumes from emerging gastroenterology and urology platform extensions.
- Angioplasty:Percutaneous transluminal coronary and peripheral interventions represent the core revenue base. FDA 510(k) pathways and EU MDR conformity requirements govern balloon compliance and burst pressure validation for this indication.
- Urological Procedures:Balloon dilation addresses ureteral strictures and benign prostatic hyperplasia. Japanese urology clinics drive adoption of hydrophilic-coated platforms for reduced mucosal trauma.
- Gastroenterology:Esophageal and colonic stricture dilation using through-the-scope balloon configurations. Smaller addressable market with specialized endoscopy integration requirements.
- Cardiology:Encompasses coronary, structural heart, and electrophysiology applications beyond conventional angioplasty. Integrated delivery networks bundle these procedures under single vendor contracts.
Procedure volume concentrates in Angioplasty. Urological Procedures follow the steepest expansion trajectory as aging demographics expand stricture disease prevalence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States sustains higher procedural volumes per capita than Germany, yet Japanese complex PCI centers generate disproportionate demand for over-the-wire specialty configurations. Regulatory divergence across these three markets shapes distinct competitive entry pathways.
United States
Hospital system consolidation has compressed independent purchasing decision points by half over the past decade, driving procurement toward multi-year supply agreements. FDA 510(k) clearance requirements for fatigue testing and rated burst pressure validation extend review timelines for coronary balloon submissions. Massachusetts and Minnesota host concentrated catheter molding capabilities serving integrated delivery networks.
Germany
EU MDR conformity pathways have tightened quality benchmarks for balloon compliance, filtering subscale manufacturers from procurement channels. Notified body audits now stretch design-dossier approval cycles, delaying market entry for new product iterations. The Rhine-Main and Munich clusters anchor European extrusion and molding operations for rapid-exchange platforms.
Japan
PMDA foreign manufacturer registration requirements segment market access, with ISO 13485-certified facilities facing streamlined pathways into the world's second-largest coronary intervention market. Aging demographics expand the addressable pool of calcified lesion cases requiring specialty balloon platforms. Tokyo and Osaka metropolitan areas concentrate complex PCI centers driving retrograde approach adoption.
India
Underpenetrated femoropopliteal intervention volumes present white space for balloon catheter platforms adapted to cost-sensitive procurement environments. CDSCO medical device regulations govern import licensing and quality system requirements for foreign manufacturers. Maharashtra and Gujarat industrial corridors host emerging domestic catheter assembly operations targeting regional price points.
Normal Balloon Catheter Market Competitive Landscape
United States producers anchor one tier; European and Japanese specialists hold differentiated positions in compliance-intensive segments. The vendor base concentrates around integrated catheter-sheath systems and proprietary balloon molding capabilities, with rapid-exchange platforms commanding standardized procurement volumes. Three archetypes dominate: diversified cardiovascular conglomerates with in-house extrusion, mid-scale specialists in niche lesion applications, and regional cost-optimized fabricators. Strategic moves center on dual-source polymer qualification and health system consolidation of vendor relationships.
Among diversified cardiovascular conglomerates, Boston Scientific, Medtronic, and Abbott exemplify distinct competitive positioning. Boston Scientific represents integrated manufacturing depth with balloon molding capabilities spanning Massachusetts and Ireland facilities. Medtronic anchors portfolio breadth through catheter-sheath system bundling. Abbott occupies a position defined by proprietary compliance technology competing on lesion-crossing performance in complex PCI cases.
| Leading Market Players |
|---|
| Boston Scientific |
| Medtronic |
| Abbott |
| Terumo |
| B. Braun |
| BD |
| Cordis |
| Cook Medical |
| Teleflex |
| Others |
Value Network & Pricing Analysis
Hospital system consolidation across the United States and Germany is compressing independent purchasing decision points and forcing manufacturers to absorb freight and inventory carrying costs within multi-year supply agreements. This procurement concentration elevates pricing power for integrated catheter-sheath system vendors while squeezing margins on standalone balloon platforms.
Pricing Analysis
Distributor margins of 15-25 percent separate manufacturer net pricing from hospital system landed costs, with direct-to-IDN contracts commanding steeper discounts in exchange for volume commitments. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by rated burst pressure certification and hydrophilic coating chemistry. Pricing pressure stems from health system GPO consolidation and the displacement of standalone balloons by bundled procedure kits. Ambulatory surgical centers exhibit highest price sensitivity due to fixed reimbursement ceilings, while Japanese complex PCI centers tolerate premium positioning for over-the-wire specialty configurations.
Supply Chain Analysis
Freight costs from East Asian polymer extrusion hubs to Massachusetts and Ireland molding facilities have elevated landed input costs for nylon and polyurethane feedstocks. Supply concentrates in China for specialized silicone compounds, the United States for high-grade PET resins, and Germany for precision extrusion equipment. Raw material dependencies include medical-grade nylon 12, thermoplastic polyurethane, and radiopaque filler compounds. Single-source vulnerability in East Asian silicone supply creates exposure to logistics disruptions and tariff volatility. Distribution runs through regional medical device distributors in the United States, direct hospital contracts in Germany, and specialized interventional cardiology dealers in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Normal Balloon Catheter Market functions as a stable compounder anchored by aging demographics and the procedural shift toward minimally invasive revascularization. Elective angioplasty scheduling retains priority within hospital budgets despite emerging calcium modification alternatives.
For Market Incumbents: Anticipate intravascular lithotripsy substitution in calcified lesion subsets by accelerating proprietary compliance technology roadmaps and securing dual-source polymer qualification before EU MDR audit backlogs extend further. Anchor defensive positioning through backward integration into balloon molding capabilities and health system GPO contract renewals that bundle rapid-exchange platforms with vascular access devices. For New Entrants and Emerging Players: Begin with peripheral artery disease intervention in India and Brazil, where femoropopliteal volumes remain underpenetrated and procurement committees prioritize cost-adapted platforms over premium branded configurations. Target ambulatory surgical center channels with rapid-exchange offerings engineered for same-day discharge protocols and minimal inventory carrying requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale specialists possessing ISO 13485-certified facilities and established PMDA foreign manufacturer registration for streamlined Japan market access. The 5-10 year viability window favors acquisition targets with hybrid extrusion capabilities and proprietary nylon-to-shaft thermal bonding expertise. Monitor FDA guidance evolution on physiologic lesion assessment as the signal for whether balloon angioplasty retains procedural priority against atherectomy alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Source Polymer Qualification | Reduces dependency on single-origin silicone suppliers and insulates margins from East Asian logistics disruptions. |
| EU MDR Design-Dossier Investment | Accelerates market entry timelines in Germany and France by preempting notified body audit backlogs. |
| Hospital System Partnership | Secures multi-year supply agreements with integrated delivery networks displacing standalone balloon purchasing. |
| Japan PMDA Registration | Opens access to the world's second-largest coronary intervention market for ISO 13485-certified facilities. |
| Specialty Balloon Platform Development | Captures premium positioning in calcified lesion subsets where conventional balloons face compliance limitations. |
Research Methodology
Direct dialogue with interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers grounded the qualitative assessment of procurement preferences and lesion-crossing performance requirements. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body audit records, CMS Medicare procedure volume data, and hospital procurement databases. Bottom-up modeling of catheter unit demand by configuration and geography triangulated against top-down market sizing from manufacturer revenue disclosures and trade flow analysis.
Segmentation outputs across product type, delivery mode, end user, and application dimensions fed into the analytical framework over the projection horizon. CAGRs were derived from regression analysis against demographic aging curves, procedural volume trends, and reimbursement pathway stability. Industry-specific forecast inputs included calcified lesion prevalence trajectories and health system consolidation rates.
Several conditions sit outside the modeled scope, including sudden FDA guidance reversals on physiologic lesion assessment, major polymer feedstock supply disruptions, and reimbursement coding shifts favoring intravascular lithotripsy. Forecasts reflect assumptions about regulatory pathway stability and elective procedure scheduling patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Venous Reservoirs Market
Cardiovascular Devices
Cardiovascular Stents Market
Cardiovascular Devices
Neuroendovascular Coil Market
Cardiovascular Devices
Ischemic Stroke Aspiration Systems Market
Cardiovascular Devices
Cardiac Medical Device Market
Cardiovascular Devices
Intra-Aortic Balloon Pump (IABP) Market
Cardiovascular Devices
Iliac Artery Stents Market
Cardiovascular Devices
Shock Wave Therapy Devices Market
Cardiovascular Devices
Vascular Snare Market
Cardiovascular Devices
Global Vascular Injury Treatment Market
Cardiovascular Devices
Microsclerotherapy Treatment Market
Cardiovascular Devices
Peripheral Vascular Interventions Market
Cardiovascular Devices
United States Cardiovascular Devices Market
Cardiovascular Devices
Pressure Infusion Bags Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Cardiac Surgery Devices Market