
 Vascular Screening Market | 2026-2036
Vascular Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Vascular Screening Market Analytics
Hospital procurement channels for vascular screening equipment is reconfiguring around value-based care contracts and bundled service agreements. Fukuda Denshi anchors its position through deep integration with Japanese hospital networks and specialized cardiovascular monitoring ecosystems. Shenzhen Mindray Bio-Medical Electronics competes aggressively on manufacturing scale, offering portable Doppler systems at price points that penetrate mid-tier diagnostic centers across Southeast Asia and Latin America.
Vascular screening encompasses non-invasive and minimally invasive diagnostic modalities that evaluate blood flow, vessel wall integrity, and luminal patency using ultrasound frequencies typically ranging from 2 to 15 MHz, Doppler signal processing, and tomographic reconstruction. The primary commercial purpose centers on early detection of atherosclerotic disease, aneurysmal dilation, and stenotic lesions before symptomatic progression mandates surgical intervention. Ultrasound systems occupy the largest installed base due to lower capital requirements and absence of ionizing radiation, while CT angiography commands premium pricing in acute care settings where spatial resolution below one millimeter determines treatment pathways. Portable devices represent the fastest-expanding technology segment as point-of-care deployment shifts screening from centralized radiology departments to primary care offices and community health programs.
The FDA governs device clearance and clinical claim substantiation for vascular screening platforms marketed in the United States, while the EU Medical Device Regulation imposes stricter post-market surveillance and clinical evidence requirements for CE-marked systems sold across European member states. Japan's PMDA maintains distinct quality management system inspections that create additional compliance layers for manufacturers seeking access to its aging patient population. Stakeholders must monitor how reimbursement code consolidation and AI diagnostic add-on payment decisions reshape capital allocation between imaging modality upgrades and software analytics capabilities.
Market Dynamics
Hospital procurement for vascular screening equipment is consolidating around value-based care contracts that bundle imaging hardware with AI diagnostic subscriptions, compressing traditional capital sales cycles into multi-year service agreements.
Growth Catalysts
- Preventive care mandates:Germany's statutory health insurance system reimburses asymptomatic vascular assessments, creating predictable procedure volume for outpatient screening networks.
- Portable Doppler advancement:Battery-powered ultrasound systems enable point-of-care deployment in primary care offices, expanding screening access beyond centralized radiology departments.
- FDA 510(k) pathway modernization:Streamlined clearance for AI-assisted diagnostic software accelerates clinical workflow integration and reduces time-to-market for algorithm developers.
Market Restraints
- Semiconductor supply concentration:Specialized analog-to-digital converters for Doppler signal processing depend on fabrication facilities concentrated in Taiwan and South Korea.
- EU MDR clinical evidence requirements:Stricter post-market surveillance mandates for CE-marked systems extend compliance timelines and elevate documentation costs for manufacturers.
- CT angiography substitution pressure:Premium acute care settings favor computed tomography for sub-millimeter spatial resolution in emergency intervention decisions.
Strategic Opportunities
- Community health program expansion:Federally qualified health centers in the United States represent underpenetrated channels for mobile screening units targeting rural populations.
- AI-telemetry convergence:Integration of edge-computing algorithms with cloud-based longitudinal tracking enables predictive risk scoring beyond episodic screening.
- Japanese aging demographics:METI-supported preventive cardiovascular programs create reimbursement tailwinds for home-monitoring device ecosystems.
Industry Challenges
- Workflow integration complexity:AI diagnostic outputs require reconfiguration of electronic health record interfaces and radiologist report templates.
- Specialized sonographer scarcity:Vascular ultrasound interpretation demands certification in spectral Doppler analysis, creating recruitment bottlenecks for screening program expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vascular Screening Market |
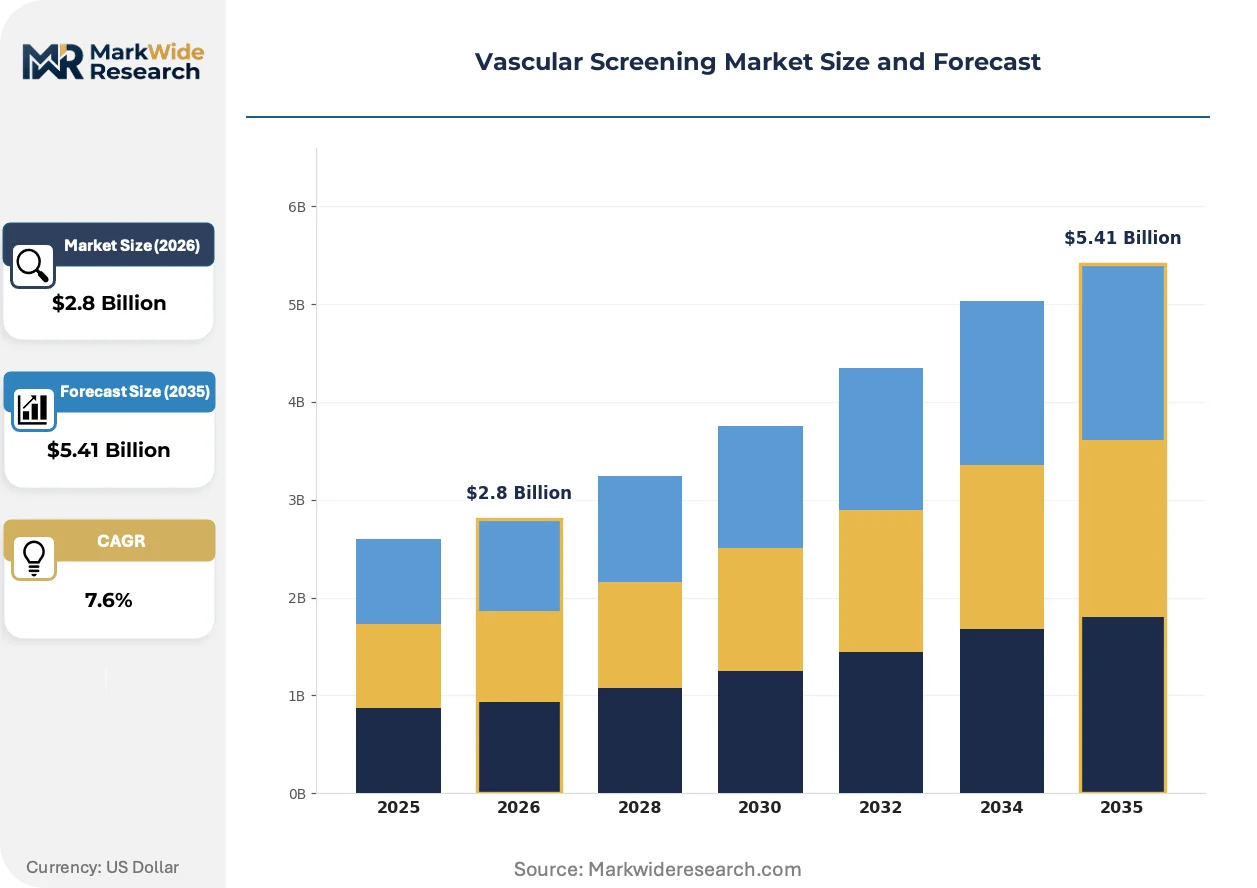
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound, Angiography, Doppler Imaging, CT Angiography Application: Peripheral Artery Disease, Aneurysm Detection, Stroke Prevention, Carotid Assessment End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Clinics Technology: 3D Imaging, Contrast Enhancement, Digital Subtraction, Portable Devices |
| Companies Covered | Fukuda Denshi, Unetixs Vascular, Collaborative Care Diagnostics, CorVascular Diagnostics, Koven Technology, D.E. Hokanson, enverdis GmbH, OMRON Healthcare, Shenzhen Mindray Bio-Medical Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vascular Screening Market Evolving Landscape
Artificial intelligence is compressing diagnostic interpretation timelines while hardware miniaturization relocates screening capability from hospital campuses to ambulatory settings.
Edge-deployed machine learning algorithms are virtualizing preliminary image analysis at the point of capture. Primary care networks in the United States are adopting these systems to reduce specialist referral backlogs. The technology is virtualizing the traditional radiologist workflow by flagging normal studies and escalating only abnormal findings.
Japan's PMDA has implemented distinct quality management system inspections for software-as-medical-device platforms. This regulatory architecture elevates documentation burdens for foreign manufacturers seeking market access. Cardiovascular AI developers are responding by establishing localized clinical validation studies and Japanese-language training datasets.
Hospital purchasing departments are consolidating vendor relationships through multi-modality equipment agreements that bundle vascular ultrasound with echocardiography and general radiology systems. Independent diagnostic centers face exclusion from these preferred supplier networks. The pattern is most visible in German hospital alliance procurement, where standardization across member facilities reduces per-unit pricing leverage.
Vascular Screening Market Segmentation
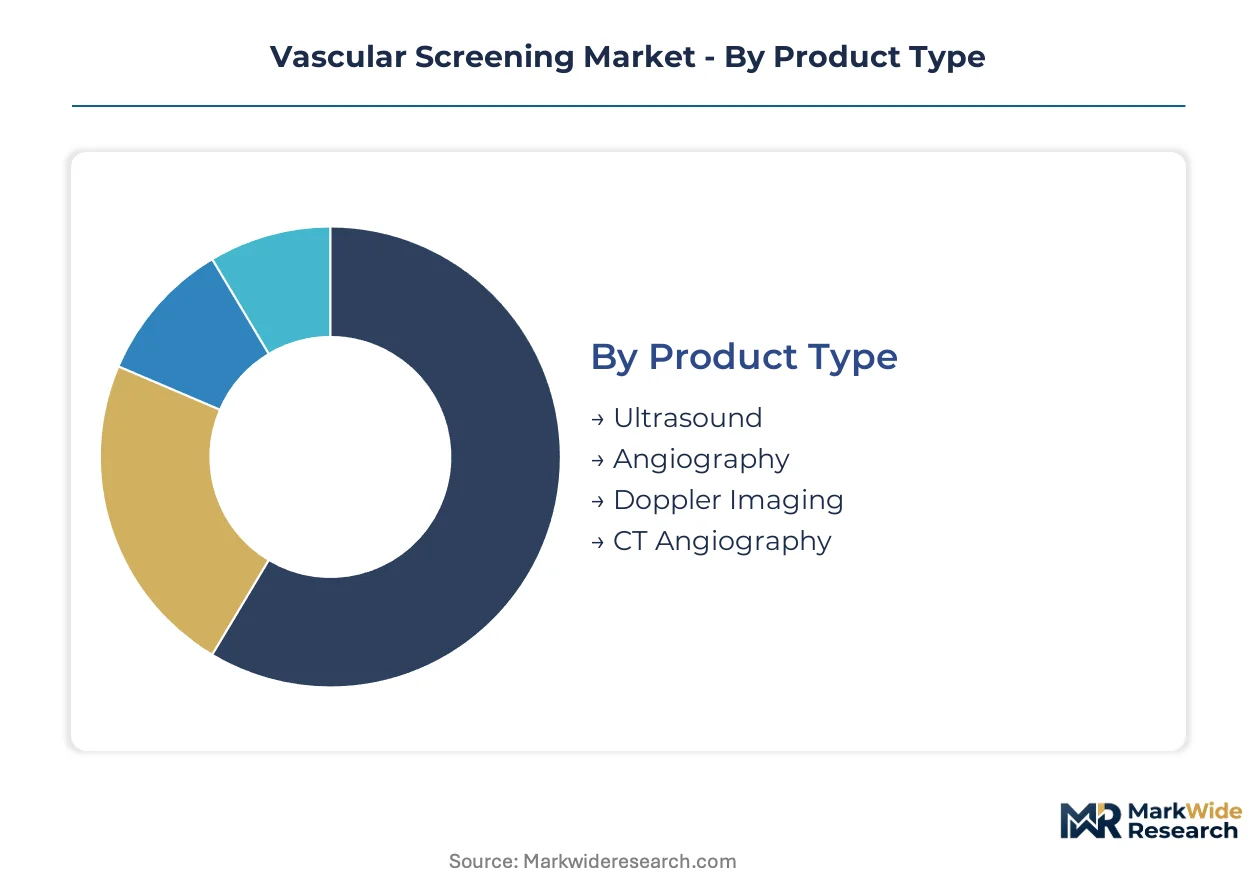
Vascular screening equipment segments exhibit divergent replacement cycles, with portable Doppler systems turning over every 3-4 years versus CT angiography platforms lasting 7-10 years. Procurement committees weigh capital intensity against reimbursement velocity when allocating budgets across these categories.
Product Type:
Ultrasound systems refresh fastest due to probe wear and software obsolescence, while CT angiography platforms command extended depreciation schedules reflecting their seven-figure price points.
- Ultrasound:Non-invasive imaging using 2-15 MHz transducers to visualize vessel walls and luminal patency without ionizing radiation. German outpatient networks drive replacement demand through statutory reimbursement for preventive assessments, compressing equipment cycles to 3-4 years.
- Angiography:X-ray based visualization requiring catheter insertion and iodinated contrast injection. Academic medical centers in the United States anchor demand for biplane systems capable of rotational acquisition during interventional procedures.
- Doppler Imaging:Spectral and color flow analysis measuring blood velocity and direction. Portable battery-powered variants are penetrating primary care offices across Southeast Asia.
- CT Angiography:Computed tomography with sub-millimeter spatial resolution for emergency intervention decisions. Japanese hospital systems prioritize dual-source configurations for cardiac gating capabilities.
Ultrasound anchors the volume base while portable Doppler variants gain share at the steepest rate.
Application:
Stroke prevention commands premium pricing due to neurological urgency, whereas peripheral artery disease screening spreads across high-volume community programs with compressed margins.
- Peripheral Artery Disease:Lower extremity assessment using ankle-brachial index and segmental pressure measurement. Federally qualified health centers in the United States represent underpenetrated deployment channels for mobile screening units.
- Aneurysm Detection:Abdominal aortic diameter surveillance using ultrasound or CT surveillance protocols. German statutory insurance mandates drive predictable screening volume for men over 65.
- Stroke Prevention:Carotid intima-media thickness and plaque characterization to stratify cerebrovascular risk. Academic stroke centers prioritize high-field MRI for vulnerable plaque imaging.
- Carotid Assessment:B-mode ultrasound with spectral Doppler velocity ratios determining stenosis severity. Japanese preventive cardiovascular programs under METI sponsorship expand home-monitoring ecosystems.
Peripheral artery disease screening generates the highest procedure count while stroke prevention applications command the steepest price escalation.
End User:
Hospital procurement consolidates through multi-year service agreements, whereas diagnostic centers face exclusion from preferred vendor networks as purchasing departments bundle modalities.
- Hospitals:Integrated delivery networks negotiating value-based care contracts that bundle imaging hardware with AI diagnostic subscriptions. North American health systems are expanding outpatient vascular programs to reduce emergency intervention costs.
- Diagnostic Centers:Independent facilities specializing in elective screening outside acute care settings. German hospital alliance procurement standardization reduces per-unit pricing leverage for standalone operators.
- Research Institutions:Academic medical centers validating novel biomarkers and imaging protocols. FDA 510(k) pathway modernization accelerates clinical workflow integration for algorithm developers.
- Outpatient Clinics:Primary care and community health settings deploying point-of-care devices. Battery-powered ultrasound enables screening relocation from centralized radiology departments.
Hospitals anchor capital expenditure volume while outpatient clinics are expanding most quickly through point-of-care deployment.
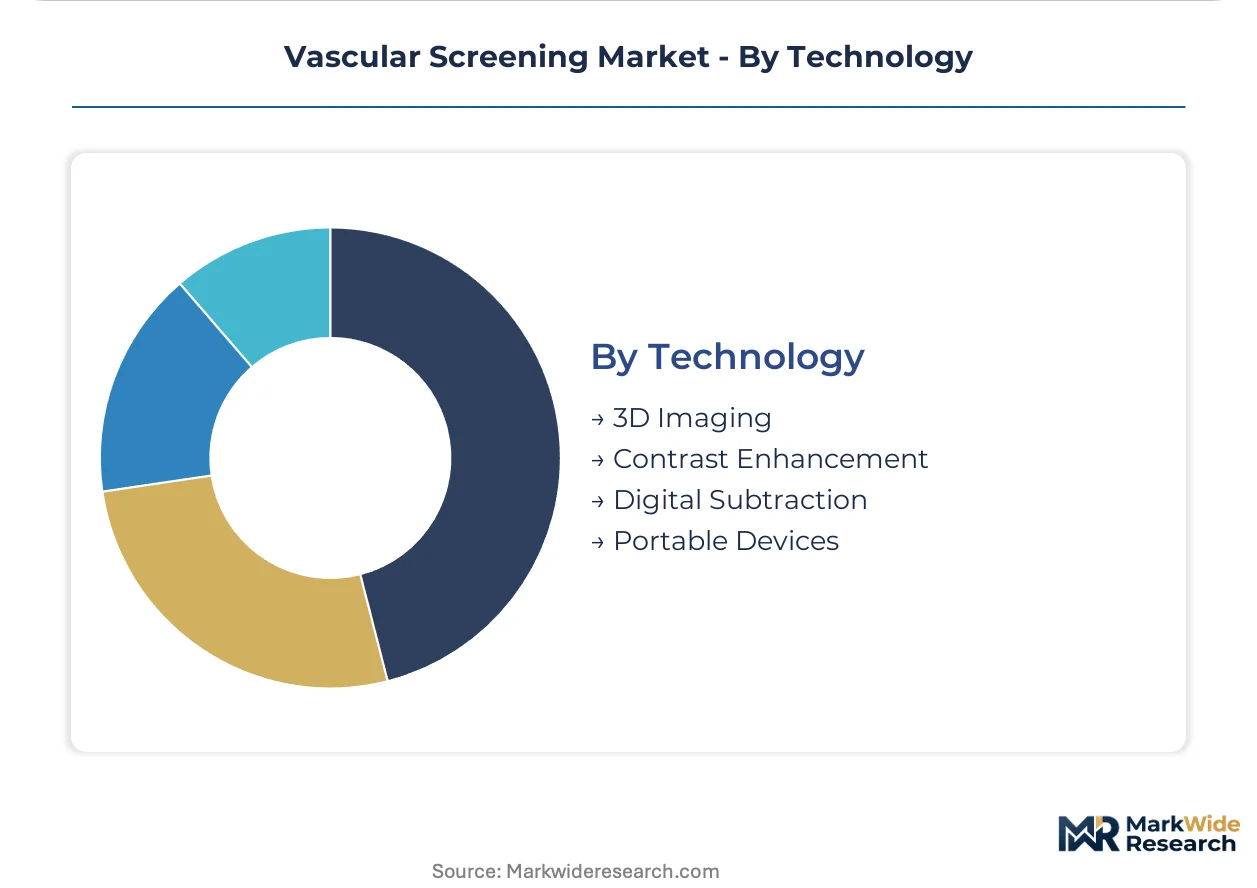
Technology:
Portable devices command the steepest growth trajectory as miniaturization relocates capability, while contrast enhancement faces substitution pressure from non-invasive alternatives.
- 3D Imaging:Volume-rendered reconstruction from rotational angiography or tomographic ultrasound. Japanese PMDA quality management inspections elevate documentation burdens for foreign manufacturers.
- Contrast Enhancement:Iodinated or gadolinium-based agents improving luminal delineation. Nephrogenic systemic fibrosis and contrast-induced nephropathy risks drive demand for non-invasive alternatives.
- Digital Subtraction:Bone and soft tissue suppression algorithms isolating vascular structures. Legacy angiography suites retain this capability for interventional guidance.
- Portable Devices:Battery-powered ultrasound with edge-computing algorithms for point-of-care interpretation. Shenzhen manufacturing scale penetrates mid-tier diagnostic centers across Latin America.
Portable devices are climbing the fastest while 3D imaging retains premium positioning in academic settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German statutory reimbursement for preventive vascular assessments commands pricing premiums that Brazilian mid-tier diagnostic centers cannot replicate, creating a transatlantic margin spread exceeding 40% on comparable ultrasound systems.
United States
Federally qualified health centers and hospital outpatient networks drive demand for mobile screening units targeting rural populations. FDA 510(k) pathway modernization accelerates AI-assisted diagnostic software clearance timelines. The Southeast corridor from Florida to Georgia anchors deployment of point-of-care Doppler systems in community health programs.
Germany
Statutory health insurance mandates for asymptomatic vascular assessments in men over 65 generate predictable procedure volume. EU MDR post-market surveillance requirements elevate documentation costs for CE-marked system manufacturers. The Ruhr industrial belt concentrates outpatient screening network expansion through hospital alliance procurement standardization.
Japan
METI-sponsored preventive cardiovascular programs expand reimbursement for home-monitoring device ecosystems. PMDA quality management system inspections create additional compliance layers for foreign software-as-medical-device platforms. The Kanto region around Tokyo anchors clinical validation studies for localized AI training datasets.
China
Domestic manufacturing scale at Shenzhen penetrates mid-tier diagnostic centers across Southeast Asia re-export markets. NMPA device registration pathways govern market access for imported vascular screening platforms. The Yangtze River Delta clusters portable ultrasound production for Latin American distribution channels.
Brazil
ANVISA regulatory pathways for imported medical devices shape competitive entry timelines for Asian manufacturers. Price-sensitive diagnostic centers in São Paulo and Minas Gerais prioritize portable Doppler systems over premium CT angiography platforms. The Southeast region concentrates independent imaging facility networks outside consolidated hospital procurement systems.
Vascular Screening Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in probe fabrication and signal processing modules. The vendor base organizes around three archetypes: full-modality conglomerates bundling vascular ultrasound with echocardiography systems, mid-scale specialists concentrating on portable Doppler advancement, and software developers licensing AI diagnostic algorithms to hardware OEMs. Consolidation pressures favor multi-year service agreements over capital sales, while geographic expansion through localized clinical validation studies represents the dominant competitive move for algorithm developers facing Japan's PMDA requirements.
Among Japanese equipment fabricators, Fukuda Denshi anchors the cardiovascular monitoring ecosystem tier through deep hospital network integration. Shenzhen Mindray Bio-Medical Electronics exemplifies manufacturing-scale competition penetrating price-sensitive mid-tier diagnostic centers across Southeast Asia and Latin America. German specialist enverdis GmbH occupies a position within the software-integrated diagnostic workflow segment, representing European regulatory compliance archetypes navigating EU MDR evidence requirements.
| Leading Market Players |
|---|
| Fukuda Denshi |
| Unetixs Vascular |
| Collaborative Care Diagnostics |
| CorVascular Diagnostics |
| Koven Technology |
| D.E. Hokanson |
| enverdis GmbH |
| OMRON Healthcare |
| Shenzhen Mindray Bio-Medical Electronics |
| Others |
Value Network & Pricing Analysis
Overcapacity in Taiwan's semiconductor fabrication facilities is compressing analog-to-digital converter margins and forcing vascular ultrasound OEMs toward multi-year service contracting rather than capital sales. This utilization dynamic simultaneously elevates supplier pricing leverage on specialized Doppler components while pressuring finished-system pricing through bundling expectations from hospital procurement committees.
Pricing Analysis
The customization-premium spread between configured-to-order CT angiography platforms and standard portable Doppler units exceeds 300% on a per-procedure basis. Three-tier pricing structure across premium, standard, and economy levels stratifies by software analytics bundling and probe durability ratings. Cost compression in the portable segment is intensifying because Shenzhen manufacturing scale floods Latin American and Southeast Asian channels. Federally qualified health centers exhibit highest price sensitivity, while Japanese academic medical centers absorb premium positioning for PMDA-validated AI diagnostic modules.
Supply Chain Analysis
Contract-manufacturing concentration in Taiwan and South Korea controls fabrication of specialized ADCs and FPGA signal processing chips essential for spectral Doppler analysis. Raw material dependencies span germanium substrates for transducer crystals, iodinated contrast media precursors sourced from Chinese chemical processors, and rare-earth magnets for portable system motors. Single-source vulnerability concentrates in Taiwan's 200mm analog foundry capacity. Distribution runs through hospital GPO contracts in North America, hospital alliance procurement in Germany, and regional distributor networks across emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vascular screening equipment demand follows capital expenditure cycles tied to hospital budget replenishment after pandemic-era deferrals, positioning the current window as cyclical recovery driven by North American health system infrastructure refresh programs.
For Market Incumbents: Harden installed-base retention by embedding AI diagnostic subscriptions into existing ultrasound fleets before portable competitors capture primary care office expansion. Deepen backward integration into probe fabrication to defend margin position against Taiwan foundry pricing volatility. Prioritize FDA 510(k) clearance velocity for algorithm updates to maintain workflow integration advantages over emerging software developers.
For New Entrants and Emerging Players: Rural United States federally qualified health centers represent the most penetrable geography for mobile screening unit deployment, with reimbursement tailwinds from preventive care mandates and minimal incumbent saturation. Brazilian mid-tier diagnostic centers offer secondary white-space opportunity given ANVISA regulatory pathways favoring price-competitive portable systems. Pursue direct-to-clinic sales models bypassing consolidated hospital procurement systems.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-as-medical-device sub-segments as cloud infrastructure displaces on-premise hardware requirements. Long-term viability favors platform integrators with hospital network lock-in over component specialists facing commoditization. Target acquisition archetypes include AI diagnostic developers with localized Japanese clinical validation studies. Watch FDA AI/ML-based SaMD guidance updates as inflection signal for algorithm valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-year service agreements with North American IDNs lock out portable competitors from outpatient expansion. |
| FDA 510(k) Submission | Streamlined clearance for AI-assisted Doppler interpretation accelerates clinical workflow integration timelines. |
| CE Marking Pathway | EU MDR compliance investment separates viable European suppliers from documentation-burdened exits. |
| Software Companion Development | Edge-computing algorithms for portable ultrasound virtualize radiologist workflow and expand primary care addressability. |
| Reimbursement Strategy | German statutory insurance code capture determines predictable procedure volume for outpatient network operators. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with vascular sonographers, hospital purchasing committee chairs, biomedical engineers, GPO contracts managers, and portable device distribution partners. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body documentation, CMS Medicare reimbursement schedules, and hospital procurement contract registries. Bottom-up equipment shipment modeling triangulated against top-down healthcare expenditure analysis across the analysis window.
Calibration against historical replacement cycles and reimbursement velocity informed the projection framework. Segmentation dimensions spanned product type, application, end user, and technology tier with geographic regulatory cluster overlays. CAGRs derived from equipment depreciation schedules, statutory screening mandate expansion rates, and AI diagnostic adoption curves. Forecast inputs included semiconductor foundry capacity utilization and PMDA software-as-medical-device inspection timelines.
Practitioners should monitor FDA AI/ML guidance revisions, EU MDR post-market surveillance enforcement intensity, and Taiwan foundry capacity allocation shifts for early signals of forecast deviation. Quarterly review of hospital capital expenditure commitment patterns and statutory insurance reimbursement code updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
US Ventricular Assist Devices Market
Cardiovascular Devices
Cardiovascular Catheter Market
Cardiovascular Devices
Non-Invasive Pulse Wave Tonometer Market
Cardiovascular Devices
Peripheral Intravenous Catheters Market
Cardiovascular Devices
Surgical and Interventional Cardiology Devices Market
Cardiovascular Devices
Vascular Prostheses Market
Cardiovascular Devices
Intravenous Catheters Market
Cardiovascular Devices
Tricuspid Valve Repair Market
Cardiovascular Devices
Non-Invasive Blood Pressure Monitors Market
Cardiovascular Devices
Cardiovascular Devices Market
Cardiovascular Devices
Cardiogenic Shock Treatment Market
Cardiovascular Devices
United Kingdom Cardiovascular Devices Market
Cardiovascular Devices
Australia Cardiovascular Devices Market
Cardiovascular Devices
Continuous Blood Pressure Monitoring Devices Market
Cardiovascular Devices
Pressure Infusion Cuffs Market
Cardiovascular Devices
US Ambulatory Cardiac Monitoring Devices Market