
 Germany Neonatal and Prenatal Devices Market | 2026-2036
Germany Neonatal and Prenatal Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Neonatal and Prenatal Devices Market Foresight
The EU Medical Device Regulation is consolidating the cost-of-entry calculus for manufacturers seeking CE marking approval in Germany. Dragerwerk AG & Co. KGaA leverages its Lübeck manufacturing base to sustain domestic production of incubators and ventilators. Siemens Healthineers AG anchors its prenatal diagnostics portfolio through advanced imaging platforms deployed across German university hospitals. Koninklijke Philips N.V. competes in monitoring devices through integrated informatics systems that streamline NICU workflow management.
Neonatal and prenatal devices encompass thermoregulation, respiratory assistance, phototherapy, and diagnostic instrumentation engineered for gestational ages from 22 weeks to full term, with incubators maintaining thermal neutral zones between 36.0°C and 36.5°C core body temperature. These systems serve the primary purpose of reducing neonatal mortality and morbidity in critical early-life interventions. Monitoring devices lead product type revenue generation due to continuous multiparameter surveillance requirements in level III NICUs. Prenatal screening applications within the application dimension show the fastest structural expansion as non-invasive prenatal testing protocols diffuse from tertiary centers into obstetric networks. Diagnostic laboratories as an end user segment concentrate margin pools through centralized genetic testing workflows that demand high-throughput automation platforms.
Germany's Federal Institute for Drugs and Medical Devices enforces MDR compliance timelines that compress market access windows for non-EU manufacturers. BSI Group and TÜV SÜD operate as notified bodies conducting conformity assessments under tightened scrutiny from EMA coordination mechanisms. Stakeholders must monitor evolving MDR guidance documents on clinical evidence requirements for legacy device renewals to preserve market positioning.
Market Dynamics
The EU Medical Device Regulation is compressing market access timelines while Bavarian and North Rhine-Westphalian NICU networks accelerate procurement of respiratory support systems, creating a bifurcated pressure landscape for device manufacturers.
Growth Catalysts
- MDR Compliance Infrastructure:Germany's Federal Institute for Drugs and Medical Devices enforcement of MDR timelines is consolidating domestic manufacturing advantages for established European producers.
- University Hospital Procurement:Berlin, Munich, and Hamburg hospital networks are expanding centralized purchasing of multiparameter monitoring systems for level III NICU capacity.
- Non-Invasive Prenatal Testing:Diffusion of NIPT protocols from tertiary obstetric centers into regional obstetric networks is expanding addressable demand for diagnostic instrumentation.
Market Restraints
- Notified Body Bottleneck:BSI Group and TÜV SÜD capacity constraints under EMA coordination scrutiny are extending CE marking timelines for legacy device renewals.
- Input Concentration:Specialized neonatal sensor components rely on concentrated Asian supply bases, exposing manufacturers to logistics volatility.
- Clinical Evidence Burden:MDR guidance documents on clinical evidence requirements are raising documentation costs for high-risk device categories.
Strategic Opportunities
- East German Network Expansion:Saxony and Thuringia obstetric networks remain underpenetrated relative to western university hospital density.
- Integrated Informatics Convergence:NICU workflow management platforms combining monitoring data with predictive analytics represent unconsolidated white space.
- Diagnostic Laboratory Automation:Centralized genetic testing workflows in German diagnostic laboratories demand high-throughput prenatal screening platforms.
Industry Challenges
- Specialized Biomedical Engineering Talent:Neonatal device calibration and maintenance requires scarce expertise in thermoregulation and respiratory mechanics.
- Legacy System Integration:New monitoring platforms must interface with existing hospital information systems across heterogeneous German state hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Neonatal and Prenatal Devices Market |
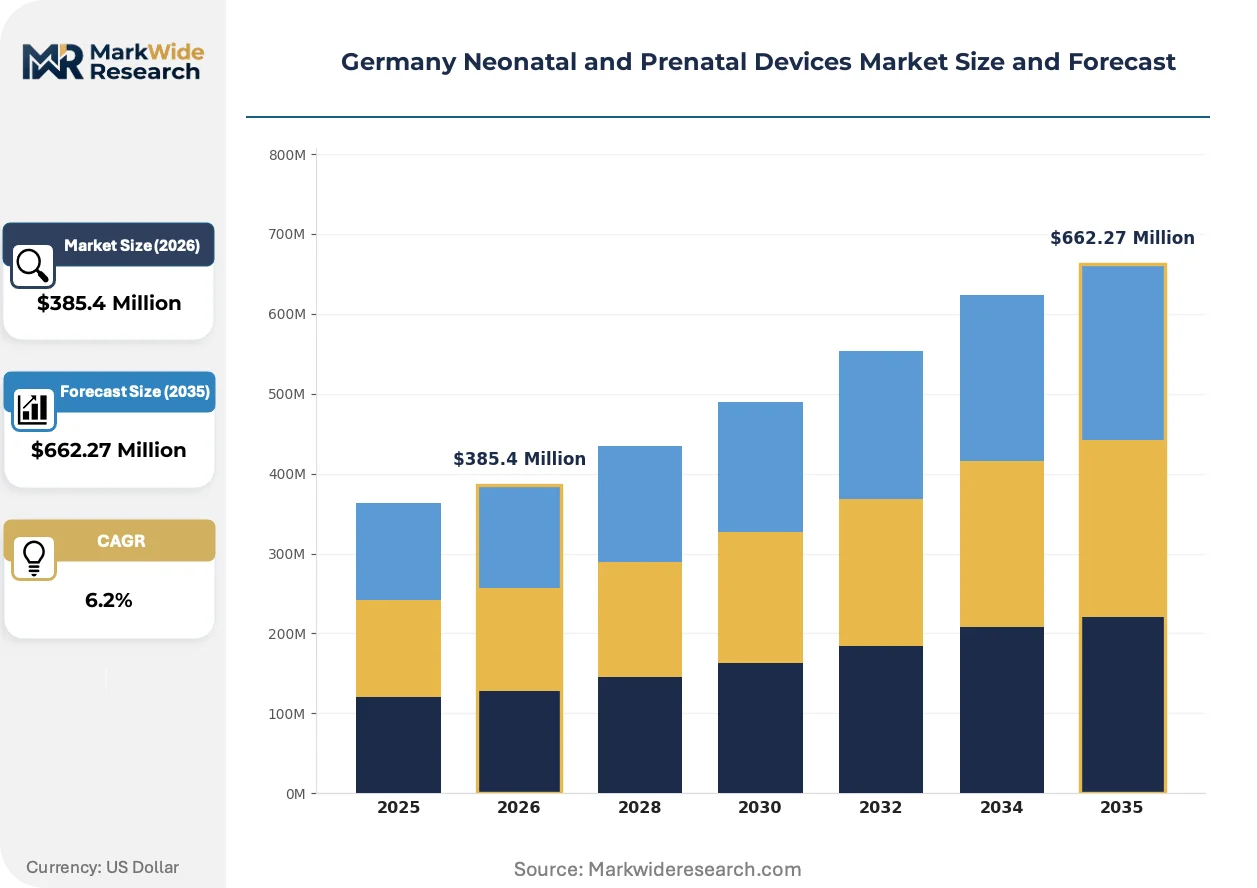
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infant Warmers, Incubators, Ventilators, Phototherapy Equipment, Monitoring Devices, Diagnostic Kits Application: Fetal Monitoring, Neonatal Resuscitation, Prenatal Screening, Jaundice Treatment, Respiratory Support, Genetic Testing End User: Maternity Clinics, Neonatal Intensive Care Units, Obstetric Centers, Pediatric Hospitals, Diagnostic Laboratories, Birthing Centers Deployment: Hospital-Based, Clinic-Based, Home Healthcare, Mobile Medical Units, Telemedicine Platforms, Specialized Care Centers |
| Companies Covered | Dragerwerk AG & Co. KGaA, F. Hoffmann-La Roche Ltd, GE Healthcare, Siemens Healthineers AG, Koninklijke Philips N.V., Medtronic PLC, Getinge AB, Fisher & Paykel Healthcare Ltd, Atom Medical Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Neonatal and Prenatal Devices Market Shifts & Advancements
Digital integration and predictive capability are reshaping competitive requirements across neonatal intensive care, with workflow optimization and diagnostic precision emerging as primary vectors of differentiation.
Artificial intelligence-enabled multiparameter monitoring is absorbing clinical decision-support functions previously handled by bedside nursing assessment. German level III NICUs in Berlin and Munich are piloting these platforms for early warning score automation. The technology is absorbing margin from conventional standalone monitoring devices by bundling analytics into hardware contracts.
Germany's MDR implementation is forcing portfolio rationalization among manufacturers with extensive legacy device catalogs. Clinical evidence requirements for class III device renewals are diverting R&D budgets toward regulatory compliance. High-risk respiratory support systems face the most compressed recertification timelines, prompting domestic manufacturers to prioritize Lübeck-based production for documentation proximity.
Buying committees in German university hospital networks are consolidating vendor relationships through multi-year managed service agreements. Equipment procurement departments are unbundling maintenance from capital purchase, shifting toward performance-guaranteed operational contracts. This restructuring is most visible in North Rhine-Westphalia's centralized hospital procurement consortia.
Germany Neonatal and Prenatal Devices Market Segmentation
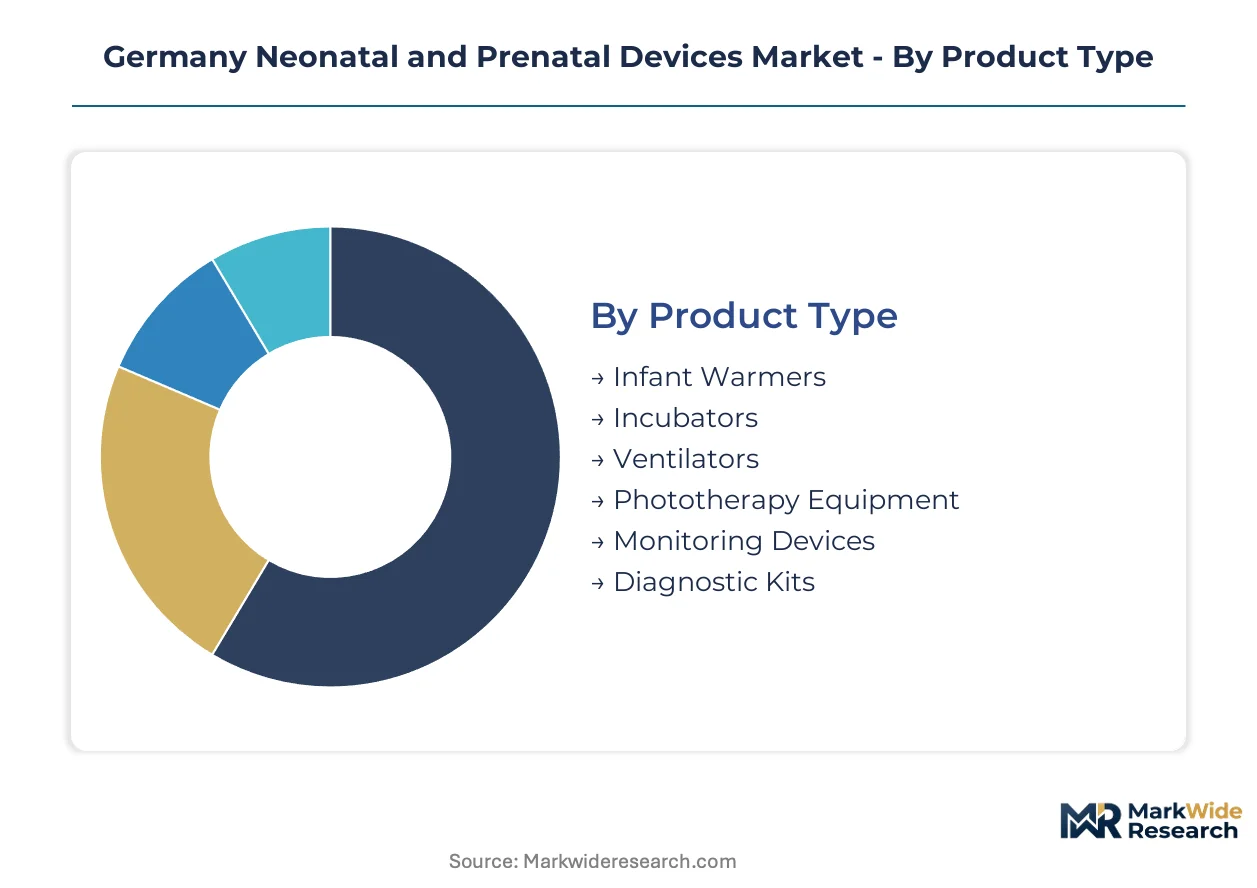
Segmentation reveals how procurement authority concentrates across German healthcare infrastructure. Product type and end-user dimensions expose where manufacturers must anchor certification resources and service networks.
Product Type:
Supply concentration for neonatal hardware tilts toward respiratory and thermoregulation systems, with domestic production in Schleswig-Holstein and Bavaria shaping availability timelines.
- Monitoring Devices:Multiparameter platforms track heart rate, blood oxygen, and respiratory patterns through integrated sensor arrays. Berlin and Munich university hospitals are expanding centralized purchasing of these systems for level III NICU capacity, absorbing margin from standalone device vendors by bundling analytics into hardware contracts.
- Incubators:Thermoregulation systems maintain thermal neutral zones between 36.0°C and 36.5°C core body temperature for premature infants. Dragerwerk's Lübeck manufacturing base sustains domestic production, compressing recertification timelines under MDR compliance pressure.
- Ventilators:Respiratory support systems for neonatal populations require precision pressure control and synchronized triggering mechanisms.
- Phototherapy Equipment:Blue light systems treat hyperbilirubinemia through wavelength-specific LED or fluorescent sources.
- Infant Warmers:Radiant heat platforms provide immediate thermal stabilization in delivery suites and emergency settings.
- Diagnostic Kits:Point-of-care testing consumables support metabolic screening and infectious disease detection.
Monitoring devices absorb the bulk of installed capacity; diagnostic kits are expanding most quickly.
Application:
Clinical workflow integration determines where technology investments concentrate, with tertiary centers anchoring protocol development before regional diffusion.
- Prenatal Screening:Non-invasive prenatal testing protocols diffuse from tertiary obstetric centers into regional obstetric networks, expanding addressable demand for high-throughput automation platforms in Saxony and Thuringia.
- Respiratory Support:Mechanical ventilation and continuous positive airway pressure systems address surfactant deficiency and apnea of prematurity. Bavarian and North Rhine-Westphalian NICU networks accelerate procurement, creating concentrated demand windows.
- Fetal Monitoring:Antepartum surveillance tracks uterine contractions and fetal heart rate patterns.
- Neonatal Resuscitation:Delivery room interventions stabilize cardiopulmonary function at birth.
- Jaundice Treatment:Phototherapy protocols reduce serum bilirubin levels in hyperbilirubinemic infants.
- Genetic Testing:Chromosomal and molecular diagnostics identify heritable conditions.
Respiratory support commands the largest share of capital expenditure; prenatal screening gains share fastest.
End User:
Procurement authority fragments across facility types, with university hospital networks consolidating vendor relationships through multi-year managed service agreements.
- Neonatal Intensive Care Units:Level III facilities provide comprehensive care for critically ill newborns, including mechanical ventilation and surgical capabilities. North Rhine-Westphalia's centralized hospital procurement consortia are unbundling maintenance from capital purchase, shifting toward performance-guaranteed operational contracts.
- Diagnostic Laboratories:Centralized genetic testing workflows demand high-throughput prenatal screening platforms. These facilities concentrate margin pools through automated sample processing and standardized reporting protocols.
- Maternity Clinics:Obstetric-focused facilities provide labor, delivery, and immediate postpartum care.
- Obstetric Centers:Specialized units manage high-risk pregnancies and fetal interventions.
- Pediatric Hospitals:General pediatric facilities with neonatal wards provide sub-specialty care.
- Birthing Centers:Low-intervention settings for uncomplicated deliveries.
NICUs anchor equipment procurement volume; diagnostic laboratories concentrate margin extraction.
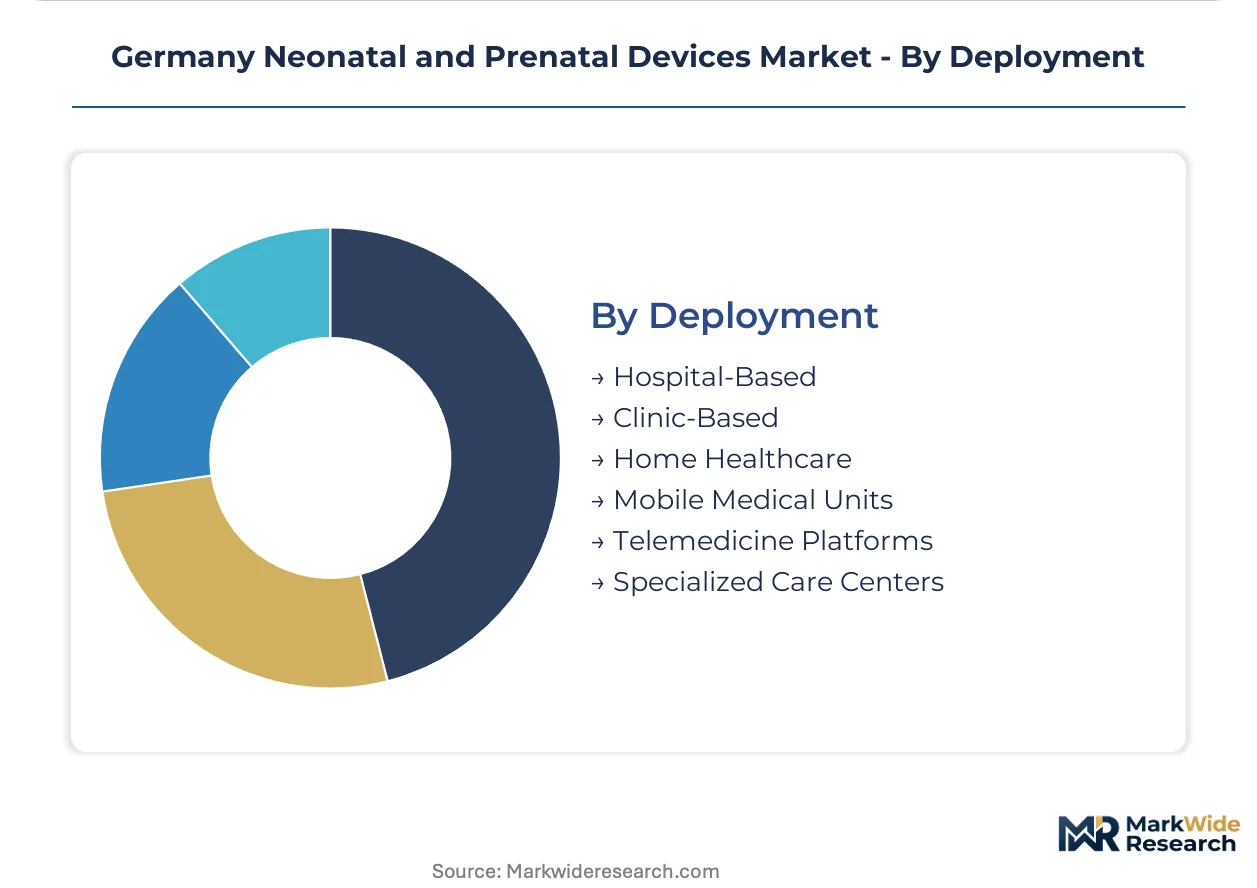
Deployment:
Physical infrastructure constraints and reimbursement frameworks shape where device deployments concentrate across German state hospital networks.
- Hospital-Based:Acute care installations dominate capital equipment deployment, with integrated informatics systems streamlining workflow management in Berlin, Munich, and Hamburg networks.
- Telemedicine Platforms:Remote consultation and monitoring capabilities extend specialist reach into underpenetrated regions, representing unconsolidated white space for predictive analytics convergence.
- Clinic-Based:Outpatient settings provide follow-up and transitional care.
- Home Healthcare:Domestic environments support post-discharge monitoring and therapy.
- Mobile Medical Units:Transportable systems enable outreach and emergency response.
- Specialized Care Centers:Dedicated facilities address specific neonatal conditions.
Hospital-based deployment holds the dominant installed base; telemedicine platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's High-Tech Strategy and the Medical Valley Erlangen cluster concentrate prenatal diagnostics R&D, anchoring regional investment flows across southern Germany.
Bavaria
University hospital networks in Munich and Erlangen drive multiparameter monitoring procurement for level III NICU expansion. The state's High-Tech Strategy funds medical device innovation through targeted grants. Medical Valley Erlangen clusters imaging and diagnostics firms developing AI-enabled fetal surveillance platforms.
North Rhine-Westphalia
Centralized hospital procurement consortia aggregate respiratory support system demand across Cologne, Düsseldorf, and Essen networks. The Federal Institute for Drugs and Medical Devices maintains regional enforcement offices in Bonn. Ruhr University Bochum anchors biomedical engineering programs supplying NICU equipment calibration specialists.
Baden-Württemberg
Stuttgart and Heidelberg university hospitals concentrate prenatal screening protocol development before regional diffusion. The state's Ministry of Economy supports MedTech startups through BioRegio STERN grants. Tübingen clusters genetic testing laboratories automating high-throughput NIPT workflows.
Berlin-Brandenburg
Charité Universitätsmedizin Berlin anchors capital equipment procurement for integrated NICU informatics systems. The Berlin Senate Department for Health coordinates telemedicine platform pilots extending specialist reach into Brandenburg's rural obstetric networks. Adlershof Science and Technology Park hosts diagnostics firms developing point-of-care neonatal testing consumables.
Hamburg
University Medical Center Hamburg-Eppendorf leads northern Germany's centralized purchasing of thermoregulation systems. The city's Health Authority enforces MDR compliance timelines for imported device registrations. Hamburg's port logistics infrastructure shapes supply chain configurations for Asian-sourced neonatal sensor components.
Germany Neonatal and Prenatal Devices Market Competitive Landscape
German producers anchor the domestic manufacturing tier; Dutch and Swiss specialists hold positions in integrated informatics and diagnostics. The vendor base concentrates around established European manufacturers with MDR certification proximity, creating tiered competition between full-portfolio incumbents and niche technology providers. Three archetypes dominate: vertically integrated domestic manufacturers, multinational health technology conglomerates with localized production, and specialized diagnostics firms. Competitive moves center on portfolio rationalization to compress recertification timelines and multi-year managed service agreements unbundling maintenance from capital purchase.
Among German-based manufacturers, Dragerwerk AG & Co. KGaA exemplifies the vertically integrated domestic archetype through its Lübeck production base. Siemens Healthineers AG occupies a position bridging imaging platforms with university hospital network relationships. Koninklijke Philips N.V. represents the multinational informatics convergence strategy, competing through integrated NICU workflow management systems. These three firms anchor distinct competitive vectors: domestic manufacturing proximity, diagnostic imaging integration, and digital platform bundling.
| Leading Market Players |
|---|
| Dragerwerk AG & Co. KGaA |
| F. Hoffmann-La Roche Ltd |
| GE Healthcare |
| Siemens Healthineers AG |
| Koninklijke Philips N.V. |
| Medtronic PLC |
| Getinge AB |
| Fisher & Paykel Healthcare Ltd |
| Atom Medical Corporation |
| Others |
Supply & Pricing Matrix
Specialized neonatal sensor components sourced from concentrated Asian manufacturing bases flow through Hamburg's port infrastructure before pricing stratifies across premium, standard, and economy tiers based on certification proximity and service bundling.
Pricing Analysis
Short lead-time premiums compress margins for manufacturers without domestic production, while spot inventory discounts attract secondary buyers in East German procurement networks. Contract-based long-term agreements dominate university hospital purchasing, with price differentiation anchored in MDR certification grade and after-sales service density. Pricing pressure stems from notified body bottlenecks extending CE marking timelines, forcing inventory carrying costs onto non-EU manufacturers. Diagnostic laboratories exhibit lowest price sensitivity due to centralized genetic testing workflows, while maternity clinics in Saxony and Thuringia face acute budget constraints.
Supply Chain Analysis
Freight cost volatility from Asian sensor component origins through Hamburg's port logistics shapes total landed cost calculations for German distributors. Manufacturing concentration in China, South Korea, and Japan for precision pressure sensors and LED phototherapy arrays creates single-source vulnerability for respiratory support system assemblers. Raw material dependencies span medical-grade polymers, semiconductor chips, and wavelength-specific LED substrates. Distribution runs through centralized hospital procurement consortia in North Rhine-Westphalia and Bavaria, bypassing traditional wholesale channels for high-value capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Medical Device Regulation erects a cost-of-compliance moat that consolidates advantages for manufacturers with notified body relationships and domestic documentation proximity, compressing market access windows for unprepared entrants.
For Market Incumbents: Acquire specialized biomedical engineering talent pools in Ruhr University Bochum and Berlin-Brandenburg corridors to anchor NICU equipment calibration capabilities. Consolidate vendor relationships through multi-year managed service agreements that unbundle maintenance from capital purchase, defending against integrated informatics convergence from multinational competitors. Prioritize Lübeck-based production documentation to compress MDR recertification timelines for high-risk respiratory support systems.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in monitoring devices opens entry paths through AI-enabled multiparameter platforms targeting underpenetrated Saxony and Thuringia obstetric networks. Telemedicine platform pilots extending specialist reach into Brandenburg's rural corridors represent unconsolidated white space with lower certification barriers. Partner with Berlin Senate Department for Health coordinators to anchor pilot deployments before scaling to university hospital networks.
For Investors and Strategic Acquirers: Notified body capacity expansion announcements from BSI Group or TÜV SÜD are the leading indicator that MDR bottlenecks are easing and legacy device renewal windows are widening. Target vertically integrated domestic manufacturers with Lübeck or Bavarian production footprints and established hospital system relationships. Watch for diagnostic laboratory automation platform consolidation in Tübingen and Heidelberg clusters as genetic testing workflows centralize.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | BSI Group and TÜV SÜD relationships compress market access timelines for compliant manufacturers. |
| Hospital System Partnership | North Rhine-Westphalia procurement consortia aggregate demand through multi-year operational contracts. |
| Software Companion Development | AI-enabled multiparameter monitoring absorbs clinical decision-support functions from bedside nursing assessment. |
| Backward Integration | Lübeck-based production of incubators and ventilators reduces recertification documentation burden under MDR. |
| Reimbursement Strategy | Federal Institute for Drugs and Medical Devices enforcement timelines shape hospital capital equipment budgeting cycles. |
Research Methodology
Document review covered hospital procurement databases, GPO contracts, and Federal Institute for Drugs and Medical Devices guidance documents, complemented by interviews with biomedical engineers, NICU clinicians, hospital purchasing committee members, and notified body assessment specialists. Secondary validation drew from BSI Group conformity assessment protocols, TÜV SÜD technical documentation, and Medical Valley Erlangen cluster investment filings. Bottom-up installed base modeling and top-down healthcare expenditure allocation were cross-referenced for triangulation.
Historical shipment data was cross-referenced against panel input from equipment procurement directors to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include product type, application, end user, and deployment mode, with regional regulatory cluster effects incorporated. CAGRs were derived from trend extrapolation adjusted for MDR compliance transition impacts and university hospital network expansion pipelines. Forecast inputs incorporated NICU capacity buildout announcements and diagnostic laboratory automation investment cycles.
Inputs from hospital procurement databases and notified body assessment queues were available through the study window; gaps in real-time legacy device renewal success rates introduce uncertainty bands around market access timeline assumptions. Stakeholders should weight assumptions against their own operating context and notified body relationship status.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
Umbilical Market
Neonatal Care
India Fetal and Neonatal Care Equipment Market
Neonatal Care
Neonatal Dialysis Market
Neonatal Care
India Neonatal and Prenatal Devices Market
Neonatal Care
Necrotising Enterocolitis (NEC) Market
Neonatal Care
Japan Neonatal and Prenatal Devices Market
Neonatal Care
North America Fetal and Neonatal Monitoring Market
Neonatal Care
Spain Neonatal and Prenatal Devices Market
Neonatal Care
Global Preterm Birth and PROM Testing Market
Neonatal Care
Australia Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal and Infant Care Equipment Market
Neonatal Care
Asia-Pacific Fetal and Neonatal Care Equipment Market
Neonatal Care
Global NICU Catheter Market
Neonatal Care
Neonatal Infant Care Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Treatment Market
Neonatal Care
Neonatal and Prenatal Devices Market