
 Global Renal Dialysis Equipment Market | 2026-2036
Global Renal Dialysis Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Renal Dialysis Equipment Market Outlook
Direct sales channels for dialysis equipment is tilting toward bundled service contracts that lock in long-term consumable revenue. Fresenius Medical Care AG leverages its vertically integrated clinic network to anchor recurring equipment placements. Baxter International competes through peritoneal dialysis specialization that sustains higher-margin home therapy conversions.
Renal dialysis equipment encompasses hemodialysis machines, dialyzers, and peritoneal dialysis systems that filter blood through semipermeable membranes, typically operating with blood flow rates of 200-500 mL/min and ultrafiltration precision within 10 mL/hour tolerances. Hemodialysis machines occupy the largest installed base due to entrenched clinic infrastructure, while portable dialysis technology represents the fastest-expanding segment as manufacturers miniaturize systems for home deployment. Dialysis centers command the dominant end-user share through high patient throughput, though home care is capturing disproportionate growth as reimbursement frameworks adapt to remote monitoring capabilities.
The FDA governs 510(k) and PMA pathways for dialysis devices in the United States, while the EU MDR and CE marking requirements reshape market access timelines across European member states. Japan's PMDA maintains distinct clinical evidence standards that filter entrants lacking localized trial data. Stakeholders must monitor reimbursement parity between in-center and home modalities as this balance determines capital allocation across product development portfolios.
Market Dynamics
Home dialysis adoption is restructuring equipment procurement patterns as reimbursement frameworks in the United States and Japan realign capital flows toward portable systems and remote monitoring infrastructure.
Growth Catalysts
- US Medicare ESRD bundled payment expansion:Reimbursement parity between in-center and home hemodialysis is redirecting provider investment toward home-based machine deployments.
- Japan's PMDA accelerated review pathway:Streamlined approval timelines for breakthrough dialysis devices are shortening market entry cycles for novel wearable systems.
- Biocompatible synthetic membrane advances:Polyethersulfone and polymethyl methacrylate dialyzer materials are reducing inflammatory response rates and extending treatment intervals.
Market Restraints
- Concentrated dialyzer membrane supply:German and Japanese specialty chemical producers control high-performance polymer feedstock, creating input bottlenecks during demand surges.
- EU MDR clinical evidence requirements:Expanded post-market surveillance obligations are extending certification timelines and elevating compliance costs for European market access.
- Water treatment infrastructure dependency:Hemodialysis requires pharmaceutical-grade purified water systems that constrain rapid clinic expansion in water-stressed regions.
Strategic Opportunities
- Brazil's underpenetrated home therapy segment:ANVISA regulatory harmonization with international standards is reducing barriers for multinational equipment suppliers entering Latin America's largest dialysis market.
- AI-integrated alarm systems:Machine learning algorithms analyzing blood pressure and ultrafiltration patterns are enabling predictive intervention protocols that reduce hospitalization rates.
- India's PLI scheme for medical devices:Production-linked incentives for domestic manufacturing are attracting component assembly investments that lower landed costs for price-sensitive hospital chains.
Industry Challenges
- Bioengineering talent scarcity:Specialized expertise in extracorporeal circuit design and hemocompatibility testing remains concentrated in German, Swiss, and Japanese research clusters.
- Legacy clinic infrastructure lock-in:Existing hemodialysis center investments in fixed-bed systems and water treatment plants create switching costs that slow home modality transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Renal Dialysis Equipment Market |
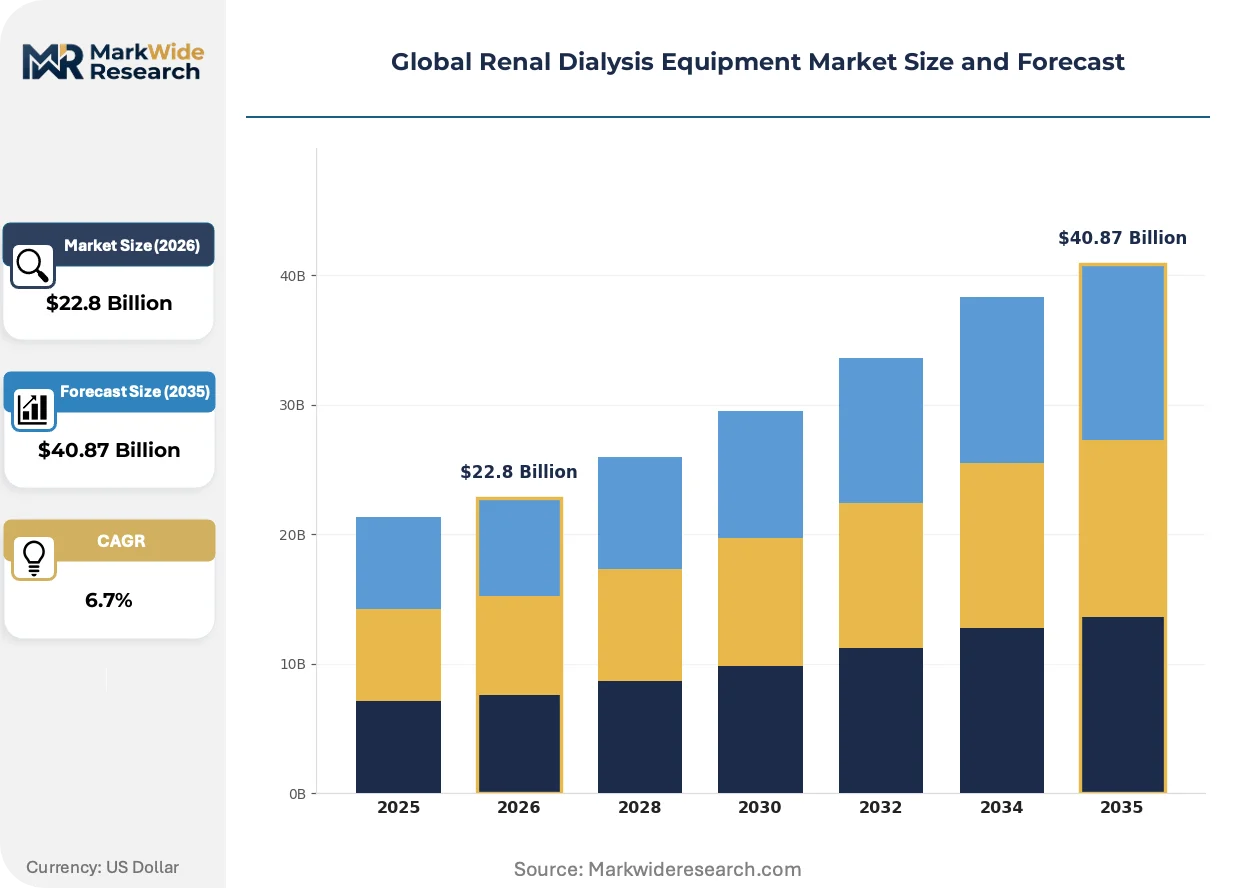
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $40.87 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemodialysis Machines, Peritoneal Dialysis Equipment, Dialyzers, Accessories End User: Hospitals, Kidney Clinics, Home Care, Dialysis Centers Technology: Conventional Dialysis, Online Dialysis, Portable Dialysis, Automated Systems Distribution Channel: Direct Sales, Retail Pharmacies, Online Platforms, Distributors |
| Companies Covered | Fresenius Medical Care AG, Baxter International, Nipro Corporation, B. Braun Melsungen AG, Nikkiso Co., Ltd., Asahi Kasei Medical Co., Ltd., Medtronic, DaVita Inc., Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Renal Dialysis Equipment Market Strategic Shifts
Device miniaturization and connectivity integration are converging to enable treatment modality migration from clinical settings toward patient-controlled environments, fundamentally altering service delivery economics.
Wearable artificial kidney prototypes utilizing sorbent-based regeneration technology are rendering obsolete the fixed-station dialysis model that has dominated chronic kidney disease management for decades. Academic medical centers in California and Texas are piloting these systems with select patient cohorts. The technology is compressing the addressable market for conventional clinic-based machines while creating new recurring revenue streams in consumable cartridges and remote monitoring subscriptions.
EU MDR Article 120 transitional provisions are forcing dialysis device manufacturers to restructure clinical evidence portfolios ahead of 2028 deadlines. Companies must now generate post-market clinical follow-up data for legacy products previously cleared under the Medical Devices Directive. German and Italian notified bodies are experiencing backlog accumulation, prompting suppliers to accelerate parallel FDA 510(k) submissions to maintain revenue continuity.
Hospital procurement departments are consolidating vendor relationships through multi-year managed service agreements that bundle equipment, disposables, and technical support. This model displaces traditional capital purchase transactions in the United States and Western Europe. Integrated delivery networks in Florida and Pennsylvania have pioneered these arrangements, extracting volume commitments in exchange for exclusive supply contracts that lock out competing manufacturers.
Global Renal Dialysis Equipment Market Segmentation
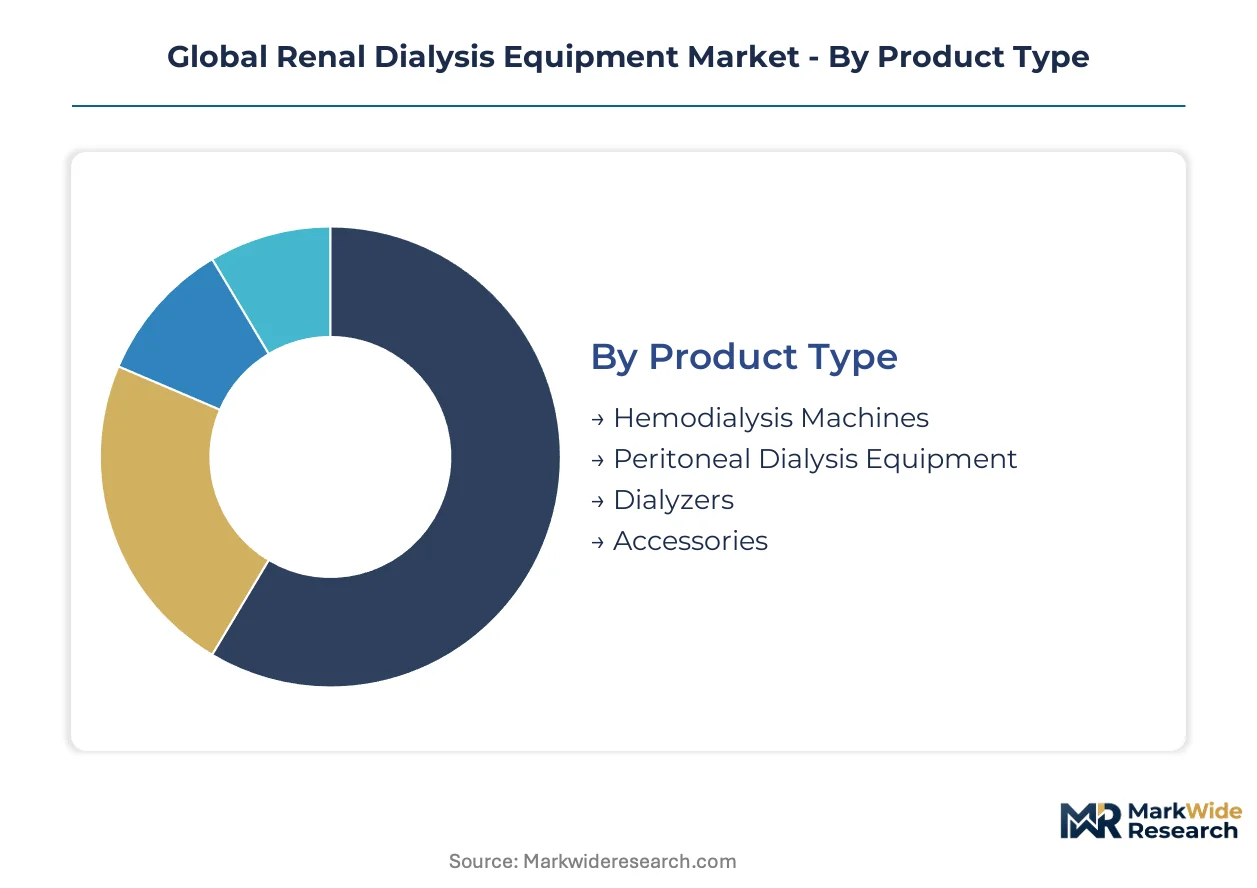
Segmentation in renal dialysis equipment reveals divergent service intensity requirements across product categories. Hemodialysis machines demand intensive technical support and preventive maintenance contracts, while consumable segments rely on logistics velocity rather than field engineering presence.
Product Type:
After-sales service intensity varies sharply across this category, with capital equipment requiring multi-year service agreements and disposable components flowing through high-velocity replenishment models.
- Hemodialysis Machines:These systems integrate blood pumps, heparin pumps, and ultrafiltration controllers operating at 200-500 mL/min flow rates. Demand concentrates in United States dialysis centers where Medicare reimbursement parity is redirecting capital budgets toward home-compatible configurations. Service contracts typically span 5-7 years with quarterly preventive maintenance intervals.
- Peritoneal Dialysis Equipment:Cyclers and solution warmers support nocturnal automated exchanges through single-catheter access. Japan's PMDA accelerated review pathway is shortening approval timelines for next-generation wearable systems, compressing product refresh cycles for established manufacturers.
- Dialyzers:Hollow-fiber membrane cartridges utilizing polysulfone or polyethersulfone materials achieve toxin clearance through 1.0-2.5 m² surface areas. German and Japanese polymer suppliers control high-performance feedstock, creating supply bottlenecks during demand surges.
- Accessories:Bloodlines, fistula needles, and transducer protectors complete the extracorporeal circuit. India's PLI scheme for medical devices is attracting component assembly investments that reduce landed costs for price-sensitive hospital procurement departments.
By volume, Dialyzers leads. By growth pace, Peritoneal Dialysis Equipment is ahead.
End User:
Procurement authority and reimbursement pathways structure this category, with institutional buyers negotiating enterprise contracts and home patients navigating insurance authorization complexity.
- Hospitals:Acute care settings deploy dialysis for emergency renal replacement through temporary vascular access. United States hospital procurement departments are consolidating vendor relationships through multi-year managed service agreements that bundle equipment, disposables, and technical support.
- Kidney Clinics:Specialized nephrology practices offer outpatient dialysis with nephrologist oversight. Brazil's underpenetrated home therapy segment is creating expansion opportunities as ANVISA regulatory harmonization reduces barriers for multinational suppliers.
- Home Care:Patients self-administer peritoneal or home hemodialysis with remote monitoring support. AI-integrated alarm systems analyzing blood pressure and ultrafiltration patterns are enabling predictive intervention protocols.
- Dialysis Centers:High-throughput facilities operate fixed-station hemodialysis with dedicated water treatment infrastructure. Legacy investments in fixed-bed systems create switching costs that slow modality transitions toward portable alternatives.
By patient throughput, Dialysis Centers dominates. By expansion trajectory, Home Care is climbing the fastest.
Technology:
Maturity gradients separate established modalities from emerging platforms, with regulatory evidence requirements widening the gap between conventional and breakthrough systems.
- Conventional Dialysis:Three-times-weekly in-center hemodialysis remains the clinical default despite inferior outcomes compared to more frequent regimens. EU MDR Article 120 transitional provisions are forcing manufacturers to restructure clinical evidence portfolios for these legacy products.
- Online Dialysis:Hemodiafiltration utilizes ultrapure dialysate as substitution fluid, enhancing middle-molecule clearance. German and Italian notified bodies are experiencing backlog accumulation for these system certifications.
- Portable Dialysis:Miniaturized systems enable treatment outside fixed clinical infrastructure. Wearable artificial kidney prototypes utilizing sorbent-based regeneration are rendering obsolete the fixed-station model in academic medical centers across California and Texas.
- Automated Systems:Peritoneal dialysis cyclers manage solution exchanges without patient intervention during sleep. Remote monitoring capabilities are adapting reimbursement frameworks toward home modality parity.
By installed base, Conventional Dialysis leads. By innovation velocity, Portable Dialysis is gaining share fastest.
Distribution Channel:
Channel economics reflect product complexity, with capital equipment flowing through direct sales and consumables fragmenting across intermediaries.
- Direct Sales:Manufacturer field forces negotiate enterprise contracts with integrated delivery networks. Florida and Pennsylvania IDNs have pioneered exclusive supply arrangements extracting volume commitments.
- Retail Pharmacies:Community pharmacies dispense peritoneal dialysis solutions and accessories for home patients. Reimbursement authorization complexity limits this channel's expansion for prescription-dependent modalities.
- Online Platforms:E-procurement portals serve smaller clinics and independent nephrology practices. India's domestic manufacturing incentives are lowering landed costs for hospital chains purchasing through digital channels.
- Distributors:Regional medical device distributors provide inventory buffering and local technical support. Water treatment infrastructure dependency constrains rapid clinic expansion in water-stressed regions, limiting distributor addressable markets.
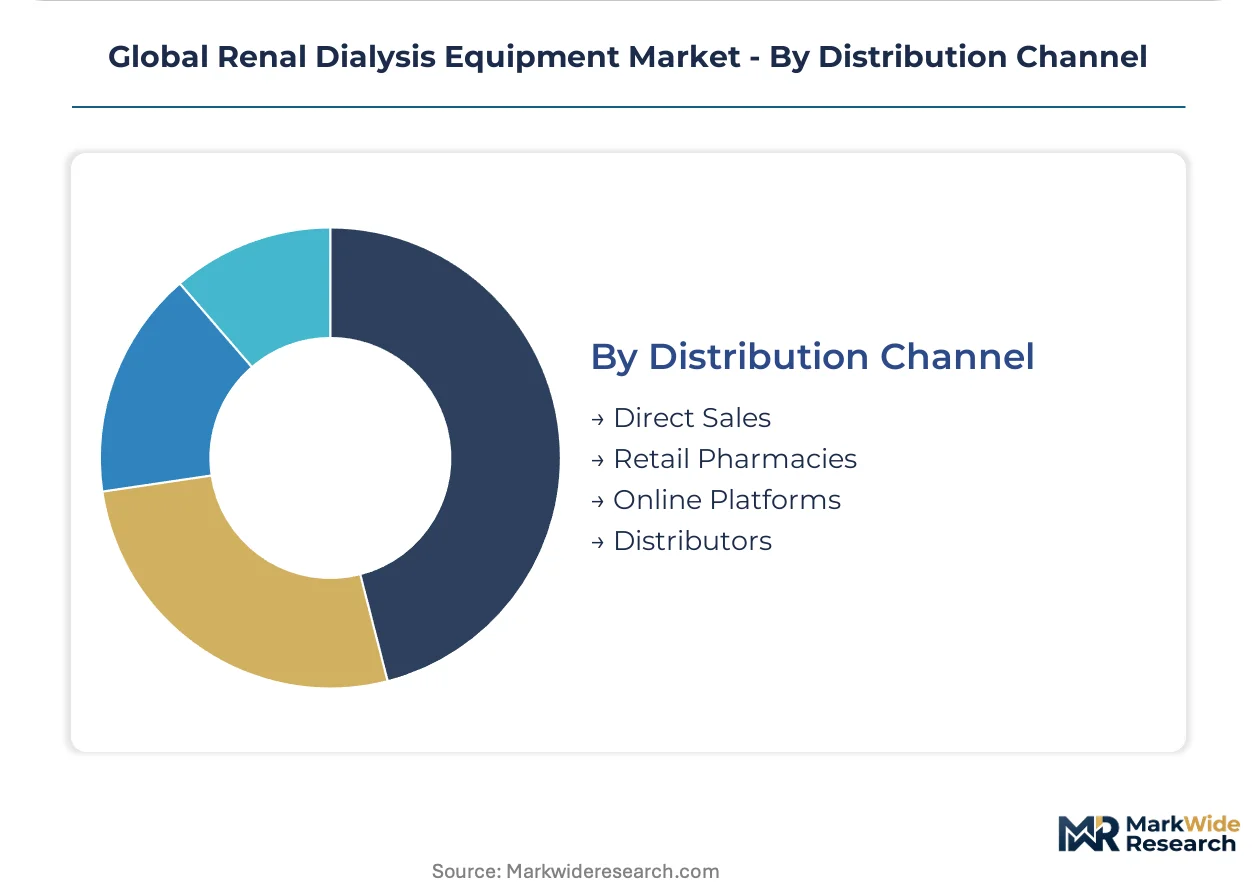
By contract value, Direct Sales leads. By channel expansion, Online Platforms shows the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese manufacturing clusters where polymer feedstock scarcity elevates dialyzer membrane premiums, while procurement leverage accumulates in United States integrated delivery networks extracting volume discounts through exclusive supply arrangements.
United States
Medicare ESRD bundled payment expansion and aging demographics sustain equipment procurement volumes across dialysis centers and home care settings. FDA 510(k) and PMA pathways govern device approvals while reimbursement parity between in-center and home hemodialysis redirects capital budgets. Academic medical centers in California and Texas pilot wearable artificial kidney prototypes utilizing sorbent-based regeneration technology.
Germany
Specialty chemical producers control high-performance polysulfone and polyethersulfone polymer feedstock for dialyzer membranes, creating supply bottlenecks during demand surges. EU MDR Article 120 transitional provisions force manufacturers to restructure clinical evidence portfolios ahead of 2028 deadlines. Notified bodies in Berlin and Munich experience certification backlog accumulation, prompting parallel FDA submission strategies.
Japan
PMDA accelerated review pathways streamline approval timelines for breakthrough dialysis devices and next-generation wearable systems. Aging population density and high chronic kidney disease prevalence sustain peritoneal dialysis equipment demand. Osaka and Tokyo research clusters concentrate specialized bioengineering expertise in extracorporeal circuit design and hemocompatibility testing.
Brazil
Underpenetrated home therapy segments create expansion opportunities as patient cohorts seek treatment flexibility outside clinic settings. ANVISA regulatory harmonization with international standards reduces barriers for multinational equipment suppliers entering Latin America's largest dialysis market. São Paulo and Rio de Janeiro kidney clinics drive outpatient infrastructure development.
India
Production-linked incentive schemes for medical devices attract component assembly investments that lower landed costs for price-sensitive hospital procurement departments. Domestic manufacturing capacity expands across Maharashtra and Gujarat industrial corridors. Water treatment infrastructure dependency constrains rapid clinic expansion in water-stressed northern and central regions.
Global Renal Dialysis Equipment Market Competitive Environment
Vertically integrated clinic operators and specialized peritoneal dialysis manufacturers split the market between bundled service contracts and higher-margin home therapy conversions. The vendor base concentrates around three strategic archetypes: captive clinic networks anchoring recurring equipment placements, membrane technology specialists controlling polymer feedstock access, and portable system innovators compressing product refresh cycles. Competitive moves center on multi-year managed service agreements locking in consumable revenue streams and regulatory parallel submissions maintaining revenue continuity across FDA and EU MDR pathways.
Among German and Japanese membrane specialists, Fresenius Medical Care AG and Asahi Kasei Medical Co., Ltd. occupy positions exemplifying vertical integration archetypes where captive clinic networks or polymer feedstock control anchor competitive positioning. Baxter International represents the peritoneal dialysis specialization vector, while Medtronic sits within the portable technology innovation tier. These three companies illustrate how geographic clustering around regulatory hubs and manufacturing corridors concentrates strategic leverage in distinct competitive dimensions.
| Leading Market Players |
|---|
| Fresenius Medical Care AG |
| Baxter International |
| Nipro Corporation |
| B. Braun Melsungen AG |
| Nikkiso Co., Ltd. |
| Asahi Kasei Medical Co., Ltd. |
| Medtronic |
| DaVita Inc. |
| Teleflex Incorporated |
| Others |
Value Chain & Pricing Dynamics
Underutilized dialyzer membrane production capacity in Germany is forcing specialty polymer suppliers to accept longer payment terms and volume-commitment contracts, compressing margins upstream while downstream equipment manufacturers consolidate procurement leverage through multi-year managed service agreements.
Pricing Analysis
The customization-premium spread between configured-to-order hemodialysis machines and standard peritoneal dialysis cyclers runs wide, with hospital procurement departments extracting discounts through exclusive supply arrangements while home care patients face limited negotiation leverage. Three-tier pricing structure across premium, standard, and economy levels stratifies by membrane biocompatibility grade and FDA 510(k) pathway tier. Cost compression in economy-tier dialyzers is intensifying because Indian component assembly investments are flooding price-sensitive markets. Dialysis centers demonstrate highest price sensitivity due to Medicare reimbursement caps, while academic medical centers piloting wearable systems show lowest sensitivity.
Supply Chain Analysis
Contract-manufacturing concentration for dialysis equipment rests with German and Japanese polymer specialists controlling hollow-fiber membrane production, alongside Indian electronics assemblers serving control system components. Geographic supply concentration centers on Germany, Japan, and India for critical inputs. Raw material dependencies include polysulfone and polyethersulfone polymer feedstock, sorbent regeneration cartridges, and pharmaceutical-grade water treatment membranes. Single-source vulnerability in German specialty chemical producers creates supply bottlenecks during demand surges. Distribution runs through direct sales forces negotiating enterprise contracts with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where remote monitoring capabilities are rewiring reimbursement frameworks toward subscription-based service models, with interoperability standards determining which device ecosystems capture patient data flows.
For Market Incumbents: Build switching-cost moats through backward integration into dialyzer membrane production and captive water treatment infrastructure deployment. Fresenius Medical Care's clinic network anchoring strategy demonstrates how vertical control over consumable supply locks out competing equipment vendors. Defensive consolidation should prioritize FDA 510(k) pathway expertise to accelerate parallel submissions ahead of EU MDR deadlines, while capacity addition in Maharashtra industrial corridors secures cost advantages for Asian market penetration. For New Entrants and Emerging Players: Brazil's underpenetrated home therapy segment offers the most penetrable white-space target, with ANVISA regulatory harmonization reducing traditional multinational barriers. India's PLI scheme for medical devices creates second-tier opportunity for component assembly specialists seeking hospital chain procurement contracts. Go-to-market positioning should emphasize AI-integrated alarm systems enabling predictive intervention protocols that reduce hospitalization rates, differentiating against legacy clinic infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward portable technology innovators with sorbent-based regeneration capabilities and established relationships with academic medical centers in California and Texas. Long-term viability across the projection horizon hinges on reimbursement parity achievement between in-center and home modalities. Acquisition target archetype: mid-cap specialists with PMDA accelerated review pathway experience and existing wearable artificial kidney pilot programs. The signal to watch is Medicare ESRD bundled payment expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 120 compliance secures European market access ahead of 2028 deadlines. |
| Hospital System Partnership | Florida and Pennsylvania IDN exclusive supply arrangements lock in consumable revenue streams. |
| Software Companion Development | AI-integrated alarm systems analyzing ultrafiltration patterns enable predictive intervention protocols. |
| Reimbursement Strategy | Medicare ESRD bundled payment parity between in-center and home modalities redirects capital budgets. |
| Backward Integration | Captive dialyzer membrane production insulates against German and Japanese polymer supply bottlenecks. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with dialysis center operations directors, hospital biomedical engineers, GPO contracts managers, and nephrology clinic administrators; alongside secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, PMDA approval registries, and EU MDR notified body certification records. Bottom-up and top-down triangulation cross-checked equipment shipment volumes against patient prevalence estimates and treatment modality penetration rates.
Forecast inputs considered product type segmentation across hemodialysis machines, peritoneal dialysis equipment, dialyzers, and accessories; end-user segmentation spanning hospitals, kidney clinics, home care, and dialysis centers; technology segmentation from conventional to portable systems; and geographic adoption patterns across the analysis window. CAGRs were derived from regression analysis of historical procurement data against demographic and reimbursement drivers, incorporating biocompatible membrane innovation cycles and regulatory pathway timeline assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by wearable artificial kidney pioneers or unexpected EU MDR deadline extensions would shift outcomes. Cross-checking against CMS Medicare claims data and Japanese PMDA approval velocity metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
South Africa Radiotherapy Market
Medical Equipment
PCR Plate Sealer Market
Medical Equipment
Global Kidney Dialysis Equipment and Supplies Market
Medical Equipment
Histology Embedding System Market
Medical Equipment
Global Medical Power Supply Market
Medical Equipment
Cell Culture Incubator Market
Medical Equipment
PMMA Healthcare Market
Medical Equipment
Global Cardiopulmonary Stress Testing Systems Market
Medical Equipment
Operating Table Parts Market
Medical Equipment
Global Vacuum Mixing Devices Market
Medical Equipment
Cryogenic Freezers Market
Medical Equipment
China Radiotherapy Market
Medical Equipment
Medication Pouch Inspection Systems Market
Medical Equipment
Medical Filter Market
Medical Equipment
Global Portable Beds Market
Medical Equipment
Ultrasound Equipment Market