
 Disposable Oxygen Masks Market | 2026-2036
Disposable Oxygen Masks Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Oxygen Masks Market Analysis
The capability gap between high-volume automated manufacturers and smaller regional suppliers is collapsing as contract molding costs fall and cleanroom outsourcing spreads. Medline Industries leverages integrated distribution across acute and post-acute channels to sustain margin capture. Dynarex Corporation anchors its position through private-label partnerships with group purchasing organizations. Flexicare Medical Limited differentiates via specialized pediatric mask geometries that navigate stricter European fit-testing protocols.
A disposable oxygen mask is a single-use respiratory interface typically constructed from medical-grade polypropylene or PVC with an elastic strap and nasal bridge, designed to deliver controlled oxygen concentrations to patients without cross-contamination risk. Adult masks dominate volume throughput in emergency departments and surgical recovery units, while pediatric masks command premium positioning due to dimensional precision requirements and smaller production batch economics. Non-rebreather masks with reservoir bags represent the fastest-expanding product configuration as high-flow oxygen therapy protocols expand across ambulance services and intensive care settings.
The FDA regulates disposable oxygen masks as Class II medical devices under 510(k) premarket notification requirements, while the EU Medical Device Regulation imposes stricter clinical evaluation and post-market surveillance obligations on manufacturers seeking CE marking. ISO 10993 biocompatibility testing and ISO 13485 quality management certification function as baseline market access credentials across both jurisdictions. Stakeholders must monitor evolving single-use plastics legislation in Europe and state-level hospital sustainability mandates in the United States, as material substitution timelines could force rapid supply chain recalibration.
Market Dynamics
Homecare oxygen therapy expansion is compressing hospital-centric supply chains as durable medical equipment distributors build direct-to-patient fulfillment networks. Post-acute care facilities now account for substantial mask consumption outside traditional inpatient channels.
Growth Catalysts
- Chronic respiratory disease prevalence:COPD and sleep apnea patient populations in the United States and Germany sustain recurring mask replacement cycles through Medicare and statutory health insurance reimbursement pathways.
- ISO 13485 certification expansion:Cleanroom outsourcing vendors in Mexico and Malaysia enable mid-tier manufacturers to access hospital procurement networks without capital-intensive facility investments.
- High-flow oxygen protocols:Emergency medical services in Australia and Canada are standardizing non-rebreather mask configurations with reservoir bags for prehospital critical care.
Market Restraints
- Medical-grade PVC resin concentration:Three petrochemical suppliers control specialty polymer feedstock for nasal bridge components, exposing converters to input cost volatility.
- EU single-use plastics directive:The European Commission's phased restrictions on disposable medical plastics force material substitution timelines that compress margin structures.
- Reusable interface competition:Silicone mask systems with sterilization protocols threaten volume erosion in surgical recovery and long-term care settings.
Strategic Opportunities
- India homecare penetration:The country's PLI scheme for medical devices and expanding health insurance coverage create white space for disposable mask distributors outside hospital procurement.
- Pediatric dimensional specialization:Stricter European fit-testing protocols for neonatal and infant populations reward manufacturers with anatomical modeling capabilities.
- Ambulance fleet electrification:Oxygen delivery systems in battery-powered emergency vehicles require lightweight mask designs that reduce portable concentrator load.
Industry Challenges
- Cleanroom technician scarcity:ISO 14644-compliant facility operations require specialized personnel that contract manufacturers struggle to retain in competitive labor markets.
- 510(k) submission complexity:FDA predicate device identification for novel mask geometries extends regulatory timelines and freezes product development capital.
- Legacy ERP integration:Hospital group purchasing organization data exchange protocols force middleware investments that strain smaller supplier IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Oxygen Masks Market |
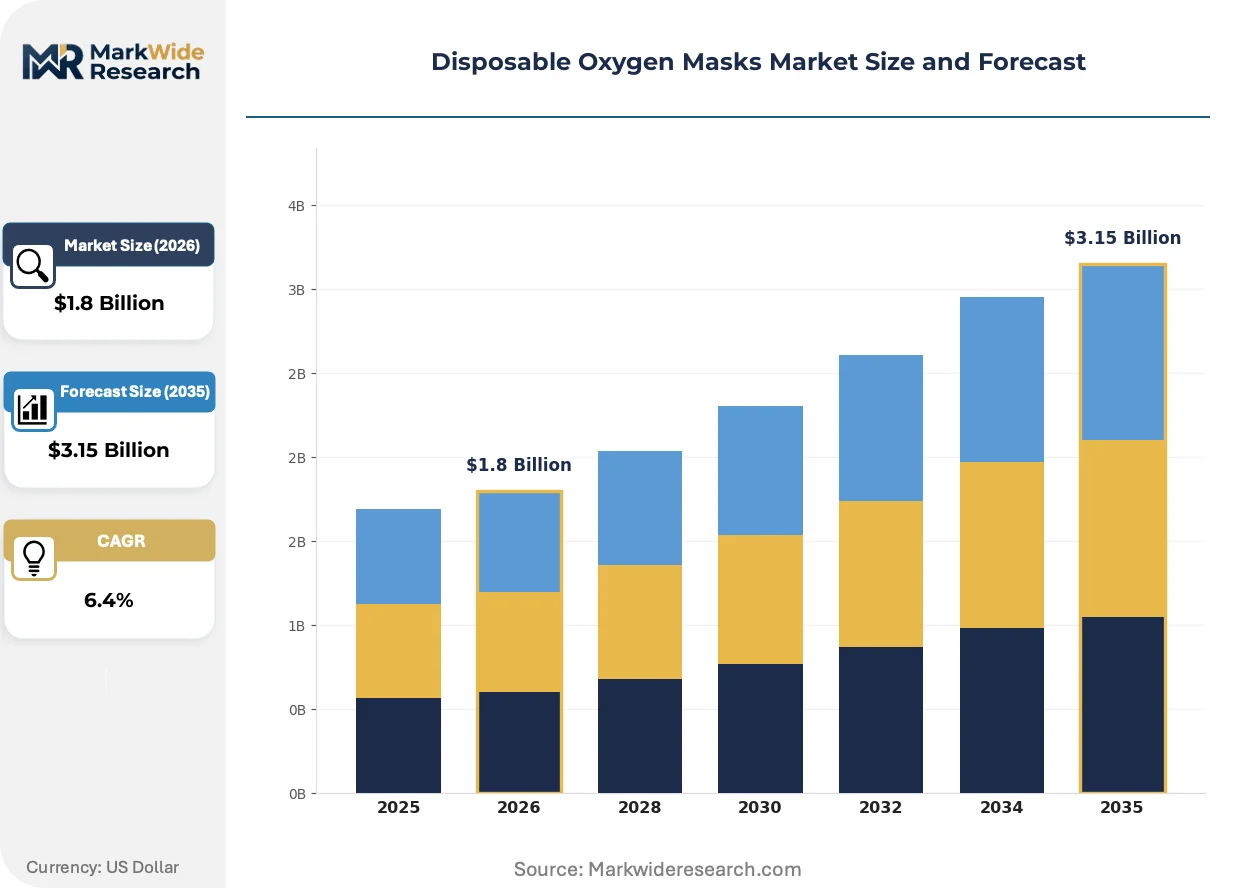
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adult Masks, Pediatric Masks, Valve Masks, Non-Rebreather Masks Material: Polypropylene, PVC, Silicone, Latex End User: Hospitals, Homecare, Ambulances, Clinics Distribution Channel: Online Retail, Medical Supply Stores, Direct Sales, Wholesalers |
| Companies Covered | Medline Industries, Besmed Health Business Corp, Dynarex Corporation, Flexicare Medical Limited, Vyaire Medical, Intersurgical Ltd., Allied Healthcare Products, Cardinal Health, Drive Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Oxygen Masks Market Emerging Trajectories
Material science advances and regulatory tightening are converging to redefine product specifications and procurement criteria across oxygen delivery interfaces. Manufacturers now compete on biocompatibility certification depth rather than unit cost alone.
Biodegradable polymer formulations derived from polylactic acid blends are displacing conventional PVC in European mask production. German and French hospital systems are piloting compostable nasal bridges and elastic straps through green procurement mandates. This material transition is compressing incumbent petrochemical suppliers' pricing power while creating certification premiums for early adopters.
The EU Medical Device Regulation's post-market surveillance requirements are extending clinical evaluation obligations for Class IIa respiratory interfaces. Manufacturers must now maintain vigilance systems that track adverse events across distributed homecare settings. Pediatric mask categories face the steepest compliance burden due to limited predicate device availability and stricter biocompatibility testing protocols.
Hospital sustainability officers are consolidating supplier relationships around vendors with verified carbon footprint disclosures. Group purchasing organizations in California and New York are embedding environmental scoring into mask tender evaluations. This behavioral shift favors integrated manufacturers with captive recycling programs over pure-play converters dependent on external resin sourcing.
Disposable Oxygen Masks Market Segmentation
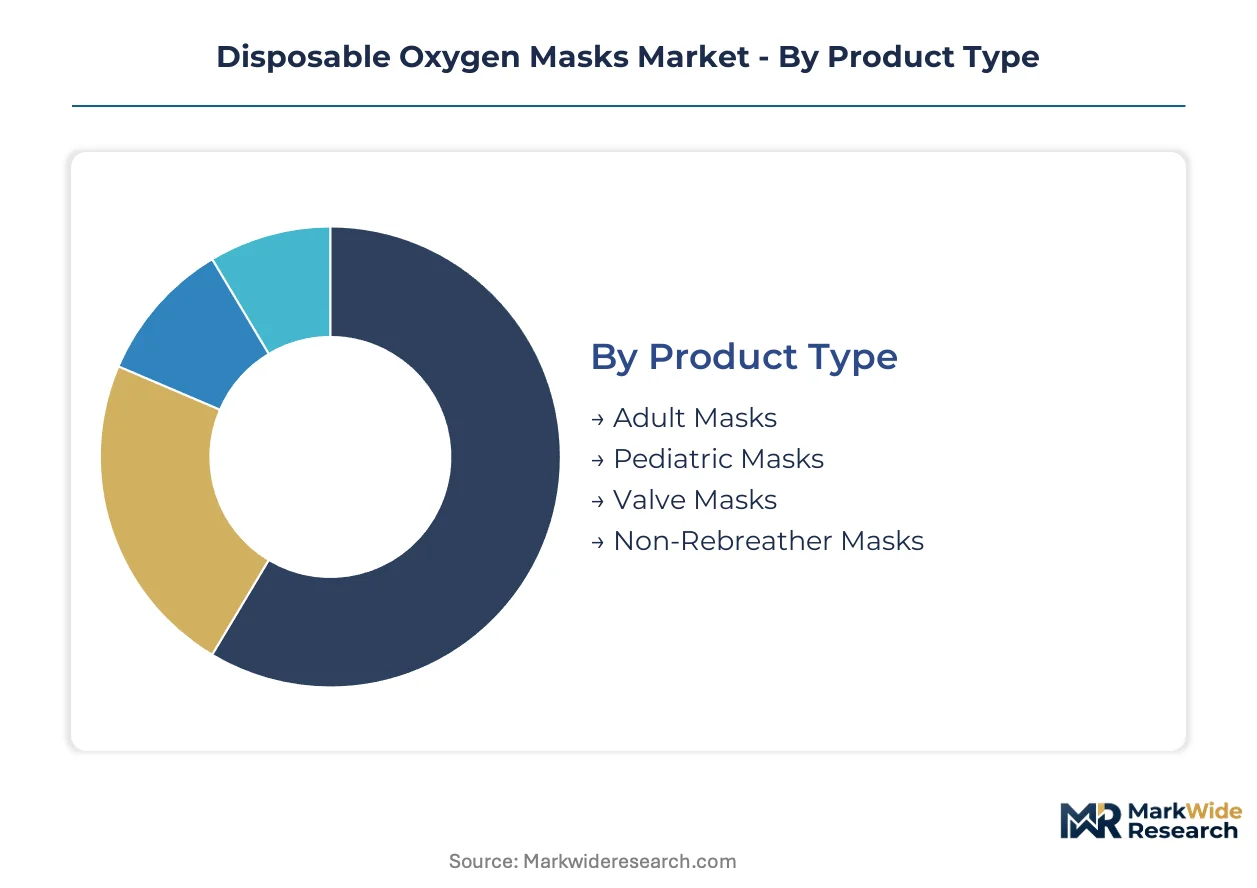
Channel economics in the disposable oxygen masks market diverge sharply across acute care procurement networks and emerging direct-to-patient fulfillment models. Segmentation strategy must account for how FDA 510(k) clearance status and ISO 13485 certification depth determine which product configurations access hospital group purchasing organizations versus retail pharmacy shelves.
Product Type:
Hospital supply chains favor configurations with established predicate device pathways, while ambulance services and homecare distributors prioritize reservoir-equipped designs for high-flow protocols.
- Adult Masks:Standard nasal bridge and elastic strap construction in medical-grade polypropylene dominates emergency department throughput. United States hospital procurement networks specify these for surgical recovery and general ward oxygen delivery, with Medicare reimbursement codes sustaining replacement cycle predictability.
- Non-Rebreather Masks:Reservoir bag configurations with one-way valves deliver FiO2 concentrations above 80% for critical hypoxia management. Australian and Canadian ambulance fleets are standardizing these for prehospital transport, compressing delivery timelines for suppliers with TGA and Health Canada registrations.
- Pediatric Masks:Anatomical precision requirements for neonatal and infant populations command specialized molding capabilities and smaller batch economics.
- Valve Masks:One-way expiratory valve designs reduce rebreathing risk in infectious disease protocols and isolation settings.
Adult masks dominate installed base. Non-rebreather masks are where expansion concentrates.
Material:
Cost tier stratification separates petrochemical-derived standards from emerging biopolymer premiums, with regulatory pressure accelerating substitution timelines.
- Polypropylene:Injection-molded medical-grade resin with ISO 10993 biocompatibility certification anchors volume production for acute care. German hospital systems are piloting recycled-content variants through green procurement mandates, compressing incumbent pricing power.
- PVC:Plasticized formulations offer dimensional stability for nasal bridge components but face EU single-use plastics directive phase-out pressure. Three petrochemical suppliers control specialty resin feedstock, exposing converters to input cost volatility.
- Silicone:Reusable interface competition threatens disposable volume in surgical recovery settings with sterilization protocol acceptance.
- Latex:Allergen concerns restrict application to specific patient populations with documented tolerance profiles.
Polypropylene captures the highest volume throughput. PVC faces the steepest substitution risk.
End User:
Customer type determines certification burden and fulfillment infrastructure requirements, with post-acute channels demanding lighter logistics footprints.
- Hospitals:Group purchasing organization compliance and FDA 510(k) predicate device matching dominate procurement criteria. California and New York sustainability officers are embedding carbon footprint scoring into tender evaluations.
- Homecare:Durable medical equipment distributors in the United States and Germany are building direct-to-patient networks outside traditional inpatient channels, compressing hospital-centric supply chain margins.
- Ambulances:Battery-powered emergency vehicle electrification is driving lightweight mask specifications to reduce portable concentrator load.
- Clinics:Outpatient respiratory therapy centers favor standard configurations with streamlined inventory management.
Hospitals retain procurement volume leadership. Homecare is climbing the fastest.
Distribution Channel:
Supply concentration varies across channel types, with integrated manufacturers capturing margin through captive distribution while pure-play converters rely on wholesaler networks.
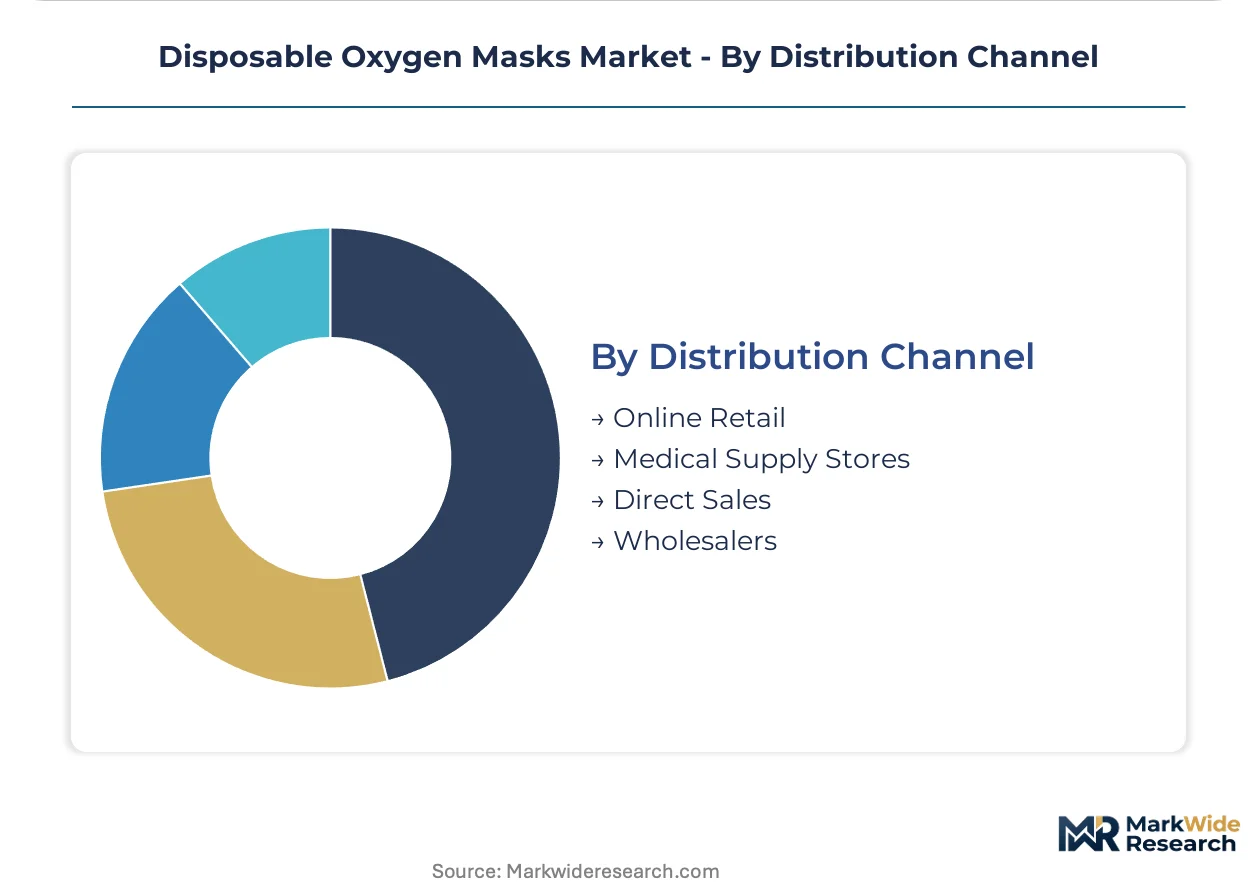
- Direct Sales:Manufacturer field forces serve hospital systems and integrated delivery networks with contract pricing and consignment inventory. Medline Industries leverages this channel across acute and post-acute segments.
- Wholesalers:Regional medical supply distributors aggregate fragmented clinic and long-term care demand, requiring middleware investments for group purchasing organization data exchange compliance.
- Medical Supply Stores:Retail pharmacy and durable medical equipment storefronts serve walk-in homecare patients with standard configurations.
- Online Retail:E-commerce platforms are expanding in India through PLI scheme-enabled domestic manufacturing and expanding health insurance coverage.
Direct sales anchor hospital procurement. Online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds German levels by roughly 15-20% for comparable mask configurations, reflecting Medicare reimbursement certainty versus EU procurement compression. This asymmetry shapes where manufacturers prioritize regulatory investment and capacity allocation.
United States
Post-acute care facilities and durable medical equipment distributors drive volume outside hospital channels. FDA 510(k) clearance requirements filter market access, with predicate device matching dominating product development timelines. Minneapolis and Chicago host concentrated distribution infrastructure serving Medicare-reimbursed homecare networks.
Germany
Statutory health insurance reimbursement sustains recurring replacement cycles for COPD patient populations. EU MDR clinical evaluation obligations extend post-market surveillance requirements for Class IIa respiratory interfaces. The Rhine-Ruhr industrial corridor anchors cleanroom manufacturing capacity for export-oriented suppliers.
India
PLI scheme incentives for medical devices and expanding health insurance coverage create white space for distributors outside hospital procurement. CDSCO medical device rules impose registration requirements that favor domestic manufacturing partnerships. Maharashtra and Gujarat industrial zones concentrate injection-molding capacity for regional supply.
Australia
Ambulance fleet standardization on non-rebreather mask configurations drives demand for TGA-registered reservoir designs. State-level procurement consolidation compresses supplier margins while favoring integrated distributors. Melbourne and Sydney anchor emergency medical service supply chains with direct manufacturer relationships.
Canada
Health Canada registration requirements align with FDA pathways, enabling cross-border supplier efficiency. Provincial health authority tender processes reward vendors with carbon footprint disclosure capabilities. Ontario's manufacturing base serves both domestic demand and US export channels.
Disposable Oxygen Masks Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated manufacturers with captive distribution capture premium positioning in hospital procurement networks, while contract converters serve price-sensitive channels through wholesaler relationships. Three archetypes dominate: diversified health conglomerates with GPO leverage, specialized respiratory device firms with anatomical modeling capabilities, and regional converters leveraging cleanroom outsourcing. M&A activity concentrates among distributors seeking vertical control over post-acute channels, while capacity expansion focuses on Mexico and Malaysia for US and EU market access.
Within the integrated distribution tier, Medline Industries exemplifies the archetype of acute-to-post-acute channel control. Among specialized device manufacturers, Flexicare Medical Limited occupies a position reflecting European regulatory specialization, while Dynarex Corporation represents private-label partnership strategies with group purchasing organizations.
| Leading Market Players |
|---|
| Medline Industries |
| Besmed Health Business Corp |
| Dynarex Corporation |
| Flexicare Medical Limited |
| Vyaire Medical |
| Intersurgical Ltd. |
| Allied Healthcare Products |
| Cardinal Health |
| Drive Medical |
| Others |
Supply Flow & Price Mechanics
FDA 510(k) clearance status gates both supplier qualification and hospital procurement pricing tiers simultaneously, compressing margin structures for converters without predicate device portfolios while rewarding integrated manufacturers with GPO contract premiums.
Pricing Analysis
Configured-to-order pediatric mask geometries with anatomical modeling capabilities command substantial premiums over standard adult configurations. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified cleanroom production from outsourced converter supply. Cost compression in standard adult masks intensifies as group purchasing organizations consolidate volumes around integrated distributors. Homecare durable medical equipment distributors exhibit highest price sensitivity, while pediatric critical care procurement committees prioritize fit-test certification over unit cost.
Supply Chain Analysis
Inventory buffers for medical-grade polypropylene resin stretch lead times when petrochemical feedstock allocation tightens. Manufacturing concentrates in the United States, Germany, and Malaysia, with cleanroom molding capacity anchored in the Rhine-Ruhr corridor and Penang industrial zones. Raw material supply draws from specialty PVC resin producers, elastic strap textile converters, and biopolymer compounders piloting polylactic acid blends. Single-source vulnerability runs through three petrochemical suppliers controlling nasal bridge component feedstock. Distribution runs through hospital group purchasing organizations, durable medical equipment networks, and direct manufacturer field forces serving integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 14644-compliant cleanroom technician scarcity constrains capacity expansion timelines, privileging manufacturers with established personnel retention programs and training pipelines over capital-rich entrants lacking operational expertise.
For Market Incumbents: Shield market position by deepening backward integration into medical-grade polymer compounding to offset petrochemical supplier pricing power, while accelerating pediatric mask portfolio expansion ahead of EU MDR clinical evaluation deadline compression. Prioritize captive recycling program certification to capture California and New York hospital sustainability procurement mandates. For New Entrants and Emerging Players: Post-acute care direct-to-patient fulfillment infrastructure represents the most penetrable white space, as hospital-centric incumbents under-serve durable medical equipment distributor networks. Target India homecare expansion through PLI scheme-enabled domestic manufacturing partnerships and health insurance reimbursement pathway navigation. For Investors and Strategic Acquirers: EU MDR post-market surveillance obligation expansion reshapes the acquisition landscape toward specialized respiratory device firms with established vigilance systems and pediatric predicate device portfolios. Monitor biodegradable polymer certification premiums as inflection indicator for material substitution timeline acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Predicate device matching shortens hospital GPO contract qualification timelines for novel mask geometries. |
| CE Marking Pathway Investment | MDR clinical evaluation depth differentiates suppliers in German statutory health insurance procurement. |
| Hospital System Partnership | Consignment inventory arrangements with integrated delivery networks lock out wholesaler-dependent competitors. |
| Biopolymer Certification Program | Polylactic acid blend validation captures European green procurement mandate premiums ahead of PVC phase-out. |
| Reimbursement Strategy Development | Medicare code alignment sustains recurring replacement cycle predictability for COPD patient populations. |
Methodological Framework
Desk research of FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and petrochemical trade flow data preceded structured interviews with biomedical engineers, GPO contracts managers, cleanroom operations directors, and durable medical equipment distributors. Primary fieldwork with clinicians and respiratory therapists validated product configuration demand patterns. Secondary sources included ISO certification registries, CMS Medicare reimbursement schedules, and customs import records. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Variance decomposition separated volume growth drivers from pricing dynamics across product type, material composition, end-user channel, and geographic regulatory cluster dimensions. CAGRs derived from segment-level trajectory analysis incorporating chronic respiratory disease prevalence projections, reimbursement pathway stability assessments, and material substitution timeline assumptions. Forecast inputs incorporated ambulance fleet electrification specifications and EU single-use plastics directive implementation schedules.
Underlying assumptions cover reimbursement continuity, regulatory implementation timelines, and polymer feedstock availability, with deviation risk concentrated in EU material substitution acceleration and FDA predicate device pathway modifications. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Americas Medical Rubber and Balloon Product Market
Medical Supplies
Medical Specialty Bags Market
Medical Supplies
Global Dried Blood Spot Collection Cards Market
Medical Supplies
Latin America Incontinence Pads Market
Medical Supplies
OTC Braces and Supports Market
Medical Supplies
Medical Tourniquets Market
Medical Supplies
Disposable Hospital Supplies Market
Medical Supplies
Lab Trays Market
Medical Supplies
Alcohol Prep Pads Market
Medical Supplies
Global Isothermal Boxes for Vaccines Market
Medical Supplies
Microtome Knife Sharpeners Market
Medical Supplies
GCC Medical Gloves Market
Medical Supplies
Casting and Splints Market
Medical Supplies
Surgical Gowns Market
Medical Supplies
Cell Freezing Media Market
Medical Supplies
Polymer Exam Gloves Market