
 Global Coil Wound Devices Market | 2026-2036
Global Coil Wound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Coil Wound Devices Market Analysis
Asian copper winding facilities are restructuring capacity to serve electric vehicle power electronics. TDK Corporation leverages advanced ferrite materials to dominate automotive-grade inductor supply. Siemens AG anchors European transformer production through captive coil manufacturing in Germany. ABB competes on industrial-scale magnetic assemblies for grid infrastructure across multiple continents.
Coil wound devices are electromagnetic components manufactured by winding conductive wire around a core material to create magnetic fields for energy transfer, filtering, or sensing; typical specifications include operating frequencies from kilohertz to megahertz and insulation classes rated to 200 degrees Celsius for high-reliability applications. Transformers command the largest revenue pool in power grid and EV charging infrastructure, while wireless charging coils represent the fastest-expanding segment driven by consumer electronics and automotive pad-based systems. Inductors for signal processing applications maintain mature, price-competitive dynamics in telecommunications equipment.
The EU Green Deal and F-Gas Regulation are mandating higher efficiency grades for power distribution transformers, directly tightening coil design specifications. China's GB standards and dual carbon goals impose parallel efficiency requirements on domestic and export-oriented manufacturers. Japan's METI enforces JIS standards that govern material purity and thermal performance in precision wound components. Stakeholders must monitor how efficiency tier migrations in Europe and Asia reshape procurement qualification criteria for core suppliers.
Market Dynamics
Electric vehicle power electronics are compressing design cycles for magnetic components, forcing coil manufacturers to synchronize R&D with automotive platform roadmaps rather than traditional industrial equipment timelines.
Growth Catalysts
- EU Green Deal efficiency mandates:F-Gas Regulation and transformer efficiency tiers are accelerating replacement demand across European distribution networks. Grid operators must upgrade legacy magnetic assemblies to meet 2025-2030 compliance windows.
- Copper winding automation:Robotic precision winding is reducing labor content in high-frequency inductor production. Asian contract manufacturers are deploying automated lines to serve EV power module suppliers.
- Wireless charging pad deployment:Automotive OEMs are specifying automotive-grade charging coils for luxury and mass-market EV platforms. Consumer electronics brands are integrating multi-device charging surfaces into furniture and infrastructure.
Market Restraints
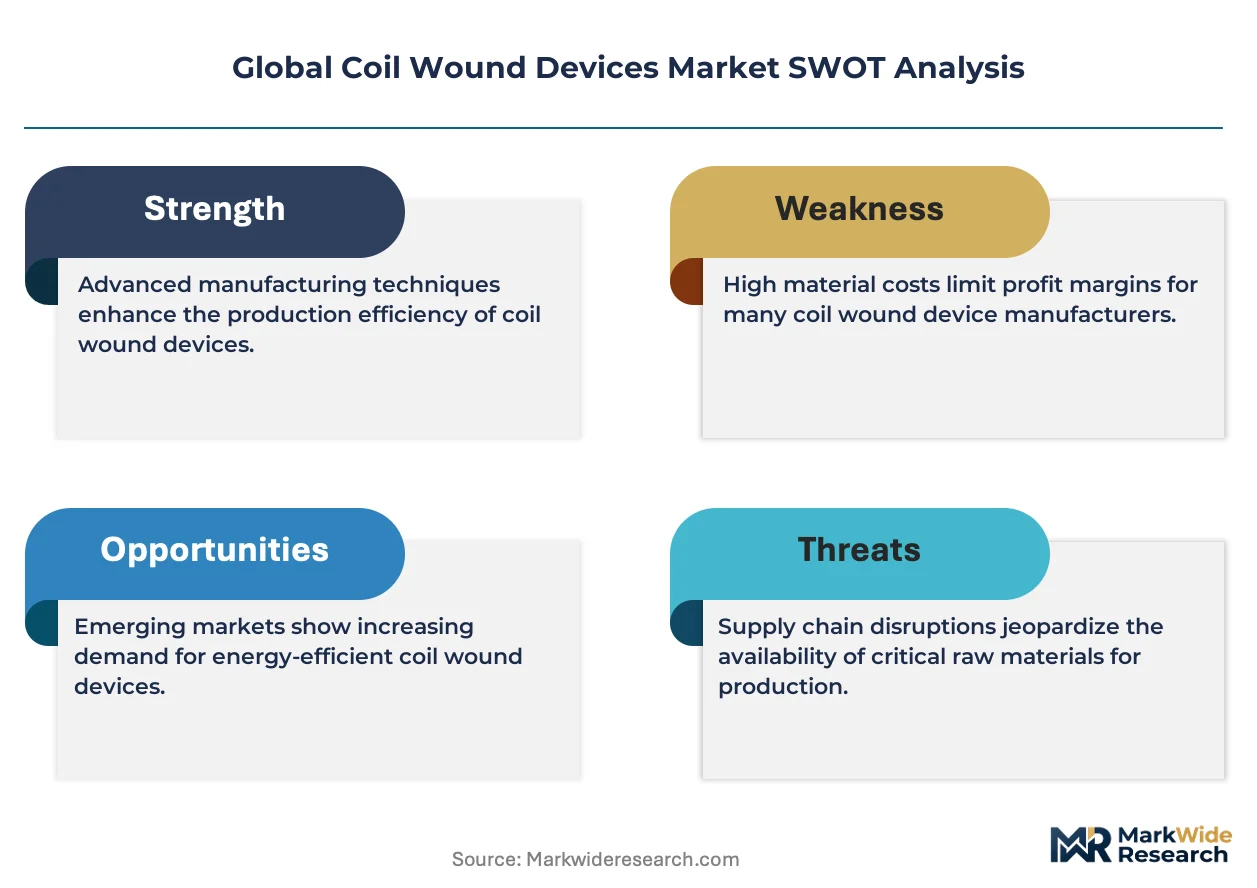
- Copper price volatility:LME copper fluctuations above historical baselines are compressing margin structures for commodity transformer producers. Smaller winding houses lack hedging capabilities to buffer input cost swings.
- Ferrite core supply concentration:Advanced manganese-zinc ferrite formulations depend on a concentrated supplier base in East Asia. Western coil manufacturers face extended lead times for high-permeability core materials.
- Silicon carbide displacement risk:Wide-bandgap semiconductors reduce passive component counts in power electronics. Some inverter designs now require fewer magnetic filtering stages than silicon IGBT alternatives.
Strategic Opportunities
- India EV component localization:PLI scheme incentives for automotive electronics are attracting coil manufacturers to establish domestic winding capacity. State-level industrial corridors in Tamil Nadu and Gujarat offer subsidized manufacturing zones.
- Medical imaging coil specialization:MRI gradient and RF coil assemblies command premium pricing and long-term supply contracts. Specialized winding techniques for superconducting applications create defensible technical moats.
- GaN-SiC convergence in chargers:Gallium nitride and silicon carbide power stages operate at frequencies demanding redesigned magnetic components. Coil suppliers mastering nanocrystalline core integration capture next-generation adapter and onboard charger sockets.
Industry Challenges
- Precision winding technician scarcity:Automated equipment still requires skilled operators for setup and quality verification. Vocational programs in Germany and Japan are failing to replenish retiring master winders.
- Automotive PPAP timeline compression:Production part approval process cycles for magnetic components have shortened from 18 months to 9 months. Suppliers must parallel-track tooling qualification with customer platform development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Coil Wound Devices Market |
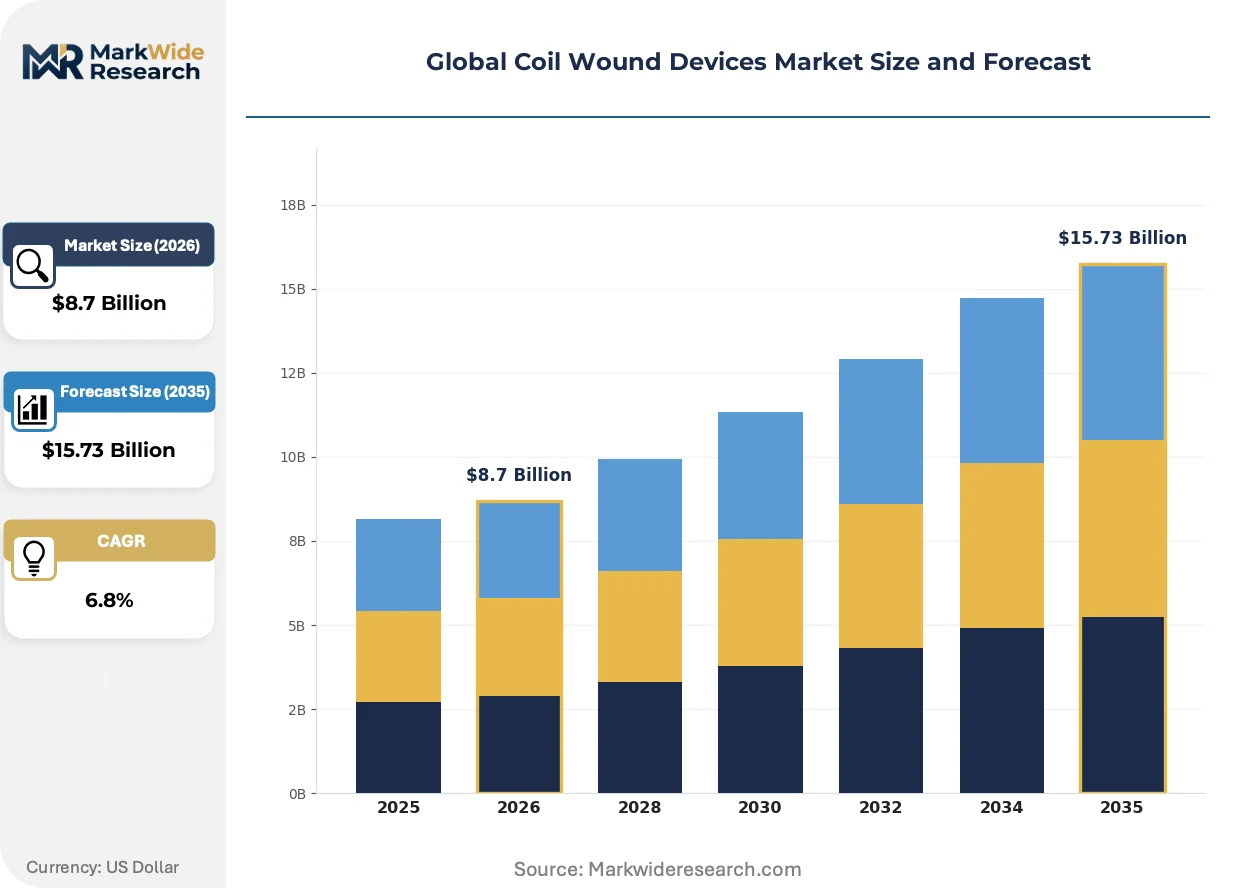
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transformers, Inductors, Chokes, Sensors End User: Telecommunications, Automotive, Industrial Automation, Consumer Electronics Technology: Magnetic Field, Electromechanical, Power Electronics, Wireless Charging Application: Power Supply, Signal Processing, Energy Storage, Electric Vehicles |
| Companies Covered | ABB, Siemens AG, Schneider Electric, Honeywell International, Parker Hannifin Corporation, Danaher Corporation, TDK Corporation, Murata Manufacturing, Emerson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Coil Wound Devices Market Emerging Trajectories
Material science advances and frequency regime shifts are restructuring competitive advantage in electromagnetic component supply. Manufacturers are racing to master core formulations and winding geometries that minimize losses at elevated switching frequencies.
Amorphous and nanocrystalline metal alloys are overtaking conventional ferrite in high-frequency power applications. Automotive onboard charger suppliers are specifying toroidal cores with these materials to achieve 98%+ efficiency at 100kHz+ switching frequencies. The technology is compressing market share for legacy ferrite suppliers in premium EV power electronics segments.
China's GB standards for transformer efficiency are tightening loss allowances for distribution equipment. Domestic manufacturers must redesign core laminations and winding configurations to meet 2025 tier requirements. Export-oriented Chinese suppliers are pre-certifying products to EU F-Gas and efficiency directives to maintain access to European utility procurement.
Automotive tier-one suppliers are consolidating magnetic component vendors and demanding systems-level warranty coverage. Single-source coil suppliers are ceding position to integrated power module houses that bundle magnetics with semiconductors. The pattern is most visible in Germany's industrial automation corridor and South Korea's consumer electronics manufacturing hubs.
Global Coil Wound Devices Market Segmentation
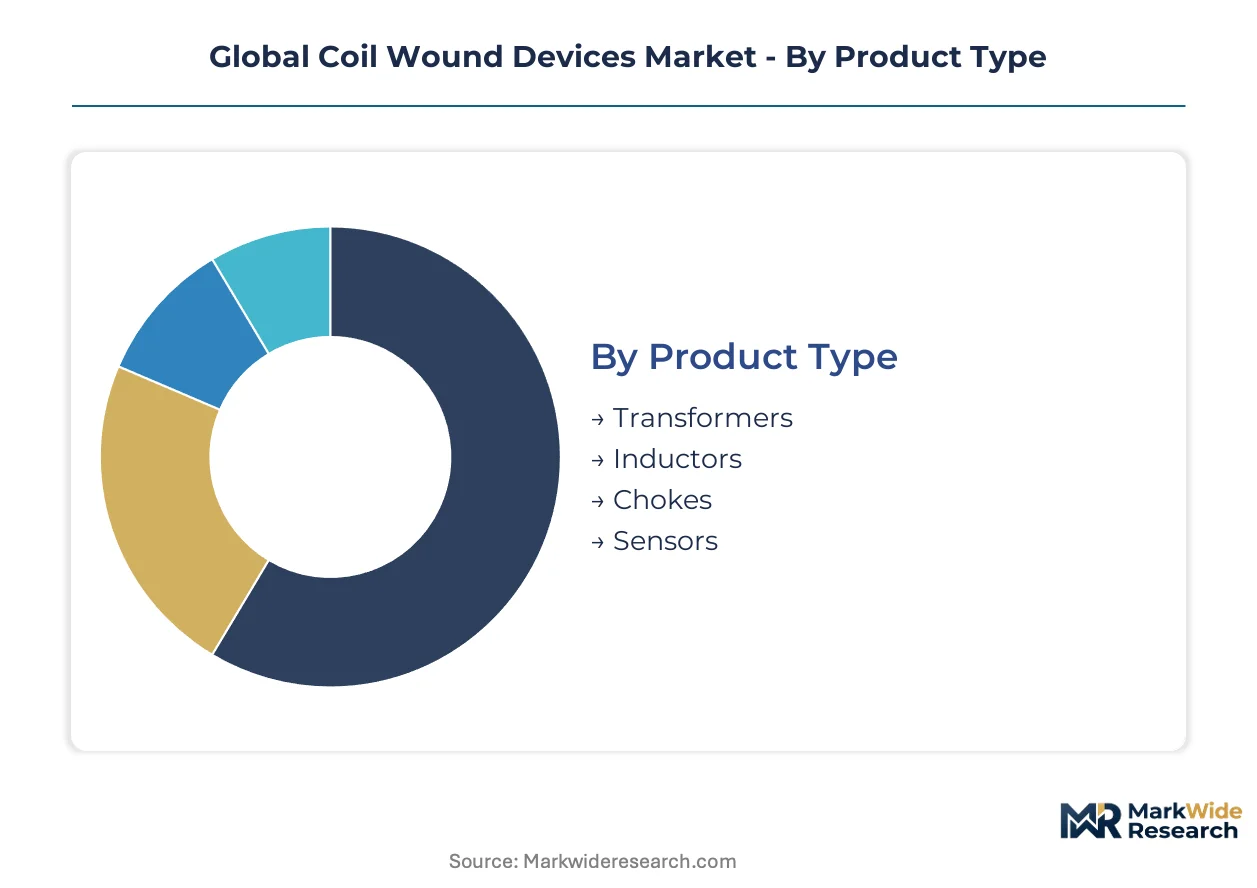
Coil wound devices serve fundamentally different electrical functions across voltage regimes and frequency domains. Segmentation reveals how transformer architectures diverge from high-frequency inductor specifications, and why automotive power electronics now command distinct material formulations from telecommunications filtering components.
Product Type:
Upgrade cycles vary dramatically across electromagnetic component categories, with grid infrastructure transformers operating on 25-40 year replacement horizons while consumer electronics inductors turn over every 3-5 years.
- Transformers:Laminated silicon steel or amorphous metal cores with interleaved windings enable voltage conversion across 50Hz-400Hz utility frequencies. EU F-Gas Regulation and China's GB efficiency tiers are forcing premature retirement of distribution transformers installed during 1990s infrastructure buildouts.
- Inductors:Ferrite or powdered iron cores with precision-wound copper wire manage energy storage and ripple filtering in switch-mode power supplies. South Korea's consumer electronics manufacturing hubs and Germany's industrial automation corridor concentrate procurement for surface-mount and through-hole formats.
- Chokes:Common-mode and differential-mode winding configurations suppress electromagnetic interference in power entry modules. Medical imaging equipment and aerospace avionics specify chokes with extended temperature ratings and MIL-STD qualification.
- Sensors:Variable reluctance and LVDT coil geometries transduce mechanical position or current flow into electrical signals. Automotive electric power steering and battery management systems integrate Hall-effect and shunt-based current sensors with custom winding profiles.
Transformers sit at the top of the volume ranking, with inductors climbing the fastest as GaN and SiC power stages proliferate in chargers and inverters.
End User:
Cost tier differentiation separates military-aerospace specifications from commodity consumer electronics, with automotive-grade components occupying a middle tier demanding PPAP qualification without full military traceability.
- Automotive:Onboard chargers, DC-DC converters, and traction inverters require AEC-Q200 qualified magnetics with -40°C to 150°C thermal envelopes. Electric vehicle manufacturers are compressing design cycles and consolidating supplier bases for magnetic assemblies.
- Industrial Automation:Servo drives, robotics power supplies, and motor controls specify robust inductors and transformers for 480V three-phase environments. Germany's Ruhr industrial corridor anchors European demand for heavy-duty magnetic components.
- Telecommunications:Base station power supplies and optical network equipment utilize compact planar magnetics and shielded inductors for high-density rack installations. 5G infrastructure deployment is sustaining demand for intermediate-frequency magnetics.
- Consumer Electronics:Smartphones, laptops, and wireless charging pads drive volumes for miniature multilayer inductors and thin-film power inductors. Asian contract manufacturers in Vietnam and Indonesia are absorbing winding capacity migration from China.
Automotive commands the steepest expansion trajectory, with telecommunications maintaining mature, replacement-driven procurement patterns.
Technology:
Application-specific magnetic architectures determine core material selection and winding geometry, with power electronics frequencies now reaching regimes where skin effect and proximity losses dominate design tradeoffs.
- Power Electronics:Buck, boost, and resonant converter topologies demand gapped ferrite cores and litz wire windings to minimize eddy current losses at 100kHz-1MHz switching frequencies. GaN and SiC semiconductors are pushing magnetic designs toward nanocrystalline and amorphous metal cores.
- Wireless Charging:Planar spiral coils with ferrite shielding plates enable inductive power transfer at 85kHz-300kHz for automotive pad systems and 100-300kHz for consumer electronics. Qi standard certification and automotive OEM validation create divergent qualification pathways.
- Magnetic Field:Permanent magnet synchronous machines and reluctance motors depend on distributed windings in stator slots for torque production. Industrial motor retrofit programs in China's manufacturing zones are sustaining demand for rewinding services.
- Electromechanical:Solenoids, relays, and contactors utilize concentrated windings on ferromagnetic plungers for linear or rotary actuation. Railway signaling and circuit breaker applications specify electromechanical coils with extended mechanical life ratings.
Power electronics occupies the dominant volume position, with wireless charging gaining share fastest as automotive pad-based systems achieve mass-market penetration.
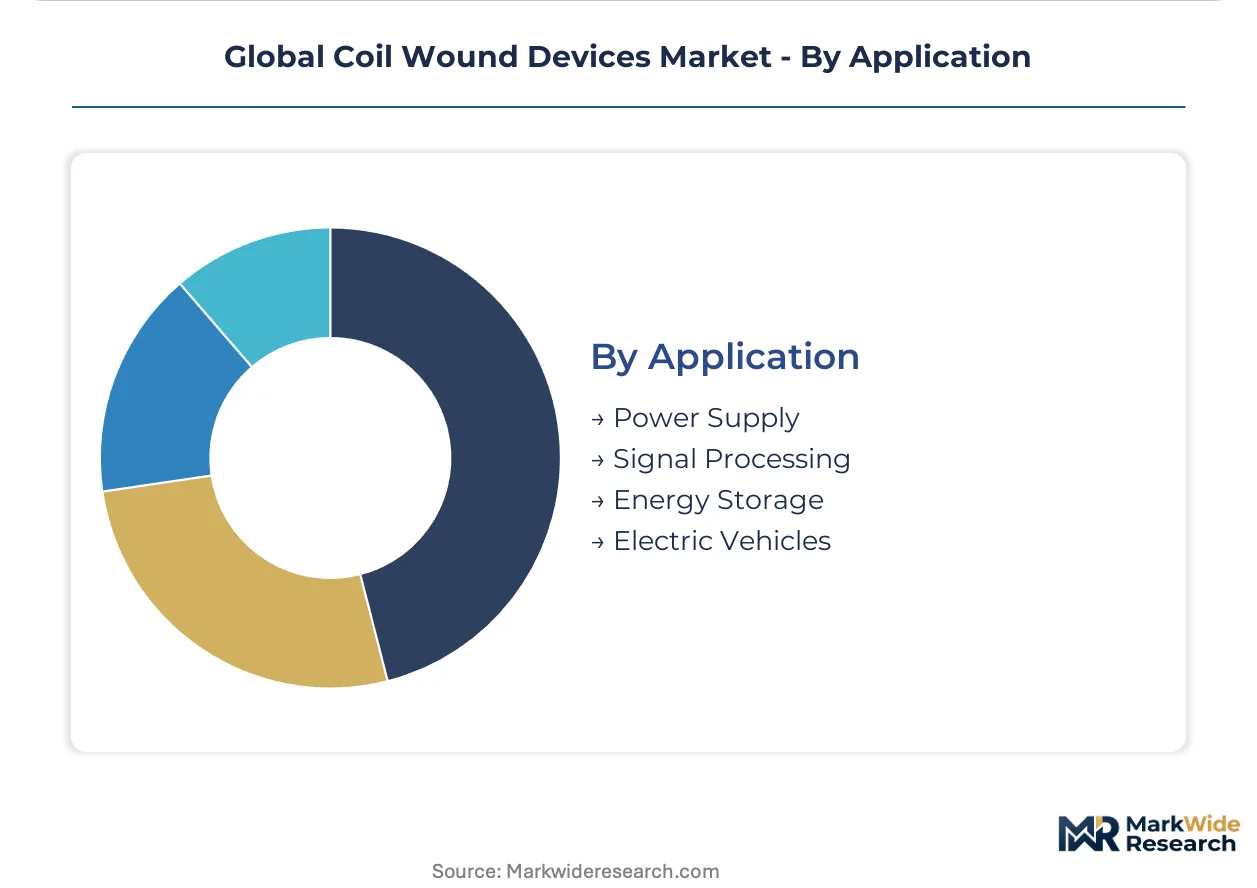
Application:
Customer type fragmentation separates utility procurement departments from automotive tier-one power module suppliers, with divergent qualification timelines and warranty structures reshaping vendor relationships.
- Electric Vehicles:Onboard chargers, traction inverters, and DC-DC converters require magnetics optimized for 400V-800V battery architectures and 10-20kW power levels. China's dual carbon goals and the EU Green Deal are tightening efficiency mandates for EV power electronics.
- Power Supply:AC-DC adapters, server power supplies, and telecom rectifiers specify universal input magnetics with active power factor correction stages. 80 PLUS efficiency certification tiers differentiate commodity from premium supply designs.
- Signal Processing:RF inductors, baluns, and impedance matching networks manage high-frequency signals in communications equipment. Japan's METI enforces JIS standards governing material purity and Q-factor consistency for precision wound RF components.
- Energy Storage:Grid-scale battery inverters and residential solar-plus-storage systems require isolation transformers and filtering inductors for bidirectional power flow. California's Title 24 building codes and Germany's EEG framework are stimulating storage inverter installations.
Power supply applications lead by installed volume, with electric vehicles expanding most quickly as platform electrification accelerates across OEM lineups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing coil winding capacity toward jurisdictions with subsidized energy costs and streamlined environmental compliance, while efficiency mandates in mature markets accelerate replacement cycles for legacy magnetic assemblies.
China
Domestic EV manufacturers are scaling procurement of high-frequency magnetics for 800V traction architectures. GB standards for transformer efficiency are tightening loss allowances through 2025. Yangtze River Delta winding facilities are retooling for automotive-grade inductor output.
Germany
Ruhr industrial corridor demand centers on heavy-duty magnetics for servo drives and robotics power supplies. EU F-Gas Regulation mandates premature retirement of distribution transformers installed during 1990s infrastructure buildouts. Bavaria hosts captive coil manufacturing for integrated power module suppliers.
United States
Grid operators are upgrading legacy magnetic assemblies to meet state-level renewable interconnection standards. FERC Order 2222 is accelerating distributed energy resource aggregation requiring bidirectional power magnetics. Texas industrial zones concentrate winding capacity for oilfield automation and energy storage inverters.
Japan
Precision wound RF components for telecommunications equipment sustain mature procurement patterns. METI enforces JIS standards governing material purity and thermal performance in high-reliability applications. Nagoya-Chubu manufacturing belt specializes in automotive sensor coils with extended temperature ratings.
South Korea
Consumer electronics brands are integrating multi-device wireless charging surfaces into infrastructure and furniture. Domestic battery manufacturers are localizing magnetic component supply for ESS power conditioning systems. Seoul Capital Area contract manufacturers absorb winding capacity migration from higher-cost Northeast Asian hubs.
Global Coil Wound Devices Market Vendor Landscape
East Asian producers anchor the high-volume tier; European specialists hold premium-positioning through integrated power module relationships. Market structure tilts toward consolidation as automotive tier-one suppliers reduce vendor counts and demand systems-level warranty coverage. Three archetypes dominate: diversified industrial conglomerates with captive magnetics divisions, pure-play electromagnetic component specialists, and contract winding houses serving consumer electronics brands. Capacity expansion and strategic partnerships represent the dominant competitive vectors as firms synchronize R&D with compressed automotive platform timelines.
Among diversified industrial conglomerates, ABB and Siemens AG exemplify the integrated power module house archetype, bundling magnetic assemblies with semiconductor and control systems. TDK Corporation occupies a specialist position within the premium-tier ferrite and inductor segment. These three entities represent contrasting strategic postures: conglomerate breadth, European industrial automation anchoring, and Japanese materials-science specialization.
| Leading Market Players |
|---|
| ABB |
| Siemens AG |
| Schneider Electric |
| Honeywell International |
| Parker Hannifin Corporation |
| Danaher Corporation |
| TDK Corporation |
| Murata Manufacturing |
| Emerson |
| Others |
Supply Flow & Price Mechanics
Robotic precision winding adoption across Asian contract manufacturers is compressing labor costs while concentrating production in subsidized industrial zones. This automation wave simultaneously lowers unit economics and locks in geographic supply advantages for early deployers.
Pricing Analysis
Distributor margins of 15-25% separate standard-grade inductors from automotive AEC-Q200 qualified components. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume commitment, with EV power module suppliers showing lowest price sensitivity due to warranty consolidation mandates. Cost compression in commodity transformers is intensifying because copper price volatility above historical baselines erodes hedging-deficient winding houses.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Seoul, and Munich coordinate hub-and-spoke patterns for ferrite cores and precision-wound assemblies. Manufacturing concentrates in China, Vietnam, and Germany, with advanced manganese-zinc ferrite formulations drawing from a concentrated East Asian supplier base. Single-source vulnerability for high-permeability core materials exposes Western coil manufacturers to extended lead times. Distribution runs through automotive tier-one power module houses and industrial equipment OEMs with captive procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as electrification infrastructure mandates across automotive and grid sectors sustain replacement and expansion cycles regardless of macro volatility.
For Market Incumbents: Anchor defensive positioning through backward integration into ferrite core production and captive winding capacity in Germany's industrial corridor. Silicon carbide displacement risk in inverter designs demands R&D synchronization with wide-bandgap semiconductor roadmaps. Certification investment in EU F-Gas and China GB efficiency tiers preserves procurement qualification access. For New Entrants and Emerging Players: India's PLI scheme for automotive electronics opens a window for domestic winding capacity establishment in Tamil Nadu and Gujarat industrial corridors. Medical imaging coil specialization offers premium pricing with long-term supply contract structures. Target ESS power conditioning systems for South Korean battery manufacturers as the most penetrable segment with localization mandates. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play electromagnetic component specialists lacking integrated power module relationships. The 5-10 year viability window favors acquisition of nanocrystalline core competency firms serving GaN-SiC charger architectures. Watch automotive PPAP timeline compression as the signal for vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrite Core Production | TDK Corporation's advanced materials science anchors premium-tier supply security against East Asian concentration. |
| Automotive AEC-Q200 Certification Investment | EU Green Deal efficiency mandates tighten qualification criteria for traction inverter and onboard charger sockets. |
| Robotic Precision Winding Deployment | Asian contract manufacturers automate lines to serve compressed EV power module design cycles. |
| Nanocrystalline Core R&D Partnership | GaN-SiC convergence in chargers demands redesigned magnetic components for 100kHz+ switching frequencies. |
| India Manufacturing Footprint Establishment | PLI scheme incentives attract coil manufacturers to state-level industrial corridors for EV component localization. |
Methodological Framework
Direct dialogue with automotive tier-one procurement officers, industrial automation plant engineers, magnetic component R&D directors, and power electronics platform engineers grounded qualitative findings. Secondary validation drew from SEC 10-K filings of diversified industrial conglomerates, customs trade data for copper winding imports, FERC grid interconnection filings, and EU F-Gas regulatory impact assessments. Bottom-up and top-down triangulation reconciled segment-level unit economics with aggregate market sizing.
Market value and volume estimates across the analysis window reflect segmented modeling by product type, end-user industry, core material technology, and geographic production cluster. CAGRs derive from regression analysis of historical procurement patterns against electrification infrastructure deployment curves. Forecast inputs include EV platform electrification roadmaps, transformer replacement cycles tied to EU F-Gas compliance windows, and wireless charging pad adoption rates in automotive and consumer electronics.
Revisions become necessary when copper price volatility exceeds modeled baselines, when wide-bandgap semiconductor adoption accelerates beyond projected timelines, or when efficiency tier migrations in Europe and Asia reshape procurement qualification criteria. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Implantable Infusion Pumps Market
Cardiovascular Devices
Global Coronary Stent Market
Cardiovascular Devices
Balloon Catheters Market
Cardiovascular Devices
Pressure Infusion Bags Market
Cardiovascular Devices
Epinephrine Auto-Injectors Market
Cardiovascular Devices
Global PTA Balloon Catheter Market
Cardiovascular Devices
Disposable Blood Pressure Cuffs Market
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Global Cardiac Arrest Treatment Market
Cardiovascular Devices
Cardiovascular Devices Market
Cardiovascular Devices
Brazil Cardiovascular Devices Market
Cardiovascular Devices
Neurovascular Stent Retrievers Market
Cardiovascular Devices
Cardiac Implantable Electronic Device Market
Cardiovascular Devices
Drug Eluting Balloon Market
Cardiovascular Devices
Peripherally Inserted Central Catheters Market
Cardiovascular Devices
Cardiac Assist Devices Market