
 Patient-Controlled Injectors Market | 2026-2036
Patient-Controlled Injectors Market Size, Share, and Industry Trends Forecast 2026-2036
Patient-Controlled Injectors Market Analytics
Connected sensor integration with Bluetooth-enabled dose tracking is reshaping how patient-controlled injectors are engineered and prescribed. West Pharmaceutical Services leverages its elastomer and containment expertise to anchor high-value partnerships with biologics developers. Gerresheimer AG sustains leadership in glass and polymer primary packaging for prefilled injector cartridges. Ypsomed AG specializes in pen and autoinjector platforms that compete directly for diabetes and multiple sclerosis therapy contracts.
Patient-controlled injectors are drug delivery devices that enable self-administration of parenteral therapies through pre-programmed or user-activated mechanisms, typically incorporating springs, compressed gas, or electromechanical drives to achieve subcutaneous or intramuscular deposition at specified depths and force profiles. Electronic injectors command premium positioning due to integrated feedback systems and dose verification, while mechanical variants retain volume leadership in cost-sensitive therapeutic categories. Subcutaneous delivery dominates the delivery mode landscape because most biologics approved for self-administration target this tissue layer, though intravenous-enabled ambulatory pump systems are gaining traction in oncology protocols.
The FDA regulates patient-controlled injectors as combination products, requiring sponsors to navigate both Center for Drug Evaluation and Research and Center for Devices and Radiological Health review pathways, which elongates development timelines but raises barriers to commoditized competition. The EU MDR and ISO 11608 series impose sterility, needlestick prevention, and usability validation standards that manufacturers must satisfy for CE marking and global market access. Stakeholders must monitor evolving pharmacovigilance requirements for connected devices and decide whether to build digital infrastructure in-house or contract with specialized health data platforms.
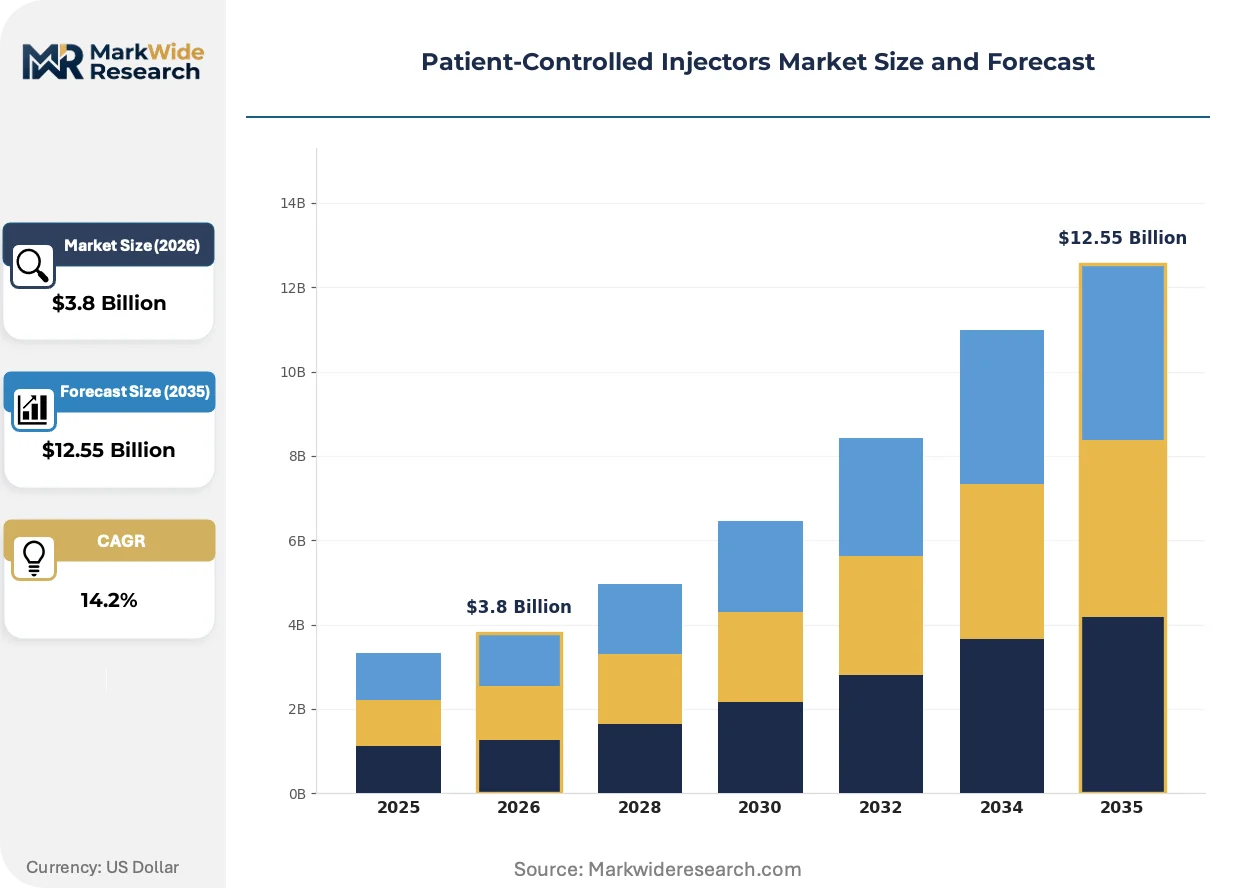
Market Dynamics
Bluetooth-enabled dose tracking is virtualizing compliance documentation, forcing manufacturers to rebuild device architectures around real-time data capture rather than mechanical reliability alone.
Growth Catalysts
- EU MDR classification rules:Stricter device categorization for combination products accelerates investment in design controls and clinical validation capabilities among European manufacturers.
- Home-based biologic administration:Reimbursement alignment in Germany and Japan shifts infusion center volumes toward self-administration protocols for multiple sclerosis and rheumatoid arthritis therapies.
- Spring-based mechanical platforms:Cost-sensitive therapeutic categories in emerging markets sustain demand for simplified injector architectures without electronic components.
Market Restraints
- Elastomer supply concentration:Specialized halobutyl rubber for cartridge seals concentrates among a limited supplier base, creating input cost volatility for cartridge manufacturers.
- FDA dual-center review:Sponsors navigate simultaneous Center for Drug Evaluation and Research and Center for Devices and Radiological Health pathways, elongating development timelines by 12-18 months.
- Prefilled syringe substitution:Lower-cost manual injection formats retain preference in price-sensitive oncology supportive care settings.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives attract contract development partners seeking cost-competitive production for export markets.
- Connected device pharmacovigilance mandates:Evolving FDA guidance on digital health data creates first-mover advantage for platforms with integrated adverse event reporting infrastructure.
- Intramuscular delivery expansion:Long-acting antipsychotic and hormonal therapies drive platform adaptation beyond subcutaneous defaults.
Industry Challenges
- Human factors engineering talent scarcity:Usability validation for ISO 11608 compliance requires specialized industrial design capabilities that outpace current workforce supply.
- Legacy health data platform integration:Hospital and pharmacy systems demand seamless electronic health record connectivity, complicating go-to-market for standalone device architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient-Controlled Injectors Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Injectors, Electronic Injectors, Disposable Injectors, Reusable Injectors Technology: Microchip Technology, Pump Technology, Sensor Technology, Needle-Free Technology Delivery Mode: Subcutaneous Delivery, Intravenous Delivery, Intramuscular Delivery, Intraosseous Delivery End User: Hospitals, Home Care Settings, Outpatient Clinics, Specialty Pharmacies |
| Companies Covered | West Pharmaceutical Services Inc., Gerresheimer AG, F. Hoffmann-La Roche Ltd., Johnson and Johnson Services Inc., Ypsomed AG, Becton Dickinson and Company, scPharmaceuticals Inc., United Therapeutics Corporation, Enable Injections, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient-Controlled Injectors Market Evolving Landscape
Device architectures are converging around sensor integration and data monetization, transforming injectors from disposable commodities into recurring revenue platforms.
Near-field communication and Bluetooth Low Energy modules are virtualizing adherence monitoring for payers and providers. Rheumatology and endocrinology practices in the United States deploy these capabilities to reduce nursing overhead for injection training. The technology is virtualizing traditional face-to-face patient support programs into automated digital interventions.
The FDA's evolving guidance on combination product digital health components compresses premarket notification requirements for well-characterized connectivity features. Sponsors now submit streamlined 510(k) pathways for dose-capture functionality that previously required de novo classification. Oncology therapy developers face the steepest adaptation curve as they retrofit legacy platforms with compliant data architectures.
Hospital procurement committees now unbundle device selection from drug contracting, forcing manufacturers to demonstrate standalone value. Specialty pharmacy distributors in Germany and Japan build direct-to-patient logistics networks that bypass traditional wholesale channels. Rheumatology practices show the most pronounced preference shift toward platforms with integrated reimbursement support services.
Patient-Controlled Injectors Market Segmentation
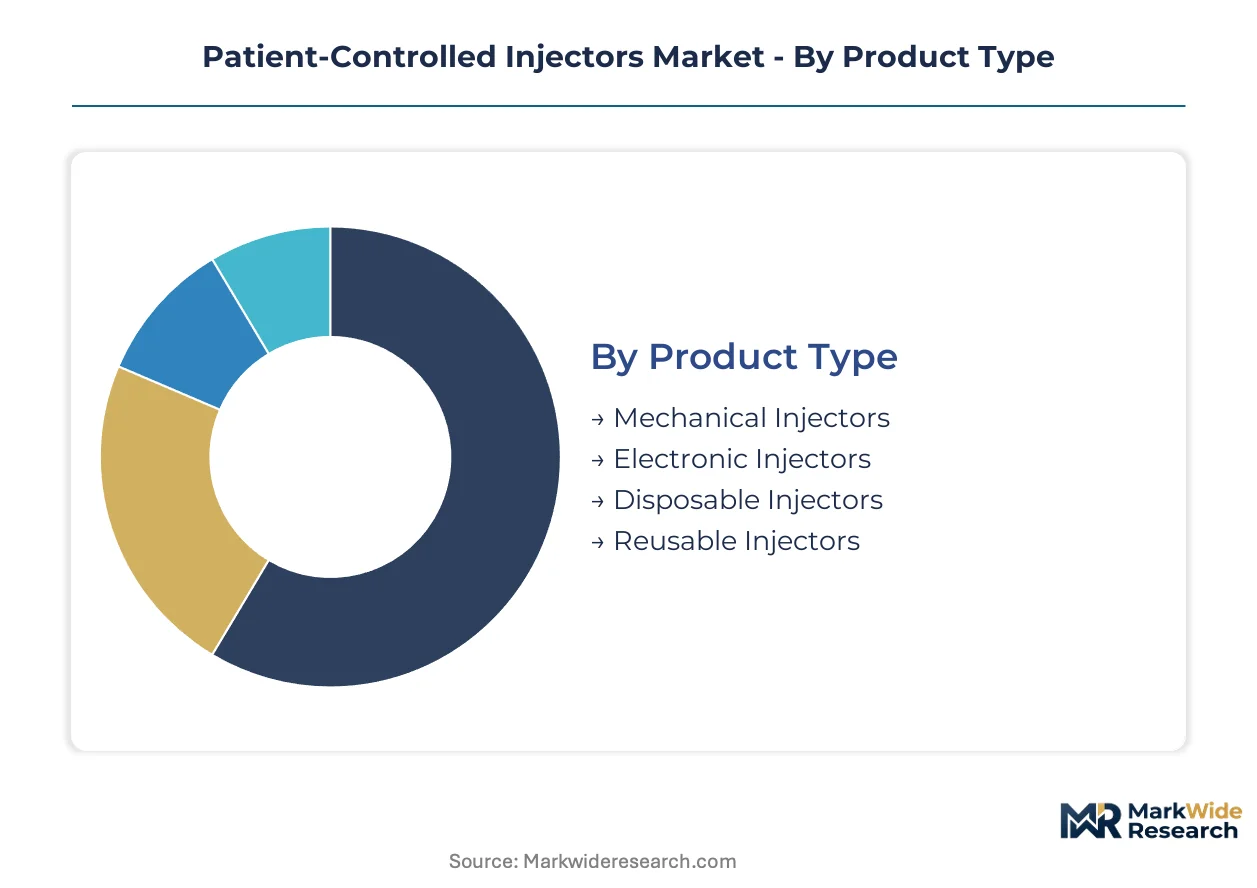
Segmentation in patient-controlled injectors reveals how device architecture, delivery mechanism, and care setting interact to determine procurement priorities. Each dimension carries distinct regulatory pathways and reimbursement implications that shape manufacturer R&D allocation.
Product Type:
Device selection spans a cost-performance spectrum from basic spring-driven units to connected electronic platforms with real-time dose verification.
- Mechanical Injectors:Spring or compressed-gas mechanisms deliver preset doses without electronic components. Demand concentrates in emerging markets and cost-sensitive oncology supportive care where reimbursement rates compress device budgets.
- Electronic Injectors:Electromechanical drives with integrated sensors enable programmable dosing, feedback systems, and Bluetooth connectivity. Rheumatology practices in the United States and Germany prioritize these platforms for biologic therapies requiring adherence documentation.
- Disposable Injectors:Single-use devices eliminate sterilization logistics and cross-contamination risk. Prefilled formats dominate insulin and multiple sclerosis therapy contracts where patient convenience drives formulary placement.
- Reusable Injectors:Cartridge-based systems with replaceable drug reservoirs reduce per-dose material cost. Long-acting antipsychotic and hormonal therapy protocols favor these for extended treatment courses.
The dominant share belongs to mechanical injectors, while electronic injectors are gaining share fastest as connected-device pharmacovigilance mandates expand.
Technology:
Core technology choices determine regulatory classification, development timeline, and partnership requirements with drug developers.
- Microchip Technology:Embedded processors control dose accuracy, timing, and user authentication. FDA combination product review pathways elongate development for these architectures, creating barriers to commoditized competition.
- Pump Technology:Continuous or bolus delivery mechanisms adapted from infusion devices serve ambulatory oncology protocols. Japan's aging population and home-care reimbursement alignment sustain demand for portable pump systems.
- Sensor Technology:Force, temperature, and position sensors enable injection depth verification and adherence capture. Germany's specialty pharmacy distributors build direct-to-patient logistics around these capabilities.
- Needle-Free Technology:Jet injection systems using high-pressure gas or spring mechanisms penetrate skin without metal needles. Pediatric and needle-phobic patient populations drive niche adoption despite higher unit costs.
Sensor technology commands premium positioning, while microchip platforms are expanding most quickly as dose-verification requirements harden.
Delivery Mode:
Tissue targeting determines force profiles, needle specifications, and training requirements across therapeutic categories.
- Subcutaneous Delivery:Deposition into adipose tissue at 4-10mm depth accommodates most biologics approved for self-administration. Diabetes and multiple sclerosis therapies default to this mode, concentrating manufacturing expertise and patient education infrastructure.
- Intravenous Delivery:Vascular access requires pump-based systems with flow rate control and occlusion detection. Ambulatory oncology protocols in the United States are retrofitting infusion center volumes with portable IV-enabled devices.
- Intramuscular Delivery:Deeper penetration into muscle tissue serves long-acting antipsychotics, hormonal therapies, and certain vaccines. Platform adaptation beyond subcutaneous defaults is accelerating as depot formulations expand.
- Intraosseous Delivery:Bone marrow access for emergency or critical care scenarios where vascular collapse prevents peripheral IV placement. Military and emergency medicine applications sustain minimal commercial volume.
Subcutaneous delivery retains the dominant share, though intramuscular platforms are climbing the fastest as long-acting formulations proliferate.
End User:
Procurement authority and reimbursement mechanics diverge sharply across institutional and community settings.
- Hospitals:Acute care facilities prioritize device standardization, electronic health record integration, and needlestick prevention. Procurement committees now unbundle device selection from drug contracting, forcing standalone value demonstration.
- Home Care Settings:Self-administration protocols for biologics require patient-friendly interfaces and remote monitoring capabilities. Germany and Japan's reimbursement alignment for home-based administration is shifting volumes from infusion centers.
- Outpatient Clinics:Rheumatology and endocrinology practices deploy connected injectors to reduce nursing overhead for injection training. Near-field communication and Bluetooth Low Energy modules virtualize traditional face-to-face support programs.
- Specialty Pharmacies:Direct-to-patient distribution networks bypass traditional wholesale channels in Germany and Japan. These intermediaries demand platforms with integrated reimbursement support services and adherence documentation.
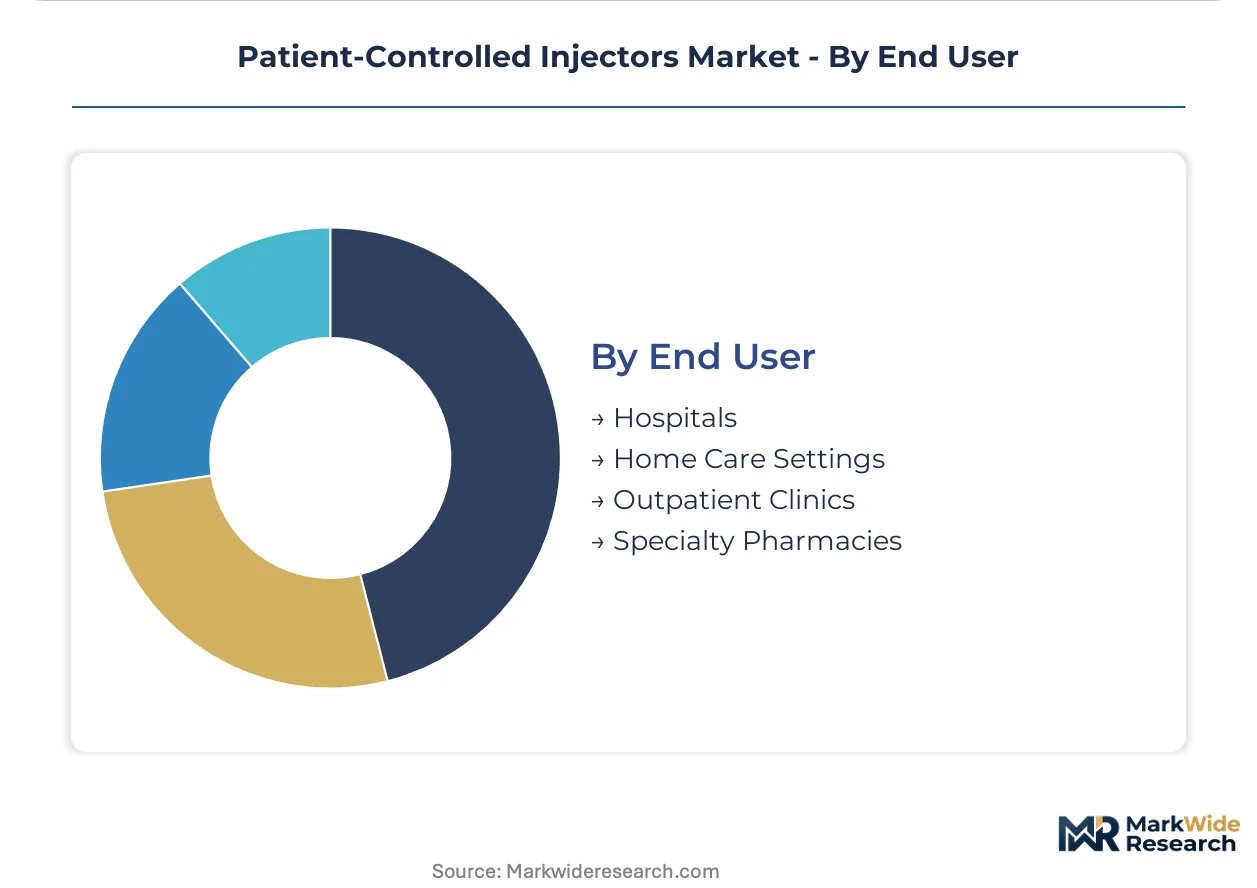
Home care settings anchor volume demand, while specialty pharmacies are expanding most quickly as distribution channels consolidate around patient-centric logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty pharmacy distributors and hospital procurement committees concentrate purchasing power in aging societies with strong home-care reimbursement frameworks. Device manufacturers prioritize regulatory alignment in markets where combination product pathways are most clearly articulated.
United States
Rheumatology and endocrinology practices drive connected injector procurement for biologic adherence monitoring. FDA dual-center review pathways for combination products elongate development timelines but raise competitive barriers. Greater Boston and San Diego biotech clusters anchor partnership activity between device developers and therapy sponsors.
Germany
Home-based administration protocols for multiple sclerosis and rheumatoid arthritis therapies shift volumes from infusion centers. EU MDR classification rules for combination products accelerate investment in design controls among domestic manufacturers. Baden-Württemberg's industrial base concentrates precision engineering capabilities for mechanical injector platforms.
Japan
Aging demographics and reimbursement alignment for self-administered biologics sustain demand for portable pump systems. PMDA consultation procedures for combination products provide regulatory predictability for sponsors. Tokyo-Osaka corridor hosts the dominant concentration of specialty pharmacy distribution networks.
Switzerland
Pharmaceutical headquarters operations create captive demand for high-reliability containment and delivery systems. Swissmedic maintains alignment with EU MDR standards while offering streamlined review for well-characterized device architectures. Basel-Zurich corridor concentrates contract manufacturing partnerships for prefilled injector cartridges.
India
Domestic manufacturing incentives under the PLI scheme attract contract development partners seeking cost-competitive production. CDSCO's evolving framework for combination products creates pathway uncertainty that favors established multinational sponsors. Maharashtra and Gujarat industrial corridors concentrate sterile manufacturing infrastructure for export markets.
Patient-Controlled Injectors Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement committees, specialty pharmacy networks, and direct-to-patient logistics platforms. Market structure tilts toward consolidated supply relationships in premium electronic segments while mechanical platforms sustain fragmented vendor pools. Two archetypes dominate: elastomer and containment specialists anchoring high-value biologics partnerships, and platform developers competing for diabetes and multiple sclerosis therapy contracts. Capacity expansion in South Asian contract manufacturing and strategic partnerships for connected device data infrastructure represent the dominant competitive moves.
Among Swiss and German fabricators, West Pharmaceutical Services Inc., Gerresheimer AG, and Ypsomed AG exemplify the tier of players leveraging geographic proximity to pharmaceutical development clusters. These entities occupy positions shaped by elastomer expertise, glass and polymer primary packaging capabilities, and pen and autoinjector platform specialization respectively. Their market presence reflects anchoring strategies built around containment integrity, cartridge manufacturing scale, and direct competition for chronic disease therapy contracts.
| Leading Market Players |
|---|
| West Pharmaceutical Services Inc. |
| Gerresheimer AG |
| F. Hoffmann-La Roche Ltd. |
| Johnson and Johnson Services Inc. |
| Ypsomed AG |
| Becton Dickinson and Company |
| scPharmaceuticals Inc. |
| United Therapeutics Corporation |
| Enable Injections |
| Others |
Value Network & Pricing Analysis
Baden-Württemberg's precision engineering cluster anchors European mechanical injector production, and its capacity utilization rates directly transmit into pricing leverage for cartridge-based systems sold into German home-care reimbursement channels.
Pricing Analysis
Cost-plus contracts with halobutyl rubber indexation dominate procurement between cartridge manufacturers and elastomer suppliers. Three-tier pricing structure across premium, standard, and economy levels separates Bluetooth-enabled electronic platforms from spring-driven mechanical units and basic disposable formats. Pricing pressure stems from prefilled syringe substitution in oncology supportive care, where manual injection formats undercut device premiums. Emerging market buyers exhibit the highest price sensitivity, while United States rheumatology practices prioritize adherence documentation over per-unit cost.
Supply Chain Analysis
Upstream feedstock for specialized elastomers concentrates among German, Japanese, and United States chemical processors. Device assembly draws from Swiss precision molding, Chinese polymer component fabrication, and Malaysian sterile finishing facilities. Single-source vulnerability around halobutyl rubber seals creates input cost volatility when petrochemical feedstock prices fluctuate. Distribution runs through specialty pharmacy networks in Germany and Japan that bypass traditional wholesale channels for direct-to-patient delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bluetooth-enabled dose tracking is reshaping patient-controlled injectors into recurring revenue platforms, and FDA guidance streamlining 510(k) pathways for connectivity features accelerates this inflection.
For Market Incumbents: Entrench elastomer supply relationships through captive sourcing agreements with German and Japanese chemical processors to defend against input cost volatility. Deepen ISO 11608 usability validation capabilities to maintain regulatory moats against commoditized mechanical competitors. Prioritize backward integration into sensor module assembly to capture value from connected-device pharmacovigilance mandates. For New Entrants and Emerging Players: Pursue India's PLI scheme for medical devices to establish cost-competitive sterile manufacturing for export markets. Target mechanical injector contracts in emerging market oncology supportive care where price sensitivity excludes electronic platforms. Lead with cartridge-based reusable formats for long-acting antipsychotic therapies to bypass established diabetes and multiple sclerosis incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because device architectures are converging around data monetization rather than mechanical reliability alone. Acquisition candidates with integrated health data infrastructure command premium positioning as FDA pharmacovigilance guidance hardens. Monitor PMDA consultation timeline compression for combination products as the signal indicating Japanese market access predictability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR classification rules accelerate design control investments for combination product sponsors. |
| Hospital System Partnership | Procurement committee unbundling forces standalone device value demonstration outside drug contracting. |
| Software Companion Development | Bluetooth Low Energy modules virtualize face-to-face patient support into automated digital interventions. |
| Reimbursement Strategy | Germany and Japan's home-based administration alignment shifts volumes from infusion centers. |
| Backward Integration | Captive halobutyl rubber supply defends against elastomer concentration among limited chemical processors. |
Research Methodology
A spread of perspectives from regulatory affairs leads at combination product sponsors, biomedical engineers at device manufacturers, hospital procurement committee members, and specialty pharmacy distribution heads converged on the working assumptions. Primary interviews combined with secondary validation against FDA 510(k) filings, EMA combination product guidance documents, ISO 11608 standards documentation, and GPO contract databases. Bottom-up segment sizing triangulated against top-down market reconstruction.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, delivery mechanism, core technology, and care setting. CAGRs derived from patient population growth, therapy approval timelines, and reimbursement policy trajectories. Forecast inputs incorporated EU MDR implementation pace and FDA digital health guidance evolution.
Sensitivities concentrate around FDA dual-center review timeline variability and elastomer supply disruption scenarios. Cross-checking against CMS Medicare biologic administration reimbursement data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Self-Expanding Stents Market
Cardiovascular Devices
Blood Fluid Warming System Market
Cardiovascular Devices
Fibromuscular Dysplasia Treatment Market
Cardiovascular Devices
Italy Cardiovascular Devices Market
Cardiovascular Devices
Asia Pacific Interventional Cardiology Market
Cardiovascular Devices
Europe Vascular Access Device Market
Cardiovascular Devices
Drug Eluting Stent (DES) Market
Cardiovascular Devices
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market
Cardiovascular Devices
Artificial Blood Vessels Market
Cardiovascular Devices
Brazil Cardiovascular Devices Market
Cardiovascular Devices
Cardiac Mapping Systems Market
Cardiovascular Devices
Intravascular Stents Market
Cardiovascular Devices
Ventricular Drainage Sets Market
Cardiovascular Devices
Percutaneous Coronary Intervention Market
Cardiovascular Devices
Global Atrial Fibrillation Surgery Market
Cardiovascular Devices
Saphenous Vein Grafts Market