
 Peptide Drug Conjugates Market | 2026-2036
Peptide Drug Conjugates Market Size, Share, and Industry Trends Forecast 2026-2036
Peptide Drug Conjugates Market Intelligence
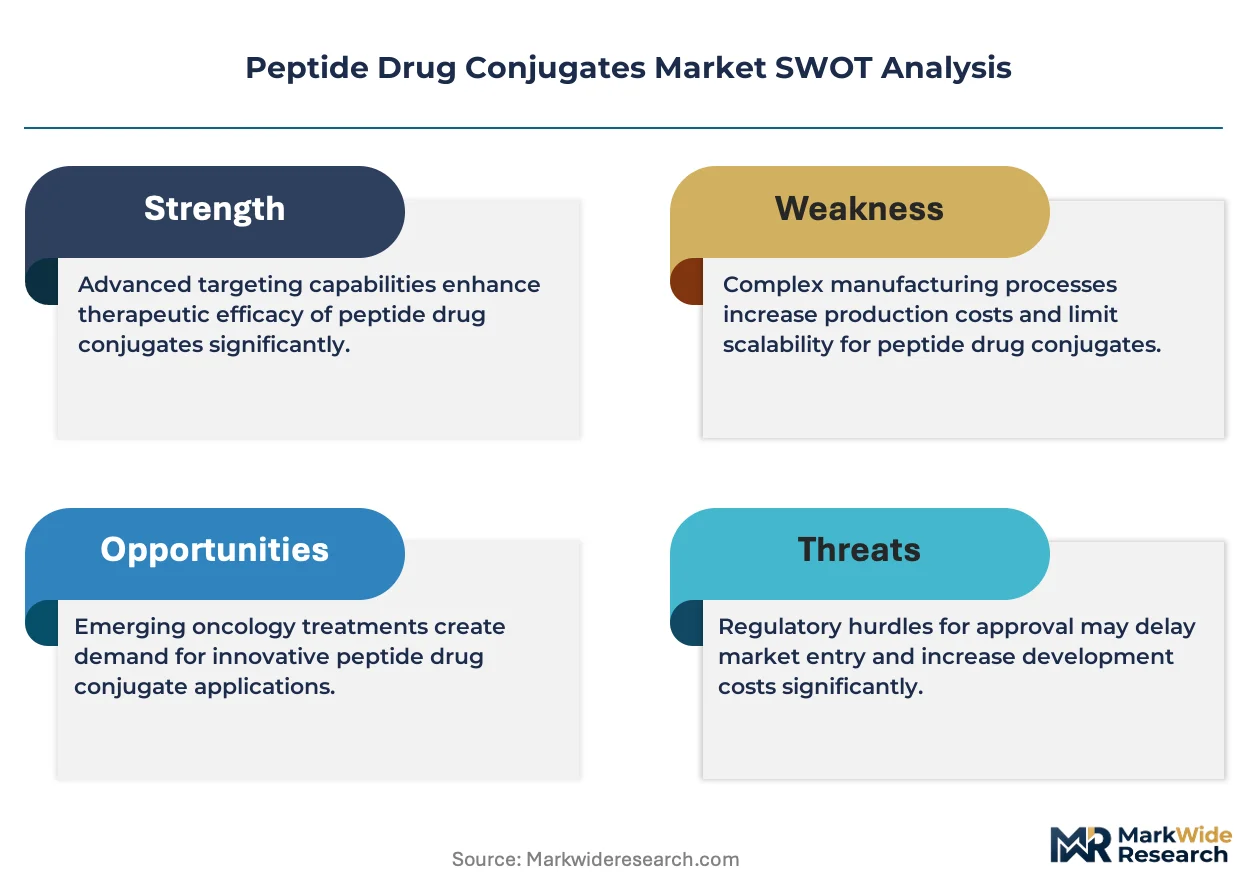
The EU Green Deal's pharmaceutical sustainability criteria is realigning manufacturing standards across European peptide conjugate supply chains. Novartis AG leverages its radioligand therapy infrastructure to dominate commercial production of peptide-based oncology agents. Bicycle Therapeutics anchors its position through proprietary bicyclic peptide platforms that enable smaller-format conjugates with enhanced tumor penetration. Oncopeptides AB specializes in targeted delivery mechanisms for hematologic malignancies, competing on clinical differentiation rather than scale.
Peptide drug conjugates are synthetic or recombinant peptide carriers covalently linked to cytotoxic payloads, diagnostic radioisotopes, or immune modulators, typically ranging from 8 to 50 amino acids with molecular weights under 10 kDa for optimal renal clearance and tissue penetration. Their primary purpose is to achieve receptor-mediated targeting of diseased cells while sparing healthy tissue, reducing systemic toxicity compared to conventional chemotherapy. Oncology applications command the largest revenue pool within therapy area segmentation, driven by validated targets such as somatostatin receptors and integrins in neuroendocrine and solid tumors. Intravenous delivery dominates current administration patterns, though subcutaneous formulations represent the fastest-growing modality as manufacturers reformulate for outpatient administration and patient compliance.
The FDA's accelerated approval regulations and the EMA's adaptive pathway frameworks are compressing development timelines while demanding robust biomarker strategies for patient selection. REACH compliance and ECHA substance registration requirements govern the chemical intermediates and linker chemistries used in European manufacturing, adding compliance layers to supply chain decisions. Stakeholders must monitor evolving payer evidence requirements for targeted therapies, as health technology assessment bodies tighten reimbursement criteria for conjugate drugs without overall survival data.
Market Dynamics
Peptide drug conjugate development is compressing around validated receptor targets as sponsors abandon exploratory biology in favor of de-risked clinical pathways, concentrating investment on somatostatin receptor and integrin programs with established patient selection biomarkers.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA's breakthrough therapy and accelerated approval designations are compressing Phase II-to-approval timelines for peptide conjugates targeting rare cancers. Sponsors now front-load biomarker validation to secure these designations.
- Renal Clearance Pharmacokinetics:The sub-10 kDa molecular weight threshold is overtaking larger antibody-drug conjugates in solid tumor penetration. Peptide formats achieve deeper tissue distribution with reduced systemic exposure.
- Boston-San Francisco Biocluster Concentration:Venture deployment and CMC infrastructure for peptide conjugates concentrates in these two metropolitan areas, creating network effects in talent and manufacturing expertise.
Market Restraints
- Linker Chemistry Input Volatility:Hydrophobic and hydrophilic linker intermediates face price instability due to concentrated specialty chemical production in Chinese and Indian contract manufacturers.
- Radioisotope Supply Concentration:Lutetium-177 and actinium-225 production concentrates at five government-funded reactors worldwide, creating single-source dependencies for radioligand peptide programs.
- REACH Compliance Friction:ECHA substance registration requirements for novel linker chemistries add 18-24 month pre-manufacturing timelines for European peptide conjugate facilities.
Strategic Opportunities
- Subcutaneous Administration Reformulation:Outpatient administration protocols are displacing infusion center dependency for peptide conjugates, expanding addressable patient populations in community oncology settings.
- EU Green Deal Manufacturing Incentives:Pharmaceutical sustainability criteria are redirecting capital toward continuous flow peptide synthesis and solvent recovery systems in European production facilities.
- Neuroendocrine Tumor Expansion:Somatostatin receptor targeting is migrating beyond pancreatic and gastrointestinal primaries into lung and thymic neuroendocrine indications with unmet need.
Industry Challenges
- Peptide Chemist Talent Scarcity:Solid-phase and solution-phase synthesis expertise concentrates at a handful of academic centers and specialized CMOs, constraining manufacturing scale-up timelines.
- Immunogenicity Assessment Complexity:Peptide conjugates require customized anti-drug antibody assay development for each novel scaffold, extending preclinical toxicology programs.
- Health Technology Assessment Evidence Bars:Payer bodies in Germany and France are tightening reimbursement criteria to require overall survival data rather than progression-free survival endpoints alone.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peptide Drug Conjugates Market |
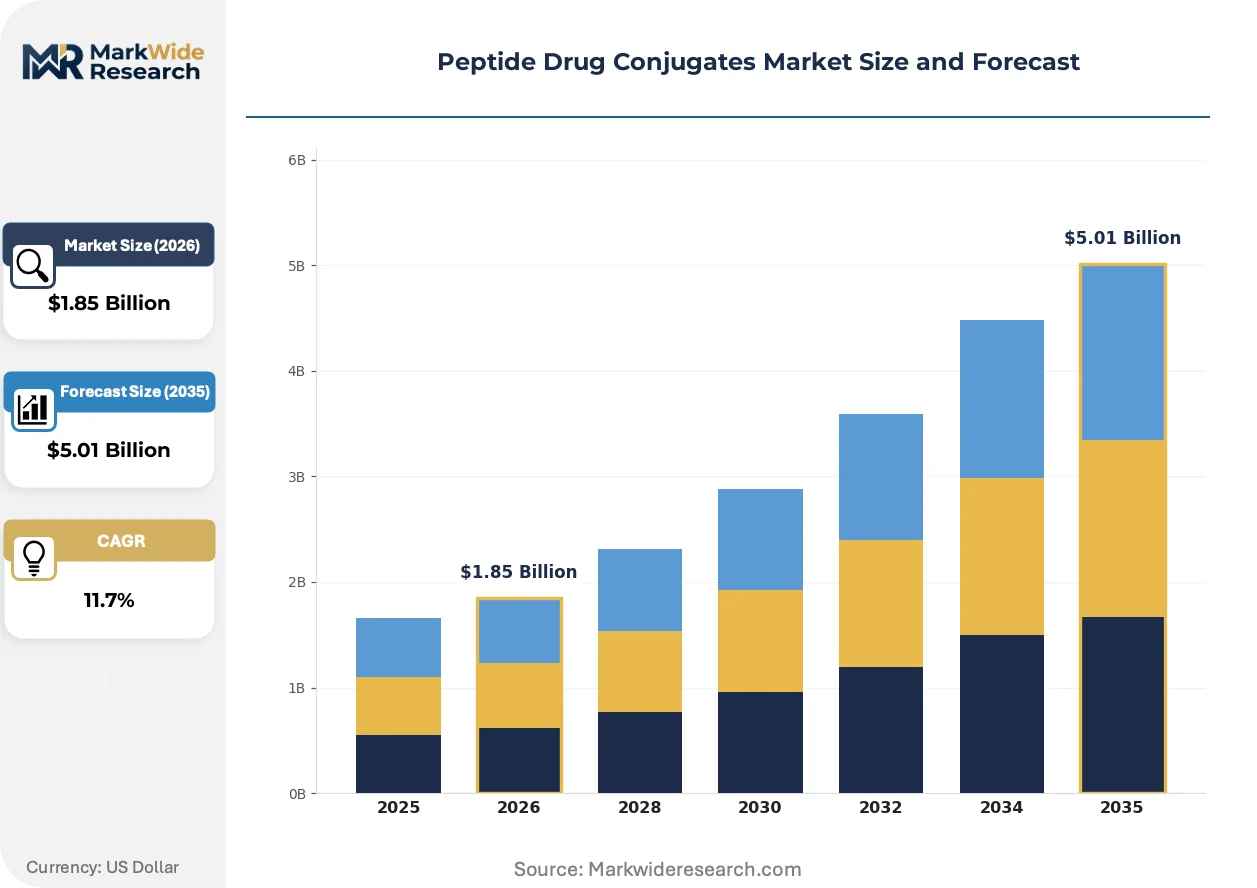
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.01 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibody-Drug Conjugates, Small Molecule Conjugates, Protein Conjugates, Nucleotide Conjugates Therapy Area: Oncology, Immunology, Infectious Diseases, Neurology Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral End User: Hospitals, Research Laboratories, Home Care, Specialty Clinics |
| Companies Covered | Novartis AG, Bicycle Therapeutics, Oncopeptides AB, AstraZeneca, Cybrexa Therapeutics, Angiochem Inc., Theratechnologies, Soricimed Biopharma, PeptiDream, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peptide Drug Conjugates Market Strategic Shifts & Innovations
Bicyclic peptide scaffolds and radioligand payload diversification are compressing the therapeutic index gap between peptide and antibody formats, while regulatory frameworks on both sides of the Atlantic recalibrate approval standards for targeted radiotherapy.
Macrocyclic peptide formats are overtaking linear peptide carriers in tumor penetration depth and metabolic stability. Solid tumor oncology programs at academic medical centers in the United States and Switzerland are adopting Bicycle Therapeutics' proprietary platform for smaller-format conjugates. The structural consequence is a compression in minimum effective dose requirements and expanded therapeutic windows against deep-tissue malignancies.
EMA's adaptive pathway framework is forcing earlier patient access negotiations for peptide radioligand therapies. Conditional marketing authorizations now require pre-specified post-approval confirmatory trial designs with overall survival endpoints. Neuroendocrine tumor indications in France and Germany face the steepest evidence escalation, with AMNOG and HAS assessments demanding head-to-head comparator data.
Academic medical centers are consolidating peptide conjugate procurement through specialized pharmacy consortia rather than individual hospital formulary reviews. The consortium model aggregates volume commitments across multiple oncology departments in exchange for risk-sharing agreements on novel radioligand agents. This consolidation is most advanced in the Netherlands and Nordic countries, where centralized health systems enable pooled purchasing infrastructure.
Peptide Drug Conjugates Market Segmentation
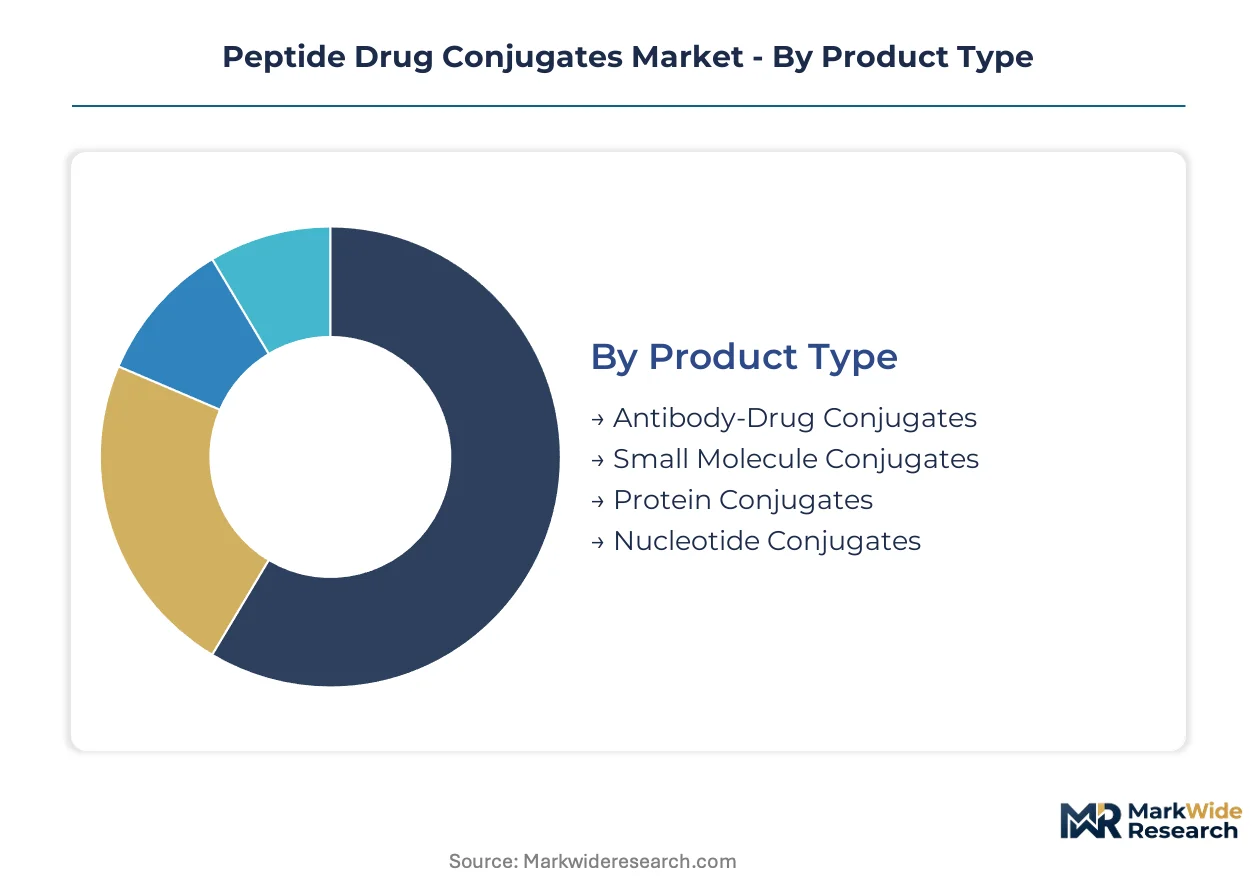
Segmentation in peptide drug conjugates reveals how molecular format, clinical setting, and administration route shape procurement decisions. Manufacturers align R&D investment with therapy-area concentration while reformulating for outpatient delivery expansion.
Product Type:
Upgrade cycles in linker chemistry and payload diversification are pushing sponsors toward next-generation conjugate architectures with improved therapeutic indices.
- Antibody-Drug Conjugates:Large-format biologics with molecular weights exceeding 150 kDa, leveraging Fc-mediated half-life extension for sustained tumor exposure. Demand concentrates in academic medical centers with infusion infrastructure, constrained by limited solid tumor penetration and manufacturing complexity at commercial scale.
- Small Molecule Conjugates:Low molecular weight carriers under 1 kDa with rapid renal clearance and high metabolic lability. Pharmaceutical sponsors in Boston and Basel are prioritizing these formats for CNS penetration programs, though off-target toxicity remains a dose-limiting challenge.
- Protein Conjugates:Mid-size scaffolds including albumin-binding domains and engineered cytokine fusions.
- Nucleotide Conjugates:Oligonucleotide-peptide chimeras for gene silencing applications in rare disease.
Small molecule conjugates sit at the top of the volume ranking, with protein conjugates climbing the fastest.
Therapy Area:
Cost tier stratification separates premium-priced oncology indications from lower-reimbursement chronic disease management.
- Oncology:Receptor-targeted radioligand and cytotoxic conjugates addressing neuroendocrine, prostate, and breast malignancies. United States and Swiss academic centers dominate demand, driven by FDA breakthrough therapy designations and concentrated specialist prescriber networks.
- Immunology:Peptide-drug constructs modulating T-cell activation and cytokine signaling for autoimmune conditions. European immunology departments are expanding compassionate use programs, though payer evidence requirements for immunogenicity surveillance create reimbursement friction.
- Infectious Diseases:Antimicrobial peptide conjugates targeting resistant bacterial and viral pathogens.
- Neurology:Blood-brain barrier penetrating formats for neurodegenerative and neuroinflammatory disorders.
Oncology commands the steepest pricing tier, with neurology gaining share fastest as blood-brain barrier engineering matures.
Delivery Mode:
Patient compliance economics and site-of-care economics are reshaping formulation priorities across administration routes.
- Intravenous:Established administration requiring infusion center infrastructure and clinical monitoring for hypersensitivity reactions. Hospital systems in Germany and the Netherlands maintain procurement concentration here, though capacity constraints are pushing sponsors toward alternative routes.
- Subcutaneous:Depot-formulation and immediate-release peptide conjugates enabling self-administration and reduced healthcare utilization. Community oncology practices in the United States are driving fastest uptake as manufacturers reformulate for outpatient substitution.
- Intramuscular:Sustained-release depot injections for chronic immunology indications.
- Oral:Gastrointestinal-stable peptide formats with permeation enhancers for systemic absorption.
Intravenous administration retains the largest installed base, with subcutaneous delivery expanding most quickly through reformulation investments.
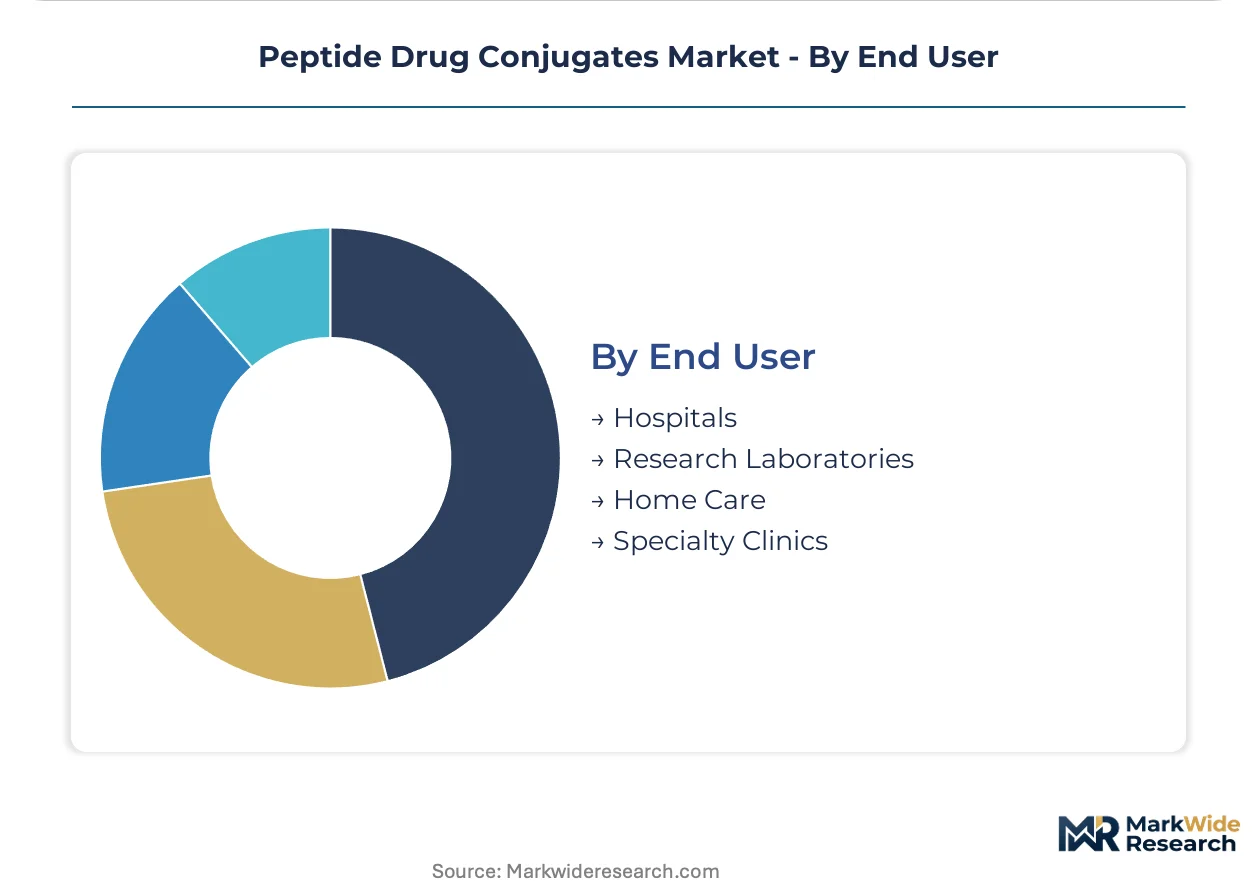
End User:
Procurement authority concentration varies sharply across settings, from centralized hospital pharmacy committees to dispersed home care nursing networks.
- Hospitals:Academic medical centers and community hospital systems with specialized oncology pharmacy infrastructure. United States health systems are consolidating peptide radioligand procurement through multi-hospital consortia, aggregating volume for risk-sharing agreements with manufacturers.
- Research Laboratories:Academic and contract research organizations conducting preclinical and early-phase clinical development. NIH-funded centers and European Research Council grant holders represent concentrated demand for investigational conjugate supply.
- Home Care:Nursing services and specialty pharmacies managing subcutaneous and oral administration in residential settings.
- Specialty Clinics:Independent oncology and infusion centers outside hospital system ownership.
Hospitals anchor procurement volume, with home care climbing fastest as subcutaneous formulations enable site-of-care migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The peptide drug conjugates industry traces its commercial roots to Swiss radiopharmaceutical manufacturing and Boston's biotechnology corridor, where early somatostatin receptor targeting programs established the clinical and regulatory templates now replicated worldwide.
United States
FDA breakthrough therapy designations and concentrated venture deployment drive development velocity around somatostatin receptor and integrin targets. The Inflation Reduction Act's Medicare negotiation provisions are reshaping pricing expectations for targeted oncology agents. Greater Boston and San Francisco Bay Area bioclusters host the densest concentration of peptide conjugate CMC infrastructure and specialist talent pools.
Germany
EMA centralized procedures and AMNOG health technology assessments create dual regulatory pressures for market access. REACH compliance and ECHA substance registration requirements extend pre-manufacturing timelines for novel linker chemistries. The Rhine-Main and Munich metropolitan regions concentrate radioligand therapy administration infrastructure at academic medical centers with specialized nuclear pharmacy capabilities.
Switzerland
Swissmedic's alignment with EMA standards accelerates parallel submission strategies for peptide radioligand therapies. Federal incentives for pharmaceutical manufacturing sustainability redirect capital toward continuous flow peptide synthesis systems. Basel and Zurich anchor commercial production and clinical development operations, leveraging established radiopharmaceutical logistics networks.
France
HAS assessment criteria demanding overall survival data are tightening reimbursement conditions for progression-free survival endpoints alone. ANSM pharmacovigilance requirements extend post-marketing surveillance obligations for immunogenicity monitoring. The Paris-Saclay cluster and Lyon biotech corridor concentrate early-phase clinical trial infrastructure for neuroendocrine tumor indications.
Netherlands
Centralized health system procurement through specialized pharmacy consortia aggregates volume commitments across multiple oncology departments. Dutch academic medical centers pioneer risk-sharing agreements for novel radioligand agents, creating template contracting structures. The Randstad metropolitan region hosts the most advanced pooled purchasing infrastructure for peptide conjugate therapeutics in Europe.
Peptide Drug Conjugates Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the peptide drug conjugate value chain, creating a tiered structure where radiopharmaceutical manufacturing infrastructure separates scalable competitors from development-stage specialists. Large-format pharmaceutical conglomerates with existing nuclear medicine capabilities occupy distinct competitive terrain from platform-technology biotechs and targeted-delivery specialists. Three archetypes dominate: radioligand therapy incumbents with reactor access and distribution networks; bicyclic and macrocyclic peptide platform companies; and hematologic malignancy specialists competing on clinical differentiation. Competitive dynamics center on manufacturing scale-up partnerships and subcutaneous formulation reformulation races.
Within the radioligand therapy tier, Novartis AG and Bicycle Therapeutics exemplify divergent scale strategies, with the former leveraging captive isotope supply chains and the latter occupying the platform-technology specialist position. Oncopeptides AB represents the targeted-delivery archetype focused on hematologic indications rather than solid tumor scale. These three entities anchor the competitive landscape without exhausting its structural variety.
| Leading Market Players |
|---|
| Novartis AG |
| Bicycle Therapeutics |
| Oncopeptides AB |
| AstraZeneca |
| Cybrexa Therapeutics |
| Angiochem Inc. |
| Theratechnologies |
| Soricimed Biopharma |
| PeptiDream |
| Others |
Cost & Logistics Intelligence
Performance-grade bifurcation between GMP-certified radioligand conjugates and research-use peptide intermediates manifests in parallel supply chain configurations, with the former commanding captive isotope contracts and cold-chain distribution while the latter flows through commoditized chemical catalogs subject to REACH registration delays.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs peptide drug conjugate procurement, with differentiation driven by FDA breakthrough therapy designation status and linker chemistry novelty. Price erosion runs through the standard tier as Chinese and Indian contract manufacturers expand specialty chemical capacity. Academic medical centers in Boston and San Francisco exhibit lowest price sensitivity due to bundled reimbursement, while community oncology practices in the United States face tightening margin pressure.
Supply Chain Analysis
Reverse-logistics infrastructure for radioligand peptide conjugates remains underdeveloped, with spent lutetium-177 and actinium-225 vials requiring specialized nuclear waste handling that concentrates at five government-funded reactors worldwide. Manufacturing feeds from linker chemistry intermediates produced in China and India, with final conjugation anchored in Switzerland and the United States. Single-source isotope dependencies create acute vulnerability to reactor maintenance schedules. Distribution runs through radiopharmaceutical networks with 72-hour delivery windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The peptide drug conjugates market compounds steadily as validated receptor targets compress development risk and front-loaded biomarker strategies secure accelerated regulatory pathways.
For Market Incumbents: To counter linker chemistry input volatility, Novartis AG and radioligand therapy leaders should secure captive isotope supply agreements with government-funded reactors and invest in continuous flow peptide synthesis systems to reduce solvent-dependent batch variability. Backward integration into specialty chemical manufacturing buffers against Indian and Chinese contract manufacturer price instability. For New Entrants and Emerging Players: Capture subcutaneous formulation white space in community oncology settings, where outpatient administration protocols remain underpenetrated relative to infusion center dependency. Bicycle Therapeutics' platform-technology model offers a template for asset-light entry. Target neuroendocrine tumor expansion into lung and thymic indications with unmet need, leveraging somatostatin receptor targeting migration beyond pancreatic and gastrointestinal primaries. For Investors and Strategic Acquirers: Consolidation pressure builds where radiopharmaceutical manufacturing infrastructure separates scalable competitors from development-stage specialists lacking reactor access. Five-to-ten year viability favors platform-technology biotechs with proprietary macrocyclic or bicyclic peptide scaffolds. Watch for EMA adaptive pathway framework decisions on conditional marketing authorizations as early signals of reimbursement trajectory for progression-free survival endpoints.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Administration Reformulation | Community oncology practices in the United States drive outpatient substitution away from infusion centers. |
| Radioligand Isotope Supply Agreement | Captive lutetium-177 and actinium-225 contracts with government-funded reactors reduce single-source vulnerability. |
| Continuous Flow Peptide Synthesis | EU Green Deal sustainability criteria redirect capital toward solvent recovery systems in European facilities. |
| Biomarker-Validated Clinical Trial Design | FDA breakthrough therapy designation front-loads patient selection strategies to compress Phase II-to-approval timelines. |
| Specialized Pharmacy Consortium Partnership | Dutch and Nordic pooled purchasing infrastructure aggregates volume commitments for risk-sharing agreements. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling and top-down revenue triangulation anchored market sizing.
Comparable-period anchoring linked the projection horizon to historical regulatory approval timelines and commercial launch trajectories across the modeling period. Segmentation dimensions included therapy area, molecular format, administration route, patient population, and regional regulatory cluster. CAGRs derived from log-linear trend fitting with adjustment for pipeline probability-weighted revenue recognition. Forecast inputs incorporated biomarker adoption curves and reimbursement evidence escalation patterns.
Regulatory pathway reversals, isotope supply disruptions, and payer evidence requirement tightening are the dominant revision risks for peptide drug conjugate forecasts. Practitioners should monitor AMNOG and HAS assessment criteria evolution, reactor maintenance schedules at government-funded facilities, and FDA accelerated approval confirmatory trial design specifications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Blood Product Market
Biopharmaceuticals
Global Mono Vaccine Market
Biopharmaceuticals
Daptomycin Market
Biopharmaceuticals
Biotherapeutics Cell Line Development Market
Biopharmaceuticals
Global Immuno Oncology Assays Market
Biopharmaceuticals
Erythropoietin Drugs Market
Biopharmaceuticals
Biopharmaceutical Oral Drug Delivery Market
Biopharmaceuticals
Anti-Tumor Drugs Market
Biopharmaceuticals
Global MRSA Drugs Market
Biopharmaceuticals
North America and Europe Pegylated Drugs Market
Biopharmaceuticals
North America Generic Oncology Drug Market
Biopharmaceuticals
Proteinuria Therapeutics Market
Biopharmaceuticals
Benzbromarone API Market
Biopharmaceuticals
Human Immunodeficiency Virus (HIV) Drugs Market
Biopharmaceuticals
Generic Oncology Drugs Market
Biopharmaceuticals
Insulin Delivery Pens Market