
 Global Immuno Oncology Assays Market | 2026-2036
Global Immuno Oncology Assays Market Size, Share, and Industry Trends Forecast 2026-2036
Global Immuno Oncology Assays Market Foresight
Modular assay panel bundling is consolidating purchasing decisions among large biopharmaceutical buyers who seek integrated workflow solutions spanning sample preparation through data analysis. Thermo Fisher Scientific leverages its end-to-end platform breadth to anchor high-volume supply contracts with top-20 pharma accounts. F. Hoffmann-La Roche Ltd sustains competitive positioning through deep specialization in companion diagnostic co-development with oncology drug pipelines. Illumina differentiates via dominance in next-generation sequencing readout integration with immune profiling assays.
Immuno oncology assays comprise laboratory methods that quantify immune cell populations, cytokine signatures, and tumor-immune interactions using antibody-based detection, fluorescent labeling, or nucleic acid amplification with sensitivity thresholds reaching picogram-per-milliliter concentrations. These assays enable patient stratification for immunotherapy response, mechanistic understanding of resistance pathways, and monitoring of immune-related adverse events in clinical settings. Multiplex assays command expanding share as researchers demand simultaneous measurement of dozens of analytes from limited clinical specimens. Single-cell analysis represents the fastest-growing technology dimension as it resolves cellular heterogeneity invisible to bulk population methods. Label-free formats occupy mature positions in secondary screening workflows where throughput requirements outweigh resolution needs.
The FDA regulates these products as in vitro diagnostics or research-use-only devices depending on intended clinical claims, while the EMA's In Vitro Diagnostic Medical Devices Regulation imposes stricter conformity assessment requirements for European market access. ISO 13485 quality management standards govern manufacturing consistency across jurisdictions, creating compliance cost barriers for emerging entrants. Stakeholders must monitor evolving reimbursement coding for multi-analyte assay panels as payers scrutinize clinical utility evidence for broad immune profiling versus single-biomarker testing.
Market Dynamics
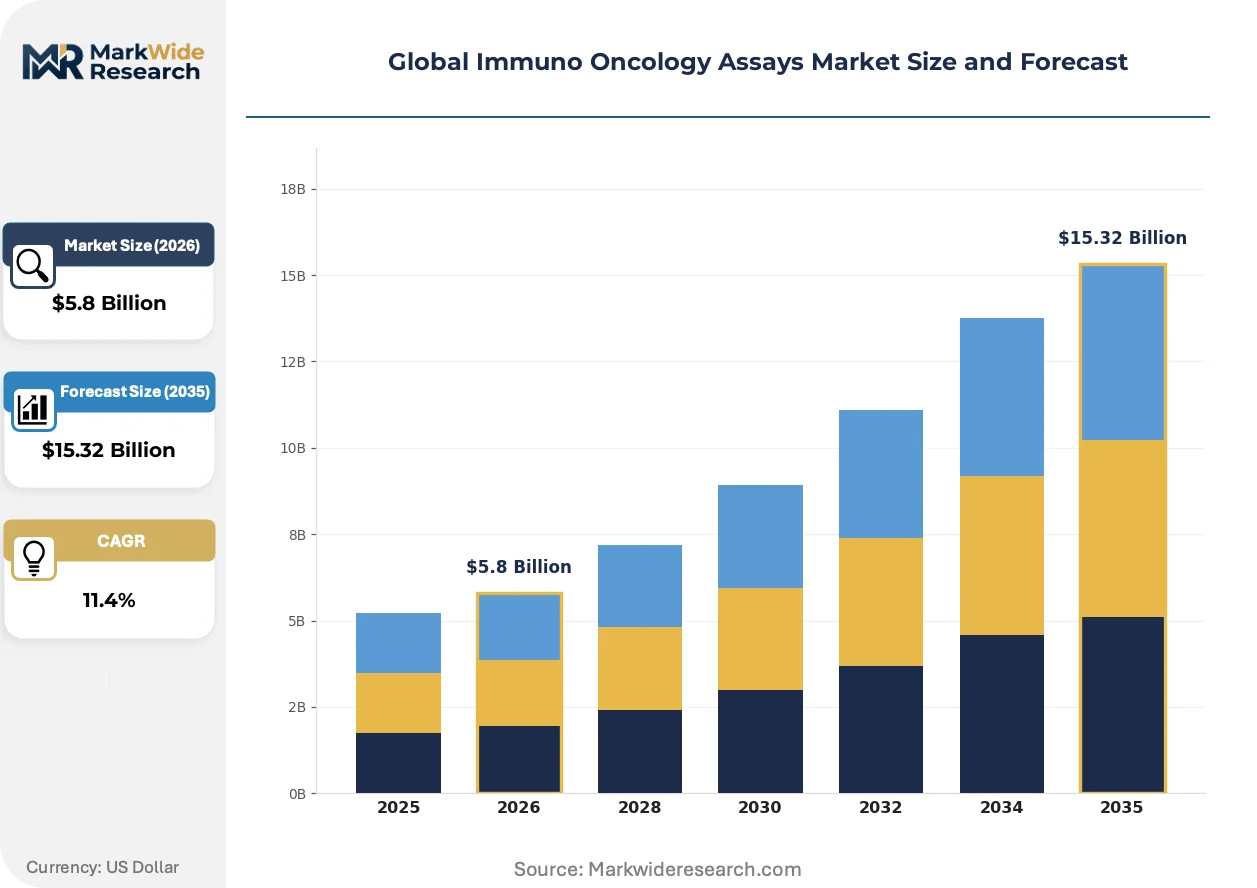
Biopharmaceutical consolidation into integrated workflow platforms is compressing vendor counts and amplifying contract values for end-to-end immuno oncology assay suppliers. This purchasing concentration rewards platform breadth over point solutions.
Growth Catalysts
- Companion diagnostic mandates:FDA's breakthrough device designation pathway accelerates commercialization timelines for novel assay formats co-developed with oncology therapeutics pipelines.
- Multiplex technology maturation:Academic medical centers in the United States, Germany, and Japan now demand simultaneous measurement of dozens of analytes from limited clinical specimens.
- Single-cell resolution imperative:Researchers require cellular heterogeneity visibility that bulk population methods cannot provide, driving investment in spatial transcriptomics and flow cytometry platforms.
Market Restraints
- ISO 13485 compliance cost barriers:Quality management certification requirements create capital intensity that disadvantages emerging entrants against established manufacturers.
- Reimbursement coding uncertainty:Payer scrutiny of clinical utility evidence for broad immune profiling versus single-biomarker testing creates revenue recognition delays for multi-analyte panel providers.
- Reagent supply concentration:Antibody and fluorescent label sourcing depends on limited qualified suppliers, exposing assay manufacturers to input volatility and qualification bottlenecks.
Strategic Opportunities
- Liquid biopsy integration:Circulating tumor DNA and immune cell capture technologies converge with immuno oncology assays to enable non-invasive monitoring of immunotherapy response.
- EMA MDR harmonization gaps:European conformity assessment requirements for in vitro diagnostics create first-mover advantages for manufacturers achieving notified body certification ahead of competitor filings.
- Immune-related adverse event surveillance:Post-market pharmacovigilance contracts with hospital networks represent underpenetrated revenue streams for cytokine profiling services in Japan and Switzerland.
Industry Challenges
- Bioinformatics talent scarcity:Multiplex and single-cell assay outputs require computational biology expertise that outpaces current training pipeline capacity in clinical diagnostics.
- Legacy LIMS integration friction:Hospital laboratory information management systems resist seamless data exchange with novel assay platforms, extending implementation timelines and support costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Immuno Oncology Assays Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $15.32 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Assay Type: Flow Cytometry, ELISA, Western Blotting, Immunohistochemistry, PCR, Microarray Application: Biomarker Discovery, Drug Development, Diagnostic Testing, Therapeutic Monitoring, Prognostic Evaluation, Vaccine Research End User: Biopharmaceutical Companies, Clinical Research Organizations, Diagnostic Laboratories, Academic Institutes, Biotechnology Firms, Contract Research Organizations Technology: Label-Based Assays, Label-Free Assays, Multiplex Assays, Single-Cell Analysis, Mass Cytometry, Imaging Cytometry |
| Companies Covered | Thermo Fisher Scientific, F. Hoffmann-La Roche Ltd, Agilent Technologies, Illumina, PerkinElmer, Merck KGaA, QIAGEN, Bio-Rad Laboratories, Sartorius, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Immuno Oncology Assays Market Shifts & Advancements
Spatial biology platforms are rewriting how tumor-immune microenvironments are characterized, shifting competitive advantage from analyte breadth to anatomical context preservation. This technological pivot demands new capital deployment and partnership structures across the supply base.
Spatial transcriptomics is rewriting the standard for immune profiling by preserving tissue architecture while quantifying gene expression at single-cell resolution. Contract research organizations serving top-20 pharmaceutical accounts are adopting these platforms within twelve-month procurement cycles. The technology is rewriting competitive positioning by decommoditizing antibody-based detection methods that cannot resolve cellular neighborhoods.
The EMA's In Vitro Diagnostic Medical Devices Regulation imposes stricter conformity assessment requirements than predecessor directives, elevating documentation burdens for European market access. Manufacturers must demonstrate clinical evidence across expanded performance criteria before notified body review. Small and mid-cap assay developers are responding by prioritizing US FDA submissions ahead of European regulatory filings.
Biopharmaceutical procurement teams now unbundle assay purchasing from instrumentation contracts, reversing prior bundled capital equipment agreements. This disintermediation of vendor lock-in strategies benefits specialized assay developers with superior analytical performance. The shift is most visible in United States-based precision oncology consortia where multi-site standardization requirements override single-source convenience preferences.
Global Immuno Oncology Assays Market Segmentation
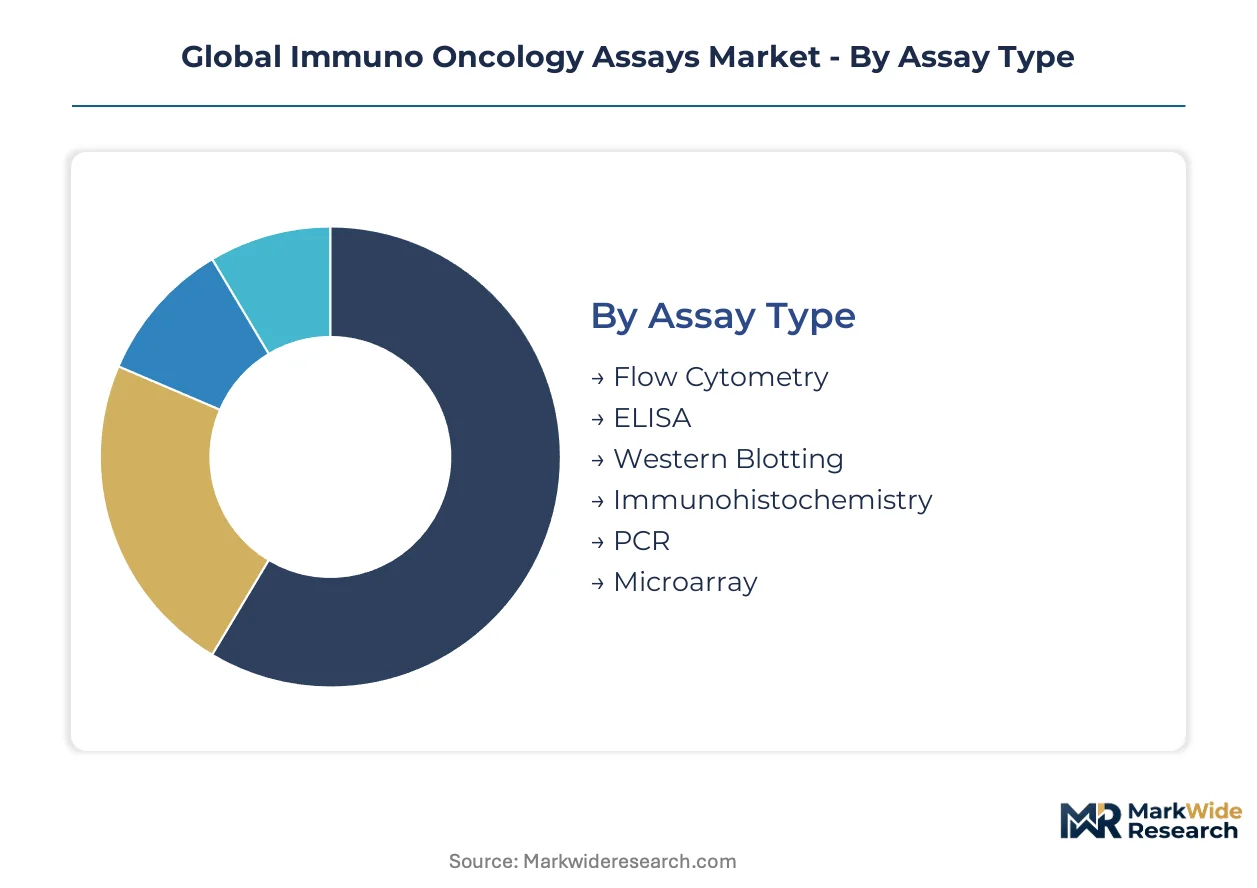
Immuno oncology assays fragment across multiple technical and commercial dimensions. Each segmentation layer reveals distinct purchasing patterns, integration requirements, and margin structures that vendors must navigate.
Assay Type:
Standalone formats dominate high-throughput screening workflows, while embedded systems integrate into automated clinical platforms.
- Flow Cytometry:Suspension-based cell counting and sorting using fluorescent antibody panels achieves single-cell resolution for immune phenotype profiling. Academic medical centers in the United States and Germany deploy these systems for CAR-T therapy monitoring where cell population dynamics determine treatment scheduling.
- ELISA:Enzyme-linked immunosorbent assays quantify soluble cytokines and checkpoint proteins with picogram-per-milliliter sensitivity. Diagnostic laboratories in Japan rely on standardized ELISA kits for immune-related adverse event surveillance in post-market pharmacovigilance programs.
- Western Blotting:Protein separation and antibody detection validates signaling pathway activation in mechanistic studies.
- Immunohistochemistry:Tissue-section antibody staining visualizes tumor-immune microarchitecture for pathology review.
- PCR:Nucleic acid amplification detects immune gene expression signatures from limited clinical specimens.
- Microarray:High-density probe platforms enable genome-wide immune profiling for biomarker discovery cohorts.
Flow Cytometry leads volumes today; Single-Cell Analysis (within Flow Cytometry) is gaining share fastest.
Application:
Cost tiers separate exploratory research from regulated clinical applications with stringent validation requirements.
- Biomarker Discovery:Exploratory profiling of immune signatures precedes clinical validation, demanding flexible assay formats that accommodate protocol iteration. Biopharmaceutical companies in Switzerland and the United States fund discovery programs through internal R&D budgets rather than diagnostic reimbursement pathways.
- Drug Development:Pharmacodynamic and patient stratification assays support oncology pipeline decision-making. Contract research organizations in Germany specialize in GLP-compliant immuno oncology assay services for Phase I-III trials.
- Diagnostic Testing:Companion diagnostic claims require FDA premarket approval or breakthrough device designation.
- Therapeutic Monitoring:Serial immune profiling tracks treatment response and resistance emergence.
- Prognostic Evaluation:Baseline immune signatures predict long-term outcomes independent of therapy selection.
- Vaccine Research:Immunogenicity assays measure cellular and humoral responses to neoantigen formulations.
Drug Development commands the largest contract values; Diagnostic Testing expands most quickly as companion diagnostic mandates proliferate.
End User:
Customer type determines purchasing authority, with consolidated biopharmaceutical procurement teams negotiating enterprise contracts.
- Biopharmaceutical Companies:Integrated workflow platforms spanning sample preparation through data analysis anchor high-volume supply agreements. Top-20 pharmaceutical accounts in the United States consolidate vendor counts to reduce qualification overhead.
- Clinical Research Organizations:Specialized service providers adopt spatial transcriptomics platforms within compressed procurement cycles to serve pharmaceutical clients.
- Diagnostic Laboratories:Hospital and reference labs prioritize ISO 13485-certified assays with established reimbursement coding.
- Academic Institutes:Research universities access grant-funded instrumentation through shared core facilities.
- Biotechnology Firms:Emerging therapeutic developers outsource assay development to conserve capital.
- Contract Research Organizations:Dedicated service providers compete on analytical performance and turnaround time.
Biopharmaceutical Companies lead volumes today; Clinical Research Organizations are climbing the fastest as outsourcing accelerates.
Technology:
Maturity curves separate established detection methods from emerging platforms requiring new capital deployment.
- Label-Based Assays:Fluorescent and enzymatic reporter systems dominate installed base and regulatory precedent. FDA-cleared immunofluorescence protocols in the United States provide reimbursement security that novel label-free formats lack.
- Multiplex Assays:Simultaneous measurement of dozens of analytes from limited clinical specimens addresses sample scarcity in pediatric oncology and repeat biopsy constraints. Academic medical centers in Japan and Germany now require multiplex capability as standard.
- Label-Free Assays:Surface plasmon resonance and bio-layer interferometry suit secondary screening where throughput outweighs resolution.
- Single-Cell Analysis:Cellular heterogeneity resolution invisible to bulk methods drives investment in spatial transcriptomics.
- Mass Cytometry:Metal-isotope detection expands simultaneous parameter measurement beyond fluorescence spectral limits.
- Imaging Cytometry:Morphometric analysis combines spatial context with quantitative phenotyping.
Label-Based Assays lead volumes today; Single-Cell Analysis shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The immuno oncology assays industry traces its commercial roots to the United States, where precision oncology infrastructure first scaled to support companion diagnostic co-development with immunotherapy pipelines. From this foundation, demand diffusion followed regulatory harmonization and biopharmaceutical manufacturing expansion into Western Europe and East Asia.
United States
FDA's breakthrough device designation pathway accelerates commercialization timelines for novel assay formats, while Medicare reimbursement frameworks for multi-analyte panels sustain diagnostic laboratory adoption. The Greater Boston and San Francisco Bay Area clusters concentrate biopharmaceutical R&D spending, with contract research organizations in these metros adopting spatial transcriptomics platforms within compressed procurement cycles.
Germany
EMA's In Vitro Diagnostic Medical Devices Regulation imposes stricter conformity assessment requirements than predecessor directives, elevating documentation burdens for European market access. Academic medical centers in Heidelberg and Munich now require multiplex capability as standard for pediatric oncology specimen analysis. The country's national pharmaceutical regulator enforces ISO 13485 quality management standards that govern manufacturing consistency across jurisdictions.
Japan
PMDA's streamlined review pathways for companion diagnostics align with METI's precision medicine initiatives to accelerate immunotherapy patient stratification. Diagnostic laboratories in Tokyo and Osaka prioritize standardized ELISA kits for immune-related adverse event surveillance in post-market pharmacovigilance programs. The Tokyo-Yokohama cluster anchors biopharmaceutical procurement consolidation into integrated workflow platforms.
Switzerland
Swissmedic's regulatory framework for in vitro diagnostics creates first-mover advantages for manufacturers achieving notified body certification ahead of competitor filings. Basel and Zurich host precision oncology consortia where multi-site standardization requirements override single-source convenience preferences. The country's central bank maintains stable funding conditions for biopharmaceutical venture capital deployment.
United Kingdom
The Medicines and Healthcare products Regulatory Agency's post-Brexit conformity assessment procedures create transitional complexity for assay market access. London and Cambridge concentrate academic medical center demand for single-cell analysis platforms that resolve cellular heterogeneity invisible to bulk population methods. NHS England's procurement frameworks increasingly unbundle assay purchasing from instrumentation contracts.
Global Immuno Oncology Assays Market Competitive Landscape
Premium-margin players sit above commodity-margin players across platform breadth and regulatory certification dimensions, with end-to-end workflow suppliers commanding contract value multiples over point-solution vendors. The vendor base stratifies into three tiers: integrated platform conglomerates, specialized companion diagnostic co-developers, and emerging single-cell technology pure-plays. Consolidation pressure rewards M&A activity that expands geographic regulatory coverage, while technology licensing agreements accelerate access to novel detection modalities.
Within the integrated platform tier, Thermo Fisher Scientific and F. Hoffmann-La Roche Ltd exemplify divergent competitive strategies—one leveraging end-to-end breadth for high-volume supply contracts, the other sustaining positioning through deep specialization in companion diagnostic pipelines. Illumina occupies a distinct position at the sequencing-readout integration frontier. These three entities represent the archetype spectrum from conglomerate scale to therapeutic co-development depth to technology platform dominance.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche Ltd |
| Agilent Technologies |
| Illumina |
| PerkinElmer |
| Merck KGaA |
| QIAGEN |
| Bio-Rad Laboratories |
| Sartorius |
| Others |
Supply & Pricing Matrix
Captive antibody production networks anchor supply positions for established assay manufacturers while locking in pricing power against emerging competitors who face qualification bottlenecks. This integration choice separates premium-tier vendors with in-house reagent manufacturing from standard-tier competitors exposed to input volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs contract negotiations, with ISO 13485 certification and FDA breakthrough device designation commanding substantial premiums over research-use-only formats. Price differentiation hinges on regulatory clearance tier and volume scale, with top-20 pharmaceutical accounts extracting favorable terms through consolidated procurement. Cost compression in the standard tier is intensifying because academic medical centers unbundle assay purchasing from instrumentation contracts. Biotechnology firms and emerging therapeutic developers exhibit highest price sensitivity, while diagnostic laboratories with established reimbursement coding show lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with qualified antibody and fluorescent label suppliers concentrated in the United States, Germany, and Switzerland. Manufacturing draws from recombinant protein production, specialized conjugation chemistry, and precision optical components as critical inputs. Tariff exposure on Chinese-sourced rare earth elements for fluorescent labels creates margin risk for mid-tier manufacturers. Distribution runs through direct sales forces for enterprise biopharmaceutical accounts and specialized distributors serving diagnostic laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
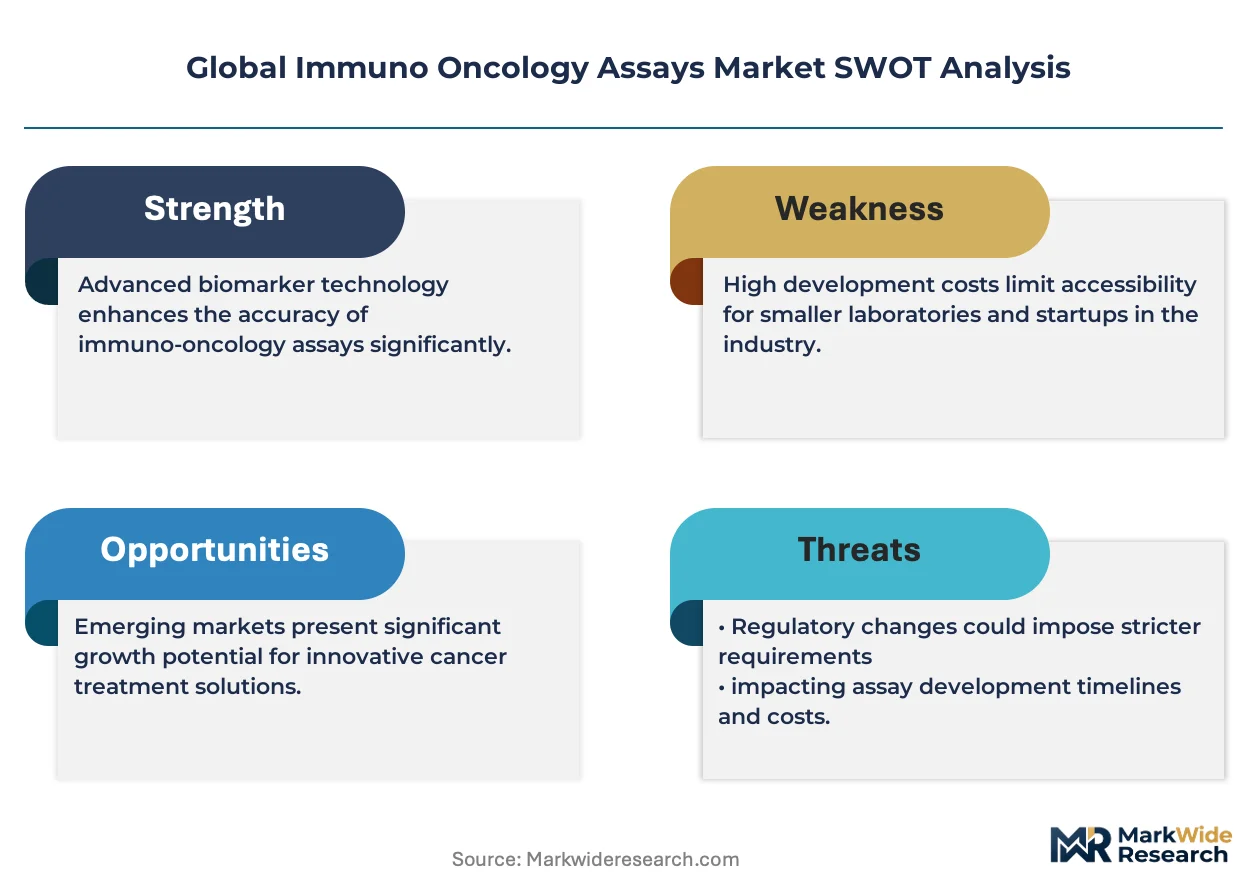
The Global Immuno Oncology Assays Market compounds steadily as companion diagnostic mandates expand reimbursement pathways for immune profiling technologies. FDA breakthrough device designations and EMA MDR harmonization gaps create durable competitive moats for certified manufacturers.
For Market Incumbents: To counter disintermediation of bundled capital equipment agreements, anchor high-volume supply contracts through end-to-end platform breadth spanning sample preparation through data analysis. Deepen ISO 13485 certification coverage across multiple notified bodies to exploit EMA MDR filing backlogs that disadvantage emerging entrants.
For New Entrants and Emerging Players: Spatial transcriptomics integration with immune profiling assays offers a technology-first wedge into contract research organization procurement cycles serving top-20 pharmaceutical accounts. Target Japan's post-market pharmacovigilance surveillance segment where cytokine profiling services remain underpenetrated. Pursue liquid biopsy convergence partnerships to bypass entrenched installed bases in flow cytometry.
For Investors and Strategic Acquirers: Roll-up economics work for specialized companion diagnostic co-developers because biopharmaceutical consolidation into integrated workflow platforms compresses vendor counts and amplifies contract values. Five-to-ten year viability favors manufacturers with notified body certification ahead of competitor filings. Watch spatial biology platform adoption rates in United States precision oncology consortia as the inflection signal for technology decommoditization.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates commercialization timelines for novel assay formats co-developed with oncology pipelines. |
| EMA Notified Body Certification | Creates first-mover advantages ahead of competitor filings under stricter MDR conformity requirements. |
| Spatial Transcriptomics Platform Adoption | Rewrites competitive positioning by decommoditizing antibody-based detection methods in tumor microenvironment analysis. |
| Liquid Biopsy Integration Partnership | Enables non-invasive immunotherapy monitoring through circulating tumor DNA convergence with immune profiling. |
| ISO 13485 Multi-Jurisdiction Certification | Reduces qualification overhead for biopharmaceutical procurement teams consolidating vendor counts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up assay volume estimates and top-down market sizing triangulated across technology, application, and end-user segmentation dimensions.
Segment-weighting approaches modeled flow cytometry, ELISA, PCR, and spatial transcriptomics platforms separately across biomarker discovery, drug development, diagnostic testing, and therapeutic monitoring applications. CAGRs were derived from instrument placement trajectories, reagent consumption curves, and service contract renewal patterns. Forecast inputs incorporated companion diagnostic mandate proliferation rates and reimbursement coding evolution for multi-analyte panels.
The model holds under stable regulatory harmonization and continued biopharmaceutical R&D spending; deviation in payer coverage decisions or antibody supply disruptions would shift trajectory boundaries. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Asia-Pacific Insulin Pens Market
Biopharmaceuticals
Compounded Bioidentical Hormone Therapy Market
Biopharmaceuticals
Germany Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Theranostics Market
Biopharmaceuticals
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market
Biopharmaceuticals
Oligonucleotide API Market
Biopharmaceuticals
Plasma Protein System Market
Biopharmaceuticals
Generic Oncology Drugs Market
Biopharmaceuticals
In Situ Gel Drug Delivery Market
Biopharmaceuticals
Plasma Protease C1-Inhibitor Market
Biopharmaceuticals
Daptomycin Market
Biopharmaceuticals
Antimycobacterial Drugs Market
Biopharmaceuticals
North America Plasma Fractionation Market
Biopharmaceuticals
Combination Antibody Therapy Market
Biopharmaceuticals
Brazil Generic Drug Market
Biopharmaceuticals
Middle East and Africa Plasma Fractionation Market