
 Global Blood Product Market | 2026-2036
Global Blood Product Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blood Product Market Foresight
The gap between premium pathogen-reduced plasma products and commodity whole blood units is expanding as hospitals prioritize safety-assured inventories over cost minimization. CSL Limited leverages its vertically integrated plasma collection network across multiple continents to secure raw material access. Grifols S.A. sustains one of the industry's largest donor center footprints, giving it volume leverage in immunoglobulin output. Takeda Pharmaceutical Company Limited differentiates through its concentrated hemophilia therapy portfolio and recombinant factor expertise.
Blood products encompass human-derived biological materials—primarily plasma, platelets, red blood cells, and cryoprecipitate—collected through whole blood donation or apheresis and processed under cold-chain conditions to preserve clotting factors and cellular viability. These products serve essential therapeutic functions in trauma resuscitation, surgical hemostasis, coagulation disorder management, and immunodeficiency replacement. Plasma-derived fractions command the dominant revenue share due to their complex fractionation requirements and chronic-disease dosing profiles, while platelet concentrates represent the fastest-expanding category as cancer chemotherapy volumes rise and apheresis collection efficiency improves. Hospital procurement now weighs shelf-life extension technologies and viral inactivation status as heavily as unit price.
The FDA enforces Current Good Manufacturing Practice standards and pathogen reduction guidance that elevate capital costs for domestic producers, while the EMA's Plasma Master File framework governs European import qualifications and traceability. WHO's Global Benchmarking Tool shapes national blood system assessments in emerging markets, indirectly steering donor recruitment and testing infrastructure investments. Stakeholders must monitor regulatory divergence between nucleic acid testing mandates and emerging pathogen reduction technologies, as compliance timing will determine which manufacturing configurations capture cross-border supply contracts.
Market Dynamics
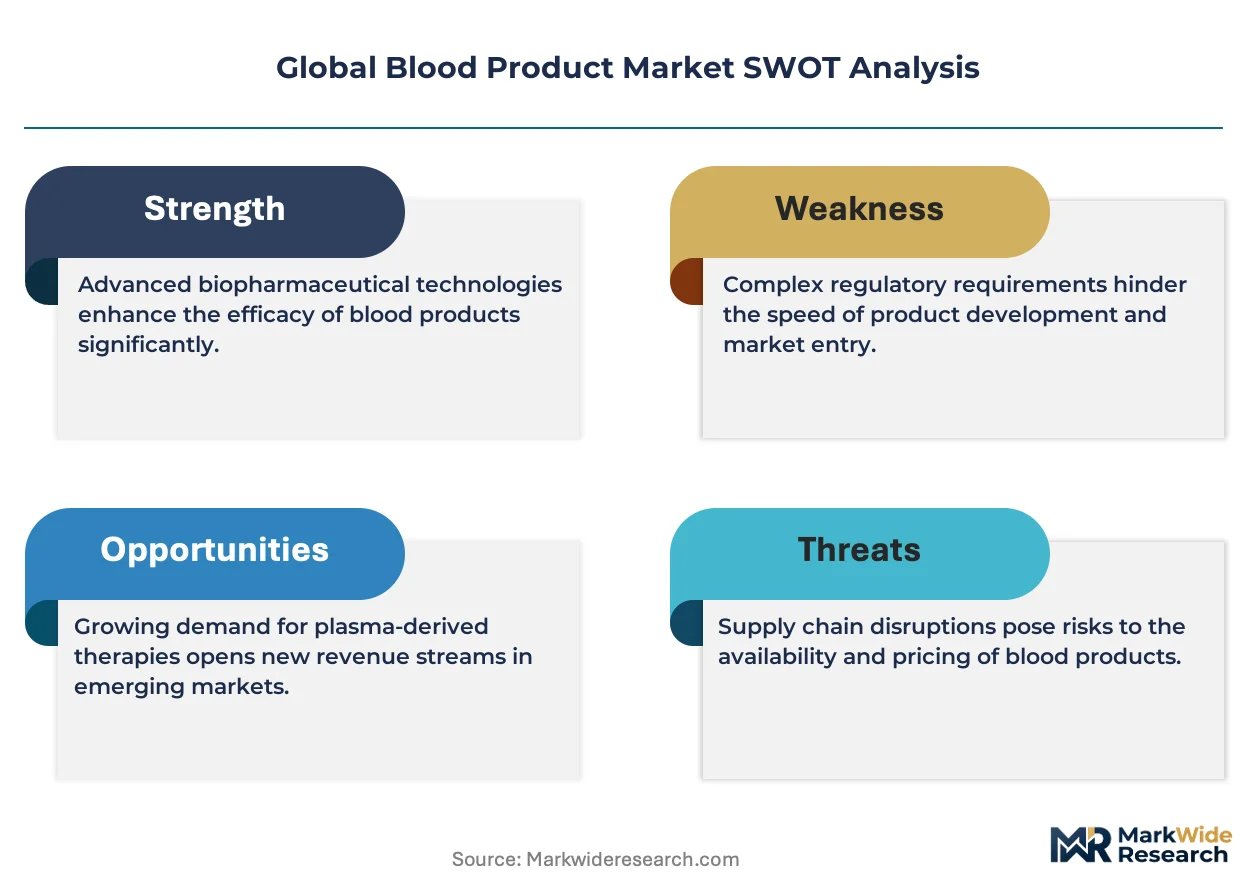
Pathogen reduction technology mandates from the FDA are compressing manufacturing timelines while elevating capital requirements, forcing producers to choose between retrofitting legacy fractionation lines or constructing greenfield facilities compliant with emerging viral inactivation standards.
Growth Catalysts
- Trauma Resuscitation Protocols:Hospital emergency departments in the United States and Germany are expanding plasma transfusion volumes for hemorrhagic shock management, driving demand for thawed plasma and cryoprecipitate inventories.
- EMA Plasma Master File Framework:European import qualification requirements are standardizing traceability documentation across member states, reducing cross-border supply friction for fractionated products.
- Apheresis Collection Efficiency:Automated plateletpheresis systems are displacing whole-blood-derived platelet units in Japan and South Korea, improving yield per donor and reducing bacterial contamination risk.
Market Restraints
- Plasma Supply Concentration:The United States supplies over sixty percent of global source plasma, creating geopolitical and pandemic-disruption exposure for fractionators dependent on American donor centers.
- Albumin Price Volatility:Chinese hospital procurement reforms are compressing albumin reimbursement rates, pressuring margin structures for plasma-derived protein manufacturers.
- Recombinant Substitution:Engineered clotting factors VIII and IX are displacing plasma-derived equivalents in hemophilia prophylaxis, threatening volume in the highest-margin therapeutic category.
Strategic Opportunities
- Indian National Blood Policy Expansion:WHO Global Benchmarking Tool assessments are steering federal investment toward centralized blood banking infrastructure in tier-two cities with underdeveloped cold-chain networks.
- Subcutaneous Immunoglobulin Formulations:Home-administration delivery systems are converging with patient preference for outpatient therapy, opening ambulatory channels previously dominated by hospital infusion centers.
- Brazilian ANVISA Harmonization:Alignment with ICH viral safety guidelines is accelerating import approval timelines for pathogen-reduced products, reducing time-to-market for international suppliers.
Industry Challenges
- Fractionation Specialist Scarcity:Protein purification and viral inactivation expertise remains concentrated among retiring cohorts in European and North American facilities, constraining technology transfer to emerging-market manufacturing sites.
- Legacy IT Integration:Donor deferral registries and production batch records across CSL, Grifols, and Takeda operate on incompatible data architectures, complicating merger integration and supply-chain visibility.
- Pathogen Reduction Validation Timelines:FDA chemistry, manufacturing, and controls reviews for solvent-detergent and amotosalen systems extend eighteen to thirty-six months, delaying product launches and freezing capital in pre-revenue assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blood Product Market |
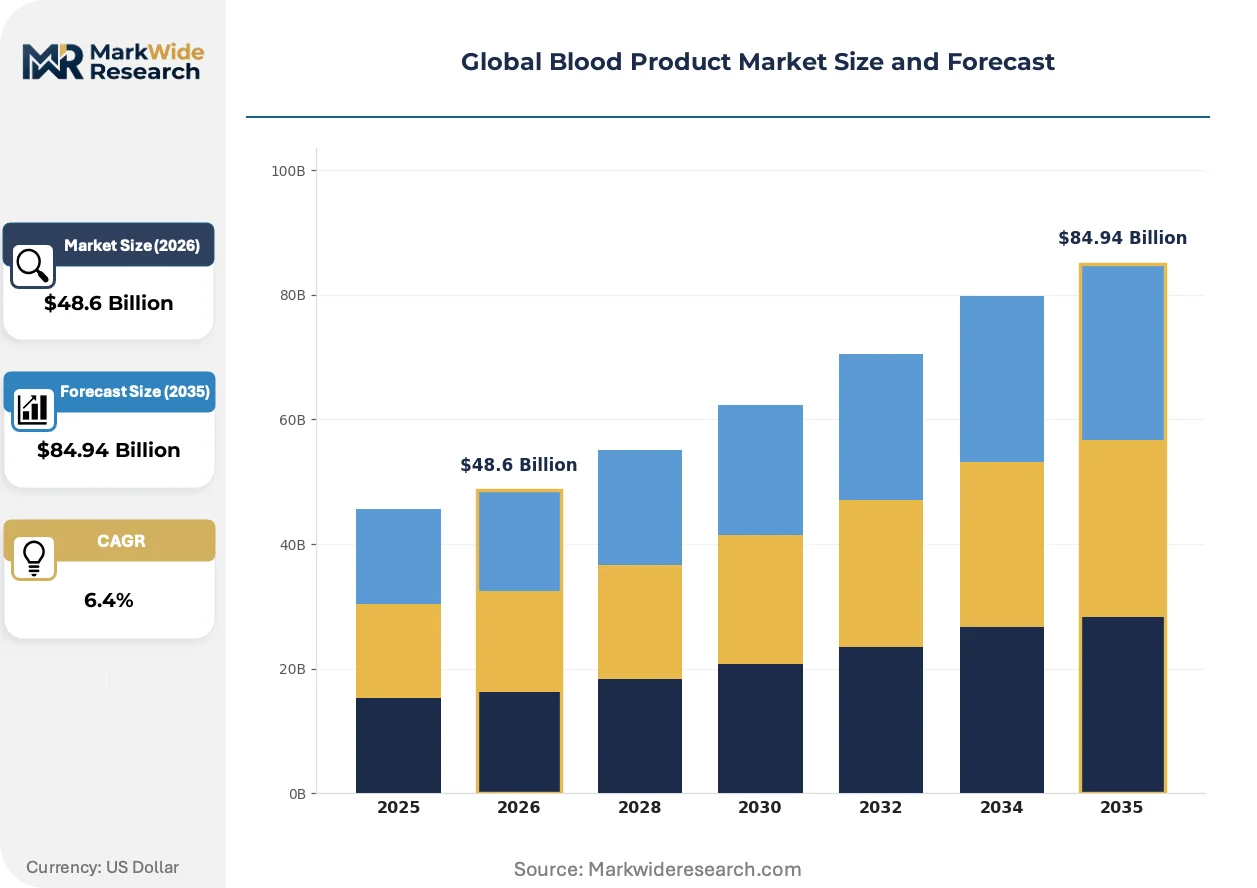
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $84.94 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Blood, Plasma, Platelets, Cryoprecipitate, Red Blood Cells Application: Trauma Care, Surgical Procedures, Anemia Treatment, Hemophilia Management, Immunotherapy End User: Hospitals, Blood Banks, Research Laboratories, Clinics, Specialized Care Centers Delivery Mode: Direct Donation, Apheresis, Synthetic Production, Frozen Storage, Lyophilized Formulations |
| Companies Covered | CSL Limited, Grifols S.A., Takeda Pharmaceutical Company Limited, Octapharma AG, Baxter International Inc., Kedrion S.p.A., Bio-Rad Laboratories, Inc., Haemonetics Corporation, LFB Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blood Product Market Shifts & Advancements
Manufacturing automation and regulatory science are compressing production cycles while safety-assurance technologies are becoming the primary basis for procurement decisions rather than unit economics alone.
Interferon-free pathogen inactivation systems are converging with continuous processing fractionation architectures to enable real-time viral safety verification. German and Austrian plasma processors are piloting these integrated lines for immunoglobulin production. This convergence is compressing batch release timelines from ninety days to under forty-five days while reducing solvent-detergent reagent costs.
REACH registration requirements for process chemicals used in plasma fractionation are elevating documentation burdens for European manufacturers. The European Chemicals Agency's 2024 updates to substance evaluation criteria are forcing reformulation of stabilizing agents in albumin and factor concentrates. Small-volume fractionators in Italy and Spain are exiting the market rather than absorbing compliance costs, concentrating supply among integrated multinationals.
Hospital blood banks are consolidating vendor relationships from multi-supplier models to dual-source frameworks with safety-technology mandates. Academic medical centers in the United States and university hospitals in Japan are requiring nucleic acid testing and pathogen reduction dual certification as minimum qualification criteria. This concentration is visible most acutely in trauma center networks across Texas, Florida, and California, where procurement committees now prioritize inventory standardization over price competition.
Global Blood Product Market Segmentation
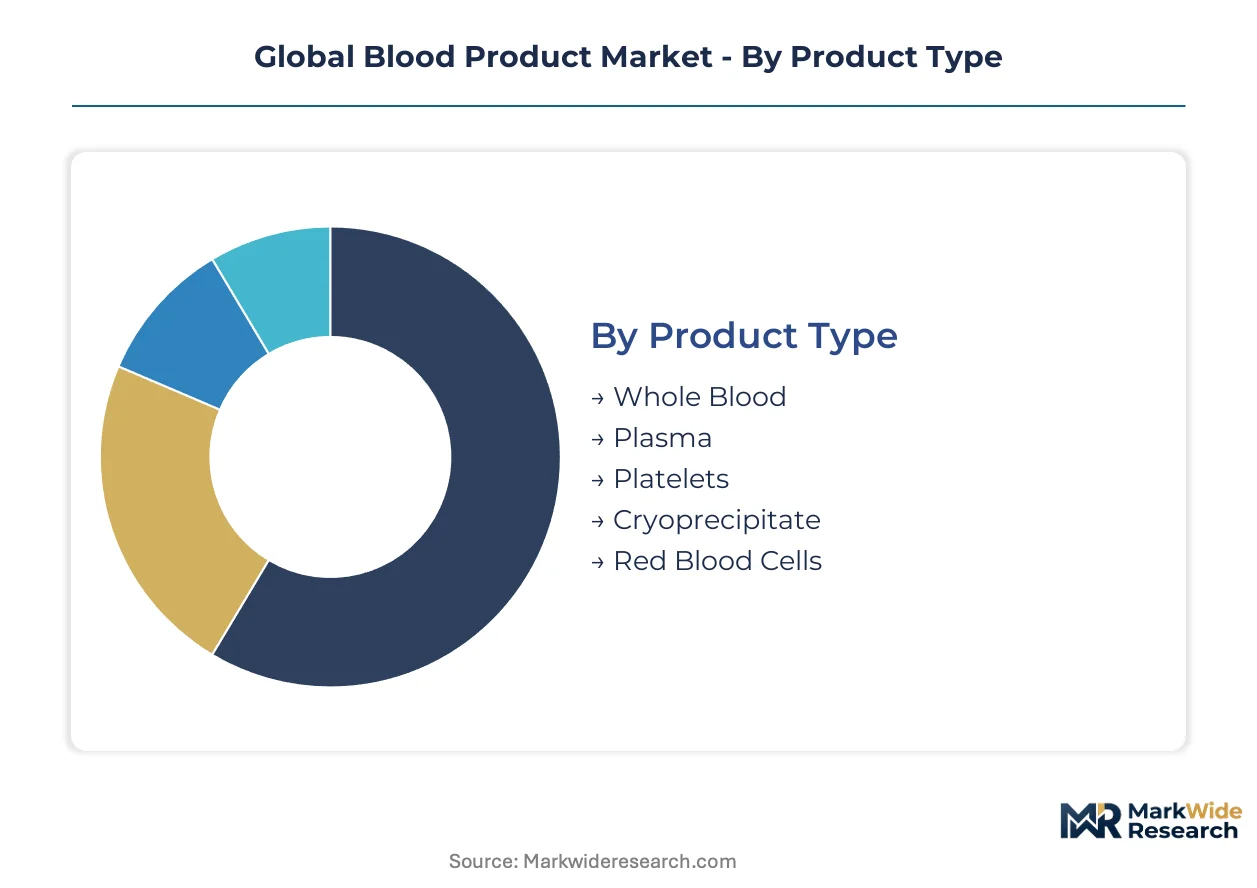
Blood product segmentation reveals how procurement priorities diverge across clinical settings and therapeutic requirements. Hospital buyers weigh shelf-life stability against viral safety certification, while fractionators optimize collection methods for yield and donor compliance.
Product Type:
Buyers in this category differentiate by therapeutic urgency and processing complexity rather than unit cost alone.
- Plasma:Source material for fractionated proteins including albumin, immunoglobulins, and clotting factors. Demand concentrates in United States trauma centers and German university hospitals prioritizing pathogen-reduced inventories for hemorrhagic shock protocols.
- Platelets:Apheresis-derived concentrates with 5-7 day shelf life. Cancer chemotherapy expansion in Japan and South Korea drives volume, with bacterial contamination risk reduction becoming a procurement mandate.
- Whole Blood:Unseparated units for massive transfusion protocols in military and rural emergency settings.
- Cryoprecipitate:Fibrinogen-rich fraction for hypofibrinogenemia and surgical bleeding.
- Red Blood Cells:Leukoreduced units for chronic transfusion-dependent anemia and surgical support.
Plasma leads volumes today; platelets are gaining share fastest.
Application:
Therapeutic use cases separate high-acuity emergency demand from chronic maintenance dosing schedules.
- Trauma Care:Massive transfusion protocols deploy plasma, platelets, and red cells in fixed ratios. United States Level I trauma centers in Texas and California stock thawed plasma for immediate availability.
- Hemophilia Management:Factor VIII and IX replacement for prophylaxis and bleed control. Recombinant substitution threatens plasma-derived volume in this high-margin category.
- Surgical Procedures:Perioperative hemostasis support across cardiac, orthopedic, and transplant specialties.
- Anemia Treatment:Red cell transfusion for chemotherapy-induced and chronic kidney disease-related cytopenias.
- Immunotherapy:Intravenous and subcutaneous immunoglobulin for primary immunodeficiency and autoimmune neuropathies.
Trauma care commands the largest emergency volumes; immunotherapy shows the steepest expansion trajectory.
End User:
Procurement authority and inventory risk tolerance vary sharply across institutional types.
- Hospitals:Integrated health systems with centralized blood banks negotiate multi-year contracts. Academic medical centers in Germany and Japan require dual pathogen reduction and nucleic acid testing certification.
- Blood Banks:Regional collection and distribution hubs managing donor recruitment and component processing under FDA or EMA oversight.
- Specialized Care Centers:Hemophilia treatment centers and immune deficiency clinics with dedicated pharmacy infrastructure for home-based therapy.
- Clinics:Outpatient transfusion services for stable chronic anemia patients.
- Research Laboratories:Cell therapy and regenerative medicine applications using leukoreduced and irradiated units.
Hospitals absorb the majority of transfusion volume; specialized care centers are expanding fastest as home administration protocols mature.
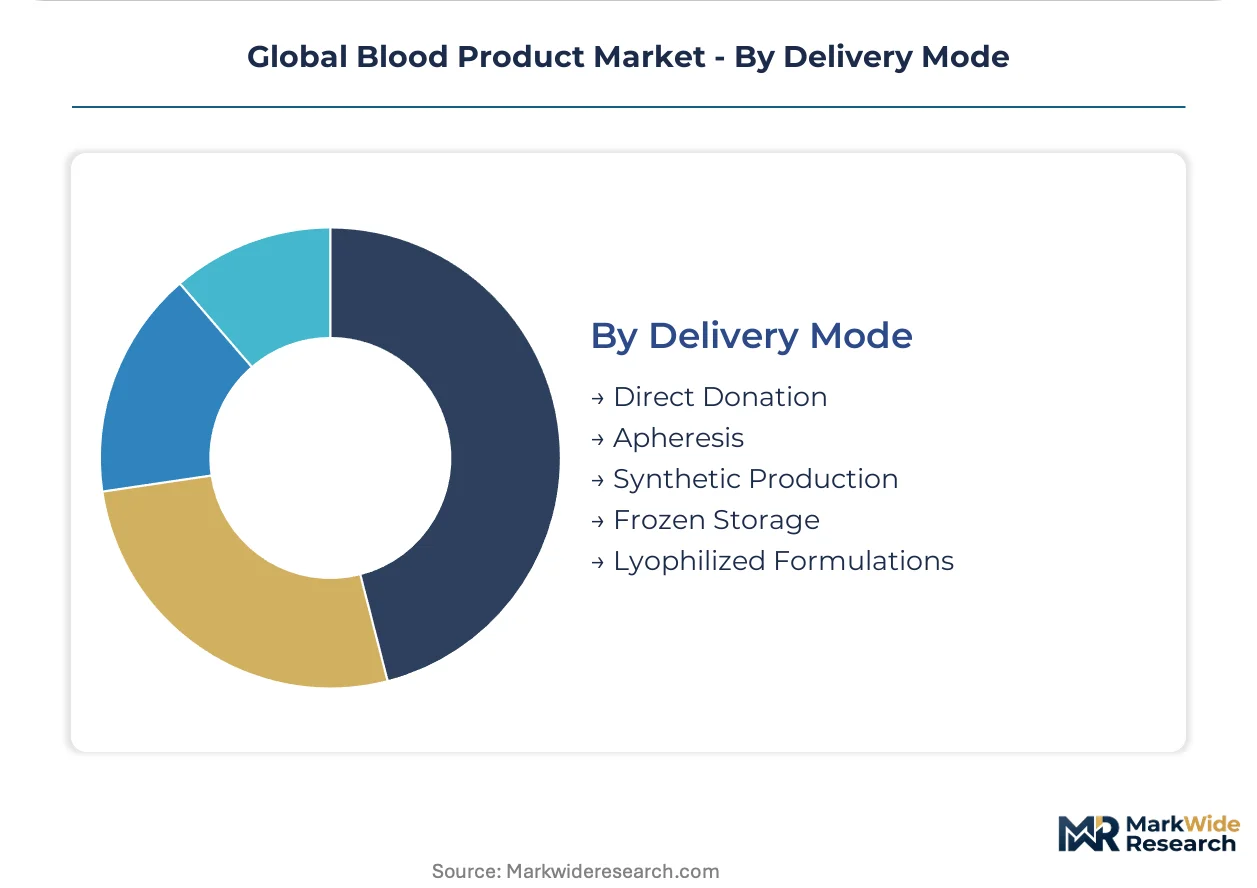
Delivery Mode:
Collection and preservation technology determines supply security and geographic reach.
- Apheresis:Automated collection yields higher platelet and plasma volumes per donor session. Japanese and South Korean networks have converted majority platelet supply to this method.
- Frozen Storage:Plasma and cryoprecipitate preservation extends shelf life to 12 months, enabling inventory buffering and military logistics.
- Direct Donation:Whole blood collection for immediate component separation remains dominant in emerging market blood systems.
- Lyophilized Formulations:Freeze-dried plasma and factor concentrates for field medicine and stockpile resilience.
- Synthetic Production:Recombinant clotting factors and albumin alternatives manufactured without human donors.
Apheresis dominates platelet and plasma collection; lyophilized formulations are climbing fastest for strategic stockpile and remote deployment applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasma collection specialists concentrate in the United States and Germany, while fractionation chemists cluster in Austrian and Swiss processing hubs. This workforce geography shapes where pathogen-reduction technologies achieve regulatory clearance first.
United States
Trauma resuscitation protocols at Level I centers in Texas and California drive thawed plasma inventory builds. FDA pathogen reduction guidance mandates are accelerating retrofit timelines for domestic fractionators. The Dallas-Fort Worth metro anchors the country's largest apheresis collection network, with donor centers expanding into secondary markets.
Germany
University hospitals in Bavaria and North Rhine-Westphalia require dual nucleic acid testing and pathogen reduction certification for all plasma-derived inventories. EMA Plasma Master File standardization reduces cross-border supply friction for Frankfurt and Munich-based distributors. The Heidelberg-Mannheim corridor hosts concentrated viral inactivation research capacity.
Japan
Automated plateletpheresis conversion reached majority share in Tokyo and Osaka metropolitan networks, displacing whole-blood-derived units. METI reimbursement frameworks favor bacterial detection technologies alongside pathogen reduction. The Kansai region's cancer chemotherapy expansion drives apheresis platelet demand growth.
India
WHO Global Benchmarking Tool assessments are steering federal investment toward centralized blood banking in tier-two cities with underdeveloped cold-chain infrastructure. CDSCO import qualification pathways are harmonizing with ICH viral safety standards for international suppliers. Maharashtra and Karnataka are prioritizing donor recruitment and testing infrastructure upgrades.
Brazil
ANVISA alignment with ICH viral safety guidelines is compressing import approval timelines for pathogen-reduced products. São Paulo's hospital networks are consolidating vendor relationships around safety-technology mandates rather than unit price. The Southeast region's academic medical centers are requiring nucleic acid testing certification as minimum qualification criteria.
Global Blood Product Market Competitive Landscape
Capital-heavy fractionators with captive plasma collection networks compete with asset-light specialty distributors focused on hospital logistics and cold-chain delivery. The vendor base concentrates among integrated multinationals with vertical control over donor recruitment through finished product release. Three archetypes dominate: plasma collection integrators with continental donor center footprints, recombinant protein specialists substituting engineered factors for plasma-derived equivalents, and regional blood system operators managing national inventory pools. Competitive moves center on M&A consolidation of donor center networks and greenfield fractionation capacity compliant with emerging viral inactivation standards.
Among integrated plasma processors, CSL Limited, Grifols S.A., and Takeda Pharmaceutical Company Limited occupy positions exemplifying collection-scale leverage. CSL Limited represents the vertically integrated archetype with multi-continental donor access. Grifols S.A. sits within the high-volume immunoglobulin tier. Takeda Pharmaceutical Company Limited anchors the hemophilia therapy concentration. These three names from the raw data illustrate how geographic donor base breadth and therapeutic portfolio focus differentiate competitive positioning without requiring specific operational claims.
| Leading Market Players |
|---|
| CSL Limited |
| Grifols S.A. |
| Takeda Pharmaceutical Company Limited |
| Octapharma AG |
| Baxter International Inc. |
| Kedrion S.p.A. |
| Bio-Rad Laboratories, Inc. |
| Haemonetics Corporation |
| LFB Group |
| Others |
Supply & Pricing Matrix
Academic medical centers in the United States and university hospitals in Japan concentrate procurement authority through multi-year safety-technology contracts rather than spot-market bidding. This buyer concentration elevates pathogen-reduced plasma products to premium pricing tiers while compressing margins for commodity whole-blood units lacking viral inactivation certification.
Pricing Analysis
Unbundled per-unit pricing for source plasma and apheresis platelets competes with bundled service contracts incorporating cold-chain logistics and inventory management. Three-tier pricing structure across pathogen-reduced, nucleic-acid-tested, and standard inventory levels separates academic medical center procurement from community hospital buying. Cost compression in Chinese albumin markets stems from centralized hospital procurement reforms. Community hospitals and rural emergency departments exhibit the highest price sensitivity, while trauma centers and hemophilia treatment centers prioritize safety certification over unit cost.
Supply Chain Analysis
FDA pathogen reduction qualification and EMA Plasma Master File certification gate access to hospital procurement lists in the United States and Germany. Plasma collection concentrates in the United States, Germany, and Austria, with fractionation chemistry anchored in Swiss and Austrian processing hubs. The supply chain draws from apheresis collection equipment, viral inactivation reagents, and cold-chain logistics infrastructure. Single-source vulnerability in United States plasma supply creates geopolitical exposure. Distribution runs through regional blood bank networks and specialized cold-chain distributors serving hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as hospital procurement committees shift from cost-minimization to safety-assurance criteria, elevating pathogen-reduced and nucleic-acid-tested inventory tiers.
For Market Incumbents: Lock in donor center network exclusivity through long-term collection agreements in Texas, Florida, and California metro corridors. Recombinant factor substitution threatens plasma-derived hemophilia therapy volumes, necessitating backward integration into pathogen-reduction technology licensing and captive fractionation capacity expansion in FDA-compliant jurisdictions. For New Entrants and Emerging Players: ANVISA alignment with ICH viral safety guidelines in Brazil opens a window for import qualification of pathogen-reduced products. Tier-two Indian cities with underdeveloped cold-chain infrastructure offer the most penetrable geographic white space. Target subcutaneous immunoglobulin home-administration channels through partnerships with specialized care center pharmacy infrastructure. For Investors and Strategic Acquirers: Integrated plasma processors with multi-continental donor footprints are the most active acquirer in this space, consolidating regional blood bank networks to secure raw material access. The five-to-ten year viability window favors fractionators with greenfield pathogen-reduction-compliant capacity over legacy retrofit-dependent competitors. Watch FDA chemistry manufacturing and controls review timelines as the signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Pathogen Reduction Technology Licensing | FDA and EMA dual certification unlocks access to academic medical center procurement committees. |
| Apheresis Collection Network Expansion | Automated plateletpheresis yield advantages displace whole-blood-derived units in Japanese metropolitan networks. |
| Subcutaneous Immunoglobulin Formulation Development | Home-administration delivery systems open ambulatory channels previously dominated by hospital infusion centers. |
| Plasma Master File Harmonization | EMA standardization reduces cross-border supply friction for Frankfurt and Munich-based distributors. |
| Lyophilized Product Portfolio Expansion | Freeze-dried plasma and factor concentrates address military and remote deployment applications with extended shelf stability. |
Research Methodology
Direct dialogue with blood bank operations directors, hospital transfusion medicine chiefs, plasma fractionation technical leads, and regulatory affairs specialists at FDA and EMA provides qualitative grounding for demand and compliance dynamics. Secondary validation draws from FDA guidance documents, EMA Plasma Master File submissions, WHO Global Benchmarking Tool assessments, and hospital procurement database records. Bottom-up and top-down triangulation cross-checks donor center capacity estimates against fractionation output projections.
Bottom-up modeling segments volume and value across product type, application, end user, and delivery mode dimensions throughout the forecast period. CAGRs derive from trajectory analysis of trauma resuscitation protocol adoption, apheresis collection efficiency improvements, and pathogen-reduction technology penetration curves. Forecast inputs incorporate plasma supply concentration metrics, albumin reimbursement rate trends in Chinese hospital systems, and recombinant factor substitution rates in hemophilia prophylaxis.
Revisions become necessary when FDA pathogen reduction mandate timelines shift, EMA substance evaluation criteria force reformulation of stabilizing agents, or pandemic disruption alters United States donor center operations. Forecasts reflect assumptions about regulatory compliance timelines and hospital procurement committee criteria evolution. A model refresh is warranted upon material change in FDA chemistry manufacturing and controls review duration or EMA Plasma Master File acceptance rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
US Generic Drug Market
Biopharmaceuticals
Global Kinase Inhibitors Market
Biopharmaceuticals
Penicillin G Acylase Market
Biopharmaceuticals
Insulin Secretagogues Market
Biopharmaceuticals
Anti-Neprilysin Market
Biopharmaceuticals
East Africa Generic Drug Market
Biopharmaceuticals
Asia-Pacific Plant-Based Biologics Market
Biopharmaceuticals
Lupus Nephritis Market
Biopharmaceuticals
Oncology Drugs Market
Biopharmaceuticals
Iran Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Biological Drugs Market
Biopharmaceuticals
Sezary Syndrome Market
Biopharmaceuticals
Global Insulin Glargine Market
Biopharmaceuticals
Oligonucleotide API Market
Biopharmaceuticals
NF-KB Inhibitors Market
Biopharmaceuticals
Tuberculosis Drugs Market