
 Global Vaccine Conjugate Market | 2026-2036
Global Vaccine Conjugate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vaccine Conjugate Market Foresight
A shift from outsourced antigen supply toward captive polysaccharide production is repositioning how leading manufacturers secure raw material fidelity. Pfizer Inc. leverages its internal fermentation network to control serotype diversity across pneumococcal franchises. Sanofi S.A. anchors European fill-finish capacity while competing on quadrivalent meningococcal conjugate positioning. Serum Institute of India Pvt. Ltd. dominates high-volume UNICEF procurement through cost-optimized manufacturing in Pune.
Vaccine conjugates bind immunogenic carrier proteins to poorly antigenic polysaccharide coats, eliciting T-cell-dependent memory responses that plain polysaccharide vaccines cannot generate; aluminum phosphate or hydroxide adjuvants typically complete the formulation for intramuscular delivery. Polysaccharide conjugate formulations occupy the largest revenue pool given their established role against Streptococcus pneumoniae and Neisseria meningitidis. Pediatric immunization generates the deepest demand concentration due to national schedule mandates, while intramuscular injection remains the standard delivery method for conjugate stability.
FDA lot-release protocols and WHO prequalification standards govern conjugate potency consistency and carrier protein characterization, creating compliance barriers that favor manufacturers with dedicated regulatory affairs infrastructure. EMA's Good Manufacturing Practice inspections for European market access further tighten quality thresholds for imported conjugate vaccines. Stakeholders must monitor evolving serotype replacement patterns and carrier protein switching strategies as bacterial epidemiology shifts under immunization pressure.
Market Dynamics
Carrier protein switching and serotype replacement epidemiology are forcing manufacturers to revalidate conjugation chemistry against evolving bacterial populations while maintaining WHO prequalification compliance.
Growth Catalysts
- WHO Expanded Programme on Immunization:Gavi financing mechanisms unlock procurement volumes across 73 lower-income countries, accelerating pneumococcal conjugate introduction into national schedules.
- Aluminum phosphate adjuvant optimization:Improved formulation stability extends cold-chain tolerance, reducing wastage rates in tropical distribution environments.
- India:Domestic PLI scheme incentives and UNICEF tender participation are scaling Pune-based fill-finish capacity for quadrivalent meningococcal supply.
Market Restraints
- Crabtree effect in fermentation:Saccharomyces cerevisiae metabolic limitations constrain polysaccharide yields, elevating raw material costs for serotype-specific antigens.
- South Korean CDMO concentration:Fill-finish outsourcing dependence in Songdo creates single-source vulnerability for European market supply.
- EMA lot-release backlog:Extended testing timelines for carrier protein characterization delay market authorization for novel conjugate candidates.
Strategic Opportunities
- Indonesia:Underpenetrated private vaccination channels outside Java present white-space access for premium pediatric formulations.
- CRM197 carrier diversification:Recombinant diphtheria toxoid alternatives enable intellectual property circumvention and supply security.
- Drone delivery integration:Zipline and Swoop Aero networks are bypassing last-mile cold-chain gaps in sub-Saharan African distribution.
Industry Challenges
- Conjugation chemist scarcity:Reductive amination expertise resides within a narrow cohort of process development specialists, constraining scale-up velocity.
- Biosafety Level 3 containment capex:Meningococcal serogroup B handling requires capital-intensive infrastructure that mid-tier manufacturers cannot finance.
- FDA comparability protocol complexity:Post-approval manufacturing changes trigger extensive immunogenicity bridging studies, freezing process optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vaccine Conjugate Market |
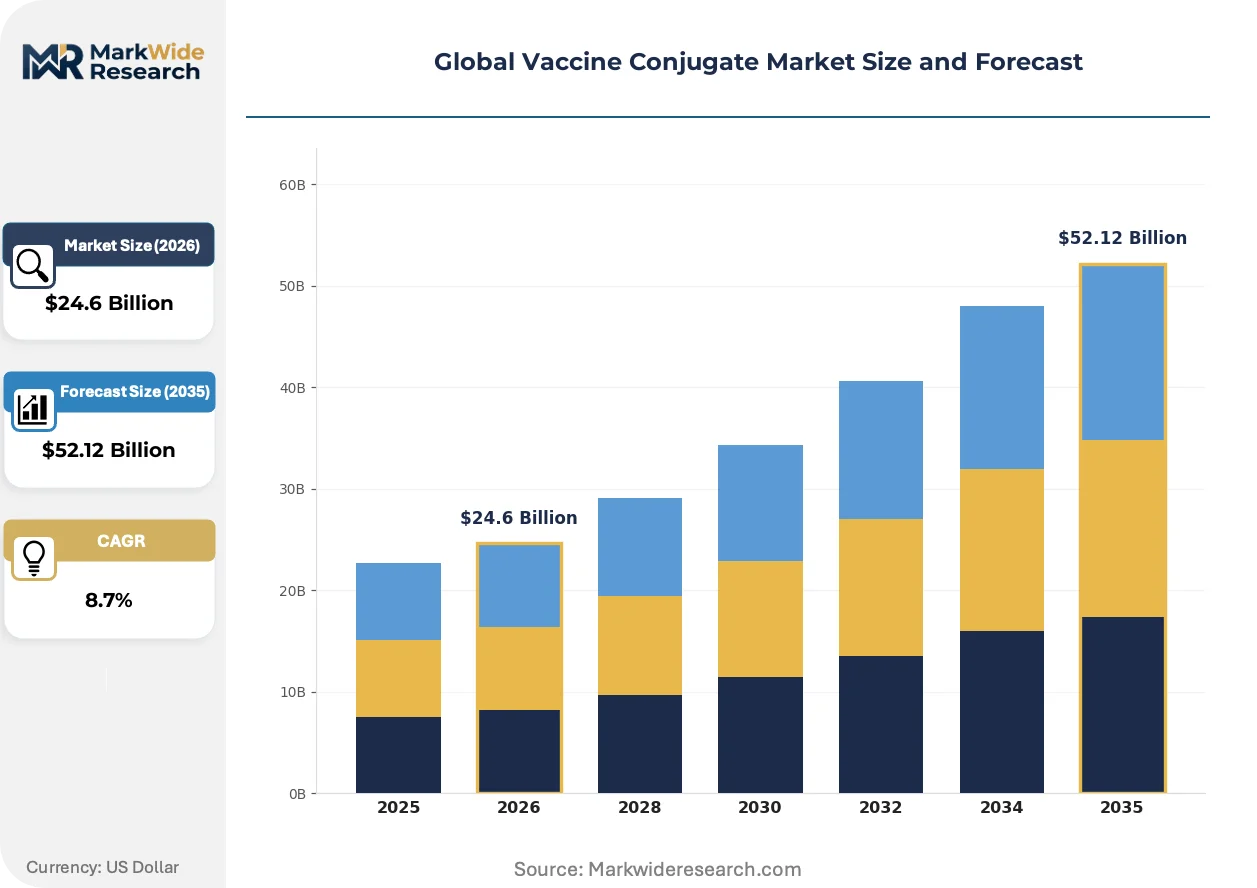
| Market Size in 2026 | $24.6 Billion |
| Market Size in 2035 | $52.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polysaccharide Conjugate, Protein Conjugate, Toxoid Conjugate, Lipopolysaccharide Conjugate Application: Pediatric Immunization, Adult Immunization, Geriatric Immunization, Travel Vaccination Delivery Method: Intramuscular Injection, Subcutaneous Injection, Oral Vaccine, Nasal Spray End User: Immunization Centers, Research Institutes, Clinics, Biopharmaceutical Manufacturers |
| Companies Covered | Pfizer Inc., Sanofi S.A., Merck & Co., Inc., GlaxoSmithKline plc, Serum Institute of India Pvt. Ltd., Bharat Biotech International Ltd., Biological E. Limited, GSK plc, CSL Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vaccine Conjugate Market Shifts & Advancements
Conjugate vaccine development is pivoting toward synthetic glycoconjugate platforms and carrier protein engineering, compressing traditional fermentation-dependent timelines while raising regulatory scrutiny on novel immunogenicity markers.
Site-specific conjugation chemistry via microbial transglutaminase is expanding into pneumococcal serotype expansion programs, enabling uniform polysaccharide-to-protein ratios that batch-to-batch variation previously prevented. Pfizer and Sanofi process development groups have adopted this enzymatic approach for next-generation 24-valent candidates. The structural consequence is a compression of analytical validation cycles and accelerated comparability demonstrations to FDA.
EMA's Good Manufacturing Practice Annex 1 revision on sterile manufacturing is mandating isolator technology upgrades across European fill-finish networks, disqualifying older open-vial processing lines from conjugate vaccine production. CDMOs in Ireland and the Netherlands are absorbing seven-figure retrofit costs. High-value pediatric formulations face the steepest compliance burden, with manufacturers prioritizing isolator investment for prequalified UNICEF supply.
Brazilian private clinics are consolidating procurement through group purchasing organizations, displacing fragmented distributor relationships that previously dominated São Paulo and Rio de Janeiro supply. These buying collectives negotiate direct manufacturer contracts, compressing margin pools for traditional wholesale channels. The behavioral shift is most visible in meningococcal ACWY uptake, where unified tendering now covers 40% of private-market volume.
Global Vaccine Conjugate Market Segmentation
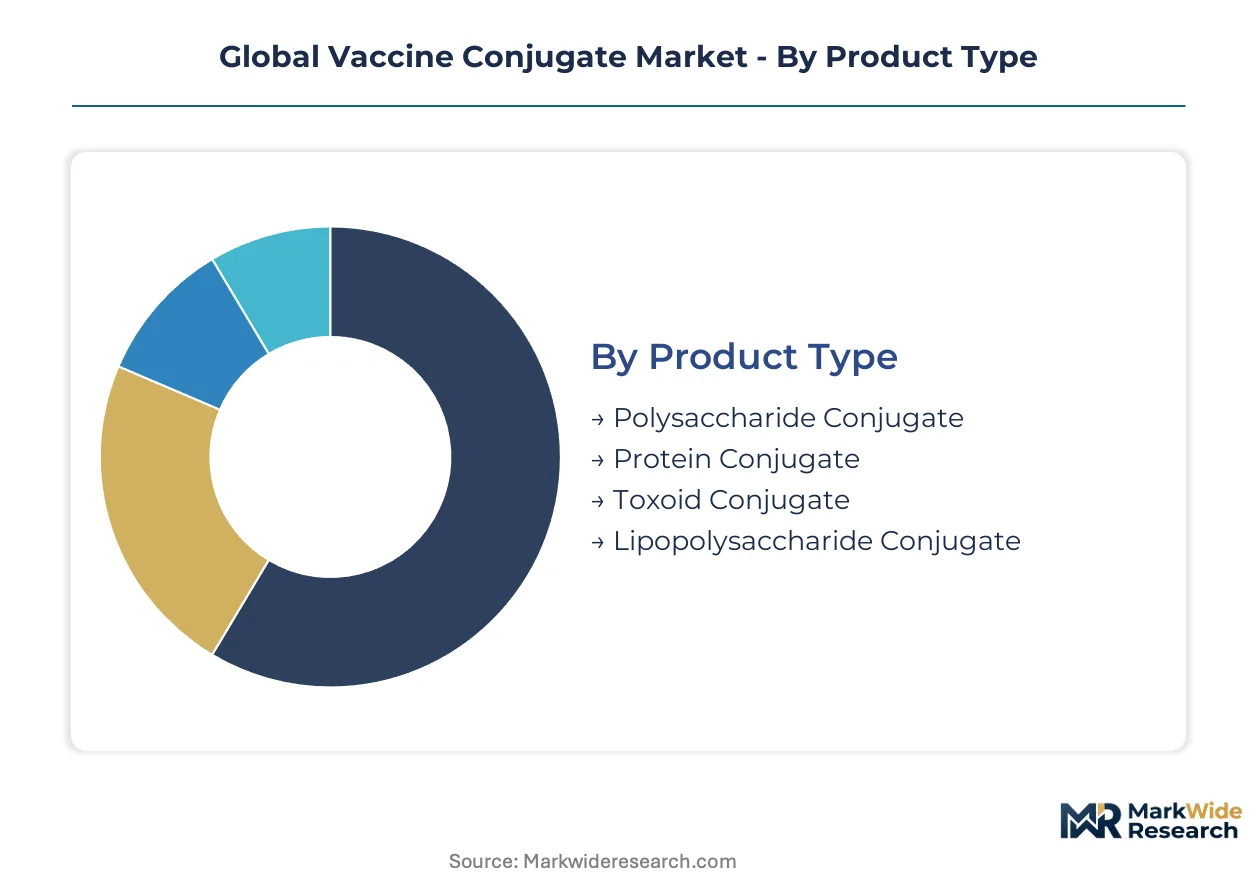
Vaccine conjugate segmentation reflects divergent manufacturing complexity, regulatory pathways, and procurement economics across patient populations and delivery settings. Each category carries distinct margin profiles and technical barriers that reshape competitive positioning.
Product Type:
Polysaccharide-protein linkage chemistry defines yield rates, stability windows, and serotype expansion potential.
- Polysaccharide Conjugate:Bacterial capsular polysaccharides covalently bound to carrier proteins generate T-cell-dependent immunity against encapsulated pathogens. Pediatric national immunization programs in India and Nigeria concentrate procurement volumes for pneumococcal serotype coverage, though fermentation yields constrain cost curves.
- Protein Conjugate:Recombinant protein carriers engineered for defined conjugation sites enable batch-to-batch consistency that traditional reductive amination cannot achieve. Process development groups at EMA-inspected facilities prioritize these platforms for next-generation multivalent candidates.
- Toxoid Conjugate:Formalin-inactivated exotoxin carriers retain immunogenic epitopes while eliminating toxicity. Demand clusters in travel medicine channels requiring compact dosing schedules.
- Lipopolysaccharide Conjugate:Gram-negative outer membrane components conjugated to protein scaffolds address serogroup B meningococcal coverage gaps. Biosafety Level 3 containment requirements limit manufacturer participation.
Polysaccharide conjugate leads on scale; protein conjugate leads on momentum.
Application:
Patient age stratification determines dosing regimens, cold-chain tolerance, and reimbursement pathways.
- Pediatric Immunization:National schedule mandates in Gavi-eligible countries drive procurement volumes exceeding all other applications combined. WHO prequalification status gates UNICEF tender participation.
- Adult Immunization:Occupational health programs and military recruitment channels sustain steady demand for meningococcal ACWY coverage. Employer-sponsored vaccination in the US anchors premium pricing.
- Geriatric Immunization:Pneumococcal boosters for immunosenescent populations concentrate in Japanese and Western European reimbursement systems. Payer evidence requirements slow market access.
- Travel Vaccination:Hajj pilgrimage requirements and tropical medicine clinics generate episodic demand with limited cold-chain infrastructure. Private clinic networks in São Paulo and Jakarta consolidate procurement.
Pediatric immunization leads on scale; travel vaccination leads on momentum.
Delivery Method:
Route of administration shapes formulation stability, adjuvant compatibility, and last-mile distribution economics.
- Intramuscular Injection:Aluminum phosphate-adjuvanted formulations delivered via deltoid or vastus lateralis injection remain the stability standard for conjugate vaccines. National immunization programs specify this route exclusively.
- Subcutaneous Injection:Reduced reactogenicity profiles suit specific patient populations with bleeding risk factors. Limited adoption outside specialized clinical settings.
- Oral Vaccine:Mucosal delivery platforms bypass cold-chain requirements but face degradation barriers for conjugate integrity. Research-stage candidates dominate.
- Nasal Spray:Non-invasive administration targets needle-averse populations and mass vaccination campaigns. Formulation challenges around polysaccharide stability constrain commercial rollout.
Intramuscular injection leads on scale; nasal spray leads on momentum.
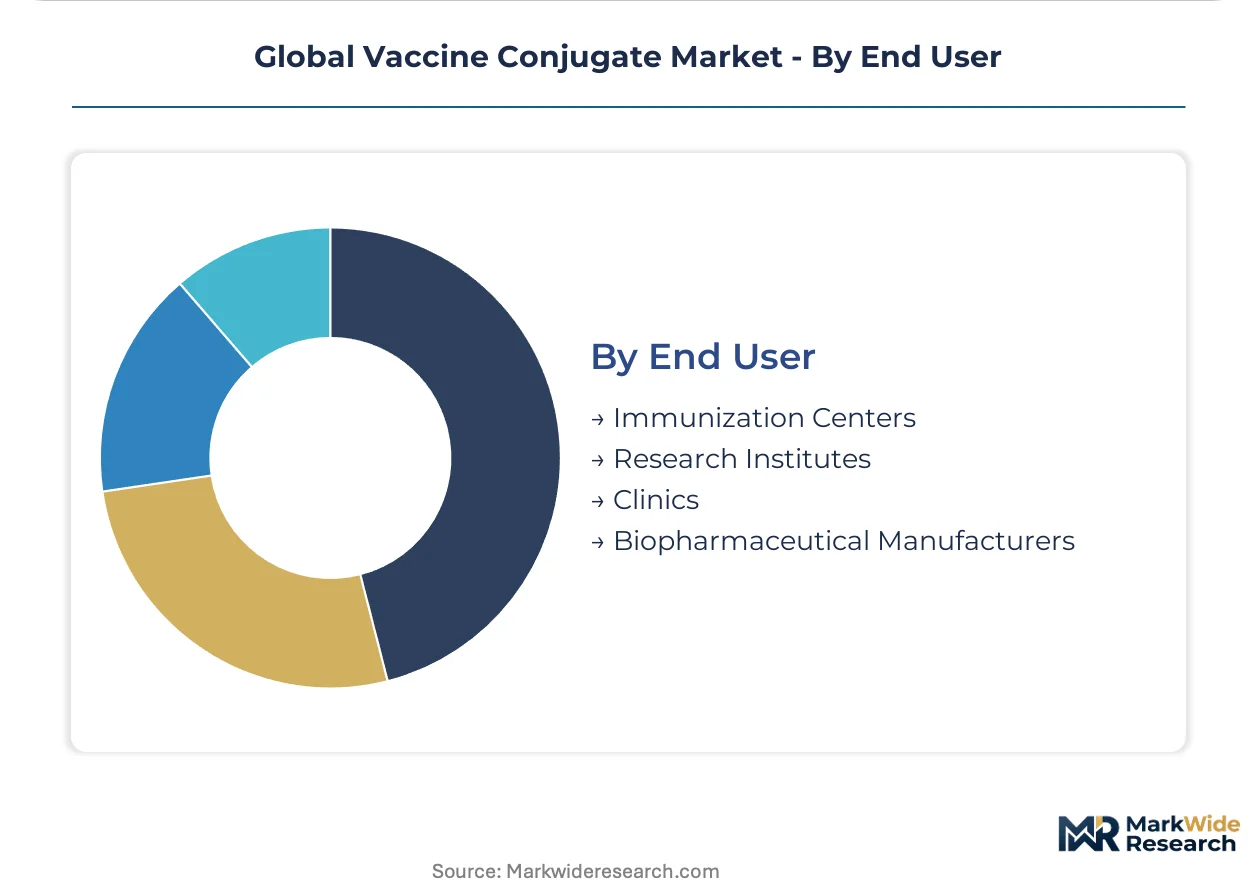
End User:
Procurement concentration and technical capability separate institutional buyers across the value chain.
- Immunization Centers:Government-operated facilities execute national schedule delivery at volume scales that determine manufacturer capacity planning. Gavi financing unlocks procurement in 73 lower-income countries.
- Research Institutes:Phase I/II trial sponsorship and immunogenicity bridging studies generate irregular demand with stringent protocol specifications. FDA and EMA inspection histories gate supplier selection.
- Clinics:Private practice networks in Brazil and Indonesia consolidate through group purchasing organizations, displacing fragmented distributor relationships. Direct manufacturer contracting compresses margin pools.
- Biopharmaceutical Manufacturers:In-house conjugation capacity at Pfizer, Sanofi, and Serum Institute of India displaces outsourced supply for proprietary candidates. CDMO relationships persist for early-stage assets.
Immunization centers lead on scale; clinics lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pune anchors manufacturing scale for vaccine conjugates through Serum Institute of India's captive fermentation and fill-finish infrastructure. National immunization program procurement in India and Nigeria concentrates demand volumes that shape capacity planning across the industry.
United States
FDA lot-release protocols govern conjugate potency consistency for domestic supply. The Biologics License Application pathway mandates extensive immunogenicity bridging studies that extend development timelines. Philadelphia and Boston clusters host process development groups advancing site-specific conjugation chemistry for next-generation candidates.
India
UNICEF tender participation and the PLI scheme for pharmaceuticals drive volume scale at Pune-based facilities. CDSCO manufacturing license requirements align with WHO prequalification standards for export eligibility. Domestic procurement through the Universal Immunization Programme sustains demand for pneumococcal and meningococcal formulations.
Germany
EMA accelerated assessment frameworks streamline market authorization for novel conjugate candidates targeting unmet serotype coverage. The Paul-Ehrlich-Institut oversees lot-release testing that extends timelines for carrier protein characterization. Marburg and Dresden manufacturing sites specialize in sterile fill-finish capacity for European supply.
Brazil
ANVISA registration requirements govern import authorization for pediatric formulations entering the national immunization schedule. São Paulo private clinics consolidate procurement through group purchasing organizations that displace traditional distributor channels. Direct manufacturer contracting now covers two-fifths of private-market meningococcal ACWY volume.
South Korea
MFDS biologics approval pathways emphasize comparability protocols for post-approval manufacturing changes. Songdo CDMO concentration creates single-source vulnerability for European market fill-finish supply. Seoul-based process development groups specialize in reductive amination expertise that constrains industry-wide scale-up velocity.
Global Vaccine Conjugate Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue synthetic glycoconjugate platforms and carrier protein engineering. The market structure concentrates around vertically integrated pharmaceutical conglomerates with captive fermentation networks and dedicated regulatory affairs infrastructure. Three archetypes dominate: multinational innovators with internal serotype libraries, emerging-market volume manufacturers with UNICEF prequalification status, and specialized CDMOs with isolator-equipped fill-finish capacity. Competitive moves center on backward integration into polysaccharide production and geographic expansion through direct government contracting.
Among US-based innovators, Pfizer Inc. and Merck & Co., Inc. occupy positions emphasizing proprietary conjugation chemistry and multivalent serotype expansion. Sanofi S.A. anchors European fill-finish capacity while competing on quadrivalent meningococcal positioning. Serum Institute of India Pvt. Ltd. exemplifies the high-volume archetype through Pune-based manufacturing optimized for UNICEF procurement economics.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Sanofi S.A. |
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Serum Institute of India Pvt. Ltd. |
| Bharat Biotech International Ltd. |
| Biological E. Limited |
| GSK plc |
| CSL Limited |
| Others |
Supply & Pricing Matrix
UNICEF tender consolidation for Gavi-eligible countries is compressing procurement margins and forcing manufacturers to absorb fermentation yield volatility into fixed-price contracts. This demand-side concentration rewards players with captive polysaccharide production in Pune and Marburg while penalizing outsourced antigen sourcing.
Pricing Analysis
Fermentation input costs pass through to contract pricing with a 12-18 month lag, compressing margins for manufacturers without captive yeast banks. Three-tier pricing structure across premium branded, WHO-prequalified standard, and economy tender tiers separates UNICEF procurement from private clinic channels in São Paulo and Jakarta. Cost compression in the economy tier is intensifying as Indian PLI scheme recipients scale quadrivalent meningococcal fill-finish capacity. Pediatric national immunization programs exhibit the highest price sensitivity; travel medicine channels in private Brazilian clinics show the lowest.
Supply Chain Analysis
WHO prequalification status gates supplier eligibility for UNICEF procurement, creating a certification bottleneck that limits active manufacturers to fewer than ten globally. Geographic supply concentration centers on India, Germany, and South Korea, with Pune fermentation capacity, Marburg isolator-equipped fill-finish, and Songdo CDMO infrastructure anchoring output. Raw material dependencies include Saccharomyces cerevisiae master cell banks, CRM197 carrier protein stocks, and aluminum phosphate adjuvant. Single-source vulnerability in South Korean fill-finish creates European supply risk. Distribution runs through government immunization centers and consolidating private clinic GPOs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in vaccine conjugates hinges on aluminum phosphate adjuvant optimization extending cold-chain tolerance and reducing tropical wastage rates that currently erode tender economics.
For Market Incumbents: Extend serotype coverage into next-generation 24-valent pneumococcal candidates using site-specific conjugation chemistry to compress FDA comparability timelines. Backward integration into polysaccharide fermentation insulates against Crabtree effect yield constraints that elevate raw material costs. Prioritize isolator technology upgrades at European fill-finish sites to maintain EMA Annex 1 compliance as open-vial lines face disqualification. For New Entrants and Emerging Players: CDMO partnerships with isolator-equipped European facilities offer the fastest path to EMA-inspected status without seven-figure retrofit capex. White-space access concentrates in Indonesian private vaccination channels outside Java, where fragmented distributor relationships remain vulnerable to direct manufacturer contracting. Target drone delivery integration in sub-Saharan African distribution to bypass last-mile cold-chain gaps that constrain incumbent reach. For Investors and Strategic Acquirers: Asymmetric upside sits with synthetic glycoconjugate platform developers that circumvent fermentation-dependent timelines and serotype-specific antigen libraries. Long-term viability over the projection horizon favors acquisition targets with recombinant carrier protein engineering capabilities and existing WHO prequalification dossiers. Watch CRM197 supply diversification initiatives as an inflection indicator for intellectual property circumvention opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway Advancement | Unlocks UNICEF tender participation across 73 Gavi-eligible countries. |
| Site-Specific Conjugation Chemistry Adoption | Enables uniform polysaccharide-to-protein ratios for 24-valent candidates. |
| Isolator Technology Upgrade | Preserves EMA manufacturing authorization under revised Annex 1 standards. |
| Carrier Protein Supply Diversification | Reduces CRM197 single-source dependence through recombinant diphtheria toxoid alternatives. |
| Drone Delivery Network Integration | Bypasses last-mile cold-chain infrastructure gaps in sub-Saharan African distribution. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combined with secondary validation. The research team conducted structured interviews with regulatory affairs leads at EMA-inspected facilities, UNICEF procurement officers, conjugation process development specialists, and hospital immunization program directors. Secondary sources include FDA Biologics License Application filings, EMA accelerated assessment pathway documentation, WHO prequalification status reports, and ClinicalTrials.gov immunogenicity study records. Bottom-up volume modeling triangulates against top-down value projections across the analysis window.
Rate-of-change decomposition separates volume growth from price evolution across pediatric, adult, geriatric, and travel vaccination applications. The analytical framework models patient age stratification, conjugation chemistry type, delivery method, and end-user procurement channel throughout the forecast period. CAGRs derive from immunization schedule mandate timelines, Gavi financing disbursement patterns, and serotype replacement epidemiology shifts. Forecast inputs include PLI scheme capacity buildout trajectories and EMA lot-release backlog duration assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carrier protein switching validation timelines and novel conjugate platform immunogenicity bridging study results. The analysis reflects documented assumptions regarding WHO prequalification pathway efficiency and EMA Annex 1 enforcement intensity. A model refresh is warranted upon material change in Gavi financing commitment levels or FDA comparability protocol complexity for post-approval manufacturing modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Mexico Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Canada Generic Drug Market
Biopharmaceuticals
Global Protein Expression Market
Biopharmaceuticals
Antibody Discovery Market
Biopharmaceuticals
Hemophilia B Market
Biopharmaceuticals
Cancer Drug Market
Biopharmaceuticals
Vaccine Production Market
Biopharmaceuticals
Female Infertility Drugs Market
Biopharmaceuticals
Laband Syndrome Therapeutics Market
Biopharmaceuticals
North America and Europe Pegylated Drugs Market
Biopharmaceuticals
Biobetters Market
Biopharmaceuticals
Levofloxacin Cyclized Ester Market
Biopharmaceuticals
Antibody Pair Kits Market
Biopharmaceuticals
China Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Atipamezole Market
Biopharmaceuticals
Global Argatroban Market