
 Erythropoietin Drugs Market | 2026-2036
Erythropoietin Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Erythropoietin Drugs Market Intelligence
Biocon Limited's recombinant protein manufacturing campus in Bangalore is expanding to serve export markets across Europe and North America. Amgen Inc. leverages decades of biologic process knowledge to sustain dominance in originator erythropoietin formulations. F. Hoffmann-La Roche Ltd. anchors its position through specialized oncology and nephrology channel relationships. Teva Pharmaceutical Industries Ltd. competes aggressively on biosimilar pricing while navigating complex patent thickets.
Erythropoietin drugs are glycoprotein hormones manufactured via recombinant DNA technology in mammalian cell cultures, stimulating red blood cell production in bone marrow through erythropoiesis activation. Recombinant erythropoietin commands premium pricing in oncology settings where precise hemoglobin management protects treatment tolerance. Biosimilars capture expanding share in chronic kidney disease therapy areas as payers enforce substitution protocols. Subcutaneous delivery modes lead in homecare settings where patient self-administration reduces clinic burden and total cost of care.
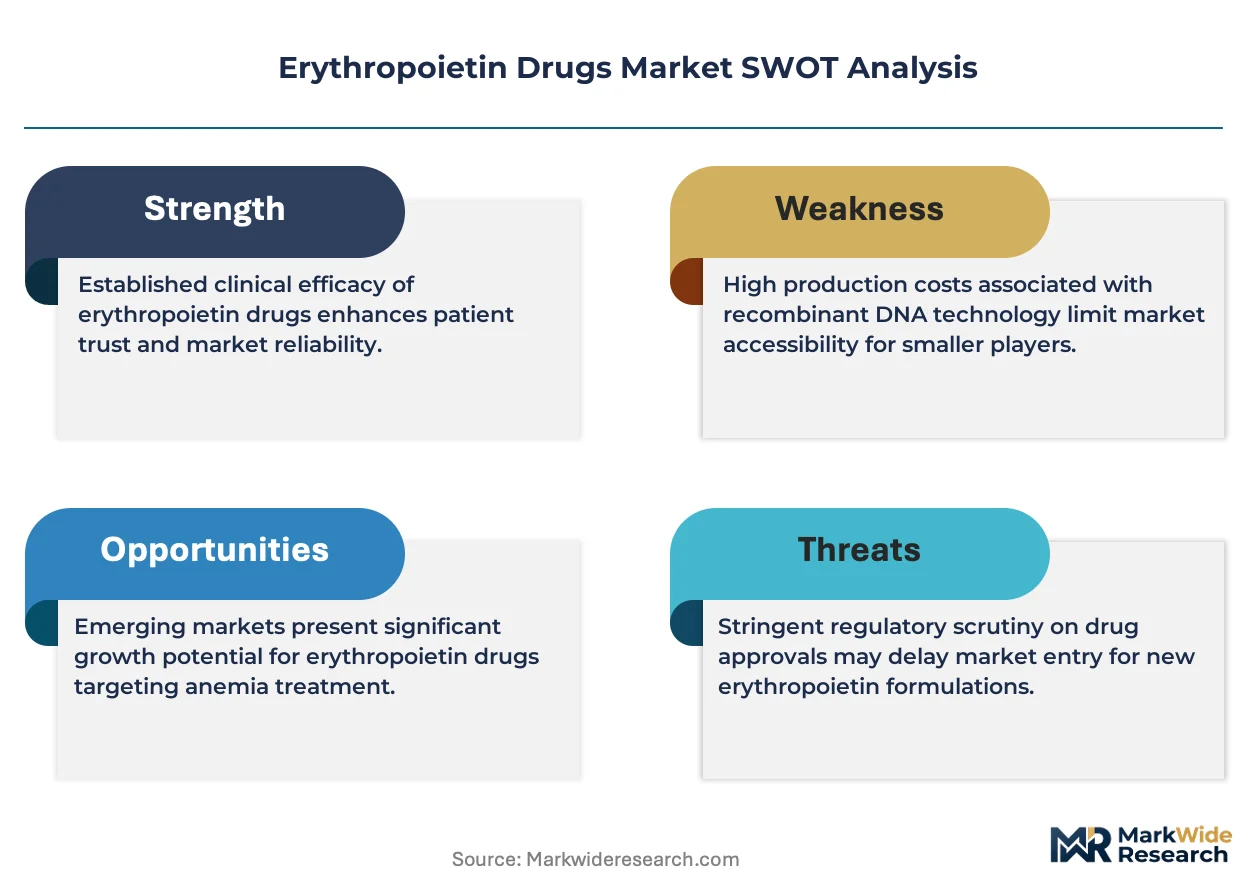
The FDA's biosimilar interchangeability standards and the EMA's biosimilar approval framework shape competitive entry timelines and prescribing confidence across developed markets. India's CDSCO enforces local clinical trial requirements that delay biosimilar launches while protecting domestic manufacturers like Biocon Limited. Stakeholders must monitor evolving interchangeability designation decisions and their cascading effects on pharmacy benefit design and physician prescribing autonomy.
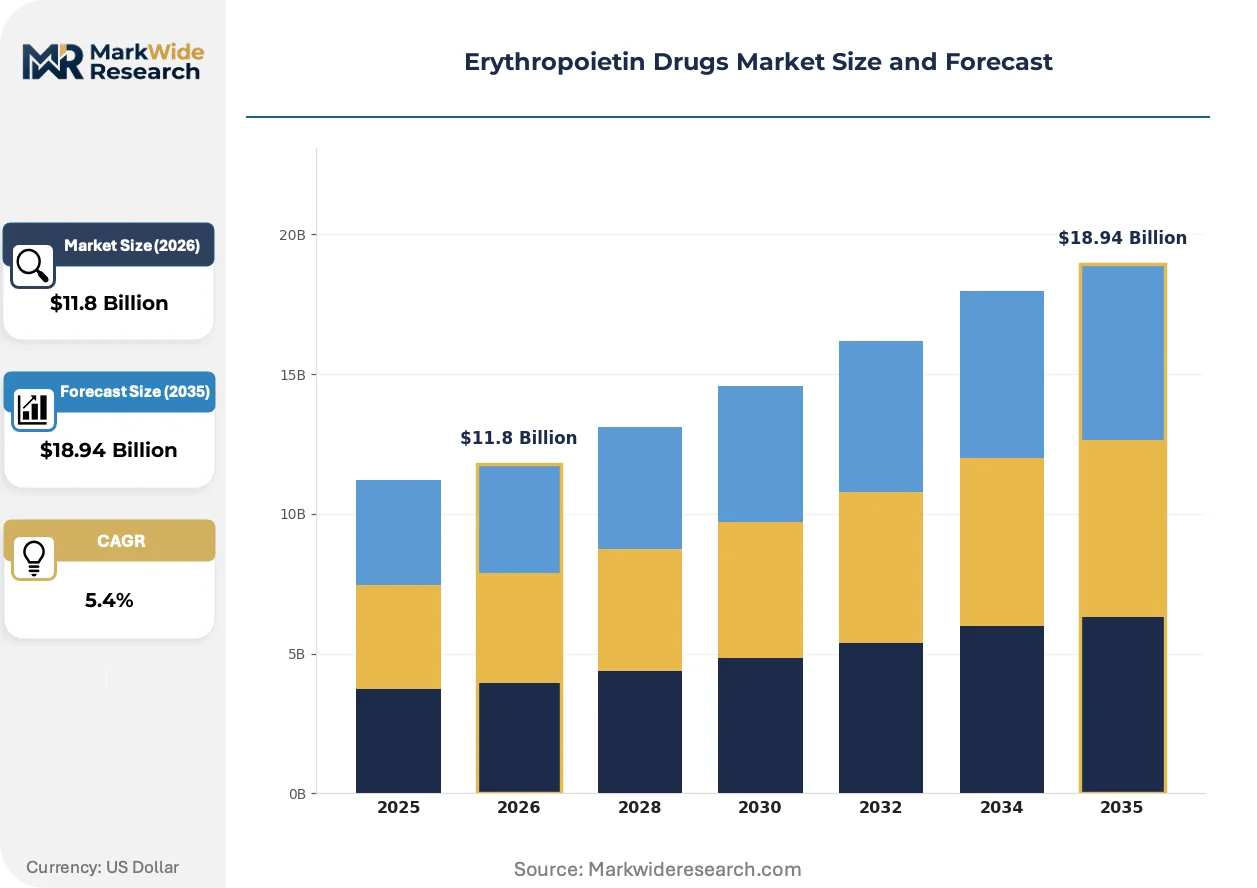
Market Dynamics
The FDA's biosimilar interchangeability pathway and EMA's streamlined approval frameworks are compressing originator exclusivity periods while accelerating generic substitution protocols across dialysis and oncology settings.
Growth Catalysts
- Chronic Kidney Disease Prevalence:Rising diabetes and hypertension rates in the United States, Germany, and Japan expand the addressable patient pool for erythropoietin therapy in nephrology clinics.
- EMA Biosimilar Framework:Accelerated European approval timelines reduce regulatory friction for biosimilar entrants, enabling faster market penetration and payer-enforced substitution.
- Subcutaneous Delivery Innovation:Homecare administration protocols reduce clinic burden and total cost of care, driving adoption among ambulatory dialysis patients.
Market Restraints
- Mammalian Cell Culture Costs:Recombinant protein manufacturing requires expensive bioreactor infrastructure and specialized media, compressing biosimilar margin structures.
- Patent Thicket Complexity:Dense intellectual property layering around erythropoietin formulations and process patents delays generic entry in key markets.
- CDSCO Local Trial Mandates:India's requirement for domestic clinical studies extends biosimilar launch timelines while protecting incumbent domestic manufacturers.
Strategic Opportunities
- Pediatric Oncology Expansion:Underpenetrated hemoglobin management protocols in pediatric cancer care present white space for formulation differentiation.
- Japanese Homecare Integration:METI-supported aging-in-place initiatives create channel opportunities for patient-administered erythropoietin outside hospital settings.
- Long-Acting Biosimilar Convergence:Fusion protein and pegylation technology combinations enable extended dosing intervals that differentiate next-generation entrants.
Industry Challenges
- Interchangeability Designation Uncertainty:Variable FDA decisions on automatic pharmacy substitution create reimbursement complexity and physician prescribing hesitation.
- Bioprocess Talent Scarcity:Shortage of mammalian cell culture specialists and analytical biochemists constrains manufacturing scale-up timelines.
- Cold Chain Integrity Requirements:Temperature-sensitive glycoprotein stability demands specialized logistics infrastructure that raises distribution costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Erythropoietin Drugs Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant Erythropoietin, Biosimilars, Procrit, Epogen Therapy Area: Chronic Kidney Disease, Cancer, Anemia, Bone Marrow Disorders Delivery Mode: Injectable, Subcutaneous, Intravenous, Oral End User: Hospitals, Clinics, Homecare Settings, Long-term Care Facilities |
| Companies Covered | Amgen Inc., Johnson & Johnson, F. Hoffmann-La Roche Ltd., Pfizer Inc., Novartis AG, Teva Pharmaceutical Industries Ltd., Biocon Limited, Sun Pharmaceutical Industries Ltd., Dr. Reddy’s Laboratories Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Erythropoietin Drugs Market Strategic Shifts & Innovations
Recombinant manufacturing advances and regulatory pathway evolution are compressing development timelines while shifting administration settings from institutional to ambulatory environments.
Prefilled syringe and auto-injector delivery systems are decentralizing erythropoietin administration from dialysis centers to patient homes. Nephrology clinics in the United States and Japan are adopting these devices to reduce chair time and staffing costs. This shift is decentralizing the traditional site-of-care model and redistributing revenue across pharmacy benefit managers and home health providers.
The FDA's biosimilar interchangeability standards are tightening evidentiary requirements for automatic substitution at the pharmacy level. Originators must now defend formulation patents against more sophisticated analytical similarity packages. Oncology practices in Germany and dialysis chains in the United States are adjusting procurement protocols to accommodate pending interchangeability designations.
Patient self-administration training programs are replacing traditional nurse-supervised injection protocols in chronic kidney disease management. Dialysis providers are unbundling medication administration from treatment sessions, shifting reimbursement risk to specialty pharmacies. This behavioral transition is most visible in Japanese homecare networks and US Medicare Advantage plans with capitated nephrology contracts.
Erythropoietin Drugs Market Segmentation
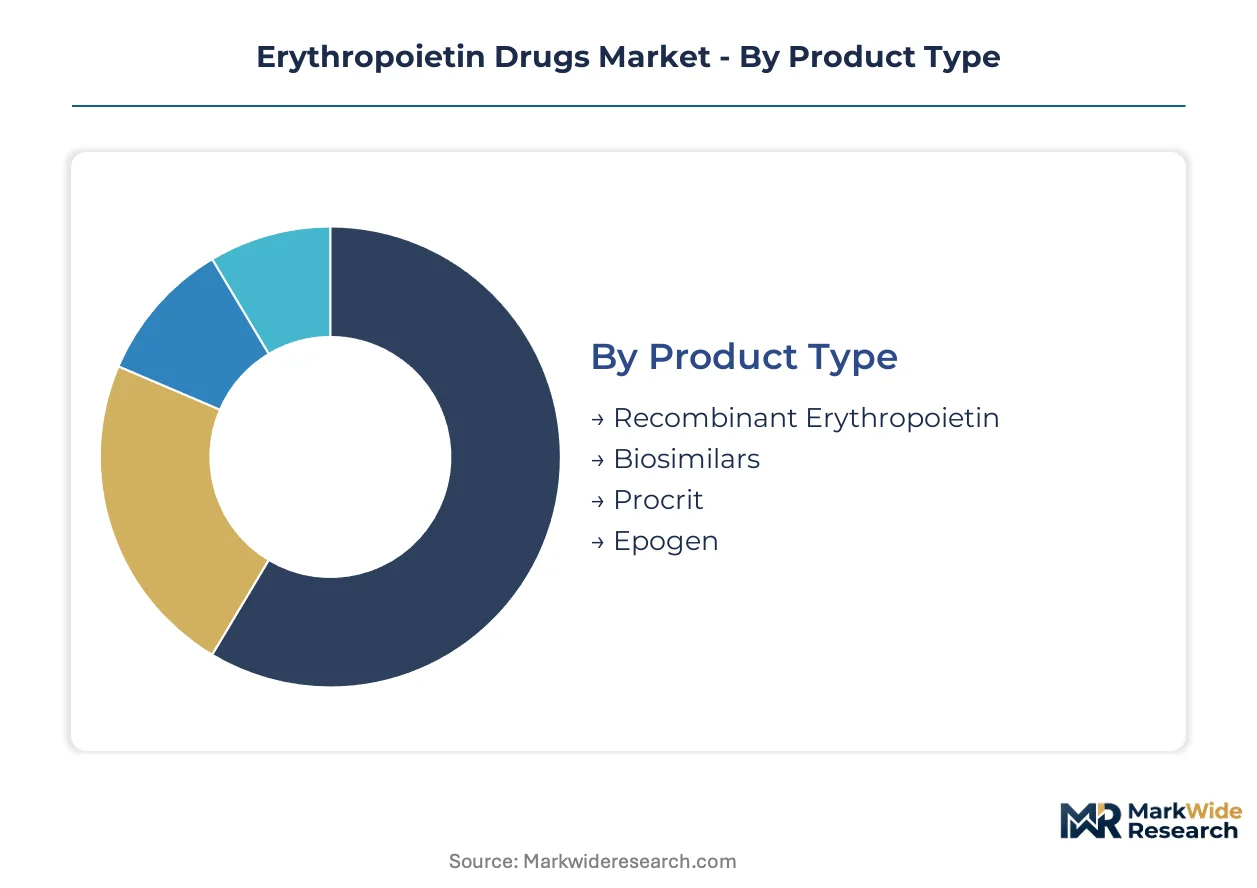
Erythropoietin market segmentation reveals how therapeutic setting, reimbursement structure, and patient mobility shape procurement patterns. Manufacturers configure product portfolios around these divisions to capture volume in dialysis chains, oncology practices, and emerging homecare channels.
Product Type:
Buyers in this category separate into originator-loyal oncology practices and cost-constrained nephrology networks pursuing biosimilar substitution.
- Recombinant Erythropoietin:Glycoprotein hormones manufactured in mammalian cell cultures deliver precise erythropoiesis activation with established immunogenicity profiles. Demand concentrates in United States oncology settings where FDA-mandated REMS programs and hemoglobin management protocols protect originator positioning. Patent cliff pressures and EMA biosimilar frameworks are compressing exclusivity periods in European dialysis networks.
- Biosimilars:Analytically similar recombinant proteins demonstrate comparable efficacy through abbreviated approval pathways, enabling payer-enforced substitution. German sickness funds and Japanese dialysis chains are driving fastest adoption as procurement tenders prioritize unit cost over brand heritage. Manufacturing complexity and cold chain requirements constrain margin structures for emerging entrants.
- Procrit:Long-acting epoetin alfa formulation with established oncology reimbursement codes in United States Medicare Part B.
- Epogen:Amgen's originator epoetin alfa maintains residual share in dialysis centers with long-term supply contracts.
Biosimilars lead volumes today; recombinant erythropoietin retains premium positioning in oncology where clinical familiarity commands pricing power.
Therapy Area:
Clinical indication determines dosing frequency, reimbursement tier, and competitive intensity across nephrology and hematology practices.
- Chronic Kidney Disease:Dialysis-dependent patients require sustained erythropoietin therapy to manage anemia of renal failure, generating predictable recurring demand. United States, Germany, and Japan anchor volume as diabetes and hypertension prevalence expands the addressable pool. Bundled payment models in US Medicare are shifting site-of-care from hospital outpatient departments to freestanding dialysis centers.
- Cancer:Chemotherapy-induced anemia demands precise hemoglobin management to protect treatment tolerance and reduce transfusion dependency. Oncology practices in Germany and Japan prioritize long-acting formulations that minimize clinic visits during immunosuppressive regimens. Reimbursement complexity and REMS requirements sustain originator preference despite biosimilar availability.
- Anemia:Broader indication covering non-renal, non-oncology etiologies with fragmented prescriber base and variable reimbursement.
- Bone Marrow Disorders:Myelodysplastic syndromes and aplastic anemia represent specialized hematology segment with limited but high-value volume.
Chronic kidney disease anchors absolute volume; cancer applications are climbing fastest as biosimilar penetration unlocks budget for expanded prophylaxis.
Delivery Mode:
Administration route shapes patient autonomy, total cost of care, and competitive differentiation in site-of-care migration.
- Subcutaneous:Self-administration capability enables homecare protocols that reduce dialysis center chair time and staffing costs. Japanese METI-supported aging-in-place initiatives and US Medicare Advantage capitation models are accelerating device adoption. Prefilled syringes and auto-injectors from established manufacturers command procurement preference in ambulatory networks.
- Intravenous:Clinic-administered dosing maintains dominance in in-center hemodialysis where vascular access already exists. United States dialysis chains and German nephrology clinics favor this route for medication administration bundled into treatment sessions. Reimbursement unbundling trends are eroding share as providers shift financial risk to specialty pharmacies.
- Injectable:General parenteral category encompassing both subcutaneous and intravenous administration with overlapping device requirements.
- Oral:Investigational hypoxia-inducible factor prolyl hydroxylase inhibitors threaten parenteral dominance with tablet convenience, though current erythropoietin market contains no approved oral formulations.
Intravenous administration retains institutional volume; subcutaneous delivery is gaining share fastest as homecare protocols mature in Japan and US commercial plans.
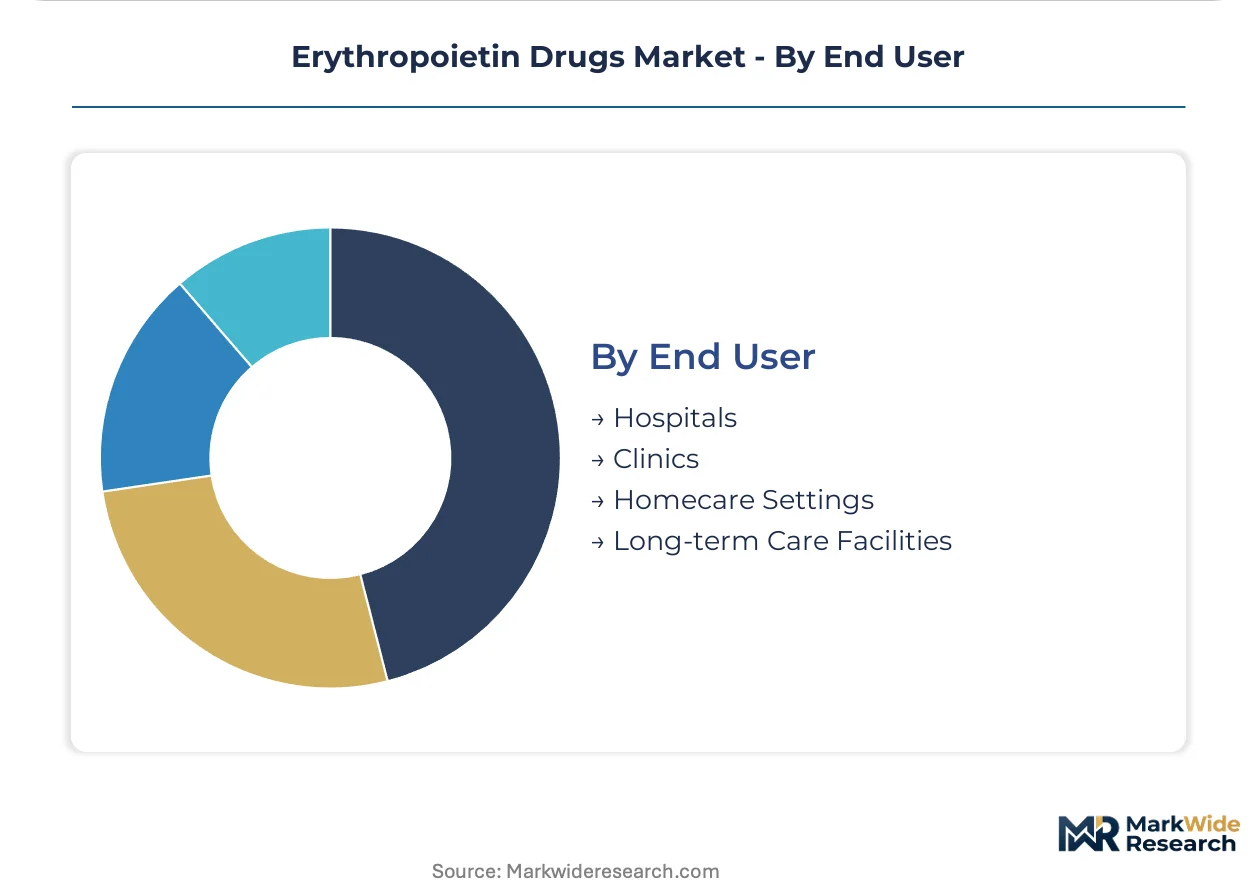
End User:
Site-of-care economics and staffing models determine formulation preference, device complexity, and distribution channel selection.
- Hospitals:Academic medical centers and community hospitals manage complex anemia cases requiring transfusion coordination and multidisciplinary oversight. United States 340B drug pricing program and German DRG-based reimbursement create procurement concentration around originator formulations. Biosimilar substitution protocols are penetrating more slowly due to pharmacy and therapeutics committee inertia.
- Homecare Settings:Patient self-administration programs reduce total cost of care while shifting reimbursement risk to specialty pharmacies and durable medical equipment suppliers. Japanese homecare networks and US Medicare Advantage plans with capitated nephrology contracts are expanding fastest. Training infrastructure and remote monitoring capabilities determine competitive positioning.
- Clinics:Freestanding nephrology and oncology practices balance clinical autonomy against payer substitution mandates.
- Long-term Care Facilities:Skilled nursing and rehabilitation centers manage post-acute anemia with limited on-site laboratory monitoring.
Hospitals lead absolute volume today; homecare settings are expanding most quickly as site-of-care migration accelerates in developed markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping erythropoietin manufacturing footprints as producers seek jurisdictions with streamlined biosimilar pathways and lower cost-of-compliance structures. The FDA's interchangeability standards and EMA's streamlined frameworks create divergent entry timelines that influence investment location decisions.
United States
Dialysis-dependent chronic kidney disease patients and Medicare Part B reimbursement protocols sustain originator volume in oncology practices. The FDA's biosimilar interchangeability designation process shapes pharmacy substitution confidence and payer benefit design. Boston and San Francisco biotech clusters host process development capabilities for next-generation erythropoietin formulations.
Germany
Sickness fund procurement tenders and bundled dialysis reimbursement accelerate biosimilar penetration in nephrology networks. The EMA's centralized approval framework reduces regulatory friction for European market entry. Baden-Württemberg and Bavaria anchor manufacturing infrastructure serving export demand across the European Union.
Japan
METI-supported aging-in-place initiatives expand homecare administration channels for subcutaneous erythropoietin delivery. The PMDA's biosimilar guidelines align with international standards while maintaining domestic clinical data requirements. The Kanto region around Tokyo concentrates dialysis center networks and specialty pharmacy distribution.
India
Domestic chronic kidney disease prevalence and government hospital procurement programs drive volume for cost-optimized biosimilars. CDSCO local clinical trial mandates extend launch timelines while protecting incumbent manufacturers. Bangalore's recombinant protein manufacturing corridor scales capacity for European and North American export markets.
Switzerland
Specialized oncology and nephrology channel relationships sustain premium positioning for originator formulations. Swissmedic's alignment with EMA procedures facilitates rapid European market access for locally developed products. The Basel biopharma cluster maintains analytical biochemistry capabilities for glycoprotein characterization.
Erythropoietin Drugs Market Key Industry Players
United States producers anchor one tier through decades of biologic process knowledge and originator formulation heritage; Indian specialists hold another through recombinant manufacturing scale and export-focused cost structures. The vendor base concentrates around mammalian cell culture capabilities with high barriers to analytical similarity demonstration. Three archetypes dominate: originator incumbents defending oncology premium positioning, biosimilar attackers competing on nephrology unit cost, and emerging entrants pursuing long-acting formulation differentiation. Capacity expansion in South Asian bioreactor infrastructure and strategic partnerships for European distribution rights constitute the dominant competitive moves.
Among established biopharmaceutical incumbents, Amgen Inc. and F. Hoffmann-La Roche Ltd. occupy positions representing originator heritage and specialized channel depth in oncology settings. Biocon Limited exemplifies the emerging-market archetype scaling recombinant protein manufacturing for regulated export markets. Teva Pharmaceutical Industries Ltd. sits within the aggressive biosimilar tier navigating patent complexity and payer substitution protocols. These three company types collectively illustrate how competitive positioning fragments across regulatory sophistication, manufacturing scale, and therapeutic focus.
| Leading Market Players |
|---|
| Amgen Inc. |
| Johnson & Johnson |
| F. Hoffmann-La Roche Ltd. |
| Pfizer Inc. |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| Biocon Limited |
| Sun Pharmaceutical Industries Ltd. |
| Dr. Reddy's Laboratories Ltd. |
| Others |
Cost & Logistics Intelligence
Originator-biosimilar bifurcation separates oncology premium tiers from nephrology commodity substitution, compressing margins in dialysis networks while protecting hemoglobin management premiums in cancer care. This divergence feeds directly into manufacturing location decisions, with high-complexity glycoprotein production clustering in Switzerland and Massachusetts while cost-optimized biosimilar capacity scales in Bangalore and Hyderabad.
Pricing Analysis
Distributor and specialty pharmacy markups vary sharply across administration settings, with homecare channels capturing margin through device bundling while clinic-administered intravenous doses flow through GPO-negotiated contracts. Three-tier pricing structure across originator oncology formulations, interchangeable biosimilars, and non-interchangeable follow-on biologics reflects FDA designation status and payer substitution protocols. Cost compression in dialysis networks is intensifying as bundled Medicare payments force unbundling of medication administration from treatment sessions. German sickness funds and Japanese dialysis chains demonstrate highest price sensitivity, while United States oncology practices retain originator preference due to REMS complexity and hemoglobin management liability.
Supply Chain Analysis
Reverse-logistics for temperature-deviated glycoprotein shipments remains underdeveloped, with most cold chain failures resulting in destruction rather than refurbishment due to protein stability constraints. Mammalian cell culture capacity concentrates in the United States, Switzerland, and India, with bioreactor infrastructure drawing from specialized media suppliers in Germany and single-use system manufacturers in Massachusetts. Chinese heparin and recombinant protein precursor supply creates single-source vulnerability for fermentation media components. Distribution runs through specialty pharmacy networks in the United States and hospital central procurement in Germany, with Japanese homecare channels expanding fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The erythropoietin market reads as a late-cycle quality story where precision hemoglobin management and interchangeability designation separate sustainable premium positioning from commodity erosion. Demand is shifting toward patient-administered subcutaneous formulations with integrated delivery devices, rewarding manufacturers with training infrastructure and remote monitoring capabilities.
For Market Incumbents: Deploy interchangeability defense through analytical similarity investments and REMS program complexity that delays automatic pharmacy substitution. Consolidate oncology channel relationships through long-acting formulation pipelines and integrated hemoglobin monitoring services. Patent thicket enforcement and process patent layering around glycosylation patterns protect against biosimilar entrants in premium therapeutic areas. For New Entrants and Emerging Players: Launch via Japanese homecare networks and United States Medicare Advantage capitated contracts where site-of-care migration creates procurement flexibility. Pediatric oncology hemoglobin management and long-acting biosimilar convergence represent the most penetrable white spaces. Go-to-market positioning should emphasize extended dosing intervals through pegylation or fusion protein technology that differentiates from originator pharmacokinetics. For Investors and Strategic Acquirers: Consolidation pressure builds where mammalian cell culture talent scarcity intersects with biosimilar margin compression and cold chain infrastructure requirements. Long-term viability favors vertically integrated players with captive bioreactor capacity and analytical biochemistry capabilities for glycoprotein characterization. The signal to watch is FDA interchangeability designation velocity for pending biosimilar filings, which will reshape pharmacy benefit design and originator defensibility.| Strategic Initiative | Industry Significance |
|---|---|
| Interchangeability Designation Pursuit | FDA interchangeability unlocks automatic pharmacy substitution and accelerates payer-enforced biosimilar conversion. |
| Long-Acting Formulation Development | Pegylation and fusion protein extensions differentiate next-generation entrants through reduced dosing frequency. |
| Homecare Channel Integration | Patient self-administration programs capture site-of-care migration value in Japanese METI-supported aging networks. |
| Mammalian Cell Culture Scale-Up | Bioreactor capacity expansion in Bangalore and Hyderabad serves regulated export demand with cost-optimized biosimilar production. |
| Cold Chain Infrastructure Investment | Temperature-controlled logistics protect glycoprotein stability through specialized distribution partnerships with specialty pharmacies. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with regulatory affairs leads at EMA and FDA, formulary directors at German sickness funds, dialysis center procurement managers in Japan, and payer access specialists at United States Medicare Advantage plans. Secondary validation drew from FDA biosimilar approval filings, EMA scientific advice outcomes, ClinicalTrials.gov erythropoietin study registries, and Japanese PMDA review reports. Bottom-up patient population modeling and top-down manufacturer revenue triangulation anchored market size estimates.
Comparable-period anchoring linked historical biosimilar penetration curves in European nephrology networks to projected United States interchangeability adoption timelines across the modeling window. Segmentation dimensions included product type, therapy area, delivery mode, and end-user setting, with regulatory cluster and reimbursement model as cross-cutting variables. CAGRs were derived from patient prevalence trends, dosing frequency evolution, and substitution protocol enforcement intensity. Forecast inputs incorporated dialysis center capacity expansion in the United States, German bundled payment model adjustments, and Japanese homecare policy implementation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA interchangeability designation delays, biosimilar immunogenicity events, or oral hypoxia-inducible factor inhibitor approval. Practitioners should monitor interchangeability designation velocity, bundled payment model unbundling trends, and cold chain infrastructure investment for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Antibody Market
Biopharmaceuticals
Human Insulin Market
Biopharmaceuticals
Germany Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Latin America Insulin Pens Market
Biopharmaceuticals
Global Swine Fever Vaccine Market
Biopharmaceuticals
Next Generation Antibody Therapeutics Market
Biopharmaceuticals
Plasma Protease C1-Inhibitor Market
Biopharmaceuticals
Chemotherapy Market
Biopharmaceuticals
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market
Biopharmaceuticals
US Generic Injectables Market
Biopharmaceuticals
Pegylated Protein Therapeutics Market
Biopharmaceuticals
Europe Insulin Delivery Devices Market
Biopharmaceuticals
Biologic Response Modifiers Market
Biopharmaceuticals
Beta Interferon Market
Biopharmaceuticals
Influenza Vaccine Market
Biopharmaceuticals
Global Anti-Infective Drugs Market