
 Custom Peptide Synthesis Services Market | 2026-2036
Custom Peptide Synthesis Services Market Size, Share, and Industry Trends Forecast 2026-2036
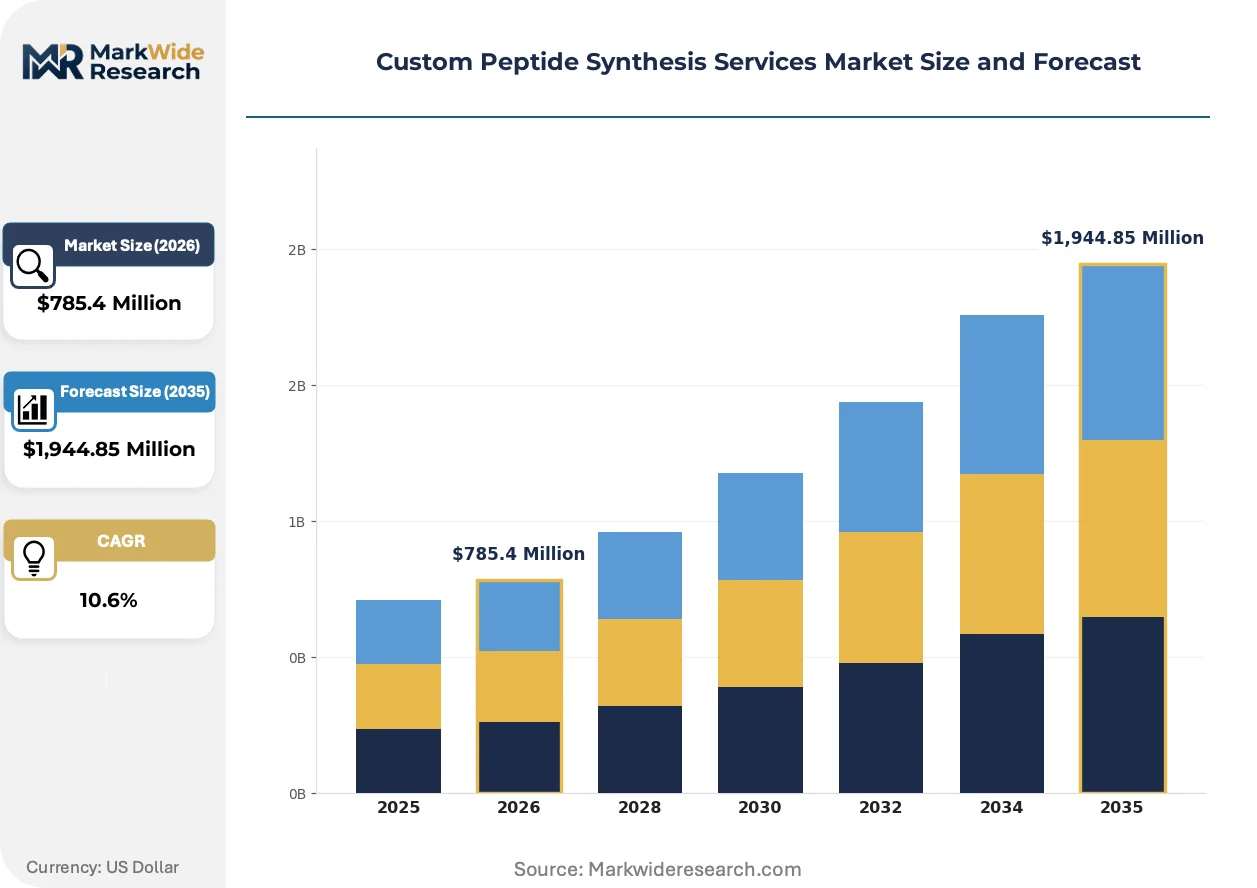
Custom Peptide Synthesis Services Market Outlook
The gap between GMP-certified custom synthesis and research-grade peptide supply is shifting from a price distinction to a capability barrier. Merck KGaA leverages its integrated pharmaceutical services footprint to anchor high-volume therapeutic peptide programs. Bachem differentiates through specialized cyclic peptide expertise and multi-kilogram cGMP manufacturing scale. GenScript competes aggressively in modified and conjugated peptide segments across Asia-Pacific research markets.
Custom peptide synthesis services encompass the design, assembly, purification, and analytical validation of amino acid chains ranging from 2 to 100+ residues using solid-phase or liquid-phase chemistries, primarily serving drug discovery, vaccine development, and diagnostic assay production. Solid phase synthesis dominates commercial throughput due to automation compatibility and stepwise yield control, while recombinant technology captures margin pools for long-chain peptides exceeding 50 residues. Therapeutic applications lead absolute demand, though vaccine development represents the fastest-expanding segment as mRNA and peptide-based immunogen platforms advance through clinical pipelines.
FDA cGMP guidelines and EMA GMP Annex 1 standards govern peptide API manufacturing, with ISO 13485 certification increasingly required for diagnostic-grade material supply. The EPA and national environmental regulators impose solvent recovery and waste stream limits on Fmoc chemistry operations, elevating capital costs for new production facilities. Stakeholders must weigh backward integration risks against captive supply advantages as peptide complexity and regulatory scrutiny intensify in parallel.
Market Dynamics
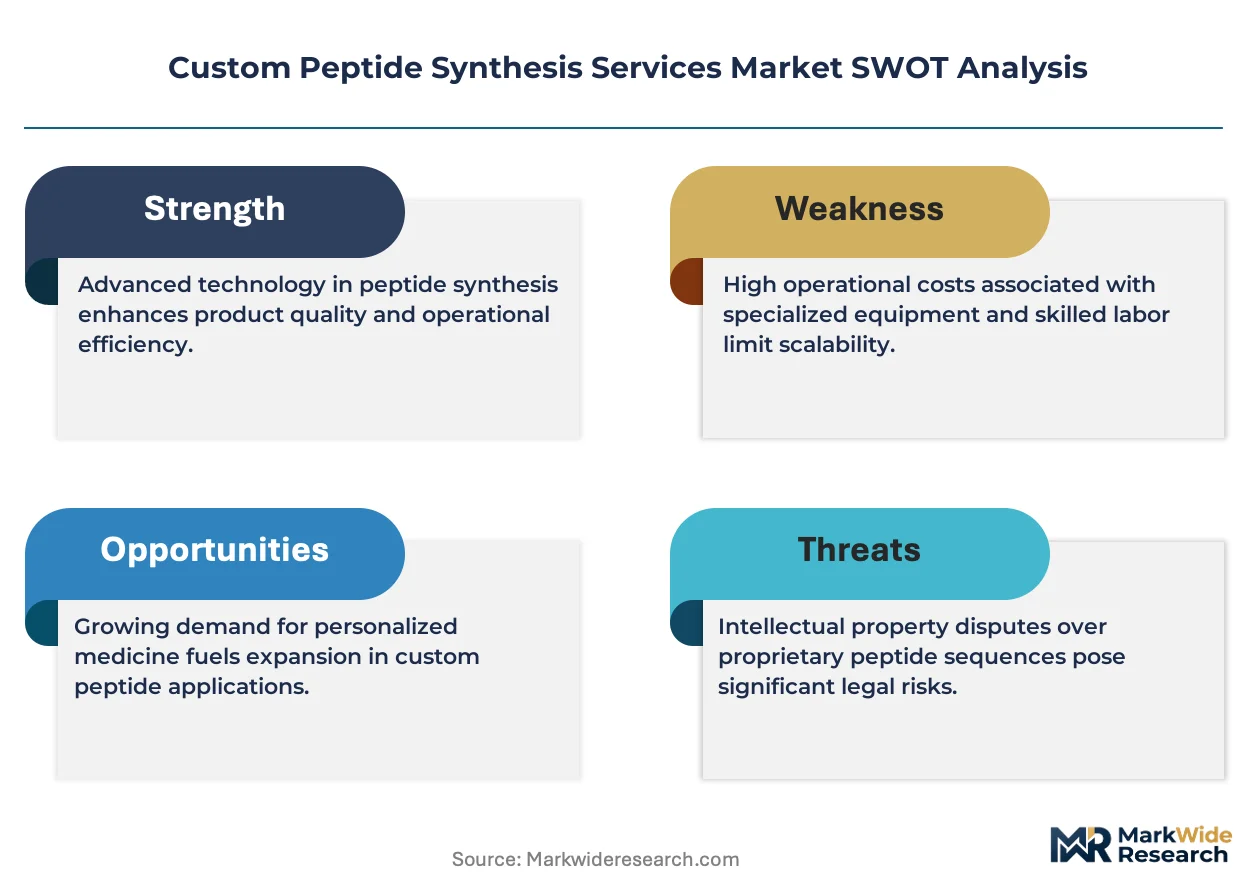
FDA cGMP and EMA GMP Annex 1 standards are compressing the supplier base by disqualifying research-grade facilities from therapeutic peptide programs, creating a capability barrier that favors capital-intensive GMP-certified producers.
Growth Catalysts
- Peptide-based vaccine platforms:mRNA and peptide immunogen pipelines are accelerating demand for complex, modified peptides in clinical-stage development.
- EMA GMP Annex 1 revision:Stricter contamination control requirements are forcing drug sponsors toward certified custom synthesis partners with validated sterile manufacturing.
- Diagnostic assay expansion:Multiplexed peptide arrays for infectious disease and oncology screening are consuming higher volumes of purified, sequence-verified material.
Market Restraints
- Fluctuating raw material costs:Amino acid derivatives and Fmoc-protected reagents face price volatility tied to Chinese fine chemical export quotas.
- Specialized equipment concentration:High-resolution mass spectrometry and preparative HPLC systems cluster in Germany, Switzerland, and the United States, limiting geographic diversification.
- Long-chain synthesis ceiling:Solid-phase chemistry yield degradation beyond 50 residues pushes therapeutic candidates toward costlier recombinant production.
Strategic Opportunities
- India biopharma outsourcing:CDSCO-aligned GMP infrastructure investments in Hyderabad and Bengaluru create capacity for mid-volume therapeutic peptide programs.
- Convergent bispecific peptide formats:Chemical ligation and native chemical ligation techniques enable modular assembly of multi-targeting therapeutics.
- Green chemistry mandates:EPA solvent recovery regulations and EU Green Deal targets reward facilities with closed-loop Fmoc chemistry and aqueous purification systems.
Industry Challenges
- Peptide chemist scarcity:Solid-phase synthesis expertise and analytical method development skills concentrate among aging specialists in Basel, Boston, and Shanghai.
- Multi-year cGMP certification timelines:FDA pre-approval inspections and EMA QP declarations delay commercial supply readiness for 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Custom Peptide Synthesis Services Market |
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,944.85 Million |
| CAGR (2026 – 2036) | 10.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cyclic Peptides, Linear Peptides, Modified Peptides, Conjugated Peptides Technology: Solid Phase Synthesis, Liquid Phase Synthesis, Recombinant Technology, Fmoc Chemistry Application: Therapeutic Applications, Research & Development, Diagnostic Applications, Vaccine Development End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Contract Research Organizations |
| Companies Covered | Merck KGaA, CordenPharma, Bachem, CSBio, CPC Scientific, Thermo Fisher Scientific, AmbioPharm, Auspep, GenScript, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Custom Peptide Synthesis Services Market Strategic Shifts
Automation and green chemistry are compressing production timelines while expanding the feasible complexity space for therapeutic peptides. These shifts are redrawing capability boundaries between research-grade and GMP-certified suppliers.
Continuous flow peptide synthesis is expanding into commercial-scale production by enabling real-time monitoring and rapid optimization of coupling efficiencies. Mid-sized biopharma sponsors are adopting flow systems for kilogram-scale campaigns previously requiring batch processing. This technology is expanding into territory dominated by traditional solid-phase reactors, compressing cost structures for standardized sequences.
EMA's revised GMP Annex 1 contamination control guidelines are mandating barrier technology and single-use systems in sterile peptide API suites. Facilities without isolator technology face capital outlays exceeding standard equipment depreciation cycles. European peptide API manufacturers are responding by consolidating aseptic filling operations into dedicated campus configurations.
Biopharma procurement teams are consolidating vendor panels from 15-20 suppliers to 3-5 strategic partners with integrated discovery-to-GMP capabilities. This concentration favors service providers offering medicinal chemistry, process development, and regulatory submission support under single contracts. The United States and Germany exhibit the most pronounced supplier rationalization, with sponsors prioritizing partners holding both FDA and EMA inspection histories.
Custom Peptide Synthesis Services Market Segmentation
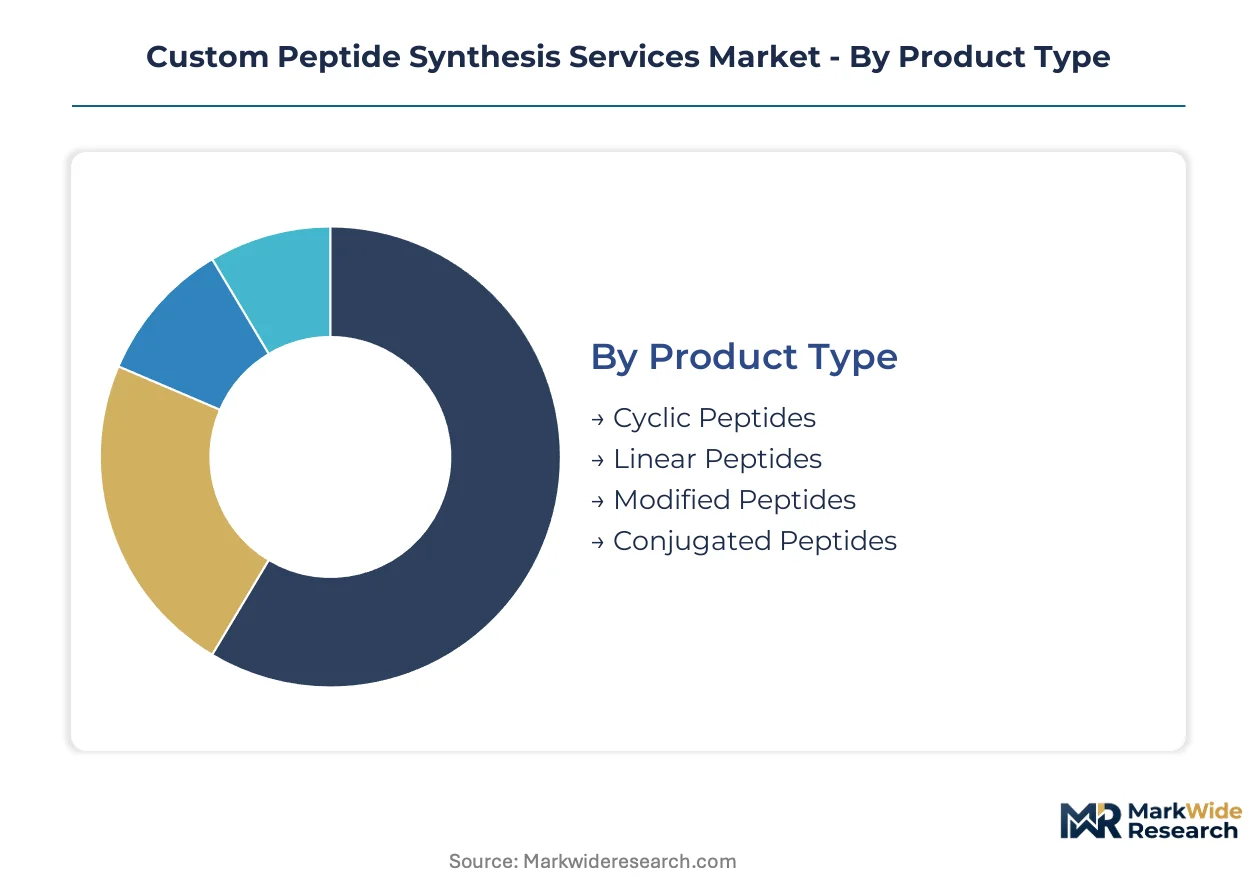
Peptide synthesis services fragment across multiple technical and commercial dimensions that determine pricing power, regulatory burden, and customer loyalty. Each segmentation axis reveals distinct capability requirements and margin structures that separate commodity catalog suppliers from strategic partners.
Product Type:
Standalone peptide formats serve discrete therapeutic targets, while embedded conjugates integrate into larger drug delivery systems or diagnostic platforms.
- Modified Peptides:Incorporate non-natural amino acids, phosphorylation, methylation, or other post-translational modifications to enhance metabolic stability or receptor selectivity. Pharmaceutical sponsors in the United States and Germany commission these for extended half-life therapeutic candidates where standard sequences fail bioavailability thresholds.
- Conjugated Peptides:Link peptide sequences to payloads including cytotoxic agents, radionuclides, or fluorescent tags through cleavable or stable linkers. Demand concentrates in oncology drug discovery pipelines across Boston and Basel, driven by antibody-drug conjugate fatigue and the search for smaller, tumor-penetrating targeting moieties.
- Cyclic Peptides:Head-to-tail or disulfide-constrained structures conferring proteolytic resistance and defined three-dimensional conformations.
- Linear Peptides:Unmodified amino acid chains serving as research tools, epitope mapping standards, and vaccine immunogen building blocks.
Modified peptides lead volumes today; conjugated peptides are gaining share fastest.
Technology:
Cost tier separation runs from high-throughput automated platforms for discovery-stage material to specialized bioreactor systems for commercial therapeutic supply.
- Solid Phase Synthesis:Automated stepwise assembly on insoluble resin supports using Fmoc or Boc protection strategies, dominating commercial throughput through reproducible yields and parallel processing capability. CDMOs in Switzerland and the United States deploy these systems for multi-kilogram campaigns serving Phase III peptide therapeutics.
- Recombinant Technology:Microbial or mammalian expression systems producing peptides exceeding 50 residues where chemical synthesis yields degrade. Chinese biopharma sponsors increasingly source long-chain therapeutic candidates through recombinant routes to bypass solid-phase length constraints.
- Liquid Phase Synthesis:Solution-based condensation chemistry reserved for specialized industrial-scale peptide manufacturing and fragment condensation approaches.
- Fmoc Chemistry:Fluorenylmethyloxycarbonyl protecting group strategy enabling mild acid-free deprotection cycles compatible with acid-sensitive modifications.
Solid phase synthesis anchors current capacity; recombinant technology is expanding most quickly.
Application:
Customer maturity separates exploratory research programs with minimal regulatory documentation from commercial therapeutic submissions requiring full cGMP compliance.
- Therapeutic Applications:Peptide active pharmaceutical ingredients for metabolic, oncology, and cardiovascular indications subject to FDA and EMA cGMP manufacturing standards. Sponsors in Germany and the United States commission multi-kilogram batches with comprehensive impurity profiling and stability documentation.
- Vaccine Development:Peptide immunogens, T-cell epitope constructs, and carrier protein conjugates advancing through mRNA and synthetic peptide vaccine platforms. Chinese and Indian biotech firms drive procurement volumes for infectious disease and therapeutic cancer vaccine pipelines.
- Research & Development:Discovery-stage peptide libraries, hit validation tools, and mechanism-of-study reagents with flexible specification tolerances.
- Diagnostic Applications:Calibrators, controls, and capture reagents for immunoassays and mass spectrometry workflows requiring ISO 13485 quality systems.
Therapeutic applications dominate revenue today; vaccine development shows the steepest expansion trajectory.
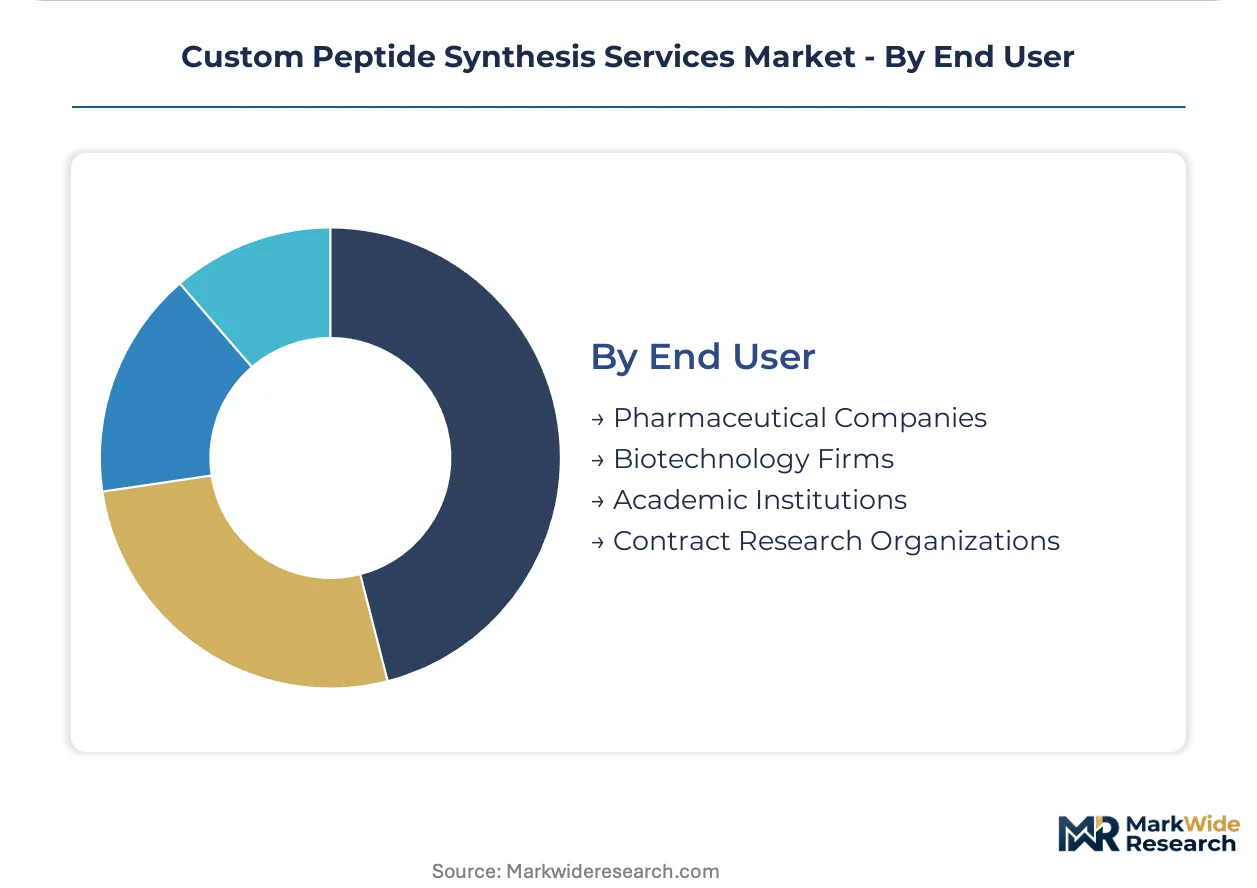
End User:
Procurement sophistication spans from academic purchase orders to pharmaceutical master service agreements with integrated regulatory support.
- Pharmaceutical Companies:Large-cap drug developers with internal peptide chemistry groups outsourcing specialized modifications, toxicology batches, and commercial API supply. Merck KGaA and Roche source through strategic partnerships covering discovery through validated manufacturing.
- Biotechnology Firms:Venture-backed and mid-cap sponsors lacking captive synthesis infrastructure, dependent on CDMOs for IND-enabling and clinical-stage material. Boston and San Francisco clusters exhibit highest outsourcing intensity per pipeline dollar.
- Academic Institutions:University research groups purchasing catalog and custom peptides through grant-funded procurement with limited quality system requirements.
- Contract Research Organizations:Service providers aggregating peptide demand across multiple sponsor programs and reselling synthesis capacity.
Pharmaceutical companies command the largest contract values; biotechnology firms are scaling procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peptide synthesis expertise clusters in Basel, Boston, and Shanghai, with veteran chemists commanding premium placement at GMP-certified facilities. This talent geography shapes where pharmaceutical sponsors source complex therapeutic programs.
United States
FDA cGMP pre-approval inspections compress supplier qualification timelines for Phase III peptide therapeutics. The EPA enforces solvent recovery mandates on Fmoc chemistry operations, elevating capital requirements for new facilities. Greater Boston hosts the densest concentration of biotechnology firms outsourcing IND-enabling material to certified CDMOs.
Germany
EMA GMP Annex 1 revisions force barrier technology investments in sterile peptide API suites. The country's national pharmaceutical regulator maintains stringent contamination control standards that disqualify research-grade facilities. North Rhine-Westphalia anchors multi-kilogram cGMP campaigns serving European commercial launches.
Switzerland
Swissmedic inspection histories command premium positioning in pharmaceutical procurement panels. REACH chemical registration requirements govern amino acid derivative imports for synthesis operations. Basel concentrates cyclic peptide expertise and analytical method development capabilities for complex therapeutic candidates.
China
NMPA alignment with ICH Q7 guidelines accelerates domestic GMP certification for export-oriented peptide manufacturers. Dual carbon goals pressure facilities to adopt aqueous purification and closed-loop solvent systems. Shanghai and Suzhou clusters scale modified and conjugated peptide output for Asia-Pacific research markets.
India
CDSCO-aligned GMP infrastructure investments in Hyderabad and Bengaluru attract mid-volume therapeutic peptide programs. The country's national pharmaceutical regulator streamlines inspection protocols for export certification. Karnataka's biopharma corridor builds sterile manufacturing capacity to capture European and North American outsourcing demand.
Custom Peptide Synthesis Services Market Competitive Environment
Top-tier vendors anchor GMP-certified therapeutic supply, while research-grade specialists serve discovery-stage demand with flexible specifications. The supplier base compresses into three tiers: integrated pharmaceutical service platforms, dedicated peptide CDMOs, and catalog-scale research providers. Strategic differentiation hinges on cGMP certification depth, modification chemistry breadth, and regulatory submission support capabilities. Consolidation favors backward integration into analytical services and captive stability testing.
Within the integrated platform tier, Merck KGaA and Thermo Fisher Scientific exemplify pharmaceutical service footprints spanning discovery through commercial API supply. Bachem occupies a position among specialized peptide CDMOs with multi-kilogram manufacturing scale and cyclic peptide expertise. GenScript anchors the Asia-Pacific research market vector with modified and conjugated peptide capabilities. These three represent distinct archetypes—pharmaceutical conglomerate, dedicated synthesis specialist, and regional research service provider—each commanding different procurement relationships based on program maturity and regulatory burden.
| Leading Market Players |
|---|
| Merck KGaA |
| CordenPharma |
| Bachem |
| CSBio |
| CPC Scientific |
| Thermo Fisher Scientific |
| AmbioPharm |
| Auspep |
| GenScript |
| Others |
Value Chain & Pricing Dynamics
Biopharma procurement consolidation from 15-20 suppliers to 3-5 strategic partners is compressing vendor margins while elevating capability premiums for GMP-certified facilities with integrated discovery-to-commercial footprints.
Pricing Analysis
Bundled service contracts spanning medicinal chemistry through regulatory submission command 40-60% premiums over unbundled peptide synthesis transactions. Price differentiation hinges on cGMP certification depth and modification chemistry breadth, with FDA-EMA dual-inspected facilities capturing highest tiers. Pricing pressure stems from Chinese fine chemical export quotas on Fmoc-protected reagents. Biotechnology firms exhibit greatest price sensitivity; large-cap pharmaceutical sponsors prioritize regulatory submission support over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese amino acid derivative production, where export quota policies create input volatility for Fmoc chemistry operations worldwide. Supply concentrates in Switzerland, Germany, and the United States for high-resolution mass spectrometry and preparative HPLC equipment. Raw material dependencies include Fmoc-protected amino acids, coupling reagents, and specialized resins. Tariff exposure on Chinese fine chemical imports represents the dominant structural risk. Distribution runs through CDMO direct contracts and pharmaceutical master service agreements with integrated regulatory support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with peptide-based vaccine platform expansion providing durable demand tailwinds across therapeutic and diagnostic applications.
For Market Incumbents: Deploy barrier technology investments to capture EMA GMP Annex 1 compliance premiums as research-grade facilities face disqualification. Consolidate analytical services and stability testing capabilities to defend against integrated pharmaceutical service platforms. The emerging threat of continuous flow peptide synthesis automation demands captive process development expertise in kilogram-scale campaigns. For New Entrants and Emerging Players: Continuous flow peptide synthesis expertise offers entry into mid-volume therapeutic programs previously requiring batch processing scale. White-space targets include India CDSCO-aligned GMP infrastructure for European and North American outsourcing demand, plus convergent bispecific peptide formats using native chemical ligation. A technology-first go-to-market angle centers on green chemistry compliance with closed-loop Fmoc systems. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized peptide CDMOs holding cyclic peptide expertise and multi-kilogram cGMP manufacturing scale. Long-term viability frames around 5-10 year therapeutic peptide pipeline maturation. Acquisition targets include facilities with isolator technology and single-use sterile API suites. The signal to watch is biopharma procurement panel consolidation velocity toward 3-5 partner structures.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Investment | EMA Annex 1 barrier technology separates qualified suppliers from disqualified research-grade competitors. |
| Continuous Flow Manufacturing Scale-Up | Real-time coupling optimization compresses timelines for kilogram-scale therapeutic peptide campaigns. |
| Green Chemistry Transition | Closed-loop Fmoc systems and aqueous purification align with EPA mandates and EU Green Deal targets. |
| Strategic Partnership Consolidation | Integrated discovery-to-GMP contracts capture procurement panel rationalization toward fewer vendors. |
| Specialized Modification Capability Expansion | Conjugated and cyclic peptide expertise commands premium positioning in oncology drug discovery pipelines. |
Study Parameters
Bottom-up therapeutic application modeling reconciled against top-down CDMO capacity tracking forms the analytical core of this study. Primary interviews with peptide chemistry directors, regulatory affairs leads, biopharma procurement managers, and CDMO business development heads combined with secondary validation from FDA filings, EMA inspection databases, ClinicalTrials.gov peptide therapeutic entries, and Swissmedic registration records. This dual approach enables triangulation between sponsor demand signals and supplier capability investments.
Input-output matrices map peptide complexity tiers, modification requirements, and certification levels against regional production capacity and regulatory cluster alignment across the projection horizon. Segmentation dimensions include product type, synthesis technology, application maturity, and end-user procurement sophistication. CAGRs derive from capacity utilization trends, pipeline progression rates, and therapeutic peptide approval velocity. Industry-specific forecast inputs incorporate Fmoc reagent cost trajectories and GMP certification timeline distributions.
The model holds under steady biopharma outsourcing ratios and stable regulatory inspection protocols; deviation in Chinese export policy or accelerated EMA guideline implementation would shift capacity allocation assumptions. Forecasts reflect documented assumptions about peptide therapeutic pipeline maturation and CDMO consolidation patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Custom Assays Market
Biotechnology Services
Insect Cell Lines Market
Biotechnology Services
Antibody Purification Service Market
Biotechnology Services
Global Protein Binding Assay Market
Biotechnology Services
Biomarker Research Services Market
Biotechnology Services
US Digital PCR Market
Biotechnology Services
Global Reporter Gene Assay Market
Biotechnology Services
Cell Line Development Market
Biotechnology Services
Global Downstream Processing Market
Biotechnology Services
Asia-Pacific Biotechnology Market
Biotechnology Services
Spain Specialty Enzymes Market
Biotechnology Services
In Vivo CRO Market
Biotechnology Services
Marine Polysaccharides Fucoidan Alginate Market
Biotechnology Services
Global DNA and RNA Banking Services Market
Biotechnology Services
Drug Discovery and Development Laboratory Services Market
Biotechnology Services
Plasmid DNA Contract Manufacturing Market