
 Radiopharmaceutical Theranostics Market | 2026-2036
Radiopharmaceutical Theranostics Market Size, Share, and Industry Trends Forecast 2026-2036
Radiopharmaceutical Theranostics Market Outlook
Hospital procurement of radiopharmaceuticals is rewriting supply chain relationships across nuclear medicine departments. Novartis leverages its end-to-end manufacturing network to control isotope sourcing for Lutathera and Pluvicto. Curium Pharma anchors European distribution through its integrated production sites in France and the Netherlands. Telix Pharmaceuticals competes on geographic reach, building regional radiopharmacy partnerships across Australia and North America.
Radiopharmaceutical theranostics pairs diagnostic imaging agents with therapeutic isotopes targeting identical biomarkers, typically using DOTA or PSMA chelators to bind lutetium-177 or actinium-225 to tumor-seeking ligands. Beta emitters currently dominate commercial revenue due to established reimbursement for lutetium-based prostate and neuroendocrine therapies. Alpha emitters represent the fastest-expanding technology segment as actinium-225 trials demonstrate superior linear energy transfer for resistant micrometastases, though manufacturing scale remains constrained.
FDA regulates radiopharmaceuticals under 21 CFR Part 312 and Part 361, while EMA oversees centralized marketing authorizations through the Committee for Medicinal Products for Human Use. Both frameworks require current Good Manufacturing Practice compliance for sterile parenteral production, which limits market entry to firms with validated hot-cell infrastructure. Stakeholders must monitor isotope supply security as reactor aging and geopolitical export controls threaten technetium-99m and molybdenum-99 availability.
Market Dynamics
Actinium-225 production bottlenecks are compressing competitive timelines as developers race to secure cyclotron capacity and reactor partnerships before alpha-emitter therapies reach commercial scale. Supply concentration in isotope sourcing is forcing strategic repositioning across the value chain.
Growth Catalysts
- FDA Parallel Pathway Reviews:Compressed approval timelines for radiopharmaceuticals are accelerating patient access to lutetium-177 and actinium-225 therapies. Academic medical centers are expanding theranostic programs in response.
- Proton Therapy Infrastructure Clusters:Concentrated cyclotron networks in the United States, Germany, and Australia are enabling localized isotope production. These hubs reduce logistics complexity for short-half-life radioisotopes.
- DOTA-PSMA Chelator Standardization:Unified binding chemistry across diagnostic and therapeutic agents is streamlining clinical workflows. Nuclear medicine departments are consolidating training protocols around this platform.
Market Restraints
- Reactor Aging and Export Controls:Technetium-99m and molybdenum-99 availability faces mounting pressure from aging research reactors and geopolitical restrictions on highly enriched uranium.
- Hot-Cell Infrastructure Scarcity:Current Good Manufacturing Practice compliance for sterile parenteral production limits market entry to firms with validated radiopharmacy facilities.
- Actinium-225 Manufacturing Scale:Linear energy transfer advantages for resistant micrometastases remain commercially constrained by production throughput limitations.
Strategic Opportunities
- EMA Centralized Authorizations:The Committee for Medicinal Products for Human Use pathway offers harmonized access across European Union member states. Developers can leverage single regulatory submissions for multi-country market entry.
- Regional Radiopharmacy Partnerships:Distributed production models in Australia and North America are reducing cold-chain logistics burdens. Telix Pharmaceuticals is building geographic reach through this channel structure.
- Neuroendocrine Expansion Beyond Prostate:Lutathera's somatostatin receptor targeting is demonstrating utility in pancreatic and gastrointestinal tumor types. Oncology departments are broadening referral pathways.
Industry Challenges
- Radiochemist Talent Pipeline:Specialized synthesis expertise for short-half-life isotopes remains concentrated in a handful of academic training programs. Workforce development lags behind program expansion timelines.
- Capex Intensity for Cyclotron Installation:Shielding, vault construction, and regulatory licensing for particle accelerator facilities require multi-year capital deployment cycles.
- 21 CFR Part 312 Compliance Complexity:Investigational New Drug applications for radiopharmaceuticals demand extensive radiation dosimetry and biodistribution data. Documentation timelines extend development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiopharmaceutical Theranostics Market |
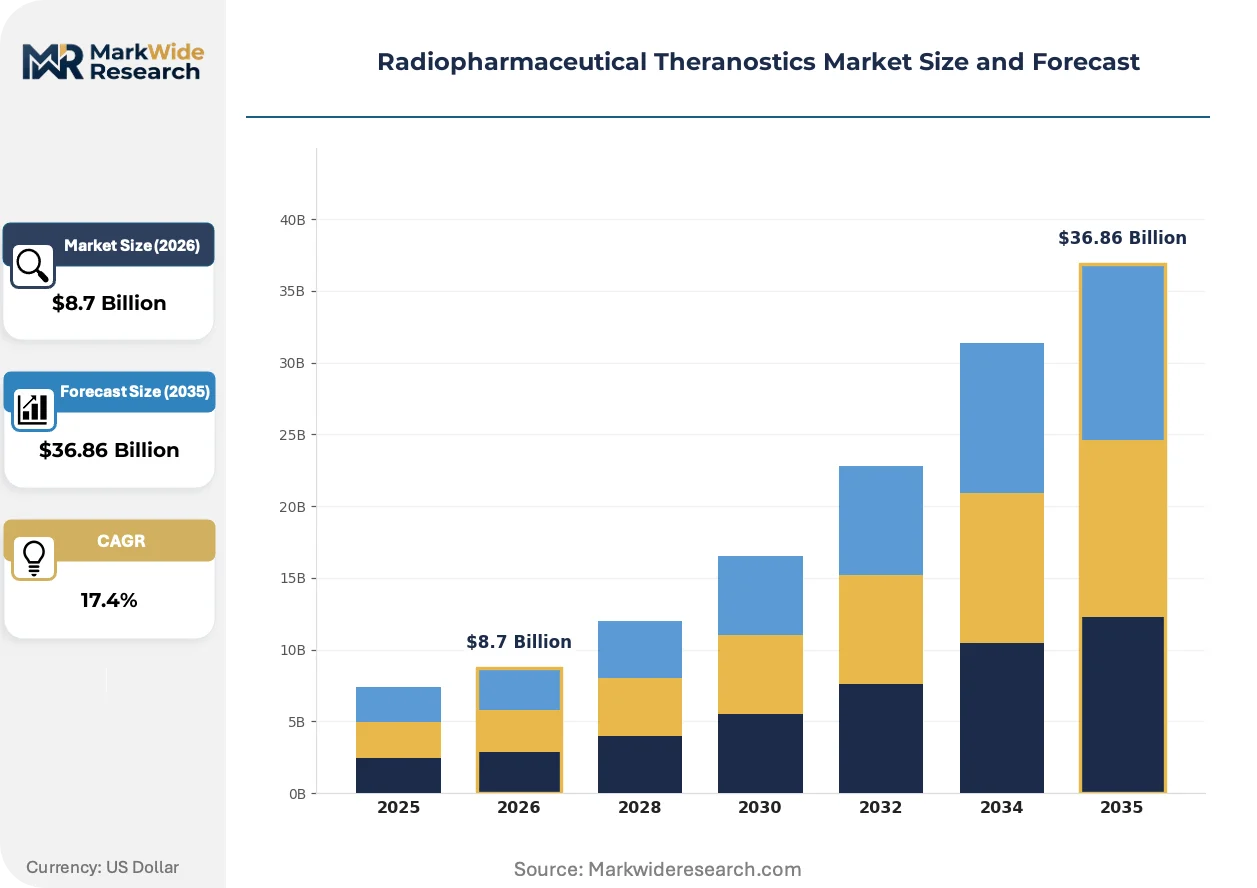
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $36.86 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beta Emitters, Alpha Emitters, PET Radiotracers, SPECT Radiotracers Therapy Area: Oncology, Cardiology, Neurology, Infectious Diseases Delivery Mode: Injectable, Oral, Intranasal, Infusion End User: Hospitals, Research Institutes, Outpatient Clinics, Diagnostic Centers |
| Companies Covered | Lantheus Medical Imaging, Curium Pharma, Novartis, Siemens Healthineers, Advanced Accelerator Applications, Bayer, Telix Pharmaceuticals, Cardinal Health, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiopharmaceutical Theranostics Market Strategic Shifts
Digital twin technology is virtualizing radiopharmaceutical manufacturing workflows, enabling remote process optimization and predictive maintenance across distributed production networks. This shift is compressing validation timelines and reducing physical prototyping requirements.
Artificial intelligence-driven dosimetry platforms are virtualizing patient-specific treatment planning for lutetium-177 and actinium-225 therapies. Nuclear medicine departments at academic medical centers are adopting these tools to personalize radiation dose calculations. The technology is virtualizing traditional blanket-dosing protocols, enabling precision adjustments based on tumor uptake kinetics and organ-at-risk exposure.
REACH regulation updates in the European Union are tightening documentation requirements for radiometal chelators and precursor chemicals. EMA marketing authorization applications now incorporate expanded environmental risk assessments for isotope disposal. Developers targeting European markets are restructuring supply chain audits to capture substance-of-very-high-concern compliance across DOTA and PSMA precursor sourcing.
Hospital procurement departments are consolidating radiopharmaceutical purchasing through centralized nuclear medicine formulary committees. Academic medical centers are displacing transactional vendor relationships with multi-year supply agreements that embed quality metrics and delivery reliability guarantees. Germany's university hospital networks are most advanced in this transition, with procurement teams negotiating isotope allocation priority rights during supply disruptions.
Radiopharmaceutical Theranostics Market Segmentation
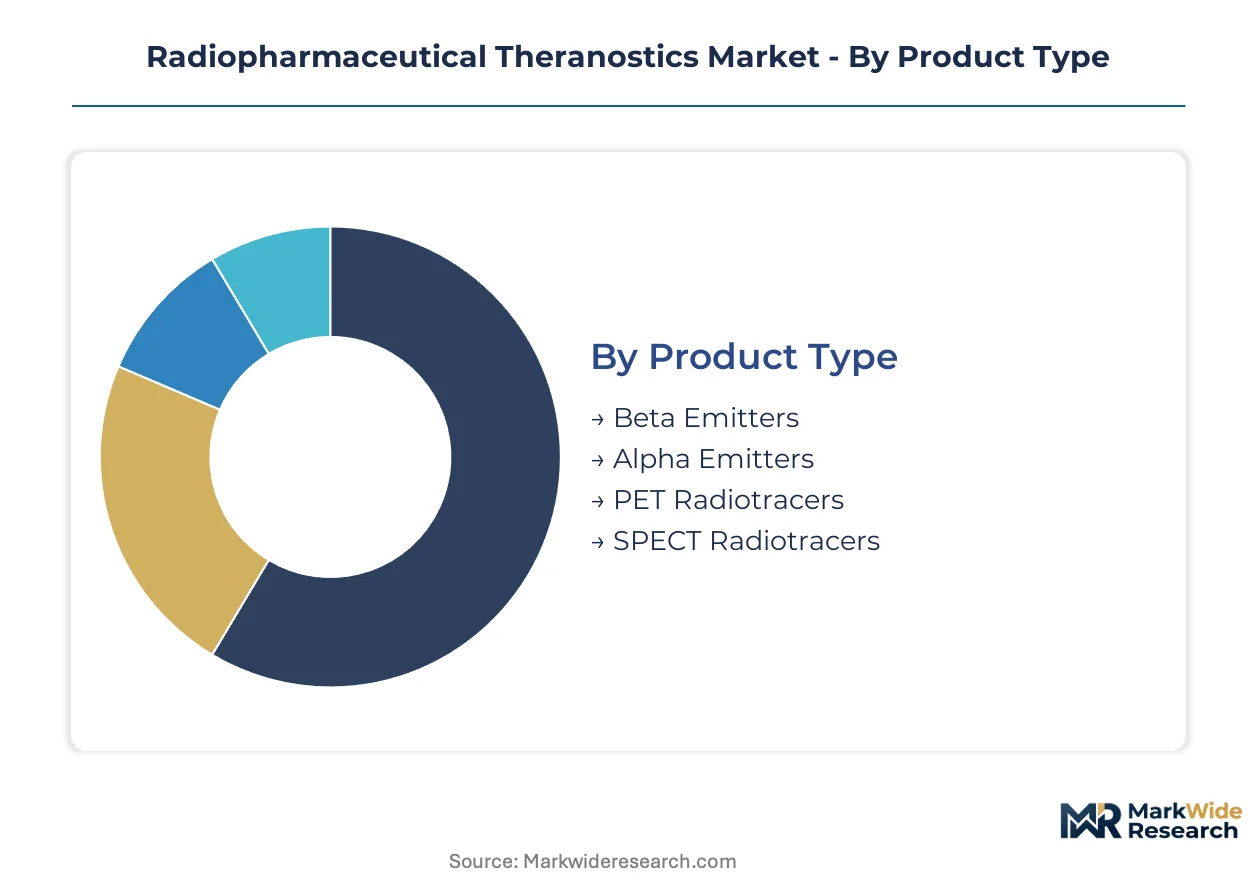
Radiopharmaceutical theranostics segmentation reveals how isotope physics, clinical application, and site-of-care economics divide commercial opportunity. Each dimension carries distinct regulatory, reimbursement, and infrastructure requirements that shape vendor strategy.
Product Type:
Mature beta-emitter platforms anchor near-term revenue while alpha-emitter technology accelerates through clinical validation.
- Beta Emitters:Lutetium-177 conjugates dominate current therapeutic revenue through established DOTA chelation chemistry. Demand concentrates in United States academic medical centers where Pluvicto and Lutathera reimbursement pathways are operational.
- Alpha Emitters:Actinium-225 delivers superior linear energy transfer for resistant micrometastases through targeted alpha therapy. Manufacturing scale constraints limit commercial availability despite promising trial data in prostate and neuroendocrine indications.
- PET Radiotracers:Gallium-68 and fluorine-18 diagnostics enable real-time theranostic pairing with therapeutic isotopes.
- SPECT Radiotracers:Technetium-99m agents remain workhorses for functional imaging despite reactor supply vulnerabilities.
Beta emitters retain volume leadership; alpha emitters hold the steepest expansion curve.
Therapy Area:
Oncology commands investment intensity while cardiology and neurology build evidence bases for expansion.
- Oncology:PSMA-targeted prostate therapies and somatostatin receptor neuroendocrine treatments generate the majority of commercial activity. United States proton therapy clusters in Texas, Florida, and California concentrate patient access infrastructure.
- Cardiology:Myocardial perfusion imaging with technetium-99m sestamibi represents a mature diagnostic segment with limited theranostic crossover potential.
- Neurology:Amyloid and tau PET tracers for Alzheimer's disease are gaining CMS reimbursement traction.
- Infectious Diseases:White blood cell labeling for occult infection localization serves niche hospital demand.
Oncology retains volume leadership; neurology holds the steepest expansion curve.
Delivery Mode:
Injectable administration dominates due to isotope half-life constraints and vascular targeting requirements.
- Injectable:Intravenous infusion of radiolabeled antibodies and small molecules constitutes the standard of care for lutetium-177 and actinium-225 therapies. Germany's university hospital networks have standardized infusion protocols across multiple sites.
- Oral:Iodine-131 thyroid therapies represent the primary oral radiopharmaceutical application with established outpatient protocols.
- Intranasal:Experimental olfactory nerve targeting for central nervous system delivery remains preclinical.
- Infusion:Continuous administration modalities are emerging for fractionated dose regimens in radiosensitive tumor types.
Injectable routes retain volume leadership; specialized infusion holds the steepest expansion curve.
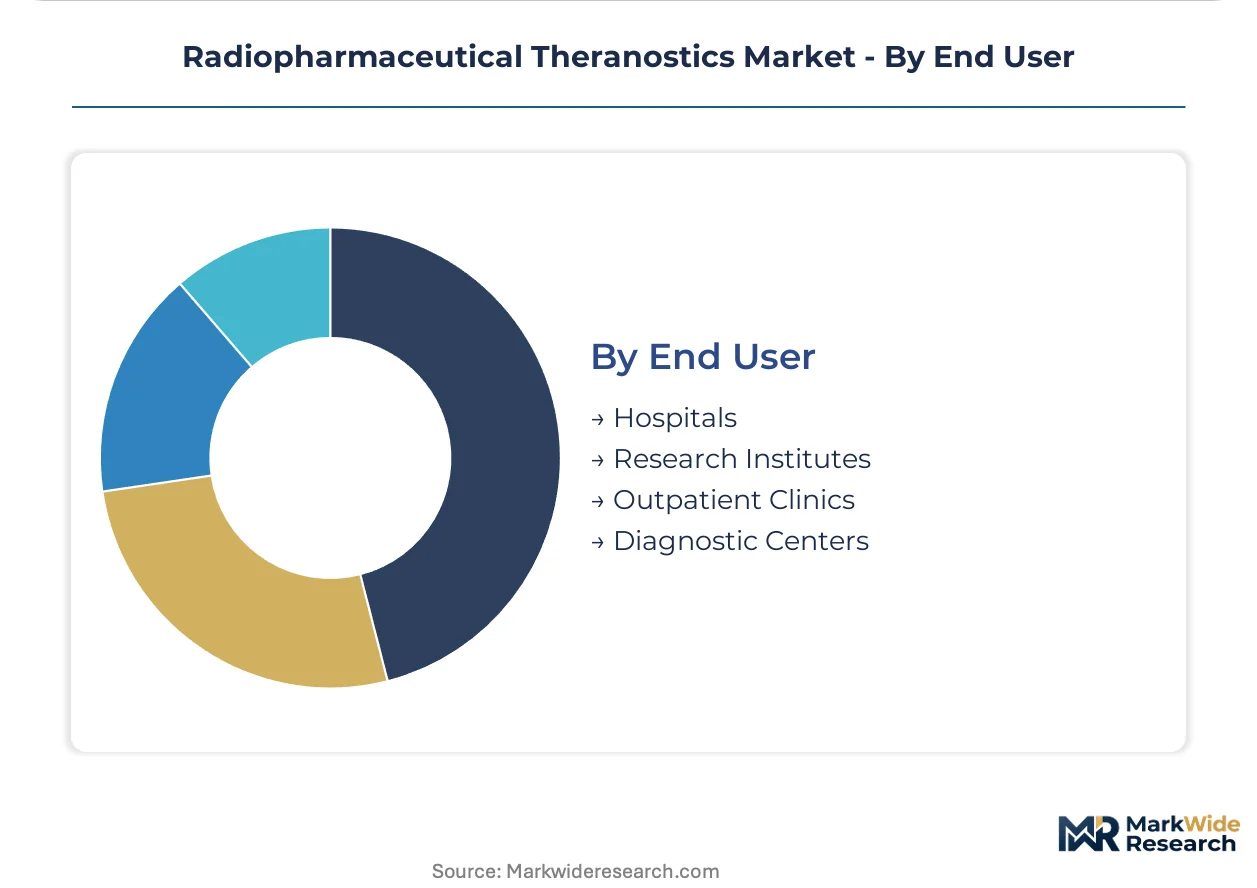
End User:
Site-of-care economics favor hospital-based administration due to radiation safety and reimbursement complexity.
- Hospitals:Academic medical centers with cyclotron infrastructure and nuclear medicine residency programs control the majority of therapeutic procedures. Australia's Peter MacCallum Cancer Centre and Royal North Shore Hospital anchor regional theranostic networks.
- Research Institutes:Phase I/II trial execution and radiochemistry method development occur primarily at National Cancer Institute-designated centers.
- Outpatient Clinics:Freestanding nuclear medicine facilities are expanding in United States markets with favorable state radiation licensing.
- Diagnostic Centers:Imaging-only sites handle PET and SPECT diagnostics without therapeutic administration capabilities.
Hospitals retain volume leadership; outpatient clinics hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cyclotron networks and reactor infrastructure anchor regional participation in radiopharmaceutical theranostics. Proton therapy clusters concentrate patient access and isotope production capabilities in specific metropolitan corridors.
United States
Academic medical centers in Texas, Florida, and California drive therapeutic procedure volume through established proton therapy infrastructure. FDA parallel pathway reviews under 21 CFR Part 312 compress approval timelines for lutetium-177 and actinium-225 therapies. Houston's Texas Medical Center anchors the nation's largest theranostic patient access network with integrated cyclotron production.
Germany
University hospital networks standardize infusion protocols across multiple sites with concentrated cyclotron capacity in Bavaria and North Rhine-Westphalia. EMA centralized marketing authorizations through the Committee for Medicinal Products for Human Use enable harmonized EU market entry. Munich's university hospital cluster leads European theranostic program expansion with dedicated radiopharmacy facilities.
Australia
Peter MacCallum Cancer Centre and Royal North Shore Hospital anchor regional theranostic networks with TGA oversight of radiopharmaceutical manufacturing. The country's cyclotron infrastructure concentrates in Melbourne and Sydney metropolitan corridors. Lucas Heights nuclear facility supports domestic isotope production for actinium-225 development programs.
France
Curium Pharma's integrated production sites in Paris and the Netherlands anchor European distribution with ANSM regulatory oversight. The country's reactor heritage supports technetium-99m and molybdenum-99 production for diagnostic applications. Paris-Saclay research cluster concentrates radiochemistry expertise and clinical trial execution.
Switzerland
Novartis leverages end-to-end manufacturing networks with Swissmedic oversight of sterile parenteral production. Basel anchors pharmaceutical radiochemistry development with proximity to German and French cyclotron networks. The country's hot-cell infrastructure supports validated current Good Manufacturing Practice compliance for commercial supply.
Radiopharmaceutical Theranostics Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in isotope sourcing and chelator chemistry. The vendor base structures around three archetypes: end-to-end manufacturers controlling isotope-to-patient supply chains, regional radiopharmacy operators building distributed production networks, and diagnostic imaging equipment suppliers enabling theranostic pairing. Consolidation pressures favor multi-year supply agreements embedding quality metrics over transactional procurement. Capacity expansion in cyclotron infrastructure and strategic partnerships for actinium-225 access represent dominant competitive moves.
Within the end-to-end manufacturer tier, Novartis and Curium Pharma exemplify platform control through integrated production networks. Telix Pharmaceuticals occupies a position among geography-focused developers building regional radiopharmacy partnerships. Siemens Healthineers and GE Healthcare anchor the diagnostic imaging equipment segment enabling theranostic workflow integration.
| Leading Market Players |
|---|
| Lantheus Medical Imaging |
| Curium Pharma |
| Novartis |
| Siemens Healthineers |
| Advanced Accelerator Applications |
| Bayer |
| Telix Pharmaceuticals |
| Cardinal Health |
| GE Healthcare |
| Others |
Value Chain & Pricing Dynamics
Cyclotron undercapacity in Australia and Germany is concentrating pricing power among incumbent isotope suppliers while forcing buyers into multi-year offtake commitments that lock in volume-discount tiers. This utilization squeeze cascades through contract structures, with academic medical centers trading price premiums for allocation priority during supply disruptions.
Pricing Analysis
Volume-discount tiering separates academic medical center consortiums from individual hospital purchasers from research-only institutes. Pricing stratifies across premium, standard, and economy tiers based on GMP certification level and cold-chain reliability guarantees. Cost compression in the economy tier is intensifying because reactor maintenance outages are forcing spot-market sourcing. Research institutes exhibit highest price sensitivity due to grant-funded procurement cycles, while proton therapy clusters in Texas and Florida show lowest sensitivity given reimbursement pass-through structures.
Supply Chain Analysis
Upstream feedstock concentration in the United States, Germany, and Australia anchors isotope production networks for lutetium-177 and actinium-225. The supply chain draws from molybdenum-99 reactor targets, DOTA chelator precursor chemicals, and sterile hot-cell manufacturing capacity. Single-source vulnerability in actinium-225 production creates bottleneck exposure as developers race for cyclotron partnerships. Distribution runs through regional radiopharmacy hubs that consolidate last-mile logistics for short-half-life products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radiopharmaceutical theranostics sits in early-cycle expansion as FDA parallel pathway reviews compress approval timelines and academic medical centers scale dedicated theranostic programs. Alpha-emitter clinical validation represents the primary penetration tailwind accelerating addressable patient population expansion.
For Market Incumbents: Insulate cyclotron capacity positions through captive supply agreements with university hospital networks before actinium-225 reaches commercial scale. Secure backward integration into DOTA chelator sourcing to offset REACH compliance cost inflation in European markets. Prioritize GMP certification maintenance as regulatory scrutiny intensifies for sterile parenteral production. For New Entrants and Emerging Players: Regional radiopharmacy partnerships in underserved Australian and North American corridors represent the most penetrable entry point for distributed production models. Alpha-emitter manufacturing scale partnerships with national reactor facilities offer differentiated access versus crowded beta-emitter competition. Pursue hospital formulary committee relationships through embedded quality metric guarantees rather than transactional bidding. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among end-to-end manufacturers controlling isotope-to-patient supply chains through integrated production networks. Long-term viability over the coming decade rests on cyclotron infrastructure ownership and therapeutic pipeline diversification beyond prostate and neuroendocrine indications. Watch for EMA centralized authorization approvals as inflection signals for European market access scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Capacity Expansion | Proton therapy clusters in Texas and Florida require localized isotope production to reduce logistics complexity for short-half-life radioisotopes. |
| Actinium-225 Manufacturing Scale-Up | Linear energy transfer advantages for resistant micrometastases remain commercially constrained without reactor partnership security. |
| EMA Centralized Authorization Pathway | Committee for Medicinal Products for Human Use submissions enable harmonized multi-country market entry across EU member states. |
| Regional Radiopharmacy Partnerships | Telix Pharmaceuticals builds geographic reach through distributed production models reducing cold-chain burdens in Australia and North America. |
| AI-Driven Dosimetry Platform Integration | Academic medical centers adopt patient-specific treatment planning tools virtualizing traditional blanket-dosing protocols for precision adjustment. |
Study Parameters
A spread of perspectives from nuclear medicine department heads, radiopharmacy operations directors, regulatory affairs specialists, and hospital procurement managers converged on the working assumptions underlying supply-demand balances. Primary fieldwork combined structured interviews with secondary validation against FDA 21 CFR Part 312 filings, EMA centralized marketing authorization submissions, ClinicalTrials.gov radiopharmaceutical entries, and hospital formulary database records. Bottom-up patient-flow modeling and top-down cyclotron capacity estimates were triangulated to anchor volume projections.
Demand-supply-balance framing structured the analytical approach across the projection horizon, with segmentation dimensions spanning isotope physics category, therapy area concentration, delivery mode complexity, and end-user site-of-care economics. CAGRs were derived from installed cyclotron base expansion rates, reimbursement pathway activation timelines, and clinical trial enrollment trajectories. Forecast inputs incorporated actinium-225 production throughput constraints and DOTA-PSMA chelator standardization adoption curves.
Practitioners should monitor reactor maintenance schedules, geopolitical export control adjustments, and alpha-emitter clinical readout timing for early signals requiring forecast revision. Cross-checking against CMS Medicare reimbursement rate publications and EMA marketing authorization approval databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Incretin-Based Drugs Market
Biopharmaceuticals
NF-KB Inhibitors Market
Biopharmaceuticals
Russia Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
France Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
US Generic Drug Market
Biopharmaceuticals
Acitretin Market
Biopharmaceuticals
Antimycobacterial Drugs Market
Biopharmaceuticals
Global Mono Vaccine Market
Biopharmaceuticals
Biological Drugs Market
Biopharmaceuticals
Gosling Plague Vaccine Market
Biopharmaceuticals
Purified Protein Derivative Market
Biopharmaceuticals
Global Cytokine Market
Biopharmaceuticals
Liposomal Doxorubicin Market
Biopharmaceuticals
Ovarian Cancer Drugs Market
Biopharmaceuticals
Discovery Bioanalysis Market
Biopharmaceuticals
Biopharmaceutical Oral Drug Delivery Market