
 Global MRSA Drugs Market | 2026-2036
Global MRSA Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global MRSA Drugs Market Outlook
Antimicrobial stewardship expertise is rotating from broad-spectrum empiric therapy toward pathogen-directed MRSA protocols, tightening formulary control in tertiary centers. Pfizer leverages its hospital channel infrastructure to sustain vancomycin-combination positioning across integrated delivery networks. Merck anchors institutional contracts through its anti-infectives portfolio, while Basilea Pharmaceutica specializes in beta-lactamase-resistant cephalosporin development for resistant gram-positive infections.
MRSA drugs comprise antibacterial agents engineered to inhibit or kill methicillin-resistant Staphylococcus aureus through mechanisms targeting altered penicillin-binding proteins or disrupting membrane integrity, with daptomycin requiring calcium-dependent insertion into bacterial cytoplasmic membranes for bactericidal activity. Linezolid competes as the oral option of choice for outpatient parenteral antimicrobial therapy transitions, whereas intravenous daptomycin dominates revenue pools in bloodstream infection protocols where nephrotoxicity concerns limit vancomycin exposure. Skin infection indications occupy the highest volume tier, though bacteremia applications command premium pricing due to longer treatment durations and higher acuity monitoring requirements.
FDA QIDP and EMA priority medicines pathways shape clinical trial investment by granting extended exclusivity for novel MRSA-active compounds, while WHO antimicrobial resistance stewardship frameworks pressure hospitals to restrict empiric vancomycin use. The European F-Gas Regulation indirectly affects cold-chain logistics for temperature-sensitive lipopeptide formulations, raising distribution compliance costs. Stakeholders must monitor FDA advisory committee signals on new chemical entity approvals versus generic linezolid erosion to time portfolio rebalancing decisions.
Market Dynamics
Antimicrobial stewardship protocols are forcing hospitals to abandon empiric vancomycin monotherapy in favor of pathogen-directed MRSA regimens, compressing formulary slots and rewarding agents with rapid bactericidal kinetics.
Growth Catalysts
- FDA QIDP Designation:Extended exclusivity incentives accelerate novel lipopeptide and oxazolidinone development timelines, attracting venture capital toward resistant gram-positive therapeutics.
- Medicare Reimbursement Bundles:Diagnostic-therapy alignment incentives in US hospital systems favor rapid pathogen identification platforms that enable targeted MRSA therapy initiation.
- Bacteremia Protocol Expansion:Tertiary care centers are embedding daptomycin and linezolid into standardized bloodstream infection order sets, creating institutional demand pull.
Market Restraints
- Generic Linezolid Erosion:Patent expiry has collapsed oral oxazolidinone pricing, constraining revenue pools for novel agents in skin infection indications.
- Cold-Chain Distribution Costs:The European F-Gas Regulation raises compliance expenses for temperature-sensitive lipopeptide formulations, squeezing margins in EU markets.
- Nephrotoxicity Substitution Ceiling:Vancomycin retains formulary presence in renal-insured populations where daptomycin monitoring costs exceed therapeutic switching benefits.
Strategic Opportunities
- Outpatient Parenteral Transition Pathways:Oral linezolid substitution for intravenous therapy in US home-infusion networks shortens hospital length-of-stay and captures post-acute care spend.
- Combination Regimen Development:Beta-lactamase-resistant cephalosporin pairings with novel agents address polymicrobial bacteremia where monotherapy faces resistance selection pressure.
- Integrated Delivery Network Contracts:Pfizer and Merck are anchoring multi-year anti-infectives agreements that bundle MRSA agents with broader hospital antibiotic portfolios.
Industry Challenges
- Clinical Trial Enrollment Friction:Declining MRSA bacteremia incidence in US tertiary centers complicates Phase III non-inferiority study powering and extends development timelines.
- Stewardship Committee Gatekeeping:Pharmacy and therapeutics committees require real-world evidence packages beyond registration trials to justify premium novel agent formulary addition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global MRSA Drugs Market |
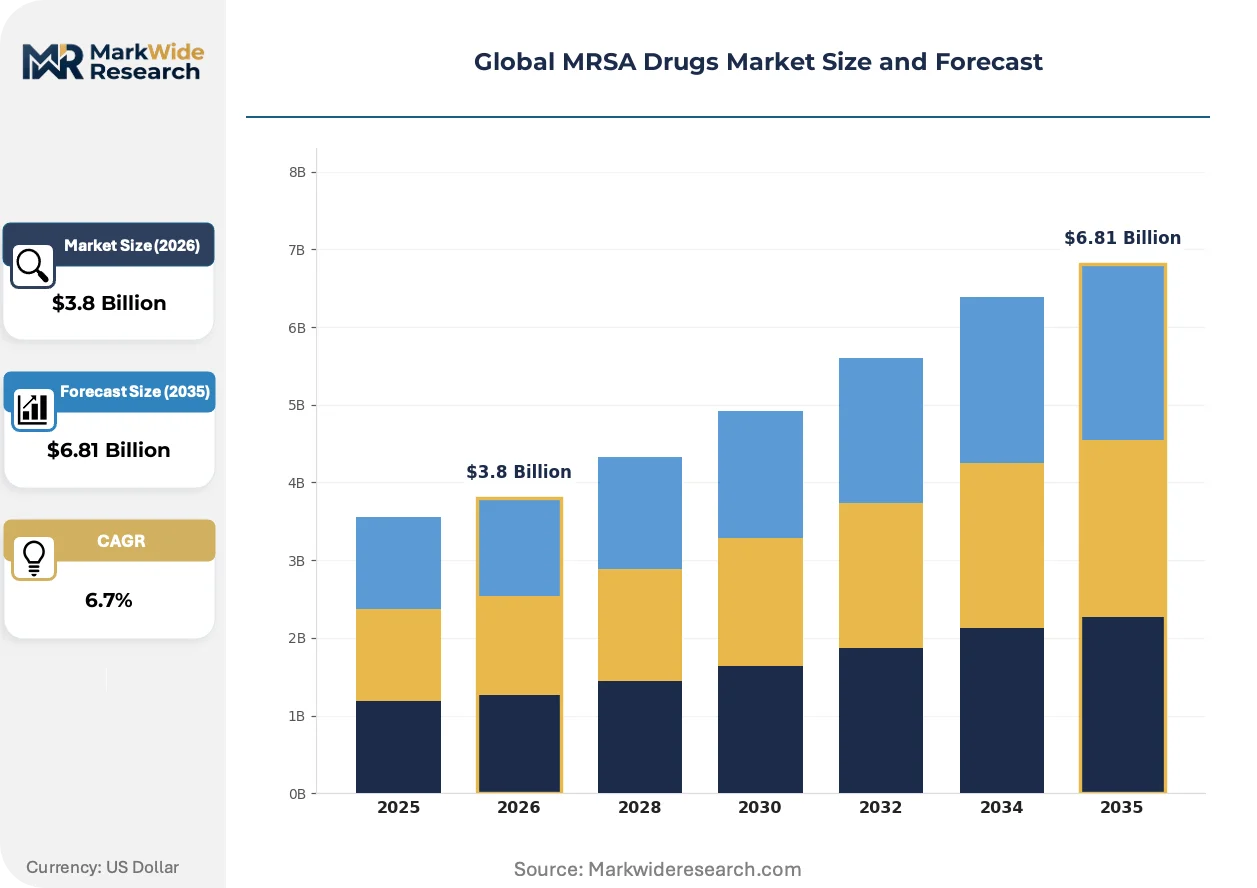
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Daptomycin, Linezolid, Telavancin, Ceftaroline Delivery Mode: Intravenous, Oral, Intramuscular, Topical Indication: Skin Infections, Bacteremia, Pneumonia, Osteomyelitis End User: Hospitals, Clinics, Homecare, Long-term Care Facilities |
| Companies Covered | Pfizer, Merck, AbbVie, Johnson & Johnson, Allergan, Theravance Biopharma, Melinta Therapeutics, Cumberland Pharmaceuticals, Basilea Pharmaceutica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global MRSA Drugs Market Strategic Shifts
Next-generation MRSA therapeutics are diverging toward rapid bactericidal mechanisms and oral bioavailability, with development pipelines prioritizing agents that escape existing resistance pathways and enable outpatient therapy transitions.
Lipopeptide engineering is bifurcating between calcium-dependent membrane insertion variants for bloodstream infections and chemically modified analogs with reduced plasma protein binding for enhanced tissue penetration. Academic medical centers in the United States are piloting these agents in osteomyelitis protocols where traditional glycopeptide penetration limits efficacy. The structural consequence is compressing vancomycin AUC-guided dosing algorithms in favor of fixed-dose lipopeptide regimens that simplify pharmacy operations.
The European F-Gas Regulation is mandating refrigerant phase-downs that indirectly disrupt cold-chain logistics for temperature-sensitive parenteral formulations, forcing distributors to retrofit warehouse infrastructure or absorb compliance penalties. Manufacturers with EU manufacturing footprints are consolidating distribution partnerships to share upgraded cold-storage capital burdens. Small-volume lipopeptide producers without scale economies face geographic market exit or third-party logistics dependency.
Hospital procurement committees are unbundling anti-infective purchasing from broad-spectrum antibiotic bundles, creating standalone MRSA agent contracting vehicles that reward clinical outcome guarantees over volume discounts. Integrated delivery networks in the United States are piloting these risk-sharing arrangements where formulary placement ties to readmission rate performance. The shift is most visible in Medicare Advantage–aligned health systems where total cost of care accountability compresses empiric therapy duration.
Global MRSA Drugs Market Segmentation
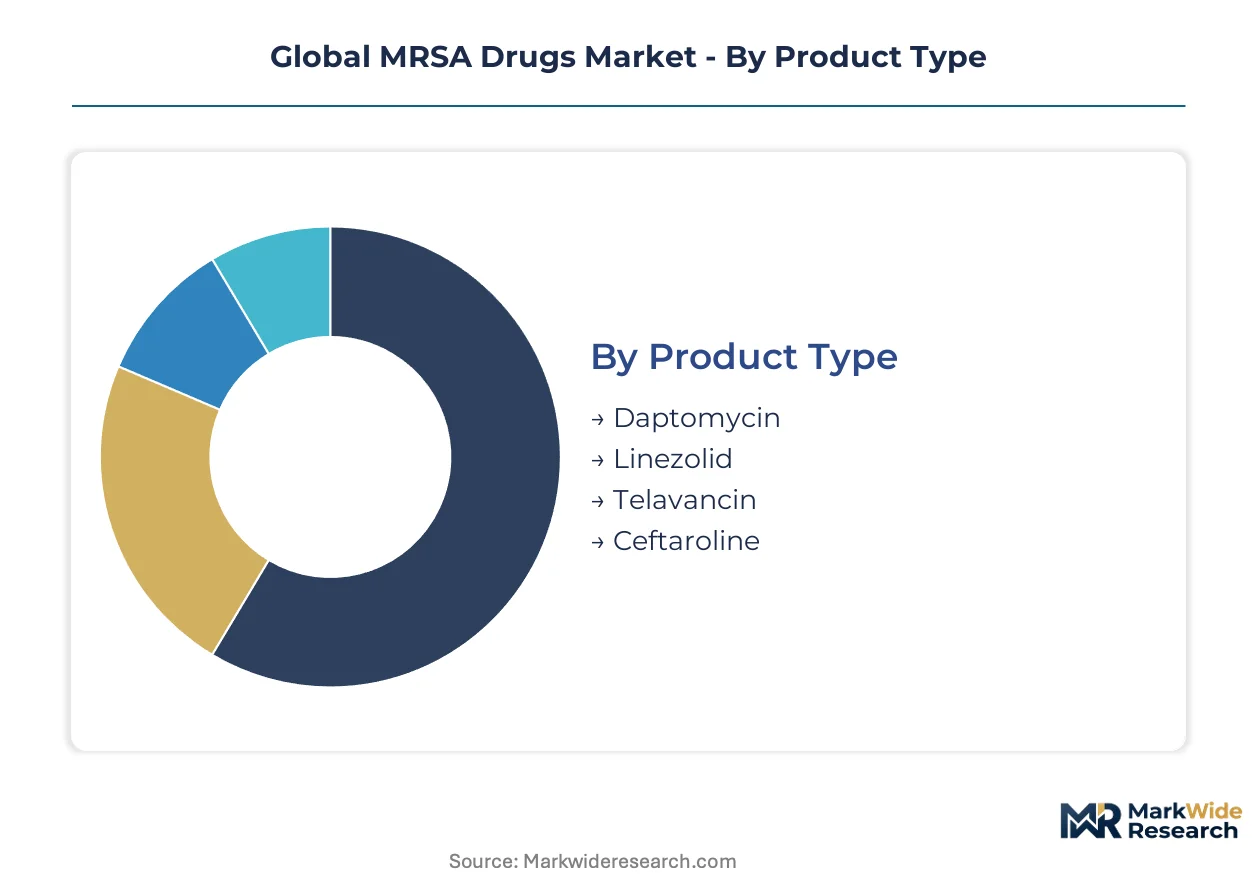
MRSA drug segmentation reveals divergent commercial dynamics across administration routes and care settings. Product-level differentiation concentrates in lipopeptide and oxazolidinone mechanisms, while delivery mode shapes reimbursement pathways and patient acuity tiers.
Product Type:
Daptomycin and linezolid anchor hospital procurement contracts in the United States, whereas telavancin and ceftaroline penetration varies by European formulary acceptance.
- Daptomycin:Calcium-dependent lipopeptide inserting into bacterial cytoplasmic membranes achieves rapid bactericidal activity against resistant gram-positive pathogens. United States tertiary centers embed this agent into bloodstream infection protocols where vancomycin nephrotoxicity limits exposure. Medicare reimbursement bundles favor its use in bacteremia with rapid pathogen identification.
- Linezolid:Oxazolidinone class agent inhibits protein synthesis through 50S ribosomal subunit binding, offering complete oral bioavailability for outpatient parenteral antimicrobial therapy transitions. United States home-infusion networks exploit this pharmacokinetic profile to shorten hospital length-of-stay and capture post-acute care spend.
- Telavancin:Lipoglycopeptide with dual mechanism of membrane disruption and cell wall synthesis inhibition requires renal monitoring that constrains formulary adoption in European markets.
- Ceftaroline:Beta-lactamase-resistant cephalosporin targets altered penicillin-binding proteins in community-acquired MRSA, finding niche positioning in polymicrobial skin infection protocols.
Daptomycin holds the largest share; momentum sits with linezolid oral transitions.
Delivery Mode:
Route selection dictates care setting economics, with intravenous administration commanding premium pricing in inpatient environments and oral formulations enabling cost-shifting to outpatient networks.
- Intravenous:Parenteral lipopeptide and glycopeptide administration dominates revenue pools in bacteremia indications requiring continuous monitoring and therapeutic drug monitoring protocols.
- Oral:Linezolid oral bioavailability eliminates infusion infrastructure requirements, positioning this route for United States Medicare Advantage home-infusion cost containment strategies.
- Intramuscular:Limited MRSA-specific applications concentrate in resource-constrained settings where vascular access is problematic, with ceftriaxone-combination regimens occasionally substituting.
- Topical:Mupirocin and retapamulin formulations address localized skin colonization in nasal decolonization protocols and minor cutaneous infections outside systemic therapy pathways.
Intravenous delivery captures the highest value per patient; oral routes are expanding most quickly through outpatient transition protocols.
Indication:
Acuity tiers separate skin infection volume from bacteremia pricing power, with osteomyelitis emerging as a contested indication for next-generation tissue-penetrating agents.
- Skin Infections:Abscess, cellulitis, and wound infection indications generate the highest prescription volumes though generic linezolid erosion has compressed margins in outpatient settings.
- Bacteremia:Bloodstream infections command premium pricing through extended treatment durations, intensive monitoring requirements, and mortality risk that justifies novel agent expenditure in United States tertiary centers.
- Pneumonia:Healthcare-associated and ventilator-associated MRSA pneumonia maintains vancomycin formulary presence despite nephrotoxicity concerns, with linezolid competing in penicillin-allergic populations.
- Osteomyelitis:Bone and joint infections challenge traditional glycopeptide penetration, creating evaluation pathways for lipopeptide analogs with reduced plasma protein binding in United States academic medical centers.
Skin infections occupy the volume tier; bacteremia applications command the steepest expansion trajectory in revenue per treated patient.
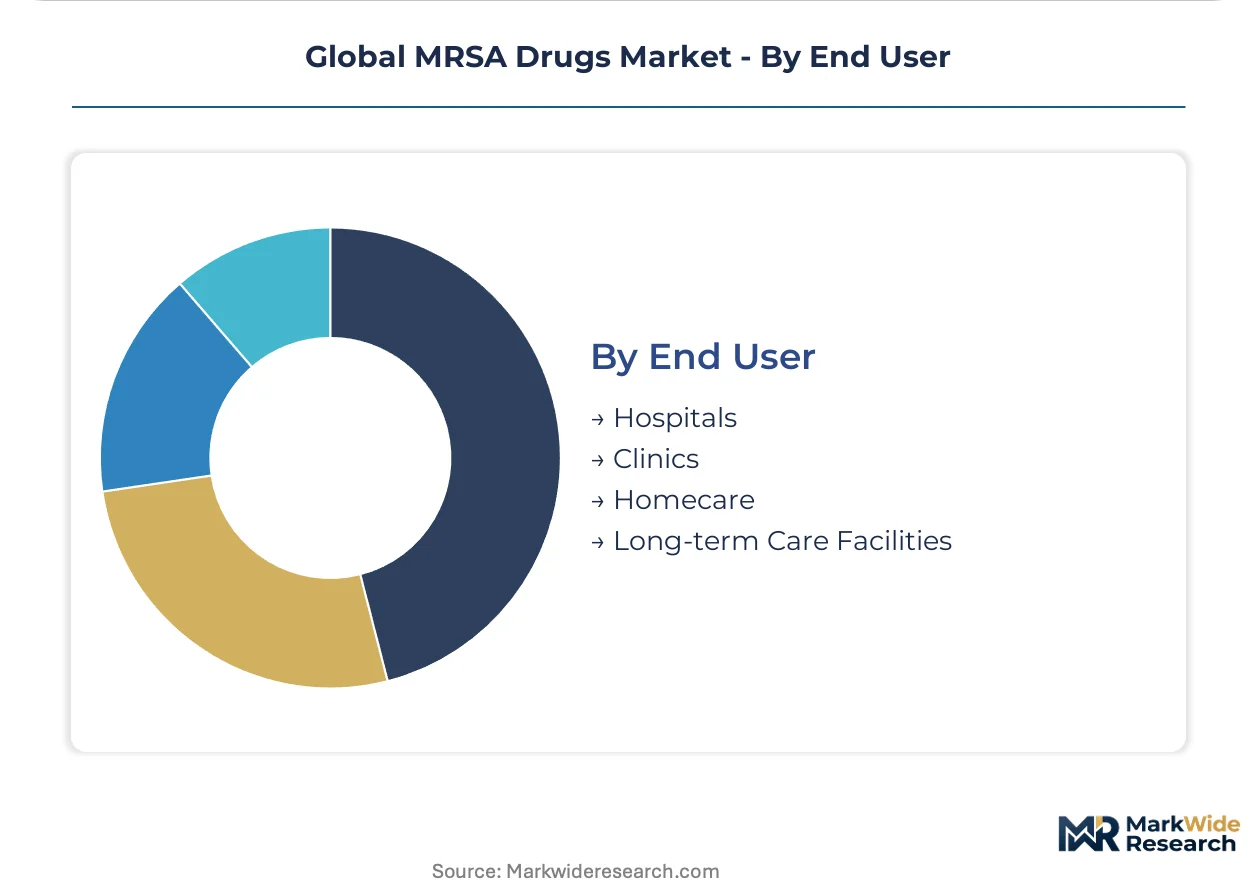
End User:
Care setting fragmentation concentrates procurement authority in United States integrated delivery networks, while European hospital systems maintain centralized pharmacy and therapeutics committee control.
- Hospitals:Inpatient bacteremia protocols and antimicrobial stewardship committees drive formulary decisions, with Pfizer and Merck anchoring multi-year anti-infectives contracts across United States health systems.
- Clinics:Outpatient infusion centers and infectious disease specialty practices manage oral transition pathways, capturing post-discharge therapy in Medicare reimbursement structures.
- Homecare:United States home-infusion networks exploit linezolid oral bioavailability to reduce hospital length-of-stay, with risk-sharing arrangements tying formulary placement to readmission performance.
- Long-term Care Facilities:Skilled nursing facilities face heightened MRSA colonization pressure, though stewardship constraints limit systemic therapy initiation outside acute exacerbation transfers.
Hospitals retain the dominant procurement position; homecare networks are gaining share fastest through oral transition economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement patterns diverge sharply between United States Medicare-reimbursed systems and European centralized pharmacy frameworks, with oral transition economics dominating North American demand while cold-chain compliance costs constrain lipopeptide distribution across EU markets.
United States
Integrated delivery networks in the United States embed daptomycin and linezolid into standardized bacteremia order sets, with Medicare reimbursement bundles rewarding rapid pathogen identification platforms. The FDA's QIDP designation accelerates novel agent development timelines through extended exclusivity incentives. Academic medical centers in Boston and the Research Triangle pilot lipopeptide analogs in osteomyelitis protocols where glycopeptide penetration limits efficacy.
Germany
German hospital pharmacies maintain centralized antimicrobial stewardship committee control over formulary decisions, with EMA priority medicines pathways shaping clinical trial investment for resistant gram-positive therapeutics. The European F-Gas Regulation mandates refrigerant phase-downs that raise distribution compliance costs for temperature-sensitive lipopeptide formulations. Pharmaceutical clusters in Baden-Württemberg and North Rhine-Westphalia consolidate cold-storage infrastructure to share upgraded capital burdens.
Japan
Japanese tertiary centers prioritize oral bioavailability for outpatient parenteral antimicrobial therapy transitions, with METI industrial policy supporting domestic beta-lactamase-resistant cephalosporin development. The PMDA accelerates review timelines for novel MRSA-active compounds addressing antimicrobial resistance stewardship frameworks. Medical institutions in the Kanto and Kansai regions evaluate next-generation tissue-penetrating agents in polymicrobial skin infection protocols.
India
Indian hospital systems face heightened MRSA colonization pressure in tertiary referral networks, with CDSCO regulatory pathways enabling accelerated generic linezolid manufacturing for cost-sensitive institutional procurement. The country's national pharmaceutical regulator emphasizes local production incentives under domestic manufacturing schemes. Healthcare clusters in Maharashtra and Karnataka pilot combination regimen development addressing polymicrobial bacteremia where monotherapy faces resistance selection pressure.
United Kingdom
United Kingdom NHS trusts implement antimicrobial stewardship protocols that restrict empiric vancomycin use in favor of pathogen-directed regimens, with NICE technology appraisals guiding formulary placement for novel agents. MHRA regulatory alignment with EMA pathways facilitates priority review for QIDP-equivalent designations. London and Southeast England academic centers generate real-world evidence packages beyond registration trials to justify premium novel agent adoption.
Global MRSA Drugs Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with hospital channel infrastructure and anti-infectives portfolio breadth determining contract anchoring capacity. The upper tier commands multi-year integrated delivery network agreements that bundle MRSA agents with broader antibiotic portfolios. Mid-tier specialists concentrate on beta-lactamase-resistant cephalosporin development or lipopeptide engineering for niche tissue-penetration indications. Competitive moves center on formulary anchoring through clinical outcome guarantees and geographic consolidation of cold-chain distribution partnerships to absorb F-Gas compliance costs.
Among integrated pharmaceutical conglomerates, Pfizer and Merck occupy positions exemplifying hospital channel dominance through anti-infectives portfolio breadth and institutional contract anchoring. Within the specialist tier, Basilea Pharmaceutica represents the beta-lactamase-resistant cephalosporin development archetype, targeting resistant gram-positive infections through mechanism-focused R&D. These three entities collectively illustrate the market's bifurcation between scale-driven bundling strategies and targeted therapeutic innovation.
| Leading Market Players |
|---|
| Pfizer |
| Merck |
| AbbVie |
| Johnson & Johnson |
| Allergan |
| Theravance Biopharma |
| Melinta Therapeutics |
| Cumberland Pharmaceuticals |
| Basilea Pharmaceutica |
| Others |
Value Chain & Pricing Dynamics
FDA's QIDP designation gates both supply qualification timelines and price differentiation tiers for novel MRSA-active compounds, compressing development economics for lipopeptide entrants while anchoring premium positioning for agents securing extended exclusivity. This regulatory threshold simultaneously shapes hospital procurement willingness-to-pay and manufacturer cold-chain infrastructure investment thresholds.
Pricing Analysis
Long-term institutional contracts anchor MRSA drug pricing, with integrated delivery networks negotiating multi-year anti-infectives bundles that embed daptomycin and linezolid into standardized bacteremia order sets. Price differentiation separates agents with oral bioavailability for outpatient transitions from intravenous-only formulations requiring infusion infrastructure. Cost compression in skin infection indications intensifies due to generic linezolid erosion, whereas bacteremia applications maintain pricing resilience through mortality-risk justification. Medicare Advantage health systems exhibit highest price sensitivity in post-acute care transitions, while tertiary centers prioritize clinical outcome guarantees over per-unit discounts.
Supply Chain Analysis
Cold-chain logistics chokepoints concentrate lipopeptide distribution reliability, with temperature-sensitive formulations demanding continuous refrigeration from United States manufacturing through hospital pharmacy receipt. Active pharmaceutical ingredient sourcing draws from India and China for generic oxazolidinone precursors, while novel agent synthesis anchors in United States and European contract manufacturing networks. Single-source vulnerability persists in specialized lipopeptide fill-finish capacity, where limited FDA-inspected sites constrain batch release velocity. Distribution runs through consolidated wholesale distributors with hospital-direct drop capabilities, though European F-Gas Regulation compliance costs are forcing geographic partnership restructuring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generic linezolid erosion and oral transition economics threaten incumbent revenue pools, forcing substitution defense through novel mechanism development and institutional contract anchoring.
For Market Incumbents: Compound formulary stickiness through clinical outcome guarantees tied to readmission rate performance in Medicare Advantage networks, while accelerating lipopeptide analog development for osteomyelitis indications where glycopeptide penetration fails. Backward integration into cold-chain distribution partnerships absorbs F-Gas compliance cost pressures in European markets.
For New Entrants and Emerging Players: FDA QIDP fast-track designation offers regulatory acceleration for beta-lactamase-resistant cephalosporin candidates targeting polymicrobial bacteremia, where resistance selection pressure creates white-space opportunity. Homecare networks in United States Medicare reimbursement structures represent the most penetrable channel, with oral bioavailability enabling direct-to-payer contracting bypassing hospital gatekeeping.
For Investors and Strategic Acquirers: EMA priority medicines pathway reshapes the acquisition landscape toward European clinical trial infrastructure and real-world evidence generation capabilities. Mid-tier specialists with beta-lactamase-resistant development programs and existing hospital formulary relationships offer viable target profiles. Watch FDA advisory committee signals on new chemical entity approvals versus accelerated generic erosion as the inflection indicator for portfolio rebalancing timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III non-inferiority studies in bacteremia indications secure QIDP extended exclusivity for lipopeptide candidates. |
| Regulatory Approval Pathway | EMA priority medicines designation accelerates European market access for novel oxazolidinone formulations. |
| Licensing Agreement | Academic medical center partnerships enable osteomyelitis protocol piloting for tissue-penetrating lipopeptide analogs. |
| Manufacturing Scale-Up | Cold-chain infrastructure consolidation shares F-Gas compliance burdens across EU distribution partnerships. |
| Pipeline Diversification | Beta-lactamase-resistant cephalosporin combinations address polymicrobial resistance selection pressure in bloodstream infections. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA QIDP designations, EMA priority medicines submissions, ClinicalTrials.gov protocols, and hospital formulary databases. Drug development executives, regulatory affairs leads, formulary directors at tertiary centers, and payer access specialists provided qualitative input on stewardship committee dynamics and procurement decision criteria. Bottom-up patient-flow modeling triangulates against top-down pharmaceutical revenue estimates across administration routes and indication tiers.
Segmentation dimensions modeled include product mechanism class, delivery mode, infection acuity tier, and regional regulatory cluster across the projection horizon. CAGRs derive from epidemiological trend analysis, reimbursement pathway evolution, and antimicrobial resistance surveillance data. Forecast inputs incorporate Medicare bundled payment incentive structures and European cold-chain compliance cost trajectories.
Decision-makers should treat outputs as directional under assumptions of stable FDA QIDP incentive continuity and unaltered Medicare diagnostic-therapy alignment frameworks; material deviation in stewardship protocol enforcement or generic erosion velocity would warrant model refresh. Practitioners should keep alternative scenarios live as EMA regulatory alignment and WHO antimicrobial resistance stewardship frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Europe Plasma Fractionation Market
Biopharmaceuticals
1-Step RT-PCR Kits Market
Biopharmaceuticals
China Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Kinase Inhibitors Market
Biopharmaceuticals
India Insulin Drug and Delivery Device Market
Biopharmaceuticals
Compounded Bioidentical Hormone Therapy Market
Biopharmaceuticals
Asia-Pacific Insulin Pens Market
Biopharmaceuticals
Immunocytokines Market
Biopharmaceuticals
Single-Domain Antibody Platforms Market
Biopharmaceuticals
Recombinant Hormone Market
Biopharmaceuticals
Global Mono Vaccine Market
Biopharmaceuticals
East Africa Generic Drug Market
Biopharmaceuticals
Middle East and Africa Plasma Fractionation Market
Biopharmaceuticals
Global Diagnostic Specialty Antibodies Market
Biopharmaceuticals
Mammalian Derived Proteins Market
Biopharmaceuticals
Global Anti-Infective Drugs Market