
 Human Immunodeficiency Virus (HIV) Drugs Market | 2026-2036
Human Immunodeficiency Virus (HIV) Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Human Immunodeficiency Virus (HIV) Drugs Market Foresight
Long-acting injectable antiretroviral technology is narrowing the gap between daily oral adherence and durable viral suppression. Gilead Sciences leverages its nucleoside reverse transcriptase inhibitor portfolio to sustain dominance in first-line regimens. ViiV Healthcare anchors the integrase inhibitor segment through concentrated R&D on cabotegravir-based therapies. Merck & Co. competes with doravirine offerings that differentiate on metabolic safety profiles.
Human immunodeficiency virus drugs comprise synthetic small molecules and biologic agents that interrupt viral replication through enzymatic inhibition, with formulations requiring bioavailability above 80 percent and half-life optimization for once-daily or extended-interval dosing. These agents serve the primary purpose of suppressing viral load to undetectable levels, preventing disease progression and transmission. Integrase inhibitors command the fastest-expanding revenue pool due to superior resistance barriers and tolerability. Injectable delivery modes capture disproportionate investment as manufacturers pursue quarterly administration cycles that reduce pill burden. Combination therapy regimens occupy the mature core of prescribing patterns, though prophylactic treatment segments show accelerated policy support.
FDA, EMA, and WHO prequalification standards shape formulation requirements, bioequivalence thresholds, and distribution eligibility for low-income country procurement. The FDA's long-acting approval pathway and WHO prequalification lists directly determine which manufacturers access volume tenders from the Global Fund and national HIV programs. Stakeholders must monitor how regulatory convergence on sustained-release delivery standards will reshape manufacturing investments and generic substitution timelines.
Market Dynamics
Long-acting injectable formulations are compressing dosing intervals from daily to quarterly, forcing manufacturers to reconfigure manufacturing assets around sustained-release platforms while hospital systems in Brazil and Kenya rebuild procurement workflows around single-administration visits.
Growth Catalysts
- PEPFAR procurement continuity:Sustained funding flows through bilateral agreements maintain volume commitments for first-line antiretroviral regimens across sub-Saharan African national programs.
- Integrase inhibitor resistance profiles:Superior genetic barriers to mutation development drive physician preference switches from protease-based combinations in treatment-experienced patient populations.
- Brazilian hospital formulary expansion:Public health system adoption of long-acting cabotegravir-rilpivirine combinations accelerates patient retention through reduced clinic visit frequency.
Market Restraints
- Active pharmaceutical ingredient concentration:Synthesis of cabotegravir and related integrase inhibitors requires specialized continuous-flow manufacturing capacity concentrated among European and Indian contract manufacturers.
- Cold-chain distribution requirements:Injectable formulations demand 2-8°C storage integrity through last-mile delivery networks in regions with unreliable electricity infrastructure.
- WHO prequalification timelines:Generic manufacturer entry into Global Fund tenders faces 18-24 month bioequivalence review cycles that delay price competition.
Strategic Opportunities
- Pre-exposure prophylaxis policy expansion:South African national guidelines now endorse injectable cabotegravir for HIV-negative populations, creating new demand pools outside treatment markets.
- Community health worker administration:Task-shifting injection delivery from physicians to trained lay providers extends reach into rural clinics without on-site clinicians.
- EMA-FDA regulatory convergence:Aligned stability testing requirements for long-acting formulations reduce duplicative development costs for multi-region launches.
Industry Challenges
- Sustained-release formulation expertise:Nanoparticle suspension manufacturing and polymer-based depot systems require specialized analytical chemistry capabilities scarce among generic developers.
- Legacy oral regimen inventory transitions:Health ministries must manage stockpile depletion of daily tablet combinations while scaling cold-chain capacity for injectable alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Immunodeficiency Virus (HIV) Drugs Market |
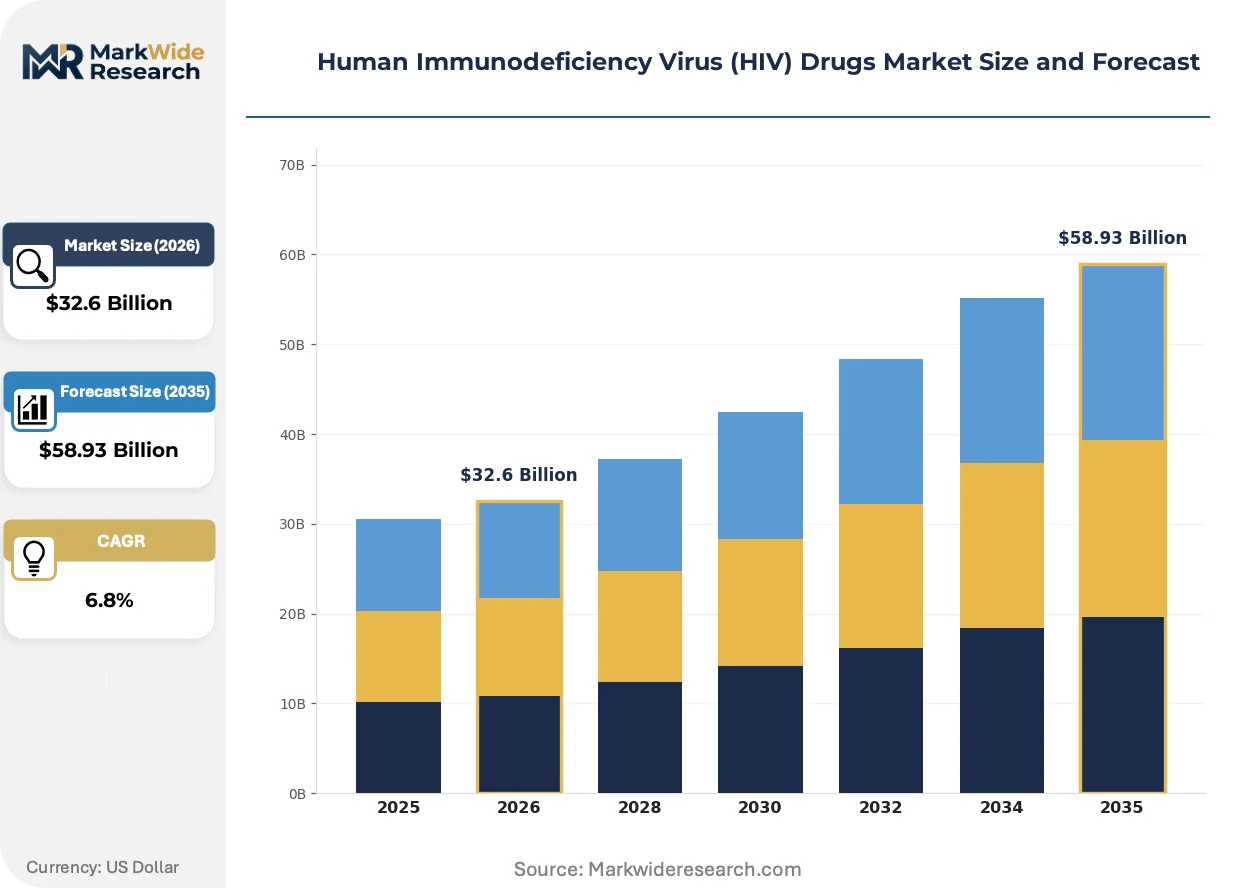
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $58.93 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NRTIs, NNRTIs, PIs, Integrase Inhibitors Therapy Area: Antiretroviral Therapy, Prophylactic Treatment, Combination Therapy, Pre-Exposure Prophylaxis End User: Hospitals, Clinics, Pharmacies, Homecare Delivery Mode: Oral, Injectable, Topical, Others |
| Companies Covered | Gilead Sciences, ViiV Healthcare, Merck & Co., Johnson & Johnson, Bristol-Myers Squibb Company, AbbVie, Boehringer Ingelheim International GmbH, Roche, Cipla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Immunodeficiency Virus (HIV) Drugs Market Shifts & Advancements
Formulation science is compressing the functional boundary between pharmaceutical and device engineering, as manufacturers engineer drug-polymer matrices that release active agents over 8-12 week intervals.
Long-acting injectable nanosuspension technology is collapsing the adherence gap that previously separated effective viral suppression from real-world patient behavior. Hospital systems in São Paulo and Nairobi are adopting quarterly administration protocols that reduce pharmacy dispensing visits by 75 percent. This compression enables reallocation of clinical staff from medication counseling to diagnostic and preventive services.
The FDA's streamlined pathway for 505(b)(2) applications for sustained-release formulations accelerates approval timelines for depot injections referencing existing oral new molecular entities. European Medicines Agency parallel scientific advice programs reduce regulatory divergence between transatlantic jurisdictions. Generic manufacturers in India are responding by building dedicated long-acting formulation facilities to capture post-patent volume tenders.
Patient advocacy organizations are demanding access parity between oral and injectable options within national reimbursement formularies. Brazil's Sistema Único de Saúde is revising procurement specifications to weight patient preference data alongside cost-effectiveness metrics. This behavioral shift is most pronounced in urban treatment centers where younger patient cohorts prioritize discretion and reduced pill visibility.
Human Immunodeficiency Virus (HIV) Drugs Market Segmentation
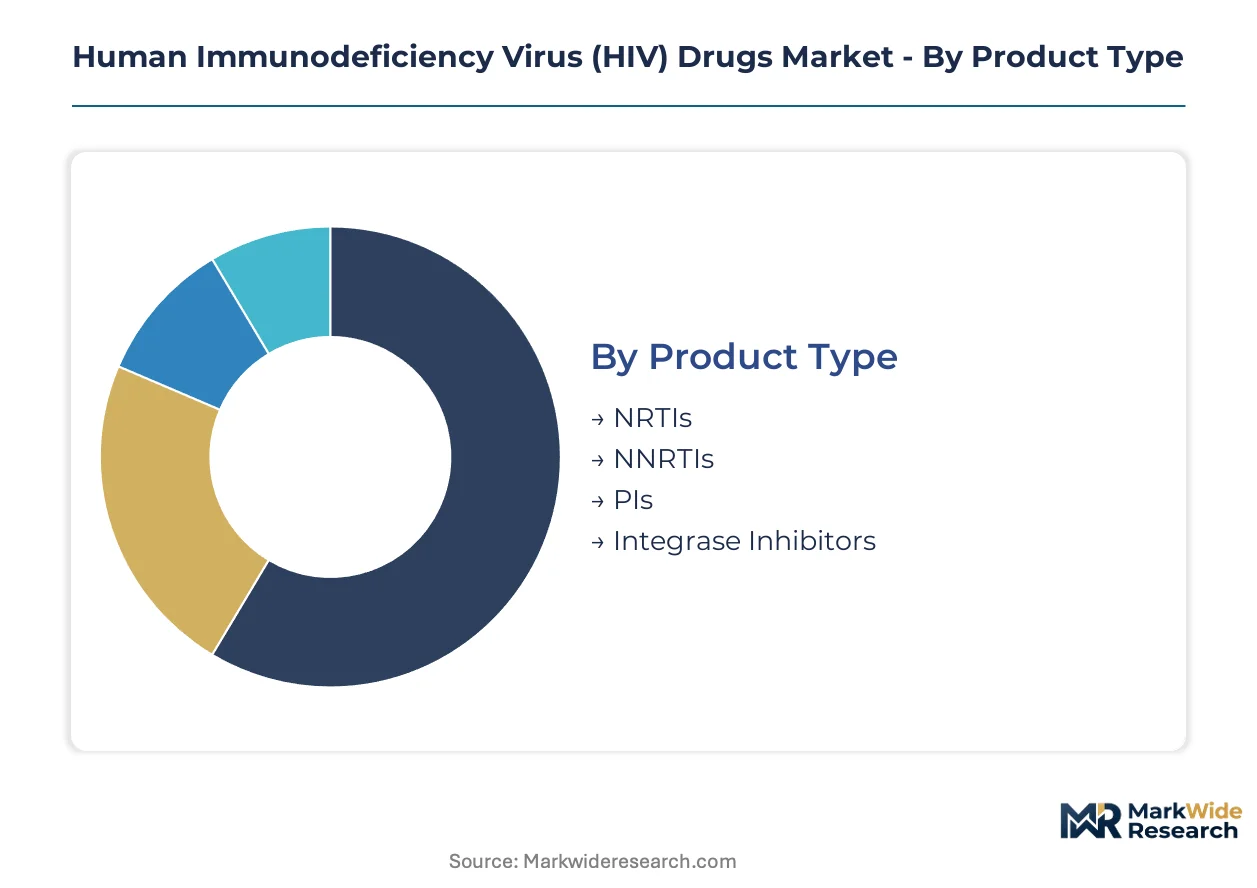
Segmentation in HIV therapeutics reveals how formulation science, care settings, and prevention strategies diverge across patient populations. Manufacturers configure R&D portfolios and manufacturing assets around distinct delivery requirements and regulatory pathways. Procurement patterns vary sharply between acute hospital settings and community-based prevention programs.
Product Type:
Cost tier stratification separates legacy oral agents from premium-priced integrase inhibitors with superior resistance profiles.
- NRTIs:Nucleoside reverse transcriptase inhibitors form the backbone of first-line regimens through fixed-dose combinations with tenofovir or abacavir. Demand concentrates in government procurement programs across sub-Saharan Africa where generic tenofovir-lamivudine-dolutegravir combinations dominate national formularies under Global Fund tenders.
- Integrase Inhibitors:These agents block viral DNA integration with higher genetic barriers to resistance and superior tolerability profiles. Hospital systems in Brazil and South Africa are switching treatment-experienced patients to dolutegravir-based regimens, driving volume shifts from protease inhibitor alternatives.
- NNRTIs:Non-nucleoside reverse transcriptase inhibitors like efavirenz remain entrenched in legacy procurement contracts despite metabolic side effect profiles that limit use in comorbid populations.
- PIs:Protease inhibitors require pharmacokinetic boosting with ritonavir or cobicistat, constraining use to salvage therapy in heavily treatment-experienced patients with documented resistance mutations.
NRTIs command the established base. The steepest expansion runs through Integrase Inhibitors.
Therapy Area:
Application scope stretches from curative-intent viral suppression to prevention in HIV-negative populations.
- Antiretroviral Therapy:Daily oral regimens suppress viral replication in infected patients, requiring sustained adherence to maintain undetectable viral loads. Brazil's Sistema Único de Saúde has expanded hospital-based dispensing to include long-acting injectable alternatives that reduce clinic visit frequency.
- Pre-Exposure Prophylaxis:Biomedical prevention in HIV-negative individuals now includes injectable cabotegravir administered every eight weeks. South Africa's national guidelines endorsement has created new demand pools outside traditional treatment markets, with community health worker administration extending reach into rural clinics.
- Combination Therapy:Multi-class regimens remain the clinical standard, though single-tablet formulations face competition from long-acting depot injections with quarterly administration cycles.
- Prophylactic Treatment:Post-exposure protocols and occupational exposure prevention occupy narrower volume segments with episodic prescribing patterns tied to emergency departments.
Antiretroviral Therapy commands the established base. The steepest expansion trajectory belongs to Pre-Exposure Prophylaxis.
End User:
Customer type determines cold-chain requirements, reimbursement complexity, and patient retention infrastructure.
- Hospitals:Acute care settings manage treatment initiation, resistance testing, and complex comorbidity cases. São Paulo's public hospital networks are rebuilding procurement workflows around single-administration visits for long-acting formulations.
- Clinics:Outpatient facilities handle stable patient monitoring and prescription renewals. Kenyan primary health centers are adopting task-shifting protocols that delegate injection administration to trained lay providers.
- Pharmacies:Retail dispensing faces margin pressure from centralized procurement, though urban chains in South Africa capture PrEP demand from younger patient cohorts prioritizing discretion.
- Homecare:Self-administered oral regimens dominate this segment, with limited penetration of home nursing for injectable therapies due to cold-chain integrity requirements.
Hospitals command the established base. The steepest expansion runs through Clinics.
Delivery Mode:
Volume concentration reflects the tension between adherence optimization and manufacturing complexity.
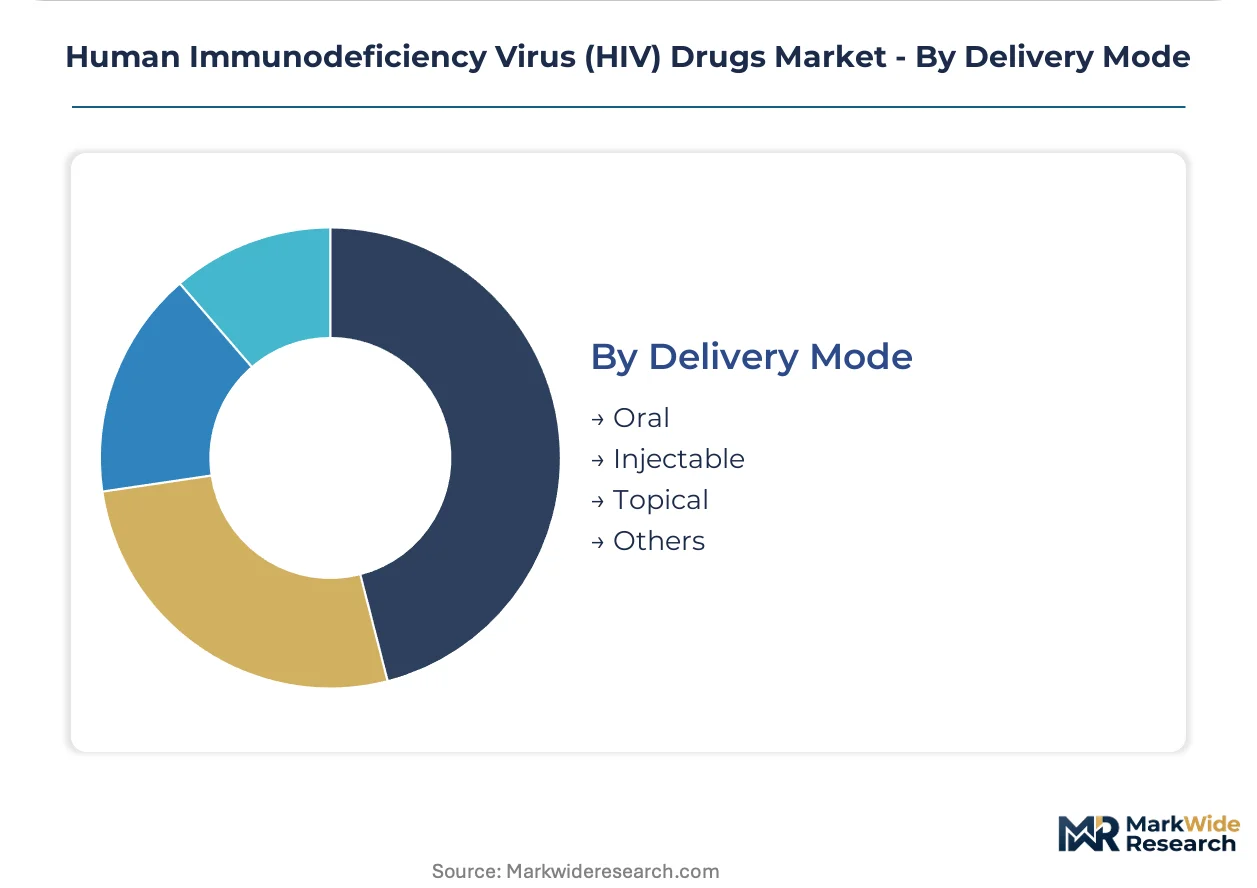
- Oral:Tablets and capsules remain the dominant format, with once-daily single-tablet regimens minimizing pill burden. Inventory transitions at health ministries must manage stockpile depletion while scaling cold-chain capacity for alternatives.
- Injectable:Nanosuspension depot formulations achieve therapeutic drug levels over 8-12 week intervals. FDA's 505(b)(2) pathway for sustained-release formulations accelerates approval timelines, while Indian generic manufacturers are building dedicated long-acting facilities to capture post-patent tenders.
- Topical:Microbicide gels and rings occupy research-phase segments with limited commercial penetration pending efficacy confirmation in large-scale trials.
- Others:Transdermal patches and implantable devices remain experimental, constrained by polymer-based depot manufacturing capabilities scarce among generic developers.
Oral delivery commands the established base. The steepest expansion runs through Injectable formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration in sub-Saharan Africa, Brazil, and South Asia determines volume allocation. Government tenders through PEPFAR and the Global Fund anchor demand. Hospital networks in São Paulo, Nairobi, and Johannesburg drive adoption of long-acting formulations.
United States
FDA's 505(b)(2) pathway for sustained-release formulations accelerates approval timelines for depot injections. Commercial payers in California and New York negotiate outcomes-based contracts for cabotegravir-rilpivirine regimens. The Boston-Cambridge biotech corridor hosts formulation specialists developing next-generation polymer-based depot systems.
Brazil
ANVISA registration requirements shape bioequivalence standards for generic integrase inhibitors entering the Sistema Único de Saúde. São Paulo's public hospital networks are rebuilding procurement workflows around single-administration visits for long-acting alternatives. Federal Ministry of Health tenders prioritize patient retention metrics alongside cost-effectiveness.
South Africa
The national Department of Health endorsed injectable cabotegravir for pre-exposure prophylaxis in HIV-negative populations. Gauteng province's urban treatment centers drive demand among younger cohorts prioritizing discretion. Cape Town's clinical research infrastructure supports decentralized trial endpoints for community health worker administration models.
India
CDSCO manufacturing licensing requirements govern active pharmaceutical ingredient production for export to Global Fund tenders. Hyderabad and Ahmedabad clusters host contract manufacturers building dedicated long-acting formulation facilities. The Department of Pharmaceuticals monitors export parity pricing for tenofovir-lamivudine-dolutegravir combinations.
Kenya
The Pharmacy and Poisons Board regulates cold-chain integrity standards for injectable antiretrovirals distributed through devolved county health systems. Nairobi's referral hospitals coordinate with primary health centers adopting task-shifting protocols for lay provider injection administration. PEPFAR bilateral agreements sustain volume commitments for first-line regimen procurement.
Human Immunodeficiency Virus (HIV) Drugs Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement tiers. The vendor base stratifies between originators holding patent-protected integrase inhibitors and generic manufacturers supplying government tenders. Three archetypes dominate: large-cap pharmaceutical conglomerates with diversified antiviral portfolios, mid-cap specialists concentrated on long-acting formulation science, and emerging-market generic houses scaling continuous-flow manufacturing. Competitive moves center on regulatory pathway acceleration and cold-chain distribution partnerships.
Within the originator tier, Gilead Sciences and ViiV Healthcare anchor distinct technology platforms. Gilead's nucleoside reverse transcriptase inhibitor portfolio sustains position in first-line oral regimens. ViiV Healthcare concentrates research and development on cabotegravir-based therapies spanning treatment and prevention indications. Merck & Co. occupies a differentiated position through doravirine offerings emphasizing metabolic safety profiles.
| Leading Market Players |
|---|
| Gilead Sciences |
| ViiV Healthcare |
| Merck & Co. |
| Johnson & Johnson |
| Bristol-Myers Squibb Company |
| AbbVie |
| Boehringer Ingelheim International GmbH |
| Roche |
| Cipla |
| Others |
Supply & Pricing Matrix
Single-source dependency on European and Indian contract manufacturers for cabotegravir active pharmaceutical ingredient synthesis compresses pricing tier spreads while forcing supply chain shape toward concentrated continuous-flow capacity. This concentration amplifies cost pass-through volatility and limits buyer leverage across procurement tiers.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient indexation dominate government procurement tenders through PEPFAR and the Global Fund. Price differentiation rests on WHO prequalification status and cold-chain certification tier, with prequalified originators commanding premiums over non-prequalified generic alternatives. Pricing pressure intensifies as Indian manufacturers scale tenofovir-lamivudine-dolutegravir production for volume tenders. National health ministries in sub-Saharan Africa exhibit highest price sensitivity, while private hospital networks in Brazil demonstrate lowest sensitivity due to retention-focused procurement metrics.
Supply Chain Analysis
Extended payment terms through supply-chain finance facilities enable Indian generic manufacturers to bridge working capital gaps during WHO prequalification review cycles. Manufacturing concentrates in India, China, and selected European sites for active pharmaceutical ingredients, with formulation finishing distributed across Brazil, South Africa, and Kenya. Raw material dependencies include tenofovir disoproxil fumarate, dolutegravir sodium, and specialized polymer excipients for depot formulations. Single-source vulnerability pervades cabotegravir nanosuspension manufacturing. Distribution runs through cold-chain logistics networks with 2-8°C integrity requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HIV drugs market functions as a defensive-moat story anchored in regulatory entrenchment. WHO prequalification and FDA 505(b)(2) pathway expertise create switching costs that protect incumbent positioning.
For Market Incumbents: Build regulatory moats through accelerated FDA long-acting pathway submissions and parallel EMA scientific advice engagement. Deepen backward integration into polymer-based depot manufacturing to capture formulation margin. Counter emerging Indian generic entrants by securing exclusive cold-chain distribution partnerships with county health systems in Kenya and South Africa. For New Entrants and Emerging Players: Rural clinic penetration in Kenya's devolved county health system offers accessible entry points. Target community health worker administration models with simplified cold-chain requirements. Pursue WHO prequalification for tenofovir-lamivudine-dolutegravir fixed-dose combinations to unlock Global Fund tender access. Differentiate through patient preference data integration in procurement specifications. For Investors and Strategic Acquirers: The market sits at a formulation-transition phase that favors mid-cap specialists with sustained-release manufacturing capabilities. Long-term viability centers on quarterly-to-biannual dosing interval compression over the next decade. Acquisition targets should demonstrate cabotegravir-compatible nanosuspension expertise and established relationships with PEPFAR procurement officers. Monitor EMA-FDA regulatory convergence announcements as inflection indicators for multi-region launch feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Acting Formulation Development | Quarterly administration cycles reduce clinic visit frequency by 75 percent in São Paulo hospital networks. |
| WHO Prequalification Pathway | Bioequivalence review cycles determine generic manufacturer access to Global Fund volume tenders. |
| Cold-Chain Distribution Partnership | 2-8°C integrity requirements through last-mile networks in Kenya constrain competitive entry. |
| Community Health Worker Training | Task-shifting protocols extend injectable PrEP reach into rural clinics without on-site clinicians. |
| Regulatory Convergence Engagement | EMA-FDA parallel scientific advice reduces duplicative development costs for sustained-release launches. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with regulatory affairs leads, formulary directors, hospital procurement managers, and payer access specialists; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and Global Fund tender databases. Bottom-up patient-volume modeling triangulated against top-down pharmaceutical expenditure data from national health ministries.
Forecast inputs incorporated antiretroviral therapy line positioning, dosage form migration from oral to injectable, administration route adoption curves, and regional regulatory cluster alignment. Segmentation dimensions spanned product class, therapy indication, end-user facility type, and delivery mode. CAGRs derived from regression analysis of historical procurement volumes against policy adoption timelines, with dosing interval compression rates and cold-chain infrastructure buildout serving as key forward indicators.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Indian generic manufacturers or sudden PEPFAR funding discontinuation would shift outcomes. Macroeconomic volatility affecting foreign exchange rates for tender pricing, regulatory delays in WHO prequalification timelines, or breakthroughs in implantable delivery technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Antibody Drug Conjugates Market
Biopharmaceuticals
Metabolism Drugs Market
Biopharmaceuticals
Global Endocrinology Drugs Market
Biopharmaceuticals
North America Biotechnology Market
Biopharmaceuticals
Europe Monoclonal Antibodies Market
Biopharmaceuticals
Global Thrombin Market
Biopharmaceuticals
Biological Drugs Market
Biopharmaceuticals
Global Human Recombinant Insulin Market
Biopharmaceuticals
Peptide Antibiotics Market
Biopharmaceuticals
In Situ Gel Drug Delivery Market
Biopharmaceuticals
Tamoxifen Market
Biopharmaceuticals
Plasmid DNA Manufacturing Market
Biopharmaceuticals
Recombinant Erythropoietin Market
Biopharmaceuticals
Insulin Pens Market
Biopharmaceuticals
Proteinuria Therapeutics Market
Biopharmaceuticals
Insulin Syringes Market