
 North America Generic Oncology Drug Market | 2026-2036
North America Generic Oncology Drug Market Size, Share, and Industry Trends Forecast 2026-2036
North America Generic Oncology Drug Market Intelligence
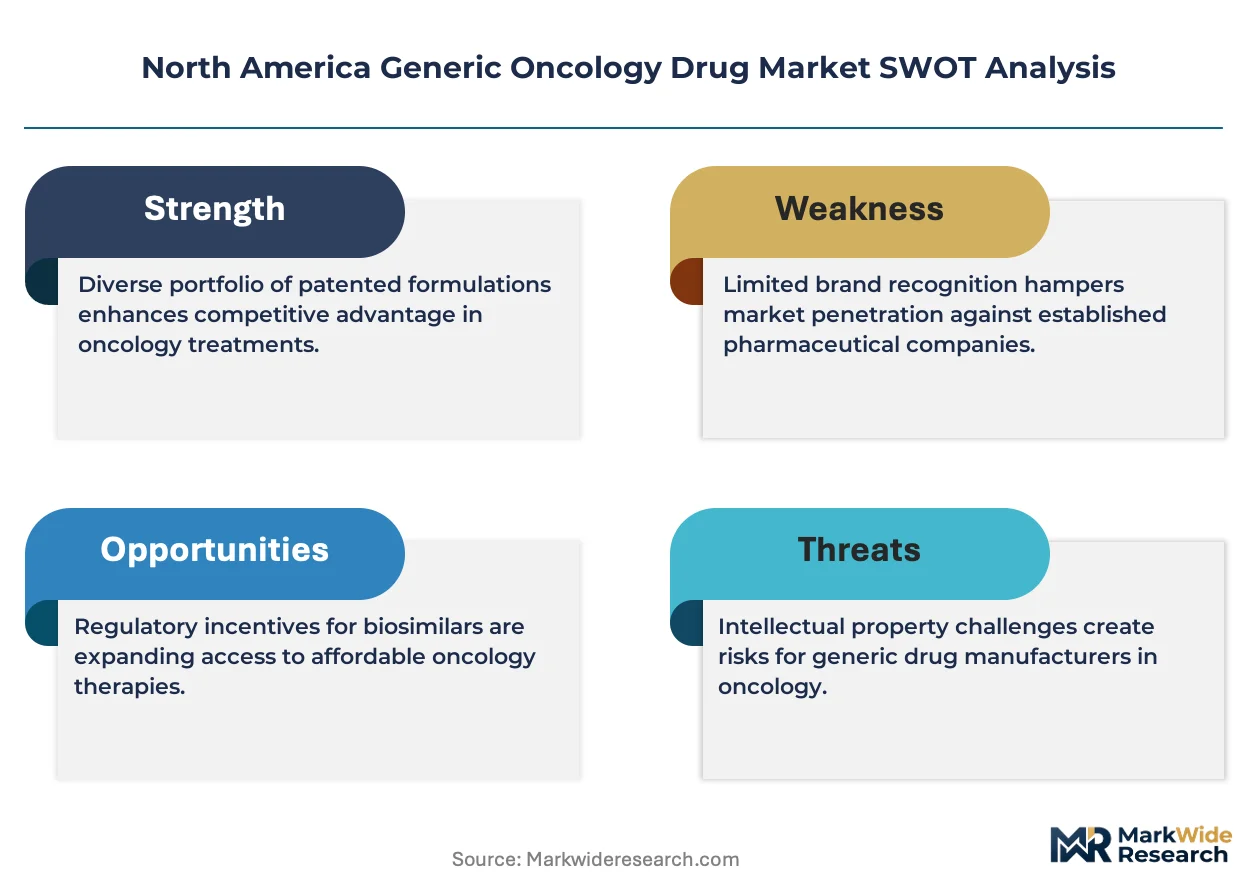
The split between premium complex generics and commodity small-molecule oncology drugs is shifting procurement economics across North American health systems. Teva Pharmaceutical Industries Ltd. leverages its vertically integrated API-to-finished-dose infrastructure to sustain cost leadership in injectable chemotherapy copies. Viatris Inc. anchors hospital pharmacy contracts through centralized distribution networks, while Fresenius Kabi AG competes in the oncology supportive care segment with specialized manufacturing for cytotoxic compounds.
Generic oncology drugs are bioequivalent therapeutic agents that replicate the safety and efficacy profiles of originator cancer medicines after patent expiry, typically requiring dissolution rates within specified pharmacokinetic windows and sterile manufacturing under isolator technology for parenteral forms. Their primary purpose is to expand patient access to essential cancer treatment while reducing payer expenditure across public and private reimbursement systems. Chemotherapy copies still occupy the largest volume share, though immunotherapy and targeted therapy segments are attracting accelerated ANDA filings as reference biologics lose exclusivity. Hospital pharmacy channels dominate distribution for injectable formulations, while retail and online pharmacy networks handle the oral solid volume for maintenance regimens.
FDA abbreviated new drug application pathways and USP monograph standards govern bioequivalence requirements, manufacturing quality, and post-market surveillance for oncology generics across the United States. Health Canada and the FDA jointly influence cross-border supply standards, particularly for sterile injectables produced under mutual recognition agreements. Stakeholders must monitor pending FDA guidance on complex generic peptide and antibody-drug conjugate copies, as these determinations will reshape which manufacturers can enter the highest-margin oncology segments.
Market Dynamics
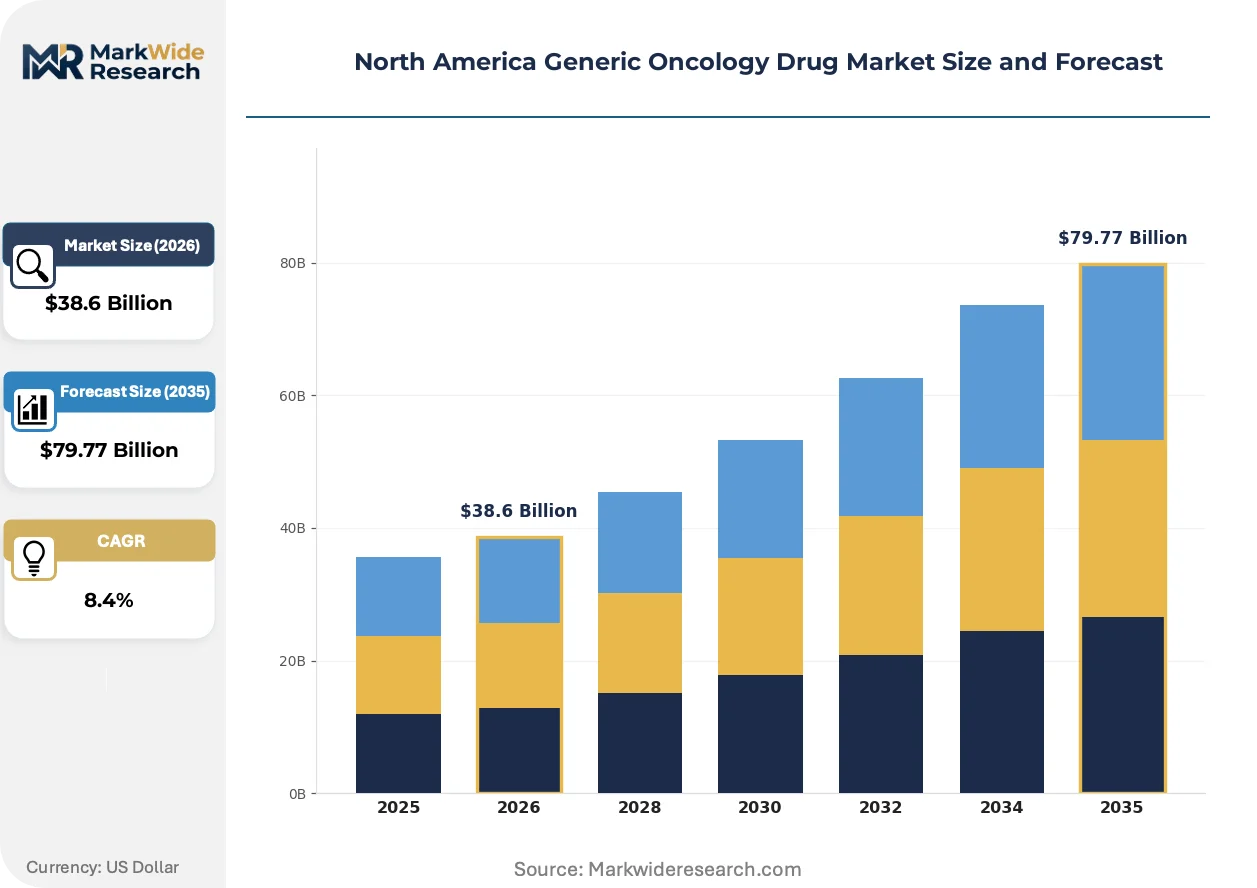
The North America generic oncology drug market is being reshaped by Medicare reimbursement reforms that compress payment differentials between originator and biosimilar chemotherapy agents, forcing manufacturers to compete on manufacturing efficiency rather than clinical differentiation alone.
Growth Catalysts
- 340B Program Expansion:Federal eligibility expansion for disproportionate-share hospitals is amplifying institutional purchasing volume for injectable oncology generics across the United States.
- FDA Complex Generic Guidance:Accelerated abbreviated approval pathways for peptide copies and antibody-drug conjugate biosimilars are reducing time-to-market for high-barrier oncology segments.
- Isolator Technology Adoption:Advanced aseptic manufacturing systems are enabling domestic production of cytotoxic parenterals previously sourced from European contract manufacturers.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient sourcing for platinum-based chemotherapies remains concentrated among Indian and Chinese bulk manufacturers, exposing formulators to geopolitical supply interruptions.
- Reimbursement Compression:Medicare's inflation rebate provisions under the Inflation Reduction Act are eroding net realized prices for oral oncology generics dispensed through Medicare Part D.
- Complex Generic Technical Barriers:Peptide and oligonucleotide copies require specialized bioequivalence demonstration that exceeds standard ANDA analytical capabilities, limiting qualified entrants.
Strategic Opportunities
- Canadian Hospital Procurement Consolidation:Provincial health authority tendering consolidation is creating volume aggregation opportunities for manufacturers with Health Canada-established drug identification numbers.
- Oncology Supportive Care Adjacencies:Growth in biosimilar filgrastim and pegfilgrastim is opening formulation expertise extensions into neutropenia prophylaxis and antiemetic portfolios.
- Specialty Pharmacy Distribution:Limited distribution network partnerships for oral oncolytics are enabling direct-to-patient models that bypass traditional wholesale markups.
Industry Challenges
- Sterile Manufacturing Workforce Scarcity:Qualified aseptic operators and isolator technicians command premium wages that inflate cost structures for parenteral oncology production.
- Post-Approval Change Management:FDA comparability protocol requirements for manufacturing site transfers create 18-24 month approval timelines that delay supply chain optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Generic Oncology Drug Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Hormonal Therapy, Immunotherapy End User: Hospitals, Clinics, Diagnostic Laboratories, Pharmaceuticals Distribution Channel: Retail Pharmacy, Hospital Pharmacy, Online Pharmacy, Wholesalers Formulation Type: Tablets, Injections, Oral Solutions, Capsules |
| Companies Covered | Teva Pharmaceutical Industries Ltd., Viatris Inc., Sandoz Group AG, Sun Pharmaceutical Industries Ltd., Cipla Ltd., Fresenius Kabi AG, Hikma Pharmaceuticals PLC, Lupin Ltd., Apotex Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Generic Oncology Drug Market Strategic Shifts & Innovations
Continuous manufacturing platforms and real-time release testing are displacing batch-oriented quality verification, compressing production cycles for high-volume chemotherapy injectables while reducing in-process inventory requirements.
Single-use bioreactor systems for biosimilar monoclonal antibody production is modularizing facility design across contract manufacturing organizations serving North American oncology markets. CMOs adopting these disposable technologies are reducing capital deployment timelines from 36 months to 18 months for new product introductions. This modularity is enabling faster capacity reallocation between biosimilar programs as reference product patent cliffs accelerate.
The FDA's forthcoming guidance on interchangeable biosimilar designation for oncology supportive care agents is tightening evidentiary standards for switching studies. Manufacturers must now demonstrate pharmacokinetic equivalence across multiple reference product lots rather than single-lot comparison. Hospital pharmacy and therapeutics committees in the United States are revising formulary placement protocols to incorporate these higher evidentiary thresholds.
Hospital pharmacy directors are consolidating injectable oncology purchasing through group purchasing organizations that negotiate sole-source contracts for therapeutic equivalents. This concentration is displacing multi-source generic strategies that previously maintained two to three approved suppliers per National Drug Code. The shift is most pronounced in the United States, where 340B-covered entities represent over 50 percent of institutional chemotherapy volume.
North America Generic Oncology Drug Market Segmentation
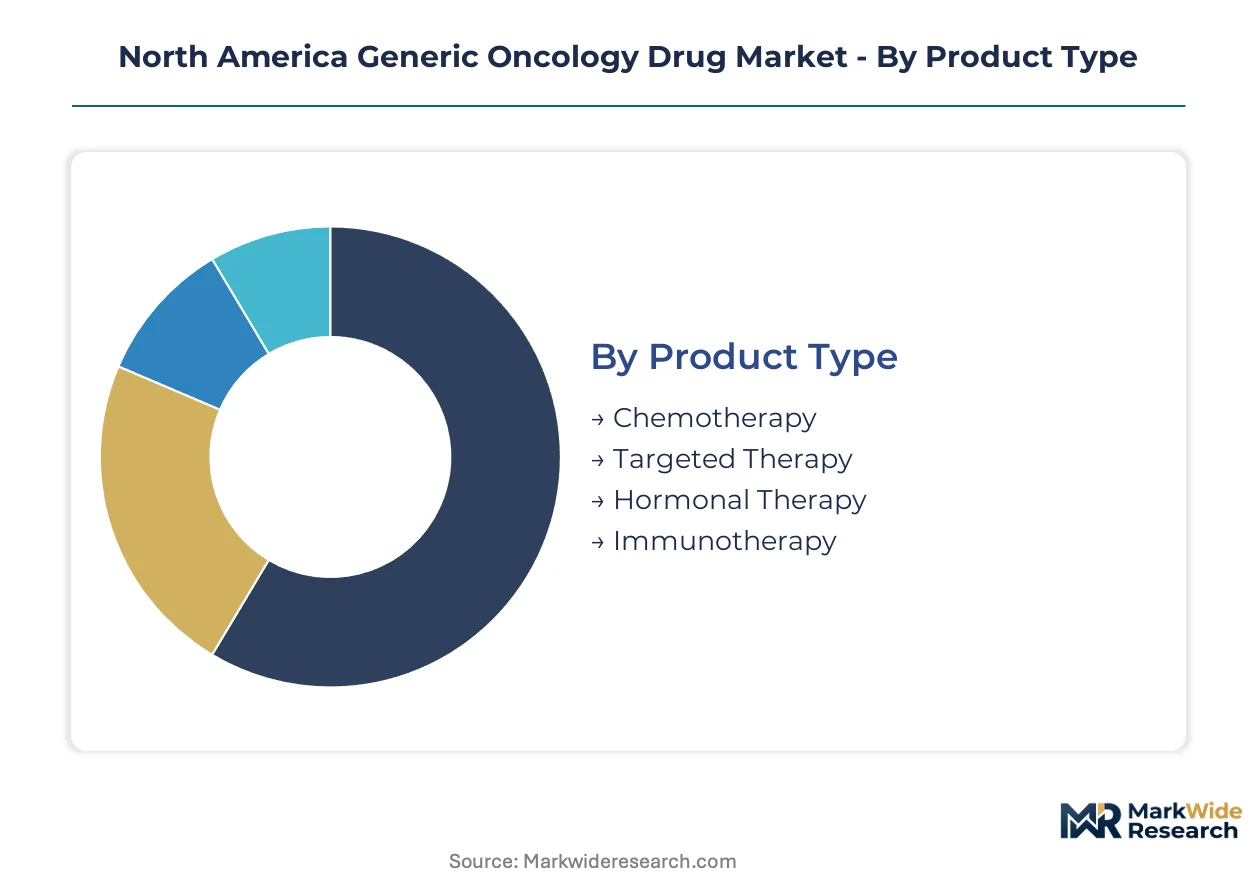
Generic oncology drug segmentation reveals how capital requirements, reimbursement pathways, and manufacturing complexity fragment competitive positioning across North American health systems. Each dimension exposes distinct barriers to entry and margin structures that determine which manufacturers can profitably serve specific patient populations.
Product Type:
Capital intensity varies sharply across therapeutic modalities, with sterile injectable manufacturing and biosimilar development demanding the heaviest upfront infrastructure investment.
- Chemotherapy:Cytotoxic alkylating agents, antimetabolites, and plant alkaloids require isolator-based aseptic manufacturing under FDA cGMP for parenteral administration. Hospital procurement through 340B-covered entities concentrates demand in carboplatin, paclitaxel, and gemcitabine copies where Medicare reimbursement reforms compress net pricing.
- Targeted Therapy:Small-molecule kinase inhibitors and PARP inhibitors replicate reference product pharmacokinetics through complex synthetic routes. Oral solid formulations dominate, with specialty pharmacy distribution capturing tyrosine kinase inhibitor volume for chronic myeloid leukemia and lung cancer maintenance regimens.
- Hormonal Therapy:Aromatase inhibitors and anti-androgens represent mature generic categories with stable API supply chains from Indian bulk manufacturers. Retail pharmacy dispensing predominates for breast and prostate cancer adjuvant therapy.
- Immunotherapy:Biosimilar monoclonal antibodies targeting PD-1/PD-L1 and CTLA-4 pathways require single-use bioreactor systems and extensive immunogenicity testing. FDA interchangeable designation standards are tightening evidentiary requirements for switching studies.
Chemotherapy absorbs the bulk of installed capacity; immunotherapy is expanding most quickly.
End User:
Customer-type concentration shapes contract negotiation leverage and inventory holding patterns across the value chain.
- Hospitals:Inpatient oncology units and infusion centers administer parenteral chemotherapy under bundled payment models. Group purchasing organization consolidation is displacing multi-source generic strategies with sole-source contracts for therapeutic equivalents.
- Clinics:Community oncology practices and ambulatory surgery centers handle routine chemotherapy administration for stable patients. Freestanding infusion centers are capturing volume from hospital outpatient departments as site-of-care migration accelerates.
- Diagnostic Laboratories:Companion diagnostic testing facilities support biomarker-driven therapy selection, creating pull-through demand for matched generic targeted therapies. Pharmacogenomic screening is expanding eligibility for precision oncology protocols.
- Pharmaceuticals:Contract manufacturing organizations and virtual pharma companies source API and finished dose for proprietary formulations. CMO capacity constraints are extending lead times for cytotoxic compound production.
Hospitals command the deepest contract penetration; clinics are gaining share fastest as site-of-care shifts accelerate.
Distribution Channel:
Channel economics determine working capital intensity and price realization through markup accumulation or disintermediation.
- Retail Pharmacy:Community and specialty pharmacies dispense oral oncology maintenance therapies under Medicare Part D. Limited distribution network partnerships are enabling direct-to-patient models that bypass traditional wholesale markups.
- Hospital Pharmacy:Centralized pharmacy operations manage formulary placement and inventory for injectable chemotherapy. 340B program expansion is amplifying institutional purchasing volume across disproportionate-share hospitals.
- Online Pharmacy:Mail-order and digital platforms handle chronic oral oncolytic refills for stable patients. Prior authorization integration is streamlining reimbursement verification for high-cost specialty generics.
- Wholesalers:Three primary distributors control flow of hospital and retail pharmacy supply. Fee-for-service arrangements are replacing buy-sell economics as pricing transparency regulations tighten.
Hospital pharmacy channels dominate injectable volume; online pharmacy is climbing the fastest as patient convenience preferences shift.
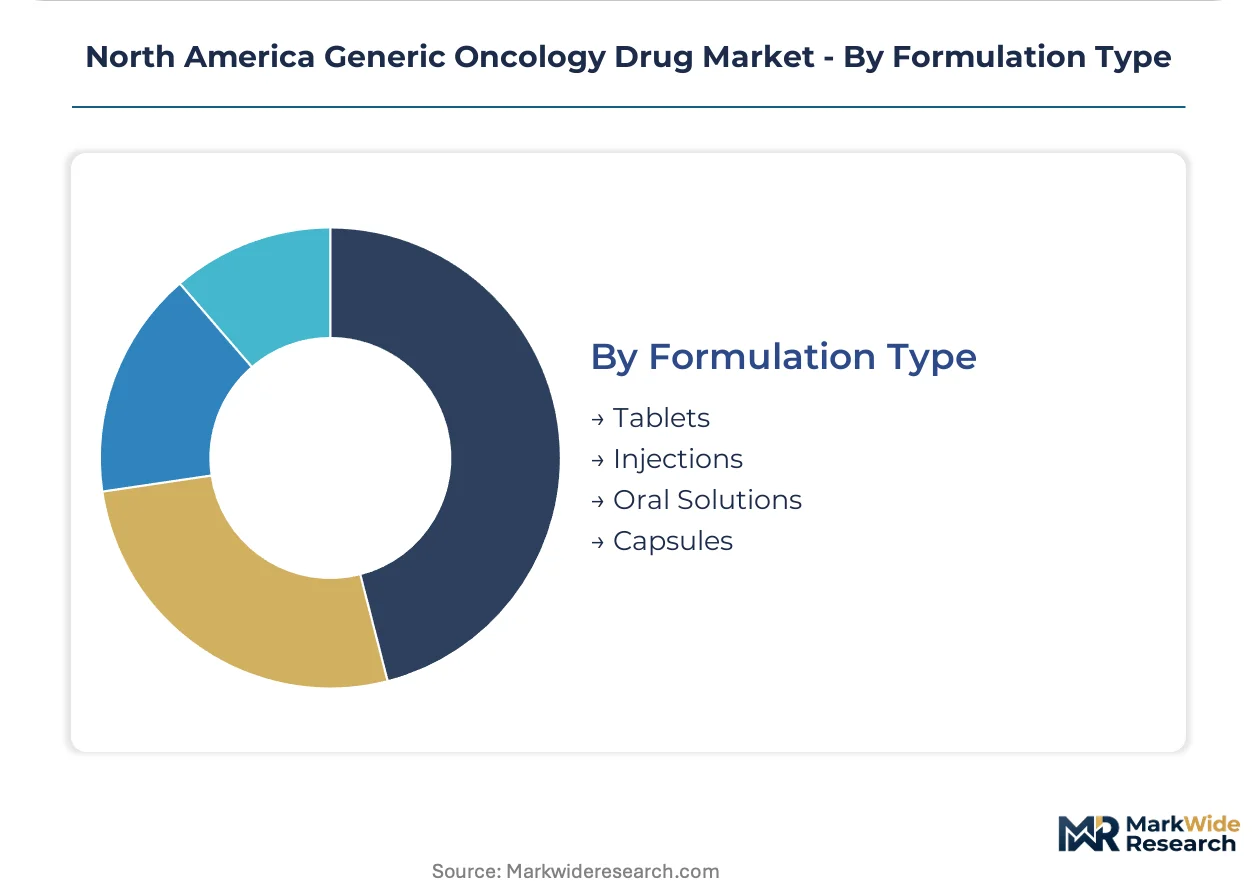
Formulation Type:
Manufacturing process requirements and stability profiles create divergent margin structures and competitive moats.
- Injections:Parenteral formulations demand sterile manufacturing under isolator technology with real-time release testing. Domestic production capacity is expanding as FDA accelerates abbreviated approval pathways for complex generics.
- Tablets:Oral solid dosage forms for kinase inhibitors and hormonal agents leverage conventional high-shear granulation and film coating. Bioequivalence demonstration relies on dissolution profile matching within specified pharmacokinetic windows.
- Oral Solutions:Liquid formulations serve pediatric and geriatric populations with swallowing difficulties. Stability testing for aqueous solutions requires accelerated aging protocols that extend development timelines.
- Capsules:Hard-shell and soft-gel encapsulation accommodates hygroscopic APIs and lipid-soluble compounds. Modified-release capsule technologies are extending generic entry into controlled-release reference products.
Injections absorb the bulk of sterile manufacturing investment; oral solutions are gaining share fastest in pediatric oncology protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The New Jersey-Philadelphia pharmaceutical corridor anchors North American generic oncology manufacturing, with FDA headquarters in Silver Spring and Health Canada in Ottawa shaping contiguous regulatory frameworks.
United States
Medicare reimbursement reforms and 340B program expansion drive institutional purchasing of injectable chemotherapy at disproportionate-share hospitals. FDA abbreviated new drug application pathways accelerate market entry for complex generics. The Boston-Cambridge biopharma cluster concentrates biosimilar development expertise, while Puerto Rico hosts sterile injectable manufacturing for mainland distribution.
Canada
Provincial health authority tendering consolidation creates volume aggregation opportunities for manufacturers with established drug identification numbers. Health Canada and FDA mutual recognition agreements streamline cross-border supply of sterile parenterals. The Toronto-Waterloo corridor hosts contract manufacturing organizations serving both domestic and export markets.
Mexico
COFEPRIS regulatory alignment with FDA standards enables integrated North American supply chains for oral oncology generics. Maquiladora manufacturing zones near the US border produce active pharmaceutical ingredients for platinum-based chemotherapies. Mexico City anchors distribution networks reaching Central American markets.
North America Generic Oncology Drug Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the North America generic oncology drug market. Vertically integrated manufacturers with captive API supply command cost advantages in injectable chemotherapy, while portfolio specialists concentrate formulation expertise in targeted therapy segments. The competitive terrain splits between scale-driven commodity players and precision-focused complex generic developers. Consolidation through group purchasing organization sole-source contracts and manufacturing site acquisitions reshapes market access.
Among Israeli-based pharmaceutical conglomerates, Teva Pharmaceutical Industries Ltd. exemplifies integrated API-to-finished-dose infrastructure. Viatris Inc. and Fresenius Kabi AG represent contrasting archetypes: the former anchors hospital pharmacy contracts through centralized distribution networks, while the latter occupies specialized manufacturing positions in oncology supportive care. These three entities illustrate how geographic origin and corporate structure map onto divergent competitive strategies in injectable and oral dosage forms.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd. |
| Viatris Inc. |
| Sandoz Group AG |
| Sun Pharmaceutical Industries Ltd. |
| Cipla Ltd. |
| Fresenius Kabi AG |
| Hikma Pharmaceuticals PLC |
| Lupin Ltd. |
| Apotex Inc. |
| Others |
Cost & Logistics Intelligence
Qualified aseptic operators and isolator technicians in the New Jersey-Philadelphia corridor command premium wages that widen spreads between domestic sterile injectable pricing and imported API-dependent alternatives. Labor-cost differentials between US-based parenteral manufacturing and Asian bulk chemical production stratify oncology generic tiers.
Pricing Analysis
Hospital formulary placement tied to clinical outcome metrics anchors value-based pricing for injectable chemotherapy copies. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified domestic manufacturers from Health Canada-registered suppliers and Indian API-dependent formulators. Cost compression in the economy tier intensifies because Medicare inflation rebate provisions erode net realized prices. 340B-covered entities exhibit highest price sensitivity; specialty pharmacy networks for oral kinase inhibitors show lowest.
Supply Chain Analysis
Regional distribution centers in Indianapolis, Memphis, and Dallas anchor hub-and-spoke patterns for hospital pharmacy delivery of cytotoxic parenterals. Active pharmaceutical ingredient sourcing draws from India, China, and Italy for platinum-based chemotherapies and taxane precursors. Single-source vulnerability concentrates in Chinese bulk manufacturers of paclitaxel intermediates. Distribution runs through three primary wholesalers operating fee-for-service arrangements with 340B entities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive API supply has become the decisive upstream lever as manufacturers race to secure cost positions in injectable oncology generics.
For Market Incumbents: To counter reimbursement compression from Medicare inflation rebate provisions, Teva Pharmaceutical Industries Ltd. and Viatris Inc. should deepen backward integration into Indian API joint ventures while expanding isolator capacity in Puerto Rico. Securing Health Canada drug identification numbers ahead of provincial tendering consolidation protects Canadian market access. For New Entrants and Emerging Players: Enter via oncology supportive care adjacencies—biosimilar filgrastim and pegfilgrastim—where formulation expertise requirements are lower than cytotoxic parenterals. Canadian provincial health authority tendering presents the most penetrable geography. Partner with established CMOs possessing FDA cGMP certification for sterile injectables rather than greenfield facility investment. For Investors and Strategic Acquirers: The window for entry favors contract manufacturing organizations with single-use bioreactor capacity and established FDA master files. Long-term viability hinges on positioning for peptide and antibody-drug conjugate biosimilar waves as reference product cliffs accelerate. Watch FDA guidance publication on complex generic evidentiary standards as the inflection signal for qualified entrant scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Adoption | Domestic sterile manufacturing capacity expands under FDA accelerated approval pathways for complex generics. |
| 340B Program Contract Consolidation | Group purchasing organizations negotiate sole-source agreements that displace multi-source generic strategies. |
| Health Canada Registration | Provincial tendering consolidation rewards early entrants with established drug identification numbers. |
| Single-Use Bioreactor Deployment | Modular CMO capacity reduces capital deployment timelines for biosimilar monoclonal antibody production. |
| Specialty Pharmacy Partnership | Limited distribution networks enable direct-to-patient models bypassing traditional wholesale markups. |
Research Approach
Multi-period observation of FDA ANDA filing volumes, Medicare reimbursement rate changes, and 340B entity purchasing patterns anchored the trend analysis, supplemented by interviews with hospital pharmacy directors, GPO contracts managers, regulatory affairs leads, and CMO operations executives. Secondary validation drew from FDA Orange Book filings, CMS Medicare Part D expenditure data, Health Canada drug product database, and hospital procurement system records. Bottom-up manufacturer capacity estimates and top-down payer expenditure analysis were triangulated.
Input-output matrices mapped chemotherapy, targeted therapy, hormonal therapy, and immunotherapy segments across formulation type, distribution channel, and end-user concentration. CAGRs were derived from regression analysis of historical volume trends against reimbursement policy variables and patent expiry schedules. Modeled dimensions included treatment line positioning, administration route, and regional regulatory cluster alignment.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA guidance delays on peptide biosimilars or geopolitical API supply interruptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
North America Biotechnology Market
Biopharmaceuticals
Interleukin-6 (IL-6) Inhibitors Market
Biopharmaceuticals
France Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Branded Generics Market
Biopharmaceuticals
Spectinomycin Market
Biopharmaceuticals
Global Bovine Blood Plasma Derivatives Market
Biopharmaceuticals
Global Incretin-Based Drugs Market
Biopharmaceuticals
Fenbendazole Market
Biopharmaceuticals
Glycoprotein Market
Biopharmaceuticals
Canada Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Theranostics Market
Biopharmaceuticals
Global Kinase Inhibitors Market
Biopharmaceuticals
Global Anti-Tuberculosis Therapeutics Market
Biopharmaceuticals
Biopharmaceutical CMO and CRO Market
Biopharmaceuticals
Global Lenalidomide Market
Biopharmaceuticals
Macrolide Drugs Market