
 Biopharmaceutical Oral Drug Delivery Market | 2026-2036
Biopharmaceutical Oral Drug Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Biopharmaceutical Oral Drug Delivery Market Analysis
GMP-plus clinical-grade formulation standards is collapsing into the mainstream as sponsors abandon legacy compendial compliance for integrated quality-by-design protocols. Pfizer Inc leverages its network of specialized oral solid dose facilities across North America and Europe to sustain supply security for high-potency biologics. Novartis AG anchors its position through deep expertise in modified-release macromolecule platforms. Catalent Inc competes aggressively on speed-to-clinic timelines for oral peptide programs.
Biopharmaceutical oral drug delivery encompasses the engineering of absorption-enhanced formulations, permeation-modified excipient matrices, and enzymatic-protection systems designed to shepherd large-molecule therapeutics through the gastrointestinal tract while preserving structural integrity and bioavailability. The primary purpose centers on converting injectable biologics into patient-administered oral dosage forms that improve adherence, reduce healthcare utilization, and expand addressable populations. Tablets dominate current volume owing to established compression tooling and coating infrastructure, yet oral solutions and suspensions are capturing faster growth in pediatric and geriatric indications where swallowability limits solid-dose uptake. Sustained release and controlled release mechanisms command premium positioning as they enable less frequent dosing for chronic biologic regimens, though immediate release retains share in acute therapeutic areas.
FDA dissolution and bioequivalence standards, EMA's quality guidelines for oral drug products, and ICH Q8-Q12 quality risk management frameworks collectively shape formulation development costs, batch release criteria, and market access timelines for new entrants. These regulatory architectures reward sponsors that invest early in design-space definition and process analytical technology, while penalizing post-approval changes that trigger supplementary reviews. Stakeholders must monitor how evolving bioequivalence requirements for complex peptides and nucleotides reshape competitive moats between originators and follow-on developers.
Market Dynamics
Specialty oncology clinics are driving administration shifts from infusion centers to home settings, compressing development timelines for absorption-enhanced oral biologic formulations. This demand migration is forcing sponsors to collapse GMP-plus clinical-grade standards into mainstream quality-by-design protocols.
Growth Catalysts
- Home-based administration:Payer reimbursement maturation in the United States, Germany, and Japan for oral oncolytics accelerates patient-administered biologic adoption.
- ICH Q8-Q12 frameworks:Quality risk management protocols reward early design-space definition, reducing supplementary review triggers for post-approval changes.
- Modified-release macromolecule platforms:Deep expertise in sustained-release and controlled-release mechanisms enables less frequent dosing for chronic biologic regimens.
Market Restraints
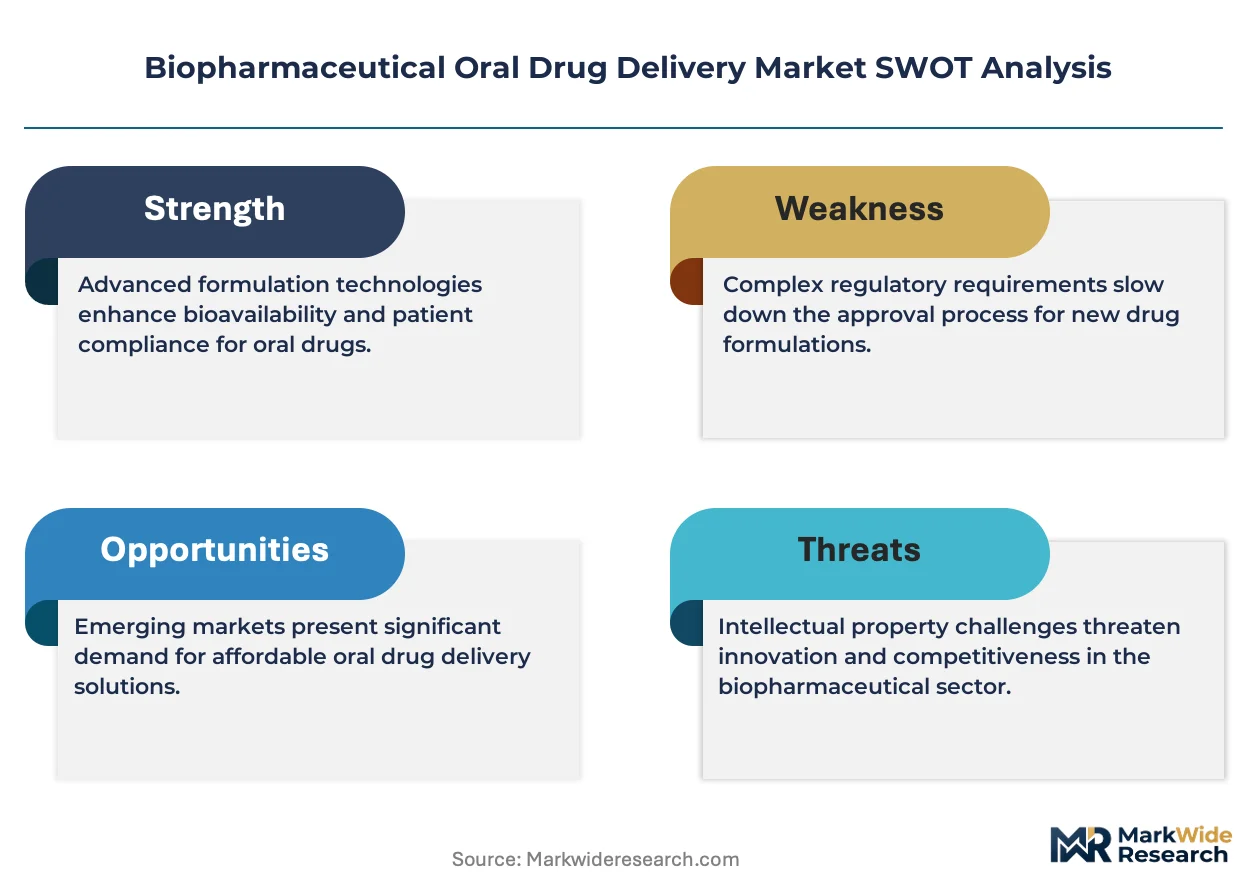
- Dissolution standard tightening:FDA and EMA bioequivalence guidelines for complex generics raise formulation development costs and batch release criteria.
- High-potency manufacturing concentration:Specialized oral solid dose facilities cluster in North America and Western Europe, creating supply security vulnerabilities.
- Enzymatic degradation barriers:Gastrointestinal protease activity limits structural integrity preservation for peptide and protein therapeutics.
Strategic Opportunities
- Pediatric and geriatric swallowability gaps:Oral solutions and suspensions capture faster growth where tablet compression infrastructure underperforms.
- Process analytical technology integration:Sponsors investing early in PAT-enabled manufacturing secure competitive moats against follow-on developers.
- Speed-to-clinic compression:Contract development organizations compete aggressively on oral peptide program timelines, opening partnership white space.
Industry Challenges
- Permeation-modified excipient sourcing:Limited qualified suppliers for absorption-enhancing matrices constrain formulation flexibility.
- Cross-functional talent scarcity:Integrated biologic-formulation expertise spanning macromolecule stability and solid-dose engineering remains rare.
- Legacy coating infrastructure retrofitting:Established compression tooling requires capital-intensive modification for high-potency biologic containment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biopharmaceutical Oral Drug Delivery Market |
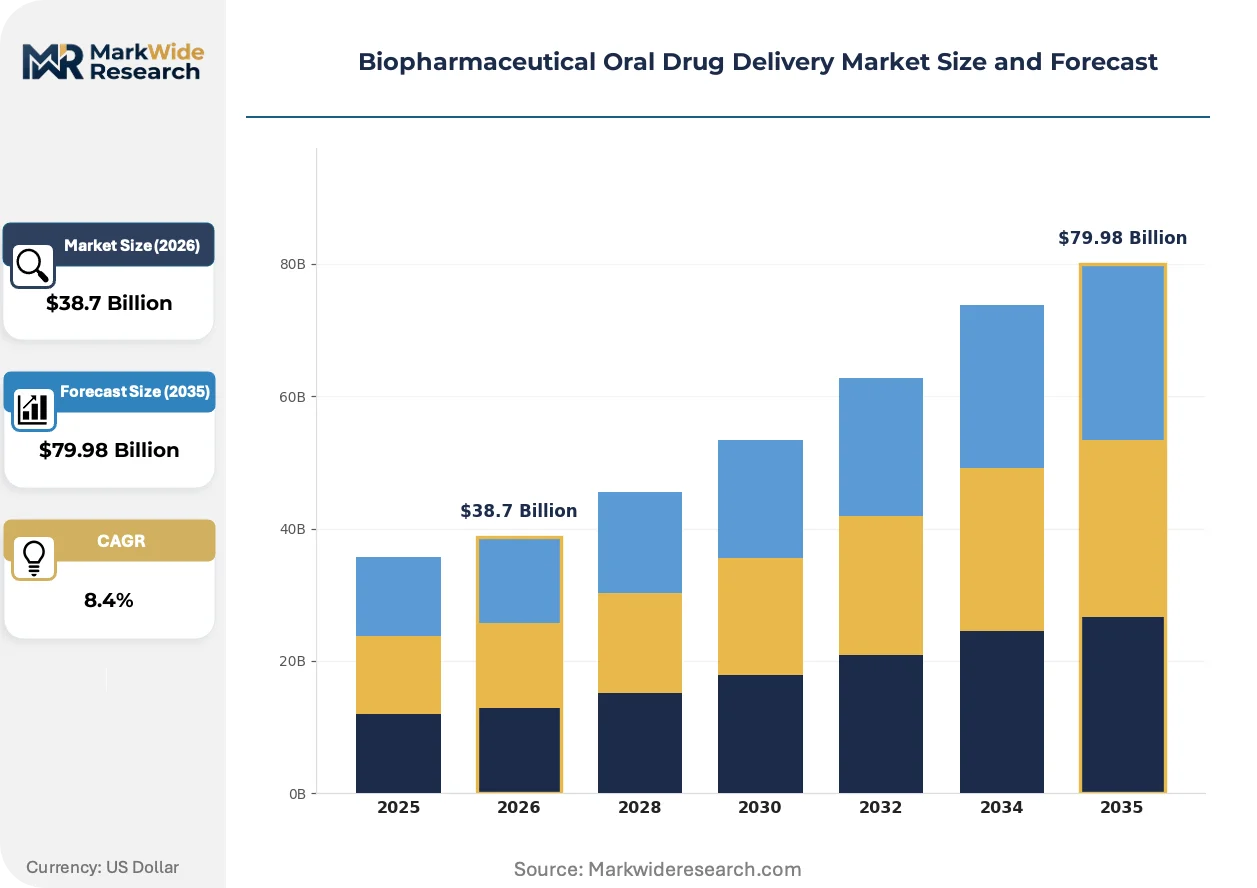
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Formulation: Tablets, Capsules, Solutions, Suspensions Release Mechanism: Sustained Release, Controlled Release, Immediate Release, Delayed Release Active Ingredient: Small Molecules, Biologics, Peptides, Nucleotides End User: Pharmaceutical Companies, Contract Manufacturers, Research Institutions, Healthcare Providers |
| Companies Covered | Pfizer Inc, Novartis AG, AbbVie Inc, Sanofi, Johnson & Johnson, Catalent Inc, Amgen Inc, F. Hoffmann-La Roche Ltd, Novo Nordisk A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biopharmaceutical Oral Drug Delivery Market Emerging Trajectories
Formulation engineering is actively fragmenting around permeation enhancement, enzymatic protection, and modified-release architectures. Three convergent developments are compressing competitive timelines.
Permeation-modified excipient matrices are fragmenting conventional formulation approaches. These absorption-enhancing systems shepherd large-molecule therapeutics through intestinal epithelia while preserving bioavailability. Pediatric and geriatric indication sponsors are adopting liquid and suspension formats fastest where swallowability constrains solid-dose uptake. The technology is fragmenting tablet-dominated volume share into format-differentiated portfolios.
EMA quality guidelines for oral drug products are tightening dissolution standards for complex peptides and nucleotides. This regulatory compression extends batch release criteria and market access timelines for new entrants. Originators with early design-space documentation are consolidating advantage against follow-on developers in European markets.
Specialty oncology procurement is compressing vendor qualification cycles. Hospital systems and specialty pharmacies are unbundling after-sales technical support from formulation supply contracts. This behavior shift is most visible in United States payer networks where oral oncolytic reimbursement maturity enables direct-to-pharmacy distribution models.
Biopharmaceutical Oral Drug Delivery Market Segmentation
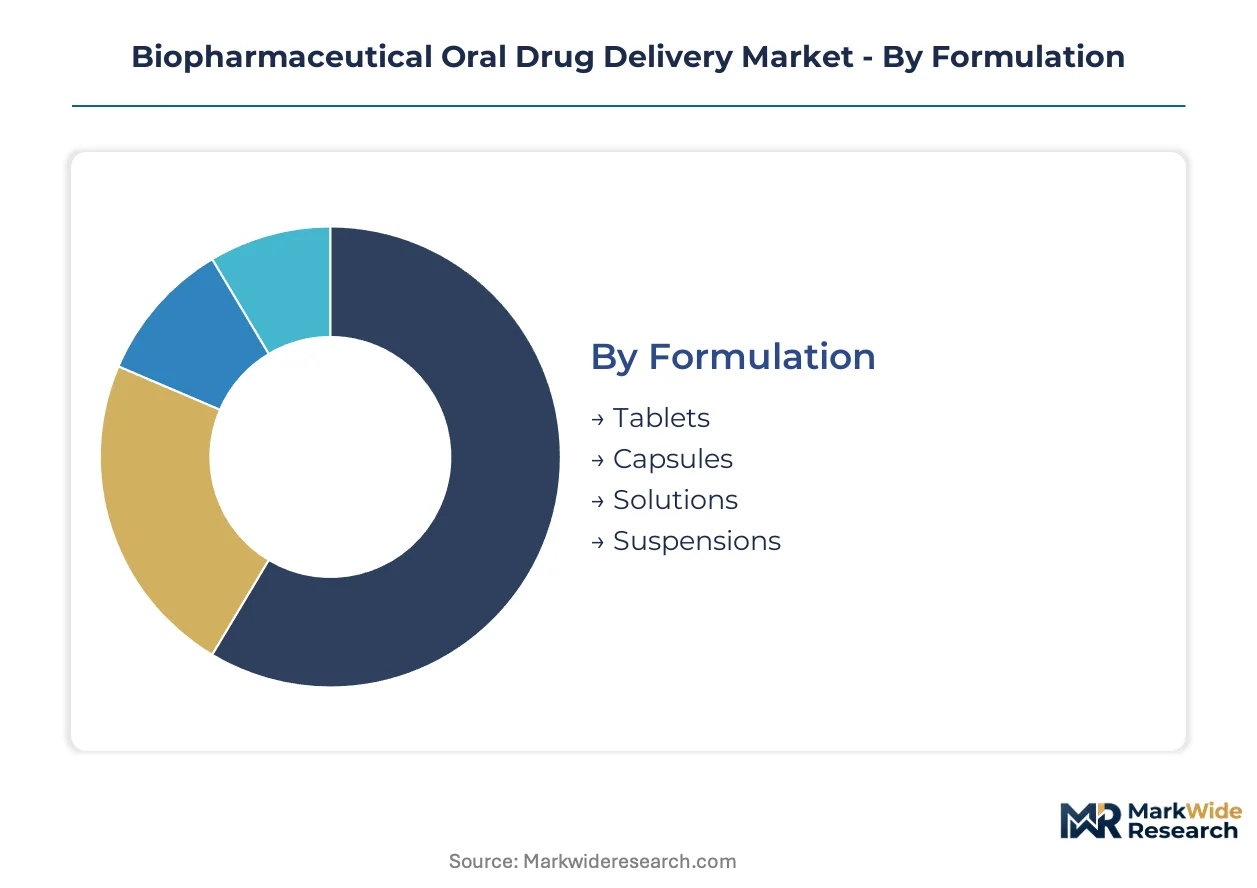
Oral biologic formulation choices directly determine regulatory pathway complexity, manufacturing capital requirements, and payer reimbursement positioning across developed markets. Segmentation reveals where technical differentiation creates defendable margin structures versus commodity competition.
Formulation:
FDA dissolution standards and EMA quality guidelines apply asymmetric stringency across solid and liquid dosage platforms, reshaping development economics.
- Tablets:Compression tooling infrastructure dominates current volume through established coating and containment systems for high-potency biologics. Demand concentrates in United States specialty oncology clinics where oral oncolytic reimbursement maturity enables home-based administration shifts from infusion centers.
- Solutions:Liquid formats bypass swallowability barriers in pediatric and geriatric populations, capturing faster growth where solid-dose uptake faces physiological constraints. Germany and Japan payer networks are accelerating adoption through direct-to-pharmacy distribution models for patient-administered biologics.
- Capsules:Gelatin and HPMC shell technologies accommodate macromolecule payloads requiring enzymatic protection through enteric coating integration.
- Suspensions:Particulate dispersion systems address bioavailability challenges for poorly soluble biologic actives, with manufacturing complexity limiting qualified supplier bases.
Tablets handle the majority of throughput; solutions is the fastest mover on share.
Release Mechanism:
Chronic versus acute therapeutic indications drive divergent margin structures across temporal control architectures.
- Sustained Release:Matrix and reservoir systems extend dosing intervals for chronic biologic regimens, commanding premium positioning through reduced healthcare utilization. United States and Japanese hospital systems prioritize these platforms for specialty oncology procurement compressing vendor qualification cycles.
- Controlled Release:Osmotic pump and membrane technologies enable precise plasma concentration profiles for narrow therapeutic index biologics. Germany's EMA-aligned quality frameworks reward early design-space documentation, consolidating originator advantage against follow-on developers.
- Immediate Release:Rapid disintegration formulations retain share in acute therapeutic areas where speed-to-onset outweighs duration optimization.
- Delayed Release:Enteric and colon-targeted systems protect acid-labile macromolecules through gastric transit, with process analytical technology integration determining competitive moats.
Sustained release commands the highest value per dose; controlled release is climbing the fastest on chronic indication penetration.
Active Ingredient:
Structural complexity tiers determine permeation enhancement requirements and enzymatic protection system specifications.
- Biologics:Monoclonal antibodies and recombinant proteins demand absorption-enhanced formulations with permeation-modified excipient matrices. Development concentrates in United States and German sponsor pipelines where ICH Q8-Q12 frameworks reward integrated quality-by-design protocols.
- Peptides:Medium-sized macromolecules balance synthetic accessibility with gastrointestinal stability challenges, driving modified-release platform adoption fastest across contract development organization portfolios.
- Small Molecules:Traditional chemical entities retain volume through established bioequivalence pathways, though differentiation shifts toward combination with biologic payloads.
- Nucleotides:RNA and DNA therapeutics face EMA tightening of dissolution standards for complex generics, extending batch release criteria for new entrants.
Biologics absorb the majority of formulation R&D investment; peptides are gaining share fastest on speed-to-clinic timeline compression.
End User:
Integration depth across development and manufacturing functions determines procurement authority and technical specification influence.
- Pharmaceutical Companies:Integrated sponsors with specialized oral solid dose facility networks control high-potency biologic supply security, collapsing GMP-plus clinical-grade standards into mainstream protocols. United States and Japan-based originators anchor demand through deep modified-release macromolecule expertise.
- Contract Manufacturers:CDMOs compete aggressively on oral peptide program timelines, with speed-to-clinic capabilities opening partnership white space in German and Japanese markets.
- Research Institutions:Academic and government laboratories drive early-stage permeation enhancement innovation, though limited manufacturing scale constrains direct procurement volume.
- Healthcare Providers:Hospital systems and specialty pharmacies unbundle after-sales technical support from supply contracts, most visible in United States payer networks with mature oral oncolytic reimbursement.
Pharmaceutical companies direct the majority of formulation specification; contract manufacturers are expanding most quickly on outsourcing trend acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized oral solid dose facilities cluster disproportionately in the United States, Germany, and Japan, creating supply security vulnerabilities that sponsors address through multi-site qualification strategies. This geographic concentration shapes regulatory pathway complexity and batch release economics across developed markets.
United States
Specialty oncology clinics drive administration shifts from infusion centers to home settings, compressing development timelines for absorption-enhanced formulations. FDA dissolution standards for complex generics reward sponsors with early design-space documentation. The Greater Boston and San Francisco Bay Area biotech corridors anchor modified-release macromolecule platform development.
Germany
EMA quality guidelines for oral drug products tighten dissolution standards for complex peptides and nucleotides, extending batch release criteria. ICH Q8-Q12 frameworks reward integrated quality-by-design protocols among integrated sponsors. The Rhine-Main and Munich metropolitan regions concentrate high-potency manufacturing infrastructure for oral biologics.
Japan
PMDA alignment with ICH quality risk management frameworks accelerates market access for sponsors with process analytical technology integration. Payer reimbursement maturity for oral oncolytics enables direct-to-pharmacy distribution models. The Kanto and Kansai industrial belts host specialized coating infrastructure for enzymatic-protection systems.
Switzerland
Swissmedic maintains stringent bioequivalence requirements that consolidate originator advantage against follow-on developers. The Basel and Zurich life sciences clusters sustain deep expertise in permeation-modified excipient matrices. Contract development organizations compete on speed-to-clinic timelines for oral peptide programs.
United Kingdom
MHRA post-Brexit regulatory autonomy preserves ICH-aligned quality frameworks while introducing supplementary review triggers for post-approval changes. The Golden Triangle of Cambridge, Oxford, and London drives early-stage permeation enhancement innovation. Healthcare provider procurement unbundles after-sales technical support from formulation supply contracts.
Biopharmaceutical Oral Drug Delivery Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated pharmaceutical sponsors commanding premium positioning through specialized facility networks while contract manufacturers compete on timeline compression. The market structure tiered across originators with deep modified-release expertise, CDMOs with speed-to-clinic capabilities, and emerging specialists in pediatric-geriatric liquid formats. Strategic archetypes include integrated sponsors with captive supply security, platform-technology licensors, and regional manufacturing specialists. Dominant competitive moves encompass strategic partnerships for excipient sourcing security and capacity expansion in qualified high-potency containment facilities.
Among integrated pharmaceutical sponsors, Pfizer Inc and Novartis AG exemplify archetypes with specialized oral solid dose infrastructure across multiple geographies. Catalent Inc occupies a position within the contract development tier, representing speed-to-clinic competitive positioning. These entities anchor the competitive landscape through differentiated approaches to quality-by-design protocol integration and manufacturing scale.
| Leading Market Players |
|---|
| Pfizer Inc |
| Novartis AG |
| AbbVie Inc |
| Sanofi |
| Johnson & Johnson |
| Catalent Inc |
| Amgen Inc |
| F. Hoffmann-La Roche Ltd |
| Novo Nordisk A/S |
| Others |
Supply Flow & Price Mechanics
Permeation-modified excipient matrices are displacing conventional absorption enhancers across formulation portfolios, simultaneously pulling supply geography toward specialized chemical manufacturers in Germany and Switzerland while compressing pricing economics for commodity-grade alternatives. This substitution dynamic rewards sponsors with qualified supplier relationships and penalizes developers dependent on legacy excipient sourcing.
Pricing Analysis
FDA bioequivalence guidelines dictate the pricing tier structure across oral biologic formulations, separating GMP-plus clinical-grade protocols from mainstream quality-by-design compliance. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and process analytical technology integration depth. Cost compression in the standard tier is intensifying because contract manufacturers compete aggressively on oral peptide program timelines. Hospital systems and specialty pharmacies demonstrate highest price sensitivity, while integrated pharmaceutical sponsors with captive manufacturing show lowest sensitivity due to supply security premiums.
Supply Chain Analysis
Strategic stockpiling of permeation-modified excipients dominates inventory strategy over just-in-time approaches, reflecting single-source vulnerability and batch release timeline uncertainty. Supply concentrates in the United States, Germany, and Japan where specialized oral solid dose facilities cluster. Raw material dependencies include gelatin and HPMC shell technologies, enzymatic-protection coating systems, and absorption-enhancing matrices. Tariff exposure on imported excipients from Switzerland constitutes the primary structural risk. Distribution runs through direct-to-pharmacy models in mature payer networks and traditional wholesale channels in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. FDA and EMA dissolution standard tightening creates switching costs that consolidate originator advantage against follow-on developers.
For Market Incumbents: Secure qualified supplier relationships for permeation-modified excipient matrices before capacity constraints tighten. Expand specialized oral solid dose facility footprints across North America and Western Europe to mitigate supply security vulnerabilities. Patent cliff exposure on legacy injectable biologics threatens revenue bases; vertical integration into modified-release macromolecule platforms preserves margin structures. For New Entrants and Emerging Players: After-sales technical support unbundling from formulation supply contracts presents the most penetrable service-layer gap in United States payer networks. Target pediatric and geriatric liquid format segments where tablet infrastructure underperforms on swallowability constraints. Pursue speed-to-clinic partnership models with mid-tier pharmaceutical sponsors lacking in-house formulation expertise. For Investors and Strategic Acquirers: Capital is best deployed toward contract development organizations with integrated process analytical technology capabilities and established oral peptide program track records. Long-term viability centers on regulatory pathway de-risking and manufacturing scale within the analysis window. Watch for FDA dissolution standard revisions for complex nucleotides as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Process Analytical Technology Integration | PAT-enabled manufacturing secures competitive moats against follow-on developers in EMA-aligned markets. |
| Modified-Release Platform Licensing | Deep macromolecule expertise commands premium positioning through reduced dosing frequency for chronic regimens. |
| Pediatric-Geriatric Format Expansion | Liquid and suspension portfolios capture growth where solid-dose swallowability limits patient access. |
| Multi-Site Manufacturing Qualification | Geographic diversification mitigates supply security vulnerabilities from high-potency facility concentration. |
| Design-Space Documentation Investment | Early ICH Q8-Q12 protocol integration reduces supplementary review triggers for post-approval changes. |
Methodological Framework
The analysis maps formulation engineering sub-sectors, each validated through drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Primary interviews with industry stakeholders combine with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up and top-down triangulation cross-checks segment outputs against aggregate market trajectories.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include formulation type, release mechanism, active ingredient complexity, and end-user integration depth. CAGRs derive from patent expiry schedules, pipeline advancement rates, and payer reimbursement maturation curves. Forecast inputs incorporate specialty oncology clinic expansion trajectories and dissolution standard revision probabilities.
Underlying assumptions cover regulatory pathway stability, excipient supply continuity, and reimbursement policy persistence, with deviation risk concentrated in FDA bioequivalence guideline revisions and EMA quality framework updates. Revision becomes warranted when dissolution standard stringency crosses thresholds that trigger supplementary review cycles for follow-on developers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Glycosylated Peptide Market
Biopharmaceuticals
Biotherapeutics Cell Line Development Market
Biopharmaceuticals
Mexico Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Targeted Protein Degradation Market
Biopharmaceuticals
North America Vaccines Market
Biopharmaceuticals
Ovarian Cancer Drugs Market
Biopharmaceuticals
Tamoxifen Market
Biopharmaceuticals
Mammalian Derived Proteins Market
Biopharmaceuticals
Drug Discovery Outsourcing Market
Biopharmaceuticals
Compounded Bioidentical Hormone Therapy Market
Biopharmaceuticals
Tuberculosis Biomarkers Market
Biopharmaceuticals
Insulin Delivery Pens Market
Biopharmaceuticals
North America HIV Drugs Market
Biopharmaceuticals
Spain Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
PCSK9 Inhibitors Market
Biopharmaceuticals
Sodium-Dependent Glucose Co-Transporter 2 (SGLT 2) Market