
 Global Mono Vaccine Market | 2026-2036
Global Mono Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mono Vaccine Market Foresight
Aftermarket cold chain logistics revenue is reshaping margin distribution across the mono vaccine value chain, pulling value downstream from manufacturing toward distribution integrity. GlaxoSmithKline plc leverages its refrigerated transport networks to sustain premium positioning in temperature-sensitive segments. Merck & Co., Inc. anchors North American supply through vertically controlled distribution partnerships. Pfizer Inc. competes on ultra-cold infrastructure investments that differentiate its mRNA delivery capabilities.
Mono vaccines are single-antigen immunological preparations containing one pathogen-derived immunogen, typically formulated with aluminum salt adjuvants or lipid nanoparticle carriers and stabilized within strict thermal parameters between two and eight degrees Celsius for non-mRNA platforms. These biologics prime adaptive immunity against specific infectious agents for prophylactic administration in human and veterinary populations. Live attenuated formulations dominate current revenue pools due to established manufacturing infrastructure and broad pediatric coverage, while mRNA platforms represent the fastest-expanding technology segment as lipid nanoparticle delivery systems mature. Pediatric immunization applications command the largest volume base through national program procurement, though travel medicine channels extract higher per-dose margins from private-pay customers.
The FDA's accelerated approval framework and the EMA's adaptive pathway program compress clinical timelines for novel mono vaccine candidates, while WHO prequalification standards govern access to United Nations procurement channels. India's CDSCO enforces parallel quality benchmarks that determine market entry for domestic manufacturers serving export markets. Stakeholders must monitor evolving stability requirements for next-generation thermostable formulations that could displace existing cold chain dependencies.
Market Dynamics
The FDA's accelerated approval pathways for mRNA platforms compress development timelines while Serum Institute of India Pvt. Ltd. anchors regional supply concentration, creating asymmetric competitive pressure between speed-to-market and manufacturing scale.
Growth Catalysts
- Pediatric immunization programs:National procurement schemes in low-income countries drive volume demand through WHO prequalification standards. Gavi procurement channels unlock access to United Nations vaccine distribution networks.
- Lipid nanoparticle delivery maturation:mRNA stabilization technologies enable thermostable formulations that reduce cold chain dependency. Platform standardization accelerates antigen swap capabilities for emerging pathogen response.
- EMA adaptive pathway program:Rolling review mechanisms compress Phase III-to-approval intervals for novel mono vaccine candidates. Conditional marketing authorizations generate early revenue streams during confirmatory studies.
Market Restraints
- Aluminum adjuvant supply concentration:Three specialty chemical suppliers control pharmaceutical-grade aluminum salt production, creating input cost volatility during demand surges.
- WHO prequalification timeline friction:Stringent stability documentation requirements extend market entry timelines by 18-24 months for manufacturers in emerging production clusters.
- Live attenuated platform substitution pressure:Established manufacturing infrastructure for traditional formulations slows mRNA capital reallocation despite superior efficacy profiles in respiratory indications.
Strategic Opportunities
- Thermostable formulation white space:Next-generation stabilization chemistries could displace existing two-to-eight-degree Celsius dependencies across African distribution networks.
- Travel medicine channel expansion:Private-pay clinics in Singapore and Dubai extract premium margins from pre-travel immunization consultations bundled with mono vaccine administration.
- India PLI scheme incentives:Production-linked incentives for biopharmaceutical manufacturing attract greenfield mRNA facility investments targeting export markets.
Industry Challenges
- Lipid nanoparticle formulation expertise gap:Limited talent pools for mRNA encapsulation chemistry constrain scale-up velocity at contract manufacturing organizations.
- Multi-jurisdiction certification complexity:Parallel FDA, EMA, and CDSCO filing requirements fragment regulatory affairs resources and extend compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mono Vaccine Market |
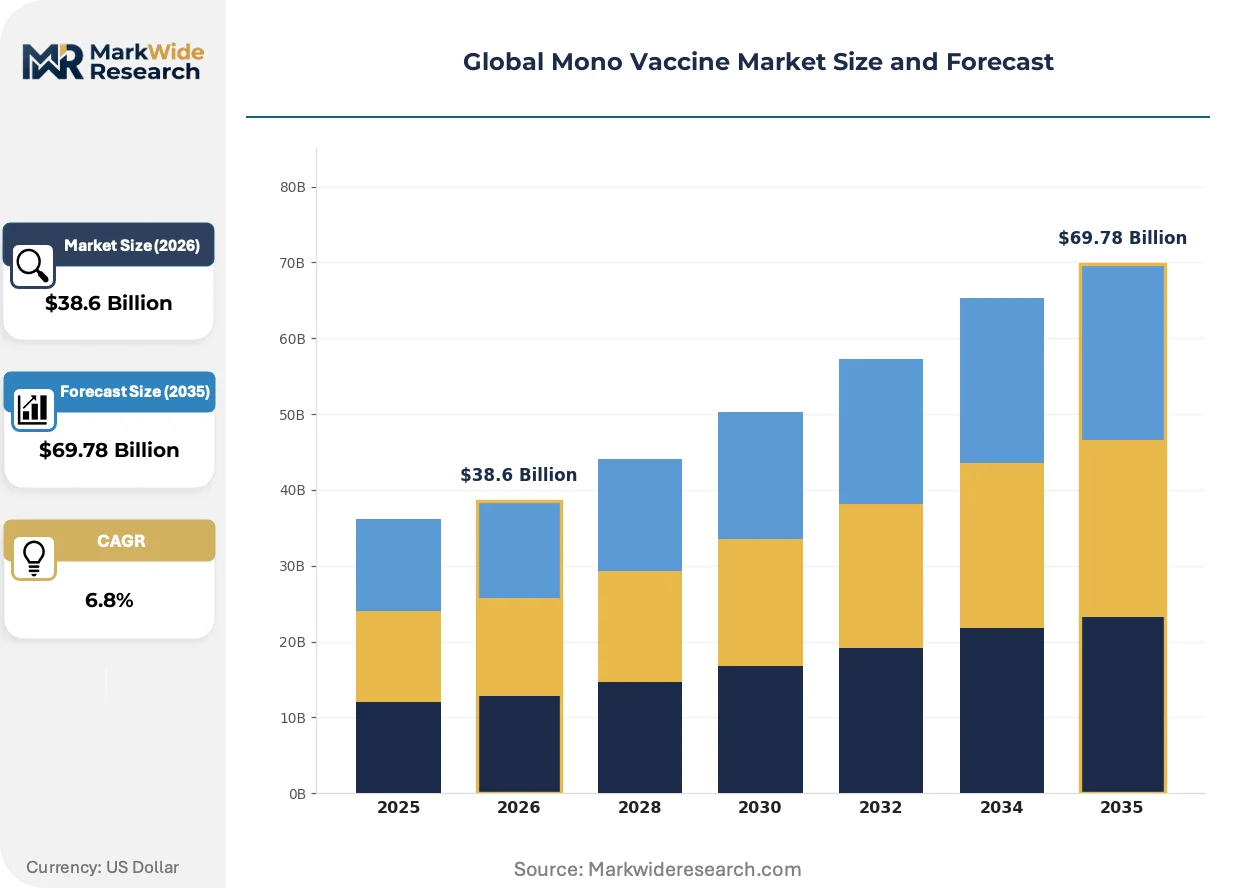
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Live Attenuated, Inactivated, Subunit, Toxoid, Conjugate, mRNA Application: Pediatric Immunization, Geriatric Immunization, Travel Medicine, Occupational Health, Maternal Immunization, Animal Health End User: Primary Care Providers, Specialized Clinics, Public Health Institutions, Research Laboratories, Veterinary Clinics, Occupational Health Centers Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Specialty Distributors, Online Pharmacies, Government Supply Chains, Cold Chain Logistics |
| Companies Covered | GlaxoSmithKline plc, Merck & Co., Inc., Pfizer Inc., Sanofi S.A., Johnson & Johnson, AstraZeneca plc, Moderna, Inc., Novavax, Inc., Serum Institute of India Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mono Vaccine Market Shifts & Advancements
Digital integration across clinical trial operations and cold chain monitoring is compressing development cycles while reshaping quality assurance protocols across the mono vaccine value chain.
Artificial intelligence-driven antigen design platforms are digitizing epitope prediction workflows that previously required months of laboratory screening. Large pharmaceutical developers deploy these tools for pandemic preparedness contracts requiring 100-day vaccine development timelines. The compression of preclinical phases is reallocating R&D budgets toward manufacturing scale-up rather than discovery biology.
REACH regulation amendments on per- and polyfluoroalkyl substances are forcing reformulation of certain stabilizing excipients used in lipid nanoparticle suspensions. European manufacturers face supply chain requalification costs for alternative surfactant chemistries. The regulatory pressure is accelerating adoption of chemically defined media formulations that eliminate undefined hydrolysate components.
Direct-to-government contracting models are displacing traditional distributor intermediaries in national immunization program procurement. Brazil's Ministry of Health and Indonesia's Bio Farma now negotiate volume commitments directly with manufacturers, compressing margin pools for regional logistics providers. This channel consolidation is most visible in Latin American and Southeast Asian markets where centralized purchasing authorities have consolidated tender authority.
Global Mono Vaccine Market Segmentation
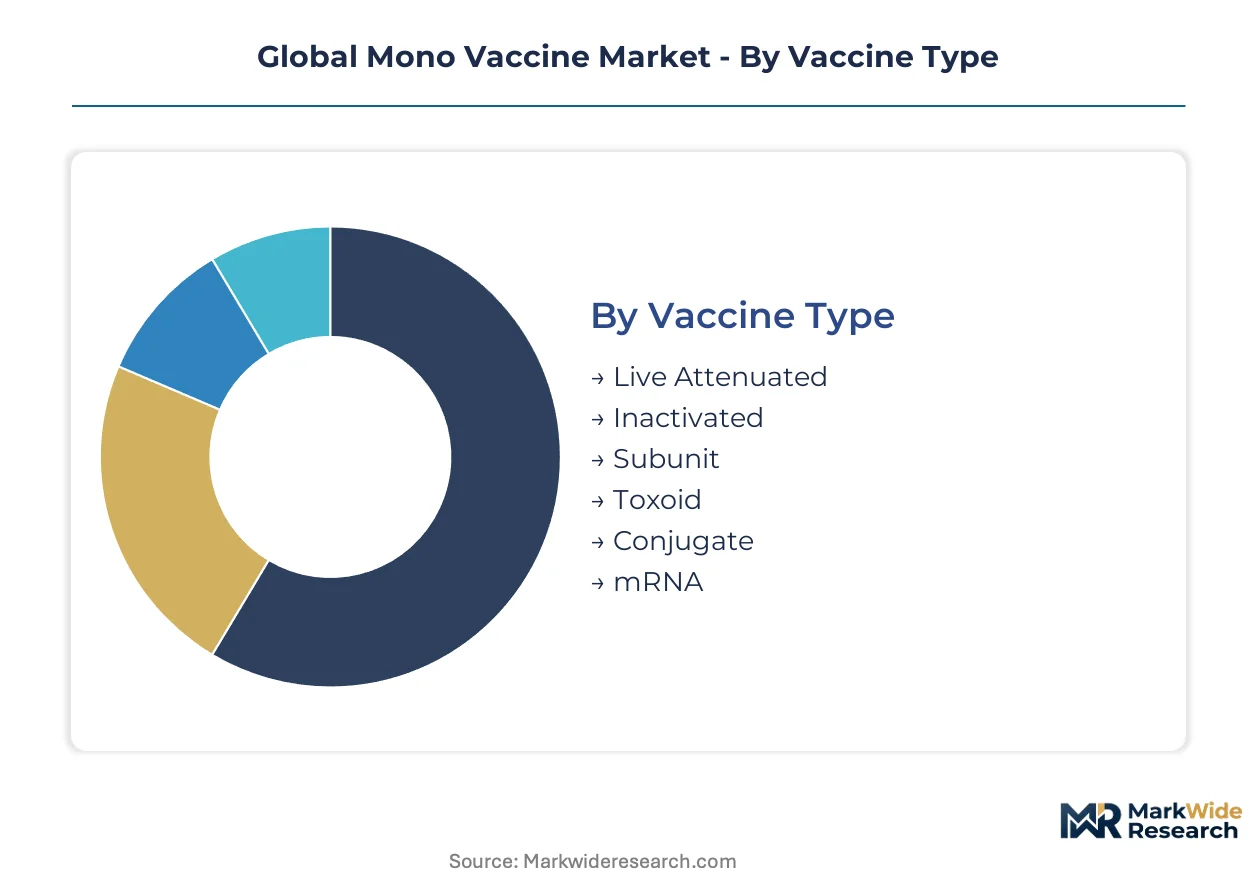
Segmentation in the mono vaccine market reveals distinct service intensity profiles across vaccine types and distribution channels. Cold chain requirements and patient population characteristics create divergent margin structures that manufacturers must navigate through specialized commercial strategies.
Vaccine Type:
After-sales service intensity varies dramatically across vaccine platforms, with mRNA formulations demanding continuous technical support for ultra-cold infrastructure while live attenuated products rely on established field service networks.
- Live Attenuated:These formulations contain weakened pathogen strains that replicate minimally in host cells to trigger robust cellular immunity. Demand concentrates in India's national immunization program through Serum Institute of India's high-volume supply contracts, constrained by thermostability limitations that require stringent two-to-eight-degree Celsius maintenance.
- mRNA:Synthetic nucleic acid sequences encoded within lipid nanoparticle carriers direct host cell protein expression for immune priming. Procurement is accelerating fastest in Singapore's travel medicine clinics and Germany's specialized vaccination centers, driven by platform flexibility enabling rapid antigen adaptation for emerging variants.
- Inactivated:Whole pathogens chemically or thermally destroyed retain immunogenicity without replication risk.
- Subunit:Purified protein or polysaccharide antigens combined with adjuvants elicit targeted humoral responses.
- Toxoid:Bacterial exotoxins inactivated by formalin treatment generate neutralizing antibody production.
- Conjugate:Polysaccharide antigens chemically linked to protein carriers enhance immunogenicity in infant populations.
Live attenuated platforms hold the largest share; momentum sits with mRNA as lipid nanoparticle manufacturing scales.
Application:
Cost tier stratification separates mass public health procurement from premium private-pay segments, with travel medicine and occupational health commanding per-dose multiples exceeding pediatric program pricing by significant margins.
- Pediatric Immunization:National program procurement through Gavi channels drives volume concentration in low-income countries. India's Universal Immunization Program and Nigeria's routine immunization schedule anchor demand, though per-dose margins compress under tender-based purchasing.
- Travel Medicine:Pre-departure consultations bundled with targeted immunizations extract premium pricing in Dubai's private clinic networks and Singapore's medical tourism corridors. Japanese business travelers and Australian tourists generate consistent demand for yellow fever and Japanese encephalitis mono vaccines.
- Geriatric Immunization:Age-related immune senescence drives demand for enhanced formulations in Japan's super-aged society.
- Occupational Health:Employer-mandated vaccination programs protect healthcare and laboratory workers against bloodborne pathogens.
- Maternal Immunization:Antenatal administration protects neonates through transplacental antibody transfer.
- Animal Health:Veterinary prophylaxis spans livestock production and companion animal segments.
Pediatric applications dominate volume; travel medicine delivers the steepest expansion trajectory in value terms.
End User:
Customer type fragmentation creates distinct purchasing behaviors, with public health institutions negotiating centralized tenders while specialized clinics compete on service bundling and consultation quality.
- Primary Care Providers:General practitioner networks administer routine immunizations within national health systems. Germany's hausarzt-centered model and the UK's NHS general practice contracts sustain steady demand for standard pediatric schedules.
- Specialized Clinics:Dedicated travel and tropical medicine centers combine consultation expertise with premium product access. Thailand's Hospital for Tropical Diseases and Brazil's Instituto de Infectologia Emílio Ribas anchor regional referral networks for complex vaccination requirements.
- Public Health Institutions:Government immunization programs procure through centralized tenders at volume-discounted rates.
- Research Laboratories:Clinical trial sites and academic medical centers source investigational and comparator products.
- Veterinary Clinics:Animal health practitioners administer livestock and companion animal vaccines.
- Occupational Health Centers:Corporate and industrial medical services manage workforce immunization compliance.
Primary care providers capture the greatest patient contact volume; specialized clinics are gaining share fastest through premium service differentiation.
Distribution Channel:
Supply concentration patterns favor vertically integrated channels in mature markets while fragmented retail networks persist in emerging economies with less centralized procurement.
- Government Supply Chains:Centralized procurement and direct-to-manufacturer contracting bypass traditional distribution intermediaries. Brazil's Ministry of Health and Indonesia's Bio Farma negotiate volume commitments directly with GlaxoSmithKline and Sanofi, compressing margins for regional logistics providers.
- Cold Chain Logistics:Temperature-controlled distribution networks command value-capture downstream from manufacturing. FedEx's SenseAware and UPS's PharmaPort platforms in the United States, plus DHL's Thermonet in Germany, sustain premium positioning through validated thermal monitoring.
- Hospital Pharmacies:Institutional procurement within integrated delivery networks consolidates purchasing power.
- Retail Pharmacies:Community-based vaccination services expand access in convenience-oriented segments.
- Specialty Distributors:Focused wholesalers serve niche therapeutic areas and geographic markets.
- Online Pharmacies:Digital channels facilitate appointment scheduling and home delivery in regulated frameworks.
Government supply chains dominate volume throughput; cold chain logistics providers are expanding most quickly as mRNA platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across procurement channels. India's national immunization program extracts maximum volume discounts through centralized tenders, while Singapore's private travel medicine clinics absorb premium markups with minimal price sensitivity. Germany's statutory health insurance system occupies the middle ground, negotiating moderate rebates on standard pediatric schedules.
United States
Pediatric immunization schedules and employer-mandated occupational health programs sustain baseline demand. The FDA's accelerated approval pathways compress development timelines for mRNA platform candidates. Boston's biotech cluster anchors translational research, with Massachusetts General Hospital and the Broad Institute driving early-phase clinical trials for next-generation lipid nanoparticle formulations.
India
The Universal Immunization Program and Gavi procurement channels generate the world's largest volume demand for live attenuated formulations. CDSCO enforces parallel quality benchmarks that determine export market access for domestic manufacturers. Pune's Serum Institute of India anchors regional supply concentration, operating high-volume fill-finish lines that serve African and Southeast Asian distribution networks.
Germany
Travel medicine clinics and specialized vaccination centers command premium per-dose margins from business travelers and medical tourists. EMA's adaptive pathway program enables rolling review mechanisms that shorten Phase III-to-approval intervals. Marburg's BioNTech manufacturing complex exemplifies mRNA production scale-up, with adjacent cold chain logistics hubs serving Central European distribution networks.
Brazil
National immunization program procurement through direct-to-government contracting displaces traditional distributor intermediaries. ANVISA enforces stability documentation requirements that extend market entry timelines for imported formulations. São Paulo's Butantan Institute anchors domestic fill-finish capacity, producing yellow fever and influenza mono vaccines for Latin American supply.
Japan
Super-aged demographic structure drives demand for enhanced geriatric formulations and adjuvanted subunit vaccines. PMDA's Sakigake designation system fast-tracks breakthrough therapies through priority review. Osaka's pharmaceutical manufacturing corridor concentrates fill-finish operations, with Kansai Airport's cold chain infrastructure enabling validated distribution to Southeast Asian markets.
Global Mono Vaccine Market Competitive Landscape
Integrated pharmaceutical conglomerates and specialized biotech platforms split the market into distinct capability tiers. Consolidation pressure intensifies as mRNA manufacturing expertise concentrates among players with captive lipid nanoparticle supply chains. Three archetypes dominate: legacy vaccine manufacturers with established cold chain networks, mRNA platform specialists with synthetic biology capabilities, and high-volume emerging market suppliers with cost-optimized fill-finish operations. Capacity expansion and strategic technology licensing represent the dominant competitive moves, with players securing antigen-adaptable platform rights for pandemic preparedness contracts.
Within the legacy manufacturer tier, GlaxoSmithKline plc and Merck & Co., Inc. occupy positions defined by refrigerated transport infrastructure and vertically controlled distribution partnerships. Pfizer Inc. exemplifies the mRNA transition archetype, with ultra-cold infrastructure investments differentiating its delivery capabilities. Serum Institute of India Pvt. Ltd. anchors the emerging market scale tier, representing cost-optimized production models that serve Gavi procurement channels.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Sanofi S.A. |
| Johnson & Johnson |
| AstraZeneca plc |
| Moderna, Inc. |
| Novavax, Inc. |
| Serum Institute of India Pvt. Ltd. |
| Others |
Supply & Pricing Matrix
DHL's Thermonet corridors linking Germany to Southeast Asia impose freight premiums that concentrate pricing power with manufacturers possessing captive cold chain infrastructure, while downstream buyers in India's national immunization program extract volume discounts that compress margins for distributors lacking thermal validation capabilities.
Pricing Analysis
After-sales service contracts for ultra-cold infrastructure maintenance drive lifetime value capture in mRNA segments. Three-tier pricing structure across premium, standard, and economy levels separates Gavi procurement rates from private travel clinic markups and veterinary commodity tiers. Cost compression in pediatric program supply is intensifying because centralized tenders in Nigeria and Indonesia consolidate purchasing volume. Public health institutions exhibit highest price sensitivity; Singapore's medical tourism corridors demonstrate least sensitivity due to bundled consultation premiums.
Supply Chain Analysis
Export-control restrictions on lipid nanoparticle manufacturing equipment limit technology transfer to emerging production clusters. Supply concentrates in India, Germany, and the United States for fill-finish capacity, while specialty aluminum salts and chemically defined media feed from concentrated chemical suppliers. Single-source vulnerability pervades pharmaceutical-grade adjuvant inputs. Distribution runs through government supply chains in volume segments and validated cold chain logistics in premium mRNA delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lipid nanoparticle formulation expertise functions as the critical chokepoint, with fewer than a dozen contract manufacturing organizations globally capable of mRNA encapsulation at commercial scale, creating asymmetric returns for players securing this talent pool.
For Market Incumbents: Build captive cold chain moats through backward integration into refrigerated transport networks that lock in Gavi procurement relationships. Secure exclusive lipid supplier contracts to foreclose emerging mRNA scale-up attempts. Anchor capacity additions in Pune and Marburg to intercept demand from African and Central European distribution networks respectively. For New Entrants and Emerging Players: Build out thermostable formulation capabilities that eliminate ultra-cold dependencies across African government supply chains. Target Brazil's ANVISA regulatory pathway for fastest emerging market entry. Pursue direct-to-government contracting models that bypass entrenched distributor relationships in Southeast Asian national immunization programs. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy pharmaceutical conglomerates spinning off vaccine divisions lacking mRNA platform capabilities. Long-term viability hinges on antigen-adaptable manufacturing infrastructure rather than single-product assets. Monitor WHO prequalification timeline compression as the signal indicating emerging market manufacturer readiness for acquisition.| Strategic Initiative | Industry Significance |
|---|---|
| Lipid Nanoparticle Manufacturing Scale-Up | Captive encapsulation capacity secures Pfizer and Moderna's mRNA platform dominance against contract manufacturing competitors. |
| Thermostable Formulation Development | Next-generation stabilization chemistries could displace cold chain dependencies across Serum Institute of India's African distribution networks. |
| Direct-to-Government Contracting | Brazil's Ministry of Health and Indonesia's Bio Farma now negotiate volume commitments directly, compressing regional logistics margins. |
| WHO Prequalification Acceleration | Streamlined stability documentation unlocks Gavi procurement channels for emerging market manufacturers in India and Southeast Asia. |
| Cold Chain Infrastructure Integration | GlaxoSmithKline's refrigerated transport networks sustain premium positioning against competitors relying on third-party logistics. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured interviews with regulatory affairs leads at EMA and CDSCO, formulary directors at Gavi and national immunization programs, cold chain logistics managers at DHL and FedEx, and manufacturing executives at Serum Institute of India and BioNTech. Secondary validation drew from FDA accelerated approval filings, WHO prequalification databases, ClinicalTrials.gov mRNA platform entries, and EMA adaptive pathway submissions. Bottom-up demand modeling triangulated against top-down market sizing across pediatric, travel medicine, and occupational health segments.
Calibration anchored historical volume data to reported procurement volumes through Gavi and UNICEF channels, then projected forward across the analysis window using platform-specific adoption curves. Segmentation dimensions modeled included vaccine type, application, end user, and distribution channel, with regional regulatory clusters treated as distinct forecast inputs. CAGRs derived from slope consistency across multiple scenario assumptions, with lipid nanoparticle manufacturing capacity expansion and thermostable formulation approval timelines serving as key sensitivity parameters.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese mRNA entrants or Indian PLI-supported greenfield facilities would shift outcomes. Material shifts in FDA accelerated approval stringency or WHO prequalification stability requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Biopharmaceuticals Contract Manufacturing Market
Biopharmaceuticals
Biopharmaceutical Excipients Market
Biopharmaceuticals
Human Insulin Market
Biopharmaceuticals
RNA Targeting Small Molecule Drug Discovery Market
Biopharmaceuticals
Human Immunodeficiency Virus (HIV) Drugs Market
Biopharmaceuticals
Russia Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
6-Azauracil Market
Biopharmaceuticals
Triptorelin Market
Biopharmaceuticals
Diabetes Drugs Market
Biopharmaceuticals
Global Swine Fever Vaccine Market
Biopharmaceuticals
Interleukin-6 (IL-6) Inhibitors Market
Biopharmaceuticals
Heparin API Market
Biopharmaceuticals
A - Estradiol Market
Biopharmaceuticals
Global Pegylated Proteins Market
Biopharmaceuticals
Brazil Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Oncology Drugs Market