
 Insulin Delivery Pens Market | 2026-2036
Insulin Delivery Pens Market Size, Share, and Industry Trends Forecast 2026-2036
Insulin Delivery Pens Market Outlook
Modularization of pen-and-cartridge systems is shifting buyer choice toward flexible, refillable platforms that reduce long-term cost burdens. Novo Nordisk A/S leverages its integrated insulin-pen portfolio to dominate high-volume diabetes markets. Sanofi competes through differentiated delivery technologies that address needle-phobia and dosing precision. Eli Lilly and Company anchors its position via sustained R&D investment in connected dosing systems.
An insulin delivery pen is a handheld, spring-loaded injection device engineered to administer precise insulin doses subcutaneously through disposable needles, typically calibrated in one-unit increments for glycemic control. Its primary commercial purpose centers on enabling reliable, patient-administered insulin therapy outside clinical settings. Disposable pens currently lead volume shipments due to convenience and lower upfront patient costs, while smart pens represent the fastest-expanding segment as Bluetooth-enabled dose tracking integrates with continuous glucose monitors. Reusable pens retain margin concentration in European markets where environmental regulations elevate device lifecycle expectations.
The FDA regulates these devices as Class II medical products under 21 CFR 882.5860, enforcing human-factors testing and dose-accuracy standards that elevate development costs for new entrants. The EMA's Medical Device Regulation and ISO 11608-1 needle-based injection system standards further constrain design flexibility while mandating interoperability testing. Japan's PMDA imposes additional localized clinical validation requirements that extend market access timelines. Stakeholders must monitor evolving cybersecurity frameworks for connected pens as regulators in multiple jurisdictions draft premarket guidance for software-as-medical-device functionality.
Market Dynamics
Smart pen connectivity standards under FDA digital health guidance are forcing device manufacturers to rebuild validation protocols around software-as-medical-device functionality, compressing development timelines while elevating cybersecurity compliance burdens.
Growth Catalysts
- Reimbursement Framework Maturation:Germany's Statutory Health Insurance system and Japan's PMDA reimbursement pathways now cover connected insulin delivery systems, accelerating patient access to dose-tracking technologies.
- Home Care Migration:Self-administration demand in United States home care settings pulls volume toward prefilled disposable pens calibrated for glycemic control without clinical supervision.
- ISO 11608-1 Harmonization:Global standardization of needle-based injection system specifications reduces regulatory fragmentation for manufacturers seeking multi-jurisdiction approval.
Market Restraints
- Biologic API Concentration:Insulin active pharmaceutical ingredient production clusters in Denmark and United States facilities, creating single-source vulnerability for pen cartridge supply.
- EMA MDR Compliance Burden:Europe's Medical Device Regulation mandates enhanced clinical evidence for reusable pen platforms, extending market access timelines by 18-24 months.
- Needle Disposal Regulation:EPA sharps waste protocols and state-level household medical waste restrictions impose logistical friction on patient self-management in United States markets.
Strategic Opportunities
- Latin America Underpenetration:Brazil's ANVISA regulatory pathway simplification and Argentina's diabetes prevalence create whitespace for disposable pen volume expansion outside saturated OECD markets.
- Continuous Glucose Monitor Convergence:Bluetooth-enabled smart pens integrating with Dexcom and Abbott sensor ecosystems enable closed-loop dosing feedback, commanding premium positioning.
- Indian PLI Scheme:India's Production Linked Incentive scheme for medical devices subsidizes domestic pen manufacturing, reducing import dependence for subcontinent diabetes management.
Industry Challenges
- Cybersecurity Talent Scarcity:Software-as-medical-device functionality requires embedded systems engineers with FDA premarket submission experience, a skill set concentrated in Boston and San Diego metro clusters.
- Legacy Health Record Integration:Hospital EMR systems lack standardized APIs for pen-generated dosing data, forcing middleware development that delays connected device deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulin Delivery Pens Market |
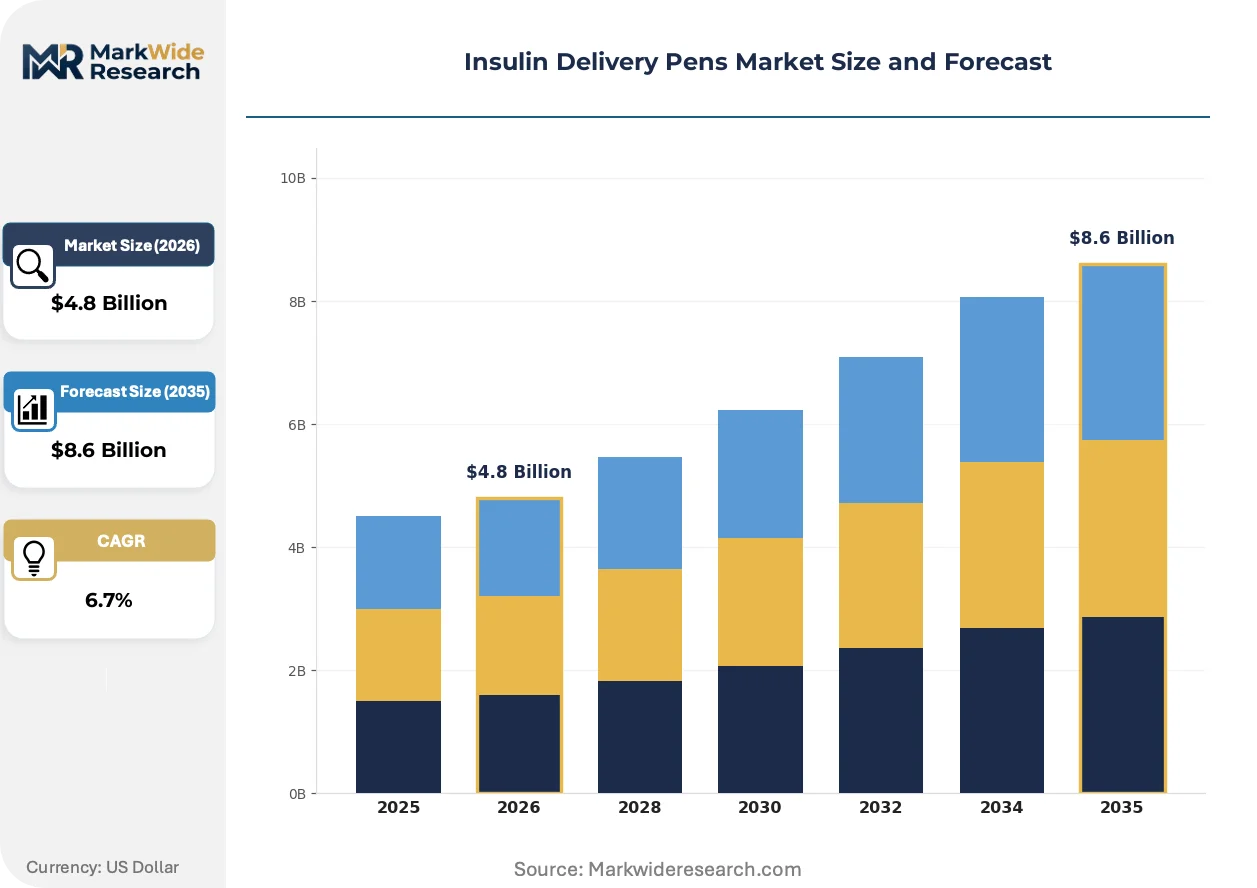
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Pens, Disposable Pens, Smart Pens, Safety Pens Delivery Mode: Subcutaneous, Intravenous, Intramuscular, Inhalation End User: Hospitals, Clinics, Home Care, Pharmacies Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Others |
| Companies Covered | Novo Nordisk A/S, Embecta Corp., Sanofi, Eli Lilly and Company, Medtronic, Ypsomed Holding AG, Insulet Corporation, Tandem Diabetes Care, Inc., Owen Mumford, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulin Delivery Pens Market Strategic Shifts
Digital biomarker integration is compressing the feedback loop between glucose sensing and insulin delivery, reshaping how device manufacturers architect pen hardware around software-defined dosing algorithms rather than mechanical precision alone.
Bluetooth-enabled dose logging is absorbing the memory function previously embedded in pen electronics, shifting data storage to smartphone applications and reducing per-unit hardware costs. Type 1 diabetes patients in United States and Germany adopt these connected systems fastest, with endocrinology practices now requiring dose-history downloads as a condition of care continuity. This architecture is absorbing margin from device manufacturers toward platform-owners controlling the data layer.
EMA's Medical Device Regulation is tightening clinical evidence requirements for pen needle compatibility claims, forcing manufacturers to conduct systematic biocompatibility studies across multiple needle suppliers. European notified bodies now reject submissions lacking ISO 11608-2 needle performance validation. Reusable pen platforms face the steepest compliance burden, with several United Kingdom and Netherlands-based manufacturers withdrawing legacy devices rather than funding retrospective clinical studies.
Patients increasingly select pens based on total cost-of-ownership calculations that include needle supply contracts and waste disposal fees, not device purchase price alone. United States pharmacy benefit managers now bundle pen and needle procurement through single-source agreements, compressing manufacturer choice for endocrinology practices. Germany's sickness funds apply similar bundling logic, steering volume toward integrated pen-needle systems with documented disposal compliance.
Insulin Delivery Pens Market Segmentation
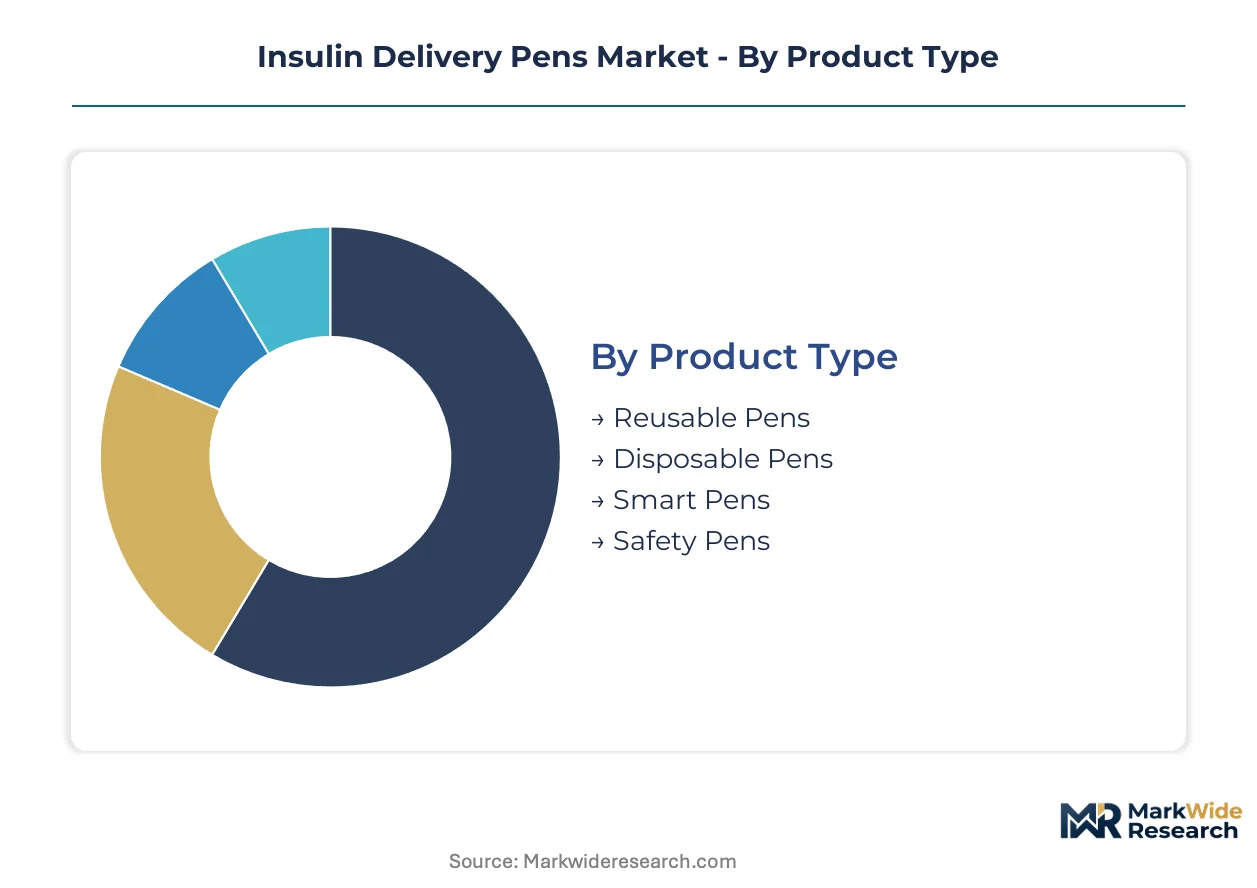
Segmentation in insulin delivery pens reveals how device architecture, clinical setting, and patient physiology intersect to determine procurement patterns. Manufacturers configure product portfolios across these axes to capture volume in reimbursement-driven markets while positioning for premium positioning in connected care ecosystems.
Product Type:
Device architecture determines capital commitment, regulatory pathway, and software integration depth for manufacturers competing across patient self-administration and clinical settings.
- Disposable Pens:Prefilled, single-use devices eliminate cartridge replacement and reduce infection risk through sealed insulin reservoirs. United States pharmacy benefit managers bundle these with needle contracts, compressing manufacturer margins while locking in volume through formulary placement.
- Smart Pens:Bluetooth-enabled dose tracking integrates with Dexcom and Abbott continuous glucose monitor ecosystems, enabling closed-loop feedback algorithms. Germany's Statutory Health Insurance reimbursement for connected dosing systems accelerates patient access in European markets where data continuity drives prescribing decisions.
- Reusable Pens:Modular cartridge systems reduce per-dose cost for high-volume Type 1 patients. EMA MDR compliance burdens extend market access timelines for legacy European manufacturers.
- Safety Pens:Needle-shielding mechanisms address occupational exposure regulations in United States hospital systems. OSHA bloodborne pathogen compliance drives procurement in clinical settings.
Disposable pens lead on scale; smart pens lead on momentum.
Delivery Mode:
Route of administration constrains device engineering, pharmacokinetic profile, and patient training requirements across diabetes management protocols.
- Subcutaneous:Abdominal or thigh injection through 4-6mm needles remains the standard for basal and bolus insulin delivery. Home care settings in Japan and the United States concentrate demand for patient-calibrated devices with one-unit dose increments.
- Intravenous:Hospital-only administration for diabetic ketoacidosis and perioperative glycemic control requires syringe pumps rather than pen devices. United States acute care systems maintain separate procurement channels for this route.
- Intramuscular:Rarely indicated for insulin due to unpredictable absorption kinetics; limited to emergency glucagon delivery in severe hypoglycemia protocols.
- Inhalation:Afrezza and similar devices bypass injection entirely, appealing to needle-phobic patients. FDA pulmonary safety requirements constrain label expansion beyond mealtime correction dosing.
Subcutaneous delivery commands installed base; inhalation routes gain share fastest among injection-averse patient cohorts.
End User:
Care setting determines regulatory scrutiny, reimbursement coding, and device feature prioritization across the insulin delivery value chain.
- Home Care:Self-administration by Type 1 and intensive Type 2 patients drives demand for discreet, portable devices with dose memory. United States patients select pens based on total cost-of-ownership including needle supply and sharps disposal fees.
- Hospitals:Inpatient glycemic management protocols require dose verification and EMR integration. Legacy health record systems lack standardized APIs for pen-generated data, forcing middleware development.
- Clinics:Endocrinology practices in Germany now require dose-history downloads as a condition of care continuity, favoring connected devices.
- Pharmacies:Retail dispensing concentrates volume in prefilled disposable formats with established reimbursement codes.
Home care settings dominate volume; hospitals impose the steepest compliance requirements on device connectivity.
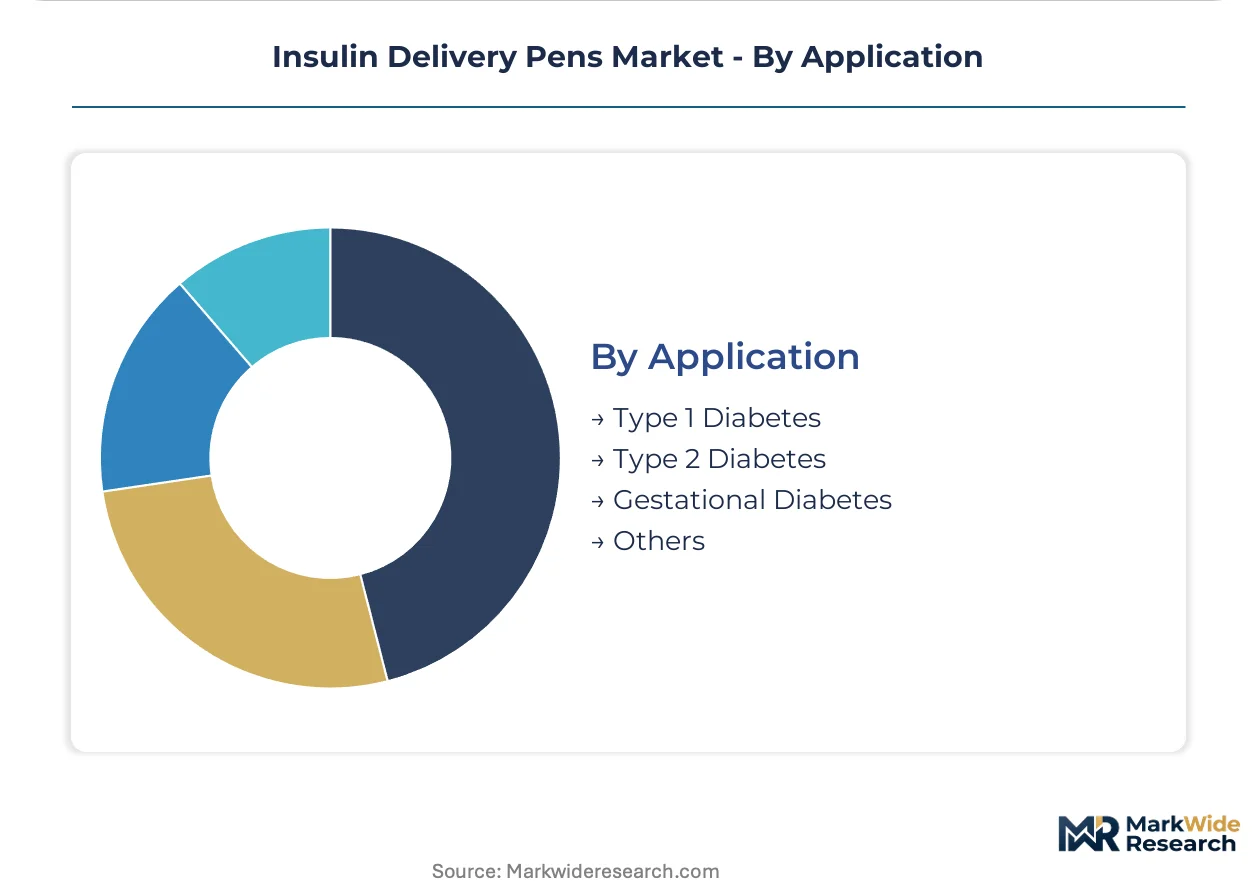
Application:
Diabetes phenotype determines insulin regimen complexity, device feature requirements, and patient education investment across therapeutic segments.
- Type 1 Diabetes:Absolute insulin deficiency requires multiple daily injections or pump therapy with precise carbohydrate counting. Patients in Germany and the United States adopt smart pen connectivity fastest due to intensive monitoring demands.
- Type 2 Diabetes:Progressive beta-cell dysfunction creates heterogeneous insulin needs; many patients maintain oral therapy for years before injection initiation. Brazil's ANVISA pathway simplification targets this expanding population in underpenetrated markets.
- Gestational Diabetes:Temporary insulin requirements during pregnancy prioritize safety and dosing simplicity over advanced features. Maternal-fetal medicine protocols favor disposable pens with clear unit markings.
- Others:Cystic fibrosis-related diabetes and steroid-induced hyperglycemia represent niche indications with specialized dosing requirements.
Type 1 diabetes concentrates premium device adoption; Type 2 diabetes represents the deepest volume reservoir for market expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark pioneered industrial-scale insulin production in the 1920s, establishing the geographic foundation for modern pen device manufacturing. Germany and Japan subsequently developed precision injection engineering capabilities that shaped contemporary device standards. Today, national reimbursement frameworks and regulatory pathways determine patient access patterns across major diabetes markets.
United States
Medicare Part D and commercial pharmacy benefit managers bundle pen-needle procurement through single-source agreements, steering volume toward integrated systems. FDA digital health guidance for connected devices compresses development timelines while elevating cybersecurity compliance. Boston and San Diego metro clusters concentrate embedded systems engineering talent for software-as-medical-device functionality.
Germany
Statutory Health Insurance reimbursement for connected insulin delivery systems accelerates smart pen adoption among Type 1 patients. EMA Medical Device Regulation mandates enhanced clinical evidence for reusable platforms, extending market access timelines. Baden-Württemberg's medical technology corridor hosts precision injection engineering specialists serving European device manufacturers.
Japan
PMDA reimbursement pathways for dose-tracking technologies expand patient access to connected pen systems. Japan's national health insurance system prioritizes devices with documented glycemic outcomes in elderly populations. Tokyo-Osaka industrial corridor concentrates domestic pen manufacturing for Asia-Pacific distribution.
Brazil
ANVISA regulatory pathway simplification targets expanding Type 2 diabetes populations in underpenetrated markets. Public health system procurement concentrates volume in cost-optimized disposable formats. São Paulo state's pharmaceutical distribution infrastructure anchors Latin American supply chain logistics.
India
Production Linked Incentive scheme subsidies reduce import dependence for domestic pen manufacturing. Central Drugs Standard Control Organization streamlines medical device registration for multinational entrants. Gujarat and Maharashtra industrial zones attract contract manufacturing investment for subcontinent diabetes management.
Insulin Delivery Pens Market Competitive Environment
The competitive structure tilts toward integrated pharmaceutical-device conglomerates with captive insulin supply. Market concentration reflects high barriers from FDA Class II validation requirements and ISO 11608-1 harmonization costs. Three archetypes dominate: vertically integrated insulin-pen manufacturers, specialized injection device engineers, and emerging connected technology platforms. Capacity expansion and strategic portfolio diversification constitute the primary competitive moves as firms position for smart pen convergence.
Among Nordic-anchored pharmaceutical conglomerates, Novo Nordisk A/S occupies a foundational position exemplifying vertical integration from active pharmaceutical ingredient through delivery device. Sanofi and Eli Lilly and Company represent diversified multinational archetypes with sustained R&D positioning in connected dosing systems. These three anchors illustrate how insulin supply security and device engineering capability combine to determine competitive standing.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Embecta Corp. |
| Sanofi |
| Eli Lilly and Company |
| Medtronic |
| Ypsomed Holding AG |
| Insulet Corporation |
| Tandem Diabetes Care, Inc. |
| Owen Mumford |
| Others |
Value Chain & Pricing Dynamics
Pharmacy benefit manager bundling of pen-needle procurement in the United States forces manufacturers to restructure cost allocation across device and consumable lines, compressing headline device prices while recovering margin through multi-year needle supply contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Bluetooth-enabled smart pens from disposable prefilled devices and modular reusable platforms. Price differentiation rests on ISO 11608-1 certification tier and after-sales data service bundling. Cost compression in the standard disposable tier is intensifying because Germany's sickness funds now mandate total cost-of-ownership calculations including sharps disposal compliance. Home care patients in the United States exhibit highest price sensitivity; hospital procurement committees in Japan demonstrate lowest sensitivity due to reimbursement pass-through mechanisms.
Supply Chain Analysis
Regional distribution centers in Denmark, the United States, and Germany operate hub-and-spoke patterns serving continental markets with 48-hour replenishment cycles. Active pharmaceutical ingredient production draws from Danish and United States facilities, while precision injection molding concentrates in Germany and Japan. Single-source vulnerability for insulin API creates structural risk should geopolitical friction disrupt North Atlantic trade lanes. Distribution runs through pharmaceutical wholesaler networks with temperature-controlled logistics mandatory for cartridge integrity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's Production Linked Incentive scheme subsidies create a 15-20 percent manufacturing cost advantage versus European production, positioning the subcontinent as the geographic-arbitrage destination for multinational volume expansion.
For Market Incumbents: Deploy backward integration into insulin API production to neutralize single-source supply risk from Danish and United States concentration. Fortify market position by accelerating FDA premarket submissions for software-as-medical-device functionality ahead of evolving cybersecurity guidance. Threat from emerging connected technology platforms demands preemptive data platform ownership rather than hardware margin defense alone. For New Entrants and Emerging Players: Bluetooth-enabled dose logging algorithms offer a technology-first wedge into the United States Type 1 diabetes segment where endocrinology practices now require dose-history downloads. White-space targets include Brazil's ANVISA-simplified regulatory pathway for expanding Type 2 populations and India's domestic manufacturing subsidy environment. Go-to-market angle should emphasize CGM ecosystem integration partnerships with Dexcom or Abbott rather than standalone device competition. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized injection device engineers possessing ISO 11608-2 needle performance validation capabilities and existing European notified body relationships. Long-term viability over the coming decade hinges on software-defined dosing algorithm differentiation rather than mechanical precision heritage. Signal to watch is FDA draft guidance finalization for connected pen cybersecurity premarket requirements as inflection indicator for compliance cost barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-Medical-Device FDA Submission | Bluetooth-enabled dose tracking meets evolving FDA digital health guidance for premarket clearance. |
| CE Marking Pathway Expansion | EMA MDR compliance for reusable platforms extends market access across European notified body jurisdictions. |
| Hospital System Partnership | EMR integration agreements with United States health systems overcome legacy API standardization gaps. |
| CGM Ecosystem Integration | Dexcom and Abbott sensor interoperability commands premium positioning in closed-loop dosing feedback. |
| Reimbursement Strategy | Germany's Statutory Health Insurance coverage for connected systems accelerates patient access and prescribing pull-through. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with endocrinology practice administrators, biomedical engineers at device manufacturers, GPO contracts managers, and regulatory affairs specialists with secondary validation against FDA 510(k) filings, EMA MDR submission databases, ISO 11608-1 standards documentation, and national reimbursement code listings. Bottom-up pen shipment estimates and top-down insulin prescription volume analysis triangulated to cross-check segment sizing.
Comparable-period anchoring to historical prescription volumes and device replacement cycles established the forecast baseline across the projection horizon. Segmentation dimensions modeled include product architecture, delivery route, care setting, diabetes phenotype, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to insulin-dependent population projections and technology adoption S-curves. Forecast inputs incorporated PMDA reimbursement pathway expansion timelines and ANVISA regulatory simplification milestones.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA cybersecurity guidance finalization, EMA MDR enforcement consistency, and insulin API supply chain geopolitical stability. Outputs reflect documented assumptions around reimbursement expansion rates and connected device adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Human Recombinant Insulin Market
Biopharmaceuticals
North America Contraceptives Market
Biopharmaceuticals
Brexucabtagene Autoleucel Market
Biopharmaceuticals
Immunotoxins Market
Biopharmaceuticals
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market
Biopharmaceuticals
Olaparib API Market
Biopharmaceuticals
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market
Biopharmaceuticals
Global Infertility Drugs Market
Biopharmaceuticals
Latin America G-CSF/ PEG-G-CSF Market
Biopharmaceuticals
Disease-Modifying Antirheumatic Drug (DMARD) Market
Biopharmaceuticals
Biologics Contract Development Market
Biopharmaceuticals
Generic Injectables Market
Biopharmaceuticals
Erythropoietin Drugs Market
Biopharmaceuticals
Somatropin Market
Biopharmaceuticals
Global Insulin Glargine Market
Biopharmaceuticals
South Korea Insulin Drugs and Delivery Devices Market