
 Biotherapeutics Cell Line Development Market | 2026-2036
Biotherapeutics Cell Line Development Market Size, Share, and Industry Trends Forecast 2026-2036
Biotherapeutics Cell Line Development Market Analysis
The gap between premium clonal cell lines and commodity expression platforms is rebalancing as sponsors demand higher productivity titers for complex biologics. Lonza Group leverages its integrated manufacturing footprint across Switzerland and Singapore to anchor high-value mammalian cell line services. Thermo Fisher Scientific competes through end-to-end workflow solutions spanning transfection reagents to analytical characterization. WuXi Biologics dominates the Asia-Pacific contract development landscape with accelerated timelines for Chinese hamster ovary cell line generation.
Biotherapeutics cell line development encompasses the genetic engineering, selection, and stabilization of host cells to produce recombinant therapeutic proteins, with Chinese hamster ovary cells achieving specific productivities exceeding 50 picograms per cell per day for monoclonal antibodies. The process serves as the foundational manufacturing step determining yield, quality attributes, and regulatory compliance for commercial biologics. Mammalian expression systems lead in value contribution due to their human-compatible glycosylation patterns required for antibody therapeutics. CRISPR technology is displacing conventional random integration approaches as the fastest-growing segment, enabling targeted knock-in of expression cassettes with reduced clone screening burden. Contract manufacturing organizations represent the most concentrated end-user margin pool, outsourcing cell line construction to specialized providers with proprietary platform technologies.
FDA guidelines on quality by design and ICH Q5D standards for cell substrate characterization shape product development timelines and documentation requirements for market authorization. EMA's investigational medicinal product dossier requirements and China's NMPA technical guidelines on genetically modified cell lines further constrain entry pathways for new developers. Stakeholders must monitor evolving regulatory convergence on next-generation sequencing-based clonality assurance as agencies replace traditional limiting dilution evidence with molecular confirmation methods.
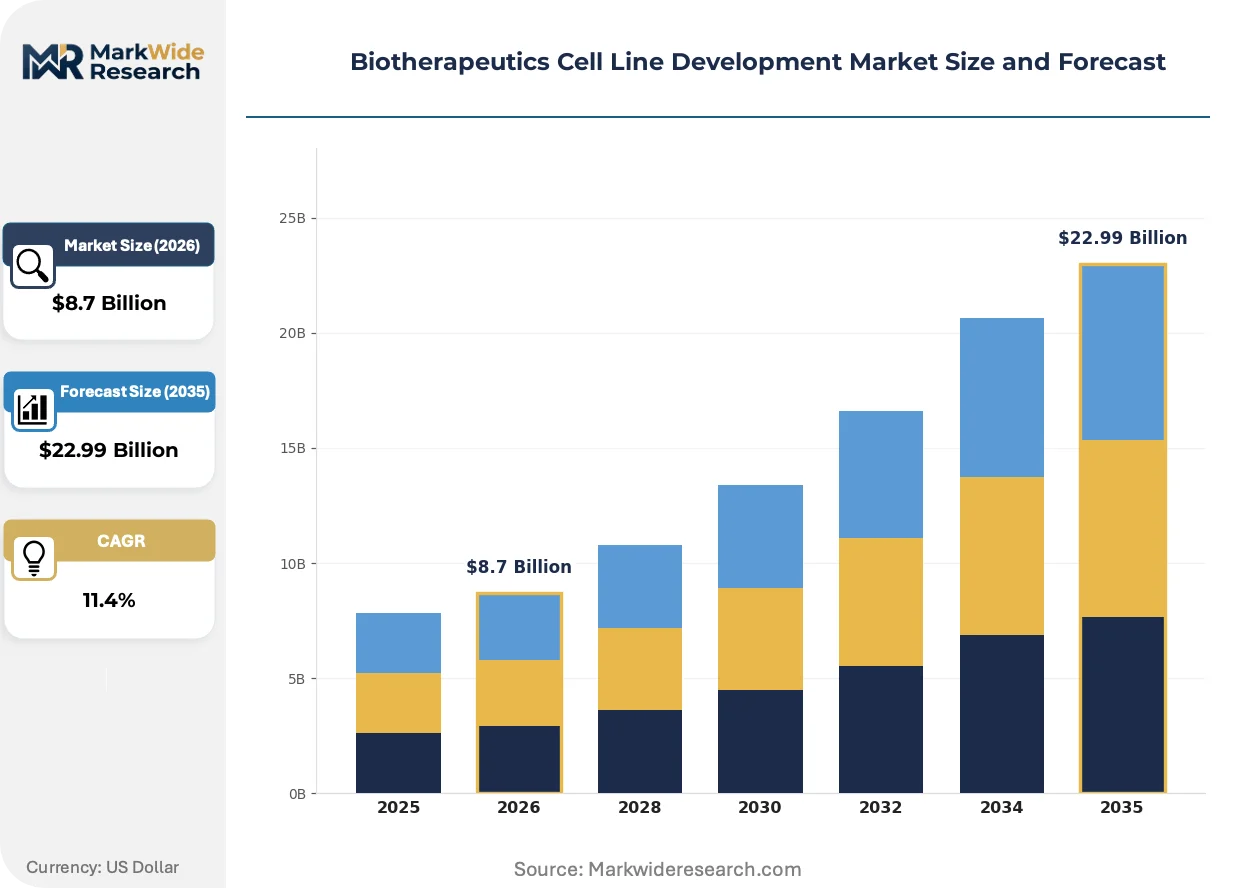
Market Dynamics
CRISPR-based precision editing is compressing clone selection timelines from months to weeks while simultaneously elevating regulatory scrutiny on genetic stability documentation across FDA, EMA, and NMPA submissions.
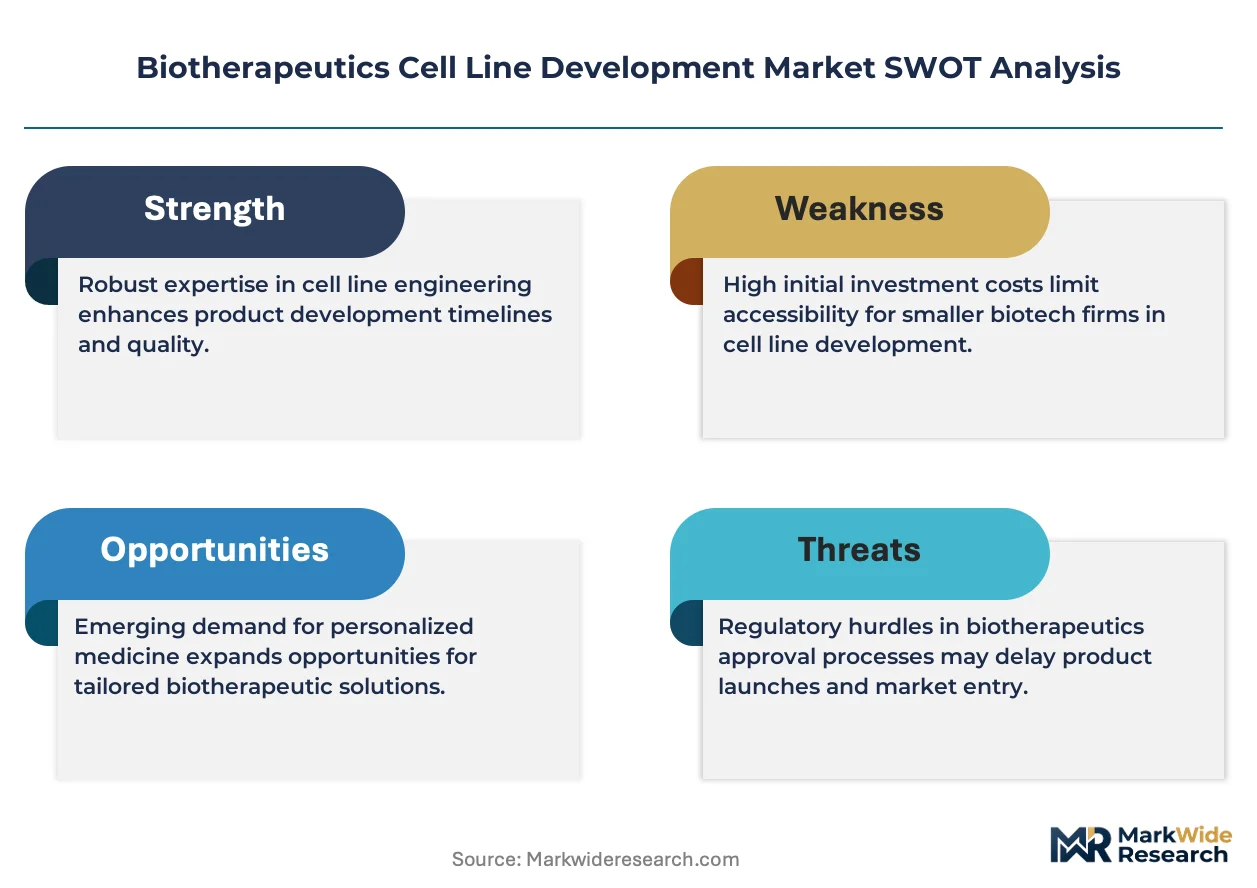
Growth Catalysts
- ICH Q5D Standards:Harmonized cell substrate characterization requirements across FDA, EMA, and NMPA jurisdictions reduce redundant documentation burdens for multi-regional filings.
- Complex Biologics Pipeline:Bispecific antibodies and antibody-drug conjugates require engineered glycosylation profiles that only mammalian expression systems deliver.
- Contract Manufacturing Concentration:Sponsors in Switzerland, Singapore, and the United States outsource cell line construction to specialized providers with proprietary platform technologies.
Market Restraints
- Proprietary Media Formulation Costs:Chemically defined serum-free media represent 35-50% of upstream production costs with limited qualified suppliers.
- Single-Source Equipment Dependency:Bioreactor instrumentation and single-use consumables concentrate supply risk with German and Swiss automation vendors.
- Clonality Assurance Burden:Next-generation sequencing validation requirements under evolving FDA guidance extend IND-enabling timelines.
Strategic Opportunities
- India CDMO Expansion:Underpenetrated biologics manufacturing capacity in Hyderabad and Bengaluru offers cost-advantaged cell line development for export markets.
- Continuous Processing Convergence:Integration of perfusion bioreactors with real-time quality analytics enables steady-state manufacturing with reduced facility footprint.
- Japan PMDA Innovation Pathway:Sakigake designation accelerates review timelines for regenerative medicine products using novel engineered cell lines.
Industry Challenges
- Cell Line Stability Expertise Gap:Shortage of molecular biologists with mammalian synthetic biology training extends candidate screening phases.
- Multi-Attribute Method Validation:Analytical method transfer from development to GMP quality control creates bottlenecks for novel glycoengineered products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biotherapeutics Cell Line Development Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cell Type: Chinese Hamster Ovary, Human Embryonic Kidney, Ramos, Hybridoma Process Stage: Transfection, Screening, Stabilization, Characterization Technology: CRISPR, Microbial Fermentation, Mammalian Expression, Spinning Bioreactor End User: Biopharmaceutical Companies, Research Institutions, Contract Manufacturing Organizations, Academic Labs |
| Companies Covered | Lonza Group, Thermo Fisher Scientific, Sartorius AG, Merck KGaA, Danaher Corporation, WuXi Biologics, Charles River Laboratories, Catalent, FUJIFILM Diosynth Biotechnologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biotherapeutics Cell Line Development Market Emerging Trajectories
Automated clone screening and artificial intelligence-guided sequence optimization are redefining productivity benchmarks while compressing the traditional 12-18 month development window.
CRISPR-Cas9 knock-in engineering is overtaking random integration as the dominant approach for expression cassette placement. Contract development organizations in the United States and Germany now specify targeted integration for 70% of new programs. This shift eliminates positional effect variation and reduces clone screening from thousands to hundreds of candidates.
EMA's revised investigational medicinal product dossier requirements now mandate extended genetic stability data for gene-edited substrates. Sponsors must demonstrate 60 population doublings without phenotypic drift. Chinese hamster ovary programs face the steepest compliance curve as legacy cell banks predate these standards.
Platform licensing agreements now dominate early-stage biotech procurement. Sponsors secure access to pre-validated host cell backgrounds with established regulatory histories rather than constructing de novo lines. This preference concentrates in oncology antibody programs where speed-to-IND determines financing milestones.
Biotherapeutics Cell Line Development Market Segmentation
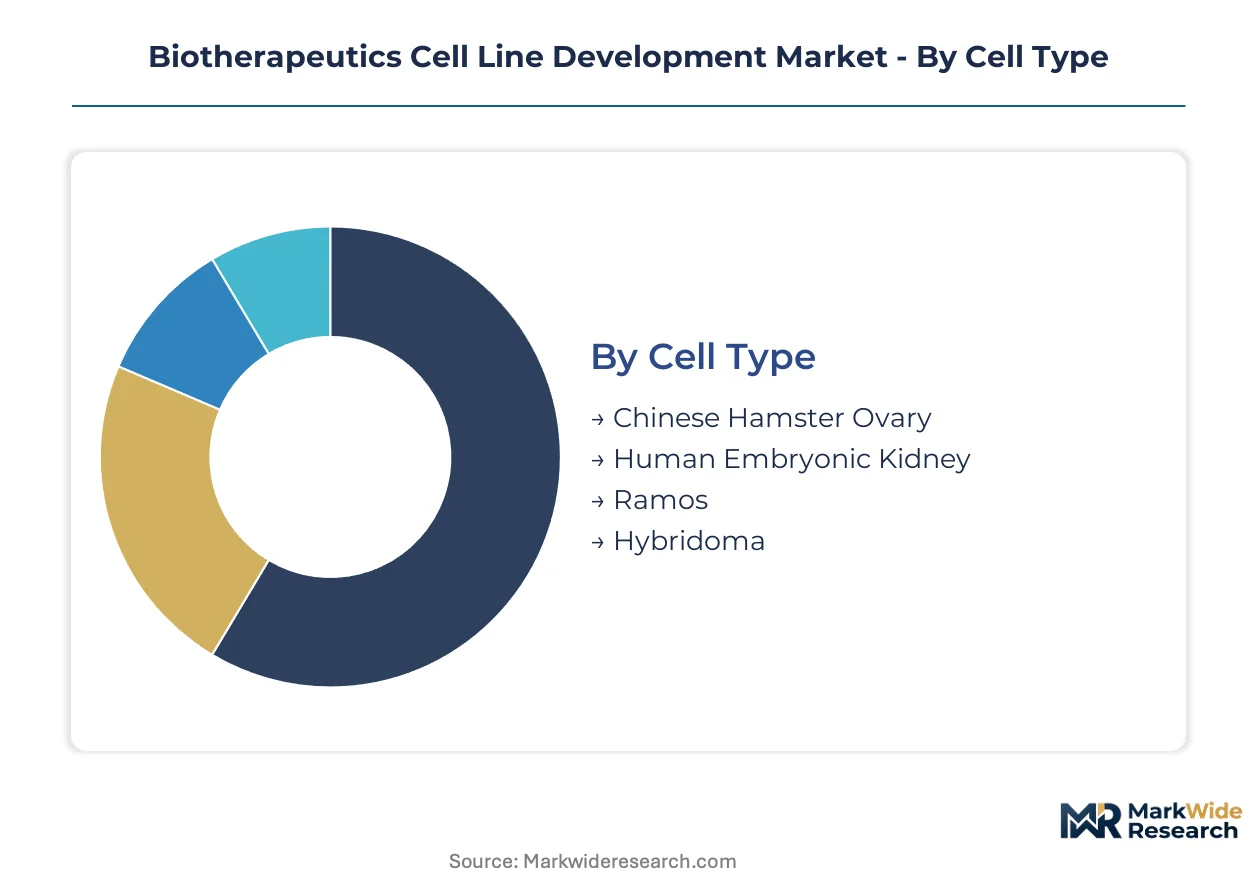
Cell line development procurement hinges on matching expression system capabilities to therapeutic modality complexity. Sponsors segment investments by glycosylation requirements, regulatory pathway, and manufacturing scale-up certainty.
Cell Type:
CHO cells dominate commercial antibody manufacturing due to their human-compatible glycosylation machinery and decades of regulatory precedent.
- Chinese Hamster Ovary:Industry-standard host for monoclonal antibody production with established master cell bank histories accepted by FDA, EMA, and NMPA. Specific productivity exceeds 50 picograms per cell per day for high-performing clones. Demand concentrates in Switzerland and Singapore where Lonza and WuXi Biologics operate integrated manufacturing campuses for Phase III and commercial supply.
- Human Embryonic Kidney:Transient expression platform enabling rapid protein production for early-stage candidate screening without stable cell line investment. HEK293 systems achieve 10-20x faster turnaround than CHO for non-glycosylated biologics. Academic labs and early-stage biotechs in Germany and the United States favor HEK for proof-of-concept studies.
- Ramos:Human B-lymphocyte line specialized for recombinant immunoglobulin secretion with native human glycosylation patterns. Niche applications include biosimilar development requiring exact glycoform matching to reference products.
- Hybridoma:Murine myeloma fusion partner for monoclonal antibody discovery, now declining in commercial manufacturing due to non-human glycosylation triggering immunogenicity concerns. Retains utility in diagnostic reagent production.
Volume sits with Chinese Hamster Ovary; growth tilts toward Human Embryonic Kidney for gene therapy vector and bispecific screening applications.
Process Stage:
Timeline compression pressure reshapes where sponsors allocate internal versus outsourced capability.
- Transfection:Electroporation and lipid-based delivery of expression vectors into host cells, with platform providers standardizing transfection efficiency above 80% through optimized protocols. Automated systems now process 96-well plates in under four hours.
- Screening:Clone selection via limiting dilution or single-cell deposition, historically consuming 3-6 months. CRISPR-enabled targeted integration reduces screening burden from thousands to hundreds of clones by eliminating positional effects.
- Stabilization:Extended culture under selective pressure to ensure expression cassette retention and phenotypic consistency across 60 population doublings. EMA's revised IMPD requirements now mandate genetic stability documentation at this stage.
- Characterization:Comprehensive identity, purity, and potency testing including clonality assurance via next-generation sequencing. FDA guidance evolution toward molecular clonality confirmation extends IND-enabling timelines.
Outsourcing concentrates in Screening and Characterization; internal capability investment targets Transfection platform standardization.
Technology:
Gene editing precision now determines competitive positioning in cell line service provision.
- CRISPR:Targeted knock-in of expression cassettes at predetermined genomic loci eliminates clone-to-clone productivity variation. Contract development organizations in the United States and Germany specify CRISPR for 70% of new antibody programs.
- Microbial Fermentation:Bacterial and yeast systems for non-glycosylated proteins including insulin analogs and growth factors. Escherichia coli platforms achieve gram-per-liter titers at manufacturing cost points below mammalian systems.
- Mammalian Expression:Encompasses CHO, HEK, and derivative lines requiring complex media formulations and bioreactor infrastructure. Represents the highest value-add segment due to glycosylation fidelity requirements for antibody therapeutics.
- Spinning Bioreactor:Perfusion culture technology enabling continuous processing with steady-state cell densities exceeding 100 million cells per milliliter. Integration with real-time quality analytics supports reduced facility footprint manufacturing.
Revenue contribution peaks with Mammalian Expression; capability expansion concentrates in CRISPR engineering services.
End User:
Procurement authority and risk tolerance differentiate buyer segments.
- Biopharmaceutical Companies:Large-cap sponsors maintain internal cell line construction for core pipeline assets while outsourcing platform technologies for speed-critical programs. Internal investment focuses on proprietary host cell backgrounds with established regulatory histories.
- Research Institutions:National laboratories and university centers access federally funded core facilities for early-stage protein production. Demand emphasizes HEK transient systems and open-source CRISPR reagents.
- Contract Manufacturing Organizations:CDMOs represent the most concentrated margin pool, building proprietary platform technologies to anchor multi-year client relationships. WuXi Biologics, Lonza, and Thermo Fisher compete on accelerated CHO timelines.
- Academic Labs:Limited budgets drive preference for kit-based transfection systems and shared institutional screening infrastructure. Publication timelines prioritize speed over regulatory documentation depth.
Spend concentration sits with Contract Manufacturing Organizations; fastest expansion occurs in Biopharmaceutical Companies reclaiming internal capability for complex modality pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biotech corridor anchors cell line development activity through concentrated venture funding and proximity to FDA headquarters. The metropolitan area hosts contract research organizations specializing in CRISPR-engineered Chinese hamster ovary platforms.
United States
FDA's quality-by-design guidelines and IND-enabling requirements drive demand for clonality-assured cell substrates. The agency's evolving stance on next-generation sequencing for genetic stability documentation extends pre-submission timelines. Greater Boston and San Francisco Bay Area clusters concentrate CDMO capacity for Phase III mammalian programs.
Germany
EMA's investigational medicinal product dossier mandates 60 population doubling stability data for gene-edited substrates. ECHA oversight of genetically modified organism containment shapes facility design standards. Heidelberg and Munich host specialized providers integrating automated clone screening with perfusion bioreactor platforms.
Switzerland
Swissmedic alignment with ICH Q5D standards streamlines multi-regional filing preparation for local sponsors. The country's dual-linguistic regulatory interface reduces documentation translation burdens. Basel and Zürich industrial zones anchor integrated manufacturing campuses serving commercial antibody supply.
China
NMPA technical guidelines on genetically modified cell lines constrain entry pathways for novel developers. The regulator's accelerated review pathways for innovative biologics compress IND-to-clinic timelines. Shanghai and Suzhou biotech parks concentrate contract development capacity for domestic and export markets.
Singapore
Economic Development Board incentives for biologics manufacturing anchor regional headquarters decisions. The national pharmaceutical regulator maintains mutual recognition arrangements with FDA and EMA. Tuas Biomedical Park hosts large-scale mammalian production facilities serving Asia-Pacific distribution.
Biotherapeutics Cell Line Development Market Vendor Landscape
Premium-margin players sit above commodity-margin players across regulatory documentation depth and platform technology sophistication. The vendor base stratifies into three tiers: integrated CDMOs with captive bioreactor networks, specialized cell line engineering boutiques, and reagent suppliers extending into services. Swiss and German automation vendors concentrate supply risk for bioreactor instrumentation. Strategic moves center on platform licensing agreements and geographic capacity expansion.
Within the integrated CDMO tier, Lonza Group and WuXi Biologics occupy positions spanning discovery through commercial manufacturing. Thermo Fisher Scientific represents the workflow consolidation archetype, bridging transfection reagents to analytical characterization. These three entities exemplify competitive positioning through regulatory history depth and accelerated timeline offerings.
| Leading Market Players |
|---|
| Lonza Group |
| Thermo Fisher Scientific |
| Sartorius AG |
| Merck KGaA |
| Danaher Corporation |
| WuXi Biologics |
| Charles River Laboratories |
| Catalent |
| FUJIFILM Diosynth Biotechnologies |
| Others |
Supply Flow & Price Mechanics
Chemically defined serum-free media formulations flow from German and Swiss specialty chemical suppliers through tiered service contracts to contract manufacturing organizations, with media costs representing 35-50% of upstream production expenses and directly determining margin structures across premium clonal cell line services versus commodity expression platforms.
Pricing Analysis
Yield-guaranteed throughput contracts anchor value-based pricing for CRISPR-engineered Chinese hamster ovary platforms, with sponsors paying premium fees for clones demonstrating specific productivity above 50 picograms per cell per day. Price differentiation separates regulatory documentation depth from speed-to-IND timelines, with EMA-compliant genetic stability packages commanding substantial premiums over exploratory screening services. Cost compression in standard transient expression services is intensifying as automated transfection platforms reduce labor intensity. Academic labs exhibit highest price sensitivity, while Phase III-stage biopharmaceutical sponsors prioritize timeline certainty over unit cost.
Supply Chain Analysis
Cell bank refurbishment and master cell line remanufacturing flows concentrate regulatory risk in the United States, Germany, and Switzerland, where specialized providers maintain archival infrastructure for multi-decade product lifecycles. Critical inputs draw from single-source German automation vendors for bioreactor instrumentation and Swiss suppliers for single-use consumables, creating concentrated supply vulnerability. Tariff exposure on precision-engineered cell culture vessels threatens cost structures for Asia-Pacific capacity expansions. Distribution runs through integrated CDMO campuses in Singapore and Basel that anchor commercial antibody supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CRISPR-based precision editing is displacing random integration approaches across contract development programs, compressing clone selection timelines while elevating documentation requirements for genetic stability assurance.
For Market Incumbents: Anticipate regulatory divergence on next-generation sequencing clonality standards across FDA, EMA, and NMPA jurisdictions by pre-investing in molecular characterization infrastructure ahead of formal guidance adoption. Consolidate backward integration into chemically defined media formulation to offset 35-50% upstream cost exposure from qualified supplier concentration. Platform licensing agreements represent the priority defensive lever against emerging boutiques offering accelerated CHO timelines. For New Entrants and Emerging Players: ICH Q5D harmonization across FDA, EMA, and NMPA jurisdictions opens a window for specialized genetic stability documentation services targeting legacy cell bank characterization gaps. White-space concentration sits with India-based contract development capacity in Hyderabad and Bengaluru, where underpenetrated biologics manufacturing infrastructure offers cost-advantaged export positioning. Japan's PMDA Sakigake designation pathway for regenerative medicine products provides the most penetrable regulatory entry angle for novel engineered cell line applications. For Investors and Strategic Acquirers: FDA draft guidance publication on molecular clonality confirmation is the leading indicator that documentation depth will separate premium-margin from commodity-margin service tiers within the analysis window. Long-term viability favors platform technology owners with established master cell bank regulatory histories over project-based service boutiques. Acquisition target archetypes include CRISPR engineering boutiques with validated knock-in protocols and proprietary landing pad cell lines. Practitioners should monitor NMPA technical guideline revisions on genetically modified cell lines for early signals of China market access trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Platform Licensing | Pre-validated host cell backgrounds with EMA-accepted master cell bank histories reduce IND-enabling timelines for oncology antibody programs. |
| Perfusion Bioreactor Integration | Continuous processing convergence with real-time quality analytics enables steady-state manufacturing with reduced Singapore facility footprint. |
| India CDMO Capacity Buildout | Hyderabad and Bengaluru infrastructure expansion captures cost-advantaged cell line development demand from export-market sponsors. |
| Genetic Stability Documentation Services | Extended 60 population doubling characterization packages address EMA revised IMPD requirements for gene-edited substrates. |
| Automated Clone Screening Deployment | Single-cell deposition systems processing 96-well plates under four hours compress screening burden from thousands to hundreds of candidates. |
Methodological Framework
FDA filings, EMA submissions, and ClinicalTrials.gov records formed the secondary backbone, cross-referenced with NMPA technical guidelines and ICH harmonization documents. Primary interviews with cell line development directors, regulatory affairs leads at contract manufacturing organizations, and bioprocess engineers at mammalian expression facilities validated segmentation assumptions. Bottom-up triangulation across technology adoption rates and top-down reconciliation against biopharmaceutical R&D expenditure patterns anchored volume estimates.
Historical trendline analysis across Chinese hamster ovary productivity benchmarks, CRISPR engineering adoption curves, and contract manufacturing outsourcing ratios established baseline growth parameters. The analytical framework modeled cell type, process stage, technology platform, and end-user procurement authority across the projection horizon. CAGRs derived from regression against biologics pipeline expansion and regulatory documentation complexity indices, with specific inputs including monoclonal antibody candidate flow into Phase I trials and CDMO capacity utilization rates in Switzerland and Singapore.
The model assumes a particular technology adoption path; alternative pathways for CRISPR-Cas9 knock-in engineering displacing conventional random integration would alter the outlook for clone screening service demand. Forecasts reflect assumptions regarding regulatory convergence timelines on molecular clonality standards and sustained biopharmaceutical sponsor preference for platform licensing over de novo cell line construction. Practitioners should monitor FDA guidance finalization on next-generation sequencing validation and NMPA enforcement patterns on genetically modified organism containment for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Biopharmaceuticals Contract Manufacturing Market
Biopharmaceuticals
Mammalian Polyclonal Igg Antibody Market
Biopharmaceuticals
Drug Discovery Outsourcing Market
Biopharmaceuticals
APAC Insulin Market
Biopharmaceuticals
Combination Antibody Therapy Market
Biopharmaceuticals
Global Thrombin Market
Biopharmaceuticals
BRAF Kinase Inhibitors Market
Biopharmaceuticals
Tetracycline Market
Biopharmaceuticals
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market
Biopharmaceuticals
Fenbendazole Market
Biopharmaceuticals
Middle East and Africa Insulin Delivery Devices Market
Biopharmaceuticals
Russia Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Tuberculosis Biomarkers Market
Biopharmaceuticals
Large Macrolide Drugs Market
Biopharmaceuticals
Global Actinic Keratosis Drugs Market
Biopharmaceuticals
North America Contraceptives Market