
 Benzbromarone API Market | 2026-2036
Benzbromarone API Market Size, Share, and Industry Trends Forecast 2026-2036
Benzbromarone API Market Insights
A shift from single-source to multi-source procurement is pivoting how pharmaceutical buyers qualify Benzbromarone API suppliers. Teva Pharmaceutical Industries leverages vertical integration across synthesis and finished-dose manufacturing to secure supply continuity. Dr. Reddy's Laboratories anchors its position through cost-efficient bulk production serving regulated and emerging markets. Hikma Pharmaceuticals differentiates via specialized compliance packages that streamline customer audits.
Benzbromarone API is a benzofuran-derived uricosuric compound with the molecular formula C17H12Br2O3, synthesized through bromination and cyclization of substituted phenoxy intermediates; it functions by inhibiting renal tubular reabsorption of uric acid to treat hyperuricemia associated with gout. Tablet formulations dominate current volume consumption due to established bioequivalence profiles and patient compliance advantages, while injectable solutions represent the fastest-expanding product type as hospitals seek rapid uric acid reduction protocols. Rheumatology applications command premium pricing through specialist channel access, whereas pharmacy compounding occupies a niche serving personalized dosing requirements.
US FDA pharmacopeial standards and ICH Q3D elemental impurity guidelines shape manufacturing investments, while India's CDSCO and China's NMPA impose country-specific impurity limits that filter export-capable suppliers. The EU REACH framework governs solvent and reagent handling in European production facilities. Stakeholders must monitor evolving pharmacopoeial harmonization between major regulatory zones to anticipate qualification burden shifts.
Market Dynamics
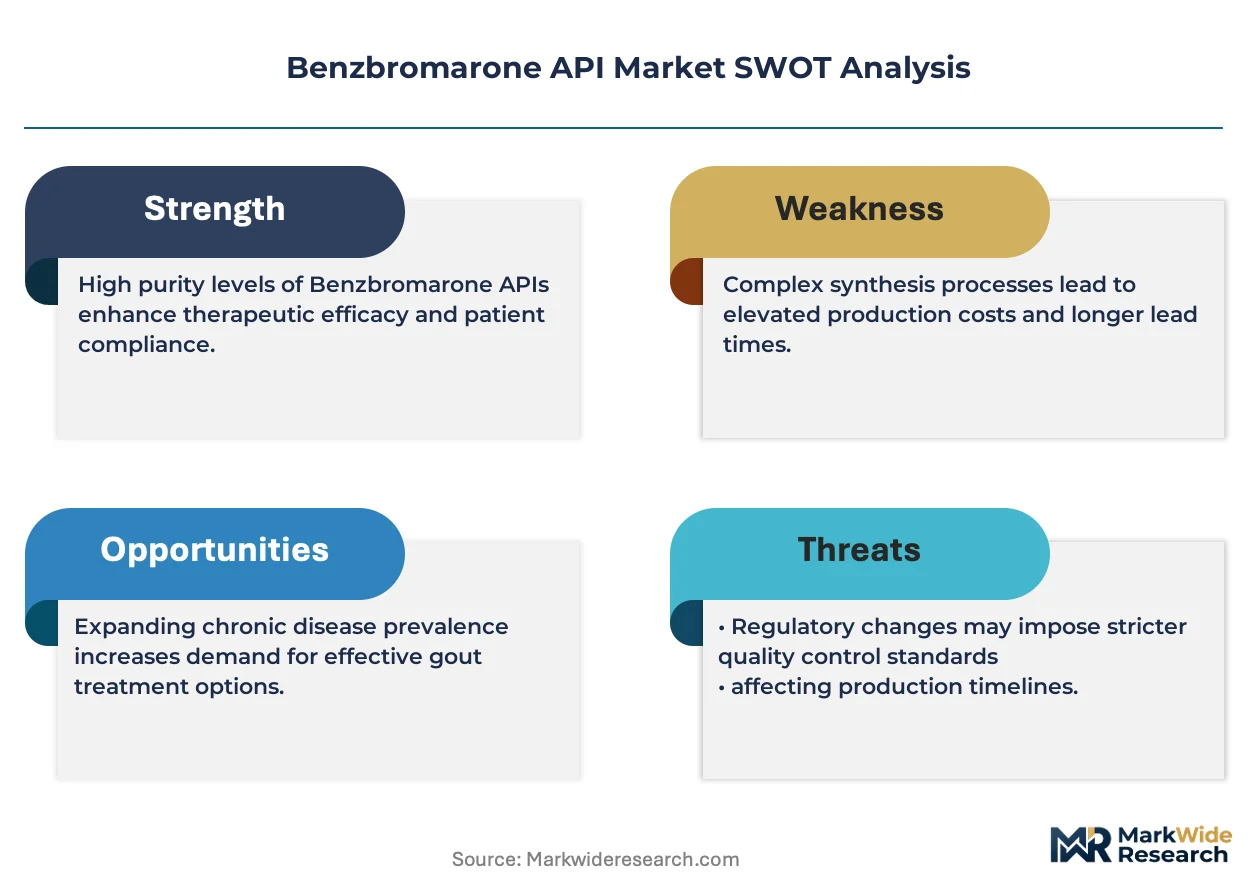
Pharmaceutical manufacturers are reconfiguring supplier networks as ICH Q3D elemental impurity guidelines and country-specific pharmacopoeial standards force simultaneous compliance across multiple regulatory zones. This multi-jurisdictional burden is compressing the qualified supplier base while amplifying procurement complexity for finished-dose formulators.
Growth Catalysts
- Chronic disease prevalence:Rising gout diagnosis rates in aging populations across Japan, Germany, and the United States are expanding prescription volumes for uricosuric therapies. Rheumatology clinics are prioritizing API security of supply.
- CDSCO export pathway expansion:India's streamlined API certification for regulated markets is accelerating supplier qualification timelines. Domestic manufacturers are capturing contract manufacturing opportunities from Western pharmaceutical companies.
- Continuous flow bromination:Adoption of flow chemistry for hazardous halogenation steps is improving yield consistency and reducing solvent waste. Technology licensors are targeting mid-scale API producers in Hyderabad and Shanghai.
Market Restraints
- Bromine feedstock volatility:Elemental bromine price swings tied to Dead Sea extraction constraints and flame-retardant sector competition are compressing margin predictability for cyclization-dependent synthesis routes.
- East Asian supply concentration:Over 70 percent of qualified Benzbromarone API capacity resides in Zhejiang Province and the Hyderabad-Chennai corridor, creating geographic risk exposure for European and North American formulators.
- Allopurinol generic substitution:Xanthine oxidase inhibitors dominate first-line hyperuricemia therapy in US and EU formularies, limiting Benzbromarone API volume expansion in price-sensitive reimbursement environments.
Strategic Opportunities
- Brazilian ANVISA prequalification:Underpenetrated Latin American rheumatology markets offer first-mover advantages for suppliers achieving Brazilian regulatory approval ahead of patent cliff transitions for competing urate-lowering therapies.
- Hospital infusion protocols:Injectable Benzbromarone formulations for acute gout management are gaining traction in Japanese and South Korean tertiary care centers, opening parenteral API demand channels distinct from oral solid dosage supply.
- Green chemistry incentives:EU REACH solvent substitution mandates and India's PLI scheme for sustainable manufacturing are rewarding capital investment in enzymatic bromination and aqueous cyclization technologies.
Industry Challenges
- Analytical method transfer complexity:Impurity profiling requirements diverge between USP, EP, and JP monographs, forcing contract laboratories to maintain multiple validated chromatographic protocols for single API lots.
- Specialized halogenation expertise:Safe handling of molecular bromine and control of regioselective substitution demand chemists with rare combination of process safety and synthetic organic qualifications, constraining workforce scalability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benzbromarone API Market |
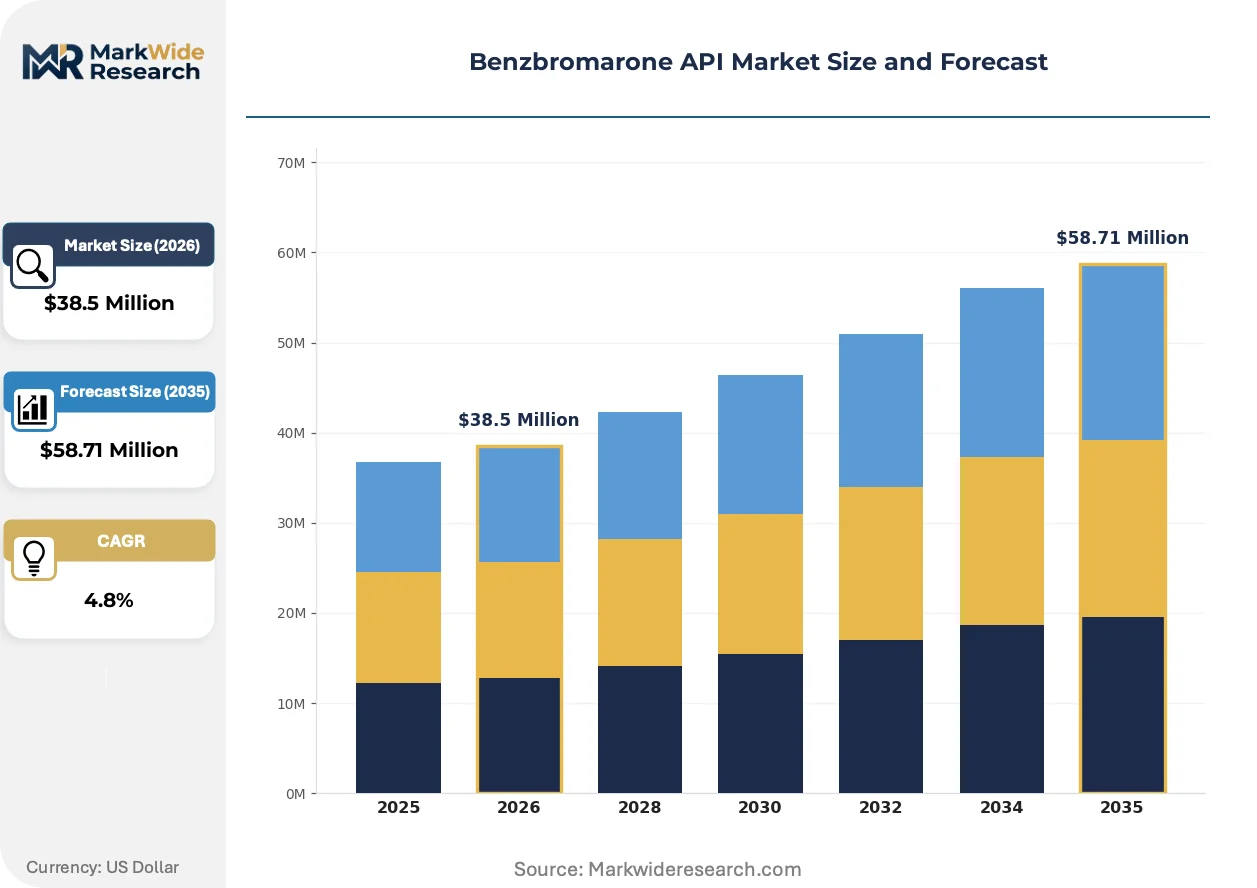
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $58.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injectable Solutions, Oral Solutions Application: Gout Treatment, Nephrology, Pharmacy Compounding, Rheumatology End User: Hospitals, Specialty Clinics, Retail Pharmacies, Online Pharmacies Distribution Channel: Direct Sales, Wholesale Distributors, Online Sales, Contract Manufacturing |
| Companies Covered | Teva Pharmaceutical Industries Ltd., Dr. Reddy's Laboratories, Mylan N.V., Novartis AG, Zydus Cadila, Hikma Pharmaceuticals, Hayao Group, Jinan Mingsheng Pharmaceutical, Shanghai Minbiotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benzbromarone API Market Trends and Innovations
Manufacturing technology and regulatory harmonization pressures are converging to reshape how Benzbromarone API is synthesized, tested, and procured. Three distinct vectors are redrawing competitive boundaries across the supply base.
Continuous flow reactor technology is decentralizing hazardous bromination steps from centralized batch facilities to modular, containerized production units. Mid-scale API manufacturers in Gujarat and Shandong are piloting these systems to reduce solvent inventory and improve thermal safety margins. This diffusion is compressing the minimum efficient scale for qualified production, enabling regional suppliers to serve national formulators without multi-tonne batch investments.
EMA's revised guideline on nitrosamine risk assessment is forcing retrospective evaluation of cyclization intermediates and catalyst residues in existing Benzbromarone dossiers. European API importers are demanding enhanced nitrosamine impurity data packages from Indian and Chinese suppliers, extending qualification timelines by six to eighteen months. Contract manufacturers with established nitrosamine control strategies are capturing preferential supply agreements from EU-based generic finished-dose marketers.
Hospital procurement consortia are consolidating API sourcing decisions through centralized tendering platforms that bundle multiple urate-lowering agents. This buyer concentration is displacing traditional distributor-mediated transactions in Germany, France, and the United Kingdom. Rheumatology-focused hospital networks are leveraging volume commitments to secure dual-source API arrangements, reducing reliance on single-qualification supplier relationships that dominated the 2015-2020 period.
Benzbromarone API Market Segmentation
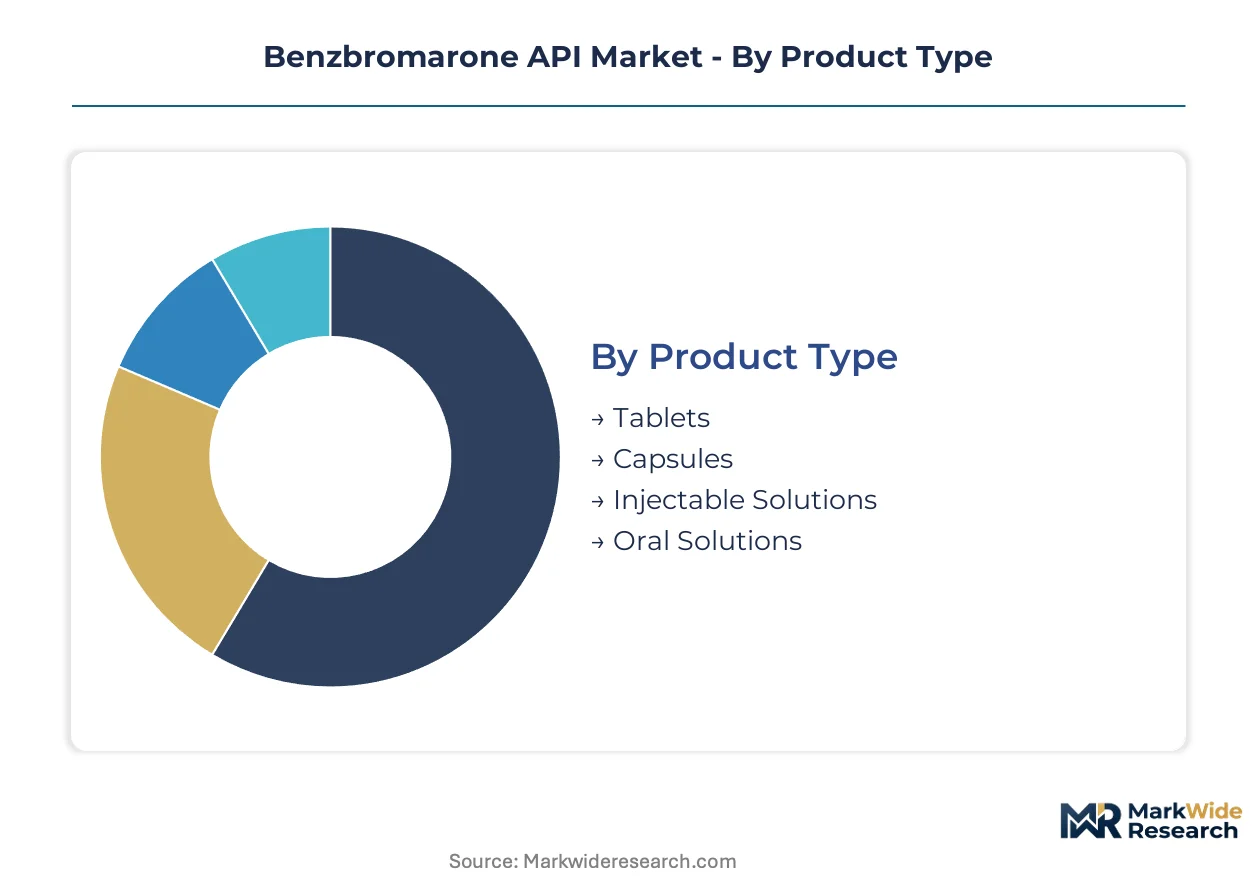
Benzbromarone API procurement patterns diverge sharply across formulation types and clinical settings. Understanding these splits allows suppliers to align manufacturing investments with where pricing power and volume commitments actually concentrate.
Product Type:
Tablets dominate current procurement volumes while injectable formats command substantial premiums per kilogram of API consumed.
- Tablets:Compressed solid dosage forms with established bioequivalence profiles and 24-hour dosing convenience. Rheumatology practices in Germany and Japan favor these for maintenance therapy, driving steady bulk API demand from qualified suppliers.
- Injectable Solutions:Parenteral formulations enabling rapid uric acid reduction in acute gout flares. Japanese and South Korean tertiary care centers are expanding infusion protocols, opening a channel with steeper API purity requirements and higher unit economics.
- Capsules:Gelatin or HPMC shells accommodating modified-release granules. Retail pharmacy chains in India prefer these for patient-specific dosing flexibility.
- Oral Solutions:Liquid suspensions for pediatric or geriatric populations with swallowing difficulties. Pharmacy compounding operations in Brazil source API for extemporaneous preparation.
Mature deployment sits with Tablets. Newer deployment is concentrated in Injectable Solutions.
Application:
Chronic disease management applications anchor volume procurement while specialized therapeutic areas extract premium pricing.
- Gout Treatment:Primary indication addressing hyperuricemia through renal urate excretion enhancement. Aging demographics across the United States, Germany, and Japan are expanding prescription volumes for first-line and refractory cases.
- Rheumatology:Specialist-managed care protocols with access to premium reimbursement tiers. Hospital networks in France and the United Kingdom consolidate purchasing through centralized tendering platforms.
- Nephrology:Adjunct therapy for chronic kidney disease patients with urate retention. Dialysis centers in South Korea and Taiwan represent emerging demand nodes.
- Pharmacy Compounding:Personalized dosing for patients with intolerance to standard strengths. Regulatory variance between USP and EP monographs complicates API qualification for cross-border compounders.
Volume procurement clusters in Gout Treatment. Margin capture concentrates in Rheumatology.
End User:
Institutional buyers leverage scale for price negotiation while direct-to-patient channels fragment order patterns.
- Hospitals:Integrated delivery networks managing acute and chronic gout populations. Procurement consortia in Germany, France, and the United Kingdom are displacing distributor-mediated transactions with centralized API tendering.
- Specialty Clinics:Rheumatology-focused practices with prescriber influence over formulation selection. Japanese clinic chains prioritize supply continuity assurances over unit cost minimization.
- Retail Pharmacies:Community dispensing points serving maintenance therapy patients. Indian retail chains are expanding generic substitution programs for price-sensitive consumers.
- Online Pharmacies:Digital platforms with direct-to-patient fulfillment. Brazilian and Mexican e-pharmacy growth is creating API demand outside traditional wholesale channels.
Contract security matters most to Hospitals. Patient access expansion runs through Online Pharmacies.
Distribution Channel:
Direct relationships reduce qualification burden while intermediaries extend geographic reach at margin cost.
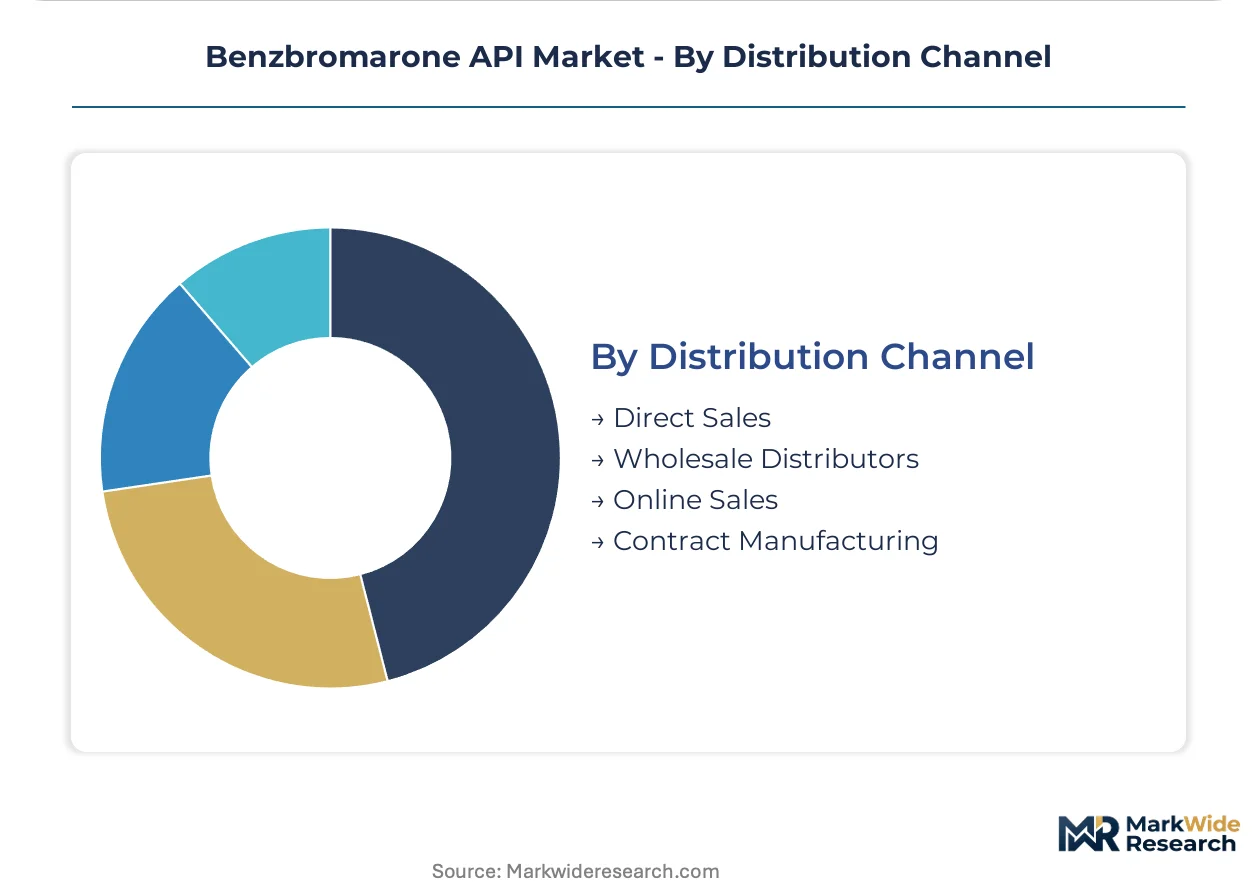
- Direct Sales:API manufacturers supplying finished-dose formulators under master service agreements. Teva Pharmaceutical Industries and Dr. Reddy's Laboratories leverage backward integration to secure captive supply.
- Wholesale Distributors:Inventory-holding intermediaries bridging qualified suppliers with smaller formulators. European distributors face margin pressure from hospital procurement consolidation.
- Online Sales:Digital platforms for spot purchasing and sample quantities. Chinese API marketplaces are attracting Indian manufacturers seeking alternative export channels.
- Contract Manufacturing:Toll production arrangements where API suppliers provide starting material for third-party finished-dose production. CDSCO export pathway expansion is accelerating Indian contract manufacturer qualification for Western pharmaceutical companies.
Relationship depth is greatest in Direct Sales. Channel diversification is advancing fastest through Contract Manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Elemental bromine extraction from Dead Sea brines in Israel anchors feedstock security for cyclization-dependent synthesis routes. Finished-dose formulators in Germany, Japan, and the United States source qualified API through divergent regulatory pathways.
United States
Rheumatology clinics in Florida and Arizona are expanding prescription volumes for refractory gout populations. FDA pharmacopeial standards and ICH Q3D elemental impurity guidelines filter qualified supplier pools. New Jersey and Massachusetts host formulation science clusters where finished-dose manufacturers audit API vendors for nitrosamine control strategies.
Germany
Hospital procurement consortia in Bavaria and North Rhine-Westphalia consolidate tendering for urate-lowering therapies through centralized platforms. EU REACH framework governs solvent substitution mandates in cyclization processes. Frankfurt and Hamburg serve as distribution nodes where wholesale distributors face margin compression from direct manufacturer relationships.
China
Zhejiang Province concentrates over half of qualified Benzbromarone API capacity serving domestic and export markets. NMPA imposes country-specific impurity limits that shape export dossier preparation. Shanghai and Shandong manufacturers are piloting continuous flow bromination reactors to improve yield consistency and reduce solvent waste.
India
Hyderabad-Chennai corridor manufacturers leverage CDSCO export pathway expansion to accelerate Western pharmaceutical company qualification timelines. The PLI scheme for sustainable manufacturing rewards capital investment in enzymatic halogenation technologies. Gujarat-based producers are capturing contract manufacturing opportunities through cost-efficient bulk production.
Japan
Tertiary care centers in Tokyo and Osaka are expanding hospital infusion protocols for acute gout management. PMDA maintains stringent pharmacopoeial standards that prioritize supply continuity assurances over unit cost minimization. Kansai region rheumatology clinic chains drive demand for injectable formulation API with steeper purity requirements.
Benzbromarone API Market Competitive Landscape
Global majors compete with regional champions across regulatory qualification and synthesis technology dimensions. The supplier base compresses around ICH Q3D compliance capabilities while fragmenting across geographic certification coverage. Three archetypes dominate: vertically integrated pharmaceutical conglomerates, cost-focused bulk specialists, and compliance-forward contract manufacturers. Capacity expansion in continuous flow halogenation and strategic partnerships for nitrosamine control data packages represent the dominant competitive moves.
Within the vertically integrated tier, Teva Pharmaceutical Industries exemplifies backward integration across synthesis and finished-dose manufacturing to secure captive supply. Dr. Reddy's Laboratories anchors the cost-efficient bulk production archetype serving regulated and emerging markets through the Hyderabad manufacturing corridor. Hikma Pharmaceuticals occupies a position within the compliance-specialist segment, streamlining customer audit processes through pre-packaged regulatory documentation. These three entities represent distinct strategic postures that shape procurement negotiations with formulators.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd. |
| Dr. Reddy's Laboratories |
| Mylan N.V. |
| Novartis AG |
| Zydus Cadila |
| Hikma Pharmaceuticals |
| Hayao Group |
| Jinan Mingsheng Pharmaceutical |
| Shanghai Minbiotech |
| Others |
Pricing and Supply Chain Analysis
EU REACH solvent substitution mandates gate qualified supply and premium-tier pricing access for Benzbromarone API manufacturers. Compliance investments in aqueous cyclization technologies separate premium-certified suppliers from standard-tier competitors serving emerging markets.
Pricing Analysis
Warranty and regulatory documentation bundling separates premium API tiers from unbundled commodity offerings. Three-tier pricing structure across premium, standard, and economy levels reflects ICH Q3D compliance depth and nitrosamine control data package completeness. Cost compression in the economy tier is intensifying because Indian and Chinese producers compete on CDSCO and NMPA export pathway speed. Retail pharmacy chains in India exhibit highest price sensitivity, while Japanese hospital procurement consortia prioritize supply continuity assurances over unit cost minimization.
Supply Chain Analysis
Direct-to-formulator channels handle multinational pharmaceutical demand, while wholesale distributors serve mid-scale generic manufacturers. Supply concentrates in Zhejiang Province, the Hyderabad-Chennai corridor, and Gujarat-based production clusters. Elemental bromine from Dead Sea extraction and substituted phenoxy intermediates anchor raw material dependencies. Single-source vulnerability in East Asian halogenation capacity exposes European and North American formulators to geographic concentration risk. Distribution runs through master service agreements for qualified supply, with spot purchasing via Chinese digital platforms for non-regulated markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into bromine feedstock security and finished-dose manufacturing represents the dominant competitive lever in this market. Players are racing to capture upstream control and downstream formulation capacity simultaneously.
For Market Incumbents: Hedge against allopurinol generic substitution pressure by securing dual-source API arrangements with Indian CDSCO-certified manufacturers. Invest in continuous flow bromination technology to reduce solvent waste and improve yield consistency. Capture rheumatology clinic chain loyalty through pre-packaged nitrosamine control documentation that streamlines PMDA and EMA audits. For New Entrants and Emerging Players: Enter via Brazilian ANVISA prequalification to capture underpenetrated Latin American rheumatology markets ahead of competing urate-lowering therapy patent cliffs. Target hospital infusion protocols in Japanese and South Korean tertiary care centers for injectable formulation API demand. Pursue toll manufacturing partnerships with European generic finished-dose marketers seeking nitrosamine-compliant supply alternatives. For Investors and Strategic Acquirers: EMA nitrosamine guideline enforcement delays exceeding twelve months are the leading indicator that contract manufacturers with established control strategies will command acquisition premiums. Long-term viability centers on synthesis technology differentiation rather than commodity scale. Prioritize mid-scale API producers in Gujarat and Shandong piloting enzymatic halogenation. Watch for CDSCO export pathway expansion acceleration as signal of Indian supplier qualification momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Bromination Adoption | Modular reactor deployment in Gujarat and Shandong reduces solvent inventory and thermal safety margins. |
| Nitrosamine Control Data Package Investment | Pre-validated impurity protocols streamline EMA and FDA qualification timelines for EU importers. |
| Backward Integration into Bromine Security | Dead Sea extraction partnerships anchor feedstock stability for cyclization-dependent synthesis routes. |
| Injectable Formulation API Capacity Addition | Parenteral purity capabilities capture Japanese hospital infusion protocol expansion in tertiary care centers. |
| CDSCO Export Pathway Qualification | Accelerated Western pharmaceutical company supplier timelines unlock contract manufacturing opportunities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Benzbromarone API market assessment. Primary interviews with API manufacturing executives, regulatory affairs leads at Indian and Chinese suppliers, hospital procurement managers in German rheumatology networks, and finished-dose formulator sourcing directors validated demand patterns. FDA pharmacopeial standards, EMA nitrosamine guidelines, CDSCO export certifications, and NMPA impurity limits provided regulatory boundary conditions. Bottom-up volume modeling across formulation types and top-down value reconciliation via trade flow analysis enabled triangulation.
Data-stream reconciliation integrated production capacity surveys, import-export transaction records, and tender award documentation from hospital procurement consortia. Segmentation modeling spanned product type, application, end user, and distribution channel dimensions, with regional regulatory cluster differentiation across US, EU, Indian, Chinese, and Japanese compliance frameworks. CAGRs were derived from trend extrapolation of prescription volume growth, adjusted for allopurinol substitution dynamics and rheumatology clinic expansion rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under bromine feedstock price volatility and pharmacopoeial harmonization delays. Forecasts reflect assumptions regarding CDSCO pathway efficiency, continuous flow technology adoption curves, and hospital procurement consolidation momentum. Periodic stress-testing of base assumptions is recommended, particularly around East Asian supply concentration risk and EMA nitrosamine enforcement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Breast Cancer Drugs Market
Biopharmaceuticals
Glucagon Injectable Market
Biopharmaceuticals
Erythropoietin Drugs Market
Biopharmaceuticals
Interleukin-6 (IL-6) Inhibitors Market
Biopharmaceuticals
Plasmid DNA Manufacturing Market
Biopharmaceuticals
Insulin Pens Market
Biopharmaceuticals
Asia-Pacific Insulin Pens Market
Biopharmaceuticals
Ocular Tuberculosis Therapeutics Market
Biopharmaceuticals
Insulin Delivery Pens Market
Biopharmaceuticals
Antibacterial Drugs Market
Biopharmaceuticals
Macrolide Drugs Market
Biopharmaceuticals
Liposomal Doxorubicin Market
Biopharmaceuticals
Polyclonal Antibodies Market
Biopharmaceuticals
Generic Drugs Market
Biopharmaceuticals
Europe Insulin Delivery Devices Market
Biopharmaceuticals
Isocitrate Dehydrogenase (IDH) Inhibitors Market