
 Proteinuria Therapeutics Market | 2026-2036
Proteinuria Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Proteinuria Therapeutics Market Outlook
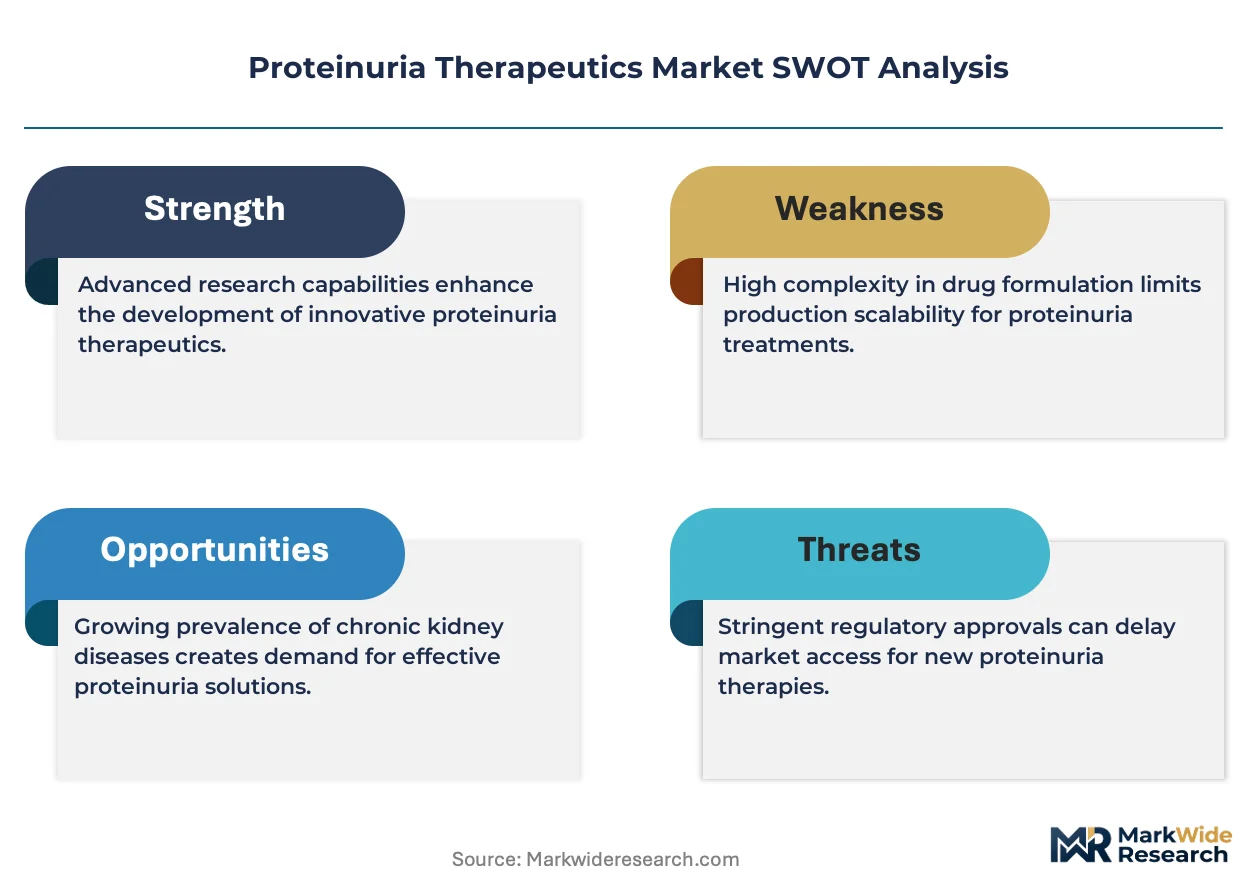
Biologics manufacturing is fragmenting across decentralized production networks, complicating supply assurance for monoclonal antibody therapies used in glomerular disease. AstraZeneca leverages its cardiovascular-renal metabolic franchise to sustain integrated development pipelines spanning SGLT2 inhibitors to emerging proteinuria targets. Boehringer Ingelheim anchors its position through deep nephrology alliances, while Novartis competes via precision medicine platforms targeting rare renal indications.
Proteinuria therapeutics comprise pharmacological agents that reduce urinary protein excretion, typically measured by urine albumin-to-creatinine ratio thresholds below 30 mg/g for normoalbuminuria control, with mechanisms spanning RAAS inhibition, SGLT2 blockade, and immunomodulation to delay end-stage renal disease progression. ACE inhibitors and angiotensin receptor blockers retain dominant prescribing share due to decades of cardiovascular outcome data, though SGLT2 inhibitors represent the fastest-growing product class as renal protective indications expand beyond glycemic control. Oral delivery mode captures the largest volume base, while injectable biologics concentrate margin pools in refractory glomerulonephritis segments.
The US FDA and EMA maintain stringent renal endpoint requirements that shape Phase III trial design and label expansion feasibility for novel proteinuria agents. Japan's PMDA operates accelerated review frameworks for orphan renal indications, creating asymmetric market access timelines across geographies. China's NMPA is harmonizing bioequivalence standards for generic ARBs, intensifying cost competition in the largest volume market. Stakeholders must monitor evolving surrogate endpoint acceptability and real-world evidence requirements that will determine which therapeutic modalities secure priority reimbursement positions.
Market Dynamics
Hospital-based nephrology departments are consolidating proteinuria management under integrated cardiovascular-renal-metabolic protocols, compressing the traditional separation between diabetes, cardiology, and renal care pathways. This structural convergence is reshaping prescribing authority and formulary placement decisions.
Growth Catalysts
- SGLT2 inhibitor label expansions:Renal protective indications now extend beyond glycemic control, pulling new prescriber specialties into proteinuria management.
- Japan's PMDA orphan frameworks:Accelerated review timelines for rare renal indications create asymmetric access advantages for novel biologics targeting refractory glomerulonephritis.
- Diabetes prevalence clusters:Diagnostic volumes concentrate in aging urban populations across the United States, Germany, and Japan, expanding the addressable patient base for albuminuria screening.
Market Restraints
- Biologics supply concentration:Decentralized manufacturing networks fragment monoclonal antibody production, complicating cold-chain assurance for glomerular disease therapies.
- Surrogate endpoint rigidity:The US FDA and EMA maintain stringent renal outcome requirements that extend Phase III timelines and raise capital barriers for novel mechanism candidates.
- Generic ARB cost compression:China's NMPA bioequivalence harmonization intensifies price competition in the largest volume market, eroding branded small-molecule margins.
Strategic Opportunities
- Real-world evidence pathways:Evolving FDA and EMA acceptance of post-market surveillance data creates alternative routes to label expansion and priority reimbursement.
- Injectable biologics in refractory segments:Margin pools concentrate in treatment-resistant glomerulonephritis where oral RAAS inhibitors fail, rewarding targeted immunomodulation development.
- Precision medicine platforms:Genomic stratification of rare renal indications enables companion diagnostic pairing and premium pricing capture in orphan populations.
Industry Challenges
- Cross-functional talent scarcity:Nephrology drug development requires integrated expertise in cardiovascular outcomes, renal biomarker validation, and immunology that few organizations possess.
- Legacy protocol integration:Hospital formulary committees must reconcile accelerated approval pathways with established ACE inhibitor and ARB prescribing habits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Proteinuria Therapeutics Market |
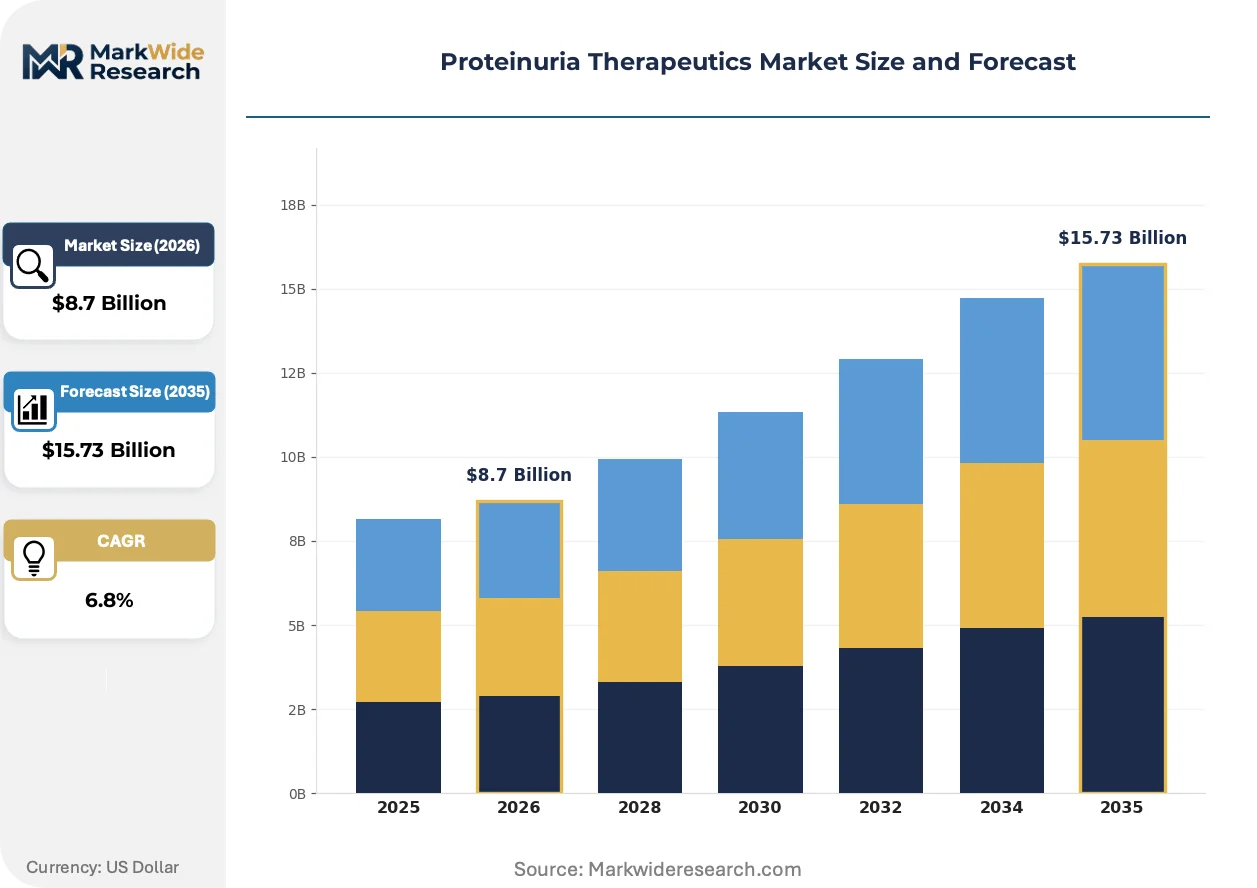
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Angiotensin Receptor Blockers, ACE Inhibitors, Diuretics, Immunosuppressants Delivery Mode: Oral, Injectable, Infusion, Transdermal End User: Hospitals, Clinics, Home Healthcare, Long-term Care Facilities Indication: Diabetic Nephropathy, Hypertensive Nephropathy, Glomerulonephritis, Other Causes |
| Companies Covered | AstraZeneca, Boehringer Ingelheim, Novartis AG, Sanofi, Takeda Pharmaceutical Company, Bristol-Myers Squibb, Travere Therapeutics, Calliditas Therapeutics, AbbVie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Proteinuria Therapeutics Market Strategic Shifts
Proteinuria therapeutics are undergoing modality diversification as oral small molecules face pressure from biologics and cell therapies in refractory indications. This shift is compressing traditional development timelines and forcing portfolio rebalancing across the industry.
Dual RAAS-SGLT2 combination regimens are migrating from sequential add-on therapy to first-line protocol in high-risk diabetic kidney disease. Major academic medical centers in the United States and Germany now initiate simultaneous blockade at diagnosis, compressing the historical step-care timeline and displacing monotherapy dominance.
The US FDA's accelerated approval pathways for renal therapeutics are reshaping Phase III trial design by accepting albuminuria reduction as a surrogate endpoint. This regulatory flexibility compresses time-to-market for novel mechanisms but requires robust confirmatory outcome studies, affecting capital allocation strategies across development-stage portfolios.
Procurement consolidation is concentrating purchasing authority within integrated health networks that span nephrology, cardiology, and endocrinology. These systems now negotiate bundled contracts for cardiovascular-renal-metabolic franchises, compressing vendor margins while rewarding therapeutic breadth over single-product depth in the United States and select Western European markets.
Proteinuria Therapeutics Market Segmentation
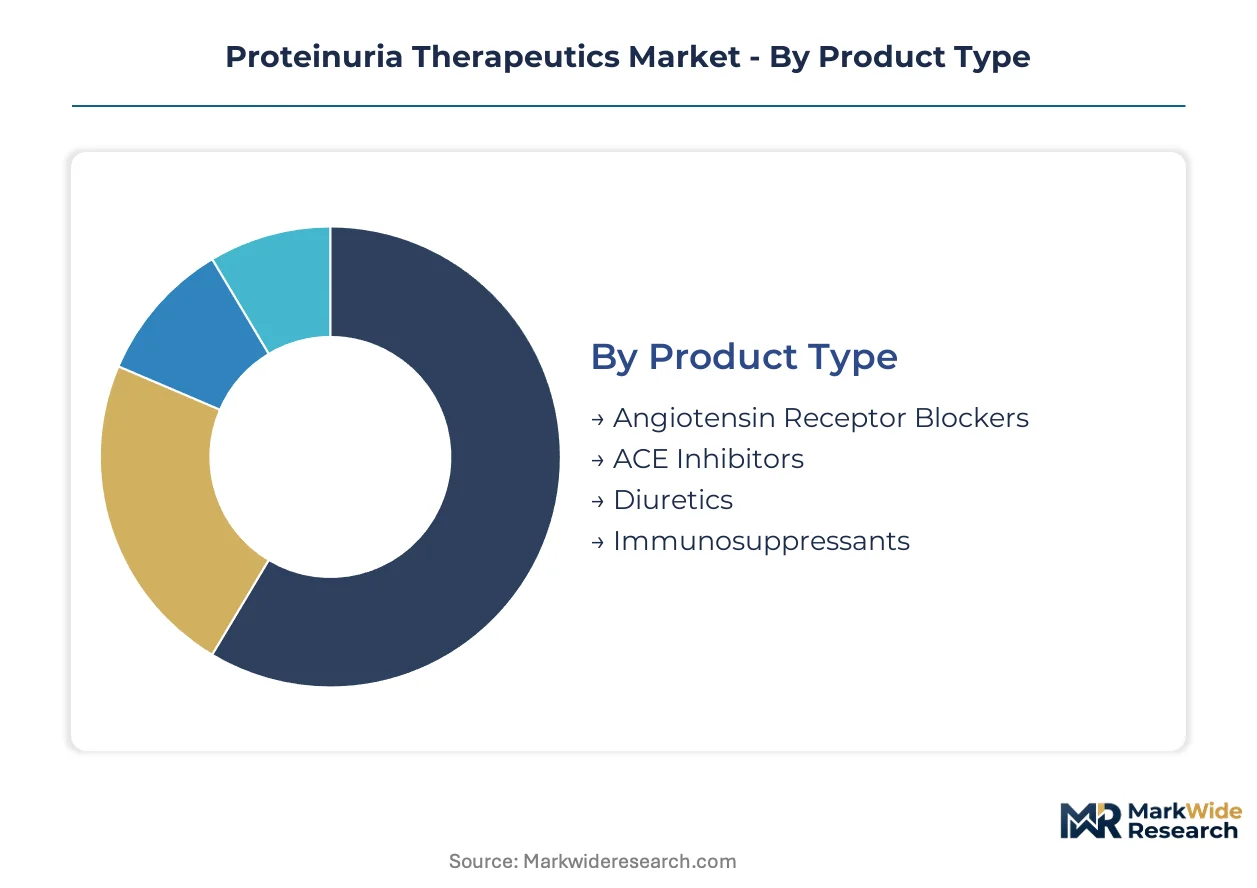
Proteinuria therapeutics segment along four critical dimensions that shape prescribing patterns, reimbursement pathways, and manufacturing scale. Understanding these divisions reveals where volume concentrates versus where margins expand.
Product Type:
Prescription cycles vary dramatically across drug classes, with generic ARBs turning over in weeks while immunosuppressants require months of titration and monitoring.
- Angiotensin Receptor Blockers:These agents block angiotensin II type 1 receptors to reduce glomerular pressure and protein filtration. Demand concentrates in primary care networks across the United States and Germany where hypertension comorbidity drives first-line prescribing, though China's NMPA bioequivalence standards intensify cost competition.
- ACE Inhibitors:Enzyme inhibitors that suppress angiotensin-converting enzyme activity remain entrenched in cardiovascular-renal-metabolic protocols. Japanese nephrology departments favor these for diabetic nephropathy given decades of domestic outcome data, even as SGLT2 inhibitors displace share in Western markets.
- Diuretics:Loop and thiazide agents adjunctively manage volume overload in proteinuric patients.
- Immunosuppressants:Calcineurin inhibitors and antimetabolites target refractory glomerulonephritis where RAAS blockade fails.
ACE inhibitors and ARBs together anchor the volume base while immunosuppressants gain share at the steepest rate in refractory indications.
Delivery Mode:
Cost tiers separate sharply across administration routes, with oral generics at the bottom and infused biologics commanding premium reimbursement.
- Oral:Small-molecule tablets and capsules dominate daily prescribing for chronic proteinuria management. German statutory health insurance funds negotiate reference pricing that compresses margins on ARB and ACE inhibitor tablets, while Japan's PMDA maintains separate premium tracks for novel oral mechanisms.
- Injectable:Subcutaneous biologics target treatment-resistant glomerulonephritis with precision immunomodulation. United States academic medical centers concentrate demand for these agents where accelerated FDA approval pathways support earlier access.
- Infusion:Intravenous biologics and plasma exchange protocols serve hospitalized nephrotic syndrome flares.
- Transdermal:Patch-based delivery remains experimental for proteinuria indications.
Oral formulations capture the widest patient base while injectable biologics expand most quickly in orphan renal indications.
End User:
Customer concentration patterns reveal where procurement authority is consolidating versus fragmenting across care settings.
- Hospitals:Integrated nephrology departments in the United States and Germany now manage proteinuria within cardiovascular-renal-metabolic bundles. These institutions negotiate franchise-level contracts with AstraZeneca and Boehringer Ingelheim that displace single-product purchasing.
- Clinics:Outpatient nephrology practices handle stable chronic kidney disease monitoring and medication titration.
- Home Healthcare:Subcutaneous self-administration of biologics shifts infusion center visits to residential settings.
- Long-term Care Facilities:Nursing homes manage proteinuria in elderly diabetic populations with limited nephrology specialist access.
Hospitals anchor institutional purchasing volume while home healthcare climbs the fastest as self-injection biologics proliferate.
Indication:
Disease-specific protocols create divergent margin structures based on diagnostic coding precision and orphan designation eligibility.
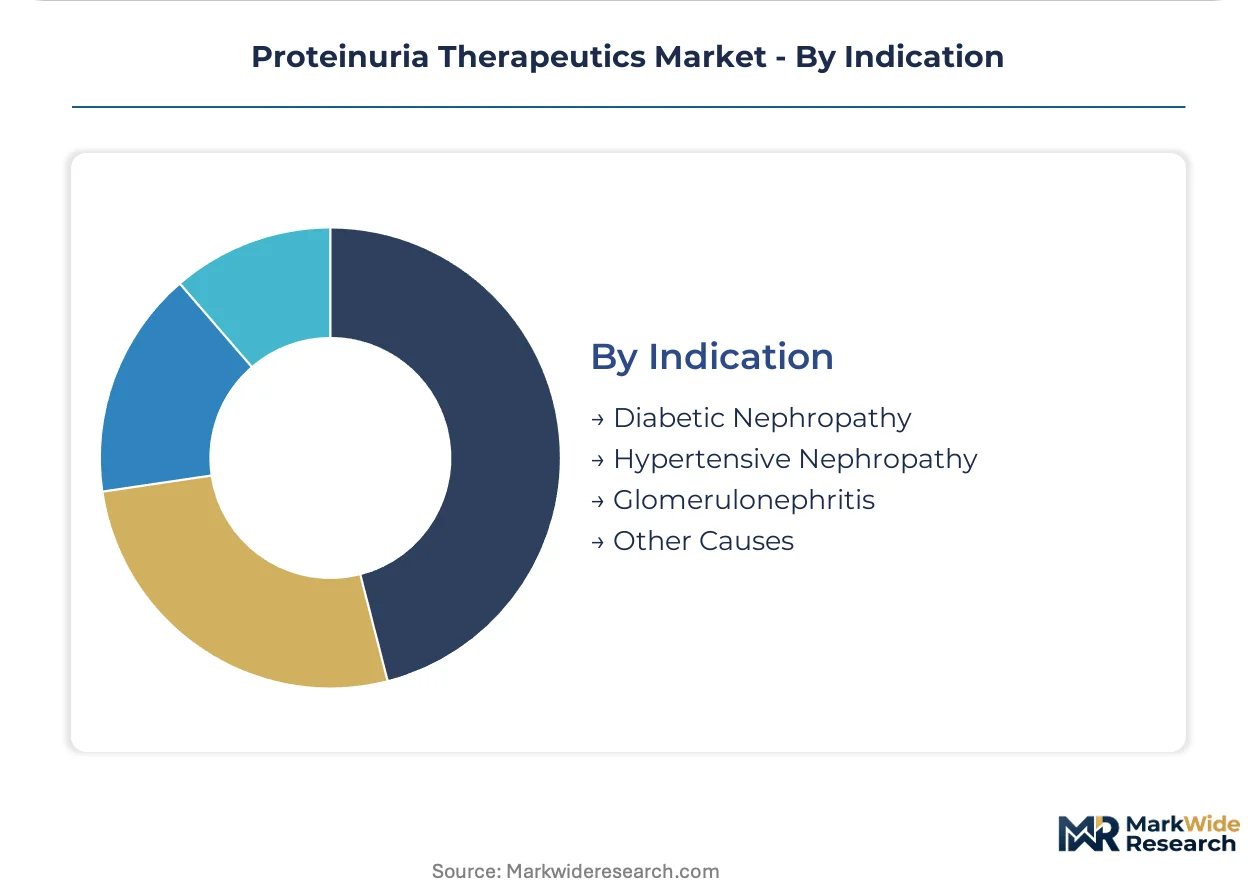
- Diabetic Nephropathy:Albuminuria screening in type 2 diabetes populations generates the largest addressable patient pool. United States endocrinology practices now initiate SGLT2 inhibitors at diagnosis per ADA guidelines, compressing the historical lag between diabetes onset and nephrology referral.
- Glomerulonephritis:Primary and secondary glomerular diseases require immunomodulation beyond RAAS blockade. Japan's PMDA orphan frameworks accelerate review for lupus nephritis and IgA nephropathy biologics, creating asymmetric access timelines.
- Hypertensive Nephropathy:Long-standing blood pressure elevation damages renal filtration barriers.
- Other Causes:Hereditary, toxic, and infectious etiologies comprise residual indications.
Diabetic nephropathy anchors the volume base while glomerulonephritis gains share at the steepest rate on biologic therapy expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical exports supply renal therapeutic demand across Central and Eastern European hospital networks, while Japanese biologics manufacturers ship precision immunomodulation agents to Southeast Asian academic medical centers.
United States
End-stage renal disease prevalence and Medicare reimbursement for SGLT2 inhibitors drive diagnostic volumes in urban diabetes clusters. The FDA's accelerated approval pathways for renal therapeutics compress Phase III timelines for novel proteinuria mechanisms. The Boston-Cambridge corridor anchors biologics development for refractory glomerulonephritis, with Massachusetts General Hospital and Brigham and Women's Hospital conducting pivotal trials.
Germany
Hypertension comorbidity and statutory health insurance reference pricing for ARBs concentrate prescribing in primary care networks. The EMA maintains stringent renal endpoint requirements that shape label expansion feasibility for European market entry. The Rhine-Ruhr metropolitan region hosts integrated cardiovascular-renal-metabolic care protocols across university hospitals in Düsseldorf and Cologne.
Japan
Aging demographics and IgA nephropathy incidence generate orphan indication demand for precision immunomodulation. The PMDA operates accelerated review frameworks for rare renal indications, creating asymmetric access timelines versus Western regulators. The Kansai region, centered on Osaka University Hospital, leads domestic outcomes research for lupus nephritis biologics.
China
Type 2 diabetes prevalence in coastal urban populations expands albuminuria screening volumes beyond nephrology specialist capacity. The NMPA harmonizes bioequivalence standards for generic ARBs, intensifying cost competition in the largest volume market. The Yangtze River Delta, spanning Shanghai and Jiangsu province, concentrates domestic manufacturing of RAAS inhibitors for regional distribution.
Proteinuria Therapeutics Market Competitive Environment
Channel-controlling players compete with product-specialist players across therapeutic modality boundaries. The market structure consolidates around cardiovascular-renal-metabolic franchise holders with integrated hospital contracting authority, while biologics specialists fragment share in refractory glomerulonephritis segments. Three archetypes dominate: multinational pharmaceutical conglomerates with renal-dedicated business units, mid-cap immunology specialists with orphan indication focus, and emerging precision medicine platforms with genomic stratification capabilities. Competitive moves center on strategic partnerships for real-world evidence generation and portfolio diversification into cell therapy modalities.
Within the multinational conglomerate tier, AstraZeneca and Novartis occupy positions anchored by cardiovascular-renal-metabolic integration, while Boehringer Ingelheim exemplifies the deep nephrology alliance archetype through sustained specialist network investment.
| Leading Market Players |
|---|
| AstraZeneca |
| Boehringer Ingelheim |
| Novartis AG |
| Sanofi |
| Takeda Pharmaceutical Company |
| Bristol-Myers Squibb |
| Travere Therapeutics |
| Calliditas Therapeutics |
| AbbVie |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European sterile injectable manufacturing is tightening supplier bargaining power and compressing margin structures for biologics used in refractory glomerulonephritis. This utilization squeeze propagates through contract renegotiations and forces buyers toward multi-year offtake commitments to secure cold-chain capacity.
Pricing Analysis
Cost-plus contracts with API indexation dominate procurement for monoclonal antibody therapies, insulating manufacturers from raw material volatility while capping upside. Price differentiation hinges on orphan designation status and FDA accelerated approval tier, with PMDA-tracked biologics commanding premium reimbursement in Japan. Pricing pressure intensifies in oral ARB segments as China's NMPA bioequivalence standards erode branded margins. Statutory health insurance funds in Germany exhibit highest price sensitivity, while United States academic medical centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
Contract manufacturing concentrates among Lonza, Catalent, and Samsung Biologics for monoclonal antibody production, with capacity allocation favoring cardiovascular-renal-metabolic franchise holders. Active pharmaceutical ingredient sourcing draws from India and China for small-molecule RAAS inhibitors, while biologics cell lines remain captive to United States and European development sites. Single-source vulnerability in lipid nanoparticle formulation creates chokepoint exposure for novel proteinuria mechanisms. Distribution runs through integrated health network formularies that consolidate purchasing authority across nephrology, cardiology, and endocrinology departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proteinuria therapeutics are recovering from a cyclical trough driven by SGLT2 inhibitor patent cliff dynamics, with pipeline replenishment now accelerating through FDA accelerated approval pathways.
For Market Incumbents: Pre-empt biosimilar encroachment by locking in exclusive formulary placement through cardiovascular-renal-metabolic bundle contracts with United States integrated delivery networks. Secure backward integration into sterile injectable capacity in Germany or Switzerland to reduce reliance on Lonza and Catalent allocation queues. Deepen real-world evidence generation partnerships with Massachusetts General Hospital and Osaka University Hospital to defend premium positioning against mechanism-of-action substitution. For New Entrants and Emerging Players: Establish a beachhead in IgA nephropathy biologics where Japan's PMDA orphan frameworks compress regulatory timelines and limit incumbent first-mover advantage. Target refractory lupus nephritis segments where RAAS inhibitor failure rates exceed 40% and pricing power remains intact. Deploy precision medicine platforms with companion diagnostic pairing to access premium reimbursement tracks unavailable to small-molecule generics. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among mid-cap immunology specialists with PMDA-tracked pipelines and existing nephrology specialist relationships. Five-to-ten-year viability favors platforms with cell therapy manufacturing capabilities or genomic stratification assets. Monitor FDA acceptance rates for albuminuria surrogate endpoints as the critical inflection signal for capital efficiency in development-stage portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | PMDA orphan designation compresses Japanese market access timelines versus FDA and EMA review cycles. |
| Manufacturing Scale-Up | Sterile injectable capacity expansion in Switzerland reduces cold-chain risk for biologics targeting refractory glomerulonephritis. |
| Pipeline Diversification | Cell therapy modality entry displaces oral small-molecule dominance in treatment-resistant proteinuria indications. |
| Strategic Partnership | Real-world evidence alliances with German statutory health insurance funds accelerate reimbursement negotiations. |
| Geographic Expansion | Yangtze River Delta manufacturing footprint captures NMPA bioequivalence harmonization opportunities for generic ARB production. |
Study Parameters
Desk research of FDA filings, EMA submissions, ClinicalTrials.gov records, and Japanese PMDA assessment reports preceded structured interviews with drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists. Secondary validation drew from CMS Medicare reimbursement databases, German statutory health insurance prescription data, and China NMPA bioequivalence study disclosures. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing across the projection horizon.
Assumptions held fixed include SGLT2 inhibitor label expansion trajectories, PMDA orphan framework continuity, and NMPA bioequivalence standard harmonization; variables stress-tested encompass FDA surrogate endpoint acceptance rates, biologics manufacturing capacity utilization, and integrated health network procurement consolidation velocity. Segmentation dimensions spanned product class, delivery mode, end-user setting, indication severity, and regional regulatory cluster. CAGRs derived from log-linear trend fitting to historical prescription volumes and forward-adjusted for pipeline probability-weighted revenue contribution.
Stress conditions across FDA review timeline variability, biologics cold-chain disruption scenarios, and generic ARB price erosion bands were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including regulatory rejection of albuminuria surrogates, manufacturing contamination events, and formulary exclusion of novel mechanisms. Quarterly review of FDA advisory committee outcomes, PMDA approval velocities, and German reference pricing adjustments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Diagnostic Specialty Antibodies Market
Biopharmaceuticals
Insulin Market
Biopharmaceuticals
Insulin Aspart Market
Biopharmaceuticals
Biopharmaceutical Oral Drug Delivery Market
Biopharmaceuticals
Bioidentical Hormones Market
Biopharmaceuticals
Global Mono Vaccine Market
Biopharmaceuticals
Glucagon Injectable Market
Biopharmaceuticals
Protein Therapeutics Market
Biopharmaceuticals
Antibiotics Market
Biopharmaceuticals
Tuberculosis Drugs Market
Biopharmaceuticals
North Africa Generic Drug Market
Biopharmaceuticals
EPO Biomarkers Market
Biopharmaceuticals
Metabolism Drugs Market
Biopharmaceuticals
Vaccine Production Market
Biopharmaceuticals
Mammalian Derived Proteins Market
Biopharmaceuticals
South Korea Insulin Drugs and Delivery Devices Market